
 Gas Equipment Market | 2026-2036
Gas Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Equipment Market Analysis
Industrial-grade specification tiers is rotating demand toward high-pressure, corrosion-resistant gas handling systems. Linde plc leverages its captive engineering capabilities to dominate hydrogen distribution equipment. Air Liquide S.A. anchors European demand through specialized cryogenic valve and regulator portfolios. Messer Group competes in fragmented regional markets with localized burner and pressure control manufacturing.
Gas equipment encompasses mechanical and electromechanical systems engineered to control, meter, compress, or combust gaseous fuels and industrial gases, typically operating at pressures from sub-ambient to 700 bar with materials selected for hydrogen embrittlement resistance or sour gas compatibility. Its primary purpose spans safe energy conversion in heating applications, precise flow management in chemical synthesis, and custody transfer measurement in utility distribution networks. Compressors and pressure control systems command the deepest margin pools due to precision machining requirements and aftermarket service attachment. Smart meters is displacing mechanical diaphragm units in utility deployments, while biogas technology segments remain nascent outside subsidized European and North American installations. Burners retains volume leadership across industrial process heating but faces technology substitution from electrification mandates in certain jurisdictions.
FDA oversight of medical gas systems, EPA emissions standards for stationary combustion sources, and EU F-Gas Regulation phase-down schedules collectively shape equipment certification requirements and replacement demand cycles. OSHA process safety management rules and ISO 19880 hydrogen fueling standards further constrain design freedoms and vendor qualification pathways. Stakeholders must monitor regulatory divergence between hydrogen-ready equipment standards in Europe and emerging frameworks in Asia-Pacific to avoid stranded certification investments.
Market Dynamics
Hydrogen-ready infrastructure mandates across European Union member states and select US jurisdictions are forcing accelerated replacement of legacy gas handling systems designed for natural gas service. Equipment vendors face compressed certification timelines as ISO 19880 hydrogen fueling standards and EU F-Gas Regulation phase-down schedules converge.
Growth Catalysts
- EU F-Gas Regulation phase-down:Mandatory refrigerant containment upgrades drive replacement demand for cryogenic valves and pressure regulators in industrial cold chains.
- Chemical synthesis expansion:Ammonia and methanol producers in China and Germany are installing high-pressure hydrogen distribution skids for feedstock flexibility.
- Metal fabrication reshoring:Oxy-fuel cutting and heat-treating operations in the United States and Poland are modernizing burner systems to meet tightening EPA and local emissions limits.
Market Restraints
- Stainless steel alloy costs:316L and duplex grades for hydrogen embrittlement resistance face price volatility tied to nickel supply concentration in Indonesia and Russia.
- Specialized machining capacity:Precision compressor component manufacturing concentrates in German and Japanese supplier networks, creating order backlogs.
- Electrification substitution:Industrial heat electrification mandates in Netherlands and Denmark jurisdictions directly displace gas burner installations in food processing and textile applications.
Strategic Opportunities
- Biogas upgrading equipment:Anaerobic digester operators in Italy and California require membrane separation and compression systems for grid injection compliance.
- Smart meter retrofit waves:Mechanical diaphragm replacement programs in UK and French utility territories create volume demand for ultrasonic and Coriolis metering technologies.
- CCUS integration:Carbon capture projects in Norway and Canada need specialized CO2 compression and pipeline injection equipment with supercritical phase handling capabilities.
Industry Challenges
- Hydrogen metallurgy expertise:Equipment engineers with hydrogen compatibility certification remain scarce relative to project pipeline demands.
- Multi-standard certification:Vendors must simultaneously satisfy ISO 19880, EU Pressure Equipment Directive, and emerging Chinese GB standards for hydrogen service, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Equipment Market |
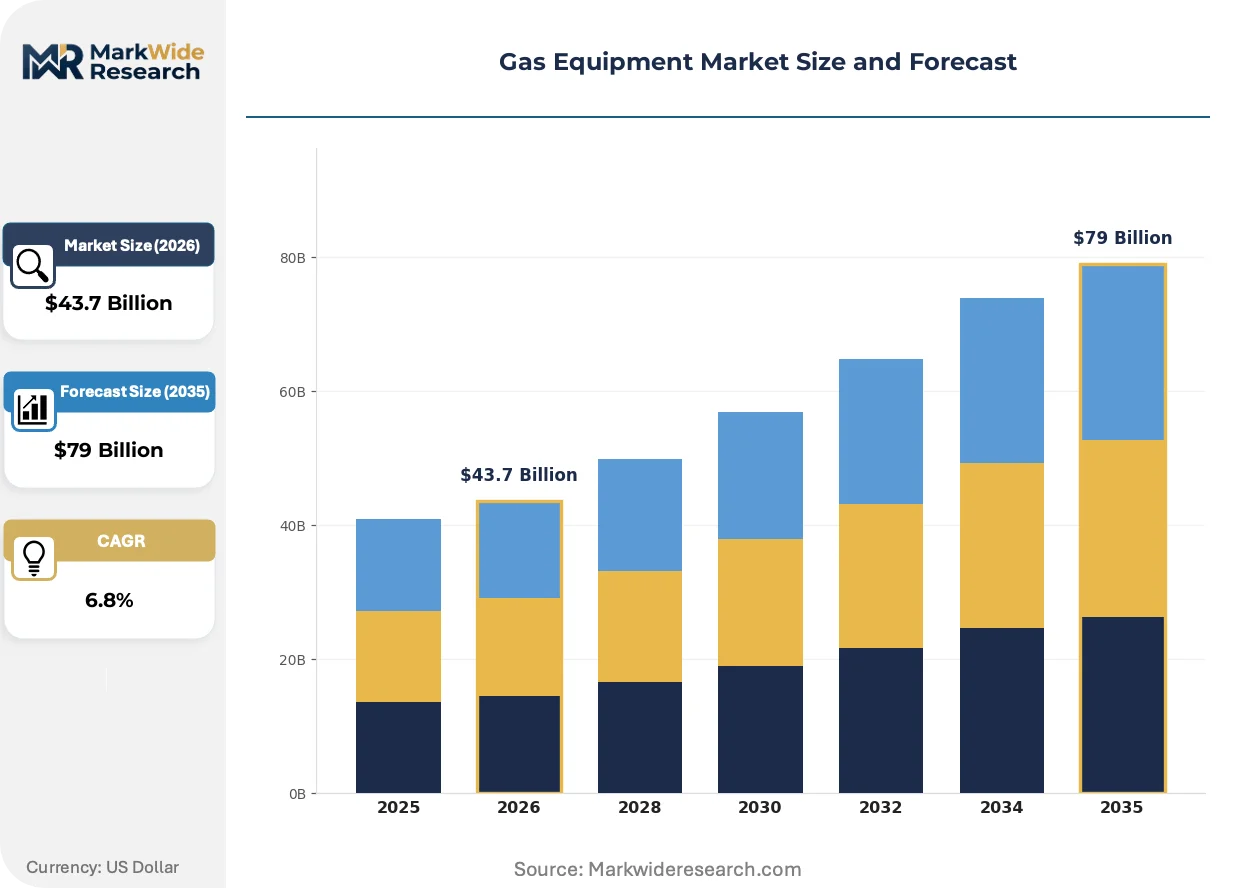
| Market Size in 2026 | $43.7 Billion |
| Market Size in 2035 | $79 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Burners, Regulators, Compressors, Valves Application: Residential Heating, Industrial Processes, Power Generation, Transportation End User: Utilities, Manufacturing, Hospitality, Residential Technology: Smart Meters, LPG Systems, Biogas Technology, Pressure Control Systems |
| Companies Covered | Linde plc, Air Liquide S.A., Air Products and Chemicals, Praxair Inc., Iwatani Corporation, Messer Group, Taiyo Nippon Sanso, GCE Holding, Matheson Tri-Gas, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Equipment Market Emerging Trajectories
Digital instrumentation and materials science advances are compressing equipment replacement cycles while expanding operational envelopes. Three developments are restructuring competitive requirements.
Ultrasonic flow meters with integrated pressure-temperature compensation are displacing mechanical diaphragm and rotary displacement units in custody transfer applications. European gas distribution utilities are specifying these systems for residential and commercial meter replacement programs. The shift eliminates moving parts, extends calibration intervals, and enables remote leak detection algorithms.
EU F-Gas Regulation phase-down schedules are forcing refrigerant system redesigns across cold chain logistics and industrial process cooling. Equipment manufacturers must certify new valve and regulator portfolios for low-global-warming-potential alternatives. German chemical processors and Dutch food manufacturers face the most compressed compliance timelines for stationary refrigeration assets.
Service contract unbundling is fragmenting traditional vendor-customer relationships in industrial gas supply. End-users in US metal fabrication and chemical sectors are separating equipment procurement from maintenance agreements, driving aftermarket parts specialists and independent service providers into burner and compressor overhaul markets. The pattern is most pronounced in Texas and Ohio manufacturing clusters where multi-vendor site standardization reduces single-source dependency.
Gas Equipment Market Segmentation
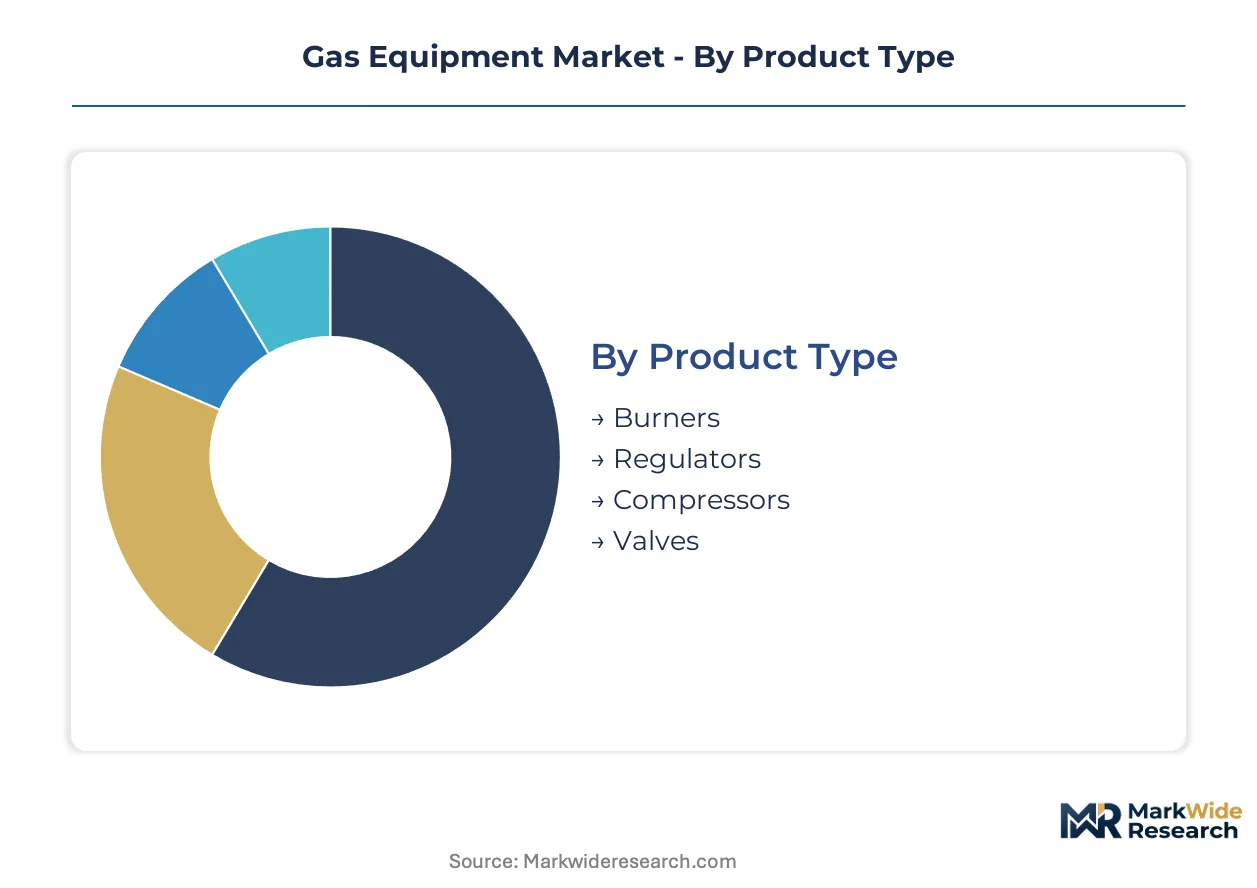
Equipment segmentation in gas infrastructure reveals divergent margin structures across mechanical versus electromechanical categories. Procurement patterns split between replacement cycles in mature utility networks and greenfield hydrogen-ready installations in industrial corridors.
Product Type:
Margin pools concentrate in precision-machined pressure control equipment where aftermarket service contracts extend revenue visibility.
- Burners:Combustion systems engineered for oxy-fuel cutting, heat-treating, and process heating applications with NOx emission controls. Metal fabrication reshoring in Poland and the United States drives replacement demand as EPA and local air quality mandates tighten. Volume leadership persists across industrial process heating despite electrification pressures in select jurisdictions.
- Compressors:Positive displacement and dynamic compression equipment operating up to 700 bar for hydrogen distribution and industrial gas custody transfer. Chemical synthesis expansion in Germany and China concentrates demand for high-pressure hydrogen feedstock flexibility. Precision machining requirements and captive service attachment sustain the deepest margin pools in this category.
- Regulators:Pressure reduction and control devices for distribution network stability.
- Valves:Isolation and control devices including cryogenic variants for cold chain logistics.
Compressors hold installed capacity. Burners is rotating up the share rankings.
Application:
Cost tier differentiation separates commodity residential hardware from specification-grade industrial systems requiring certification documentation.
- Industrial Processes:Equipment deployed across chemical synthesis, metal fabrication, and food processing with specialized material specifications for hydrogen embrittlement resistance. Ammonia and methanol producers in China and Germany anchor demand for high-pressure distribution skids. Tightening emissions frameworks accelerate replacement cycles beyond normal depreciation schedules.
- Residential Heating:Boilers, furnaces, and water heaters for single-family and multi-unit dwellings. European Union member states and select US jurisdictions mandate hydrogen-ready compatibility in new installations, forcing design modifications ahead of infrastructure rollout.
- Power Generation:Gas turbines and reciprocating engines for grid stability and distributed generation.
- Transportation:Vehicle fueling infrastructure and onboard storage systems for compressed natural gas and hydrogen mobility.
Industrial Processes holds installed capacity. Residential Heating is climbing the fastest.
End User:
Customer type determines procurement sophistication, with utilities leveraging scale for standardization while manufacturing segments prioritize uptime guarantees.
- Utilities:Gas distribution network operators managing residential, commercial, and industrial meter parks with regulatory custody transfer obligations. UK and French territories drive smart meter retrofit waves displacing mechanical diaphragm units with ultrasonic and Coriolis technologies.
- Manufacturing:Chemical processors, metal fabricators, and food manufacturers with process-critical gas supply requirements. Texas and Ohio manufacturing clusters exhibit pronounced service contract unbundling, separating equipment procurement from maintenance agreements.
- Hospitality:Commercial kitchens and lodging facilities with combustion equipment for heating and cooking applications.
- Residential:Individual homeowners and property managers sourcing replacement equipment through contractor channels.
Utilities holds installed capacity. Manufacturing is gaining share fastest.
Technology:
Supply concentration in precision machining networks constrains capacity for next-generation instrumentation and hydrogen-compatible systems.
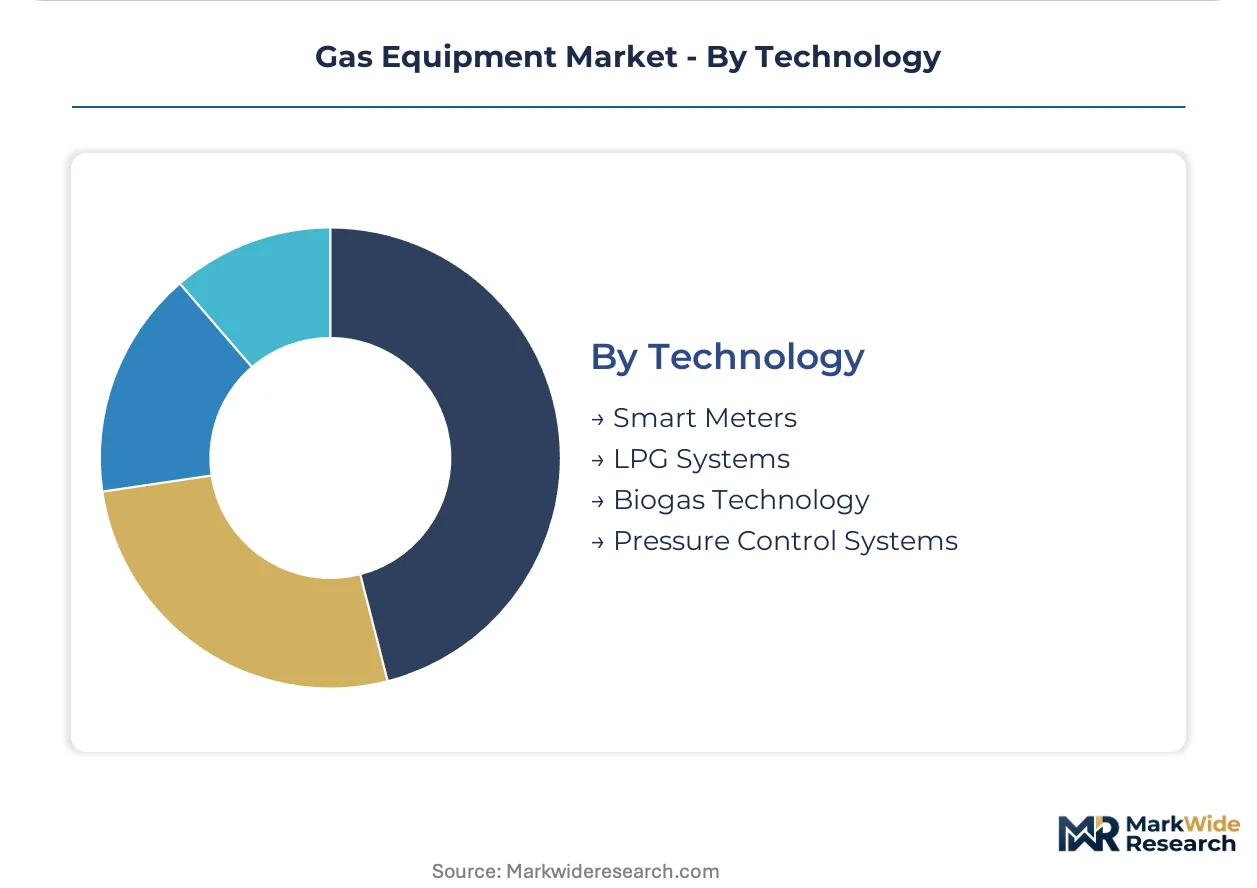
- Smart Meters:Ultrasonic and Coriolis flow measurement with integrated pressure-temperature compensation and remote leak detection algorithms. European gas distribution utilities specify these systems for residential and commercial replacement programs, eliminating moving parts and extending calibration intervals.
- Pressure Control Systems:Integrated valve, regulator, and sensor arrays for high-pressure hydrogen distribution and industrial process stability. German and Japanese supplier network concentration creates order backlogs as hydrogen infrastructure mandates compress certification timelines.
- LPG Systems:Liquefied petroleum gas storage, vaporization, and distribution equipment for residential and commercial applications.
- Biogas Technology:Anaerobic digester upgrading equipment including membrane separation and compression for grid injection compliance.
Pressure Control Systems holds installed capacity. Smart Meters is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision machining capacity for hydrogen-compatible components concentrates in German and Japanese supplier networks, creating order backlogs that constrain equipment availability across multiple demand centers. Hydrogen-ready infrastructure mandates in the European Union and select US jurisdictions are accelerating replacement cycles beyond normal depreciation schedules.
United States
Metal fabrication reshoring in Texas and Ohio drives burner system modernization as EPA emissions limits tighten. OSHA process safety management rules constrain design freedoms for high-pressure hydrogen distribution skids. The Gulf Coast petrochemical corridor anchors demand for cryogenic valve and regulator portfolios serving ammonia and methanol producers.
Germany
Chemical synthesis expansion in the Rhine-Ruhr and Ludwigshafen clusters concentrates demand for high-pressure hydrogen feedstock flexibility. EU F-Gas Regulation phase-down schedules force refrigerant system redesigns across industrial process cooling. Bavarian precision engineering networks supply compressor components facing capacity constraints from compressed certification timelines.
China
Ammonia and methanol producers in the Yangtze River Delta and Shandong Peninsula install high-pressure hydrogen distribution skids for feedstock flexibility. Emerging GB standards for hydrogen service extend vendor qualification timelines alongside ISO 19880 requirements. State-led hydrogen network investments concentrate equipment procurement in coastal industrial corridors.
Japan
Specialized machining capacity for precision compressor components faces order backlogs from hydrogen infrastructure project pipelines. METI hydrogen fueling standards and ISO 19880 convergence compress equipment certification windows. The Chubu and Kansai industrial belts anchor demand for pressure control systems serving semiconductor and chemical manufacturing.
United Kingdom
Utility smart meter retrofit programs displace mechanical diaphragm units with ultrasonic and Coriolis technologies across residential and commercial meter parks. OFGEM custody transfer obligations drive standardization in network stability equipment. The Midlands manufacturing cluster exhibits pronounced service contract unbundling, separating burner and compressor procurement from maintenance agreements.
Gas Equipment Market Vendor Landscape
Concentration sits with diversified industrial gas conglomerates possessing captive engineering capabilities and established certification pathways. The vendor base stratifies across three tiers: integrated gas suppliers with in-house equipment manufacturing, specialized component fabricators serving regional markets, and aftermarket service specialists exploiting unbundled maintenance contracts. Strategic moves center on hydrogen metallurgy capability acquisition and multi-standard certification acceleration to compress qualification timelines.
Among European-based industrial gas suppliers, Linde plc and Air Liquide S.A. exemplify the integrated conglomerate archetype with captive engineering networks spanning hydrogen distribution and cryogenic systems. Messer Group occupies a position within the regional specialist tier, competing through localized manufacturing and pressure control portfolio breadth. Iwatani Corporation represents the Asia-Pacific anchored player with exposure to Japanese hydrogen infrastructure standard-setting.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide S.A. |
| Air Products and Chemicals |
| Praxair Inc. |
| Iwatani Corporation |
| Messer Group |
| Taiyo Nippon Sanso |
| GCE Holding |
| Matheson Tri-Gas |
| Others |
Supply Flow & Price Mechanics
Twelve-to-eighteen-month order backlogs for precision-machined compressor components concentrate pricing power with German and Japanese supplier networks while forcing buyers into long-term offtake commitments. This lead-time environment rewards vendors with captive metallurgy capabilities and penalizes procurement teams dependent on spot-market alloy sourcing.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure across cryogenic valve and regulator portfolios, separating certified hydrogen-compatible systems from legacy natural gas equipment. Three-tier pricing stratifies across specification-grade industrial systems, utility-standard meter parks, and commodity residential hardware, with certification level and after-sales service bundling as primary differentiation drivers. Cost compression in stainless steel alloy inputs is intensifying because nickel supply volatility out of Indonesia feeds into 316L and duplex grade pricing. Manufacturing segments in Texas and Ohio exhibit the highest price sensitivity as service contract unbundling fragments traditional vendor relationships.
Supply Chain Analysis
Strait of Malacca transit routes for nickel ore and specialty alloy feedstocks underpin supply continuity for hydrogen embrittlement-resistant materials. Manufacturing concentration in Germany, Japan, and China draws from Indonesian nickel, Russian chromium, and Australian rare earth inputs, creating tariff exposure as trade policy shifts disrupt alloy cost structures. Distribution runs through regional equipment distributors serving utility meter parks and direct OEM channels for industrial process operators. Single-source vulnerability in Bavarian precision engineering networks constrains compressor component availability across multiple demand centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service contracts for burner and compressor overhaul are expanding faster than hardware procurement as Texas and Ohio manufacturing clusters unbundle maintenance agreements from equipment purchases. This service-attach dynamic restructures vendor economics toward recurring revenue streams.
For Market Incumbents: Fortify hydrogen metallurgy certification capabilities to compress ISO 19880 and EU Pressure Equipment Directive qualification timelines before emerging Chinese GB standards fragment compliance requirements. Backward integration into specialty alloy sourcing hedges nickel price volatility from Indonesian supply concentration. Capacity expansion in precision machining networks alleviates order backlogs threatening market share retention. For New Entrants and Emerging Players: Lead with biogas upgrading equipment for anaerobic digester operators in Italy and California, where membrane separation and compression systems face limited established vendor penetration. Target independent service providers in UK and French utility territories as channel partners for smart meter retrofit programs. Position around ultrasonic and Coriolis metering technologies displacing mechanical diaphragm units in custody transfer applications. For Investors and Strategic Acquirers: Long-term, this sits as a hydrogen infrastructure enabler play because EU member states and select US jurisdictions mandate hydrogen-ready compatibility ahead of network rollout. Acquisition candidates include precision machining specialists with ISO 19880 certification pathways and aftermarket service platforms with multi-vendor site standardization capabilities. Monitor hydrogen fueling station deployment rates as the inflection indicator for equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Metallurgy Certification Investment | ISO 19880 and EU Pressure Equipment Directive compliance compresses vendor qualification timelines ahead of infrastructure mandates. |
| Backward Integration into Alloy Sourcing | Captive supply of 316L and duplex grades hedges nickel price volatility from Indonesian supply concentration. |
| Aftermarket Service Platform Buildout | Independent overhaul capabilities capture unbundled maintenance contracts from Texas and Ohio manufacturing clusters. |
| Smart Meter Technology Partnership | Ultrasonic and Coriolis metering alliances penetrate UK and French utility retrofit programs displacing mechanical units. |
| Biogas Upgrading Equipment Launch | Membrane separation and compression systems address anaerobic digester grid injection compliance in Italy and California. |
Methodological Framework
A spread of perspectives from plant engineers at ammonia and methanol producers, procurement leads at metal fabrication facilities, aftermarket service heads at compressor overhaul shops, and regulatory affairs specialists at industrial gas suppliers converged on the working assumptions shaping this analysis. Primary fieldwork combined with secondary validation from SEC 10-K filings, customs and trade data, EU F-Gas Regulation implementation reports, and ISO 19880 certification databases. Bottom-up equipment shipment tallies and top-down hydrogen infrastructure investment forecasts were triangulated to anchor volume estimates.
Segmentation dimensions modeled include product type, application, end user, and technology tier across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, regulatory mandate timelines, and greenfield hydrogen infrastructure deployment trajectories. Hydrogen-ready compatibility requirements and smart meter retrofit program schedules served as industry-specific forecast inputs throughout the modeling period.
Forecasts assume regulatory continuity in EU F-Gas Regulation phase-down schedules and OSHA process safety management enforcement; material policy shifts would require re-modeling equipment replacement demand curves. Commodity price volatility in nickel and specialty alloys, plus certification timeline extensions from multi-standard convergence, constitute specific risk factors that could revise projections. Practitioners should keep alternative scenarios live as hydrogen infrastructure buildout rates and electrification mandate intensities evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
High-Purity Fluoropolymer Valves Market
Valves
Explosion Isolation Valves Market
Valves
Blasting Stemming Plugs Market
Valves
Oil Drain Valves Market
Valves
Global Solenoid Valves Market
Valves
Chemical Injection Metering Pumps and Valves Market
Valves
Servo Valves Market
Valves
Harmonic Dampers Market
Valves
Top Drive Systems Market
Valves
Low Voltage (LV) and Medium Voltage (MV) Switchgear Market
Valves
Global Valve Positioners Market
Valves
Europe Butterfly Valve Market
Valves
Degassing Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Valve Driver Market
Valves
Industrial Vacuum Valves Market