
 Global Marine Actuators and Valves Market | 2026-2036
Global Marine Actuators and Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Marine Actuators and Valves Market Intelligence
DNV GL type approval for critical flow control components is collapsing the supplier pool to highly specialized manufacturers. Rotork plc leverages its portfolio of certified electric actuators for complex naval and commercial vessels. Emerson Electric Co. differentiates through integrated automation platforms that combine valve control with vessel management. IMI plc sustains its position by focusing on severe service valves for high-pressure LNG carrier applications.
Marine actuators and valves are mechanical or electromechanical devices designed to regulate, direct, or control the flow of fluids in critical systems aboard maritime vessels and offshore structures. They are engineered from materials like duplex stainless steel to withstand saline corrosion and high operating pressures. Electric actuators are gaining share over hydraulic and pneumatic types, offering better integration with smart valve control systems. Shipbuilding and offshore platforms are dominant applications, while marine HVAC systems constitute a key specialized segment.
International Maritime Organization (IMO) regulations on emissions directly mandate new flow control systems for exhaust gas scrubbers and alternative fuels like LNG. Product standards are enforced through CE marking in Europe and type approvals from classification societies such as the American Bureau of Shipping (ABS) in the US. Consequently, future procurement decisions will prioritize vendors offering a fully certified component package that guarantees compliance across international waters.
Market Dynamics
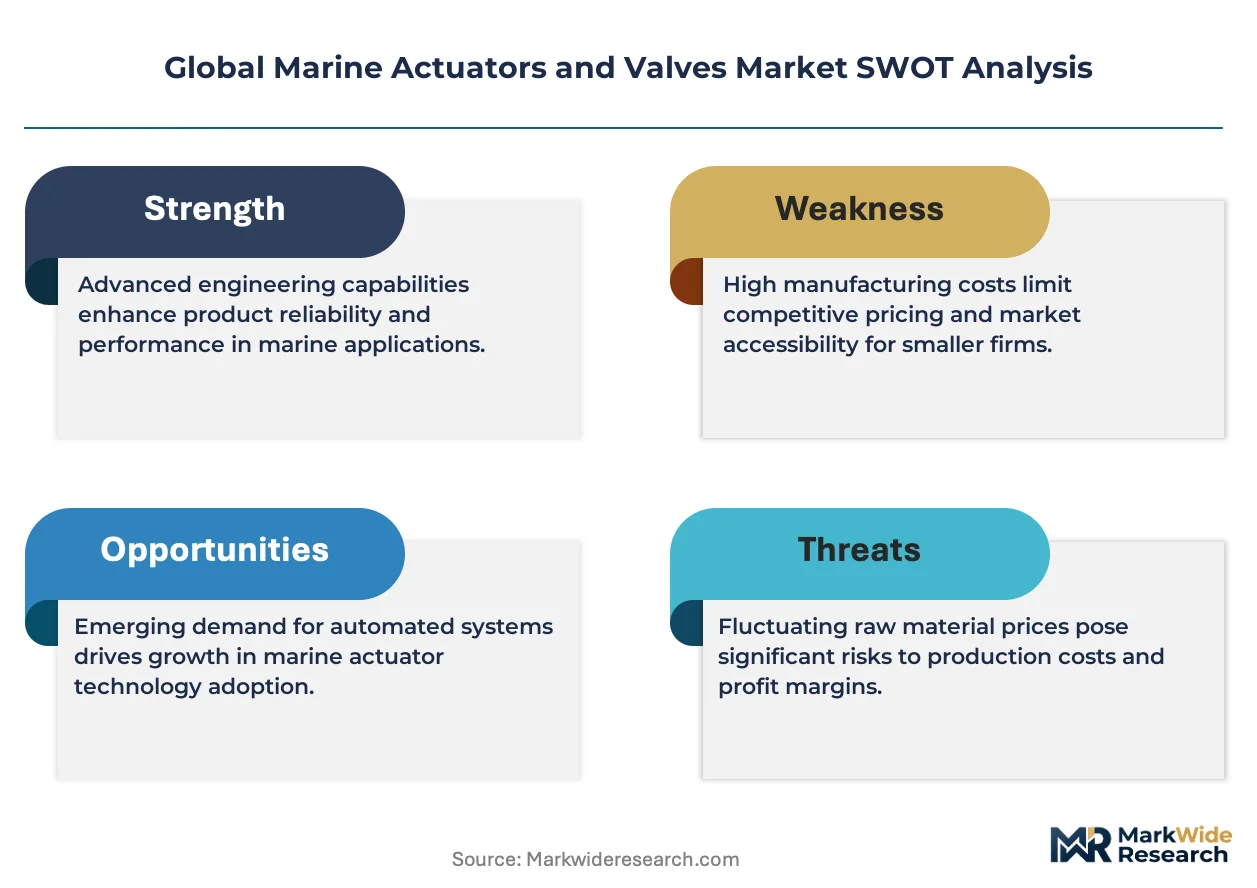
The central force shaping the market is the convergence of stringent emissions regulations and the requirement for type-approved components, which concentrates purchasing power toward vendors with certified, high-performance portfolios for complex vessels.
Growth Catalysts
- IMO Regulations:International Maritime Organization mandates for exhaust gas scrubbers and alternative fuel systems like LNG directly necessitate the installation of new, specialized valves and actuators on both new builds and retrofitted vessels.
- Offshore Exploration:Expansion of offshore energy platforms, particularly for oil, gas, and wind projects in regions like the North Sea and off the coast of Brazil, drives consumption of corrosion-resistant, high-pressure flow control systems.
- Electrification Trend:A transition from hydraulic and pneumatic actuators to electric variants offers superior integration with digital vessel management and smart valve control systems, improving precision, diagnostics, and energy efficiency.
Market Restraints
- Input Material Volatility:The cost and supply of critical raw materials, specifically duplex stainless steel and other nickel alloys required for corrosion resistance, are subject to significant price fluctuations, impacting manufacturer margins.
- High Certification Barriers:The rigorous and costly type-approval process from classification societies like DNV GL and the American Bureau of Shipping (ABS) creates a high barrier to entry, limiting the supplier pool.
- Long Replacement Cycles:Marine components are designed for extreme durability and long service life, resulting in slow replacement cycles on existing vessels unless driven by regulatory mandates or catastrophic failure.
Strategic Opportunities
- Alternative Fuel Systems:The shipping industry's pivot to alternative fuels such as ammonia, methanol, and hydrogen creates a significant opportunity for developing severe service valves and actuators engineered for cryogenic temperatures and high-toxicity containment.
- Digital Twin Integration:Developing actuators and valves with embedded sensors that feed data to a vessel's digital twin enables predictive maintenance, optimizing performance and reducing downtime for fleet operators. * Marine HVAC Retrofits: Upgrading aging marine HVAC systems to meet new energy efficiency standards provides a specialized niche for smaller, more precise electric actuators and control valves in the aftermarket segment.
Industry Challenges
- Installation Skill Gap:A shortage of technicians skilled in installing and servicing advanced electromechanical and automated valve systems, as opposed to traditional mechanical ones, presents an operational bottleneck for shipyards and service providers.
- Legacy System Integration:Ensuring seamless interoperability between new, digitally controlled actuators and older, analog vessel management and control platforms is a significant technical challenge during retrofitting projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Marine Actuators and Valves Market |
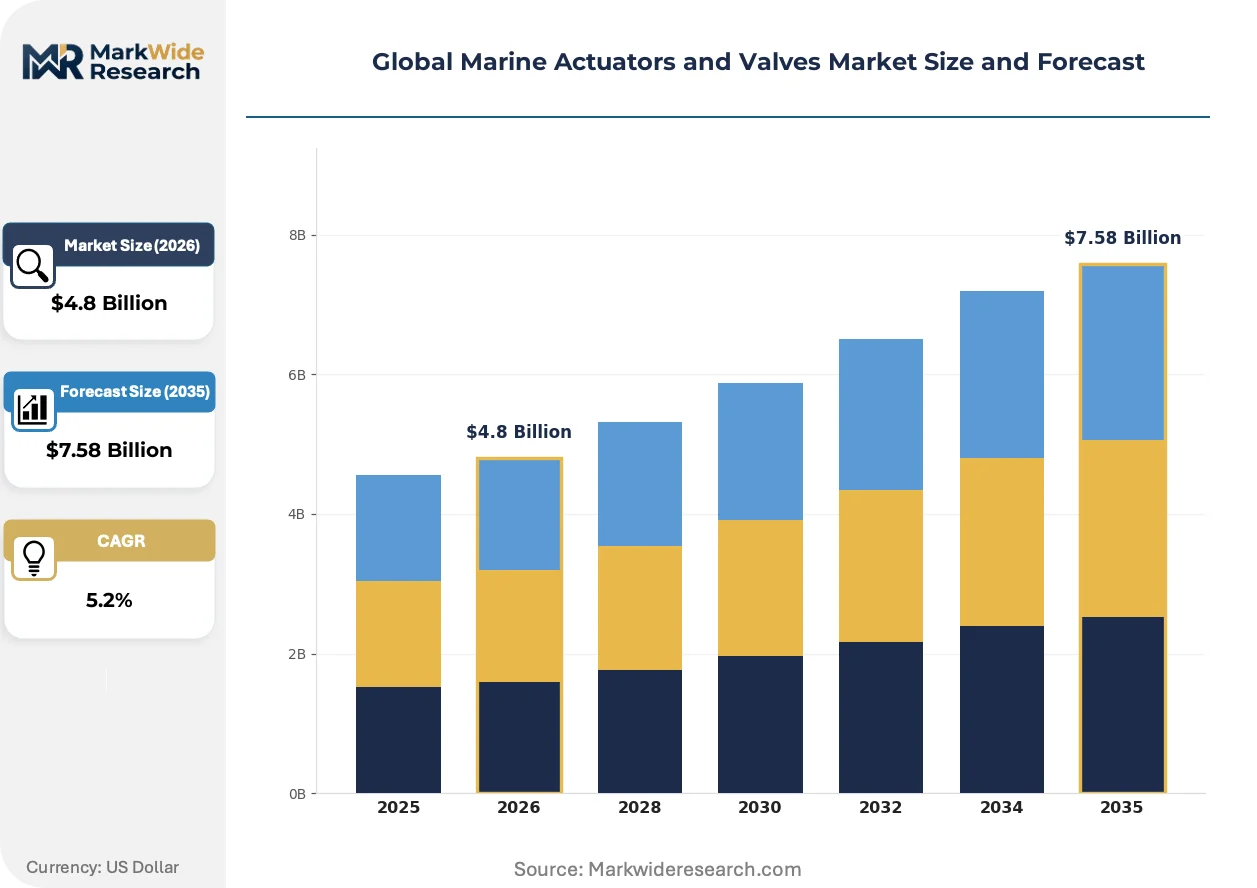
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.58 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Actuators, Pneumatic Actuators, Hydraulic Actuators, Ball Valves, Butterfly Valves, Globe Valves Technology: Electromechanical, Electrohydraulic, Smart Valve Control, Manual Override, Digital Modulation, Automatic Positioners Application: Shipbuilding, Offshore Platforms, Submarine Systems, Cargo Handling, Port Infrastructure, Marine HVAC End User: Shipyards, Marine Equipment Manufacturers, Port Authorities, Naval Defense, Offshore Service Providers |
| Companies Covered | Rotork plc, Curtiss-Wright Corporation, Emerson Electric Co., IMI plc, Alfa Laval AB, Flowserve Corporation, KITZ Corporation, Watts Water Technologies, Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Marine Actuators and Valves Market Strategic Shifts & Innovations
A fundamental shift toward intelligent, automated flow control systems defines the market's trajectory. This evolution prioritizes system-level compliance and operational efficiency over the performance of standalone mechanical components, favoring integrated solutions.
Smart valve control systems provide real-time diagnostics and remote operation capabilities through integration with a vessel's central network. Naval and complex commercial vessel operators are the primary adopters, seeking to improve system reliability and reduce onboard crew requirements. This integration is decomposing the traditional boundary between mechanical components and vessel-wide automation networks, creating a single, interconnected system.
The EU Green Deal imposes strict emissions reduction targets on the maritime sector, accelerating investment in cleaner technologies. This framework directly influences design by mandating efficient flow control for alternative fuels and exhaust gas treatment systems. New shipbuilding and retrofitting projects destined for European ports are most affected, with procurement decisions prioritizing components that guarantee compliance.
Demand patterns are evolving from sourcing individual valves and actuators to procuring complete, pre-certified flow control packages. This change disrupts the traditional component-level sales model, favoring vendors who can deliver a fully integrated and compliant system. This behavior is most visible in high-stakes projects such as LNG carriers and floating production storage and offloading (FPSO) units, particularly within South Korean shipyards.
Global Marine Actuators and Valves Market Segmentation
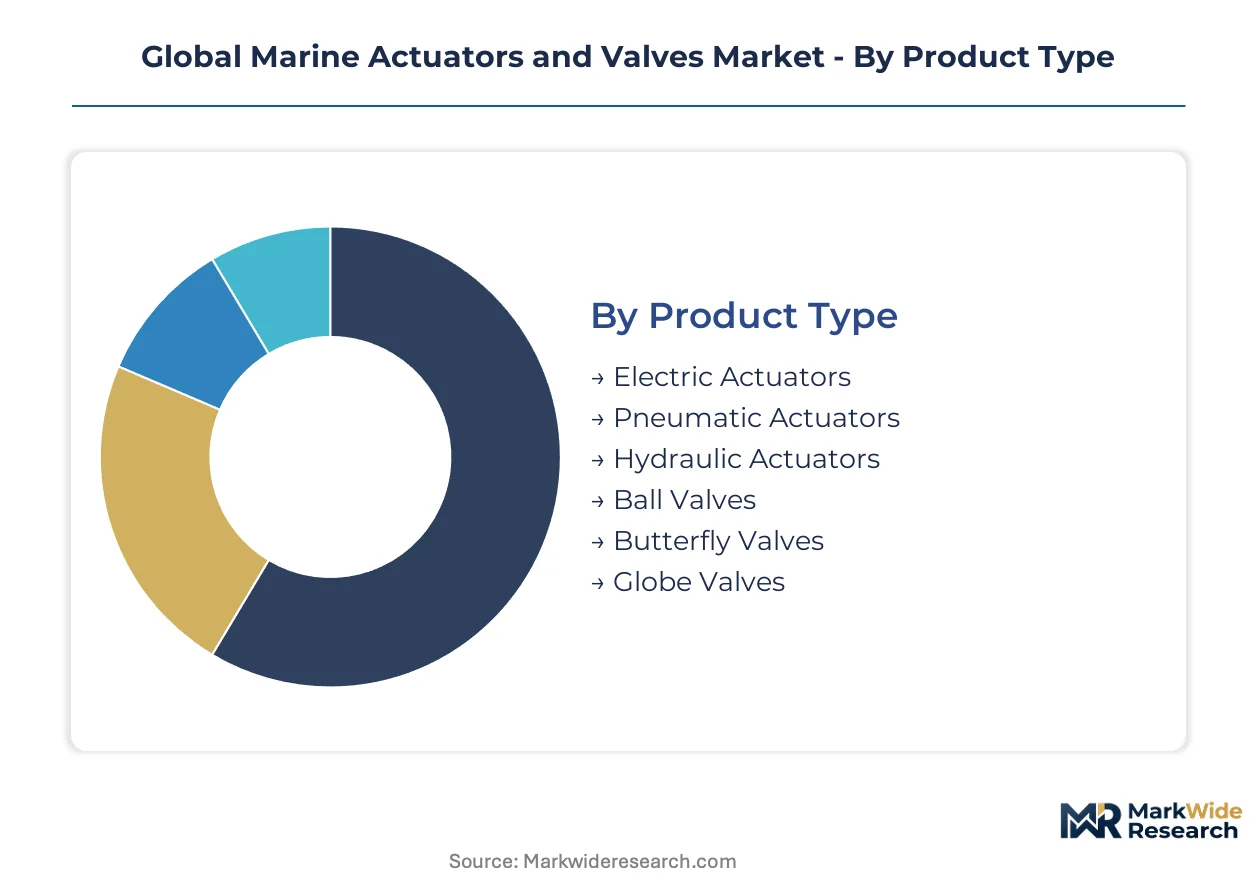
Market segmentation provides a granular view of the diverse requirements and purchasing behaviors within the marine actuators and valves industry. Analyzing these distinct categories helps stakeholders understand where specialized engineering, material science, and regulatory compliance converge to define product utility and market penetration.
Product Type:
The geographic distribution of marine actuator and valve demand often reflects regional shipbuilding specializations and stringent regulatory environments.
- Electric Actuators:These are electromechanical devices converting electrical energy into mechanical motion for precise valve operation. Demand concentrates in European and South Korean shipyards, driven by the need for better integration with smart vessel management systems and energy efficiency mandates.
- Ball Valves:These quarter-turn valves utilize a hollow, pivoting ball to control fluid flow, offering robust shut-off capabilities. Demand is particularly high in LNG carrier construction, especially in South Korea, due to their effectiveness in cryogenic applications and high-pressure containment.
- Pneumatic Actuators:Devices using compressed air to generate linear or rotary motion for valve control. They remain prevalent in older vessels and specific applications where electrical power is a constraint.
- Hydraulic Actuators:Components employing pressurized fluid to operate valves, delivering high force output. These are utilized in heavy-duty applications like steering gear and large cargo systems.
- Butterfly Valves:Quarter-turn valves regulating flow with a rotating disc. These are widely adopted for ballast water treatment systems due to their compact design and efficient operation.
- Globe Valves:Linear motion valves primarily used for throttling flow and regulating pressure. They are essential in steam and cooling water systems aboard commercial ships.
Electric Actuators hold the largest share; momentum sits with Ball Valves.
Technology:
The cost structure for marine valve technologies varies significantly, reflecting component complexity and integration requirements.
- Smart Valve Control:These integrated systems incorporate sensors and software for real-time monitoring and remote operation of valves. Adoption is accelerating in naval vessels and complex commercial ships, driven by needs for predictive maintenance and reduced onboard crew dependency.
- Electromechanical:Technologies combining electrical and mechanical principles to operate actuators, offering precise control and diagnostic capabilities. Demand is strong in new build projects requiring high accuracy and energy efficiency for propulsion and auxiliary systems.
- Electrohydraulic:Systems combining electrical signaling with hydraulic power for high-force valve actuation. These are employed in critical applications demanding both significant power and precision.
- Manual Override:Mechanical backup systems enabling local, human-powered operation of automated valves. This feature is a mandatory safety requirement across virtually all vessel types.
- Digital Modulation:Techniques using digital signals to finely adjust valve positions and flow rates. This enhances efficiency in engine cooling and fuel management systems.
- Automatic Positioners:Devices that receive a control signal and precisely adjust the valve actuator to the desired position. They are critical for maintaining stable process parameters in marine systems.
Smart Valve Control systems are expanding most quickly, transforming operational paradigms.
Application:
Specific marine applications dictate distinct requirements for flow control systems, influencing material selection and certification standards.
- Shipbuilding:This involves the integration of actuators and valves into new vessel construction across all types, from tankers to cruise ships. Demand is concentrated in major shipbuilding nations such as South Korea, driven by global trade expansion and fleet renewal.
- Offshore Platforms:This segment covers the deployment of flow control components on oil and gas rigs, floating production storage and offloading (FPSO) units, and offshore wind installations. Consumption is high in the North Sea and off the coast of Brazil, fueled by ongoing energy exploration and production activities.
- Submarine Systems:Highly specialized valves and actuators engineered for extreme pressure, stealth requirements, and long-term reliability. This application primarily serves naval defense sectors globally.
- Cargo Handling:Flow control systems for loading, unloading, and transferring various liquid and bulk cargoes. These are essential for chemical tankers, LNG carriers, and bulk carriers.
- Port Infrastructure:Utilization of valves and actuators in onshore facilities for bunkering, water treatment, and industrial processes. This supports the broader maritime logistics ecosystem.
- Marine HVAC:Components for regulating air conditioning, heating, and ventilation systems aboard vessels. These are critical for crew comfort and the cooling of sensitive equipment.
Shipbuilding projects currently represent the largest segment, with Offshore Platforms demonstrating significant expansion.
End User:
Different end-user segments exhibit unique procurement patterns and technical specifications for marine flow control solutions.
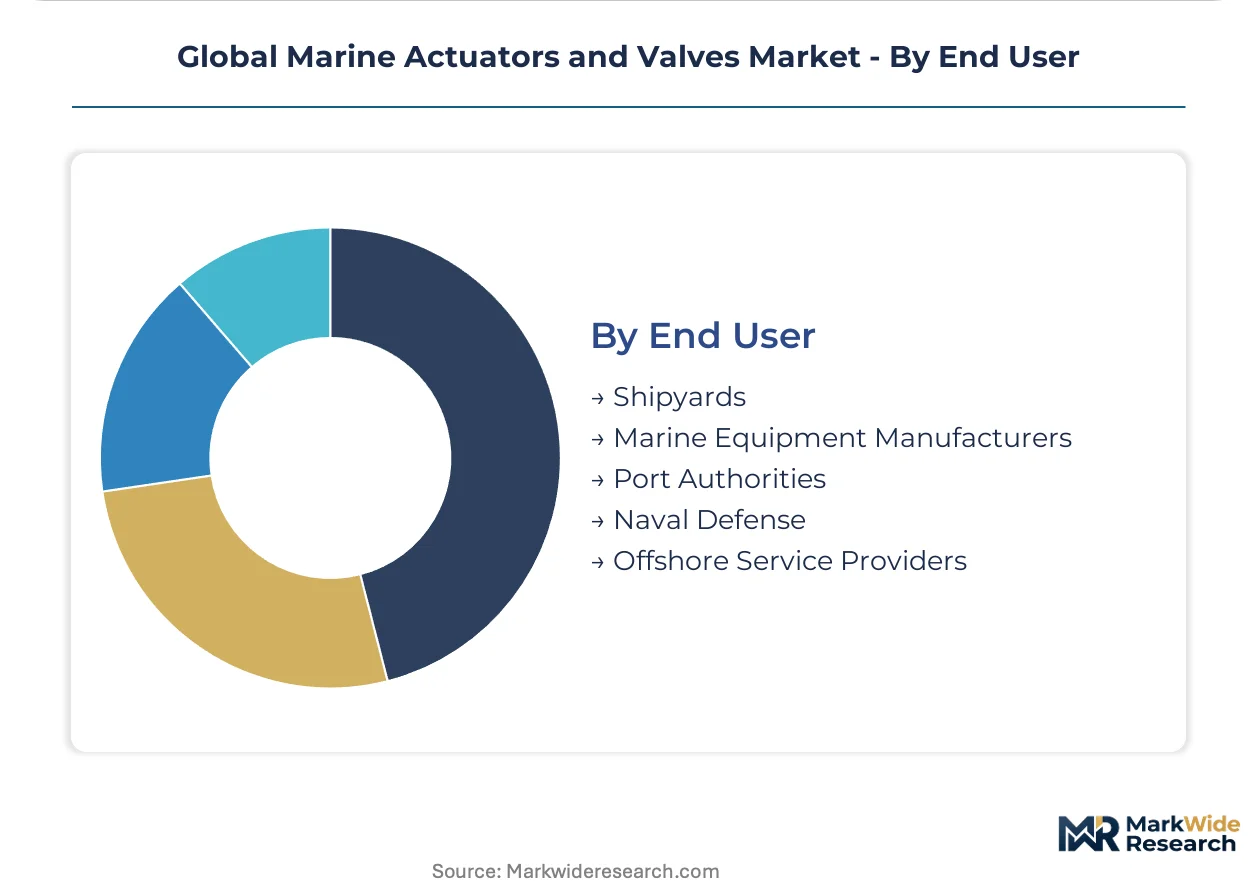
- Shipyards:These are the primary purchasers of actuators and valves for integration into new vessel builds and major retrofitting projects. Procurement decisions are heavily influenced by classification society requirements and demanding delivery timelines for complex vessels.
- Offshore Service Providers:Operators and maintenance companies for offshore oil, gas, and wind installations. They prioritize durable, corrosion-resistant components for continuous operation in harsh marine environments, often requiring specialized certifications.
- Marine Equipment Manufacturers:Companies that integrate actuators and valves into larger systems like pumps, engines, or exhaust gas scrubbers. They often seek pre-certified components for their own product offerings.
- Port Authorities:Entities responsible for managing port operations, including infrastructure development and environmental compliance. They procure valves for water management, bunkering facilities, and safety systems.
- Naval Defense:Military organizations requiring highly specialized, robust, and often custom-designed flow control systems. Performance under extreme conditions, reliability, and security are paramount for these applications.
Shipyards remain the dominant end-user category, while Offshore Service Providers are increasingly influential buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer-archetype concentration for marine actuators and valves centers on shipyards and offshore operators requiring fully certified component packages for complex vessels. Demand patterns are shaped by regional shipbuilding specializations, offshore energy projects, and varying regulatory frameworks. Each major maritime hub presents unique procurement drivers and compliance standards for flow control systems.
South Korea
South Korean shipyards drive demand for marine actuators and valves, particularly for LNG carrier construction. Stringent classification society requirements from DNV GL and ABS influence procurement decisions for these specialized vessels. Major shipbuilding hubs like Ulsan and Geoje concentrate specialized component integration into new builds. This region prioritizes vendors offering pre-certified, high-performance solutions.
United States
Offshore exploration and naval defense projects fuel demand for high-performance flow control systems in the United States. American Bureau of Shipping (ABS) type approvals are crucial for compliance in these critical applications. The Gulf Coast region, including Houston, serves as a hub for offshore equipment suppliers and service providers. US Coast Guard regulations also mandate specific safety and operational standards.
Germany
European energy efficiency mandates and the EU Green Deal shape demand for advanced marine flow control in Germany. CE marking and DNV GL certifications ensure product conformity for new builds and retrofits across the commercial fleet. Northern German maritime clusters around Hamburg focus on complex commercial vessel outfitting and technological innovation. This region emphasizes environmental compliance and operational efficiency.
Brazil
Deepwater oil and gas extraction projects off the coast of Brazil require robust, corrosion-resistant actuators and valves. Brazilian Navy regulations and local content policies influence procurement for offshore platforms. The Rio de Janeiro area supports extensive offshore energy production and related services. This market segment prioritizes durability and resilience in harsh marine environments.
Netherlands
North Sea offshore wind and specialized vessel construction projects create demand for marine actuators and valves in the Netherlands. Compliance with EU Green Deal directives and DNV GL standards is essential for maritime operations. Rotterdam's port and maritime technology centers are key for advanced flow control solutions. The focus here is on sustainable and highly efficient systems.
Global Marine Actuators and Valves Market Key Industry Players
Player mix skews toward specialized component manufacturers capable of meeting rigorous certification requirements. The market exhibits consolidation around vendors offering integrated, high-performance portfolios for complex marine applications. Strategic archetypes include specialized component providers, integrated automation platform developers, and severe service valve experts. Companies pursue technology integration and strategic partnerships to deliver comprehensive, certified solutions.
Specialists in critical flow control components, Rotork plc and Emerson Electric Co. exemplify the shift towards integrated and certified solutions. Rotork plc, a UK-based company, anchors the electric actuator segment with its certified portfolio for naval and commercial vessels, reflecting a focus on precision and reliability. The US-based Emerson Electric Co. represents providers of integrated automation platforms that combine valve control with broader vessel management systems, emphasizing systemic efficiency. IMI plc, also a UK-based entity, occupies a position among manufacturers focusing on severe service valves for high-pressure LNG carrier applications, highlighting durability in extreme conditions.
| Leading Market Players |
|---|
| Rotork plc |
| Curtiss-Wright Corporation |
| Emerson Electric Co. |
| IMI plc |
| Alfa Laval AB |
| Flowserve Corporation |
| KITZ Corporation |
| Watts Water Technologies |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
DNV GL type approval gates both supply qualification and price differentiation for marine actuators and valves. This rigorous process limits the vendor pool, impacting market dynamics.
Pricing Analysis
Cost-plus contract patterns, often indexed to duplex stainless steel and nickel alloy prices, define procurement for critical marine actuators. Price differentiation stems from certification levels, such as ABS or DNV GL approval, and customization for severe service applications. Pricing pressure arises from fluctuating raw material costs and intense competition among certified suppliers. Naval defense and LNG carrier projects exhibit lower price sensitivity, while standard shipbuilding projects are more cost-conscious.
Supply Chain Analysis
Specialized foundries and manufacturing hubs in South Korea, Germany, and the United States underpin the supply chain for marine actuators and valves. Raw material dependencies center on duplex stainless steel, nickel alloys, and specialized seals. Single-source vulnerability for certified components poses a structural supply chain risk. Distribution runs through direct OEM channels and specialized maritime equipment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marine actuators and valves market is experiencing high-growth disruption, driven by stringent IMO emissions regulations and the accelerating electrification trend. This necessitates strategic adjustments across the value chain.
For Market Incumbents: Secure DNV GL and ABS type approvals for advanced alternative fuel systems to counter emerging specialist threats. Consolidate market share by acquiring smaller certified manufacturers, particularly those with expertise in cryogenic or high-toxicity applications. Invest in R&D for predictive maintenance capabilities to differentiate against commoditization. Control key distribution channels to mitigate margin pressure from new entrants.
For New Entrants and Emerging Players: Differentiate on specialized niches, targeting the marine HVAC retrofit market with precise, energy-efficient electric actuators. Focus on developing components for emerging alternative fuels like ammonia and hydrogen, where certification requirements are still evolving. Penetrate smaller, regional shipyards or offshore wind projects that require tailored, compliant solutions. Offer integrated digital twin capabilities as a go-to-market angle for operational efficiency.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upwards across specialized certification and R&D for severe service applications, indicating long-term market viability. Acquisition targets should be mid-cap specialists with established type approvals and proprietary material science expertise in duplex stainless steel. Focus on companies capable of integrating smart valve control systems into broader vessel management platforms. The signal to watch is the pace of new IMO regulatory mandates for alternative fuels.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | Secure DNV GL and ABS approvals for new alternative fuel valve designs. |
| Digital Integration | Embed sensors into actuators for real-time data flow to vessel digital twins. |
| Material Science R&D | Develop advanced corrosion-resistant alloys for high-pressure LNG applications. |
| Strategic Partnerships | Collaborate with automation providers for integrated vessel management systems. |
| Niche Acquisition | Acquire specialists in cryogenic valve technology for hydrogen or ammonia carriers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with shipyard procurement managers, offshore platform engineers, marine equipment manufacturers, and naval defense specialists. Secondary validation involved reviewing DNV GL and ABS type approval databases, IMO regulatory documents, and shipbuilding association reports. This approach combined qualitative insights with quantitative data. Bottom-up data aggregation and top-down market sizing ensured comprehensive coverage.
The forecast modeling utilized a robust analytical framework across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional shipbuilding clusters. Compound annual growth rates were derived from historical trends and projected regulatory impacts. Key inputs included new vessel build orders and offshore energy project pipelines.
The analysis sits within stated boundaries; outcomes outside current IMO regulatory trajectories or major geopolitical shifts would require recalibration. Forecasts reflect assumptions regarding material supply stability and certification process consistency. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
3-Way Pilot Operated Directional Control Valves Market
Valves
Air Heated Vaporizer Market
Valves
Cathodic Protection Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Backflow Preventers Market
Valves
Harmonic Dampers Market
Valves
Explosion Isolation Valves Market
Valves
Valve Driver Market
Valves
Emergency Shut Down Valves (ESDV) Market
Valves
Sandblast Valves Market
Valves
Global Gas Pressure Regulator Market
Valves
Rupture Discs Market
Valves
Global Automotive Valves Market
Valves
Ball Valves Market
Valves
Pipeline Pigging Equipment Market
Valves
Global Compression Packing Market