
 Chemical Injection Pump Market | 2026-2036
Chemical Injection Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Injection Pump Market Outlook
Midstream pipeline operators is collapsing as the fastest-expanding buyer archetype for high-pressure chemical injection systems. Grundfos Holding A/S leverages its electromechanical diaphragm platforms to anchor Nordic and North Sea offshore contracts. Milton Roy Company dominates API 675-compliant metering pumps for sour service applications in Permian Basin operations. LEWA GmbH specializes in hermetically sealed hydraulically actuated diaphragm designs that sustain zero-emission compliance in European petrochemical corridors.
A chemical injection pump is a precision positive-displacement device engineered to deliver metered volumes of treatment chemicals against elevated system pressures, typically achieving accuracy within one percent of setpoint across variable viscosity fluids. These units inject corrosion inhibitors, scale suppressants, and biocides directly into process streams, wellbores, or transmission lines to protect infrastructure integrity and maintain production throughput. Diaphragm pumps command the largest installed base due to their leak-free operation and compatibility with hazardous chemistries, while peristaltic configurations capture expanding share in low-pressure water treatment skids where elastomer tube replacement simplifies maintenance. Electromechanical technology leads value generation through variable-frequency drive integration, though pneumatic systems retain footholds in explosive atmosphere zones where spark containment governs specification.
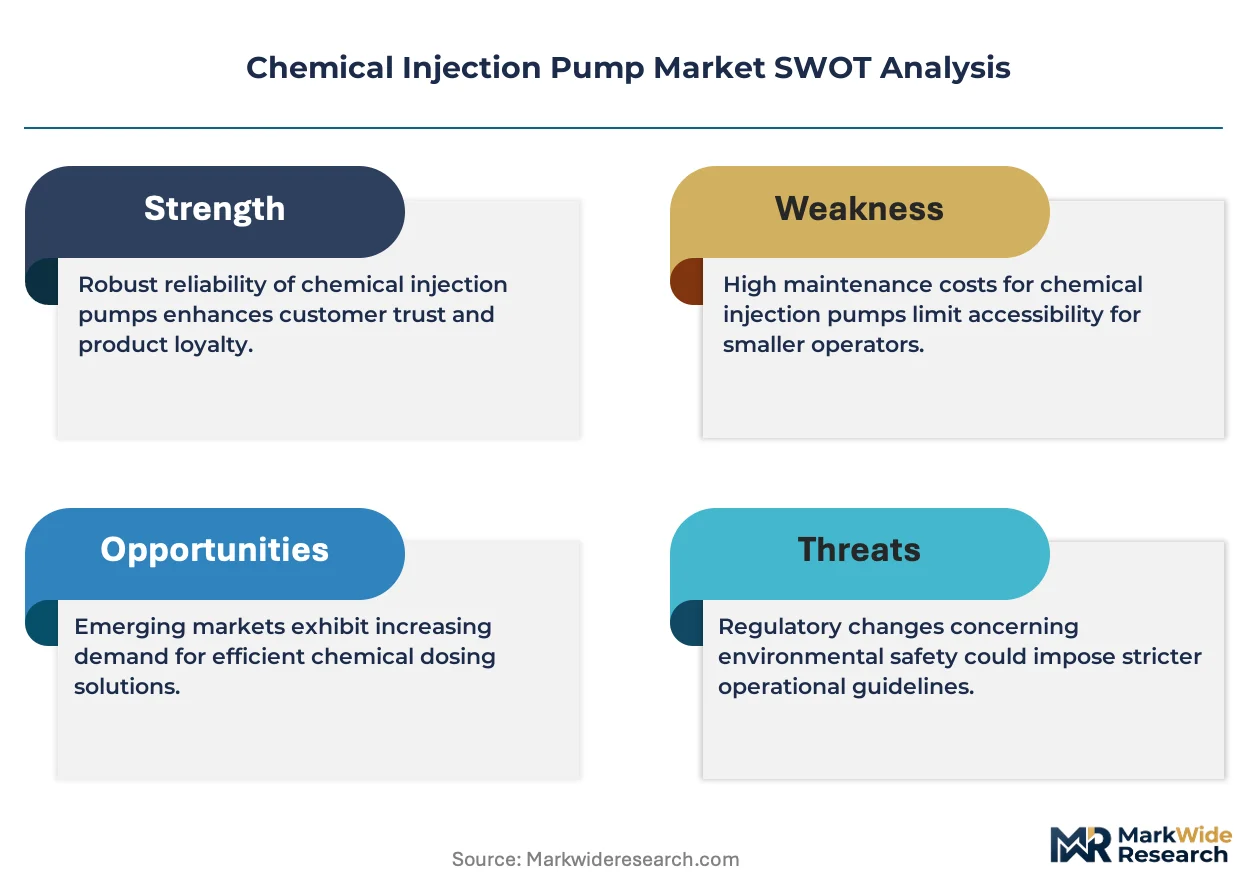
The EPA enforces Clean Water Act effluent limits that mandate precise coagulant and disinfectant dosing at municipal and industrial outfalls, directly elevating specification requirements for calibration-stable pump technologies. API 675 and ISO 13709 standards govern pulsation control and materials selection in hydrocarbon service, creating compliance barriers for uncertified suppliers. OSHA Process Safety Management rules compound these pressures by requiring documented chemical inventory controls that favor automated injection over manual batch treatment. Stakeholders must weigh electromechanical upgrade cycles against pneumatic retrofit economics as electrification mandates tighten across upstream and midstream operating jurisdictions.
Market Dynamics
Midstream pipeline operators are collapsing as the fastest-expanding buyer archetype for high-pressure chemical injection systems, compressing procurement cycles and forcing pump manufacturers to reconfigure service networks around linear infrastructure corridors rather than wellhead clusters.
Growth Catalysts
- EPA effluent guidelines:Tightening Clean Water Act limits mandate precise coagulant dosing at industrial outfalls, elevating specification requirements for calibration-stable metering technologies across municipal and manufacturing discharge points.
- Shale basin water volumes:Produced water treatment in Texas and North Dakota shale formations requires continuous chemical injection for corrosion inhibition and scale suppression, anchoring replacement demand for diaphragm pump fleets.
- Electromechanical variable-frequency drives:Integration of VFD-controlled diaphragm actuation delivers one-percent setpoint accuracy across variable viscosity fluids, displacing pneumatic systems in electrification-mandated operating jurisdictions.
Market Restraints
- Specialized elastomer supply concentration:Fluoropolymer diaphragm and seal production concentrates among limited specialty chemical suppliers, exposing pump OEMs to fluorinated material availability constraints and price volatility.
- API 675 certification barriers:Compliance costs for pulsation control and materials selection standards create structural exclusion for uncertified suppliers attempting entry into sour service hydrocarbon applications.
- Peristaltic tube replacement economics:Low-pressure water treatment skids favor elastomer tube pumps where simplified maintenance competes against diaphragm precision in non-critical dosing applications.
Strategic Opportunities
- European petrochemical corridor electrification:Zero-emission mandates in EU industrial zones favor hermetically sealed hydraulically actuated diaphragm designs that eliminate fugitive emissions from chemical injection operations.
- Offshore platform unmanned conversion:Remote monitoring and predictive maintenance integration enables chemical injection system deployment on unmanned installations, reducing helicopter logistics burden in North Sea operations.
- Carbon capture solvent injection:Emerging amine and novel solvent circulation requirements in post-combustion capture facilities create specification demand for corrosion-resistant high-pressure metering pumps.
Industry Challenges
- Diaphragm material science talent scarcity:Compound formulation expertise for chemically resistant elastomer and thermoplastic diaphragms concentrates among retiring specialists, constraining OEM product development velocity.
- Legacy pneumatic infrastructure retrofit complexity:Explosive atmosphere zones with existing air distribution networks resist electromechanical conversion due to spark containment re-certification timelines and capital replacement cycles.
- ISO 13709 materials traceability documentation:Hydrocarbon service pump procurement now requires full mill certificate chains and NACE-compliant metallurgy verification, extending order-to-delivery intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Injection Pump Market |
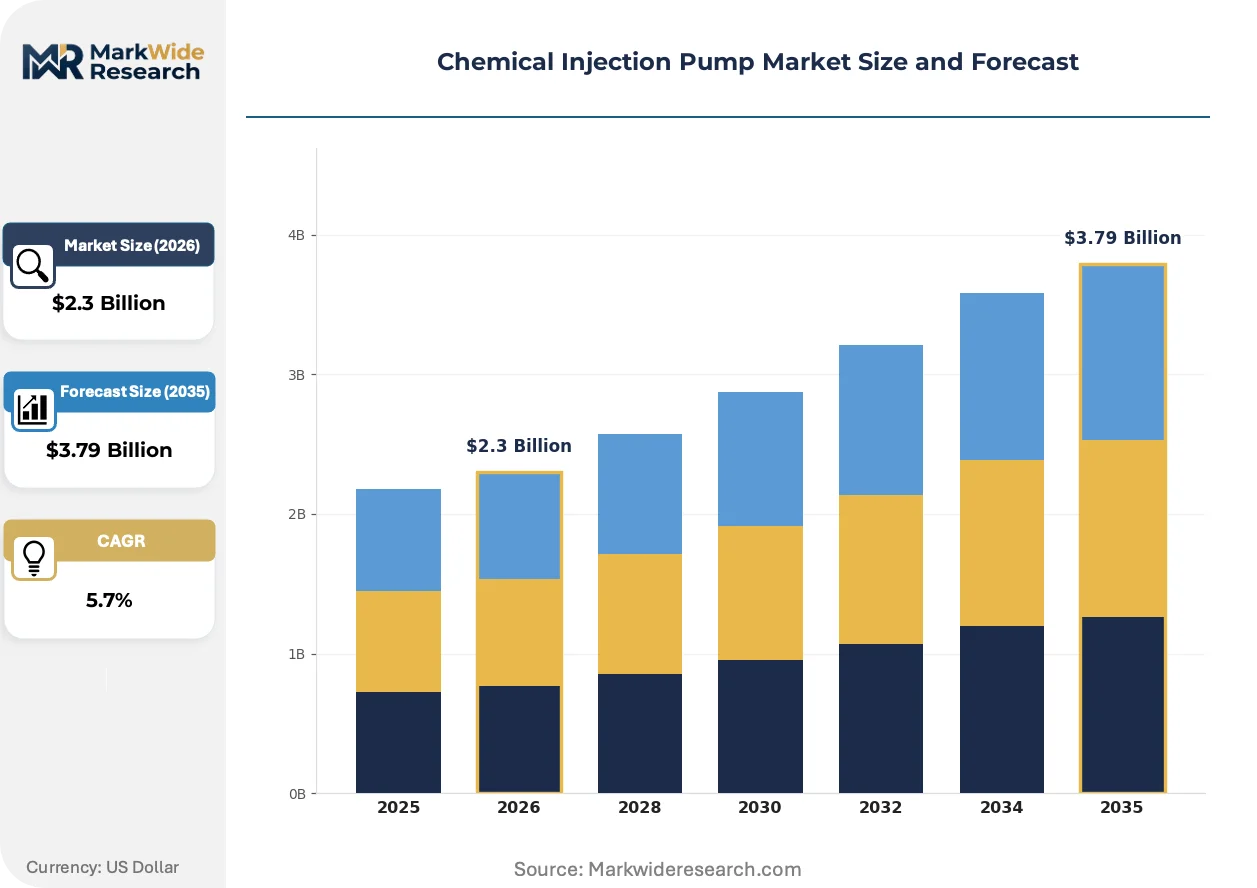
| Market Size in 2026 | $2.3 Billion |
| Market Size in 2035 | $3.79 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Peristaltic Pumps, Gear Pumps, Piston Pumps Application: Oil & Gas, Water Treatment, Chemical Processing, Agriculture End User: Municipalities, Industrial Facilities, Agriculture Operations, Oil Refineries Technology: Electromechanical Systems, Hydraulic Systems, Pneumatic Systems, Manual Systems |
| Companies Covered | Grundfos Holding A/S, Milton Roy Company, ProMinent GmbH, LEWA GmbH, Idex Corporation, SEKO S.p.A., SPX FLOW, Inc., Dover Corporation, Graco Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Injection Pump Market Strategic Shifts
Electrification mandates and emission containment requirements are compressing technology adoption cycles, forcing simultaneous evolution in pump actuation architectures, materials science, and field service delivery models.
Smart diaphragm pump controllers with embedded pressure and flow sensors are miniaturizing into compact skid-mounted packages that integrate variable-frequency drive electronics directly at the pump head. Permian Basin operators are adopting these integrated electromechanical units at replacement rates exceeding conventional pneumatic retrofits. The technology is miniaturizing field footprint requirements while eliminating external control panel infrastructure, compressing installation costs and enabling deployment in space-constrained offshore modules.
REACH authorization procedures for per- and polyfluoroalkyl substances are accelerating fluoropolymer diaphragm material substitution programs across European chemical processing facilities. Industrial pump OEMs face reformulation deadlines for seals and diaphragms that contact hazardous chemistries. The regulation is forcing accelerated qualification of alternative elastomer compounds in pharmaceutical and specialty chemical injection applications, with German and Dutch petrochemical corridors leading compliance investment.
After-sales service unbundling is fragmenting traditional pump procurement relationships as midstream operators separate hardware acquisition from calibration and spare parts logistics. Third-party maintenance providers are capturing recurring revenue streams through remote diagnostics subscriptions and diaphragm replacement scheduling. This pattern concentrates most visibly in Texas and North Dakota shale basins where produced water treatment uptime penalties exceed capital equipment depreciation costs.
Chemical Injection Pump Market Segmentation
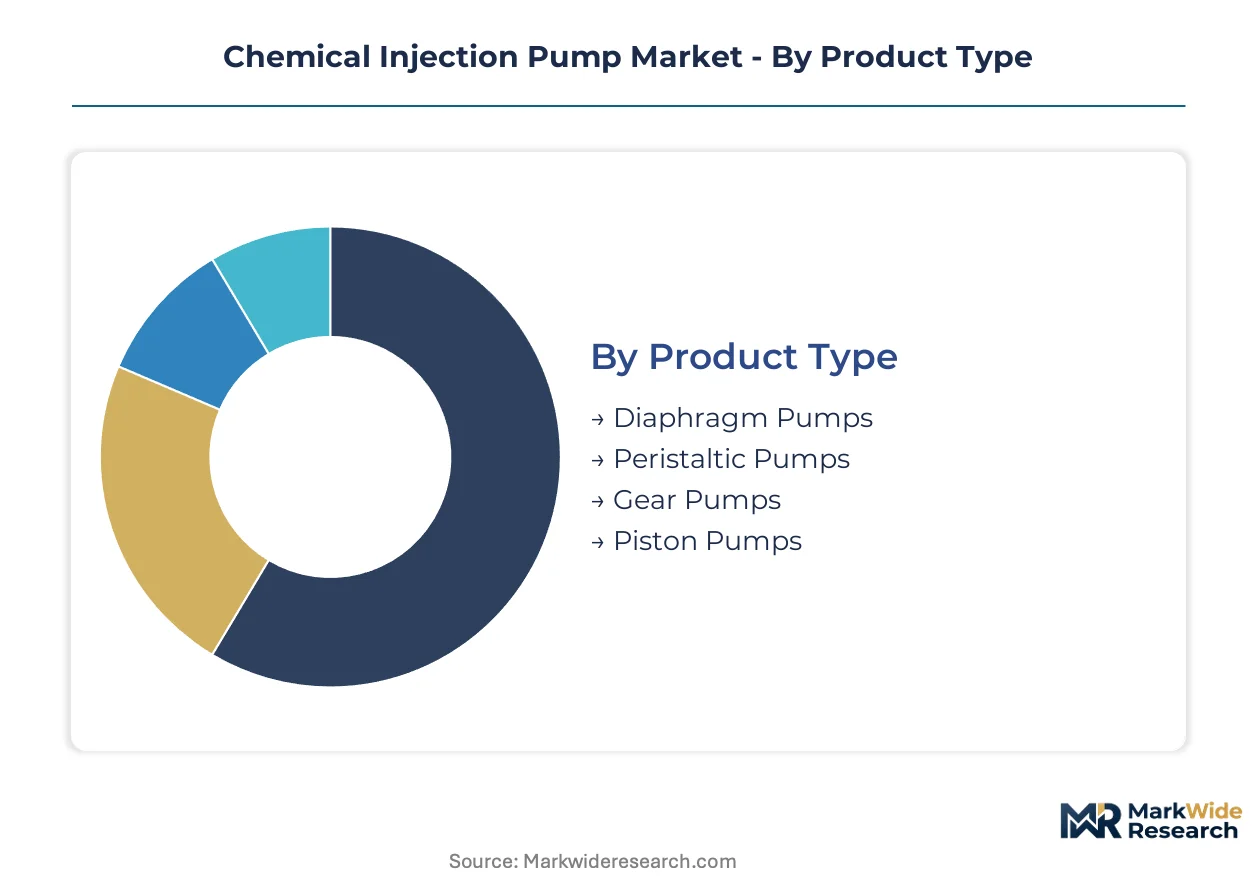
Chemical injection pump procurement diverges sharply across end-use contexts, with hydrocarbon service demanding API-certified precision while water treatment prioritizes maintenance accessibility. Segmentation reveals how regulatory stringency and fluid chemistry dictate technology selection across operating environments.
Product Type:
EPA effluent guidelines and API 675 compliance requirements create divergent specification pathways, with leak-free operation mandates favoring certain architectures over others in hazardous chemical service.
- Diaphragm Pumps:Hermetically sealed positive-displacement mechanisms isolate process fluid from pump internals through elastomer or thermoplastic diaphragms, achieving zero-emission containment. Demand concentrates in Texas and North Dakota shale basins where produced water corrosion inhibition requires continuous injection against high wellhead pressures. API 675 pulsation control standards govern specification for sour service applications, elevating certified suppliers over commodity alternatives.
- Peristaltic Pumps:Roller-actuated elastomer tubes compress and release to generate suction and discharge, eliminating valves and seals from fluid contact. Water treatment skids in municipal and industrial discharge facilities favor this architecture where tube replacement simplifies maintenance and low-pressure dosing tolerates reduced precision. REACH fluoropolymer restrictions are accelerating alternative elastomer qualification in European pharmaceutical applications.
- Gear Pumps:Meshing rotors deliver continuous flow with minimal pulsation, suited for viscous polymer and lubricant injection where shear sensitivity matters. Chemical processing facilities deploy these for additive metering in non-hazardous service.
- Piston Pumps:Reciprocating plungers achieve ultra-high pressure capability for enhanced oil recovery chemical injection, though seal maintenance requirements limit adoption in unmanned installations.
Established volume favors Diaphragm Pumps; emerging adoption favors Peristaltic Pumps.
Application:
Cost tier differentiation separates capital-intensive hydrocarbon infrastructure from operational-expense-driven municipal systems, with procurement authority residing in distinct organizational functions.
- Oil & Gas:Upstream production, midstream transmission, and downstream refining operations inject corrosion inhibitors, scale suppressants, and hydrate preventers across wellbores, flowlines, and process units. Midstream pipeline operators are collapsing procurement cycles for high-pressure systems as linear infrastructure expansion outpaces wellhead cluster growth. OSHA Process Safety Management documentation requirements favor automated injection over manual batch treatment.
- Water Treatment:Coagulant, disinfectant, and pH adjustment chemical dosing at municipal outfalls and industrial discharge points demands calibration-stable metering. Tightening Clean Water Act limits elevate specification requirements for precision pumps with embedded flow verification.
- Chemical Processing:Specialty chemical and pharmaceutical manufacturing requires inert material construction and CIP/SIP compatibility for aggressive solvent and reagent handling.
- Agriculture:Fertigation and pesticide injection systems prioritize cost minimization and field durability over laboratory-grade precision, with pneumatic systems retaining foothold in remote locations lacking electrical infrastructure.
Capital deployment intensity peaks in Oil & Gas; replacement frequency accelerates in Water Treatment.
End User:
Customer type determines specification authority, with municipal procurement governed by public bidding protocols while industrial facilities retain technical discretion.
- Municipalities:Public water and wastewater treatment authorities operate under EPA consent decree timelines and ratepayer-funded capital programs, favoring proven technologies with extensive reference installations.
- Industrial Facilities:Manufacturing discharge compliance drives coagulant and neutralization chemical injection, with site engineers prioritizing uptime guarantees over initial capital cost.
- Agriculture Operations:Irrigation district and large-scale farming cooperatives specify pumps for chemigation systems, with seasonal usage patterns favoring simple maintenance over automation sophistication.
- Oil Refineries:Downstream process units inject anti-foulants and pH control chemicals into crude distillation and hydrotreater circuits, with NACE-compliant metallurgy mandatory for sour service.
Specification complexity concentrates in Oil Refineries; standardization pressure dominates Municipalities.
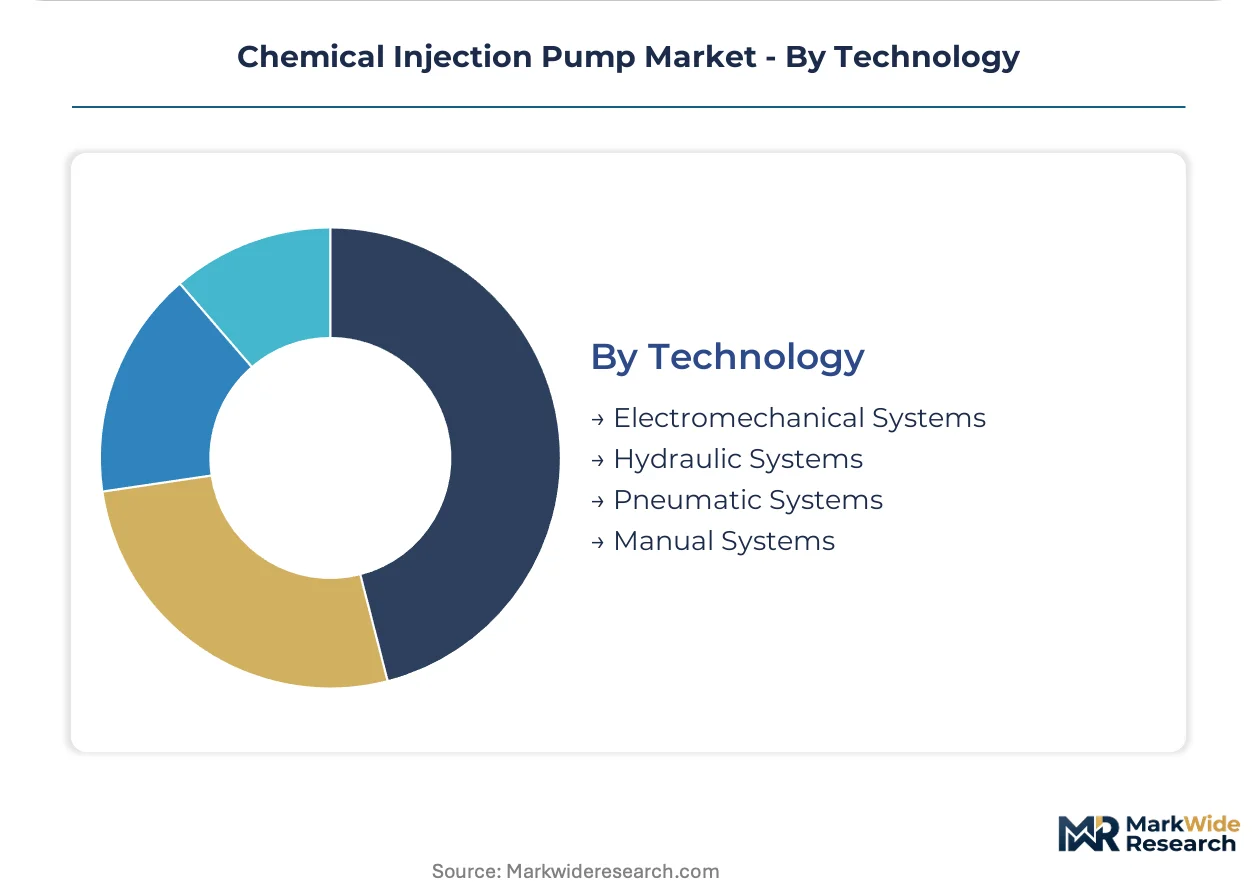
Technology:
Actuation architecture selection reflects electrification mandate penetration and explosive atmosphere classification across operating jurisdictions.
- Electromechanical Systems:Variable-frequency drive integration delivers one-percent setpoint accuracy with direct digital control interface. Permian Basin operators are adopting integrated electromechanical units at replacement rates exceeding pneumatic retrofits as electrification mandates tighten.
- Hydraulic Systems:Oil-actuated diaphragm designs achieve hermetic sealing for zero-emission compliance in EU petrochemical corridors facing fugitive emission regulations.
- Pneumatic Systems:Compressed air actuation retains mandatory deployment in Class I Division 1 explosive atmosphere zones where spark containment governs specification, though air distribution infrastructure maintenance burdens operational cost.
- Manual Systems:Hand-operated metering persists in remote locations and backup applications where power availability is unreliable and injection rates are intermittent.
Electrification tailwinds favor Electromechanical Systems; hazardous classification preserves Pneumatic Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty diaphragm manufacturing concentrates among German and Danish pump OEMs, while North American shale operators drive replacement demand through produced water treatment expansion. Regulatory divergence between EPA effluent mandates and EU fluoropolymer restrictions creates distinct specification pathways across jurisdictions.
United States
Permian Basin and Bakken shale formations anchor demand for high-pressure corrosion inhibition systems as produced water volumes climb. EPA Clean Water Act enforcement tightens coagulant dosing precision at municipal and industrial outfalls. Houston and Midland-Odessa industrial clusters concentrate midstream pipeline procurement for linear infrastructure chemical injection.
Germany
Ruhr Valley petrochemical corridors and Bavarian specialty chemical parks sustain specification demand for hermetically sealed hydraulic diaphragm designs. REACH authorization timelines for per- and polyfluoroalkyl substances accelerate fluoropolymer diaphragm substitution programs. LEWA GmbH anchors zero-emission compliance engineering from its Leonberg headquarters.
China
State-backed shale gas development in Sichuan and Xinjiang basins expands sour service chemical injection requirements. MEE effluent discharge standards tighten industrial wastewater treatment dosing accuracy mandates. Yangtze River Delta chemical processing clusters drive API 675-certified pump procurement for refinery anti-foulant injection.
Saudi Arabia
Aramco offshore and onshore expansion programs sustain demand for unmanned platform chemical injection systems in high-H2S environments. The country's national oil company procurement standards mandate NACE-compliant metallurgy and full materials traceability documentation. Eastern Province industrial cities anchor downstream refinery chemical dosing infrastructure deployment.
Norway
North Sea platform electrification and unmanned conversion programs favor remote-monitored electromechanical diaphragm systems. Norwegian Petroleum Safety Authority emission containment rules elevate hermetic sealing specifications. Stavanger and Bergen subsea engineering clusters concentrate offshore chemical injection system integration expertise.
Chemical Injection Pump Market Competitive Environment
Concentration sits with electromechanical diaphragm specialists and hydraulic zero-emission engineering houses. The vendor base stratifies across three tiers: integrated industrial conglomerates with broad pump portfolios, mid-scale specialists with API certification depth, and regional fabricators serving non-critical water treatment applications. Dominant competitive moves include backward integration into fluoropolymer diaphragm compound formulation and predictive maintenance service unbundling to capture recurring calibration revenue.
Among European electromechanical and hydraulic specialists, Grundfos Holding A/S, LEWA GmbH, and Milton Roy Company occupy positions that exemplify divergent technology anchoring strategies. Grundfos represents the integrated electromechanical platform approach with variable-frequency drive integration. LEWA sits within the hermetic hydraulic tier serving EU zero-emission mandates. Milton Roy anchors API 675-certified sour service specification in North American hydrocarbon corridors. SEKO S.p.A. and ProMinent GmbH exemplify mid-scale specialists with concentrated dosing precision expertise.
| Leading Market Players |
|---|
| Grundfos Holding A/S |
| Milton Roy Company |
| ProMinent GmbH |
| LEWA GmbH |
| Idex Corporation |
| SEKO S.p.A. |
| SPX FLOW, Inc. |
| Dover Corporation |
| Graco Inc |
| Others |
Value Chain & Pricing Dynamics
Twenty-six-week diaphragm compound lead times concentrate pricing power among German and Danish OEMs with captive elastomer formulation capabilities, while spot-market fluoropolymer buyers absorb volatility from REACH authorization timelines. This inventory compression elevates contract premiums for API 675-certified systems against commodity alternatives.
Pricing Analysis
API 675 compliance dictates the pricing tier structure across hydrocarbon service applications, separating NACE-certified metallurgy packages from standard carbon steel configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with after-sales calibration bundling capturing recurring revenue in Texas shale basins. Cost compression in peristaltic tube replacement economics intensifies as water treatment skids prioritize maintenance accessibility over precision. Municipal procurement committees exhibit highest price sensitivity due to ratepayer-funded capital constraints, while Aramco offshore specifications tolerate premium positioning for unmanned platform reliability.
Supply Chain Analysis
Diaphragm inventory cycles stretching to half-year durations expose pump OEMs to fluoropolymer availability constraints from Belgian and Japanese specialty chemical suppliers. Manufacturing gravity centers on Germany, Denmark, and the United States for electromechanical platform assembly, with Chinese machining feeds supplying cast housings and drive components. Supply chain risk concentrates in single-source fluorinated elastomer compounders facing ECHA authorization deadlines. Distribution runs through authorized service networks in Midland-Odessa and Houston corridors, compressing field response times against third-party maintenance unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical injection pump penetration sits at early-cycle expansion as produced water volumes in Permian and Bakken formations force continuous treatment infrastructure deployment ahead of wellhead decline curves.
For Market Incumbents: Compound defensive positioning through backward integration into diaphragm compound formulation, securing supply continuity against REACH fluoropolymer restrictions. Anchor service network density in linear midstream corridors where procurement cycles are collapsing. Certification investment in ISO 13709 materials traceability documentation extends order-to-delivery intervals but excludes uncertified competitors from sour service awards. For New Entrants and Emerging Players: Predictive maintenance software subscriptions represent the service-layer gap where incumbents under-serve midstream operators separating hardware from calibration logistics. Target water treatment skids in municipal discharge compliance where EPA consent decree timelines compress procurement authority. Lead with elastomer tube replacement scheduling platforms that monetize uptime guarantees over capital equipment margins. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because emission containment mandates and electrification requirements are accelerating replacement cycles beyond historical depreciation schedules. Acquisition targets center on mid-scale specialists with API 675 certification depth and hermetic hydraulic engineering capabilities. The signal to watch is fluoropolymer diaphragm substitution program announcements from European petrochemical operators facing reformulation deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diaphragm Compounding | Captive fluoropolymer supply secures margin stability against ECHA authorization volatility. |
| Remote Monitoring Platform Deployment | Unmanned North Sea installations demand predictive maintenance integration for helicopter logistics reduction. |
| API 675 Certification Investment | Pulsation control compliance creates structural exclusion for uncertified suppliers in Permian sour service. |
| Service Network Unbundling | Third-party calibration subscriptions capture recurring revenue from midstream operators prioritizing uptime. |
| Hermetic Hydraulic Design Expansion | Zero-emission EU mandates favor oil-actuated diaphragm architectures in Ruhr Valley corridors. |
Study Parameters
Operator-level perspectives from maintenance directors at Permian Basin producers, midstream pipeline procurement leads, and aftermarket service heads anchored the qualitative base for this analysis. Secondary validation drew from EPA enforcement databases, API certification registries, and SEC filings from listed pump OEMs. Bottom-up unit deployment estimates triangulated against top-down hydrocarbon production forecasts across the analysis window.
Sensitivity analysis tested forecast robustness against variable electrification mandate penetration rates and fluoropolymer substitution timelines. Segmentation modeling spanned product architecture, actuation technology, end-use application, and regional regulatory cluster throughout the projection horizon. CAGR derivation incorporated replacement cycle compression from produced water volume expansion and emission containment retrofit requirements.
Underlying assumptions cover stable EPA effluent enforcement intensity and REACH authorization procedural timelines, with deviation risk concentrated in fluorinated material availability disruptions and midstream capital allocation shifts. Revision becomes warranted when electrification mandate adoption crosses threshold penetration in explosive atmosphere zones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Industrial Pump Control Panels Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Pump Over Tanks Market
Pumps and Control Devices
Membrane Pump Market
Pumps and Control Devices
Split Casing Pump Market
Pumps and Control Devices
Progressive Cavity Pump (PCP) Market
Pumps and Control Devices
Industrial Oil Filter Machine Market
Pumps and Control Devices
High Power Air Pump Market
Pumps and Control Devices
Electrostatic Spraying System Market
Pumps and Control Devices
Peristaltic Pumps Market
Pumps and Control Devices
Lubrication Pump Systems Market
Pumps and Control Devices
Flow Back Equipment Market
Pumps and Control Devices
Industrial Vacuum Pumps Market
Pumps and Control Devices
Heating Tape Market
Pumps and Control Devices
Melt & Gear Pump Market
Pumps and Control Devices
Spiral Classifier Market