
 Global Industrial Thermostatic Control Valves Market | 2026-2036
Global Industrial Thermostatic Control Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Global Industrial Thermostatic Control Valves Market Outlook
Power generation utilities are redrawing procurement priorities toward predictive-maintenance-ready valve assemblies, while chemical processors retain legacy mechanical specifications. Danfoss A/S leverages its Nordic district heating installed base to extend aftermarket service contracts across Northern Europe. IMI plc specializes in severe-service trim designs that sustain premium positioning in refinery hydrogen cracking units. Honeywell International Inc. competes through integrated building-automation bundles that anchor thermostat valve sales within larger HVAC retrofit packages.
Industrial thermostatic control valves are self-acting temperature regulators that modulate fluid flow through expansion-element actuation, typically within set-point ranges of 0°C to 350°C, to maintain process or ambient thermal stability without external power. These devices serve primary industrial purposes in steam tracing, engine cooling, heat exchanger regulation, and compressor anti-surge protection where precise thermal equilibrium prevents equipment damage or energy waste. Two-way valves dominate installed volume in legacy HVAC and light manufacturing settings where simple on-off thermal regulation suffices, but three-way valves capture expanding share in combined heat-and-power networks requiring blended stream control. Pneumatic technology retains structural importance in oil and gas explosion-risk zones where electrical actuation faces intrinsic safety constraints, while electric actuation grows fastest in smart-building applications demanding BACnet-integrated feedback loops.
EPA emissions standards for industrial boilers and the EU F-Gas Regulation are tightening thermal-efficiency mandates that force valve replacement cycles shorter than historical fifteen-year norms, while China's GB standards on industrial energy consumption impose parallel efficiency verification requirements on domestic process plants. The International Organization for Standardization maintains ISO 23551-1 for thermostatic gas valves and ISO 7005-1 for flange compatibility, frameworks that shape cross-border procurement specifications and vendor qualification protocols. Stakeholders must monitor divergence between regional efficiency certification timelines to avoid stranded inventory in multi-country project pipelines.
Market Dynamics
Refrigerant-phase-down mandates across multiple jurisdictions are compressing replacement cycles for legacy valve infrastructure, forcing simultaneous capital deployment across process industries that historically staggered equipment refresh timelines.
Growth Catalysts
- EU F-Gas Regulation:The refrigerant-phase-down schedule compels European chemical processors to retrofit thermal management systems ahead of historical replacement intervals, creating concentrated demand spikes in Germany and the Netherlands.
- Three-way pneumatic valve adoption:Reactor temperature stability requirements in hydrogen cracking and polymerization units are driving specification upgrades from two-way mechanical designs to blended-stream control architectures.
- District heating retrofits:Nordic and Baltic municipal utilities are expanding procurement of self-acting temperature regulators for network balancing, leveraging existing Danfoss and IMI installed bases for aftermarket service extensions.
Market Restraints
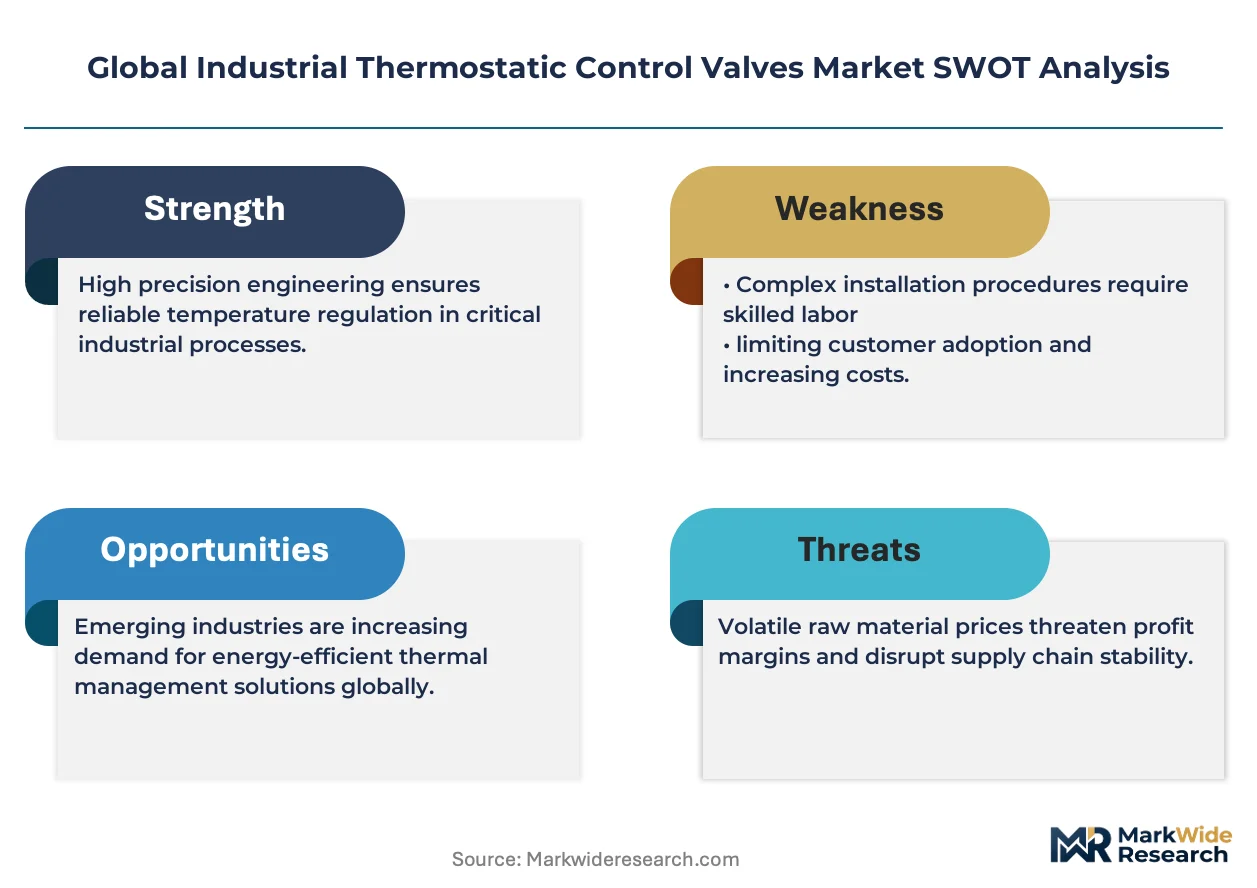
- Copper and nickel alloy volatility:Expansion-element housings and severe-service trim materials face input cost swings that compress OEM margins and deter long-term fixed-price contracting.
- Specialized foundry concentration:Precision casting capacity for high-temperature valve bodies clusters in German and Chinese supplier networks, creating geographic supply risk for multi-site project developers.
- Mechanical-to-electric substitution ceiling:Explosion-risk zones in oil and gas extraction retain pneumatic actuation requirements that block full conversion to smart-building electric architectures, fragmenting R&D investment.
Strategic Opportunities
- India process plant efficiency mandates:Bureau of Energy Efficiency standards on industrial thermal systems create first-mover positioning for valve OEMs establishing local assembly partnerships ahead of domestic content requirements.
- Digital twin integration:Convergence of BACnet-integrated valve feedback with predictive maintenance platforms enables outcome-based service contracting for power generation utilities.
- China dual carbon alignment:GB standards on industrial energy consumption verification reward thermostatic control valve deployments with measurable thermal efficiency gains, opening state-backed financing channels.
Industry Challenges
- Cross-standard certification timelines:ISO 23551-1 thermostatic gas valve testing and EU F-Gas compliance verification operate on divergent approval schedules, stranding inventory in multi-country project pipelines.
- Legacy system integration friction:Smart-building electric actuation retrofits face BACnet protocol mismatches with 1990s-era building management systems, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Industrial Thermostatic Control Valves Market |
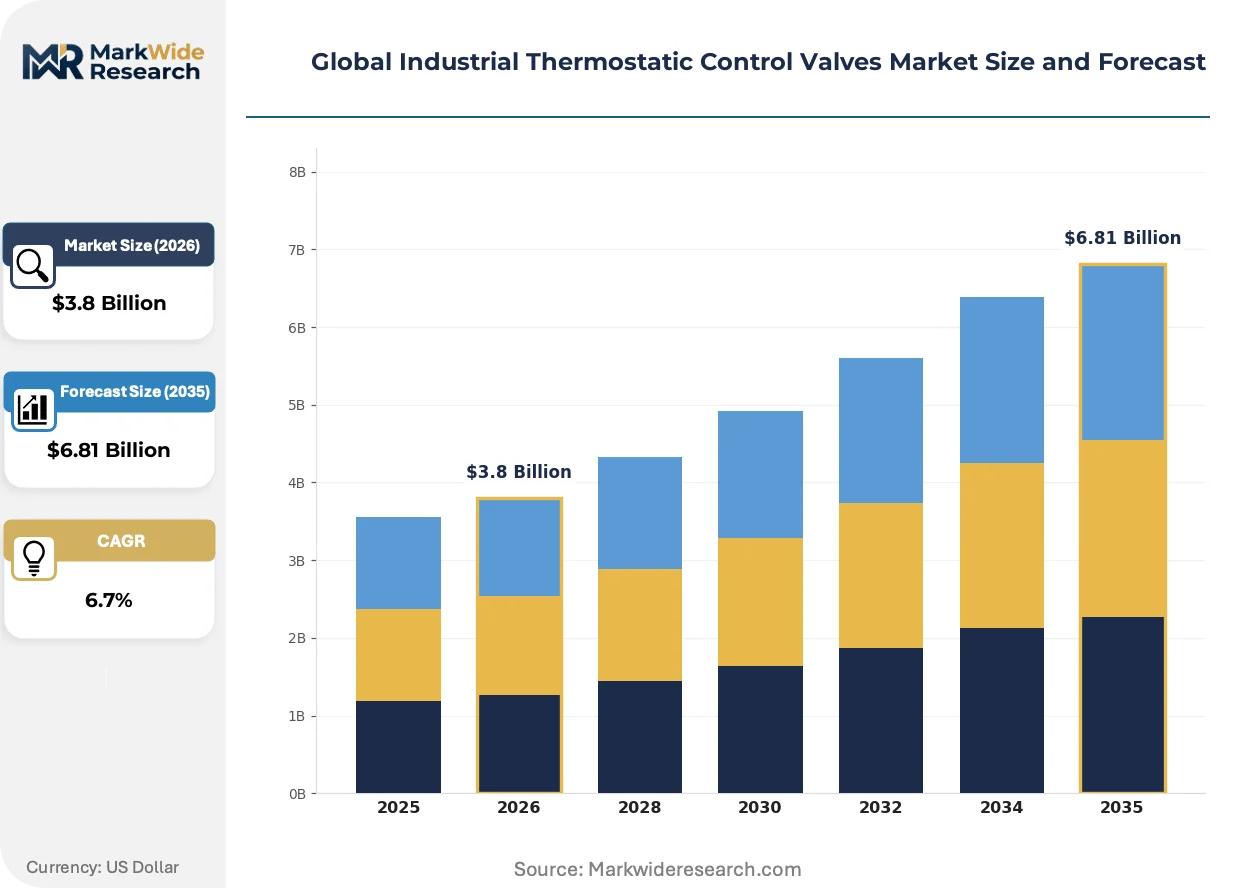
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Way Valves, Three-Way Valves, Automatic Valves, Manual Valves Technology: Electric, Pneumatic, Hydraulic, Mechanical Application: HVAC, Chemical Processing, Oil & Gas, Power Generation End User: Manufacturing, Construction, Energy, Water Treatment |
| Companies Covered | AMOT, IMI plc, Honeywell International Inc., Flowserve Corporation, Spirax-Sarco Engineering plc, Danfoss A/S, Schneider Electric SE, Belimo Holding AG, Emerson Electric Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Industrial Thermostatic Control Valves Market Strategic Shifts
Valve actuation architectures are splitting into two incompatible development tracks, with pneumatic designs optimizing for intrinsic safety and electric variants racing toward predictive analytics integration.
Sensor-embedded expansion elements are bifurcating the installed base. These devices combine traditional thermal actuation with real-time temperature telemetry for remote monitoring. Chemical processors in hydrogen cracking units are adopting them fastest, compressing the competitive window for purely mechanical suppliers. The technology is bifurcating procurement specifications into predictive-maintenance-ready and legacy-mechanical categories.
EPA emissions standards for industrial boilers are tightening thermal-efficiency verification requirements. Plant operators must now document continuous temperature control precision rather than periodic manual calibration. Packaged boiler systems in the United States are most affected, with specification writers embedding ISO 7005-1 flange compatibility as a baseline procurement filter.
Service contracting is unbundling from hardware sales. Power generation utilities now separate valve assembly procurement from aftermarket maintenance, pitting OEM service divisions against independent facility management firms. This pattern is most visible in German district heating networks, where municipal operators tender maintenance separately from initial equipment supply.
Global Industrial Thermostatic Control Valves Market Segmentation
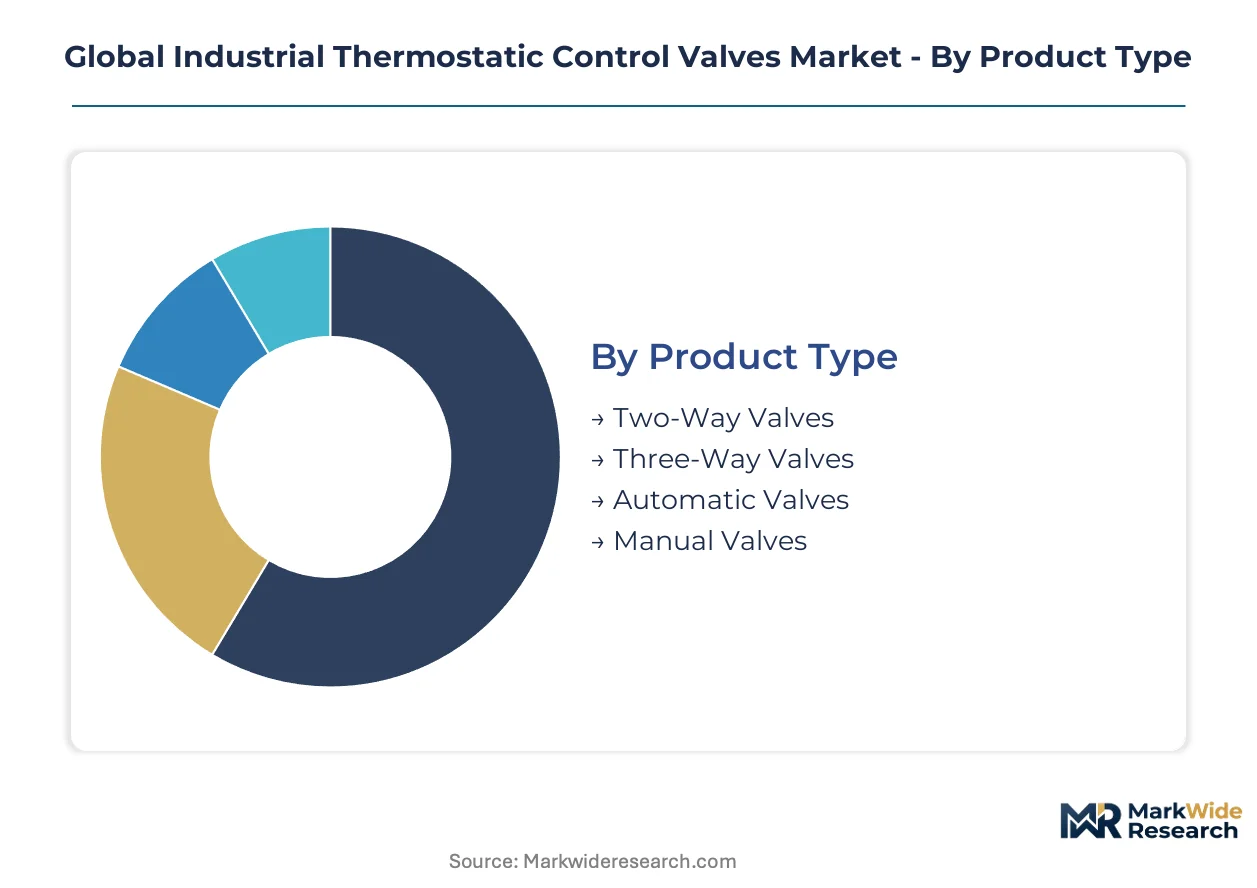
Thermostatic control valve procurement channels diverge sharply by segment complexity. Two-way mechanical units flow through distributor networks serving light manufacturing, while three-way pneumatic assemblies require direct OEM engagement for reactor-grade specifications.
Product Type:
Channel mix varies from stocking distributors for standardized two-way units to project-direct sales for engineered three-way configurations.
- Two-Way Valves:Self-acting temperature regulators with single inlet and outlet ports, typically specified for 0°C to 150°C set-point ranges in steam tracing and engine cooling loops. Demand concentrates in German district heating retrofits where municipal utilities prioritize network balancing hardware with minimal commissioning complexity. The EU F-Gas Regulation accelerates replacement cycles in these legacy installations.
- Three-Way Valves:Blended-stream control architectures featuring dual outlet ports for mixing or diverting service, essential for combined heat-and-power networks and hydrogen cracking units. Chemical processors in the Netherlands and China specify these for reactor temperature stability, driving specification upgrades from simpler mechanical designs.
- Automatic Valves:Sensor-embedded expansion elements with real-time telemetry capability for predictive maintenance platforms.
- Manual Valves:Hand-wheel operated bypass units for maintenance isolation and emergency override functions.
By volume, two-way valves lead. By growth pace, three-way configurations are climbing the fastest.
Technology:
Cost tier stratification separates premium electric actuation from commodity mechanical alternatives.
- Electric:BACnet-integrated servo motors with position feedback loops enabling smart-building automation and digital twin integration. Power generation utilities in the United States specify these for predictive-maintenance-ready valve assemblies, though adoption faces protocol friction with 1990s-era building management systems.
- Pneumatic:Compressed-air diaphragm actuators meeting intrinsic safety requirements for explosion-risk zones in oil and gas extraction. North Sea platforms and Middle Eastern upstream facilities retain this technology where electrical actuation faces regulatory prohibition, fragmenting R&D investment away from full electrification.
- Hydraulic:Oil-pressure actuation for high-force requirements in severe-service refinery applications.
- Mechanical:Expansion-element actuation without external power, dominant in legacy HVAC and budget-constrained process plants.
Mechanical technology retains the largest installed base. Electric actuation shows the steepest expansion trajectory.
Application:
Customer type determines procurement pattern, with utilities tendering maintenance separately from hardware.
- HVAC:Building-automation-integrated temperature regulation for commercial and institutional climate control. German municipal operators unbundle service contracting from equipment supply, pitting OEM service divisions against independent facility management firms.
- Chemical Processing:Reactor thermal management and heat exchanger regulation in polymerization and hydrogen cracking units. China's GB standards on industrial energy consumption verification reward deployments with measurable efficiency gains, opening state-backed financing channels.
- Oil & Gas:Compressor anti-surge protection and wellhead thermal regulation in upstream and midstream operations.
- Power Generation:Steam turbine bypass and boiler feedwater temperature control in thermal and combined-cycle plants.
Chemical processing commands premium pricing. HVAC delivers the highest unit volumes.
End User:
Geographic concentration aligns with national efficiency mandates and petrochemical capacity additions.
- Manufacturing:Process temperature control in automotive, food processing, and pharmaceutical production lines. India's Bureau of Energy Efficiency standards on industrial thermal systems create first-mover positioning for OEMs establishing local assembly partnerships.
- Construction:Embedded HVAC infrastructure in commercial building projects and district heating network extensions.
- Energy:Power plant and renewable energy storage thermal management systems.
- Water Treatment:Temperature regulation in desalination, wastewater processing, and municipal distribution systems.
Manufacturing absorbs the most units by volume. Energy sector procurement is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical capacity additions and district heating retrofits concentrate procurement authority among municipal utilities and process plant operators in Germany, China, and the United States. These buyer archetypes command specification-setting power that shapes vendor qualification protocols across regional supply chains.
United States
Power generation utilities in Texas and the Midwest are redrawing procurement priorities toward predictive-maintenance-ready valve assemblies. EPA emissions standards for industrial boilers tighten thermal-efficiency verification requirements. Packaged boiler systems in the Ohio River Valley embed ISO 7005-1 flange compatibility as a baseline procurement filter.
Germany
Municipal operators in the Ruhr and Bavaria unbundle service contracting from equipment supply for district heating retrofits. The EU F-Gas Regulation compels chemical processors in Ludwigshafen to retrofit thermal management systems ahead of historical replacement intervals. Severe-service trim designs sustain premium positioning in refinery hydrogen cracking units along the Rhine.
China
GB standards on industrial energy consumption verification reward thermostatic control valve deployments with measurable thermal efficiency gains in the Yangtze River Delta. State-backed financing channels open for petrochemical capacity additions in Ningbo and Dalian. Three-way pneumatic units capture expanding share in combined heat-and-power networks requiring blended stream control.
Netherlands
Chemical processors in Rotterdam specify three-way valves for reactor temperature stability in polymerization units. The EU F-Gas Regulation accelerates replacement cycles for legacy valve infrastructure. Port industrial clusters concentrate demand for hydrogen cracking thermal management systems.
India
Bureau of Energy Efficiency standards on industrial thermal systems create first-mover positioning for valve OEMs establishing local assembly partnerships in Gujarat and Maharashtra. Automotive and pharmaceutical production lines absorb standardized two-way mechanical units through distributor networks. Domestic content requirements are tightening for state-backed process plant efficiency mandates.
Global Industrial Thermostatic Control Valves Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with valve divisions nested within broader automation portfolios. Consolidation pressure operates at the mid-tier where specialized foundry capacity constraints favor scale-driven procurement relationships. Two strategic archetypes dominate: severe-service specialists commanding premium positioning in hydrogen cracking and refinery applications, and building-automation integrators anchoring thermostat valve sales within larger HVAC retrofit packages. Competitive moves center on aftermarket service contract extensions and digital twin integration for predictive maintenance platforms.
Within the severe-service tier, IMI plc and Flowserve Corporation exemplify positioning around high-temperature trim designs for refinery applications. Danfoss A/S occupies a distinct geography-driven anchor in Nordic district heating networks. Honeywell International Inc. sits within the building-automation integrator archetype, leveraging control-system bundling to capture HVAC retrofit procurement. These three entities represent the span from pure-play valve engineering to automation-platform envelopment.
| Leading Market Players |
|---|
| AMOT |
| IMI plc |
| Honeywell International Inc. |
| Flowserve Corporation |
| Spirax-Sarco Engineering plc |
| Danfoss A/S |
| Schneider Electric SE |
| Belimo Holding AG |
| Emerson Electric Co. |
| Others |
Value Chain & Pricing Dynamics
Specialized foundry utilization rates above 85% in German and Chinese precision casting networks create asymmetric scale advantages that compress price floors for high-temperature valve bodies while elevating entry barriers for second-tier competitors. This concentration permits incumbent OEMs to enforce long-term copper and nickel alloy indexation clauses that transfer raw material volatility downstream to municipal utilities and process plant operators.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper and nickel indexation dominate procurement for severe-service trim components, insulating German foundries from margin erosion while exposing chemical processors to input cost passthrough. Three-tier pricing structure across predictive-maintenance-ready, standard pneumatic, and economy mechanical tiers reflects certification grade divergence and after-sales service bundling. Price compression in the economy tier intensifies as Indian distributors flood light manufacturing channels with unbranded two-way units. Municipal utilities in district heating networks exhibit lowest price sensitivity due to state-backed financing, while independent automotive parts manufacturers drive hardest bargain for standardized mechanical valves.
Supply Chain Analysis
Inventory cycles stretching 16-20 weeks for severe-service valve bodies reflect foundry order backlogs concentrated in Germany, China, and Japan, where precision casting capacity feeds global OEM assembly networks. Expansion-element housings draw from copper alloy mills in Chile and Indonesia, while nickel-based superalloy trim sources from Russian and Canadian mining operations now subject to tariff exposure. Single-source vulnerability concentrates in German severe-service foundries serving hydrogen cracking specifications. Distribution runs through project-direct channels for three-way pneumatic assemblies and stocking distributors for two-way mechanical units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial thermostatic control valves market sits in early-cycle recovery as refrigerant-phase-down mandates force replacement spending ahead of historical intervals, compressing demand from a 15-year to a 7-10 year equipment refresh rhythm.
For Market Incumbents: Compound aftermarket service contract coverage across Nordic and Baltic district heating networks before Danfoss and IMI extend their installed base lock-in, while securing precision casting capacity reservations in German supplier networks to defend against Chinese foundry competition. Backward integration into copper alloy billet supply hedges London Metal Exchange volatility that threatens margin stability in economy-tier mechanical valve production. For New Entrants and Emerging Players: Differentiate on sensor-embedded expansion element architectures for predictive maintenance platforms, targeting power generation utilities in Texas and the Midwest where procurement unbundling creates vendor switching windows. India's Bureau of Energy Efficiency efficiency mandates present the most penetrable geography for local assembly partnerships ahead of domestic content requirements tightening. Pursue white-label supply agreements with German HVAC distributors lacking smart-building electric actuation capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors severe-service specialists with captive foundry relationships and ISO 23551-1 certification depth over building-automation integrators facing BACnet protocol friction in retrofit markets. Long-term viability rests on hydrogen economy thermal management exposure and district heating network modernization tailwinds. Watch EU F-Gas Regulation phase-down acceleration announcements as the inflection signal for replacement cycle compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Alloy Supply | Captive billet sourcing from Chilean mills insulates margins from London Metal Exchange volatility. |
| Digital Twin Platform Integration | BACnet-embedded valve telemetry enables outcome-based service contracting with Texas power utilities. |
| Local Assembly Partnership in India | Gujarat and Maharashtra facilities satisfy Bureau of Energy Efficiency domestic content requirements. |
| Severe-Service Foundry Capacity Reservation | Locked precision casting slots in German networks defend hydrogen cracking specification access. |
| Predictive Maintenance Service Unbundling | Separate maintenance tenders from hardware supply capture German municipal operator procurement shifts. |
Study Parameters
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads and secondary sources including customs/trade data, SEC 10-K filings, and ISO certification registries anchors the qualitative findings. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across product type, technology, application, and end user dimensions.
Sensitivity analysis around copper and nickel price trajectories, EU F-Gas Regulation phase-down acceleration scenarios, and Chinese GB standards enforcement intensity shapes the analytical framework across the projection horizon. Modeled dimensions span valve architecture, actuation technology, process application severity, and regional regulatory cluster. CAGRs derive from installed base replacement cycle compression and petrochemical capacity addition pipelines, with hydrogen economy thermal management demand and district heating retrofit backlogs as industry-specific forecast inputs.
Material uncertainties — refrigerant-phase-down schedule revisions, foundry capacity expansion delays, and trade policy shifts affecting copper alloy feedstock — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these exogenous factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Axial and Radial Seals Market
Valves
Insulation Flanges Market
Valves
Angle Opening Ball Locator Market
Valves
Pipeline and Process Services Market
Valves
Steel Cylinder Market
Valves
GCC and MENA Valves Market
Valves
Flanges Market
Valves
Blow - Off Valves Market
Valves
Pup Joint Market
Valves
Global Gas Pressure Regulator Market
Valves
Europe Valves Market
Valves
Mechanical Shaft Seal Market
Valves
North America High Voltage Switchgear Market
Valves
Global Marine Actuators and Valves Market
Valves
Emergency Venting System Market
Valves
Actuators and Valves Market