
 Cervical Cancer Screening Market | 2026-2036
Cervical Cancer Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Cervical Cancer Screening Market Analysis
CE marking under the EU MDR is unwinding market access for legacy colposcopy and biopsy device suppliers. Hologic Inc. leverages integrated assay-to-imaging workflows to sustain laboratory loyalty in North America. Qiagen N.V. competes through molecular HPV assay specialization, while F. Hoffmann-La Roche Ltd. anchors high-throughput diagnostic platforms in centralized lab networks.
Cervical cancer screening encompasses cytologic evaluation, human papillomavirus nucleic acid detection, and visual inspection methods to identify precancerous lesions before invasive disease develops. Liquid-based cytology preserves cellular architecture in preservative media, enabling automated slide imaging and reducing sampling error compared with conventional Pap smears. HPV tests command expanding share as primary screening modalities, while digital pathology systems are displacing manual microscopy in high-volume diagnostic laboratories. Diagnostic laboratories capture concentrated margin pools through bundled screening and follow-up service contracts.
The FDA governs HPV assay approvals through premarket notification and premarket authorization pathways, while the WHO sets screening interval and test-algorithm guidance that shapes national procurement priorities. EMA and notified bodies enforce MDR technical documentation and clinical evidence requirements for devices marketed in Europe. Stakeholders must monitor evolving WHO recommendations on self-sampling HPV protocols and regulatory harmonization across major jurisdictions to align product development with reimbursement access.
Market Dynamics
WHO screen-and-treat protocol revisions are compressing diagnostic workflows from multi-visit pathways toward same-day molecular triage, forcing manufacturers to integrate assay and imaging capabilities or lose procurement eligibility in national health programs.
Growth Catalysts
- India's population-based screening camps:Government procurement under the National Programme for Prevention and Control of Cancer expands cytology and HPV testing infrastructure into district hospitals and mobile units.
- EMA MDR compliance deadlines:Stricter clinical evidence requirements for colposcopy and biopsy devices accelerate replacement cycles as legacy suppliers exit the European market.
- Liquid-based cytology automation:Automated slide imaging systems reduce pathologist review time and sampling error, driving laboratory upgrade demand in high-throughput networks.
Market Restraints
- HPV assay cost concentration:Molecular reagent pricing remains elevated due to patent-protected nucleic acid amplification chemistries, limiting adoption in lower-tier laboratories.
- Pathologist workforce scarcity:Cytotechnologist training pipelines in Southeast Asia and sub-Saharan Africa fail to match screening program expansion timelines.
- Self-sampling regulatory lag:FDA and EMA have approved limited HPV self-collection indications, constraining decentralized screening models despite WHO endorsement.
Strategic Opportunities
- Digital pathology platform convergence:Integration of whole-slide imaging with AI-assisted cytology review creates bundled service offerings for centralized diagnostic networks.
- Thailand's universal screening mandate:Ministry of Public Health procurement for district-level HPV testing opens volume contracts for regional distributors.
- Point-of-care molecular miniaturization:Battery-operated isothermal amplification devices enable same-day screen-and-treat protocols in rural clinics without cold chain logistics.
Industry Challenges
- CE marking technical documentation:EU MDR clinical evaluation report requirements demand prospective performance studies that extend product launch timelines by 18-24 months.
- Laboratory information system integration:Disparate HL7 and DICOM standards between cytology analyzers, digital pathology archives, and hospital EMRs create interoperability friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cervical Cancer Screening Market |
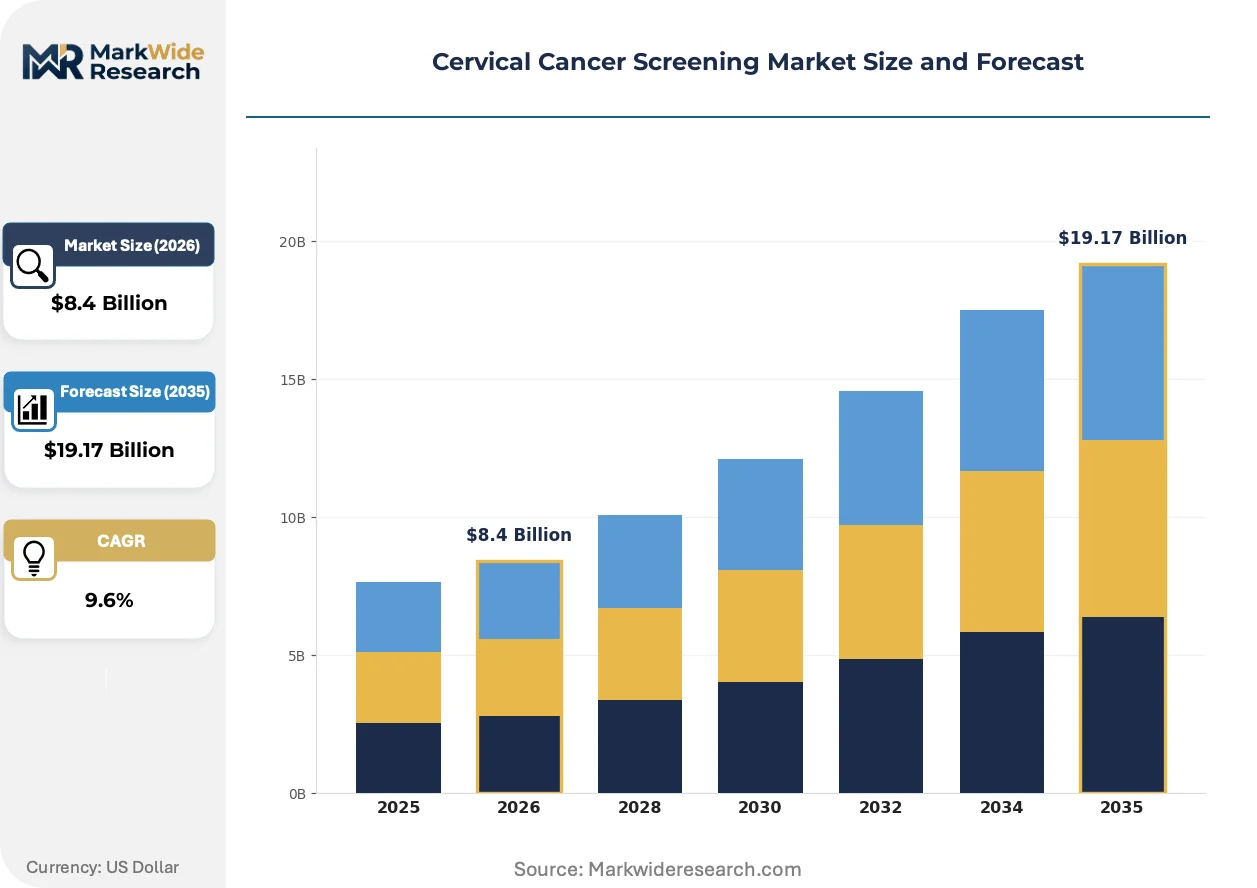
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $19.17 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cytology Tests, HPV Tests, Colposcopy Devices, Biopsy Equipment Technology: Liquid-Based Cytology, Digital Pathology, Molecular Diagnostic, Visual Inspection End User: Hospitals, Clinics, Diagnostic Laboratories, Research Institutes Service Type: Screening Services, Follow-Up Services, Consultation Services, Diagnostic Services |
| Companies Covered | Hologic Inc., Qiagen N.V., F. Hoffmann-La Roche Ltd., Becton Dickinson and Company, Abbott Laboratories, Thermo Fisher Scientific Inc., Siemens Healthineers AG, Quest Diagnostics Incorporated, Oncocyte Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cervical Cancer Screening Market Emerging Trajectories
Artificial intelligence-assisted cytology is restructuring diagnostic labor allocation while regulatory frameworks for self-sampling HPV protocols mature across major jurisdictions.
AI-powered cervical cytology screening software is decomposing the traditional pathologist-led review model by automating negative case triage. Large commercial laboratories in North America and Western Europe are deploying these algorithms at scale, reducing manual slide review volume by over 50 percent. This technology is decomposing the economics of centralized cytology services, compressing per-test labor costs and enabling same-day result turnaround that manual microscopy cannot match.
REACH and RoHS substance restrictions are tightening material compliance requirements for plastic consumables used in liquid-based cytology collection devices. Manufacturers must reformulate preservative media vials and transfer pipettes to eliminate phthalates and heavy metal catalyst residues. European notified bodies are now requiring full material disclosure documentation as part of CE marking technical files, extending certification cycles for suppliers without established green chemistry programs.
Consolidated laboratory networks are unbundling after-sales service contracts from instrument procurement, opting instead for multi-vendor maintenance agreements managed by third-party clinical engineering firms. This purchasing behavior shift is disrupting traditional manufacturer service revenue streams in the United States and Germany. Academic medical centers and regional hospital chains are driving this transition, prioritizing uptime guarantees and response-time penalties over OEM-branded service relationships.
Cervical Cancer Screening Market Segmentation
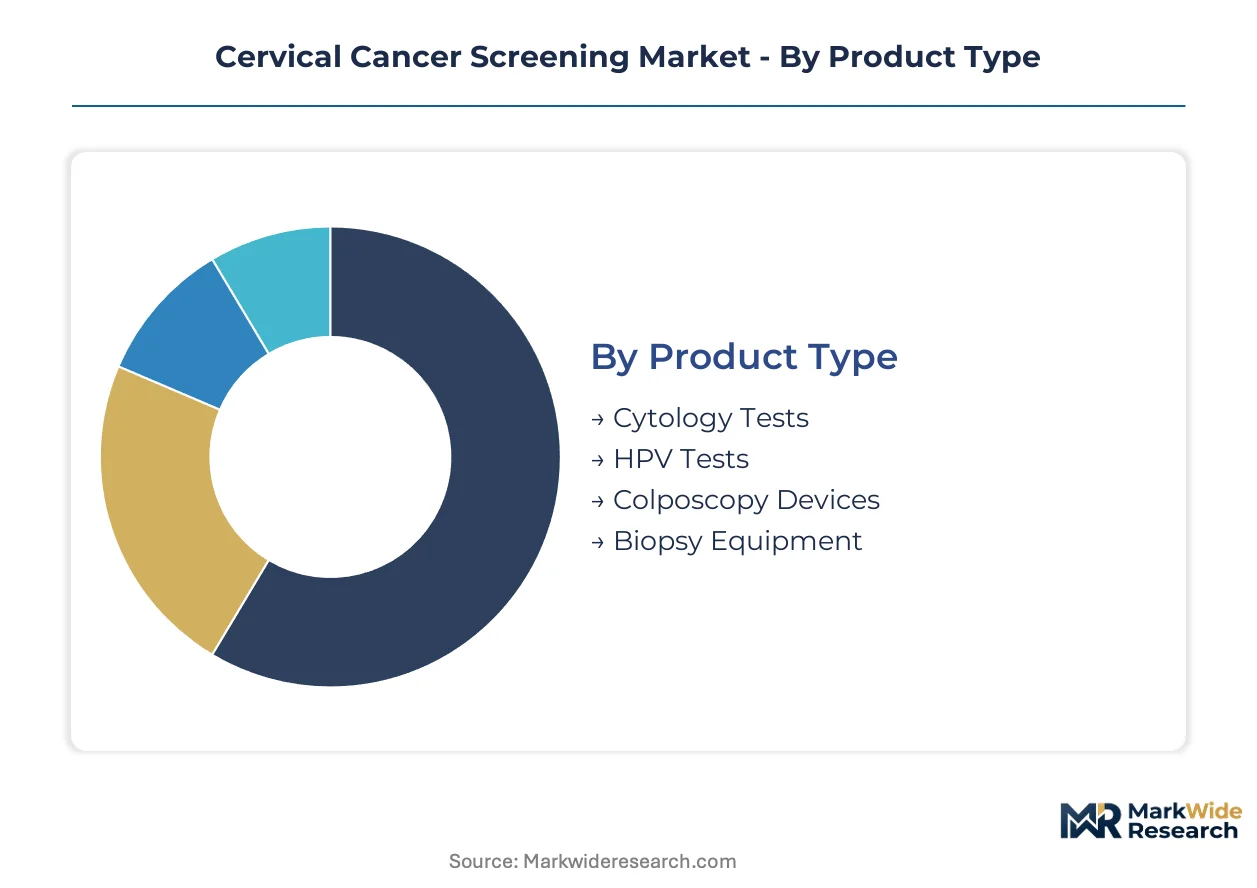
Product heterogeneity in cervical cancer screening creates distinct margin pools and procurement pathways. Molecular diagnostics command premium pricing in centralized laboratories while visual methods penetrate resource-limited settings. Understanding segment substitution dynamics reveals where technology transitions will compress or expand addressable revenue.
Product Type:
HPV tests exert the strongest substitution pressure on legacy cytology, compressing colposcopy referral volumes as primary screening algorithms shift.
- Cytology Tests:Conventional Pap smears and liquid-based preparations detect morphological abnormalities in cervical epithelial cells. District hospitals in India rely on these for population screening camps under government procurement, though HPV primary screening is displacing their role in tier-one cities.
- HPV Tests:Nucleic acid amplification assays detect high-risk human papillomavirus genotypes. Centralized diagnostic laboratories in Thailand and Vietnam are scaling these as primary screening modalities, driven by WHO screen-and-treat protocol endorsements that enable same-day molecular triage.
- Colposcopy Devices:Optical magnification systems with green filter and acetic acid application for lesion visualization.
- Biopsy Equipment:Punch forceps and endocervical curettes for histological sampling of suspicious lesions.
HPV tests anchor the volume base while cytology tests gain share at the steepest rate in price-sensitive procurement segments.
Technology:
Cost tier stratification separates premium molecular platforms from low-cost visual methods, with digital pathology occupying an intermediate automation tier.
- Liquid-Based Cytology:Cellular preservation in methanol-based media enables automated slide preparation and imaging. High-throughput diagnostic networks in Germany and the United States deploy these systems to reduce sampling error and pathologist review burden.
- Digital Pathology:Whole-slide imaging combined with AI-assisted cytology review transforms diagnostic labor allocation. Academic medical centers in Singapore and South Korea are piloting these platforms to enable remote pathology consultation across island and mountainous regions.
- Molecular Diagnostic:PCR and isothermal amplification chemistries for HPV DNA/RNA detection.
- Visual Inspection:Acetic acid or Lugol's iodine application with naked-eye assessment for immediate screen-and-treat.
Visual inspection anchors the volume base in low-resource settings while digital pathology climbs the fastest in consolidated laboratory networks.
End User:
Customer type determines purchasing behavior, with diagnostic laboratories bundling services and hospitals prioritizing integrated instrument-imaging workflows.
- Hospitals:Integrated care delivery sites combining screening, diagnosis, and treatment. Tertiary hospitals in Bangkok and Mumbai are consolidating cytology and colposcopy services under single vendor contracts to streamline patient pathways.
- Diagnostic Laboratories:Centralized high-volume testing facilities with automated platforms. Commercial laboratory chains in the United States and Germany are unbundling service contracts from instrument procurement, opting for multi-vendor maintenance agreements.
- Clinics:Primary care and specialty outpatient settings with point-of-care testing capabilities.
- Research Institutes:Academic and government facilities conducting epidemiological studies and assay validation.
Diagnostic laboratories anchor the volume base while clinics expand most quickly with point-of-care molecular miniaturization.
Service Type:
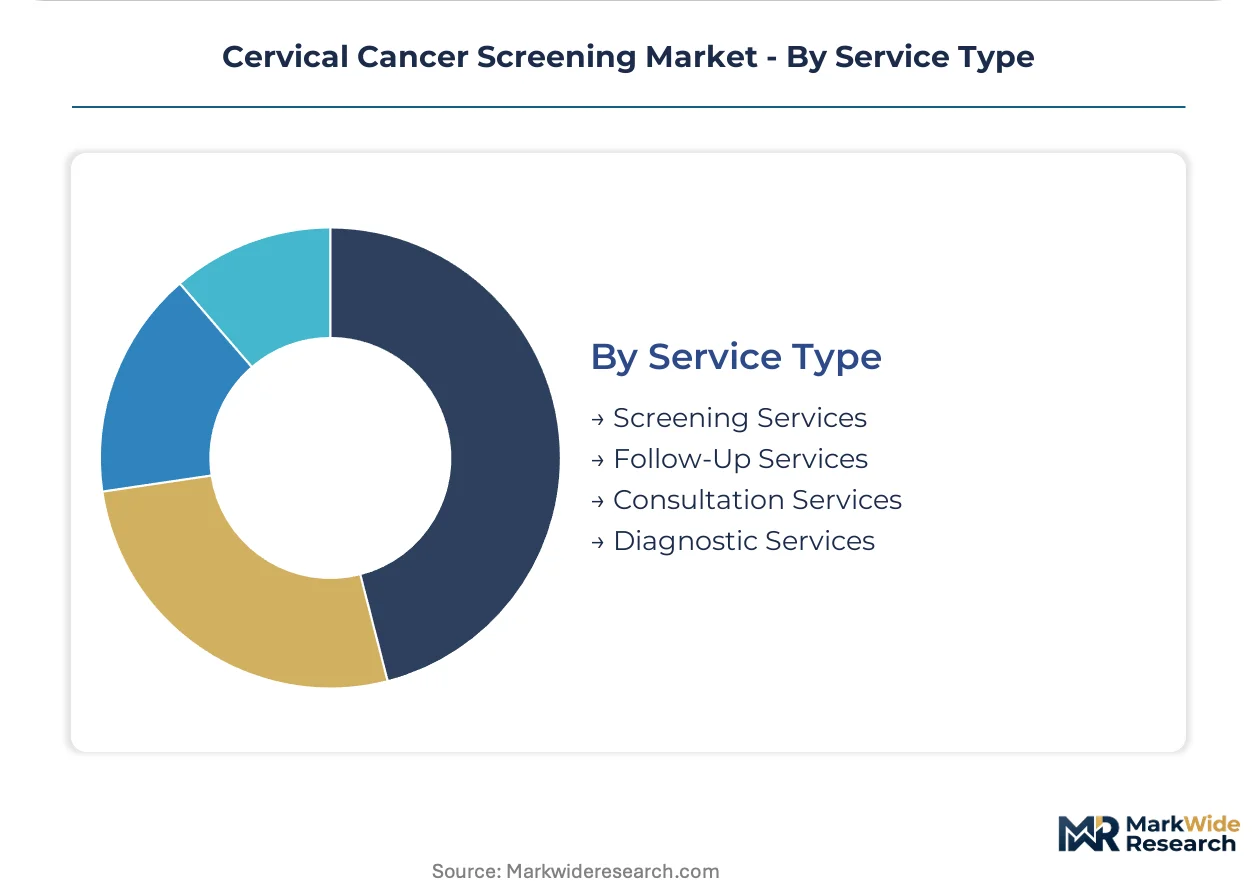
Application maturity varies, with screening services commoditizing and follow-up services capturing concentrated margin through specialized triage.
- Screening Services:Population-based testing programs for asymptomatic individuals. India's National Programme for Prevention and Control of Cancer is scaling these through mobile units and district hospital networks, creating volume contracts for regional distributors.
- Follow-Up Services:Colposcopy, biopsy, and histopathology for screen-positive patients. Specialized gynecologic oncology centers in Seoul and Tokyo command premium pricing for these services through bundled care pathways.
- Consultation Services:Specialist referral for abnormal results and treatment planning.
- Diagnostic Services:Confirmatory testing and staging for suspected invasive disease.
Screening services anchor the volume base while follow-up services capture margin expansion through risk-stratified care pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government procurement mandates are reshaping national screening infrastructure, with WHO screen-and-treat protocols redirecting public health budgets toward molecular diagnostics and same-day triage capabilities.
United States
FDA premarket authorization pathways govern HPV assay approvals, creating regulatory moats for established diagnostic platforms. Commercial laboratory chains in California and Texas are unbundling service contracts from instrument procurement, opting for multi-vendor maintenance agreements. Academic medical centers in Boston anchor digital pathology pilot programs integrating AI-assisted cytology review.
Germany
EMA MDR compliance deadlines for colposcopy and biopsy devices are accelerating replacement cycles as legacy suppliers exit. High-throughput diagnostic networks in Bavaria and North Rhine-Westphalia deploy liquid-based cytology automation to reduce pathologist review burden. REACH substance restrictions are forcing reformulation of plastic consumables in preservative media vials.
India
The National Programme for Prevention and Control of Cancer is scaling population-based screening camps through mobile units and district hospital networks. CDSCO regulates in-vitro diagnostic imports while state governments in Maharashtra and Karnataka issue volume tenders for cytology and HPV testing infrastructure. Procurement concentrates in tier-one cities where HPV primary screening displaces conventional Pap smears.
Thailand
Ministry of Public Health procurement for district-level HPV testing opens volume contracts for regional distributors under universal screening mandates. Bangkok's tertiary hospitals are consolidating cytology and colposcopy services under single vendor contracts to streamline patient pathways. Isothermal amplification devices enable same-day screen-and-treat protocols in rural clinics without cold chain logistics.
South Korea
MFDS regulates HPV assay approvals while national health insurance reimbursement shapes test-algorithm adoption. Academic medical centers in Seoul command premium pricing for follow-up services through bundled gynecologic oncology pathways. Singapore and South Korea pilot digital pathology platforms to enable remote consultation across island and mountainous regions.
Cervical Cancer Screening Market Vendor Landscape
Player mix skews toward integrated diagnostic conglomerates with assay-to-imaging workflows and specialized molecular assay developers. Market structure concentrates around laboratory loyalty programs and bundled service contracts in North America, while price-sensitive procurement in Asia-Pacific fragments purchasing across regional distributors. Two strategic archetypes dominate: platform-integrated systems suppliers and molecular reagent specialists. Competitive moves center on M&A for digital pathology capabilities and strategic partnerships for point-of-care miniaturization.
Among integrated diagnostic conglomerates, Hologic Inc. and F. Hoffmann-La Roche Ltd. occupy positions exemplifying platform-anchored market presence, while Qiagen N.V. represents the molecular assay specialization archetype. These three entities illustrate how laboratory loyalty programs and high-throughput diagnostic platforms create differentiated competitive positions across centralized networks.
| Leading Market Players |
|---|
| Hologic Inc. |
| Qiagen N.V. |
| F. Hoffmann-La Roche Ltd. |
| Becton Dickinson and Company |
| Abbott Laboratories |
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Quest Diagnostics Incorporated |
| Oncocyte Corporation |
| Others |
Supply Flow & Price Mechanics
EU MDR technical documentation requirements gate both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb extended certification cycles that compress margin pools while creating tiered access based on clinical evidence depth. Diagnostic laboratories exploit this fragmentation to unbundle service contracts from instrument procurement, intensifying price competition among qualified suppliers.
Pricing Analysis
Cost-plus contracts with raw material indexation dominate HPV reagent procurement in centralized laboratory networks. Pricing stratifies across premium molecular platforms, standard cytology automation, and economy visual inspection tiers, with differentiation driven by throughput capacity and assay sensitivity specifications. Cost compression in the economy tier intensifies because government tenders in India and Thailand prioritize unit economics over performance margins. District hospital procurement committees exhibit highest price sensitivity, while academic medical centers in Seoul and Singapore accept premium positioning for integrated assay-to-imaging workflows.
Supply Chain Analysis
Strategic stockpiling of preservative media and amplification reagents prevails over just-in-time inventory among diagnostic manufacturers facing cold chain vulnerabilities. Manufacturing concentration centers on Germany, the United States, and China for automated cytology platforms, while South Korea and Japan anchor molecular diagnostic component supply. Raw material dependencies include methanol-based cellular preservatives, PCR enzyme formulations, and optical-grade glass for colposcopy lenses. Single-source vulnerability concentrates in patented nucleic acid amplification chemistries. Distribution runs through regional distributor networks in Southeast Asia and direct-to-laboratory contracts in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pathologist workforce scarcity constrains screening program expansion timelines, creating competitive advantage for manufacturers with AI-assisted cytology platforms that reduce manual review burden. This capability gap rewards early movers in automated triage and remote diagnostic networks.
For Market Incumbents: Shield laboratory loyalty in North America through integrated assay-to-imaging workflow subscriptions that embed switching costs. Deepen backward integration into digital pathology software development to counter emerging AI-native entrants. Prioritize CE marking completion for legacy colposcopy devices before MDR compliance deadlines eliminate European market access for competitors with weaker clinical evidence portfolios.
For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated market entry for point-of-care HPV self-sampling platforms addressing regulatory lag constraints. Target rural clinic networks in Thailand and Vietnam where same-day molecular triage protocols remain undersupplied. Pursue ministry of health pilot partnerships to generate performance data supporting national procurement eligibility.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate diagnostic divisions with stranded colposcopy assets facing EU MDR compliance failure. Long-term viability hinges on molecular assay specialization and AI-enabled labor substitution rather than legacy instrument manufacturing. Monitor WHO self-sampling protocol endorsement timing as inflection indicator for decentralized screening model capital deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR compliance deadlines in Germany accelerate replacement cycles for compliant suppliers. |
| Hospital System Partnership | Bangkok tertiary networks consolidate cytology and colposcopy under single vendor contracts. |
| Software Companion Development | AI-assisted cytology review reduces pathologist labor allocation by over half in pilot deployments. |
| Reimbursement Strategy | MFDS national health insurance decisions in Seoul shape test-algorithm adoption across South Korea. |
| Strategic Partnership | Isothermal amplification licensing enables battery-operated point-of-care devices in rural Thai clinics. |
Methodological Framework
A spread of perspectives from diagnostic laboratory directors, hospital procurement committees, biomedical engineers, and GPO contracts managers converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from FDA 510(k) filings, EMA MDR technical documentation, WHO screening guideline repositories, and hospital procurement databases. Bottom-up instrument and reagent volume estimates triangulated against top-down national health expenditure allocations across the analysis window.
Segmentation dimensions modeled include product type, technology platform, end-user facility category, and service application across the projection horizon. CAGRs derived from logistic diffusion curves fitted to screening program expansion timelines and instrument replacement cycles. Forecast inputs incorporated WHO protocol revision probability, regulatory approval velocity by jurisdiction, and pathologist workforce growth projections.
Underlying assumptions cover stable reimbursement policy continuity and cold chain infrastructure expansion rates, with deviation risk concentrated in self-sampling regulatory acceleration and AI diagnostic liability frameworks. Revision becomes warranted when WHO endorsement of decentralized screening protocols crosses implementation thresholds in major markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Clinical Diagnosis Automation Market