
 Dermal Curettes Market | 2026-2036
Dermal Curettes Market Size, Share, and Industry Trends Forecast 2026-2036
Dermal Curettes Market Outlook
Cosmetic surgery is expanding as a demand vertical for dermal curettes, pulling instrument specifications toward finer tips and ergonomic handles. Becton, Dickinson and Co. leverages its hospital distribution network to sustain volume across wound care and biopsy applications. Integra LifeSciences Holdings Corp. differentiates through specialized instrument portfolios targeting outpatient dermatology. KAI Medical anchors supply in Asian markets with cost-optimized stainless steel designs.
Dermal curettes are handheld surgical instruments with a sharp, oval or circular cutting loop at the distal end, typically manufactured from medical-grade stainless steel or sterilizable polymers, designed for scraping or excising superficial skin lesions with controlled depth and minimal collateral tissue disruption. Stainless steel curettes dominate surgical and biopsy applications where edge sharpness and repeated autoclave cycles matter, while single-use plastic variants gain share in dermatology clinics seeking to eliminate reprocessing overhead and cross-contamination liability. Composite materials occupy a niche where weight reduction and disposable convenience intersect with moderate procedural complexity.
FDA 510(k) clearance requirements shape instrument design and labeling for US market entry, while the EU Medical Device Regulation (MDR) and CE marking enforce biocompatibility and traceability standards across European supply chains. ISO 13485 certification operates as a baseline qualifier for Original Equipment Manufacturer relationships, filtering out contract manufacturers lacking quality management documentation. Stakeholders must monitor how sterilization validation protocols evolve under MDR transitional provisions and whether US outpatient surgery center accreditation shifts toward mandating single-use instruments for specific lesion categories.
Market Dynamics
Single-use instrument conversion is compressing the addressable market for reprocessable stainless steel curettes while expanding total procedure volumes through reduced setup overhead and infection-control liability.
Growth Catalysts
- EU MDR sterilization traceability mandates:Dermatology clinics across Germany and France are abandoning in-house reprocessing for disposable polymer curettes to eliminate documentation burden and audit exposure.
- Outpatient biopsy volume expansion:Screening program intensification in Japan and the United States sustains instrument throughput across dermatology and pathology workflows.
- Polymer molding advances:Medical-grade plastics now achieve edge sharpness sufficient for superficial lesion excision, opening substitution pathways in low-complexity procedures.
Market Restraints
- Medical-grade stainless steel price volatility:Nickel and chromium input cost swings squeeze margin structures for reusable instrument manufacturers concentrated in Solingen and Sheffield.
- Autoclave infrastructure lock-in:Surgical centers with capital-intensive sterilization suites face sunk-cost resistance to single-use conversion despite operational benefits.
- Sharps disposal regulatory burden:EPA hazardous waste protocols in the United States add per-procedure cost layers that partially offset single-use convenience.
Strategic Opportunities
- Indian dermatology clinic expansion:Metro hospital chains in Mumbai and Delhi are professionalizing outpatient skin surgery, creating first-mover openings for sterilizable polymer portfolios.
- Cosmetic procedure channel development:Medspa networks in South Korea and Brazil represent underpenetrated demand for fine-tip curettes optimized for aesthetic lesion removal.
- ISO 13485 certification arbitrage:Contract manufacturers in Malaysia and Vietnam with quality management documentation can capture OEM relationships from European incumbents facing MDR compliance costs.
Industry Challenges
- Biocompatibility testing timeline compression:ISO 10993 cytotoxicity and sensitization studies for new polymer formulations extend product development cycles beyond typical capital planning horizons.
- Legacy instrument refurbishment skill scarcity:Sharpening and edge restoration expertise for stainless steel curettes is concentrating among aging technicians in German and Japanese manufacturing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dermal Curettes Market |
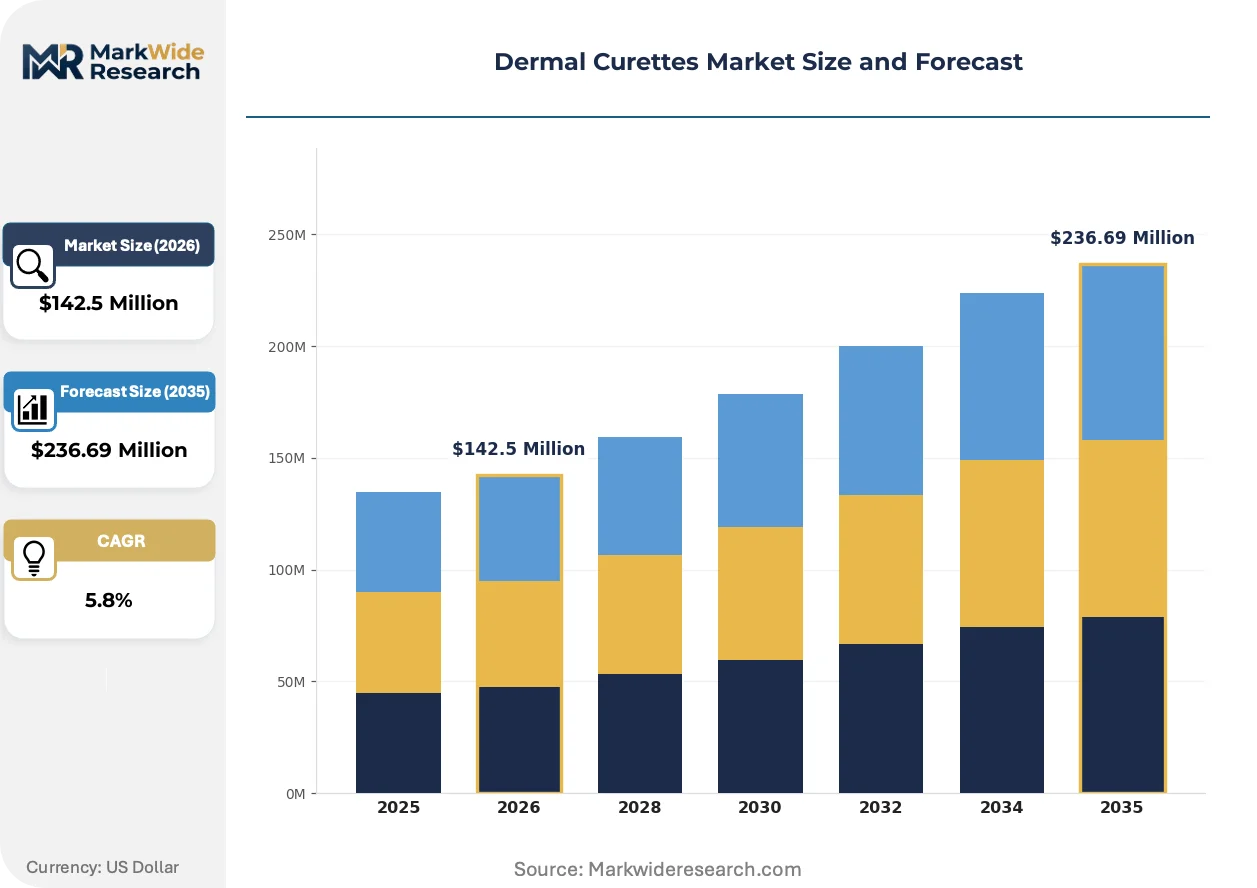
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $236.69 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Use, Reusable, Disposable, Surgical Material: Stainless Steel, Plastic, Composite, Glass End User: Dermatology Clinics, Hospitals, Medical Research, Cosmetic Surgery Application: Wound Care, Skin Lesion Removal, Surgery, Biopsy |
| Companies Covered | Becton, Dickinson and Co., Integra LifeSciences Holdings Corp., KAI Medical, Sklar Surgical Instruments, Delasco, Stiefel (GSK), Tejco Vision, Sklar Corporation, SFM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dermal Curettes Market Strategic Shifts
Instrument specifications are fragmenting across procedure complexity tiers, with material science and regulatory compliance operating as simultaneous forcing functions on product architecture and go-to-market economics.
Precision-molded polymer curettes with integrated depth-limiting collars are overtaking conventional stainless steel in dermatology clinic settings where lesion depth consistency matters more than edge longevity. Outpatient facilities in the United States and Germany are standardizing on these variants for screening biopsies. The shift is compressing addressable volume for reprocessable metal instruments in low-acuity segments while expanding total procedure feasibility through reduced per-case preparation time.
MDR Article 10 clinical evidence requirements for Class I reusable surgical instruments are forcing European manufacturers to generate post-market surveillance data previously unnecessary for legacy curette registrations. Small instrument specialists in Tuttlingen and Sialkot face documentation costs that favor portfolio rationalization toward disposable alternatives. German distributors are responding by consolidating supplier relationships around firms with established quality management infrastructure.
Consignment inventory arrangements are displacing outright purchase models in United States hospital systems seeking to convert instrument ownership to variable cost structures. Dermatology departments at academic medical centers in Boston and Houston now receive curette kits on usage-based replenishment rather than capital budget allocation. The pattern is most visible in high-volume screening programs where consumption predictability supports vendor-managed inventory economics.
Dermal Curettes Market Segmentation
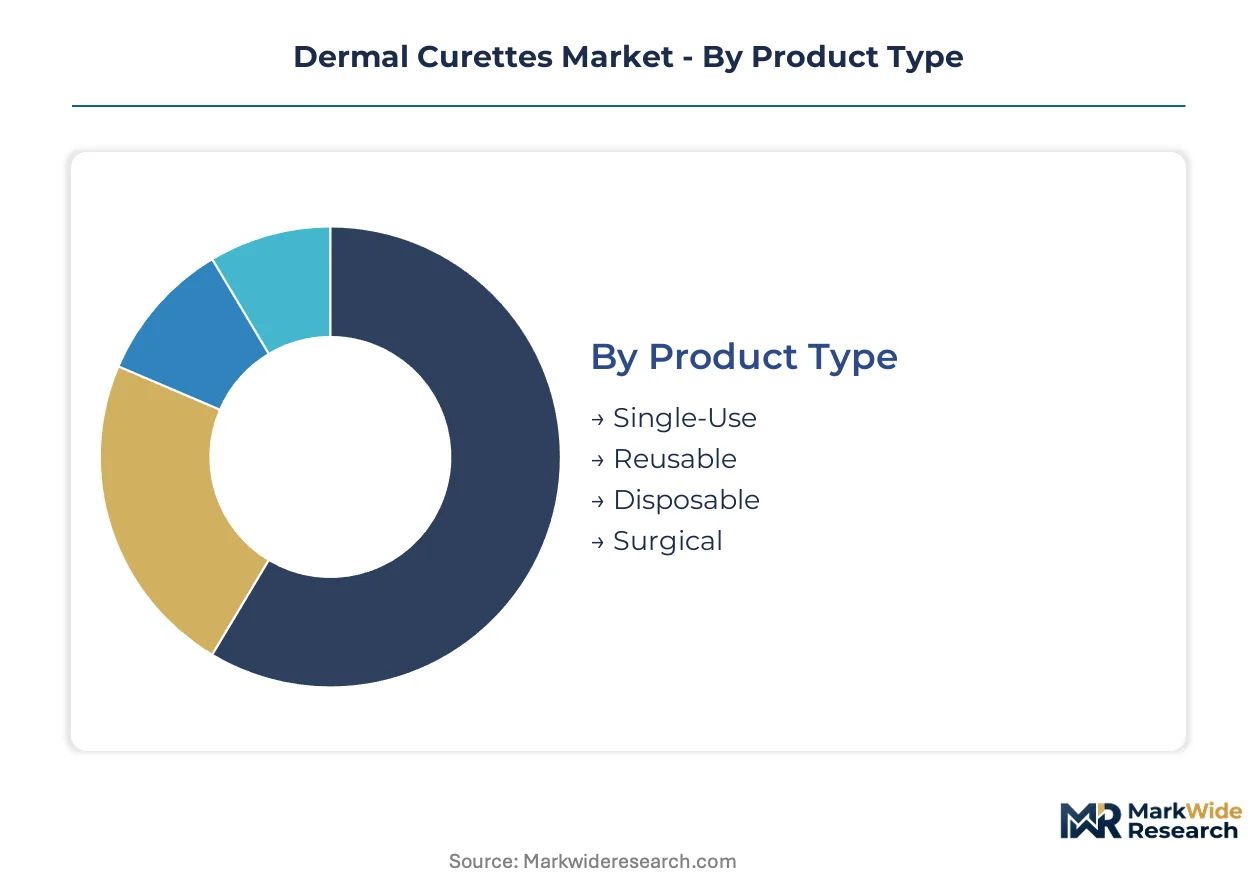
Instrument selection in dermal curettes hinges on sterilization economics, procedural complexity, and regulatory exposure across clinical settings. Segmentation reveals how material science and end-use requirements fragment demand into distinct procurement tiers with divergent margin structures.
Product Type:
Upgrade cycles accelerate where reprocessing liability outweighs capital recovery timelines for reusable instruments.
- Single-Use:Polymer curettes with pre-sterilized packaging eliminate autoclave validation and cross-contamination exposure. Demand concentrates in United States dermatology clinics where FDA outpatient surgery center accreditation tightens instrument documentation requirements.
- Reusable:Medical-grade stainless steel designs withstand hundreds of autoclave cycles with periodic edge restoration. German surgical centers retain preference for these variants where capital-intensive sterilization infrastructure creates sunk-cost resistance to conversion.
- Disposable:Lightweight polymer alternatives bridge cost and convenience for moderate-volume outpatient settings.
- Surgical:Precision-engineered variants with ergonomic handle geometry target operating room workflows.
Single-Use sits at the top of the volume ranking, with Disposable climbing the fastest.
Material:
Cost tiers separate premium edge retention from economy-grade convenience in procurement decisions.
- Stainless Steel:Martensitic and austenitic alloys deliver superior edge sharpness and thermal stability for repeated sterilization. Japanese manufacturers in Seki and German producers in Solingen dominate supply chains for biopsy-grade instruments.
- Plastic:Medical-grade polymers achieve molded edge geometries sufficient for superficial lesion excision. United States clinic chains standardize on these variants to eliminate EPA sharps disposal documentation burdens.
- Composite:Hybrid constructions balance weight reduction with structural rigidity for extended procedures.
- Glass:Specialized variants serve niche applications requiring optical clarity or chemical inertness.
Stainless Steel commands the largest installed base, though Plastic gains share fastest in outpatient conversion.
End User:
Customer type determines whether procurement prioritizes throughput efficiency or capital depreciation schedules.
- Dermatology Clinics:High-frequency screening workflows favor single-use instruments with minimal setup overhead.
- Hospitals:Integrated sterilization departments sustain reusable metal curette volumes for surgical and biopsy applications.
- Medical Research:Protocol standardization demands traceable instrument specifications with batch documentation.
- Cosmetic Surgery:Fine-tip precision requirements drive specification toward ergonomic polymer designs.
Dermatology Clinics generate the highest procedure volume, while Cosmetic Surgery expands most quickly.
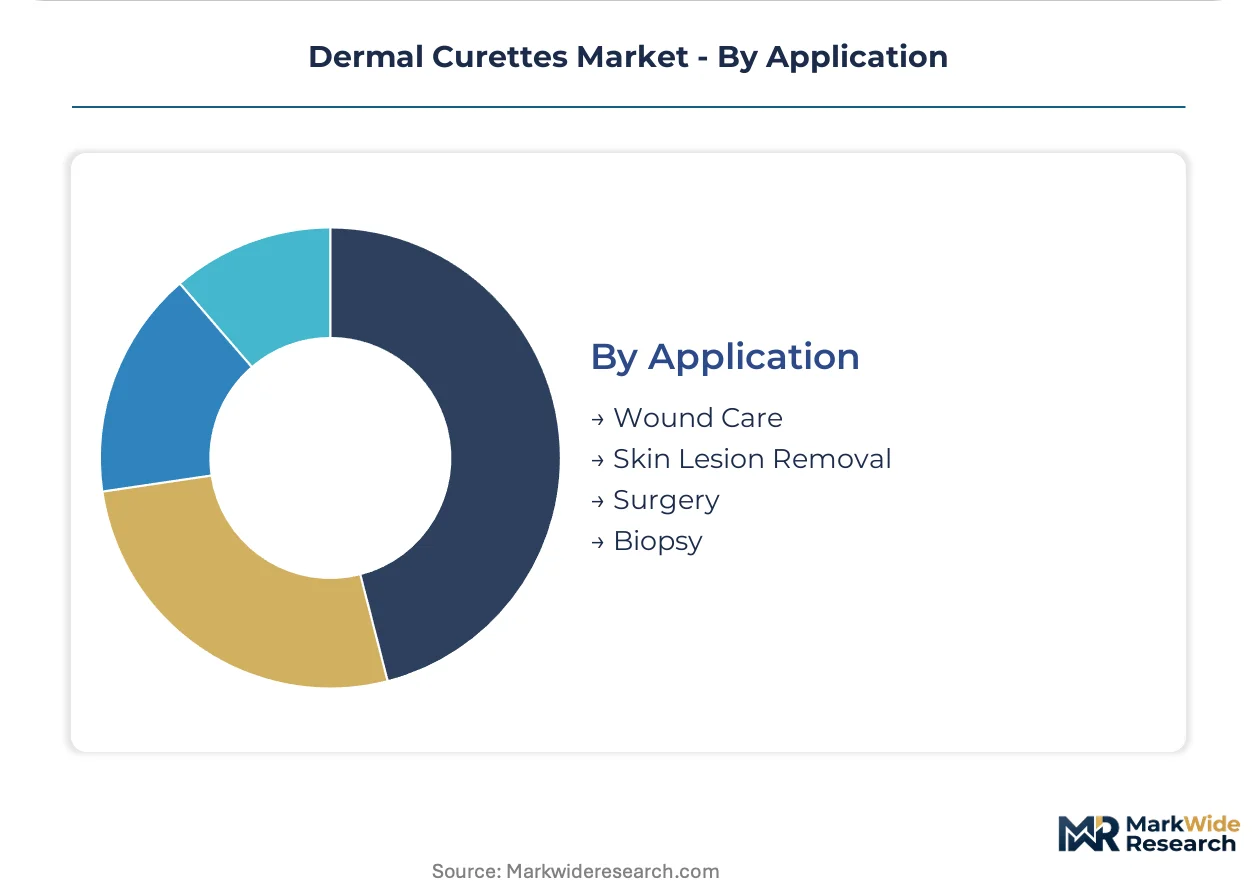
Application:
Procedural complexity dictates whether edge longevity or disposable convenience dominates instrument selection.
- Wound Care:Debridement protocols in United States long-term care facilities favor single-use polymer curettes to reduce infection liability.
- Skin Lesion Removal:Superficial excision in German outpatient settings drives demand for depth-limiting collar designs.
- Surgery:Operating room requirements sustain stainless steel preference where edge retention across multiple procedures matters.
- Biopsy:Screening program intensification in Japan sustains instrument throughput for histopathological sampling.
Wound Care leads in disposable conversion, with Biopsy maintaining steadiest reusable instrument demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting manufacturing investment toward jurisdictions where MDR compliance costs and sterilization documentation burdens remain lighter. Contract manufacturers in Southeast Asia now capture OEM relationships that European incumbents find marginally unprofitable under tightened traceability mandates.
United States
FDA outpatient surgery center accreditation is tightening instrument documentation requirements for dermatology clinics. EPA hazardous waste protocols add per-procedure disposal costs that partially offset single-use convenience. Academic medical centers in Boston and Houston now operate on consignment inventory models rather than capital budget allocation.
Germany
EU MDR Article 10 clinical evidence requirements for Class I reusable instruments are forcing post-market surveillance data generation previously unnecessary for legacy registrations. Solingen-based manufacturers face documentation costs that favor portfolio rationalization toward disposable alternatives. Tuttlingen distributors are consolidating supplier relationships around firms with established quality management infrastructure.
Japan
Screening program intensification sustains instrument throughput for histopathological sampling across dermatology and pathology workflows. PMDA harmonization with ISO 13485 standards streamlines quality management documentation for domestic manufacturers. Seki-based producers retain dominance in biopsy-grade stainless steel supply chains.
India
Metro hospital chains in Mumbai and Delhi are professionalizing outpatient skin surgery, creating first-mover openings for sterilizable polymer portfolios. CDSCO medical device rules are gradually converging with international standards, though registration timelines remain unpredictable. Sialkot-based contract manufacturers are capturing re-export volumes for European distributors seeking cost-optimized sourcing.
South Korea
Medspa networks represent underpenetrated demand for fine-tip curettes optimized for aesthetic lesion removal. MFDS regulatory pathways for polymer-based instruments are shortening as local biocompatibility testing capacity expands. Seoul-based distributors are building direct relationships with dermatology clinic chains bypassing traditional hospital procurement channels.
Dermal Curettes Market Competitive Environment
Portfolio diversification dominates the current landscape as manufacturers hedge between reusable metal and single-use polymer demand trajectories. The vendor base separates into three functional tiers: integrated hospital supply conglomerates with distribution scale, specialized surgical instrument houses with regional manufacturing heritage, and emerging polymer-focused entrants with molding expertise. Strategic archetypes include quality-system arbitrageurs capturing OEM relationships from compliance-burdened European incumbents, and premium-brand defenders leveraging autoclave infrastructure lock-in at surgical centers. M&A activity concentrates on sterilization service networks and polymer molding capacity, while geographic expansion targets Indian and Southeast Asian clinic professionalization.
Among diversified medical technology conglomerates, Becton, Dickinson and Co. and Integra LifeSciences Holdings Corp. occupy positions anchored by hospital distribution networks and specialized instrument portfolios respectively. KAI Medical represents the Asia-focused manufacturing archetype with cost-optimized stainless steel supply chains. These three entities exemplify how scale, specialization, and regional cost positioning fragment competitive advantage across distinct procurement tiers.
| Leading Market Players |
|---|
| Becton, Dickinson and Co. |
| Integra LifeSciences Holdings Corp. |
| KAI Medical |
| Sklar Surgical Instruments |
| Delasco |
| Stiefel (GSK) |
| Tejco Vision |
| Sklar Corporation |
| SFM |
| Others |
Value Chain & Pricing Dynamics
United States dermatology clinic chains concentrate procurement power through consignment inventory arrangements, converting instrument ownership from capital expenditure to variable cost structures that reshape supplier pricing models toward usage-based replenishment economics.
Pricing Analysis
Distributor margins in the 15-25% range separate sterilizable polymer curettes from premium stainless steel biopsy-grade instruments. Price differentiation rests on ISO 13485 certification tier and autoclave cycle durability, with German surgical centers exhibiting lowest price sensitivity due to capital-intensive sterilization infrastructure lock-in. Cost compression in the reusable metal tier intensifies because nickel and chromium input volatility squeezes Solingen-based manufacturers. United States outpatient clinics demonstrate highest price sensitivity, driving fastest conversion to single-use alternatives.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing patterns for European distributors seeking cost-optimized stainless steel curettes. Manufacturing gravity centers on Germany, Japan, and Pakistan, with Seki and Solingen anchoring premium biopsy-grade supply and Sialkot feeding re-export volumes. Raw material dependencies draw from medical-grade martensitic stainless steel, medical-grade polymers, and nickel-chromium alloys. Single-source vulnerability concentrates in Solingen's aging technician base for edge restoration expertise. Distribution runs through hospital supply conglomerates and specialized surgical instrument distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dermal curettes market functions as a stable compounder where outpatient screening program intensification sustains instrument throughput across dermatology and pathology workflows.
For Market Incumbents: Anchor market position through backward integration into polymer molding capacity and certification infrastructure that emerging Asian contract manufacturers cannot rapidly replicate. Consolidate supplier relationships around firms with established ISO 13485 documentation to offset MDR compliance cost burdens. Defend against sterilizable polymer substitution by emphasizing autoclave infrastructure lock-in at German and Japanese surgical centers. For New Entrants and Emerging Players: Enter via underpenetrated medspa networks in South Korea and Brazil where fine-tip precision requirements for aesthetic lesion removal outstrip incumbent polymer design portfolios. Target Indian metro hospital chains in Mumbai and Delhi professionalizing outpatient skin surgery with sterilizable polymer portfolios priced below European import equivalents. Build direct relationships with dermatology clinic chains bypassing traditional hospital procurement channels. For Investors and Strategic Acquirers: Hospital supply conglomerates with wound care and dermatology distribution networks are the most active acquirers in this space, seeking to convert instrument ownership to variable cost structures. Long-term viability rests on exposure to screening program intensification rather than discretionary cosmetic procedure cyclicality. Monitor PMDA-FDA harmonization progress as signal for accelerated quality management documentation requirements that would favor incumbents with established regulatory infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Polymer Molding Capacity Expansion | Captures single-use conversion demand from United States dermatology clinics facing EPA sharps disposal documentation burdens. |
| ISO 13485 Certification Investment | Qualifies contract manufacturers for OEM relationships as European incumbents face MDR Article 10 surveillance costs. |
| Consignment Inventory Partnership | Converts academic medical center procurement from capital budget allocation to usage-based replenishment economics. |
| Fine-Tip Precision R&D Program | Addresses medspa network demand for aesthetic lesion removal instruments in South Korea and Brazil. |
| Backward Integration into Medical-Grade Steel | Offsets nickel-chromium price volatility squeezing margin structures for reusable instrument manufacturers. |
Study Parameters
Direct dialogue with dermatology clinic procurement managers, hospital purchasing committee members, biomedical engineers specializing in surgical instruments, and GPO contracts managers grounded the qualitative foundation. Secondary validation drew from FDA 510(k) filings, EU MDR transitional provision documentation, hospital procurement databases, and customs trade records for medical-grade stainless steel. Bottom-up procedure volume estimates triangulated against top-down manufacturer shipment data.
Bottom-up modeling anchored the analytical lens, with top-down manufacturer revenue cross-checks ensuring consistency. Segmentation dimensions spanned product type, material grade, end-user facility type, and application complexity across the projection horizon. CAGRs were derived from instrument throughput trajectories tied to screening program intensification and single-use conversion elasticity. Forecast inputs incorporated sterilization infrastructure depreciation schedules and biocompatibility testing timeline compression for polymer formulations.
Inputs from hospital procurement databases and GPO contract disclosures were available through the study window; gaps in real-time inventory velocity data from consignment arrangements introduce uncertainty bands around near-term volume estimates. Forecasts reflect assumptions regarding MDR transitional provision enforcement timing and outpatient surgery center accreditation evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Surgical Pliers Market
Surgical Instruments
Minimally Invasive Thoracic Surgery Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Global Pain Management and Surgical Devices Market
Surgical Instruments
Global Powered Surgical Instruments Market
Surgical Instruments
Huber Needles Market
Surgical Instruments
United States Minimally Invasive Surgery Market
Surgical Instruments
India Surgical Sutures Market
Surgical Instruments
Ultrasonic Scissors Market
Surgical Instruments
Neurosurgical Drills Market
Surgical Instruments
Surgical Equipment Market
Surgical Instruments
Surgical Broaches Market
Surgical Instruments
GCC Minimally Invasive Surgery Market
Surgical Instruments
Dental Surgical Microscopes Market