
 Chromosomal Aberration Test Market | 2026-2036
Chromosomal Aberration Test Market Size, Share, and Industry Trends Forecast 2026-2036
Chromosomal Aberration Test Market Analytics
Next-generation sequencing integration into cytogenetic workflows is rewriting how laboratories detect structural and numerical chromosomal abnormalities. Thermo Fisher Scientific leverages its Ion Torrent platform to anchor clinical adoption in molecular diagnostics. Charles River Laboratories sustains its position through GLP-compliant toxicology screening services for pharmaceutical clients. Eurofins Scientific differentiates via distributed laboratory networks spanning multiple regulatory jurisdictions.
Chromosomal aberration testing encompasses cytogenetic methods that identify structural variations including deletions, duplications, inversions, translocations, and aneuploidy in metaphase spreads or interphase nuclei, with resolution thresholds ranging from 5-10 megabases for standard karyotyping down to single-nucleotide variants for sequencing-based approaches. These tests serve primary purposes in prenatal diagnosis, oncology biomarker discovery, and regulatory genotoxicity assessment for pharmaceutical candidate safety. Fluorescence in situ hybridization retains dominance in solid tumor pathology where rapid turnaround for HER2 or ALK status guides therapeutic selection. Next-generation sequencing captures the fastest expansion trajectory as bioinformatics pipelines mature for copy-number variant detection in constitutional disorders. Microarray analysis occupies a narrowing but defensible position in developmental delay evaluations where balanced rearrangements matter less than dosage sensitivity.
FDA guidance on reproductive toxicity testing and ICH S2(R1) genotoxicity guidelines shape demand patterns for pharmaceutical toxicology services in the United States. EMA's MDR and IVDR frameworks in Europe impose clinical evidence requirements that filter market access for novel cytogenetic platforms. Stakeholders must monitor how WHO laboratory quality standards and OECD test guideline revisions influence harmonization of chromosomal aberration protocols across jurisdictions.
Market Dynamics
Next-generation sequencing platforms are compressing turnaround times from weeks to days while simultaneously expanding detectable variant classes beyond the resolution limits of conventional karyotyping, forcing laboratories to reconfigure capital deployment and staff training priorities.
Growth Catalysts
- ICH M7(R2) Guidelines:Pharmaceutical toxicology screening budgets are expanding to meet genotoxic impurity assessment mandates across the United States and European Union.
- Prenatal Diagnostics:Non-invasive prenatal testing adoption is accelerating demand for confirmatory cytogenetic workflows in maternal-fetal medicine clinics.
- Oncology Biomarker Discovery:Solid tumor pathology departments require rapid fluorescence in situ hybridization for HER2 and ALK status determination to guide therapeutic selection.
Market Restraints
- Capital Intensity:Sequencing platform acquisition and bioinformatics infrastructure require substantial upfront investment, limiting participation to well-capitalized laboratory networks.
- Regulatory Fragmentation:Divergent EMA MDR and FDA premarket review timelines create parallel compliance burdens for platform developers seeking multi-jurisdictional approval.
- Technical Limitation:Standard karyotyping maintains superior detection of balanced chromosomal rearrangements that sequencing-based methods frequently miss.
Strategic Opportunities
- Underpenetrated Geography:India's expanding network of accredited cytogenetic laboratories presents whitespace for distributed testing infrastructure outside metropolitan hospital clusters.
- Technology Convergence:Artificial intelligence-assisted karyotype analysis integrated with digital imaging systems promises automated metaphase screening.
- Regulatory Tailwind:WHO laboratory quality standards harmonization initiatives are reducing protocol validation costs for laboratories seeking international accreditation.
Industry Challenges
- Bioinformatics Talent Scarcity:Copy-number variant interpretation requires specialized computational biology expertise that outpaces current training program output.
- Legacy System Integration:Laboratory information management systems designed for karyotype workflows resist seamless data exchange with sequencing pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromosomal Aberration Test Market |
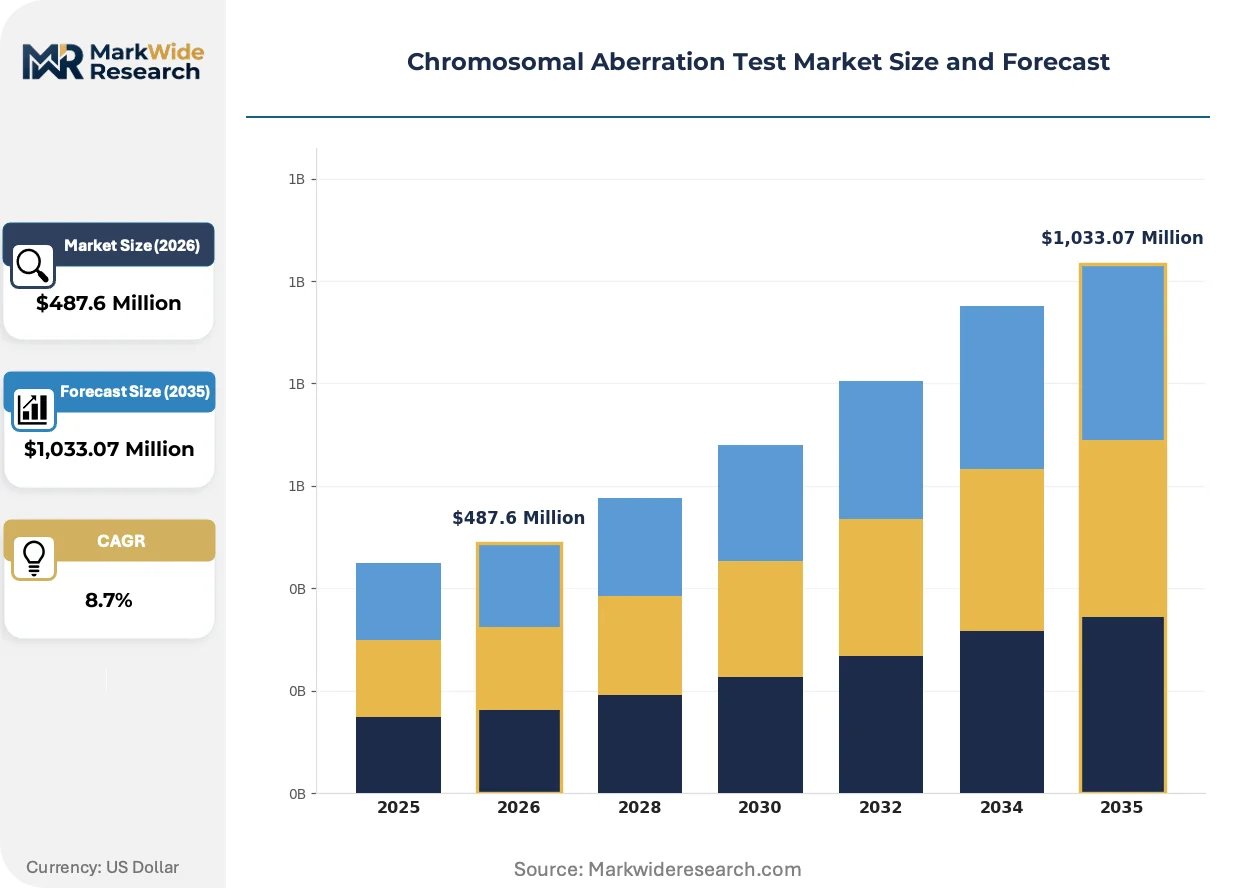
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluorescence In Situ Hybridization, Karyotyping, Microarray Analysis, Next-Generation Sequencing End User: Hospitals, Diagnostic Laboratories, Research Institutes, Pharmaceutical Companies Technology: Cytogenetics, Digital PCR, Bioinformatics, Molecular Diagnostics Application: Oncology, Prenatal Testing, Genetic Disorders, Personalized Medicine |
| Companies Covered | Thermo Fisher Scientific, Inc., Charles River Laboratories International, Laboratory Corporation of America Holdings, Eurofins Scientific, Syngene International Limited, Jubilant Life Sciences Limited, Gentronix Ltd., Inotiv Inc., Creative Bioarray, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromosomal Aberration Test Market Evolving Landscape
Sequencing-based cytogenetic methods are fundamentally altering how structural and numerical abnormalities are detected, interpreted, and reported across clinical and regulatory applications. This technological transition is compressing established service models while creating new capability requirements.
Optical genome mapping technology is rendering obsolete traditional fluorescence in situ hybridization for detecting cryptic structural variants in constitutional disorder evaluations. Clinical cytogenetics laboratories in Germany and Japan are adopting these platforms to resolve complex chromosomal rearrangements that escape microarray detection. The structural consequence is a bifurcation in service offerings between rapid screening and high-resolution definitive characterization.
EMA's In Vitro Diagnostic Regulation (IVDR) is imposing clinical evidence requirements that filter market access for novel cytogenetic platforms in European Union member states. Manufacturers must now generate prospective performance data rather than relying on analytical equivalence to predicate devices. High-complexity molecular pathology laboratories are responding by consolidating validation efforts across multi-site networks to distribute compliance costs.
Contract research organizations are unbundling genotoxicity testing packages to offer à la carte chromosomal aberration assays rather than bundled regulatory submission packages. Pharmaceutical sponsors in the United States are selecting discrete test modules based on compound class and regulatory pathway rather than accepting standardized panels. This behavioral shift is most visible among mid-cap biotechnology developers with limited internal toxicology infrastructure.
Chromosomal Aberration Test Market Segmentation
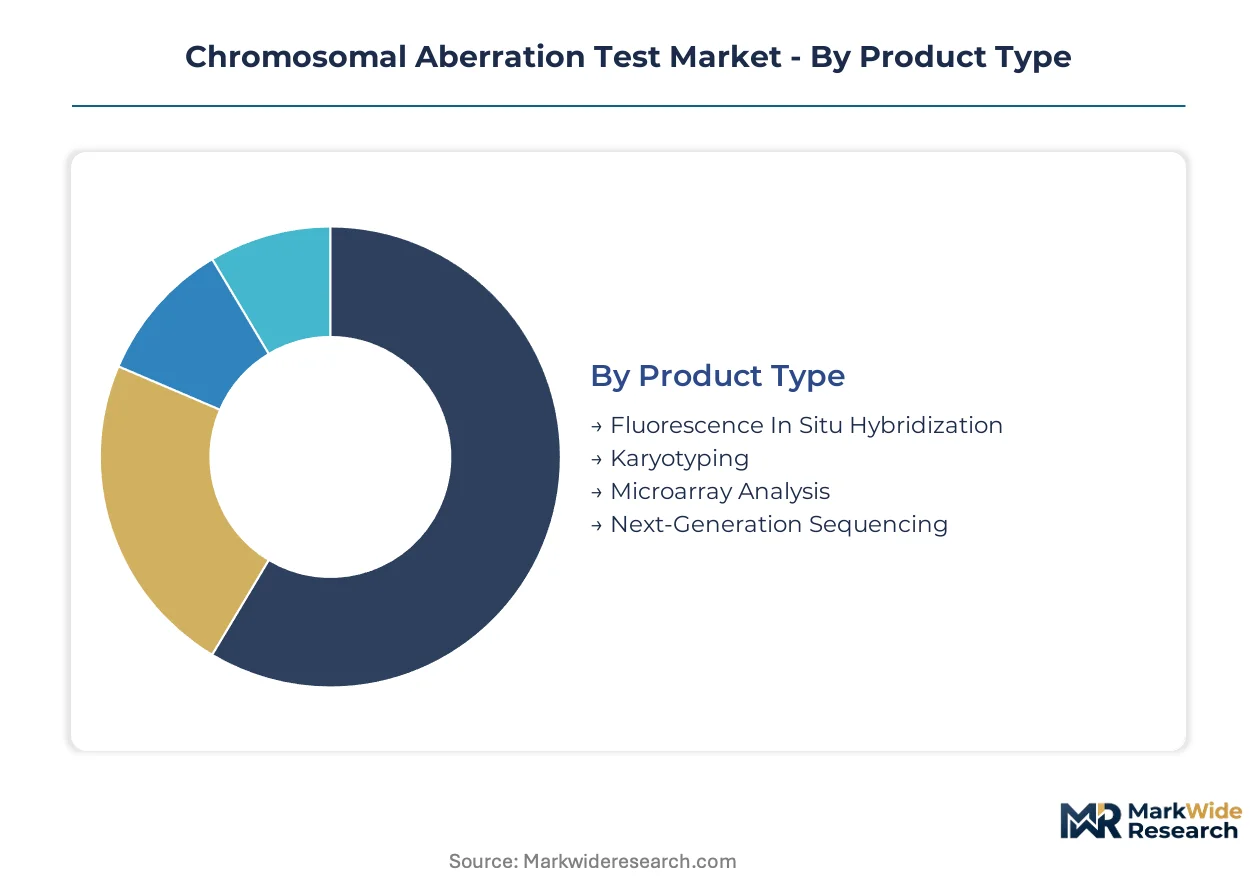
Segmentation reveals how chromosomal aberration testing fragments across distinct technology platforms, user capabilities, and clinical workflows. Each dimension carries different capital requirements, regulatory burdens, and service intensity profiles that reshape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product categories, with sequencing platforms demanding continuous bioinformatics support while conventional methods require only periodic maintenance.
- Next-Generation Sequencing:High-throughput platforms detect copy-number variants and single-nucleotide changes at resolutions below 1 kilobase. Demand concentrates in academic medical centers in the United States and Germany where bioinformatics infrastructure justifies capital deployment. Steep learning curves and pipeline validation requirements create vendor lock-in effects.
- Fluorescence In Situ Hybridization:Probe-based detection of targeted loci maintains dominance in solid tumor pathology for HER2 and ALK status determination. Hospital laboratories in Japan and the United States favor FISH for rapid turnaround in therapeutic decision-making. Lower capital barriers preserve accessibility for mid-sized diagnostic networks.
- Karyotyping:G-banded metaphase analysis remains the regulatory gold standard for genotoxicity assessment under OECD and ICH guidelines.
- Microarray Analysis:Comparative genomic hybridization arrays serve developmental delay evaluations where dosage sensitivity outweighs structural rearrangement detection.
By volume, Karyotyping leads. By growth pace, Next-Generation Sequencing is ahead.
End User:
Customer capability tiers determine purchasing patterns, with sophisticated buyers demanding integrated workflow solutions while price-sensitive segments prioritize discrete test access.
- Diagnostic Laboratories:Independent and hospital-affiliated labs process high sample volumes across prenatal and oncology indications. Networks in the United States and Germany are consolidating to amortize sequencing platform costs across broader catchment populations. Regulatory accreditation requirements filter market participation.
- Pharmaceutical Companies:Sponsors of drug development programs require GLP-compliant chromosomal aberration testing for regulatory submission packages. United States-based biotechnology developers outsource toxicology screening to contract research organizations rather than building captive capabilities.
- Hospitals:Integrated health systems favor rapid in-house FISH for oncology biomarker testing over send-out models.
- Research Institutes:Academic centers drive adoption of emerging optical genome mapping technologies for constitutional disorder research.
Diagnostic Laboratories capture the largest revenue share. Pharmaceutical Companies are expanding most quickly.
Technology:
Technology maturity curves diverge, with established cytogenetic methods facing displacement pressure from digitally-enabled molecular approaches.
- Molecular Diagnostics:PCR-based and sequencing methods are capturing share from conventional microscopy across prenatal and cancer applications. Clinical laboratories in Japan and the United States lead adoption of automated nucleic acid extraction and library preparation systems. Workflow integration with electronic health records drives purchasing decisions.
- Bioinformatics:Computational pipelines for variant calling and interpretation represent the fastest-expanding capability requirement. Copy-number variant detection algorithms require specialized expertise that outpaces training program output in the United States and European Union.
- Cytogenetics:Microscopy-based chromosome analysis retains regulatory-mandated roles in pharmaceutical toxicology testing.
- Digital PCR:Absolute quantification methods serve niche applications in mosaicism detection and chimerism monitoring.
Cytogenetics maintains installed base dominance. Bioinformatics is climbing the fastest.
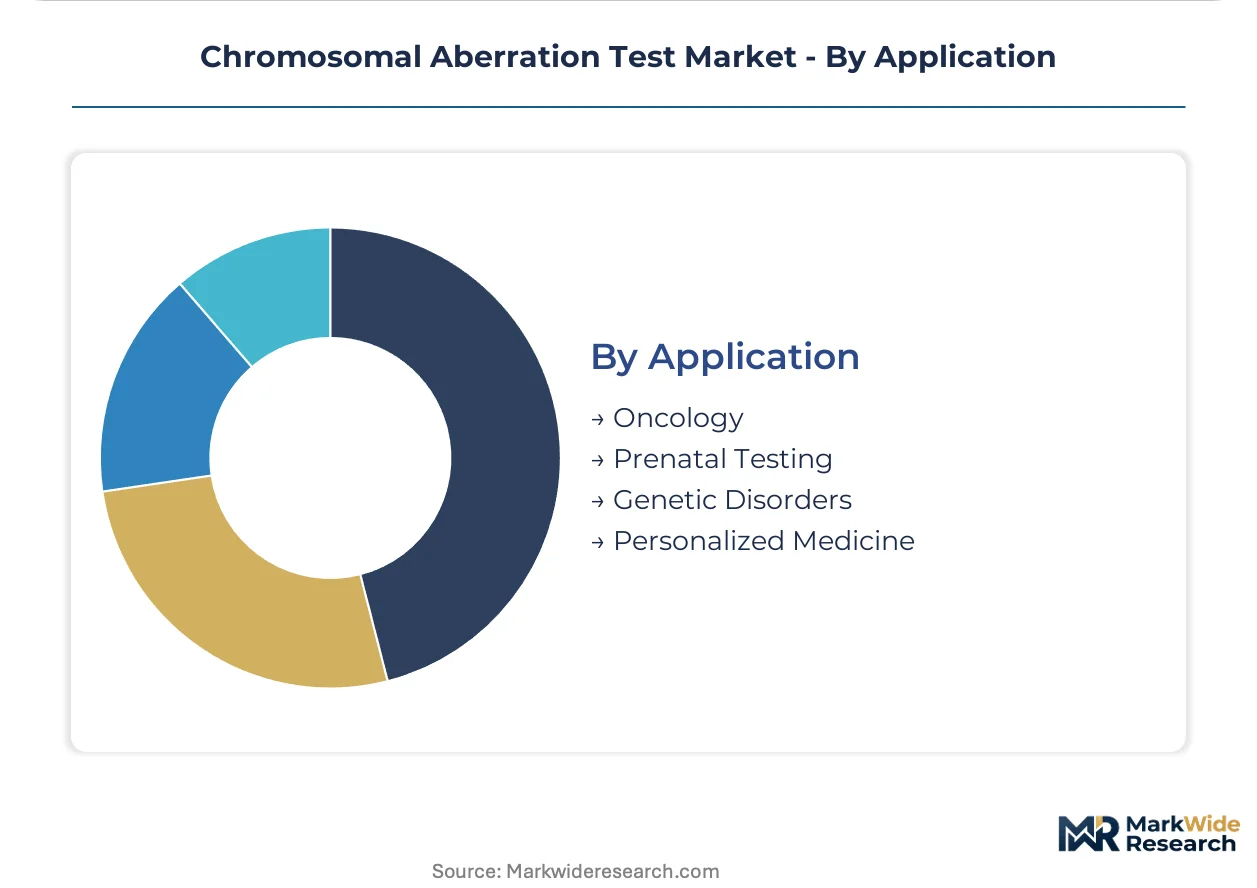
Application:
Application segments reflect divergent reimbursement environments and clinical urgency profiles that reshape test menu prioritization.
- Oncology:Solid tumor and hematologic malignancy testing drives fluorescence in situ hybridization volume for therapeutic selection. United States pathology departments require rapid HER2, ALK, and MYC status determination to guide targeted therapy decisions. Companion diagnostic development partnerships link test manufacturers to pharmaceutical sponsors.
- Prenatal Testing:Non-invasive prenatal testing uptake is accelerating demand for confirmatory invasive cytogenetic procedures. Maternal-fetal medicine clinics in Germany and Japan maintain high karyotyping and microarray utilization for definitive diagnosis.
- Genetic Disorders:Constitutional abnormality detection serves pediatric and adult rare disease diagnostic odysseys.
- Personalized Medicine:Pharmacogenomic and tumor profiling applications are emerging as precision oncology expands.
Oncology leads by procedure volume. Personalized Medicine is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports chromosomal aberration testing services and platforms to pharmaceutical sponsors across the European Union and United States, anchoring a trade corridor that channels regulatory toxicology expertise toward North American drug development pipelines.
United States
FDA premarket review timelines and ICH S2(R1) genotoxicity guidelines drive toxicology screening demand among biotechnology developers. The agency's reproductive toxicity testing requirements shape purchasing patterns for GLP-compliant chromosomal aberration assays. Greater Boston's concentration of contract research organizations processes substantial pharmaceutical sponsor volume.
Germany
EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements that filter platform market access across EU member states. The country's national pharmaceutical regulator enforces stringent laboratory accreditation standards under IVDR transition timelines. Bavaria's clinical cytogenetics laboratories adopt optical genome mapping for constitutional disorder resolution.
Japan
PMDA guidance on companion diagnostics accelerates fluorescence in situ hybridization adoption for solid tumor biomarker testing. METI industrial standards support domestic sequencing platform development for prenatal applications. Kansai region pathology departments maintain rapid HER2 and ALK status determination workflows.
India
CDSCO regulatory harmonization initiatives expand accredited cytogenetic laboratory networks beyond metropolitan hospital clusters. The country's national pharmaceutical regulator aligns with OECD test guidelines for genotoxicity assessment. Maharashtra's diagnostic chains build distributed testing infrastructure for prenatal and oncology screening.
United Kingdom
NHS England commissioning frameworks reshape reimbursement for non-invasive prenatal testing confirmatory procedures. The national health technology assessment body evaluates sequencing platform cost-effectiveness against conventional karyotyping. London's academic medical centers drive bioinformatics pipeline adoption for copy-number variant detection.
Chromosomal Aberration Test Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where integrated life science conglomerates anchor the premium segment and regional service laboratories occupy mid-market positions. The vendor base stratifies between capital-intensive platform manufacturers and service-dominant contract research organizations. Two strategic archetypes dominate: sequencing platform developers with captive bioinformatics ecosystems, and distributed laboratory networks leveraging multi-jurisdictional regulatory accreditations. Competitive moves center on M&A consolidation of niche toxicology service providers and technology licensing partnerships that embed sequencing workflows into hospital laboratory information systems.
Among United States-based conglomerates, Thermo Fisher Scientific, Inc. and Laboratory Corporation of America Holdings exemplify the platform-service integration archetype, while Charles River Laboratories International occupies a position representing the GLP-compliant toxicology specialist tier. These three entities anchor distinct competitive vectors without overlapping strategic positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Charles River Laboratories International |
| Laboratory Corporation of America Holdings |
| Eurofins Scientific |
| Syngene International Limited |
| Jubilant Life Sciences Limited |
| Gentronix Ltd. |
| Inotiv Inc. |
| Creative Bioarray |
| Others |
Value Network & Pricing Analysis
Single-source dependency on Ion Torrent and NovaSeq consumables determines both pricing tier spreads and supply chain shape across clinical cytogenetic laboratories. ICH M7(R2) compliance mandates create a dual-track procurement environment where GLP-certified reagents command premium positioning against research-use alternatives.
Pricing Analysis
Next-generation versus legacy platform pricing gaps exceed threefold across equivalent test volumes, with sequencing-based cytogenetic assays positioned at premium tiers against karyotyping and FISH alternatives. A three-tier pricing structure across premium, standard, and economy levels stratifies by bioinformatics support depth, with bundled variant interpretation commanding highest positioning. Cost compression in standard-tier karyotyping services is intensifying because hospital laboratories internalize slide preparation workflows. Pharmaceutical toxicology sponsors demonstrate least price sensitivity due to regulatory submission imperatives, while independent diagnostic networks in India negotiate aggressively on per-sample rates.
Supply Chain Analysis
Extended payment terms from sequencing platform manufacturers to academic medical center buyers now stretch 90-120 days, reflecting supplier-financing pressure amid capital deployment cycles. Manufacturing concentration in the United States, Germany, and Japan anchors reagent and instrument supply, with optical genome mapping hardware drawing from specialized component ecosystems in Bavaria and Massachusetts. Semiconductor shortages in flowcell production create single-source vulnerability for Illumina-dependent laboratories. Distribution runs through authorized distributor networks in regulated markets and direct procurement relationships in research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chromosomal aberration test market sits in early-cycle recovery following IVDR implementation disruptions, with pharmaceutical toxicology screening budgets expanding as ICH guideline harmonization restores regulatory clarity.
For Market Incumbents: Pre-empt optical genome mapping displacement of FISH in constitutional disorder workflows by accelerating platform validation partnerships with German and Japanese reference laboratories. Consolidate niche toxicology service providers in Greater Boston and Bavaria to defend GLP-compliant market share against unbundled CRO offerings. Certification investment in IVDR Annex IX quality management systems represents the critical lever for European Union market retention.
For New Entrants and Emerging Players: India's accredited cytogenetic laboratory networks outside metropolitan hospital clusters represent the most penetrable entry point for distributed testing infrastructure. Mid-cap biotechnology developers with limited internal toxicology infrastructure offer à la carte chromosomal aberration assay demand without bundled package requirements. A go-to-market angle anchored to WHO laboratory quality standards harmonization reduces protocol validation friction for international accreditation.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors GLP-compliant toxicology specialists with captive pharmaceutical sponsor relationships. Long-term viability hinges on bioinformatics pipeline differentiation as sequencing commoditizes. Acquisition targets should demonstrate proven copy-number variant algorithm validation and multi-jurisdictional regulatory accreditations. The signal to watch is CRO unbundling velocity among United States biotechnology developers as a predictor of discrete assay demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration with LIS | Sequencing pipeline embedding into hospital laboratory information systems reduces workflow friction for cytogenetic laboratories. |
| Multi-Jurisdictional Accreditation | IVDR, FDA, and PMDA quality certifications expand addressable market for contract research organizations serving global pharmaceutical sponsors. |
| Bioinformatics Pipeline Development | Copy-number variant detection algorithms address talent scarcity constraining clinical interpretation capacity in the United States and European Union. |
| Optical Genome Mapping Validation | German and Japanese reference laboratory partnerships establish clinical evidence for constitutional disorder applications beyond microarray resolution. |
| GLP-Compliant Service Expansion | OECD test guideline-aligned toxicology screening captures pharmaceutical sponsor outsourcing as internal capabilities contract. |
Research Methodology
A standing panel of clinical cytogenetics laboratory directors, pharmaceutical toxicology executives, regulatory affairs specialists, and bioinformatics pipeline developers provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA 510(k) filings, EMA IVDR technical documentation, ClinicalTrials.gov genotoxicity study registrations, and OECD test guideline revision drafts. Bottom-up test volume modeling and top-down pharmaceutical R&D expenditure analysis were triangulated against platform installation databases.
Scenario-bracketing around IVDR implementation timelines, NIPT confirmatory procedure reimbursement shifts, and pharmaceutical outsourcing elasticity shaped analytical framework construction across the projection horizon. Segmentation dimensions spanned technology platform, end-user capability tier, application indication, and regional regulatory cluster. CAGRs were derived from installed base expansion rates, test menu migration patterns, and per-sample pricing trajectory assumptions. Forecast inputs incorporated bioinformatics talent pipeline constraints and sequencing platform replacement cycle dynamics.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D funding, healthcare reimbursement policy, or semiconductor supply availability would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and technology substitution elasticities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Kidney Function Tests Market