
 Global Electronic Clinical Outcome Assessment Solutions Market | 2026-2036
Global Electronic Clinical Outcome Assessment Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Clinical Outcome Assessment Solutions Market Foresight
The EU Medical Device Regulation is decoupling paper-based patient assessments from acceptable clinical evidence standards across European pharma sponsors. Medidata Solutions leverages its platform scale to anchor cloud deployments across multinational trial portfolios. IQVIA sustains competitive density through integrated real-world evidence services that bundle eCOA with broader data offerings.
Electronic Clinical Outcome Assessment Solutions comprise software platforms, mobile applications, and connected devices that capture standardized patient-reported and clinician-reported data through validated instruments, transmitting encrypted responses to centralized trial databases with audit trails and regulatory-grade data integrity. These systems serve the core commercial purpose of replacing paper diaries and site-based assessments with timestamped, tamper-evident digital records that satisfy FDA 21 CFR Part 11 and EMA data quality requirements. eCOA Platforms occupy the deepest margin pools where configuration complexity and regulatory validation create switching costs for sponsors. Mobile Applications are capturing the fastest expansion as bring-your-own-device protocols reduce patient burden in decentralized trials. Wearable Devices remain nascent but specialize in capturing objective functional measures that complement subjective patient reports.
FDA enforces 21 CFR Part 11 compliance for electronic records in clinical investigations, while EMA's ICH E6(R2) guidelines mandate risk-based quality management that elevates eCOA audit capabilities. The FDA's draft guidance on decentralized clinical trials is reshaping deployment requirements for remote patient monitoring technologies. Stakeholders must monitor how evolving EMA and FDA convergence on eSource standards will determine platform interoperability investments and vendor qualification protocols.
Market Dynamics
Decentralized trial protocols are compressing site-based data collection infrastructure, forcing sponsors to reconfigure validation workflows around patient-owned devices and remote monitoring endpoints.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in US clinical investigations compel sponsors to retire paper diaries for timestamped digital capture systems.
- Biotech clusters:Concentrated R&D spending in Boston and San Francisco accelerates procurement of cloud-native assessment platforms for phase II-III trials.
- Bring-your-own-device protocols:Patient-owned smartphones reduce hardware distribution costs while expanding enrollment access across rural and elderly populations.
Market Restraints
- Platform switching costs:Validated instrument libraries and site training investments lock sponsors into incumbent vendors despite superior alternatives.
- EU MDR compliance timelines:European device regulation extends qualification periods for connected diagnostic peripherals, delaying trial start dates.
- Data localization requirements:China's cybersecurity law and Russia's data sovereignty rules fragment cloud architectures, raising infrastructure complexity for multinational sponsors.
Strategic Opportunities
- Japan's PMDA decentralized trial guidance:Regulatory clarity on remote monitoring creates first-mover advantage for eCOA vendors with Japanese language validation.
- Wearable-PRO convergence:Integration of accelerometer data with patient-reported outcomes opens objective functional measures in neurology and respiratory trials.
- Direct-to-patient distribution:Bypassing investigative sites for device provisioning and support contracts reduces per-patient costs by eliminating site markup.
Industry Challenges
- 21 CFR Part 11 audit trail gaps:Mobile operating system updates frequently invalidate timestamp integrity, requiring continuous revalidation cycles.
- Site workforce retraining:Investigators and coordinators lack proficiency in troubleshooting patient-reported technical failures on diverse device ecosystems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Clinical Outcome Assessment Solutions Market |
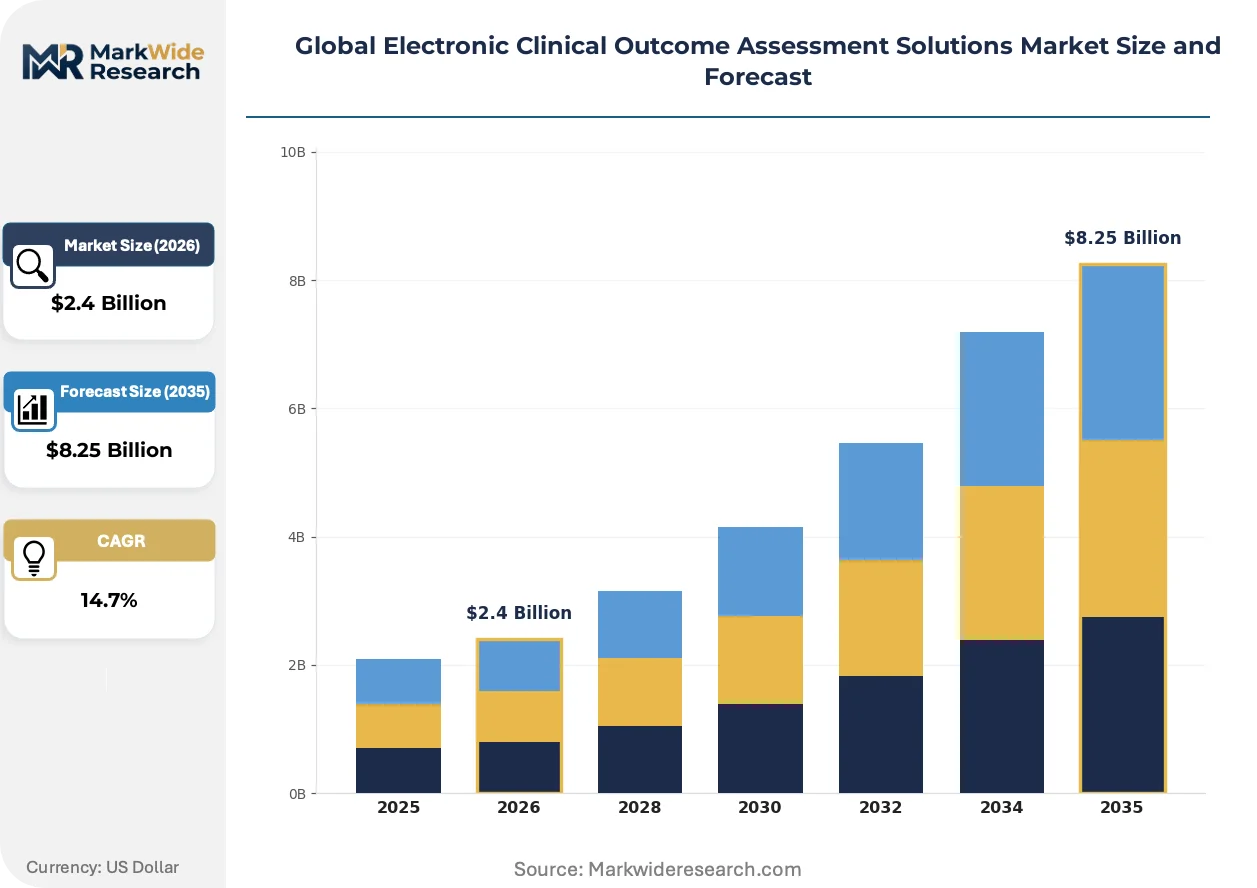
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.25 Billion |
| CAGR (2026 – 2036) | 14.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: eCOA Platforms, Mobile Applications, Web-Based Tools, Electronic Data Capture, Wearable Devices Application Area: Clinical Trials, Patient-Reported Outcomes, Real-World Evidence, Disease Monitoring, Treatment Effectiveness End User: Pharmaceutical Companies, Contract Research Organizations, Biotech Firms, Academic Research, Medical Device Manufacturers Deployment Model: Cloud-Based, On-Premise, Hybrid, SaaS, Dedicated Hosting |
| Companies Covered | Medidata Solutions, IQVIA, Signant Health, Clario, ICON plc, Oracle Corporation, Parexel International, Veeva Systems, YPrime, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Clinical Outcome Assessment Solutions Market Shifts & Advancements
Platform architectures are converging around modular microservices that decouple instrument validation from deployment infrastructure, enabling faster reconfiguration across therapeutic areas.
Cloud-native eCOA platforms are consolidating vendor landscapes as pharmaceutical sponsors prioritize single-provider contracts covering electronic patient-reported outcomes, clinician-reported outcomes, and observer-reported outcomes. Mid-tier CROs are accelerating adoption to match larger rivals' data integration capabilities. The technology is consolidating margin pools around configuration specialists who can navigate multi-regulatory validation requirements.
EMA's ICH E6(R2) risk-based quality management guidelines are elevating audit trail capabilities from checkbox compliance to competitive differentiation. Sponsors must now demonstrate proactive detection of anomalous response patterns. European phase III oncology trials are most affected, with sponsors deploying machine learning-based signal detection to satisfy inspector expectations.
Patient enrollment behavior is fragmenting across demographic cohorts, with elderly participants demanding telephone backup support while younger cohorts reject anything beyond native mobile applications. Site-based recruitment is losing share to direct-to-patient digital advertising and social media outreach. This shift is most visible in United States immunology trials, where geographic dispersion of rare disease populations makes traditional site density models uneconomical.
Global Electronic Clinical Outcome Assessment Solutions Market Segmentation
eCOA solution architecture fragments across four structural dimensions that determine procurement patterns and margin capture. Certification requirements, deployment complexity, and end-user sophistication create divergent commercial dynamics within each category.
Solution Type:
FDA 21 CFR Part 11 compliance burdens concentrate most heavily on platforms handling electronic records and signatures, while mobile and wearable segments navigate lighter but expanding validation requirements.
- eCOA Platforms:Comprehensive software systems integrating instrument libraries, patient diaries, and clinician interfaces with built-in audit trails and regulatory-grade data integrity. Demand concentrates among phase III oncology sponsors in the United States where multi-site trial complexity requires centralized configuration management and 21 CFR Part 11 validation creates substantial switching costs.
- Mobile Applications:Native and web-based patient-facing interfaces deployed on smartphones and tablets under bring-your-own-device protocols. Biotech clusters in Boston and San Francisco are accelerating procurement as decentralized trial models reduce hardware distribution overhead and expand rural patient access.
- Web-Based Tools:Browser-accessible assessment interfaces requiring no local installation, typically deployed for clinician-reported outcomes and site-based data entry.
- Electronic Data Capture:Backend systems managing case report forms and clinical database structures, often bundled with eCOA functionality or deployed as separate modules.
- Wearable Devices:Connected sensors capturing objective functional measures including accelerometry, heart rate variability, and sleep architecture to complement subjective patient reports.
eCOA Platforms sit at the top of the volume ranking, with Mobile Applications climbing the fastest.
Application Area:
Commercial intensity varies sharply by therapeutic use case, with trial-phase applications commanding premium pricing against post-market surveillance tools.
- Clinical Trials:Regulatory-grade data collection for investigational product evaluation across all phases, requiring full 21 CFR Part 11 or EMA ICH E6(R2) compliance with comprehensive audit trails and risk-based quality management.
- Patient-Reported Outcomes:Direct capture of symptoms, quality of life, and functional status from trial participants, with demand surging in United States immunology studies where geographic dispersion of rare disease populations makes traditional site density models uneconomical.
- Real-World Evidence:Post-authorization safety and effectiveness monitoring using non-interventional study designs with reduced validation requirements.
- Disease Monitoring:Longitudinal tracking of chronic conditions outside formal trial structures, typically deployed through health system partnerships.
- Treatment Effectiveness:Comparative effectiveness research and value demonstration studies for payer negotiations.
Clinical Trials capture the largest revenue pool, with Patient-Reported Outcomes expanding most quickly.
End User:
Procurement sophistication and contract scale diverge dramatically across buyer types, from multinational pharmaceutical enterprises to resource-constrained academic centers.
- Pharmaceutical Companies:Large-cap sponsors with centralized vendor qualification programs and preference for single-provider contracts covering electronic patient-reported outcomes, clinician-reported outcomes, and observer-reported outcomes across global trial portfolios.
- Contract Research Organizations:Full-service and functional providers competing on data integration capabilities, with mid-tier CROs accelerating eCOA adoption to match larger rivals.
- Biotech Firms:Venture-backed developers in Boston and San Francisco driving procurement of cloud-native assessment platforms for phase II-III trials with limited internal IT infrastructure.
- Academic Research:University medical centers and independent investigators with constrained budgets and preference for open-source or institutionally licensed tools.
- Medical Device Manufacturers:Sponsors of device trials navigating EU MDR compliance timelines that extend qualification periods for connected diagnostic peripherals.
Pharmaceutical Companies dominate contract value, with Biotech Firms gaining share fastest.
Deployment Model:
Infrastructure choices determine data sovereignty compliance, operational flexibility, and total cost of ownership across multinational trial footprints.
- Cloud-Based:Multi-tenant SaaS architectures with automatic updates and elastic scaling, preferred by sponsors seeking rapid deployment without capital infrastructure investment.
- On-Premise:Self-managed installations within sponsor or site data centers, retained by organizations with legacy compliance frameworks or restrictive data localization requirements in China and Russia.
- Hybrid:Mixed architectures separating patient-facing components in cloud environments from sensitive clinical databases in controlled on-premise environments.
- SaaS:Subscription-based software delivery with vendor-managed infrastructure and shared responsibility for validation documentation.
- Dedicated Hosting:Single-tenant cloud deployments providing isolation without full on-premise capital burden, increasingly selected for phase III trials requiring enhanced data segregation.
Cloud-Based deployments hold the volume lead, with Hybrid models ascending fastest amid data sovereignty fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The electronic clinical outcome assessment industry traces its commercial roots to United States pharmaceutical hubs where FDA 21 CFR Part 11 mandates first compelled sponsors to abandon paper diaries. Early platform development concentrated around Boston and San Francisco biotech clusters before expanding to European regulatory compliance centers and Asia-Pacific trial growth markets.
United States
FDA enforcement of 21 CFR Part 11 electronic records standards drives sponsor procurement of validated timestamp capture systems. The agency's draft guidance on decentralized clinical trials accelerates bring-your-own-device protocol adoption. Boston and San Francisco biotech clusters anchor cloud-native platform demand for phase II-III oncology and immunology studies.
Germany
EMA ICH E6(R2) risk-based quality management guidelines elevate audit trail capabilities as competitive differentiators for German contract research organizations. The EU Medical Device Regulation extends qualification timelines for connected diagnostic peripherals in device trials. Frankfurt and Munich host multinational sponsor procurement centers prioritizing single-provider eCOA contracts.
Japan
PMDA decentralized trial guidance creates regulatory clarity for remote patient monitoring technologies. Pharmaceutical sponsors accelerate Japanese language validation investments for platform localization. Tokyo and Osaka medical centers pilot wearable-PRO convergence in neurology trials requiring objective functional measures.
China
NMPA clinical data integrity requirements align with international eSource standards while cybersecurity law fragments cloud architectures. Domestic sponsors navigate data localization mandates for patient-reported outcome platforms. Shanghai and Beijing biotech parks attract multinational eCOA vendors establishing compliant hosting infrastructure.
United Kingdom
MHRA post-Brexit regulatory divergence from EMA creates parallel validation requirements for UK trial sites. London-based pharmaceutical headquarters drive demand for hybrid cloud deployments separating patient-facing components from clinical databases. Cambridge and Oxford academic medical centers advance open-source instrument libraries for academic research budgets.
Global Electronic Clinical Outcome Assessment Solutions Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory validation depth and instrument library breadth. The vendor landscape consolidates around platform-scale specialists with multinational deployment capabilities and mid-tier configurators competing on therapeutic-area speed. Three archetypes dominate: integrated clinical technology conglomerates, pure-play eCOA platform vendors, and CRO-embedded service providers. Competitive intensity centers on M&A activity absorbing point-solution vendors and strategic partnerships bundling eCOA with electronic data capture and clinical trial management systems.
Within the integrated technology tier, Medidata Solutions and Oracle Corporation exemplify platform-scale positioning through cloud infrastructure and enterprise software lineage. IQVIA occupies a distinct archetype bridging real-world evidence services with eCOA deployment, reflecting CRO-consolidation strategy. These three entities represent contrasting origins—clinical software specialization, database enterprise expansion, and contract research integration—illuminating how regulatory validation depth and global site network access determine competitive position.
| Leading Market Players |
|---|
| Medidata Solutions |
| IQVIA |
| Signant Health |
| Clario |
| ICON plc |
| Oracle Corporation |
| Parexel International |
| Veeva Systems |
| YPrime |
| Others |
Supply & Pricing Matrix
FDA 21 CFR Part 11 validation requirements gate qualified supply access and premium-tier pricing power for eCOA platform vendors, compressing margins for non-compliant configurators while elevating validated instrument libraries to strategic differentiators. Pharmaceutical sponsors in Boston and San Francisco biotech clusters absorb cost premiums for regulatory-grade audit trails, forcing mid-tier CROs toward economy-tier SaaS deployments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by regulatory validation depth and instrument library breadth. Premium tiers capture sponsors requiring 21 CFR Part 11 compliance with built-in audit trails, while economy SaaS subscriptions attract academic researchers with constrained budgets. Cost compression in standard-tier mobile applications intensifies as bring-your-own-device protocols commoditize patient-facing interfaces. Biotech firms exhibit highest price sensitivity, prioritizing rapid deployment over customization depth.
Supply Chain Analysis
Freight costs for connected diagnostic peripherals from Germany and Japan amplify total cost of ownership for EU MDR-compliant device trials. Software development talent concentrates in the United States, India, and Ireland, with cloud infrastructure anchoring in Frankfurt and Singapore data centers. Single-source vulnerability in Japanese-language validation services threatens trial timelines for PMDA submissions. Distribution runs through vendor-managed SaaS portals with direct-to-patient device provisioning bypassing investigative sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
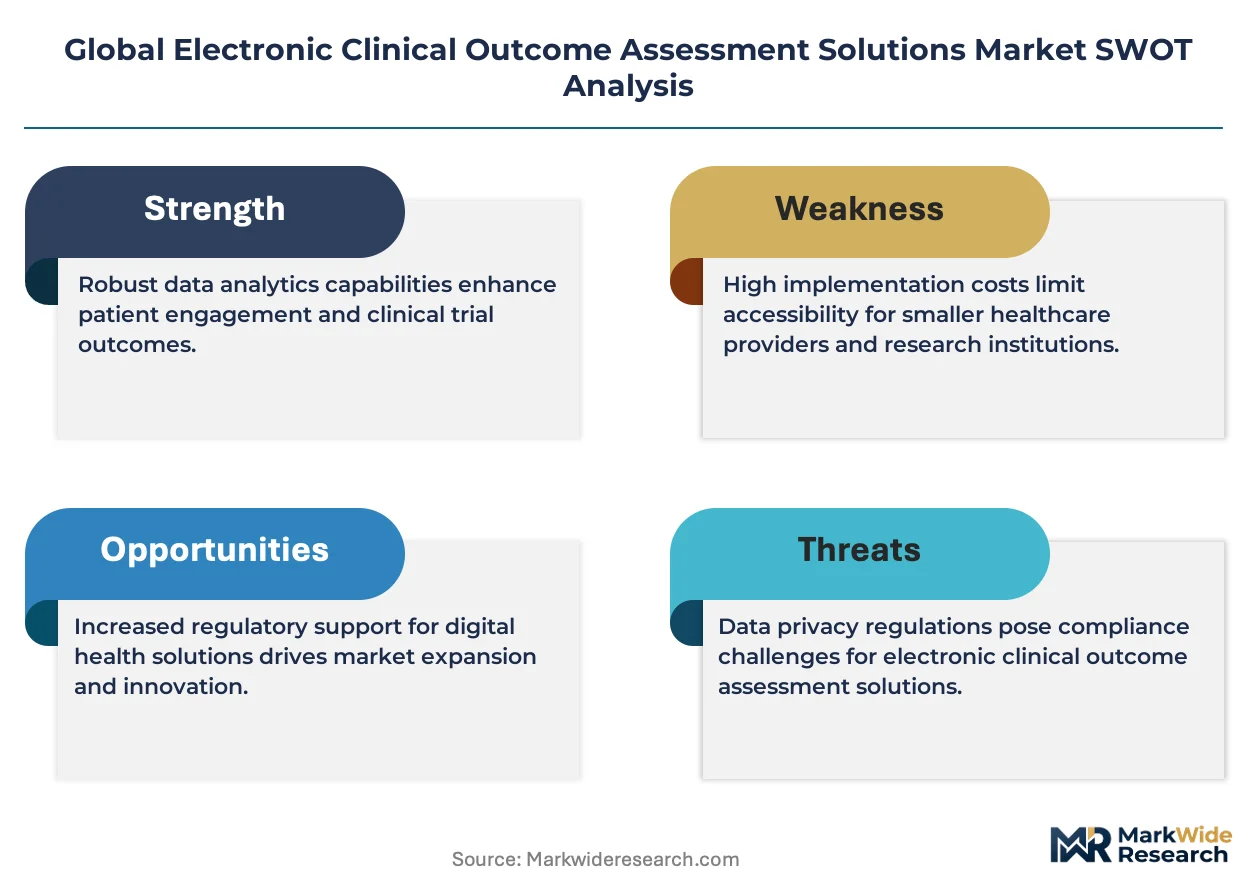
The Global Electronic Clinical Outcome Assessment Solutions Market functions as a geographic-arbitrage play where Japanese regulatory clarity on decentralized trials commands premium pricing against fragmented EU MDR compliance timelines.
For Market Incumbents: Hedge against wearable-PRO convergence disruption by acquiring accelerometer analytics specialists and deepening Japanese-language platform localization. Incumbent vendors must anchor cloud deployments in Frankfurt and Singapore to preempt data sovereignty fragmentation while defending instrument library switching costs against modular microservices challengers. For New Entrants and Emerging Players: The mid-tier price-point gap between validated platform incumbents and economy SaaS configurators opens white-space in hybrid cloud deployments for UK MHRA post-Brexit trials. Target academic medical centers in Cambridge and Oxford with open-source instrument libraries. Pursue direct-to-patient distribution partnerships eliminating site markup. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier eCOA configurators because regulatory validation depth creates customer captivity and EMA-FDA convergence on eSource standards accelerates vendor consolidation. Five-to-ten-year viability hinges on platform-scale deployment capabilities. Watch PMDA decentralized trial guidance adoption rates as inflection signal for Japanese market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Validation Investment | 21 CFR Part 11 compliance anchors premium-tier pricing and customer retention. |
| Japanese Language Localization | PMDA guidance clarity creates first-mover positioning in decentralized trial expansion. |
| Wearable-PRO Integration | Accelerometer data convergence captures neurology trial objective functional measures. |
| Hybrid Cloud Deployment | MHRA post-Brexit divergence demands UK-EU data segregation architecture. |
| Direct-to-Patient Distribution | Bypassing site markup reduces per-patient costs in rare disease immunology trials. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads, clinical data managers, eCOA platform engineers, and hospital procurement committees with secondary validation against FDA 21 CFR Part 11 guidance documents, EMA ICH E6(R2) submissions, ClinicalTrials.gov registry data, and GPO contract databases. Bottom-up instrument deployment counts triangulated against top-down sponsor IT spending estimates.
Segment-weighting across the modeling period applied differential growth assumptions to eCOA platforms, mobile applications, wearable devices, and web-based tools by therapeutic area, trial phase, deployment model, and regional regulatory cluster. CAGRs derived from sponsor procurement velocity in Boston and San Francisco biotech corridors, EU MDR compliance timeline impacts, and PMDA decentralized trial guidance adoption curves.
Caveats apply where FDA eSource standard revisions or EMA-FDA convergence delays could materially shift the outlook for platform interoperability investments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Global High-Resolution Melting Analysis Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Oral Cancer Diagnostics Market