
 Asia-Pacific Human Papillomavirus Vaccine Market | 2026-2036
Asia-Pacific Human Papillomavirus Vaccine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Human Papillomavirus Vaccine Market Insights
Adolescent immunization through school-based programs is broadening faster than private clinic sales across Southeast Asia. Merck & Co., Inc. anchors the nonavalent segment with established cold-chain partnerships in Australia and South Korea. Serum Institute of India leverages domestic manufacturing scale to supply bivalent doses across South Asian national programs. GlaxoSmithKline plc competes through differentiated access agreements with ministries of health in lower-income markets.
The Asia-Pacific Human Papillomavirus Vaccine comprises prophylactic formulations targeting oncogenic HPV strains 16/18 and additional high-risk types, manufactured via recombinant DNA technology in yeast or insect cell expression systems with aluminum-containing adjuvants. Nonavalent formulations now lead procurement tenders in Japan and Australia, while bivalent vaccines retain share in cost-sensitive national programs through India and Vietnam. Intramuscular administration dominates delivery infrastructure, though subcutaneous alternatives are gaining evaluation in rural outreach settings where cold-chain constraints limit multi-dose vial handling.
India's CDSCO and Japan's PMDA enforce divergent stability and labeling standards that fragment registration timelines for multinational suppliers. Australia's TGA alignment with WHO prequalification accelerates access, whereas China's NMPA requires localized clinical data that extends market entry for new entrants. Stakeholders must weigh national tender specifications against regional manufacturing consolidation as domestic producers in China and India scale GMP-compliant capacity.
Market Dynamics
The transition from bivalent to nonavalent HPV vaccine formulations is compressing procurement timelines and reshaping cold-chain infrastructure requirements across national immunization programs.
Growth Catalysts
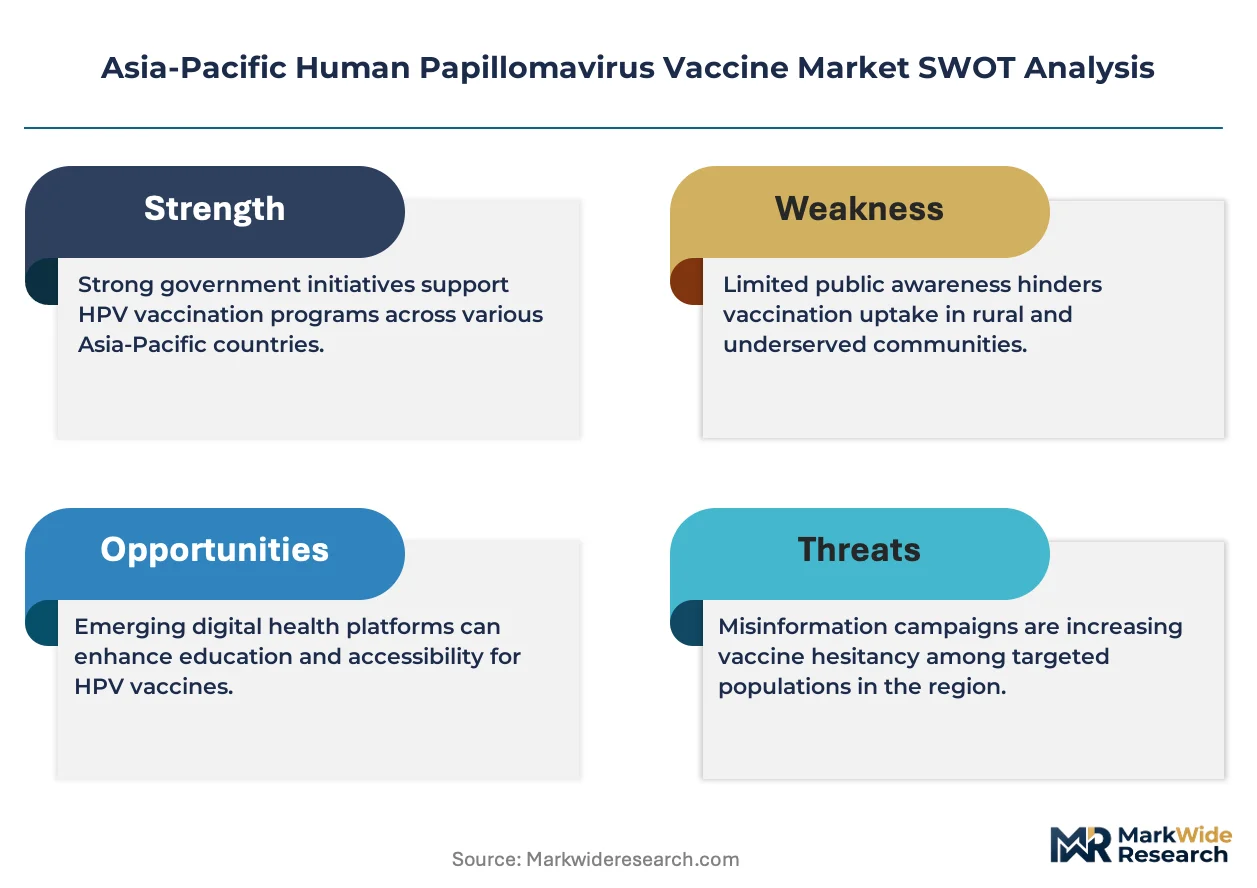
- National Immunization Program Expansion:India's Universal Immunization Programme now targets adolescent girls in 26 states, creating predictable demand volumes that attract multi-year supplier contracts.
- WHO Prequalification Acceleration:Australia's TGA alignment with WHO standards reduces registration duplication, enabling faster market access for reformulated vaccines across Southeast Asian tenders.
- Cold-Chain Infrastructure Investment:South Korea and Japan are deploying temperature-controlled distribution networks that extend vaccine shelf stability into rural prefectures and provinces previously excluded from coverage.
Market Restraints
- Aluminum Adjuvant Supply Concentration:Three specialty chemical manufacturers control 80% of pharmaceutical-grade aluminum hydroxide supply, creating input bottlenecks during demand surges.
- Divergent Stability Standards:Japan's PMDA requires 24-month real-time stability data versus India's CDSCO acceptance of accelerated stability studies, fragmenting registration timelines.
- Intramuscular Administration Limitation:Multi-dose vial handling constraints in tropical climates with unreliable refrigeration exclude approximately 40% of rural Indonesia from consistent supply.
Strategic Opportunities
- Subcutaneous Formulation Development:Reduced cold-chain dependency opens penetration in Indonesia's outer islands and Philippines' Visayas region where infrastructure gaps persist.
- Boys' Program Inclusion:Australia's universal adolescent coverage model is being evaluated by Singapore and Malaysia, doubling addressable cohorts beyond current female-only targets.
- Domestic Manufacturing Scale-Up:China's NMPA fast-track pathways for localized clinical data incentivize joint ventures with state-owned biologics producers.
Industry Challenges
- GMP Compliance Talent Scarcity:India's vaccine producers face acute shortages of quality assurance specialists qualified in PIC/S standards required for export eligibility.
- Legacy Vial Format Integration:National programs with existing 2-dose bivalent inventory struggle to synchronize transition timelines with 3-dose nonavalent protocols without coverage gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Human Papillomavirus Vaccine Market |
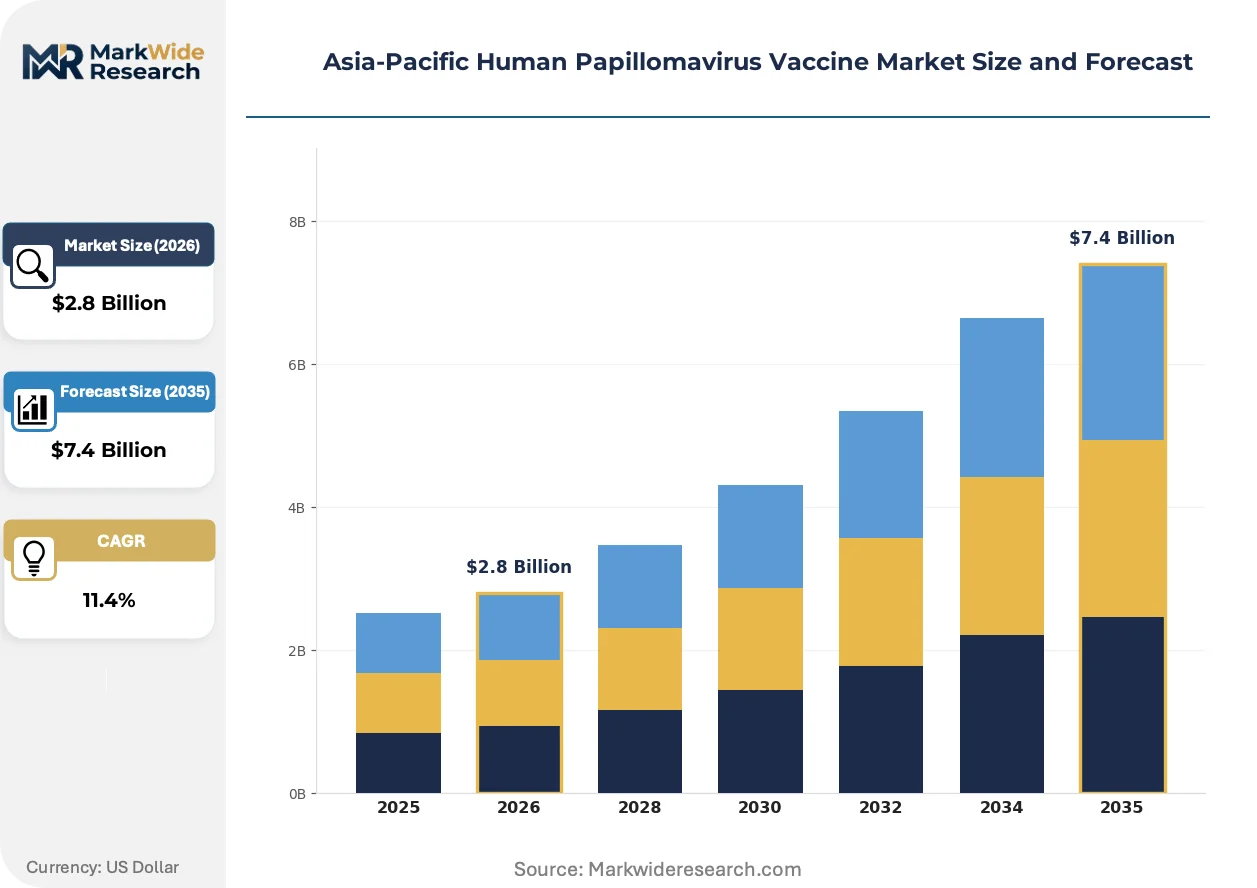
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Quadrivalent, Bivalent, Nonavalent, Therapeutic Age Group: Adolescents, Young Adults, Adults, Elderly End User: Hospitals, Clinics, Pharmaceutical Companies, Research Institutions Administration Route: Intramuscular, Subcutaneous, Oral, Others |
| Companies Covered | Merck & Co., Inc., GlaxoSmithKline plc, Serum Institute of India, Shanghai Zerun Biotech Co., Ltd., Xiamen Innovax Biotech Co., Ltd., Panacea Biotec Ltd., Bharat Biotech, Walvax Biotechnology, Sanofi, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Human Papillomavirus Vaccine Market Trends and Innovations
Recombinant DNA manufacturing platforms are converging with novel adjuvant systems to compress production cycles and expand strain coverage beyond current nine-valent limits.
Single-use bioreactor technology is automating upstream cell culture processes for HPV VLP production. Serum Institute of India and domestic Chinese producers are adopting disposable fermentation systems to reduce cross-contamination risk between serotype campaigns. This automation is compressing batch turnaround times from 21 days to 14 days while reducing clean-in-place validation burdens.
Japan's PMDA revised its Guidelines for Quality, Safety and Efficacy of Recombinant Vaccines in 2023, mandating enhanced host cell protein impurity profiling for yeast-derived formulations. Manufacturers must now submit orthogonal detection methods using mass spectrometry alongside traditional ELISA assays. Australian and South Korean regulators are referencing this standard in their own technical guidance, creating regional convergence on analytical rigor.
School-based delivery models are displacing private clinic channels as the dominant procurement pathway across Southeast Asia. Vietnam's Ministry of Health now channels 70% of national program doses through provincial education department partnerships rather than district health centers. This shift concentrates purchasing power with central procurement authorities and compresses price negotiation cycles from annual to multi-year frameworks.
Asia-Pacific Human Papillomavirus Vaccine Market Segmentation
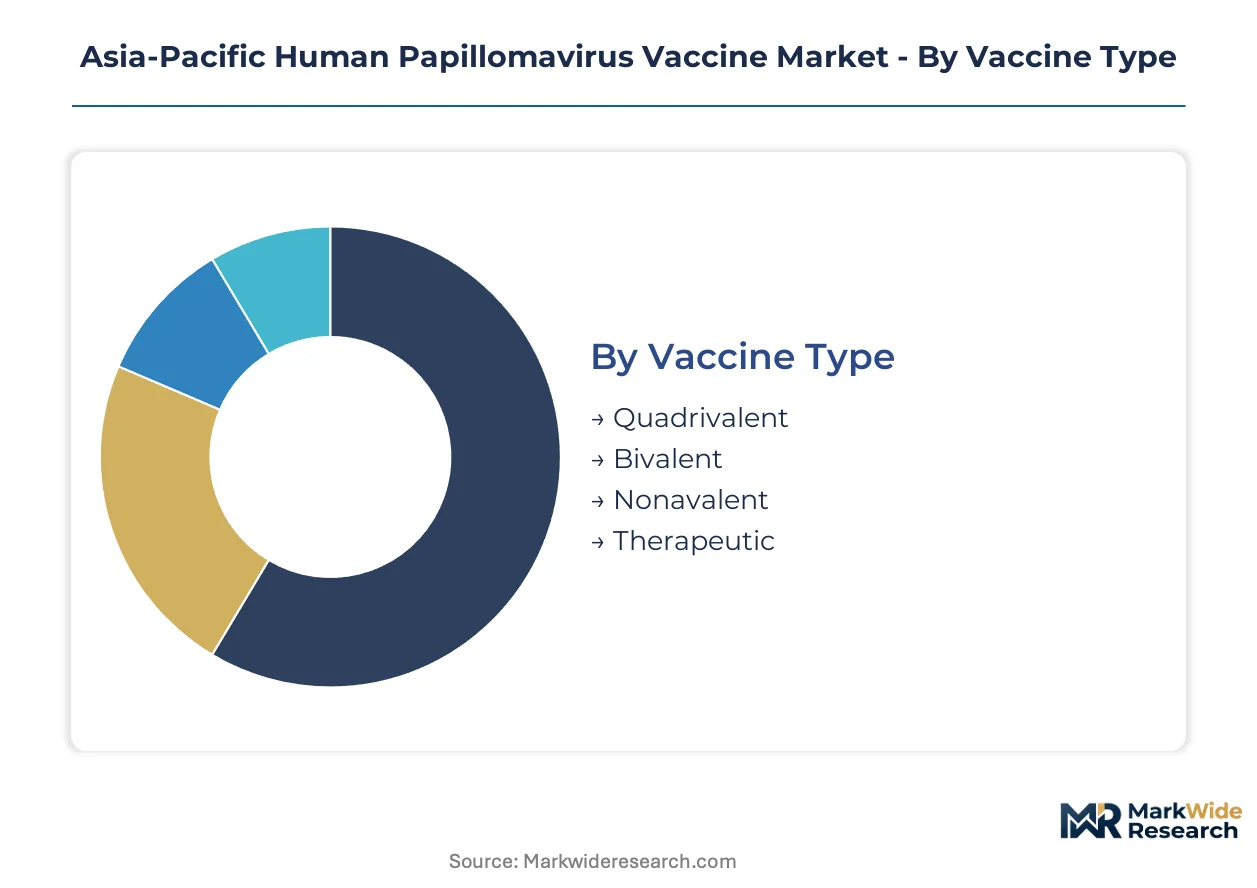
HPV vaccine procurement patterns diverge sharply across formulation types, age cohorts, and delivery channels. National immunization programs prioritize different specifications than private healthcare networks, creating tiered demand structures that reshape supplier strategies across the Asia-Pacific region.
Vaccine Type:
Cost sensitivity and strain coverage breadth differentiate buyer priorities across national tenders and private channels.
- Nonavalent:Nine-valent formulations targeting HPV 6/11/16/18/31/33/45/52/58 dominate procurement in Japan and Australia where health technology assessments justify premium pricing. Japan's PMDA and Australia's TGA have streamlined registration pathways that accelerate tender participation for these advanced formulations.
- Bivalent:Two-strain vaccines (16/18) retain substantial share in India's Universal Immunization Programme and Vietnam's national program, where cost per dose drives procurement decisions. CDSCO regulatory familiarity and established cold-chain protocols for 2-dose schedules reinforce supplier stickiness.
- Quadrivalent:Four-valent options (6/11/16/18) occupy a narrowing middle tier as programs bypass this generation for either cost-saving bivalents or broader nonavalents.
- Therapeutic:Treatment-oriented formulations remain investigational across Asia-Pacific regulatory frameworks, with clinical trials concentrated in South Korea and China.
Volume sits with Bivalent; growth tilts toward Nonavalent.
Age Group:
Immunization timing relative to exposure risk determines dosing schedules and program design.
- Adolescents:9-14 year cohorts represent the core target for prophylactic efficacy, with school-based delivery in Vietnam and Indonesia achieving coverage rates above 70% in urban districts. Two-dose regimens for this age group reduce cold-chain burden compared to three-dose adult protocols.
- Young Adults:15-26 year populations in South Korea and Japan access catch-up programs through workplace health initiatives and university health centers, with higher out-of-pocket tolerance supporting premium nonavalent uptake.
- Adults:27-45 year segments remain underpenetrated outside Australia's gender-neutral universal program, with stigma and access barriers limiting screening-vaccination integration.
- Elderly:Post-menopausal populations show minimal commercial traction given diminished prophylactic rationale and absence of therapeutic alternatives.
Adolescents anchor procurement volumes; Young Adults generate the steepest expansion trajectory.
End User:
Channel structure determines pricing power and inventory risk allocation between public and private systems.
- Hospitals:Tertiary medical centers in China's tier-one cities and India's metropolitan hubs manage multi-dose vial inventory for outpatient immunization services, with NMPA and CDSCO GMP compliance requirements filtering supplier pools.
- Clinics:District health centers and private practice networks in the Philippines and Indonesia handle last-mile delivery, where cold-chain gaps between -2°C and 8°C storage compromise dose stability.
- Pharmaceutical Companies:Domestic manufacturers in China and India source bulk antigens and adjuvants for fill-finish operations, with backward integration into aluminum hydroxide supply reducing input cost volatility.
- Research Institutions:Academic medical centers in Australia and South Korea conduct post-marketing surveillance and next-generation therapeutic trials, generating real-world evidence that influences PMDA and MFDS label updates.
Procurement concentrates with Hospitals; Clinics face the steepest infrastructure constraints.
Administration Route:
Delivery mechanics shape cold-chain requirements and workforce training needs across rural-urban divides.
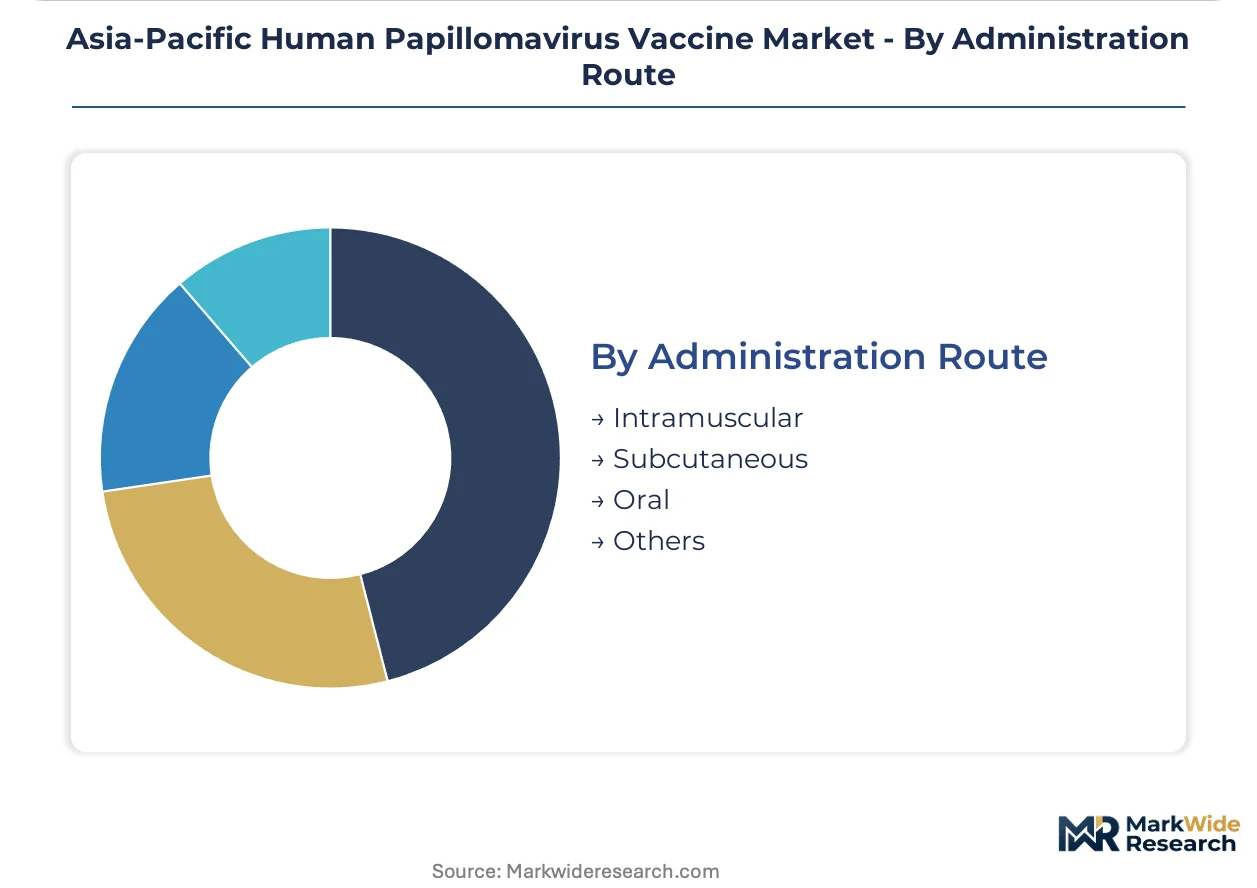
- Intramuscular:Deltoid or anterolateral thigh injection dominates current practice, requiring trained healthcare workers and sterile needle disposal systems that strain Indonesia's outer island clinics.
- Subcutaneous:Alternative delivery is gaining evaluation in Philippines' Visayas region and India's northeastern states, where reduced cold-chain sensitivity and simplified handling protocols address infrastructure gaps.
- Oral:No approved oral HPV vaccines exist; mucosal immunization research at Australian and Japanese institutions remains preclinical.
- Others:Intradermal and intranasal routes are experimental, with phase I trials limited to South Korean biotech development programs.
Intramuscular commands installed base; Subcutaneous development targets access expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's pharmaceutical special economic zones in Hyderabad and Pune concentrate vaccine fill-finish operations serving domestic and export markets. These tax-advantaged clusters attract multinational joint ventures seeking CDSCO-compliant manufacturing scale.
China
Domestic biologics producers in the Yangtze River Delta are scaling GMP-compliant capacity for nonavalent formulations. NMPA fast-track pathways for localized clinical data incentivize partnerships with state-owned manufacturers. Shanghai and Suzhou biotech parks host the majority of recombinant VLP production infrastructure.
India
Serum Institute of India anchors bivalent supply across South Asian national programs through its Pune manufacturing base. CDSCO regulatory familiarity and established 2-dose cold-chain protocols reinforce supplier relationships. Maharashtra and Gujarat house the bulk of pharmaceutical-grade aluminum hydroxide processing capacity.
Japan
PMDA's 2023 revised guidelines for recombinant vaccines mandate enhanced host cell protein impurity profiling using mass spectrometry. Tokyo and Osaka medical centers drive nonavalent procurement through health technology assessment frameworks. Kanto region distributors deploy temperature-controlled networks extending shelf stability into rural prefectures.
Australia
TGA alignment with WHO prequalification standards accelerates reformulated vaccine registration across Southeast Asian tenders. Melbourne and Sydney research institutions conduct post-marketing surveillance generating real-world evidence. School-based delivery models in New South Wales and Victoria achieve coverage rates above 80% in urban districts.
Indonesia
Cold-chain gaps between -2°C and 8°C storage exclude approximately 40% of rural outer islands from consistent intramuscular supply. The Ministry of Health channels procurement through central authorities compressing price negotiation cycles. Java-based distributors struggle with last-mile delivery to Papua and Maluku provinces.
Asia-Pacific Human Papillomavirus Vaccine Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational innovators dominating premium nonavalent tenders while domestic producers capture cost-sensitive national programs. The market structure concentrates around three strategic archetypes: research-intensive multinationals with established regulatory pathways, scaled domestic manufacturers leveraging backward integration into adjuvant supply, and emerging biotech ventures pursuing novel formulation development. Competitive moves center on cold-chain partnership expansion and multi-year tender positioning.
Within the multinational tier, Merck & Co., Inc. and GlaxoSmithKline plc occupy positions defined by decades of PMDA and TGA registration experience. Serum Institute of India exemplifies the scale-driven domestic archetype, with its Pune operations representing the largest bivalent production base serving CDSCO-regulated markets. These three anchors illustrate how regulatory familiarity and manufacturing geography determine competitive boundaries across the Asia-Pacific region.
| Leading Market Players |
|---|
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Serum Institute of India |
| Shanghai Zerun Biotech Co., Ltd. |
| Xiamen Innovax Biotech Co., Ltd. |
| Panacea Biotec Ltd. |
| Bharat Biotech |
| Walvax Biotechnology |
| Sanofi |
| Others |
Pricing and Supply Chain Analysis
Japan's PMDA 2023 revised guidelines for recombinant vaccine quality standards gate qualified supply access and premium-tier pricing power, as manufacturers must demonstrate enhanced host cell protein impurity profiling to serve tender markets in Tokyo and Osaka medical centers.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent procurement from scheduled tenders, with Australia's TGA-aligned programs commanding premium rates for rapid registration turnaround while India's CDSCO-regulated spot inventory trades at discounts. Three-tier pricing structure across premium nonavalent, standard quadrivalent, and economy bivalent levels reflects strain coverage breadth and regulatory certification tier. Cost compression in bivalent segments intensifies as Serum Institute of India scales domestic production. National immunization programs in Vietnam and Indonesia exhibit highest price sensitivity, whereas Japan's health technology assessment frameworks tolerate premium nonavalent positioning.
Supply Chain Analysis
Workforce availability constraints in Maharashtra and Gujarat pharmaceutical clusters limit GMP-compliant quality assurance specialist pools, compressing batch release timelines for export-eligible production. Supply concentrates in India, China, and South Korea, with recombinant VLP production anchored in Pune biotech parks and Yangtze River Delta facilities. Aluminum hydroxide adjuvant, yeast-derived antigens, and single-use bioreactor consumables constitute critical input dependencies. Single-source vulnerability in pharmaceutical-grade aluminum hydroxide from three specialty chemical manufacturers creates bottleneck risk during demand surges. Distribution runs through central procurement authorities in Jakarta and Hanoi, with provincial education departments displacing district health centers as primary delivery nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific HPV vaccine procurement is consolidating around suppliers with proven PMDA and TGA registration pathways, forcing weaker players without multi-year tender positioning toward exit or niche subcutaneous formulation development.
For Market Incumbents: Deepen cold-chain partnership density in Indonesia's outer islands and India's northeastern states to preempt subcutaneous formulation entrants. Anchor multi-year supply agreements with Vietnam's Ministry of Education and India's Universal Immunization Programme before domestic Chinese producers achieve NMPA fast-track scale. Vertical integration into aluminum hydroxide supply buffers input cost volatility from concentrated specialty chemical manufacturers.
For New Entrants and Emerging Players: Subcutaneous delivery technology-first wedges open penetration in Philippines' Visayas region and Papua New Guinea where intramuscular cold-chain gaps exclude forty percent of rural populations from consistent supply. Target Indonesia's Maluku and Papua provinces as most penetrable geographies, where Java-based distributors struggle with last-mile temperature-controlled delivery. Pursue joint venture structures with state-owned Chinese biologics producers to access NMPA localized clinical data pathways.
For Investors and Strategic Acquirers: Australia's evaluation of gender-neutral adolescent coverage expansion is the leading indicator that addressable cohorts will double beyond female-only targets across Singapore and Malaysia. Five-to-ten year viability favors scaled domestic manufacturers with backward-integrated adjuvant supply and proven CDSCO or NMPA regulatory track records. Watch for PMDA mass spectrometry impurity profiling standard adoption by Australia's TGA and South Korea's MFDS as convergence signal accelerating nonavalent procurement timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Reduced cold-chain dependency opens Indonesia's outer islands and Philippines' Visayas region to consistent supply. |
| Domestic Manufacturing Joint Venture | NMPA fast-track pathways in China's Yangtze River Delta incentivize partnerships with state-owned biologics producers. |
| Multi-Year Tender Positioning | Vietnam's Ministry of Health channels seventy percent of doses through education department partnerships compressing negotiation cycles. |
| Backward Integration into Adjuvant Supply | Pharmaceutical-grade aluminum hydroxide captive production reduces input bottleneck exposure from three specialty manufacturers. |
| Regulatory Convergence Investment | PMDA mass spectrometry impurity profiling capability accelerates TGA and MFDS reference standard adoption. |
Research Methodology
CDSCO registration filings, PMDA approval databases, and WHO prequalification records formed the secondary backbone, supplemented by customs trade data on aluminum hydroxide imports and tender documentation from Vietnam's Ministry of Health. Primary interviews with vaccine development executives, regulatory affairs leads at multinational suppliers, national immunization program managers, and hospital procurement directors in tier-one Chinese cities triangulated against secondary validation. Bottom-up volume estimates from state-level Universal Immunization Programme expansion data reconciled with top-down market sizing across formulation types and age cohorts.
Historical trendline analysis of bivalent-to-nonavalent procurement shifts anchored the projection framework across the analysis window. Segmentation dimensions modeled include vaccine type, age group stratification, administration route, end-user channel, and regional regulatory cluster alignment. CAGRs derived from tender volume trajectories in India's twenty-six state programs and Australia's school-based coverage expansion. Industry-specific forecast inputs incorporated cold-chain infrastructure investment pipelines in South Korea and Japan, plus subcutaneous formulation clinical trial progression in Philippines' Department of Health evaluations.
Several conditions sit outside the modeled scope, including therapeutic HPV vaccine commercialization timelines, intranasal route regulatory approval pathways, and aluminum adjuvant substitution by novel immunostimulant systems. Forecasts reflect documented assumptions on national program expansion rates, PMDA guideline convergence adoption, and cold-chain infrastructure deployment schedules. Material deviation in subcutaneous formulation efficacy data, gender-neutral program adoption velocity, or aluminum hydroxide supply concentration disruption warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Europe Generic Drug Market
Pharmaceuticals
Fucosidosis Therapeutics Market
Pharmaceuticals
Middle-East and Africa Sodium-Dependent Glucose Co-Transporter 2 Inhibitors Market
Pharmaceuticals
Istradefylline API Market
Pharmaceuticals
Oral Anticoagulant Market
Pharmaceuticals
Latin America Meglitinide Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market
Pharmaceuticals
Herpes Labialis Treatment Market
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
Global Antacids Market
Pharmaceuticals
Middle East and Africa Gastrointestinal Drugs Market
Pharmaceuticals
Hydroxycarbamide Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Global Atosiban Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Narcotic Analgesics Market