
 Clinical Diagnosis Automation Market | 2026-2036
Clinical Diagnosis Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Diagnosis Automation Market Outlook
Hospital procurement departments are collapsing legacy instrument refresh cycles from seven years to four years as labor cost inflation strains operational budgets. Thermo Fisher Scientific leverages its life sciences instrumentation heritage to anchor automated sample-to-answer workflows in high-throughput laboratories. Danaher Corporation sustains competitive density through diagnostics platform specialization across Beckman Coulter and Cepheid operating units. Siemens Healthineers dominates imaging-automation integration with AI-radiology systems that compress scan interpretation turnaround.
Clinical diagnosis automation encompasses hardware-software systems that execute specimen processing, analytical measurement, and diagnostic interpretation with minimal human intervention, typically operating through throughput rates exceeding 1,000 tests per hour on integrated modular tracks. These systems serve primarily to reduce diagnostic error rates and extend laboratory capacity during workforce contraction. Imaging Devices capture the dominant share of product-type value pools, reflecting persistent capital allocation toward MRI and CT automation retrofits. Artificial Intelligence within the technology dimension represents the fastest-expanding margin pool, as algorithm licensing generates recurring revenue streams distinct from capital hardware sales. Pathology applications lag radiology in automation penetration, creating residual upside for whole-slide imaging and computational histopathology vendors.
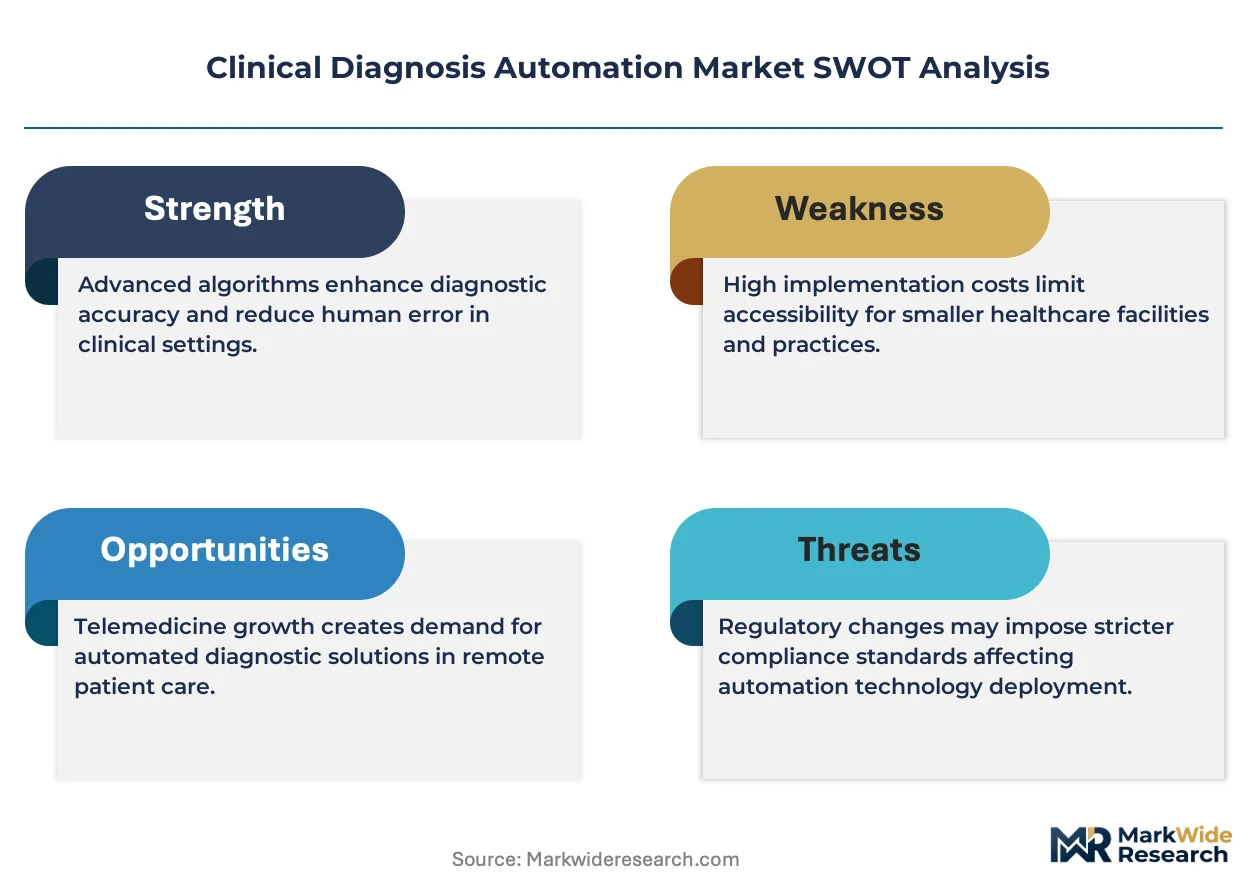
FDA premarket review under the Software as a Medical Device framework shapes commercialization timelines and clinical evidence requirements for algorithm developers seeking diagnostic claims. The European Medical Device Regulation and In Vitro Diagnostic Regulation impose conformity assessment burdens that favor established manufacturers with notified body relationships and quality management infrastructure. Cloud Computing deployments face GDPR data-localization constraints that complicate multi-tenant diagnostic platform architectures across EU member states. Stakeholders must weigh regulatory capital requirements against algorithm differentiation timelines when sequencing geographic market entry.
Market Dynamics
Laboratory staffing shortages are compressing diagnostic turnaround requirements, forcing hospital systems to prioritize throughput automation over incremental instrument upgrades. This structural pressure is reshaping capital allocation toward integrated sample-to-answer platforms that minimize manual touchpoints.
Growth Catalysts
- FDA Software as a Medical Device framework:The streamlined premarket review pathway accelerates algorithm commercialization timelines for diagnostic AI developers. This regulatory clarity attracts venture deployment toward clinical decision-support tools.
- Integrated delivery networks:Centralized purchasing consortia in the United States consolidate procurement volume, creating anchor demand for high-throughput automation suites. These networks negotiate enterprise-wide service agreements that lock in multi-year platform commitments.
- Computational histopathology:Whole-slide imaging systems penetrate anatomic pathology workflows previously resistant to digitization. Digital pathology platforms enable remote consultation and AI-assisted quantification of tissue biomarkers.
Market Restraints
- Reagent supply concentration:Proprietary consumable lock-in from dominant platform manufacturers creates switching costs that deter laboratory migration. Single-source dependency exposes operations to price escalation and supply interruption.
- European IVD Regulation conformity assessment:Extended notified body queue times delay market entry for novel diagnostic algorithms. Small developers lack quality management infrastructure to navigate MDR technical documentation requirements.
- Cloud infrastructure localization mandates:GDPR data-residency rules fragment multi-tenant diagnostic architectures across EU member states. Compliance complexity elevates operational overhead for algorithm-as-a-service deployments.
Strategic Opportunities
- Point-of-care molecular diagnostics:Miniaturized sample-to-answer systems penetrate ambulatory settings outside traditional laboratory infrastructure. Decentralized testing networks reduce specimen transport delays for time-critical infectious disease panels.
- Japan's regulatory harmonization:PMDA alignment with IMDRF guidance documents accelerates approval timelines for AI-diagnostic software validated in US or EU markets. This convergence reduces redundant clinical evidence generation for multinational developers.
- Interoperability standards convergence:HL7 FHIR and DICOM integration enable seamless data exchange between imaging devices and electronic health records. Standardized APIs reduce custom integration costs for multi-vendor laboratory environments.
Industry Challenges
- Computational pathology expertise scarcity:Dual-qualified professionals possessing both histologic interpretation and machine learning engineering skills command premium compensation. Academic training pipelines produce insufficient hybrid talent to support platform deployment at scale.
- Legacy instrument integration complexity:Pre-analytical automation retrofitting requires custom middleware development for disparate analyzer generations. Proprietary communication protocols from incumbent manufacturers obstruct seamless track-based specimen routing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Diagnosis Automation Market |
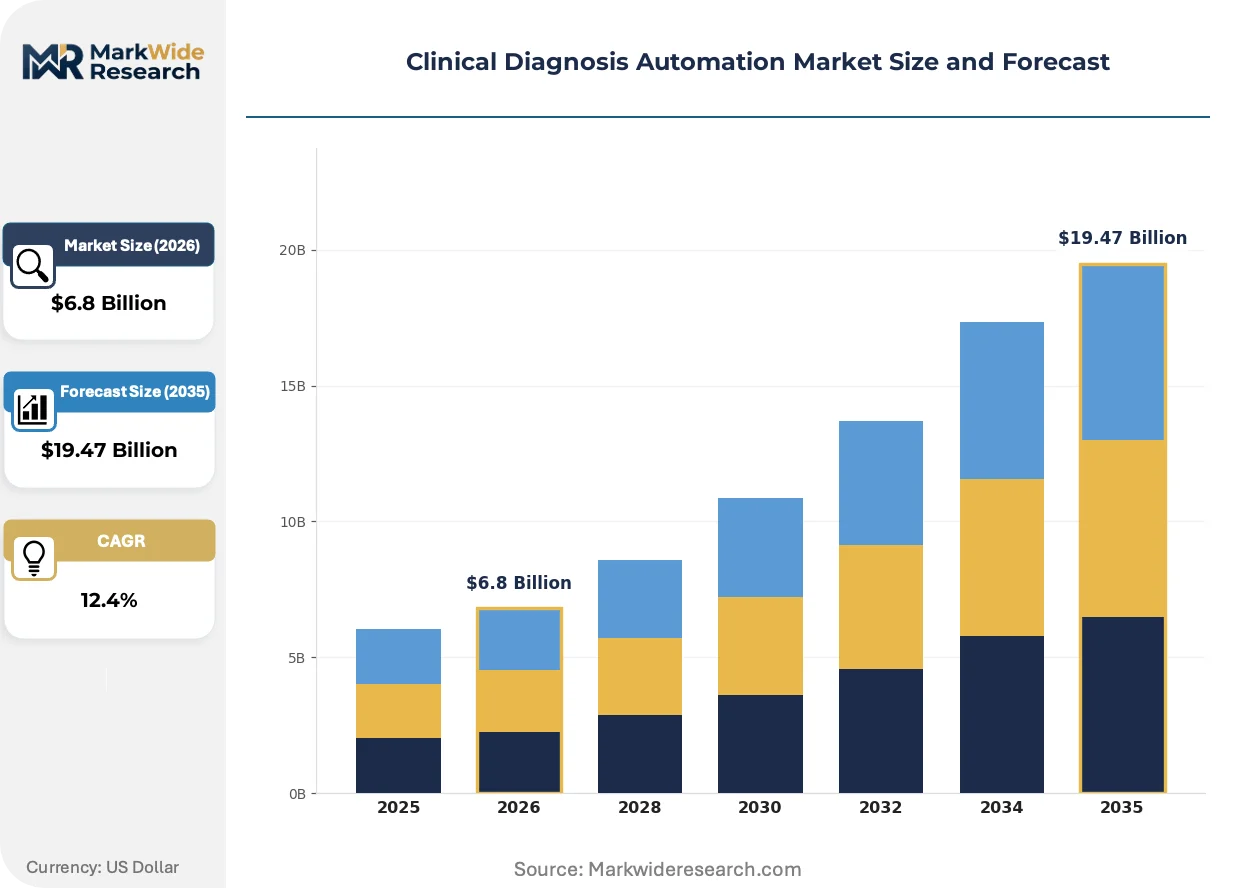
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Software, Imaging Devices, Monitoring Systems, Data Analytics Tools End User: Clinics, Hospitals, Laboratories, Research Institutions Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Robotics Application: Pathology, Radiology, Cardiology, Neurology |
| Companies Covered | Thermo Fisher Scientific, Danaher Corporation, Siemens Healthineers AG, Hoffmann-La Roche Ltd, Becton Dickinson, Abbott Laboratories, Tecan Trading AG, PerkinElmer Inc., Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Diagnosis Automation Market Strategic Shifts
Diagnostic platform architectures are fragmenting into modular, software-defined systems that decouple analytical hardware from algorithmic interpretation layers. This separation enables continuous capability expansion without physical instrument replacement.
Multiplexed assay chemistries are bifurcating diagnostic testing into high-complexity reference laboratory panels and streamlined near-patient platforms. Academic medical centers deploy comprehensive genomic and proteomic profiling on integrated mass spectrometry tracks, while urgent care networks adopt cartridge-based respiratory pathogen detection. This divergence is compressing the addressable market for mid-tier analyzer configurations that lack clear positioning against either extreme.
The EU AI Act risk classification framework imposes conformity assessment obligations on diagnostic algorithms supporting critical healthcare decisions. High-risk AI systems must demonstrate performance robustness across demographic subgroups and maintain post-market surveillance registries. European pathology laboratories now prioritize vendors with established notified body relationships and documented algorithmic bias mitigation protocols.
Hospital capital committees are consolidating discrete instrument procurement into enterprise automation partnerships with multi-year service commitments. This concentration displaces transactional equipment purchasing through distributor channels. The United States exhibits the most pronounced shift, where integrated delivery networks negotiate sole-source agreements covering pre-analytical processing, analytical measurement, and results reporting infrastructure.
Clinical Diagnosis Automation Market Segmentation
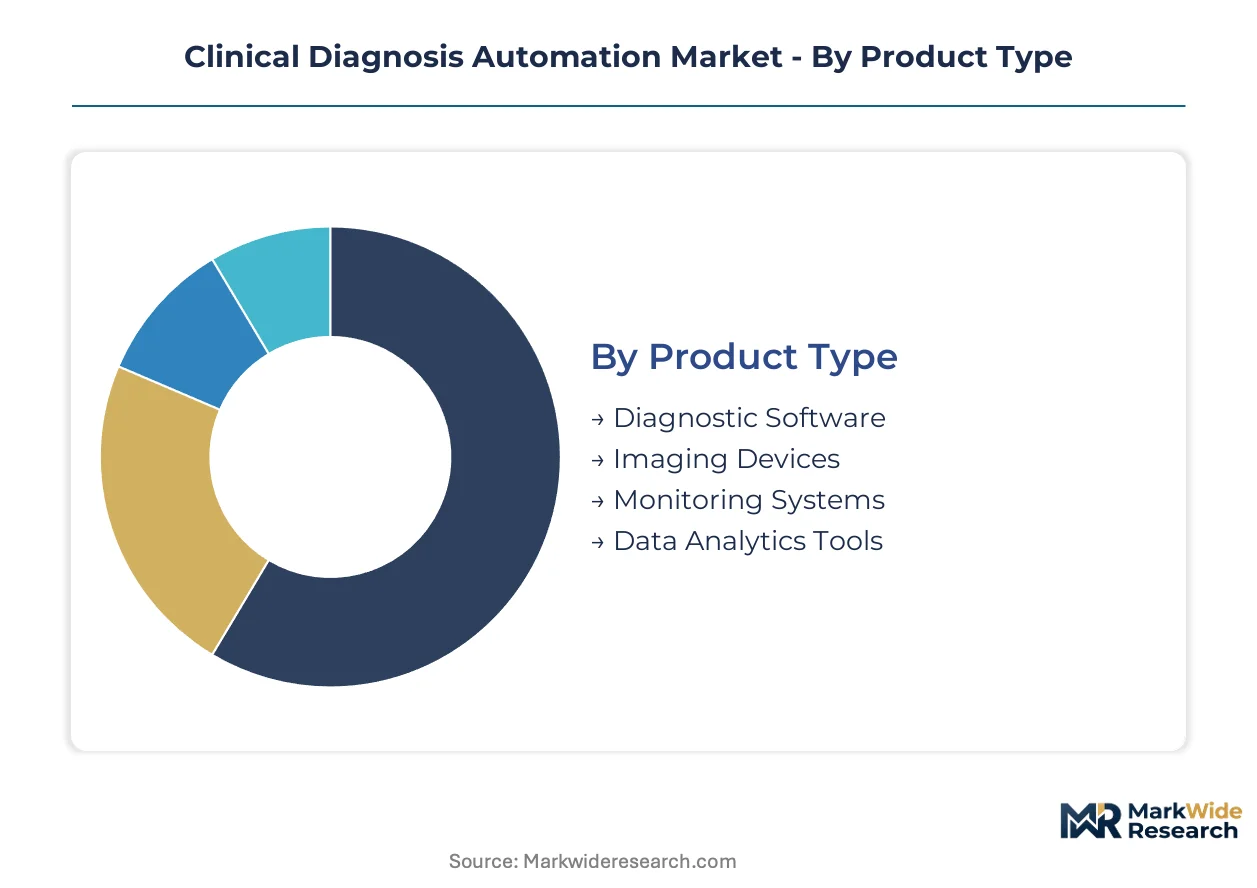
Segmentation reveals how value migrates across hardware, software, and service layers in clinical diagnosis automation. Procurement patterns diverge sharply between capital-intensive imaging platforms and recurring-revenue algorithm licensing.
Product Type:
Margin pools concentrate in systems that generate consumable or licensing revenue rather than one-time hardware sales.
- Imaging Devices:MRI and CT automation retrofits integrate AI-powered scan interpretation with hardware control systems. Hospital integrated delivery networks in the United States prioritize these platforms for enterprise-wide standardization, compressing refresh cycles from seven years to four years amid labor cost pressures.
- Diagnostic Software:Algorithm-as-a-service models under the FDA Software as a Medical Device framework generate recurring revenue distinct from capital sales. Venture deployment concentrates here as premarket review pathways clarify commercialization timelines for clinical decision-support tools.
- Monitoring Systems:Continuous patient monitoring automation bridges acute and ambulatory settings.
- Data Analytics Tools:Laboratory information system integration layers enable cross-platform workflow orchestration.
The dominant share belongs to Imaging Devices, while Diagnostic Software is closing the gap fastest.
End User:
Procurement authority determines contract structure and vendor relationship intensity across customer types.
- Hospitals:Centralized capital committees negotiate multi-year enterprise automation partnerships covering pre-analytical processing through results reporting. These sole-source agreements displace transactional purchasing through distributor channels.
- Laboratories:High-throughput facilities prioritize integrated sample-to-answer platforms that minimize manual touchpoints. Staffing shortages force acceleration toward modular track-based specimen routing systems.
- Clinics:Point-of-care molecular diagnostics penetration creates demand for miniaturized sample-to-answer systems outside traditional laboratory infrastructure.
- Research Institutions:Academic medical centers deploy comprehensive genomic and proteomic profiling on integrated mass spectrometry tracks.
Hospitals command the largest procurement volume, though Laboratories show the steepest automation urgency.
Technology:
Technology selection determines regulatory pathway complexity and post-market surveillance obligations.
- Artificial Intelligence:EU AI Act high-risk classification imposes conformity assessment for algorithms supporting critical healthcare decisions, requiring performance robustness across demographic subgroups and post-market surveillance registries.
- Cloud Computing:GDPR data-localization constraints fragment multi-tenant architectures across EU member states, elevating operational overhead for algorithm-as-a-service deployments.
- Machine Learning:Computational histopathology applications depend on dual-qualified professionals possessing both histologic interpretation and engineering skills.
- Robotics:Pre-analytical automation retrofitting demands custom middleware for disparate analyzer generations.
Artificial Intelligence attracts the most regulatory attention, while Cloud Computing faces the most severe compliance fragmentation.
Application:
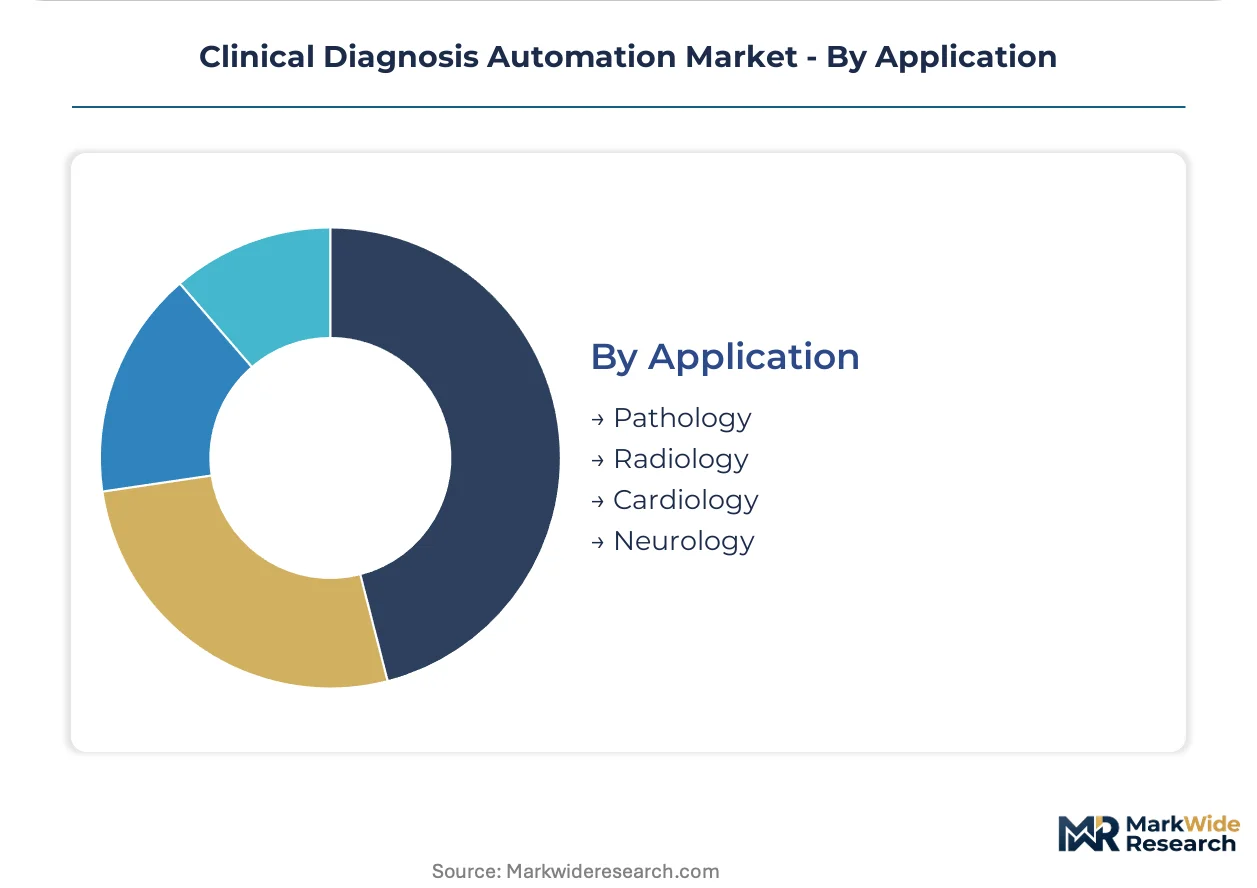
Automation maturity varies widely across medical specialties, creating divergent competitive dynamics.
- Radiology:AI-radiology systems from Siemens Healthineers dominate imaging-automation integration, compressing scan interpretation turnaround through deep learning-based detection and quantification.
- Pathology:Whole-slide imaging and computational histopathology lag radiology penetration, creating residual upside for vendors as anatomic pathology workflows digitize.
- Cardiology:Automated ECG interpretation and echocardiography quantification reduce specialist reading burden.
- Neurology:MRI-based biomarker quantification for neurodegenerative conditions requires specialized algorithm validation.
Radiology holds the deepest automation penetration, while Pathology presents the largest remaining expansion opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States commands diagnostic automation procurement through integrated delivery networks anchored by major healthcare infrastructure clusters. Germany's laboratory consolidation and Japan's regulatory harmonization create parallel demand centers for high-throughput platforms.
United States
Hospital integrated delivery networks consolidate procurement volume through centralized capital committees negotiating sole-source automation partnerships. FDA Software as a Medical Device framework accelerates commercialization timelines for algorithm developers seeking diagnostic claims. The Boston-Cambridge corridor concentrates computational pathology ventures alongside academic medical centers deploying whole-slide imaging at scale.
Germany
Industrial laboratory automation heritage from precision engineering clusters drives demand for modular track-based specimen routing systems. EU Medical Device Regulation and In Vitro Diagnostic Regulation impose conformity assessment burdens favoring established manufacturers with notified body relationships. The Rhine-Ruhr metropolitan region hosts diagnostics platform specialization across multiple operating units serving high-throughput hospital laboratories.
Japan
PMDA alignment with IMDRF guidance documents reduces redundant clinical evidence generation for AI-diagnostic software validated in US or EU markets. METI industrial policy supports domestic production of imaging-automation integration systems. The Kanto region around Tokyo concentrates radiology AI deployment alongside aging population demands for compressed scan interpretation turnaround.
China
NMPA regulatory pathways for AI-assisted diagnostic software compress time-to-market for algorithm developers targeting hospital procurement. National healthcare infrastructure investment prioritizes imaging device automation retrofits in tier-one city medical centers. The Yangtze River Delta cluster around Shanghai anchors domestic manufacturing of laboratory automation hardware for regional distribution.
United Kingdom
NHS England centralized procurement frameworks favor enterprise automation partnerships over transactional equipment purchasing through distributor channels. MHRA post-Brexit regulatory autonomy maintains alignment with FDA premarket review standards for software as medical device submissions. The Oxford-Cambridge-London arc concentrates digital pathology platform deployment alongside academic research institutions.
Clinical Diagnosis Automation Market Competitive Environment
Concentration sits with diversified life sciences conglomerates possessing diagnostics platform specialization across multiple operating units. The vendor base stratifies into three tiers: integrated conglomerates with life sciences instrumentation heritage, pure-play diagnostics specialists, and emerging algorithm-as-a-service developers. Competitive positioning depends on FDA premarket review pathway navigation, reagent supply chain control, and multi-year enterprise service agreement capture.
Among US-based diversified conglomerates, Thermo Fisher Scientific anchors automated sample-to-answer workflows through life sciences instrumentation heritage. Danaher Corporation occupies a position across Beckman Coulter and Cepheid operating units sustaining competitive density in diagnostics platform specialization. Siemens Healthineers AG exemplifies imaging-automation integration dominance with AI-radiology systems compressing scan interpretation turnaround.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Danaher Corporation |
| Siemens Healthineers AG |
| Hoffmann-La Roche Ltd |
| Becton Dickinson |
| Abbott Laboratories |
| Tecan Trading AG |
| PerkinElmer Inc. |
| Bio-Rad Laboratories Inc. |
| Others |
Value Chain & Pricing Dynamics
FDA Software as a Medical Device certification gates both vendor qualification and price tiering simultaneously, as laboratories demand documented algorithmic validation before committing to multi-year service contracts. This regulatory filter stratifies the vendor base into those commanding premium pricing through cleared diagnostic claims versus uncertified competitors competing on hardware cost alone.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement, with integrated delivery networks extracting 15-25% price concessions against list rates for sole-source automation partnerships. Pricing stratifies across premium, standard, and economy tiers based on FDA clearance status and reagent lock-in intensity. Cost compression in mid-tier analyzer configurations is intensifying because laboratories bypass these systems for either high-complexity reference platforms or streamlined point-of-care devices. Hospital capital committees show lowest price sensitivity for imaging-automation integration, while independent reference laboratories face acute budget constraints.
Supply Chain Analysis
Port congestion on transpacific trade lanes elevates inbound logistics costs for precision optical components sourced from Japanese and German manufacturing clusters. Component supply concentrates in Germany, Japan, and the United States for high-resolution imaging sensors, liquid-handling robotics, and mass spectrometry ion sources. Single-source vulnerability pervades proprietary reagent chemistries, where Thermo Fisher Scientific and Danaher Corporation maintain captive production of diagnostic consumables. Distribution runs through integrated delivery network procurement consortia in the United States, with regional distributors serving fragmented laboratory markets in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity pervades this market as diagnostic platform architectures decouple hardware from algorithmic layers, creating niches for specialized software developers between incumbent conglomerates and point-of-care innovators.
For Market Incumbents: Secure reagent supply chain control through backward integration into specialty chemical production, insulating margins from third-party price escalation. Lock in multi-year enterprise service agreements with integrated delivery networks before point-of-care molecular diagnostics erode centralized laboratory volume. FDA Software as a Medical Device framework acceleration threatens to commoditize hardware, making algorithmic differentiation the priority lever for pricing power.
For New Entrants and Emerging Players: Lead with computational histopathology applications in anatomic pathology workflows, where whole-slide imaging penetration lags radiology automation by several years. Target mid-sized health systems lacking capital committee scale for sole-source conglomerate deals, offering modular subscription pricing without reagent lock-in. Go-to-market execution should emphasize remote consultation capabilities that address pathologist staffing shortages directly.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across algorithm-as-a-service sub-segments, reducing barrier-to-entry for software-native diagnostic developers. Long-term viability over the coming decade favors acquisition targets possessing FDA-cleared algorithms with demonstrated performance robustness across demographic subgroups. Watch for PMDA approval timeline compression as the signal indicating when Japanese market entry costs drop sufficiently to trigger multinational expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Software as a Medical Device Submission | Accelerates commercialization timelines for AI-diagnostic developers seeking diagnostic claims. |
| CE Marking Pathway under EU AI Act | Opens European market access for high-risk algorithmic systems with documented bias mitigation. |
| Hospital System Partnership | Locks in multi-year enterprise automation commitments through integrated delivery network procurement. |
| Software Companion Development | Enables continuous capability expansion without physical instrument replacement in modular architectures. |
| Reimbursement Strategy | Secures CPT code coverage for algorithm-assisted interpretation, driving clinical adoption. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EU MDR technical documentation, and hospital procurement databases. Interviews with laboratory directors, biomedical engineers, GPO contracts managers, and regulatory affairs specialists informed demand-side validation. Secondary sources include CMS Medicare reimbursement data, SEC 10-K filings from diversified life sciences conglomerates, and IVD manufacturer quality management disclosures. Bottom-up test volume modeling triangulates against top-down capital expenditure tracking across integrated delivery networks.
Segmentation dimensions modeled span product type, end user, technology, and application, with cross-cutting analysis of regulatory pathway complexity across the projection horizon. CAGRs derive from instrument refresh cycle compression, algorithm licensing revenue mix shifts, and point-of-care decentralization trends. Industry-specific inputs include FDA premarket review queue times, notified body capacity constraints under EU IVD Regulation, and cloud infrastructure localization cost premiums.
Forecasts assume regulatory continuity in FDA Software as a Medical Device and EU AI Act regimes; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Preimplantation Genetic Testing Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market