
 Bone Metabolism Test Market | 2026-2036
Bone Metabolism Test Market Size, Share, and Industry Trends Forecast 2026-2036
Bone Metabolism Test Market Outlook
Germany is narrowing its position as Europe's reference laboratory hub for bone metabolism assays, with centralized testing networks consolidating regional demand. F. Hoffmann-La Roche AG leverages its automated immunoassay platforms to sustain high-throughput processing in hospital laboratories. Siemens Healthineers anchors its competitive stance through integrated imaging and biomarker workflows that span bone density scanning to serological testing. Abbott Laboratories differentiates via point-of-care connectivity solutions that link home care settings to central laboratory information systems.
Bone metabolism tests measure biochemical markers of bone formation and resorption, including osteocalcin, C-terminal telopeptide, and procollagen type I N-terminal propeptide, typically analyzed through serum or urine samples using immunoassay or chromatographic methods to evaluate skeletal turnover rates and metabolic bone disease status. These diagnostics enable clinicians to monitor osteoporosis treatment efficacy, detect secondary causes of bone loss, and stratify fracture risk before radiographic changes appear. Biomarker-based testing represents the largest product segment due to repeat monitoring requirements for chronic therapies, while bone density scanning commands premium pricing through capital-intensive DEXA infrastructure. Diagnostic kits for osteoporosis applications dominate procedure volumes, though hyperparathyroidism panels generate higher per-test margins through specialized endocrinology referrals.
The FDA regulates bone metabolism assays as Class II medical devices requiring 510(k) clearance, while the EMA's In Vitro Diagnostic Regulation mandates clinical evidence standards that reshape kit validation requirements across European markets. Laboratory accreditation under ISO 15189 governs analytical quality for hospital and independent testing facilities, directly influencing reagent procurement decisions and platform standardization. Stakeholders must evaluate how evolving reimbursement thresholds for biomarker-based fracture risk assessment will reshape test menu economics and capital deployment priorities across integrated delivery networks.
Market Dynamics
Centralized laboratory consolidation across Germany is compressing procurement timelines and forcing reagent suppliers to negotiate multi-year exclusive supply agreements with reference networks, fundamentally altering vendor economics and platform lock-in strategies.
Growth Catalysts
- Aging Demographics in Germany:The country's 65-plus population expansion sustains consistent test volumes for osteoporosis monitoring, with statutory health insurance covering annual biomarker panels for high-risk cohorts.
- FDA 510(k) Pathway Clarity:Streamlined clearance timelines for Class II immunoassay modifications accelerate product iteration cycles, enabling faster market entry for enhanced sensitivity kits targeting C-terminal telopeptide detection.
- Automated Immunoassay Platforms:High-throughput analyzer deployment in hospital laboratories reduces per-test labor costs and enables 24-hour turnaround for emergency fracture risk stratification.
Market Restraints
- Reimbursement Compression:Germany's uniform assessment standard for laboratory diagnostics caps biomarker test pricing, compressing margins for specialized hyperparathyroidism panels despite higher complexity.
- Capital Intensity of DEXA Infrastructure:Bone density scanning requires substantial upfront equipment investment and dedicated radiology space, limiting deployment to tertiary centers and restricting rural access.
- Sample Stability Limitations:C-terminal telopeptide degradation within 24 hours of collection necessitates cold-chain logistics or immediate processing, constraining point-of-care expansion and home collection models.
Strategic Opportunities
- Underpenetrated Home Care Connectivity:Remote patient monitoring integration creates white space for ambulatory testing networks linking home health nurses to central laboratory information systems in Bavaria and North Rhine-Westphalia.
- EMA In Vitro Diagnostic Regulation Harmonization:Common technical documentation requirements across EU member states reduce duplicate validation costs, enabling kit manufacturers to scale production for multi-country tenders.
- Multiplex Biomarker Convergence:Simultaneous quantification of osteocalcin, procollagen type I N-terminal propeptide, and vitamin D on single platforms streamlines osteoporosis workups and reduces sample volume requirements.
Industry Challenges
- ISO 15189 Accreditation Burden:Independent laboratories face extensive documentation and proficiency testing requirements to maintain analytical quality certification, diverting resources from service expansion.
- Legacy LIS Integration Complexity:Hospital information system interoperability gaps between automated immunoassay analyzers and electronic health records delay result reporting and create manual transcription risks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bone Metabolism Test Market |
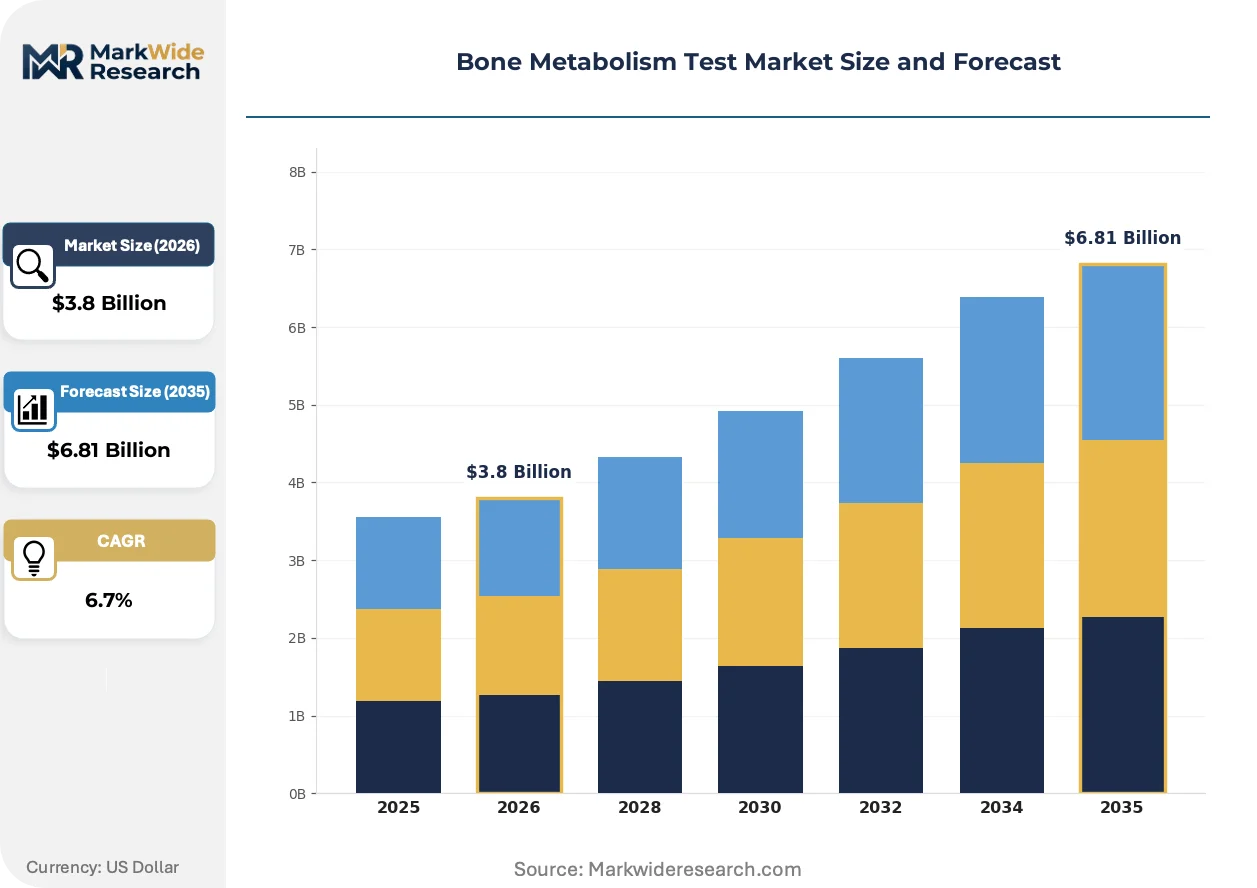
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biomarkers, Imaging Agents, Diagnostic Kits, Reagents Application: Osteoporosis, Osteomalacia, Hyperparathyroidism, Osteogenesis Imperfecta End User: Hospitals, Diagnostic Laboratories, Research Institutes, Home Care Settings Technology: Enzyme-Linked Immunosorbent Assay, Radioimmunoassay, Bone Density Scanning, Liquid Chromatography |
| Companies Covered | F. Hoffmann-La Roche AG, Siemens Healthineers, Abbott Laboratories, DiaSorin S.p.A., Beckman Coulter, Inc., Bio-Rad Laboratories, Inc., Ortho Clinical Diagnostics, QuidelOrtho Corporation, Thermo Fisher Scientific Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bone Metabolism Test Market Strategic Shifts
Digital pathology integration and cloud-based analytics are compressing the interval between sample acquisition and clinical decision-making, while regulatory harmonization efforts reshape validation protocols across European markets.
Liquid chromatography-tandem mass spectrometry for vitamin D metabolite quantification is virtualizing reference laboratory workflows, with university hospital networks in Heidelberg and Munich adopting these platforms for standardized 25-hydroxyvitamin D reporting. This technology is virtualizing the role of traditional immunoassay methods in high-complexity testing environments.
The EMA's In Vitro Diagnostic Regulation mandates clinical performance studies for novel biomarker claims, elevating evidence standards above predecessor directive requirements. Kit manufacturers must now submit prospective patient data rather than analytical validation alone, extending development timelines by 12-18 months for osteoporosis risk algorithms. German notified bodies are prioritizing bone metabolism assay reviews given the chronic disease monitoring indication volume.
Consolidated procurement by hospital purchasing cooperatives is displacing individual laboratory reagent negotiations, with Rhineland-Palatinate and Baden-Württemberg health networks awarding exclusive multi-year supply contracts. This concentration shifts vendor focus from product differentiation toward total cost-of-ownership demonstrations and analyzer placement incentives.
Bone Metabolism Test Market Segmentation
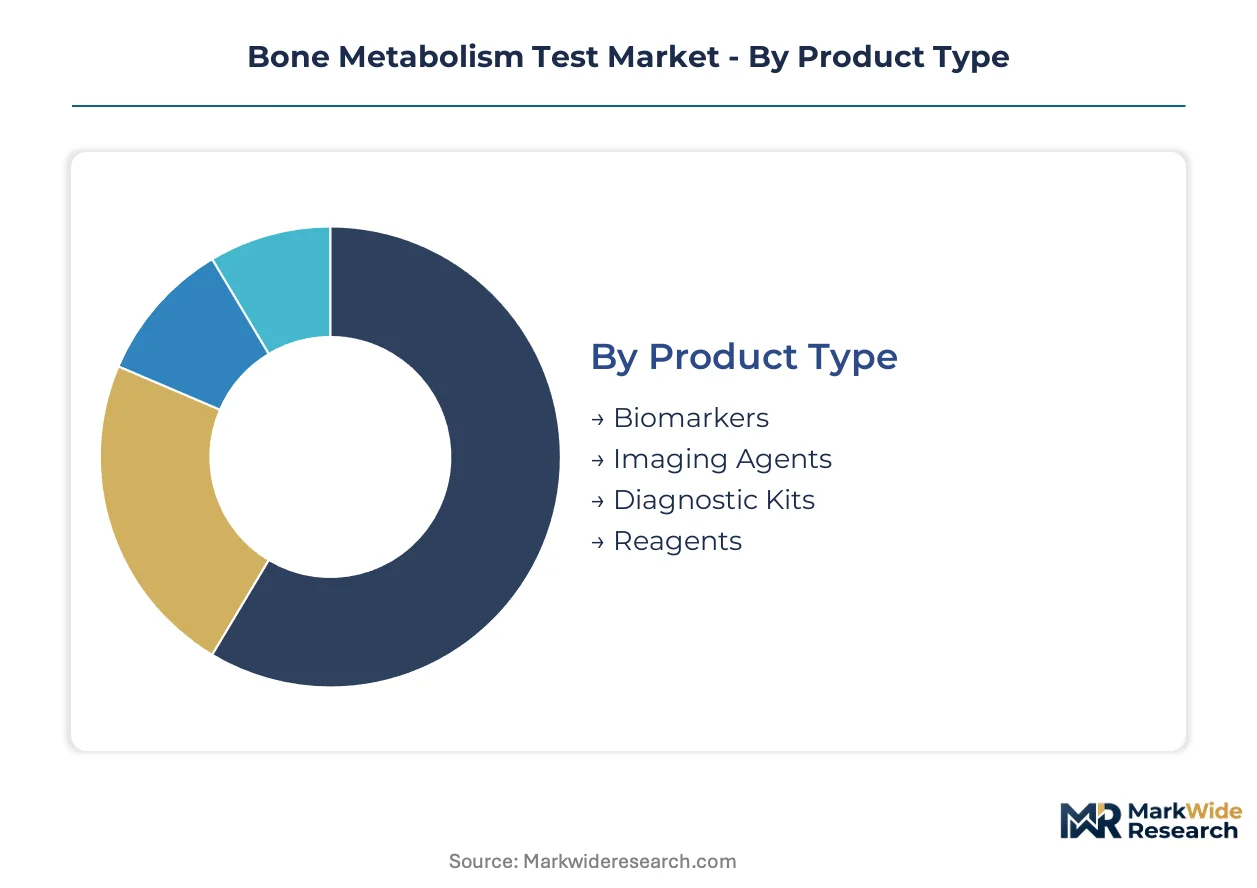
Segmentation reveals how bone metabolism diagnostics fragment across technical platforms, clinical indications, and care delivery settings. Each dimension carries distinct procurement patterns, regulatory pathways, and margin structures that shape vendor strategy.
Product Type:
After-sales service intensity varies sharply across product categories, with reagent contracts demanding continuous technical support while imaging agents require minimal ongoing vendor interaction.
- Biomarkers:Serum and urine-based analytes including osteocalcin and C-terminal telopeptide require cold-chain logistics and 24-hour processing windows. Demand clusters in German hospital laboratories where statutory insurance covers annual monitoring panels for high-risk cohorts.
- Diagnostic Kits:Pre-configured immunoassay panels for osteoporosis workups command premium positioning through ISO 15189-compliant quality documentation. Procurement concentrates in Rhineland-Palatinate and Baden-Württemberg health networks that negotiate exclusive multi-year supply agreements.
- Imaging Agents:Contrast media for bone scintigraphy and specialized radiopharmaceuticals serve tertiary referral centers.
- Reagents:Bulk chemistry supplies for automated analyzers generate recurring revenue through analyzer placement contracts.
Biomarkers hold the largest share; momentum sits with diagnostic kits as procurement consolidation accelerates.
Application:
Cost tier differentiation separates routine osteoporosis screening from specialized endocrinology referrals, with reimbursement thresholds determining test menu economics.
- Osteoporosis:Chronic disease monitoring drives repeat test volumes for bone turnover markers, with DEXA scanning and serological panels forming standard care pathways. German statutory health insurance funds annual biomarker assessments for postmenopausal women and elderly men with fracture history.
- Hyperparathyroidism:Specialized endocrine workups generate elevated per-test margins through parathyroid hormone and calcium metabolism panels. Demand localizes in university hospital networks across Heidelberg and Munich where complex case referrals concentrate.
- Osteomalacia:Vitamin D deficiency diagnostics serve nutritional medicine and geriatric practices.
- Osteogenesis Imperfecta:Rare disease genetic testing and collagen marker analysis supports pediatric orthopedics and specialized metabolic units.
Osteoporosis dominates procedure volumes; hyperparathyroidism delivers the steepest margin expansion trajectory.
End User:
Customer type determines platform complexity requirements, with hospital laboratories prioritizing throughput while home care settings demand connectivity solutions.
- Diagnostic Laboratories:Centralized reference networks in Germany consolidate regional test volumes, requiring high-throughput automated immunoassay platforms with 24-hour turnaround capabilities. ISO 15189 accreditation mandates drive standardization around vendor-integrated analyzer ecosystems.
- Home Care Settings:Remote patient monitoring creates emerging demand for point-of-care connectivity linking home health nurses to central laboratory information systems in Bavaria and North Rhine-Westphalia. Sample stability limitations for C-terminal telopeptide constrain expansion.
- Hospitals:Acute care facilities require emergency fracture risk stratification with rapid result reporting.
- Research Institutes:Academic medical centers drive adoption of liquid chromatography-tandem mass spectrometry for standardized vitamin D metabolite quantification.
Diagnostic laboratories capture the greatest volume; home care settings are expanding most quickly as ambulatory networks mature.
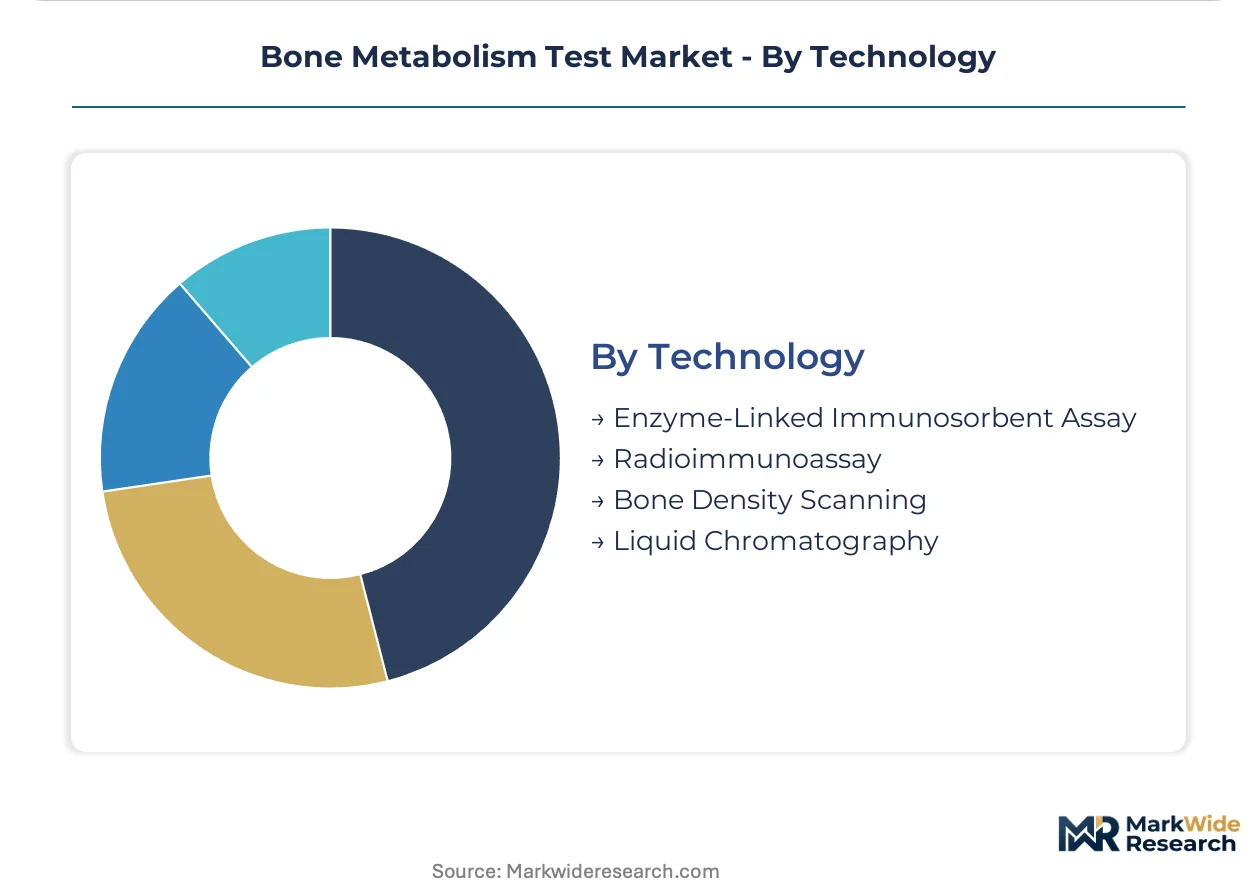
Technology:
Supply concentration favors automated immunoassay platforms in high-volume settings while chromatographic methods retain niche positioning in reference laboratories.
- Enzyme-Linked Immunosorbent Assay:ELISA platforms deliver cost-effective bone turnover marker quantification for mid-volume laboratories, with open-system architectures enabling reagent flexibility. Deployment concentrates in independent testing facilities seeking to avoid analyzer lock-in.
- Bone Density Scanning:DEXA infrastructure commands capital-intensive investment and dedicated radiology space, restricting deployment to tertiary centers. Premium pricing reflects equipment amortization and specialized technician requirements.
- Radioimmunoassay:Legacy methods persist in specialized endocrine reference laboratories.
- Liquid Chromatography:LC-MS/MS systems virtualize vitamin D metabolite workflows in university hospital networks.
Enzyme-linked immunosorbent assay retains the broadest installed base; bone density scanning maintains premium positioning despite capital constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA guidance on Class II immunoassay clearances anchors strategic positioning in the United States, while Germany's centralized laboratory networks concentrate procurement power across European markets.
United States
Hospital laboratory consolidation drives automated platform deployment for bone turnover marker quantification. The FDA's 510(k) pathway streamlines clearance timelines for enhanced sensitivity C-terminal telopeptide kits. Academic medical centers in Boston and Rochester anchor reference standardization for vitamin D metabolite reporting.
Germany
Statutory health insurance funds annual biomarker panels for postmenopausal osteoporosis monitoring. The EMA's In Vitro Diagnostic Regulation mandates clinical performance studies extending kit validation timelines. Heidelberg and Munich university hospital networks adopt liquid chromatography-tandem mass spectrometry for standardized 25-hydroxyvitamin D workflows.
Japan
Aging demographics sustain diagnostic volumes for fracture risk stratification in geriatric populations. PMDA oversight of in vitro diagnostics shapes evidence requirements for novel biomarker claims. Tokyo and Osaka metropolitan areas concentrate high-throughput analyzer installations in integrated hospital networks.
China
Expanding tertiary hospital infrastructure creates demand for bone density scanning and serological testing capacity. NMPA regulation of Class II medical devices governs immunoassay kit registration pathways. Shanghai and Beijing medical centers pioneer multiplex biomarker platform adoption for osteoporosis workup standardization.
United Kingdom
NHS England commissioning frameworks determine reimbursement thresholds for biomarker-based fracture risk assessment. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR technical standards. London and Manchester reference laboratories consolidate regional test volumes through hub-and-spoke network configurations.
Bone Metabolism Test Market Competitive Environment
Integrated diagnostics conglomerates and specialized immunoassay developers split the market between platform ecosystems and reagent flexibility. Three archetypes dominate: automated analyzer manufacturers with captive reagent supply, independent kit vendors serving open-system laboratories, and imaging-device firms extending into biomarker workflows. Competitive moves concentrate on exclusive supply agreements with purchasing cooperatives and analyzer placement incentives that lock in multi-year reagent commitments.
Among Swiss and German-integrated healthcare conglomerates, F. Hoffmann-La Roche AG and Siemens Healthineers exemplify the platform-ecosystem archetype through automated immunoassay infrastructure. Abbott Laboratories represents the point-of-care connectivity tier, occupying a position linking ambulatory settings to central laboratory networks. These three anchors illustrate how vendor economics increasingly depend on total cost-of-ownership demonstrations rather than standalone product differentiation.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche AG |
| Siemens Healthineers |
| Abbott Laboratories |
| DiaSorin S.p.A. |
| Beckman Coulter, Inc. |
| Bio-Rad Laboratories, Inc. |
| Ortho Clinical Diagnostics |
| QuidelOrtho Corporation |
| Thermo Fisher Scientific Inc. |
| Others |
Value Chain & Pricing Dynamics
The Frankfurt-Rotterdam freight corridor shapes cost dynamics across reagent supply chains, with cold-chain logistics expenses for biomarker kits compressing margins for distributors serving decentralized laboratories while enabling premium pricing for hospital networks with integrated processing capabilities.
Pricing Analysis
German statutory reimbursement caps create a 15-20% price spread between Rhineland-Palatinate hospital networks and independent Bavarian laboratories for identical osteocalcin panels. Three-tier pricing structure across premium, standard, and economy levels separates ISO 15189-accredited reference laboratories from mid-volume independent facilities and price-sensitive point-of-care operators. Cost compression in standard-tier reagent contracts is intensifying because consolidated purchasing cooperatives demand multi-year exclusivity commitments. Diagnostic laboratories with captive analyzer ecosystems exhibit the lowest price sensitivity, while home care connectivity providers face acute margin pressure from sample stability logistics.
Supply Chain Analysis
Monoclonal antibody feedstock production concentrates in Switzerland, Germany, and the United States, with recombinant protein suppliers anchoring upstream capacity for osteocalcin and C-terminal telopeptide assay development. Reagent manufacturing draws from specialized fermentation media, purified antibodies, and chromatographic resins, with cold-chain distribution tethered to validated 2-8°C logistics networks. Single-source vulnerability persists for high-affinity antibody clones used in automated immunoassay platforms. Distribution runs through regional reference laboratory hubs that consolidate procurement for affiliated hospital networks across German federal states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent diagnostic platforms face substitution pressure from liquid chromatography-tandem mass spectrometry workflows that virtualize vitamin D metabolite quantification in academic medical centers.
For Market Incumbents: Entrench analyzer placement contracts through captive reagent supply agreements that lock hospital networks into multi-year consumable commitments. Deepen backward integration into monoclonal antibody production to secure feedstock against supply interruptions. Counter LC-MS/MS substitution by demonstrating total cost-of-ownership advantages for high-throughput osteoporosis monitoring panels. For New Entrants and Emerging Players: Bavaria's home care connectivity infrastructure offers underpenetrated ambulatory testing networks linking home health nurses to central laboratory information systems. Target point-of-care biomarker platforms with stabilized C-terminal telopeptide collection devices that bypass cold-chain constraints. Pursue partnership pathways with telemedicine operators serving rural fracture risk stratification. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underoptimized immunoassay divisions lacking hospital system integration depth. The five-to-ten year viability window favors platform-ecosystem vendors over standalone kit manufacturers as procurement consolidation accelerates. Monitor EMA In Vitro Diagnostic Regulation enforcement patterns as the signal indicating whether clinical evidence requirements will extend development timelines further.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EMA's IVDR clinical performance studies extend validation timelines for novel osteoporosis risk algorithms. |
| Hospital System Partnership | Exclusive supply agreements with Rhineland-Palatinate purchasing cooperatives lock in multi-year reagent commitments. |
| Software Companion Development | Cloud-based analytics integration compresses turnaround between sample acquisition and clinical decision-making. |
| Reimbursement Strategy | German uniform assessment standard negotiations determine biomarker panel economics across statutory insurance. |
| Backward Integration | In-house monoclonal antibody production secures feedstock supply against single-source vulnerability risks. |
Study Parameters
The analysis maps biomarker assay platforms, diagnostic kit configurations, imaging agent workflows, and reagent supply chains, each validated through laboratory directors, procurement officers at hospital purchasing cooperatives, regulatory affairs specialists navigating FDA 510(k) pathways, and biomedical engineers integrating automated analyzers. Primary interview data triangulates against FDA 510(k) clearance databases, EMA IVDR technical documentation, ISO 15189 accreditation records, and German statutory health insurance reimbursement schedules. Bottom-up test volume modeling and top-down market sizing converge through iterative validation across stakeholder inputs.
Assumptions hold regulatory pathway timelines and reimbursement thresholds constant while varying technology substitution rates and procurement consolidation velocity across the projection horizon. Segmentation dimensions include product type, clinical application, end-user setting, and technology platform, with regional regulatory clusters modeled separately. CAGRs derive from weighted average growth across segment-level demand drivers, incorporating aging demographic trajectories, biomarker panel expansion rates, and analyzer placement cycles as industry-specific inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by LC-MS/MS platform vendors or point-of-care connectivity specialists would shift outcomes beyond modeled ranges. Cross-checking against hospital capital expenditure disclosures and GPO contract award databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Angiogenesis Assays Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Clinical Microbiology Market