
 Global Lung Cancer Screening Software Market | 2026-2036
Global Lung Cancer Screening Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lung Cancer Screening Software Market Foresight
Modular bundling of AI nodule detection with existing PACS infrastructure is hardening as the dominant procurement pattern. Siemens Healthineers leverages its installed base of CT scanners to anchor integrated screening workflows across European hospital networks. GE Healthcare competes through deep learning modules embedded directly into imaging hardware, reducing standalone software procurement cycles.
Lung cancer screening software comprises algorithmic systems that analyze low-dose computed tomography (LDCT) thoracic images to identify pulmonary nodules, quantify malignancy risk through volumetric tracking, and generate structured reports for radiologist review. These platforms typically process DICOM-standard imaging data with sub-millimeter slice resolution and must demonstrate sensitivity thresholds exceeding 90% for regulatory clearance. AI-Enabled Tools capture the fastest-expanding margin pool as vendors race to convert pattern-recognition research into reimbursable clinical workflows. Cloud-Based Platform deployments are accelerating among telemedicine providers seeking centralized image management without on-premise infrastructure overhead.
FDA premarket notification requirements under 21 CFR Part 892 govern software-as-medical-device classifications for nodule detection algorithms, while the EU AI Act imposes conformity obligations on high-risk diagnostic AI deployed within European imaging centers. The Centers for Medicare & Medicaid Services national coverage determination for LDCT lung cancer screening directly conditions software reimbursement on integration with accredited screening registries. Stakeholders must monitor evolving FDA guidance on adaptive AI algorithms that modify performance through continued learning from clinical data inputs.
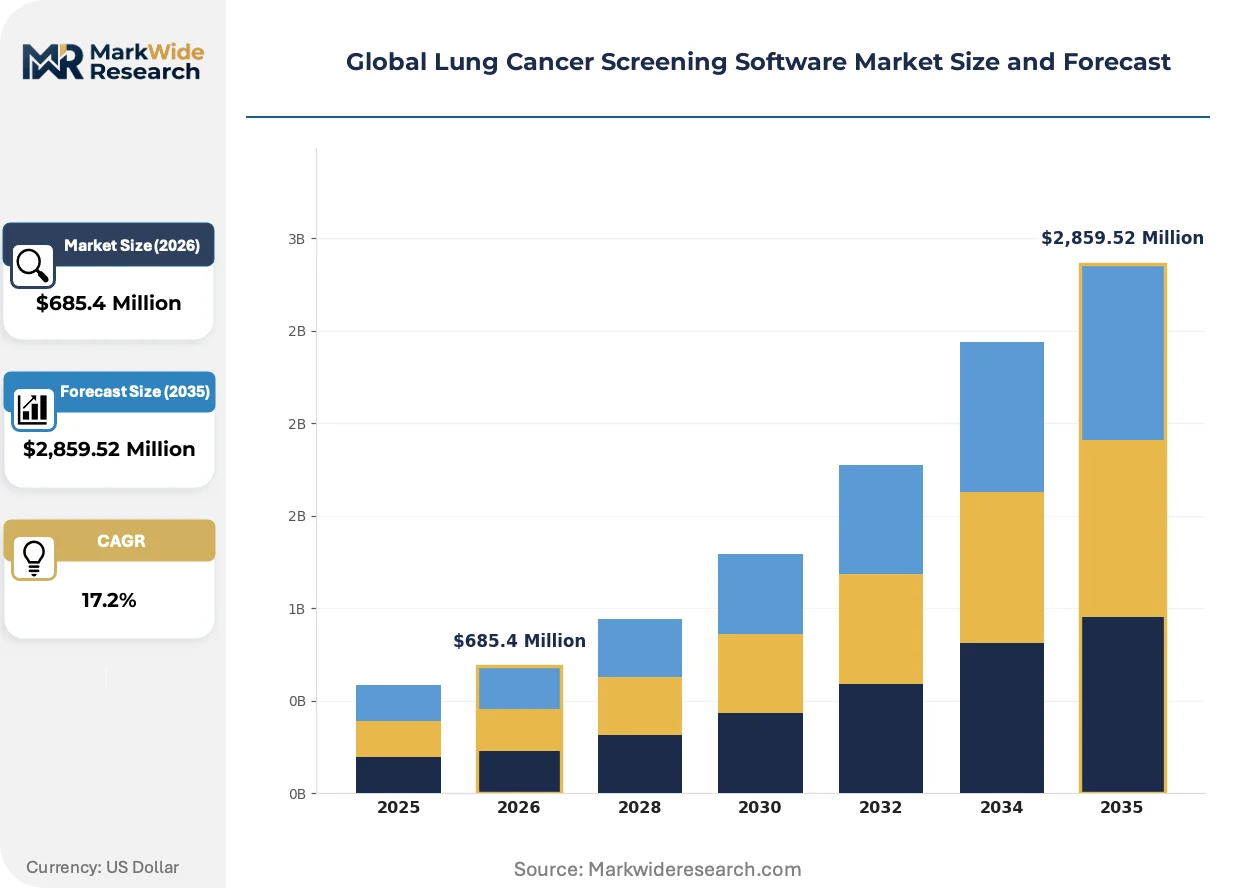
Market Dynamics
The integration of adaptive AI algorithms with low-dose CT workflows is compressing procurement cycles and forcing vendors to bundle software with hardware or cloud infrastructure rather than sell standalone licenses.
Growth Catalysts
- Medicare reimbursement expansion:The Centers for Medicare & Medicaid Services national coverage determination for LDCT screening mandates software integration with accredited registries, creating institutional pull for compliant platforms across United States hospital networks.
- EU AI Act conformity pathways:High-risk diagnostic AI classification under European Union regulations is accelerating vendor investment in CE-marked, auditable algorithmic systems for European imaging centers.
- Volumetric tracking protocols:Sub-millimeter nodule measurement standards are driving radiology departments toward automated quantification tools that reduce inter-reader variability in longitudinal screening programs.
Market Restraints
- Validation cost burden:Multi-site clinical trials required for FDA 510(k) clearance under 21 CFR Part 892 impose seven-figure expenditure thresholds that exclude mid-cap developers from commercialization.
- Cloud infrastructure dependency:Telemedicine providers and distributed imaging networks face recurring latency and data sovereignty constraints when deploying centralized AI processing across state or national borders.
- Radiologist workflow friction:Alert fatigue from high-sensitivity nodule detection algorithms without specificity calibration degrades clinical trust and slows institutional adoption curves.
Strategic Opportunities
- India diagnostic imaging networks:Tier-2 and Tier-3 cities with rising CT scanner penetration but limited specialist radiologist density present white-space demand for teleradiology-integrated screening platforms.
- Japan lung cancer screening mandates:METI-backed population health initiatives and employer-sponsored screening programs are creating procurement windows for AI-assisted LDCT workflows in corporate health clinics.
- Edge computing convergence:On-device inference chips embedded directly into CT gantry electronics are unifying image acquisition and real-time analysis, eliminating network transmission bottlenecks for high-volume screening sites.
Industry Challenges
- Interoperability certification timelines:DICOM-RT and HL7 FHIR compliance validation for multi-vendor PACS environments extends software deployment cycles by 6-12 months at integrated delivery networks.
- Adaptive algorithm governance:Continual learning systems that modify performance based on clinical feedback create unresolved liability frameworks when post-deployment drift affects sensitivity thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lung Cancer Screening Software Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,859.52 Million |
| CAGR (2026 – 2036) | 17.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Platform, AI-Enabled Tools, CAD Integration, Image Analysis Software Technology: Deep Learning, Machine Learning, Natural Language Processing, Pattern Recognition, Radiomics Screening Application: Early Detection, Risk Assessment, Nodule Detection, Diagnostic Support, Prognostic Analysis End User: Imaging Centers, Diagnostic Laboratories, Oncology Research Institutes, Telemedicine Providers |
| Companies Covered | Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Nuance Communications, Inc., FUJIFILM Holdings Corporation, PenRad Technologies, Inc., Eon Health, MRS Systems, Inc., MagView, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lung Cancer Screening Software Market Shifts & Advancements
Algorithmic unification of image analysis, risk stratification, and structured reporting into single-vendor platforms is collapsing the multi-point solution architectures that dominated early-stage AI deployment in thoracic imaging.
Federated learning architectures are unifying model training across institutional boundaries without centralized data pooling. Academic medical centers in Germany, the United Kingdom, and the Netherlands are adopting these frameworks to comply with GDPR data localization requirements while accessing multi-site cohorts for algorithm refinement. Siemens Healthineers and GE Healthcare are embedding federated nodes within their cloud platforms, compressing the timeline from research validation to regulatory submission.
The EU AI Act's high-risk system classification is mandating conformity assessment bodies to audit training data provenance and performance drift monitoring for nodule detection algorithms. European imaging centers now require documented post-market surveillance plans as a condition of procurement, shifting vendor investment toward explainable AI interfaces and automated bias detection tools. France's ANSM and Germany's BfArM are coordinating mutual recognition agreements to streamline multi-national deployment.
Radiology group purchasing organizations are consolidating vendor evaluation authority and demanding outcome-based contracts tied to false-positive reduction metrics. United States health systems including Kaiser Permanente and Mayo Clinic have established centralized AI validation committees that pre-certify algorithms before local deployment, replacing the previous model of individual radiologist-driven procurement. This concentration of buying power is compressing pricing flexibility and favoring vendors with established registry integration and malpractice indemnification frameworks.
Global Lung Cancer Screening Software Market Segmentation
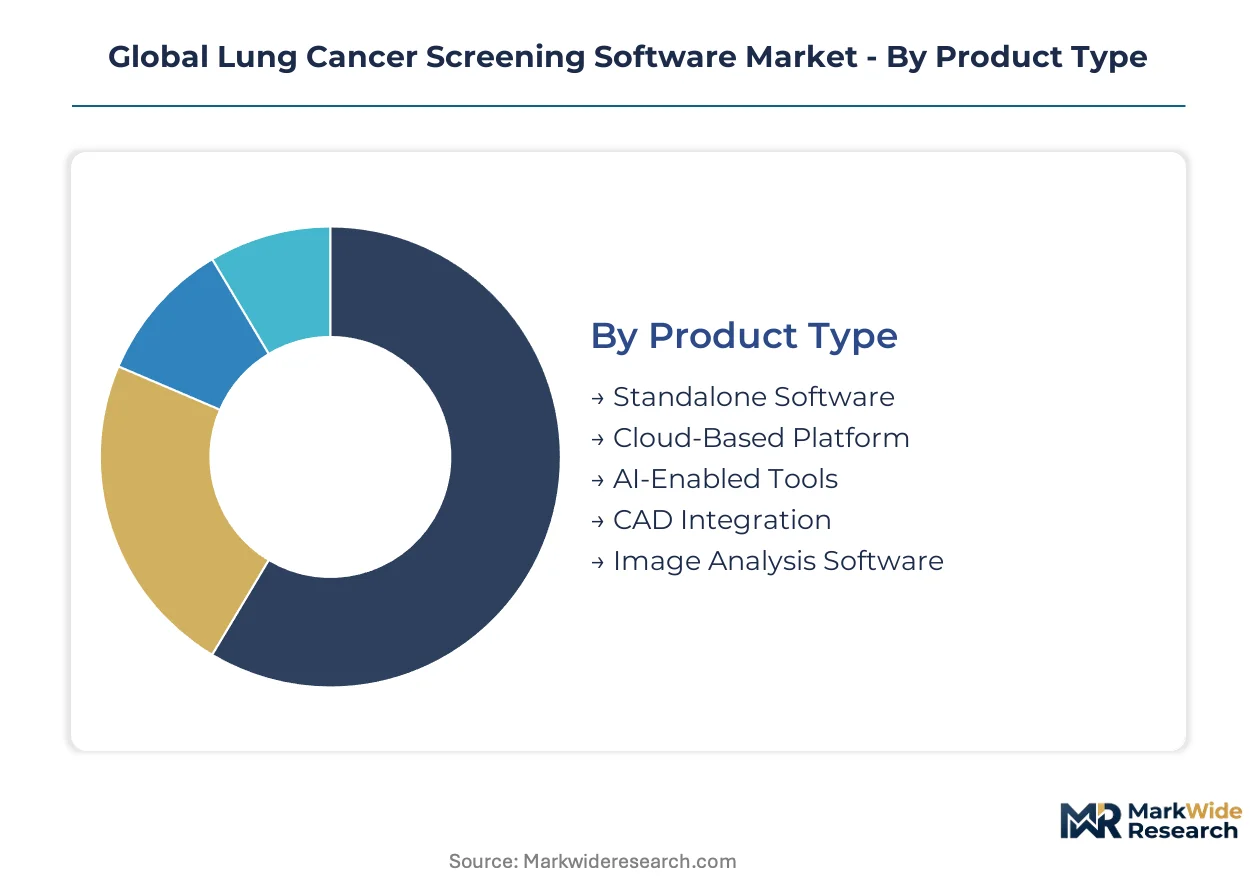
Segmentation in lung cancer screening software reflects divergent deployment architectures. Vendors must calibrate integration depth, computational approach, and clinical workflow positioning to match institutional procurement priorities.
Product Type:
Standalone offerings sit outside PACS infrastructure, while embedded modules fuse directly into CT acquisition systems and cloud-native platforms centralize multi-site image management.
- AI-Enabled Tools:Algorithmic modules processing LDCT volumes through trained neural networks for nodule detection and malignancy scoring. United States hospital networks under CMS reimbursement mandates drive procurement of FDA-cleared platforms with registry integration capabilities.
- Cloud-Based Platform:Centralized architectures hosting image storage, AI inference, and structured reporting through browser-based interfaces. Telemedicine providers across Germany and the Netherlands adopt these to comply with GDPR data localization while enabling distributed radiologist access.
- Standalone Software:On-premise installations requiring dedicated hardware and local IT maintenance. Smaller imaging centers in India with limited cloud infrastructure reliance represent residual demand pockets.
- CAD Integration:Computer-aided detection modules embedded within legacy PACS workflows. European hospitals with Siemens Healthineers or GE Healthcare scanner fleets favor these for minimized workflow disruption.
- Image Analysis Software:Volumetric quantification tools for longitudinal nodule tracking without diagnostic AI components. Research institutions in Japan employ these for protocol standardization in employer-sponsored screening programs.
AI-Enabled Tools lead volumes today; Cloud-Based Platform is gaining share fastest.
Technology:
Computational approaches range from supervised classification models to unsupervised pattern extraction, with regulatory clearance complexity varying by algorithmic transparency.
- Deep Learning:Multi-layer neural architectures trained on annotated thoracic CT datasets for end-to-end nodule detection. FDA 510(k) pathways under 21 CFR Part 892 favor these for sensitivity thresholds exceeding 90% in clinical validation trials.
- Machine Learning:Traditional supervised algorithms with explicit feature engineering for risk stratification. European imaging centers under EU AI Act conformity requirements prefer these for auditable decision boundaries and explainable outputs.
- Natural Language Processing:Text extraction systems converting radiology reports into structured screening registry data. United States health systems leverage these for CMS-mandated outcome documentation.
- Pattern Recognition:Rule-based image analysis for texture and shape classification. Legacy deployments in Japanese corporate health clinics persist due to METI-backed standardization protocols.
- Radiomics:High-dimensional feature quantification from medical images for prognostic modeling. Academic medical centers in Germany and the United Kingdom deploy these within federated learning frameworks for multi-site algorithm refinement.
Deep Learning dominates revenue concentration; Machine Learning is climbing the fastest amid regulatory pressure for algorithmic transparency.
Screening Application:
Functional modules span the screening continuum from population triage through treatment planning, with reimbursement eligibility conditioning commercial viability.
- Nodule Detection:Primary screening algorithms identifying pulmonary nodules at sub-millimeter slice resolution. United States Medicare coverage determination for LDCT screening directly reimburses these when integrated with accredited registries.
- Risk Assessment:Integrative models combining imaging biomarkers with clinical variables for malignancy probability scoring. Kaiser Permanente and Mayo Clinic validation committees pre-certify these for system-wide deployment.
- Early Detection:Population-scale triage tools for asymptomatic high-risk cohorts. Japan's employer-sponsored screening mandates create procurement windows in corporate health clinics.
- Diagnostic Support:Secondary analysis tools assisting radiologist interpretation without autonomous diagnostic claims. Imaging centers in India with limited specialist density adopt these for teleradiology workflow augmentation.
- Prognostic Analysis:Longitudinal tracking systems predicting nodule growth trajectories. Oncology research institutes in the Netherlands employ these within clinical trial frameworks.
Nodule Detection leads volumes today; Risk Assessment is expanding most quickly as outcome-based contracting gains traction.
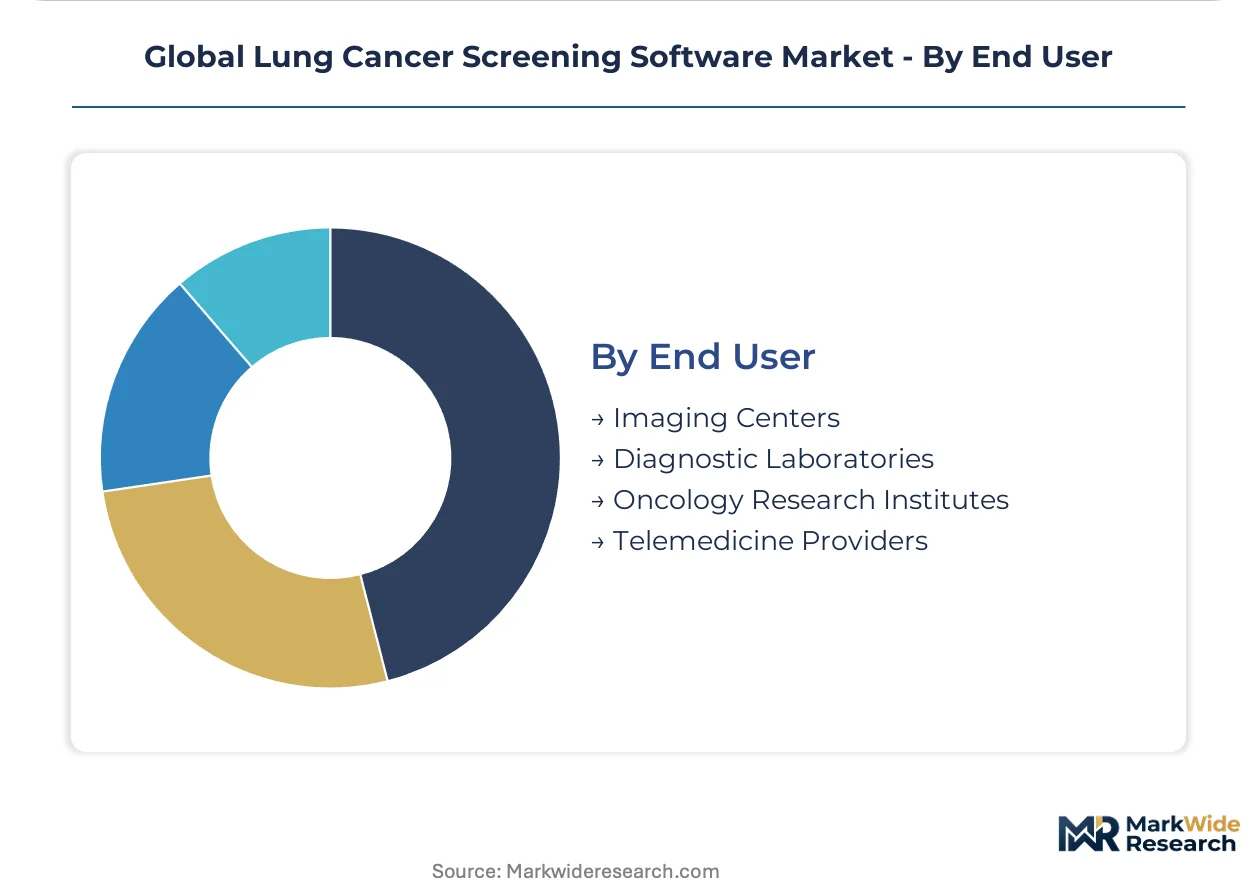
End User:
Institutional buyers vary in procurement authority, technical infrastructure, and reimbursement access, fragmenting vendor go-to-market approaches.
- Imaging Centers:Dedicated radiology facilities with high LDCT throughput and direct CMS billing relationships. United States outpatient chains represent the fastest-expanding buyer segment as screening protocol standardization advances.
- Telemedicine Providers:Distributed networks connecting patients with remote radiologist interpretation. Cloud-based platform deployments accelerate among these operators seeking centralized image management without on-premise overhead.
- Diagnostic Laboratories:Pathology-focused institutions expanding into imaging services through acquisition. European networks under EMA diagnostic regulation harmonization drive integration demand.
- Oncology Research Institutes:Academic centers conducting clinical trials and algorithm validation studies. Federated learning adoption concentrates at German, British, and Dutch institutions for GDPR-compliant multi-site collaboration.
Imaging Centers lead volumes today; Telemedicine Providers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Computed tomography screening protocols first achieved scale in United States academic medical centers during the National Lung Screening Trial, establishing the clinical evidence base that now drives software procurement across high-income health systems.
United States
CMS reimbursement mandates for accredited registry integration pull hospital networks toward FDA-cleared platforms. The national coverage determination for annual LDCT screening conditions payment on structured reporting compliance. Major health systems in California and the Northeast Corridor operate centralized AI validation committees that pre-certify algorithms before local deployment.
Germany
Federated learning adoption concentrates at academic medical centers seeking GDPR-compliant multi-site collaboration for algorithm refinement. BfArM coordinates mutual recognition agreements with France's ANSM to streamline CE-marked AI deployment across hospital networks. The Rhine-Ruhr and Bavarian medical technology clusters host integration pilots between Siemens Healthineers CT fleets and cloud-native screening platforms.
Japan
Employer-sponsored screening mandates under METI-backed population health initiatives create procurement windows in corporate health clinics. PMDA regulatory pathways favor volumetric tracking protocols with documented inter-reader variability reduction. The Kanto region around Tokyo anchors deployment of AI-assisted workflows in occupational medicine settings.
India
Tier-2 and Tier-3 cities with rising CT scanner penetration but limited specialist radiologist density present demand for teleradiology-integrated screening platforms. CDSCO medical device regulations govern software-as-medical-device classifications for nodule detection algorithms. Diagnostic imaging networks in Maharashtra and Karnataka pilot cloud-based platforms to bypass on-premise infrastructure constraints.
Netherlands
Oncology research institutes deploy prognostic analysis tools within clinical trial frameworks requiring longitudinal nodule tracking. GDPR data localization requirements accelerate adoption of federated learning architectures that unify model training without centralized data pooling. The Amsterdam-Utrecht medical research corridor leads European coordination on post-market surveillance plans for high-risk diagnostic AI.
Global Lung Cancer Screening Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory certification depth and PACS integration sophistication. The vendor base organizes into three tiers: imaging hardware incumbents bundling software with CT scanner fleets, standalone AI developers seeking FDA 510(k) clearance, and cloud-native platforms targeting telemedicine networks. Dominant competitive moves include federated learning partnerships with academic medical centers and outcome-based contracting tied to false-positive reduction metrics.
Among imaging hardware incumbents, Siemens Healthineers and GE Healthcare exemplify the integrated-platform archetype, anchoring screening workflows through CT scanner installed bases. Nuance Communications, Inc. occupies a position within the speech-recognition-to-structured-reporting pipeline, representing the workflow-layer specialization tier.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Nuance Communications, Inc. |
| FUJIFILM Holdings Corporation |
| PenRad Technologies, Inc. |
| Eon Health |
| MRS Systems, Inc. |
| MagView |
| Others |
Supply & Pricing Matrix
Radiology group purchasing organization consolidation across United States health systems is compressing vendor pricing flexibility and forcing suppliers toward outcome-based contract structures with malpractice indemnification bundles.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared platforms with registry integration from CE-marked European alternatives and uncertified research-grade tools. Price differentiation hinges on 510(k) clearance status and PACS integration depth. Cost compression in the standard tier is intensifying because cloud-native entrants are undercutting on-premise licensing models. Imaging centers in India exhibit highest price sensitivity; Kaiser Permanente-scale IDNs command volume discounts exceeding 40% off list.
Supply Chain Analysis
India's domestic-content mandates for government-procured medical devices are reshaping sourcing patterns for CT scanner hardware and edge-computing inference chips. Software development concentrates in the United States, Germany, and Israel; GPU acceleration hardware draws from Taiwan and South Korea. Single-source vulnerability in NVIDIA A100/H100 supply creates deployment bottlenecks for deep learning training pipelines. Distribution runs through radiology GPOs and hospital system centralized AI validation committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds returns through regulatory ratcheting, with the EU AI Act's high-risk system classification creating irreversible compliance thresholds that lock out uncertified competitors.
For Market Incumbents: Anchor screening workflow dominance through backward integration into edge-computing CT gantry electronics, eliminating network transmission latency for high-volume sites. Defend against cloud-native disrupters by embedding federated learning nodes within existing PACS infrastructure, creating switching costs through multi-site algorithm refinement partnerships with German and Dutch academic medical centers.
For New Entrants and Emerging Players: Cloud-native teleradiology platforms offer the most penetrable entry vector for telemedicine providers across India's Tier-2 and Tier-3 cities lacking specialist radiologist density. Target employer-sponsored screening mandates in Japan's Kanto region through METI-aligned volumetric tracking protocols. Pursue white-label CAD integration partnerships with Siemens Healthineers and GE Healthcare scanner fleets rather than standalone FDA 510(k) pathways.
For Investors and Strategic Acquirers: Asymmetric upside sits with cloud-native platforms possessing GDPR-compliant federated learning architectures and established CE-marking pathways under EU AI Act conformity assessment. Long-term viability favors vendors with dual FDA-EU regulatory clearance and embedded registry integration capabilities. Watch for inflection when CMS expands reimbursement beyond high-risk populations to broader screening cohorts.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | GDPR-compliant multi-site algorithm refinement accelerates regulatory submission timelines at German academic medical centers. |
| FDA 510(k) Submission | Clearance under 21 CFR Part 892 unlocks Medicare reimbursement for LDCT screening integrated with accredited registries. |
| Hospital System Partnership | Pre-certification by Kaiser Permanente or Mayo Clinic validation committees enables system-wide deployment across IDNs. |
| Edge Computing Integration | On-device inference chips embedded in CT gantry electronics eliminate network bottlenecks for high-volume United States screening sites. |
| Reimbursement Strategy | CMS national coverage determination compliance conditions software payment on structured reporting integration with accredited registries. |
Research Methodology
Multiple input streams — primary interviews with radiology department heads, AI validation committee chairs, and GPO contracts managers; secondary validation through FDA 510(k) filings, CMS Medicare reimbursement databases, and EU AI Act conformity assessment records — were reconciled through bottom-up and top-down triangulation.
Data-stream reconciliation across deployment model, health system scale, regional regulatory cluster, and PACS integration complexity shaped the analytical framework over the projection horizon. CAGRs derived from installed base expansion rates and reimbursement policy elasticity were cross-checked against CT scanner shipment data and cloud infrastructure capex disclosures from telemedicine providers.
The model assumes a particular technology adoption path; alternative pathways for adaptive AI algorithms with continual learning capabilities would alter the outlook if FDA guidance on post-deployment drift monitoring shifts. Forecasts reflect assumptions regarding Medicare reimbursement expansion velocity and EU AI Act enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Solutions
Protein Detection and Quantification Market
Diagnostic Solutions
Global Ioversol Market
Diagnostic Solutions
Europe Lung Cancer Screening Software Market
Diagnostic Solutions
Protein Assays Market
Diagnostic Solutions
Hepatitis C Diagnosis and Treatment Market
Diagnostic Solutions
North America Lung Cancer Screening Software Market
Diagnostic Solutions
Mobile Applications for Melanoma Detection Market
Diagnostic Solutions
Global Enzyme-Linked Immunosorbent Assay (ELISA) Market
Diagnostic Solutions
Multiple Reaction Monitoring Assay Market
Diagnostic Solutions
Oral Screening Systems Market
Diagnostic Solutions
Near-Patient Molecular Solutions Market
Diagnostic Solutions
Global Upper Gastrointestinal (GI) Series Market
Diagnostic Solutions
Total Bile Acid Assay Kit Market
Diagnostic Solutions
Middle East and Africa Lung Cancer Screening Software Market