
 Global Nasopharyngeal Swab Market | 2026-2036
Global Nasopharyngeal Swab Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nasopharyngeal Swab Market Foresight
Chinese polymer fiber producers is decoupling from historic European supply chains for nasopharyngeal swab raw materials, forcing manufacturers to qualify alternative substrate sources. BD leverages backward integration into synthetic flocking operations to secure nylon fiber supply. Thermo Fisher Scientific anchors its position through ISO-certified cleanroom manufacturing across multiple continents. COPAN Diagnostics specializes in automated specimen collection systems that reduce human variability in sample quality.
A nasopharyngeal swab consists of a slender shaft with an absorbent tip designed to collect respiratory epithelial cells from the nasopharyngeal cavity, typically manufactured with shaft lengths of 150-155 mm and tip diameters of 1.5-2.0 mm to navigate the nasal turbinate geometry safely. The device serves as the primary collection vehicle for molecular diagnostic testing of viral respiratory pathogens, with flocked nylon tips demonstrating superior cell release compared to woven fiber alternatives. Foam-tipped products command premium positioning in pediatric and geriatric applications where reduced mucosal trauma drives procurement decisions. Diagnostic laboratories represent the most concentrated end-user margin pool due to high-volume contractual purchasing and integrated logistics requirements.
The FDA regulates nasopharyngeal swabs as Class I medical devices with 510(k) clearance pathways, while the EU MDR imposes stricter biocompatibility and clinical evidence standards for products marketed in Europe. China's NMPA requires domestic registration and manufacturing facility audits for imported specimen collection devices, creating asymmetric market access conditions. ISO 13485 quality management certification has become a baseline procurement filter for government tenders across OECD markets. Stakeholders must monitor evolving regulatory divergence between major jurisdictions as it reshapes manufacturing location decisions and compliance cost structures.
Market Dynamics
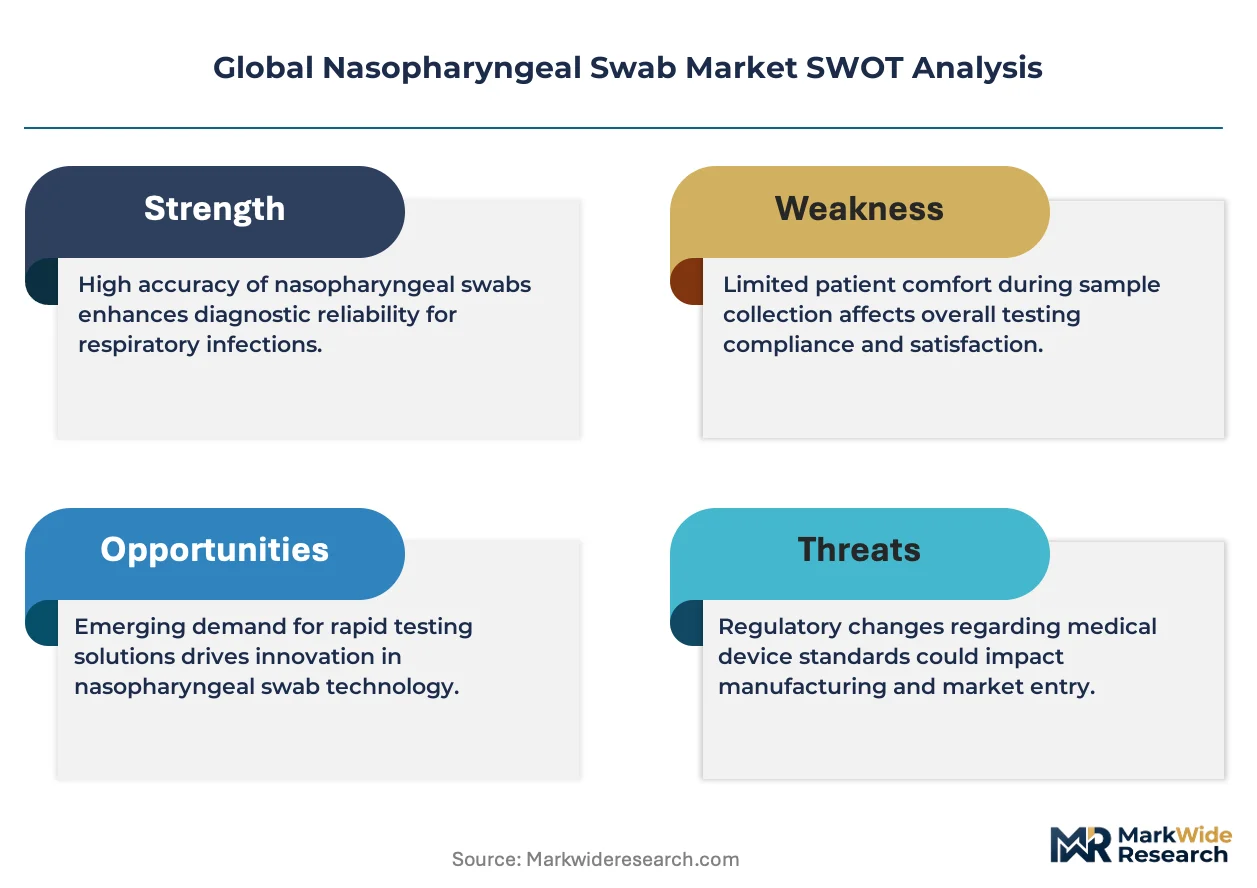
Raw material supply chain decoupling between Chinese polymer fiber producers and European manufacturers is forcing nasopharyngeal swab producers to requalify substrate sources, compressing qualification timelines while elevating quality assurance costs.
Growth Catalysts
- FDA 510(k) pathway streamlining:Expedited clearance for diagnostic sample collection devices accelerates product launch timelines for manufacturers targeting US hospital networks.
- Respiratory pathogen panel expansion:Diagnostic laboratories are consolidating procurement volumes around integrated molecular testing workflows, creating pull-through demand for compatible collection devices.
- Flocked nylon tip technology:Superior epithelial cell release characteristics versus woven fiber alternatives drive specification upgrades in high-sensitivity PCR applications.
Market Restraints
- Nylon fiber supply concentration:Synthetic flocking raw material production clusters in East Asian chemical manufacturing corridors, exposing Western converters to freight cost volatility and tariff exposure.
- EU MDR biocompatibility burden:Stricter clinical evidence requirements for Class I device reclassification extend registration timelines and inflate regulatory consulting expenditures.
- Foam tip cost premium:Pediatric and geriatric applications requiring reduced mucosal trauma absorb 15-40% higher unit costs, limiting addressable market penetration in price-sensitive procurement environments.
Strategic Opportunities
- Automated specimen collection systems:COPAN Diagnostics' robotics integration demonstrates pathway to reduce human variability in sample quality, opening hospital laboratory automation budgets.
- ISO 13485 certification arbitrage:Cleanroom manufacturing investments in Southeast Asian production zones capture OECD tender participation rights at lower facility operating costs.
- Home collection kit channel:Direct-to-consumer respiratory testing authorization creates bypass opportunity around traditional hospital procurement committees.
Industry Challenges
- Multi-jurisdiction registration synchronization:China's NMPA facility audit requirements run parallel to FDA 510(k) reviews, stretching regulatory affairs team capacity and delaying coordinated product launches.
- Cleanroom capex intensity:ISO-certified manufacturing expansion requires dedicated HVAC and environmental monitoring infrastructure that consumes 18-24 month deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nasopharyngeal Swab Market |
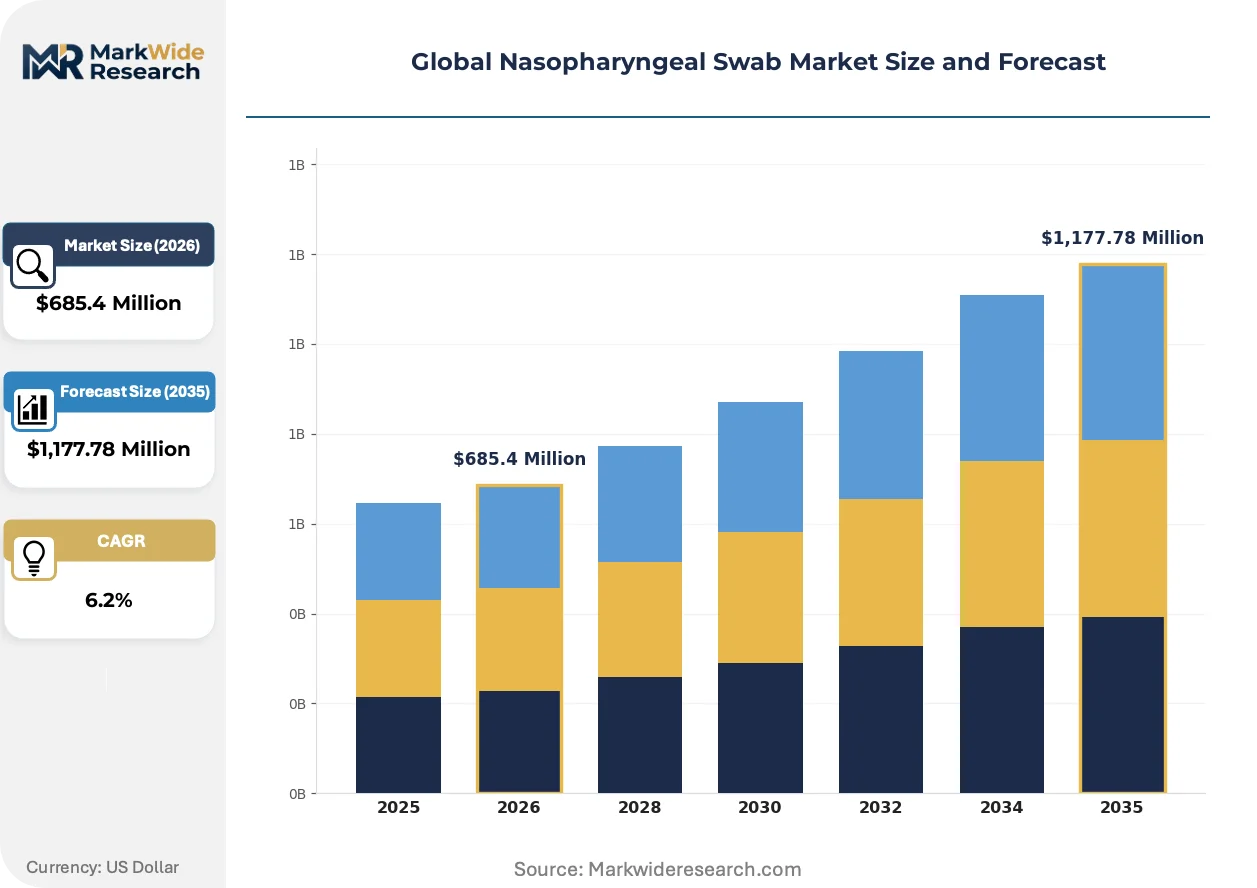
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,177.78 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sterile Nylon, Rayon-tip, Foam-tipped, Polyester, Polyester Dacron Application: COVID-19 Testing, Influenza Detection, RSV Diagnosis, Adenovirus Testing, Other Viral Screening End User: Diagnostic Laboratories, Public Health Agencies, Research Institutes, Point-of-Care Centers, Screening Facilities Distribution Channel: Hospital Pharmacies, Online Retailers, Medical Distributors, Government Procurement, Direct Sales |
| Companies Covered | BD, C. R. Bard, Thermo Fisher Scientific, Cardinal Health, SARSTEDT AG & Co. KG, COPAN Diagnostics, Medical Wire & Equipment, Titan Biotech, Puritan Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nasopharyngeal Swab Market Shifts & Advancements
Manufacturing automation and regulatory technology convergence are compressing quality variance while elevating compliance documentation burdens across production networks.
Flocked nylon tip technology is integrating precision electrostatic flocking controls that deposit uniform fiber density across the absorbent surface. High-throughput diagnostic laboratories in Germany and the United States are specifying these enhanced tips for respiratory pathogen panels requiring minimal cell lysis variation. This fiber engineering standardization is integrating automated optical inspection systems that reject dimensional outliers before packaging, reducing downstream PCR failure rates attributed to sample inadequacy.
The EU MDR's 2021 device classification recalibration imposes biocompatibility testing protocols previously reserved for higher-risk categories. European notified bodies are demanding extended cytotoxicity and sensitization studies for nasopharyngeal swabs, extending technical file preparation by four to six months. Manufacturers with legacy CE certificates under the Medical Devices Directive face compressed transition timelines that favor organizations with established clinical affairs infrastructure in Brussels and Frankfurt regulatory corridors.
Diagnostic laboratory procurement committees are consolidating vendor relationships around integrated supply contracts bundling collection devices with molecular testing reagents. This purchasing centralization displaces fragmented spot-buying through distributor intermediaries, concentrating volume with manufacturers offering logistics integration and consignment inventory programs. The shift is most visible in United States health system networks where laboratory consolidation has reduced independent buying centers by over sixty percent since 2020.
Global Nasopharyngeal Swab Market Segmentation
Swab specification and procurement channel choices determine diagnostic accuracy and supply security. Manufacturers align product portfolios with end-user workflow requirements and regulatory compliance tiers.
Product Type:
Material selection hinges on cell release efficiency, mucosal trauma tolerance, and downstream PCR compatibility.
- Sterile Nylon:Electrostatic flocking creates perpendicular fiber orientation that releases epithelial cells with minimal mechanical agitation. Diagnostic laboratories in Germany and the United States specify this construction for high-sensitivity respiratory pathogen panels.
- Foam-tipped:Open-cell polyurethane construction compresses against nasal turbinate geometry with reduced insertion trauma. Pediatric wards and geriatric facilities absorb 15-40% unit cost premiums to secure patient compliance advantages.
- Rayon-tip:Woven cellulose fiber construction offers cost-efficient specimen collection for routine screening applications.
- Polyester:Synthetic filament construction provides chemical resistance for transport media compatibility.
- Polyester Dacron:Tightly wound fiber construction suits basic viral detection where cell yield requirements are moderate.
Volume sits with Sterile Nylon; growth tilts toward Foam-tipped.
Application:
Test menu expansion drives specification divergence between high-volume screening and specialized pathogen detection.
- COVID-19 Testing:Sustained demand from surveillance programs and travel clearance requirements maintains procurement volumes even as acute case surveillance contracts. China's health commission and US hospital networks anchor contractual purchasing.
- Influenza Detection:Seasonal vaccination efficacy monitoring and antiviral prescribing protocols require compatible collection devices for rapid molecular assays. Public health agencies consolidate procurement around dual COVID-influenza panel workflows.
- RSV Diagnosis:Neonatal unit protocols and pediatric emergency departments specify gentle-collection variants.
- Adenovirus Testing:Military recruitment and congregate living screening drives periodic bulk purchasing.
- Other Viral Screening:Metagenomic sequencing applications and emerging pathogen research create spot demand for specialized collection geometries.
Procurement concentrates in COVID-19 Testing; Influenza Detection climbs fastest as multiplex panel adoption accelerates.
End User:
Buyer sophistication and volume scale separate integrated laboratory networks from fragmented point-of-care deployment.
- Diagnostic Laboratories:High-throughput PCR facilities in the United States and Germany negotiate consignment inventory arrangements and logistics integration. Contractual bundling with molecular reagent suppliers concentrates margin capture with manufacturers offering ISO 13485-certified cleanroom production.
- Public Health Agencies:National stockpiling programs and outbreak response protocols drive surge-capacity requirements with stringent domestic content preferences.
- Research Institutes:Specimen biobanking and longitudinal cohort studies demand lot-traceable devices with extended stability documentation.
- Point-of-Care Centers:Rapid antigen testing workflows prioritize single-pack sterility and intuitive collection guidance.
- Screening Facilities:Mass testing sites and workplace programs optimize for unit economics and bulk packaging efficiency.
Revenue pools concentrate in Diagnostic Laboratories; Public Health Agencies are expanding most quickly as pandemic preparedness budgets institutionalize.
Distribution Channel:
Channel selection reflects procurement governance structures and urgency requirements across buyer segments.
- Medical Distributors:Inventory aggregation and same-day fulfillment capabilities serve hospital network procurement committees. McKesson and Cardinal Health in the United States, plus regional specialists in Germany, consolidate fragmented laboratory demand.
- Government Procurement:Tender participation requires domestic manufacturing facility audits and NMPA, FDA, or EU MDR registration alignment. China's centralized purchasing and US Strategic National Stockpile allocations dominate volume.
- Hospital Pharmacies:Emergency department and inpatient unit replenishment prioritizes immediate availability over contract pricing.
- Online Retailers:Direct-to-consumer respiratory testing kits bypass traditional procurement hierarchies.
- Direct Sales:Large integrated delivery networks negotiate manufacturer-direct arrangements with consignment terms.
Medical Distributors handle present volume; Government Procurement shows steepest expansion trajectory as sovereign stockpiling programs mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer fiber manufacturing corridors in Zhejiang and Jiangsu provinces anchor raw material supply for nasopharyngeal swab production, with East Asian chemical clusters feeding converters across three continents. Demand concentrates where diagnostic infrastructure and regulatory frameworks align.
United States
Hospital network consolidation and laboratory integration drive procurement centralization around integrated supply contracts. FDA 510(k) pathway streamlining accelerates clearance timelines for domestic manufacturers. Boston and Research Triangle Park clusters host molecular diagnostic firms that specify flocked nylon construction for high-sensitivity PCR workflows.
China
National health commission stockpiling programs and mass screening infrastructure sustain volume procurement through centralized purchasing. NMPA facility audit requirements for imported devices create asymmetric market access favoring domestic registrants. Yangtze River Delta manufacturing zones concentrate electrostatic flocking equipment and synthetic fiber conversion capacity.
Germany
Diagnostic laboratory automation and respiratory pathogen panel standardization drive specification upgrades toward precision-flocked tips. EU MDR biocompatibility testing protocols extend technical file preparation timelines. Frankfurt and Munich regulatory corridors host notified body operations and clinical affairs infrastructure.
Japan
PMDA quality management oversight and aging demographics expand pediatric and geriatric application demand for reduced-trauma collection devices. METI industrial policy supports domestic manufacturing resilience for critical medical supplies. Kansai region chemical producers supply specialty polymer substrates to medical device converters.
India
CDSCO medical device rules and public health laboratory expansion create procurement scale for cost-optimized rayon and polyester constructions. PLI scheme incentives attract cleanroom manufacturing investments. Gujarat and Maharashtra pharmaceutical clusters integrate specimen collection devices into diagnostic reagent bundling strategies.
Global Nasopharyngeal Swab Market Competitive Landscape
Global majors compete with regional champions across regulatory certification and cleanroom manufacturing scale, producing a tiered structure where ISO 13485 certification separates tender-eligible suppliers from spot-market participants. Three archetypes dominate: integrated life science conglomerates with backward control over synthetic fiber supply, specialized diagnostic collection device firms with automation expertise, and regional converters serving price-sensitive procurement channels. Capacity expansion and strategic partnerships constitute the primary competitive moves, with manufacturers qualifying alternative substrate sources to offset supply chain decoupling.
Among US-based conglomerates, BD and Thermo Fisher Scientific exemplify integrated archetypes with captive supply chain elements and multi-continent cleanroom networks. COPAN Diagnostics represents the automation-specialist tier, with Italian origins and robotics integration capabilities that reduce human variability in sample collection. SARSTEDT AG & Co. KG anchors the European mid-cap specialist position, with German corporate structure and family-owned governance typical of precision manufacturing firms serving diagnostic laboratory procurement committees.
| Leading Market Players |
|---|
| BD |
| C. R. Bard |
| Thermo Fisher Scientific |
| Cardinal Health |
| SARSTEDT AG & Co. KG |
| COPAN Diagnostics |
| Medical Wire & Equipment |
| Titan Biotech |
| Puritan Medical Products |
| Others |
Supply & Pricing Matrix
Backward integration into synthetic flocking operations anchors supply security and pricing power for nasopharyngeal swab manufacturers navigating raw material decoupling between Chinese polymer fiber producers and European converters. Captive nylon fiber production insulates integrated players from freight cost volatility while compressing qualification timelines for alternative substrate sources.
Pricing Analysis
Service bundling separates contract pricing from spot-market transactions, with diagnostic laboratories securing consignment inventory arrangements and logistics integration alongside per-unit device costs. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with ISO 13485-certified cleanroom products commanding 15-40% premiums over non-certified alternatives. Cost compression in the economy tier intensifies as Asian converters absorb regulatory consulting expenditures for EU MDR compliance. Public health agencies demonstrate lowest price sensitivity due to sovereign stockpiling mandates, while point-of-care centers face acute budget constraints.
Supply Chain Analysis
Single-source vulnerability sits with East Asian chemical manufacturing corridors in Zhejiang and Jiangsu provinces, where electrostatic flocking equipment and synthetic fiber conversion capacity concentrate. Nylon polymer substrates, precision flocking machinery, and sterile packaging materials draw from China, Germany, and Japan. Tariff exposure on cross-Pacific freight routes threatens margin stability for Western converters dependent on Chinese raw material inputs. Distribution runs through medical distributors aggregating hospital network demand alongside government procurement channels managing sovereign stockpile allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nasopharyngeal swab market is becoming a vertical-integration race, with manufacturers pursuing backward control over synthetic fiber supply to offset raw material requalification burdens and secure pricing power in consolidated laboratory procurement channels.
For Market Incumbents: Deepen captive nylon fiber production through electrostatic flocking equipment acquisition in Southeast Asian production zones, securing ISO 13485 certification arbitrage against emerging Asian converters. Expand consignment inventory arrangements with United States health system networks to displace spot-market competitors, while accelerating EU MDR technical file preparation to capture legacy CE certificate transition demand. For New Entrants and Emerging Players: Launch via direct-to-consumer home collection kit channels, bypassing traditional hospital procurement committees and GPO contract barriers. Target pediatric and geriatric foam-tipped segments where reduced mucosal trauma specifications absorb premium pricing and incumbent concentration remains lowest. Pursue NMPA domestic registration pathways to access China's centralized health commission purchasing. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by integrated life science conglomerates seeking cleanroom manufacturing scale and multi-continent regulatory certification infrastructure. Five-to-ten year viability favors manufacturers with established clinical affairs presence in Brussels and Frankfurt regulatory corridors. Monitor FDA 510(k) clearance velocity as inflection indicator for US hospital network procurement momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Fiber Supply | Captive nylon flocking production insulates BD and Thermo Fisher from Chinese-European supply chain decoupling. |
| ISO 13485 Cleanroom Certification Expansion | Southeast Asian facility investments by COPAN Diagnostics capture OECD tender participation at lower operating costs. |
| Automated Specimen Collection System Development | Robotics integration reduces human variability in sample quality, opening hospital laboratory automation budgets. |
| EU MDR Technical File Preparation Acceleration | Extended cytotoxicity studies position SARSTEDT for legacy CE certificate transition timelines. |
| Home Collection Kit Channel Authorization | Direct-to-consumer respiratory testing creates bypass opportunity around traditional procurement hierarchies. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical file submissions, NMPA registration databases, and hospital procurement records, complemented by interviews with diagnostic laboratory directors, GPO contracts managers, biomedical engineers, and regulatory affairs leads. Secondary validation drew from ISO certification registries, customs trade data, and molecular diagnostic reagent bundling disclosures. Bottom-up demand modeling and top-down supply capacity assessments were triangulated to reconcile volume estimates.
Segmentation outputs reflect product type, application, end user, and distribution channel dimensions across the projection horizon, with regional regulatory clusters and cleanroom certification tiers as cross-cutting variables. CAGRs were derived from installed base analysis of PCR laboratory capacity, respiratory pathogen panel adoption curves, and sovereign stockpiling program budgets. Forecast inputs incorporated electrostatic flocking technology diffusion rates and EU MDR transition timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for automated specimen collection systems would alter the outlook if robotics integration accelerates beyond current hospital laboratory capital expenditure planning. Forecasts reflect assumptions about regulatory divergence persistence and raw material requalification timeline compression. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Prenatal and New-Born Genetic Testing Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market