
 Global Cardiac Marker Testing Market | 2026-2036
Global Cardiac Marker Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiac Marker Testing Market Foresight
Reagent rental and subscription-based instrument placement is recalibrating how laboratories procure cardiac marker platforms. Abbott Laboratories leverages its Alinity ecosystem to lock in multi-year consumable contracts across integrated delivery networks. Siemens Healthineers anchors its competitive stance through decentralized point-of-care troponin configurations that reduce emergency department turnaround times. Beckman Coulter competes on high-throughput immunoassay throughput for core lab consolidation strategies.
Cardiac marker testing encompasses quantitative biochemical assays that detect proteins released during myocardial injury, with troponin I assays achieving detection thresholds below 0.01 ng/mL for rule-out protocols within one hour of presentation. These diagnostics serve primarily to stratify acute coronary syndrome risk, monitor therapeutic response, and prognosticate heart failure progression. Troponin I dominates test type revenue due to its specificity for cardiac muscle damage and integration into universal definition of myocardial infarction criteria. Point of care testing technology captures the fastest expansion trajectory as emergency departments and ambulance services demand result generation without central lab transport delays. Immunoassay platforms remain the mature volume backbone, though chemiluminescence configurations command premium positioning through superior sensitivity and throughput economics.
The FDA regulates cardiac marker assays as Class II medical devices requiring 510(k) premarket notification, while CLIA establishes laboratory quality standards that shape test complexity designations and personnel requirements. EMA's In Vitro Diagnostic Regulation mandates post-market performance surveillance and notified body involvement for high-risk cardiac devices, elevating compliance investment across European distribution. Japan's PMDA enforces Japan Industrial Standards for analytical performance that constrain import eligibility for non-domestic manufacturers. Stakeholders must monitor evolving harmonization between FDA and IVDR clinical evidence expectations to avoid duplicative validation burdens that fragment product development roadmaps.
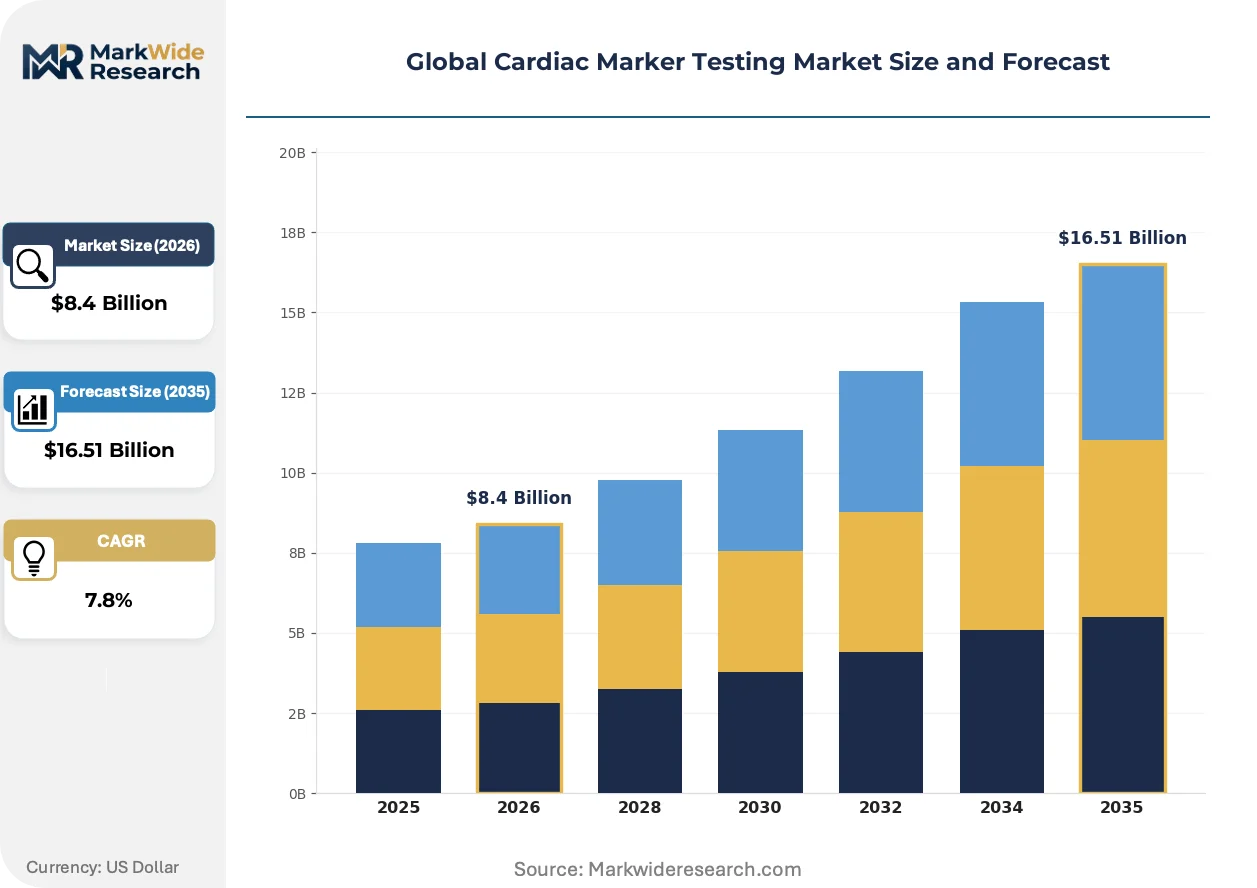
Market Dynamics
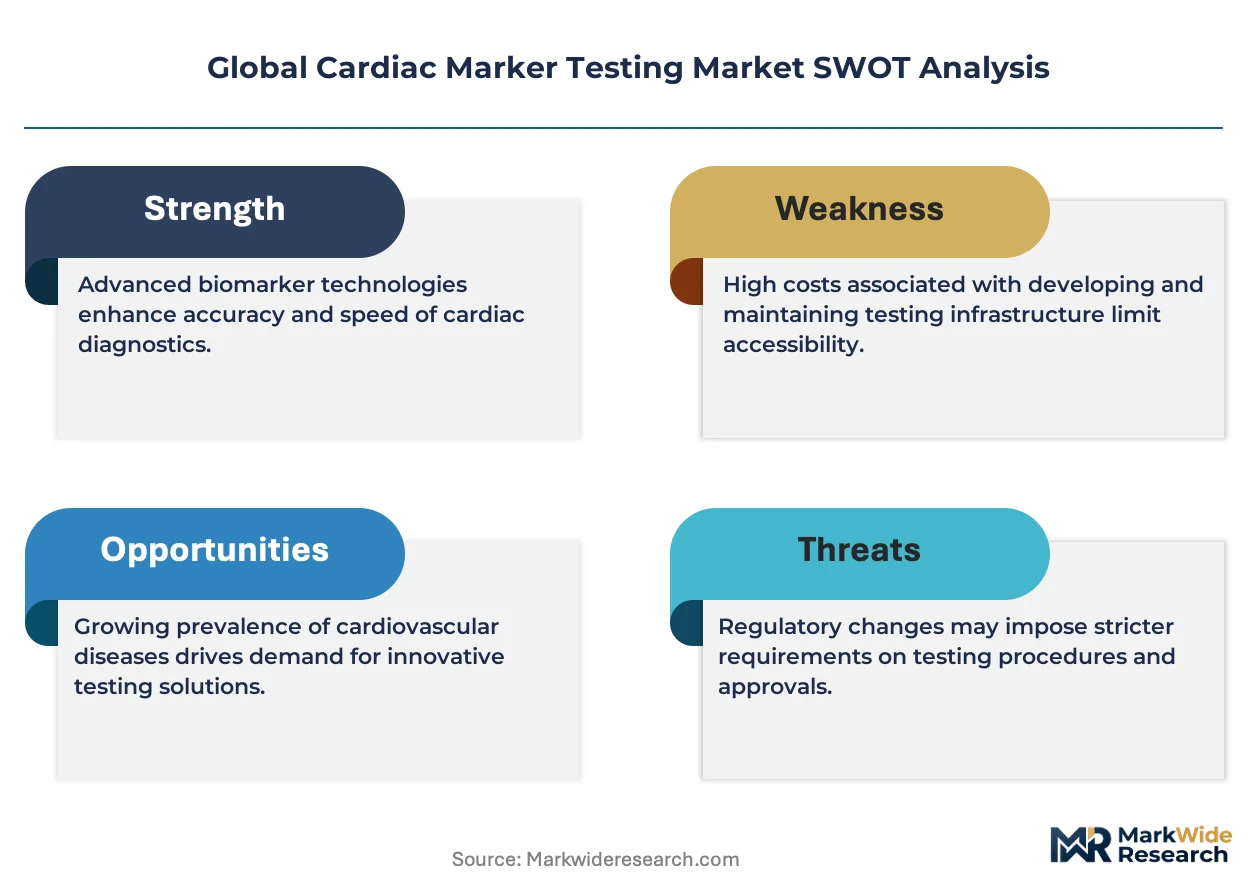
CLIA complexity categorization and FDA 510(k) pathway revisions are compressing assay development timelines while elevating validation burdens for cardiac marker manufacturers. Laboratories must now reconcile automated high-throughput platforms with decentralized point-of-care deployment.
Growth Catalysts
- High-sensitivity troponin protocols:Emergency departments in the United States and Germany are adopting one-hour rule-out algorithms that expand test frequency per patient encounter.
- EMA IVDR post-market surveillance:European notified body involvement is accelerating quality differentiation that favors established assay manufacturers with robust clinical evidence portfolios.
- Ambulance-based point-of-care deployment:Pre-hospital troponin testing in Japan and Australia is creating new demand nodes outside traditional hospital laboratory channels.
Market Restraints
- Reagent rental contract lock-in:Multi-year consumable commitments to Abbott and Siemens platforms constrain laboratory switching flexibility and suppress price competition.
- Antibody raw material concentration:Specialized troponin antibody production concentrates among a handful of European and North American suppliers, exposing assay manufacturers to batch variability risk.
- CLIA high-complexity personnel requirements:Certified laboratory scientist staffing shortages in rural United States markets limit test menu expansion regardless of platform capacity.
Strategic Opportunities
- India's cardiovascular disease burden:Underpenetrated tier-two and tier-three cities present white space for affordable chemiluminescence platforms as CDSCO streamlines IVD registration pathways.
- NT-proBNP heart failure monitoring:Outpatient chronic disease management programs in Germany and Japan are expanding biomarker surveillance beyond acute coronary syndrome episodes.
- Digital pathology integration:Convergence of immunoassay data with electronic health record analytics is enabling risk stratification tools that laboratories can monetize as service extensions.
Industry Challenges
- Cross-platform standardization gaps:Troponin I assay harmonization between Beckman Coulter, Abbott, and Roche methodologies remains incomplete, complicating serial testing protocols.
- Legacy LIS integration complexity:Hospital information system interoperability with new Alinity and Atellica configurations demands substantial IT capital and extended implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiac Marker Testing Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Troponin I, Creatine Kinase-MB, Myoglobin, B-Type Natriuretic Peptide, Lactate Dehydrogenase, Heart-type Fatty Acid Binding Protein Technology: Immunoassay, Enzyme-linked Immunosorbent Assay, Chemiluminescence, Fluorescence Immunoassay, Point of Care Testing, Electrochemiluminescence End User: Hospital Laboratories, Diagnostic Centers, Cardiology Clinics, Research Institutions, Emergency Care Units, Specialty Labs Sample Type: Whole Blood, Serum, Plasma, Urine, Saliva, Capillary Blood |
| Companies Covered | Thermo Fisher Scientific, Randox Laboratories, Roche Diagnostics Corporation, bioMérieux, Ortho Clinical Diagnostics, Abbott Laboratories, Beckman Coulter, Becton Dickinson and Company, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiac Marker Testing Market Shifts & Advancements
Cardiac marker testing is fragmenting across centralized core laboratory automation and distributed emergency department deployment. Manufacturers are engineering platform architectures that accommodate both throughput extremes without assay performance degradation.
High-sensitivity troponin I immunoassay architecture is modularizing around interchangeable detection modules that laboratories can reconfigure between STAT and batch processing modes. Emergency departments in the United States and Germany are adopting these flexible platforms to eliminate duplicate instrument footprints. The structural consequence is compressing capital deployment cycles as hospitals defer dedicated point-of-care purchases in favor of adaptable core lab extensions.
EMA's In Vitro Diagnostic Regulation is mandating post-market performance surveillance and notified body recertification for high-risk cardiac devices. European manufacturers face elevated compliance investment that disproportionately burdens mid-tier assay developers. Cardiac troponin and natriuretic peptide product categories are responding through accelerated clinical evidence generation and strategic withdrawal of legacy assays from EU distribution.
Integrated delivery networks are consolidating procurement authority over previously autonomous hospital laboratories. United States health systems are unbundling instrument placement from reagent supply agreements, replacing them with performance-guaranteed service contracts. This behavior is most visible in multi-hospital Catholic health systems and academic medical center networks where centralized supply chain functions now dictate platform standardization.
Global Cardiac Marker Testing Market Segmentation
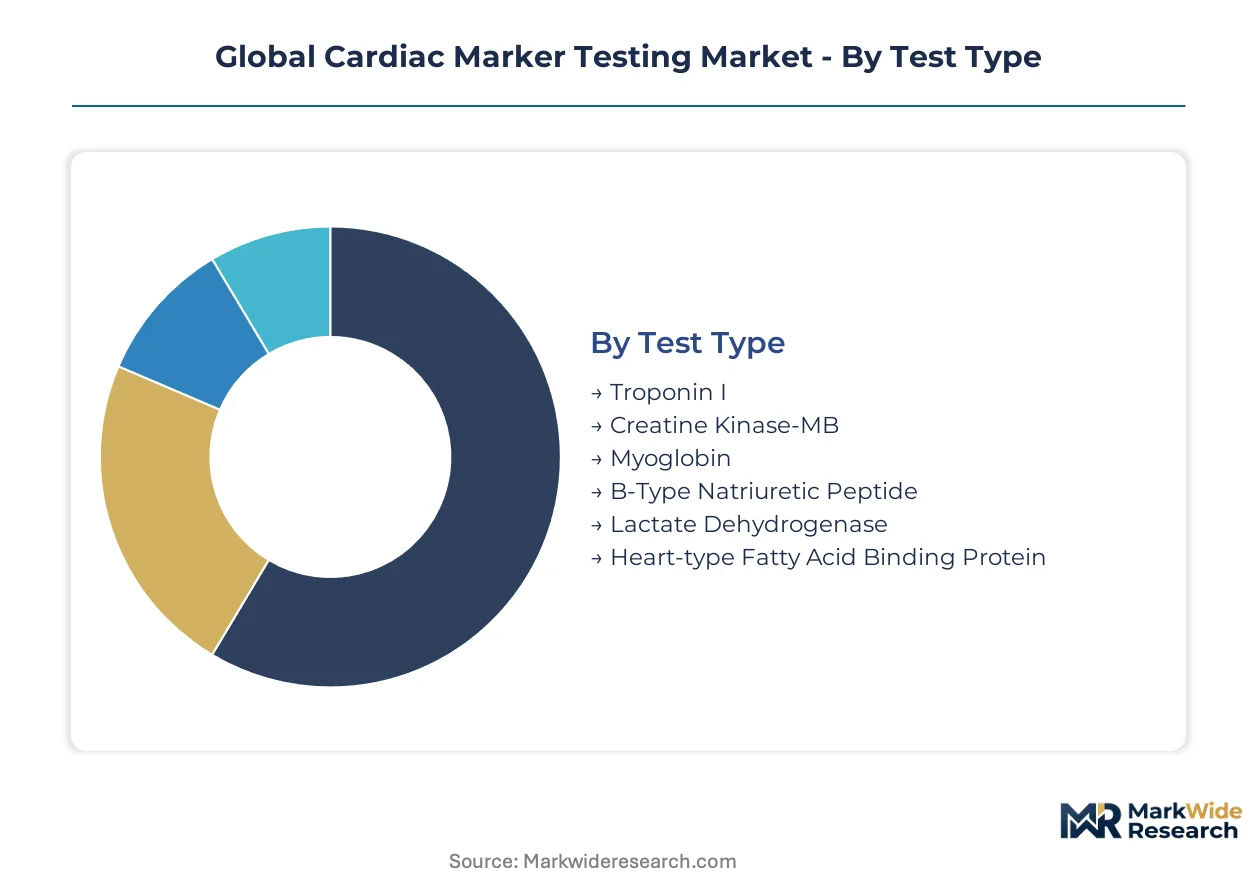
Cardiac marker testing segments fragment across clinical workflow intensity, analytical sensitivity requirements, and care setting infrastructure. Procurement decisions in hospital laboratories diverge sharply from emergency department point-of-care deployments, creating distinct performance specifications within each category.
Test Type:
Clinical utility and guideline incorporation separate high-volume routine assays from emerging biomarkers seeking protocol integration.
- Troponin I:High-sensitivity immunoassays detect cardiac muscle damage below 0.01 ng/mL thresholds, enabling one-hour rule-out protocols in United States and German emergency departments. FDA 510(k) clearances and universal myocardial infarction definition criteria lock this biomarker into acute coronary syndrome diagnostic pathways.
- B-Type Natriuretic Peptide:Quantitative assays for NT-proBNP and BNP fragments stratify heart failure severity and monitor therapeutic response in German and Japanese outpatient programs. Chronic disease management expansion is pushing testing beyond acute episodes into ambulatory surveillance.
- Creatine Kinase-MB:Traditional myocardial injury marker with declining protocol relevance as troponin sensitivity improves.
- Myoglobin:Early-rise kinetics support early exclusion of myocardial infarction in combination algorithms.
- Lactate Dehydrogenase:Nonspecific enzyme marker retained for cost-sensitive testing environments and differential diagnosis panels.
- Heart-type Fatty Acid Binding Protein:Emerging early marker with limited regulatory validation but pre-hospital research interest in Japan and Australia.
Troponin I leads volumes today; B-Type Natriuretic Peptide is gaining share fastest.
Technology:
Platform selection hinges on throughput requirements, capital constraints, and result turnaround specifications across laboratory tiers.
- Chemiluminescence:Acridinium-ester and alkaline phosphatase conjugate systems deliver sub-picogram sensitivity with batch processing economics. Core laboratories in United States academic medical centers and German hospital networks deploy these for high-volume troponin and natriuretic peptide testing.
- Point of Care Testing:Handheld and cartridge-based analyzers generate results within 15 minutes without central lab transport. Ambulance services in Japan and emergency departments in Australia are expanding pre-hospital deployment to compress door-to-diagnosis intervals.
- Immunoassay:Conventional enzyme and fluorescence detection platforms retain installed base in mid-tier hospital laboratories.
- Enzyme-linked Immunosorbent Assay:Microplate formats persist in research and low-volume reference laboratory settings.
- Fluorescence Immunoassay:Time-resolved detection configurations serve mid-throughput laboratories seeking sensitivity without full chemiluminescence capital investment.
- Electrochemiluminescence:Ruthenium-based detection with magnetic bead separation commands premium positioning in consolidated health system laboratories.
Chemiluminescence anchors core laboratory throughput; Point of Care Testing is expanding most quickly into decentralized settings.
End User:
Capital intensity and test menu breadth determine which facilities operate automated platforms versus outsourced or point-of-care alternatives.
- Hospital Laboratories:Integrated delivery networks in United States Catholic health systems and German university hospitals operate centralized high-throughput lines. Automated immunoassay tracks process troponin, BNP, and CK-MB on shared platforms with STAT prioritization capabilities.
- Emergency Care Units:Standalone point-of-care deployments in United States and Australian emergency departments bypass central lab queues for chest pain triage. FDA-cleared handheld devices and waived complexity status under CLIA enable nurse-operated testing.
- Diagnostic Centers:Independent reference laboratories in India and Brazil aggregate samples from multiple facilities, favoring batch-optimized platforms.
- Cardiology Clinics:Office-based practices in Japan and Germany perform limited BNP monitoring with compact analyzer footprints.
- Research Institutions:Academic centers validate novel biomarkers including heart-type fatty acid binding protein for prospective clinical trials.
- Specialty Labs:Focused cardiac reference services in Switzerland and United Kingdom maintain harmonization panels for assay standardization studies.
Hospital Laboratories concentrate absolute test volumes; Emergency Care Units are climbing the fastest as pre-hospital protocols proliferate.
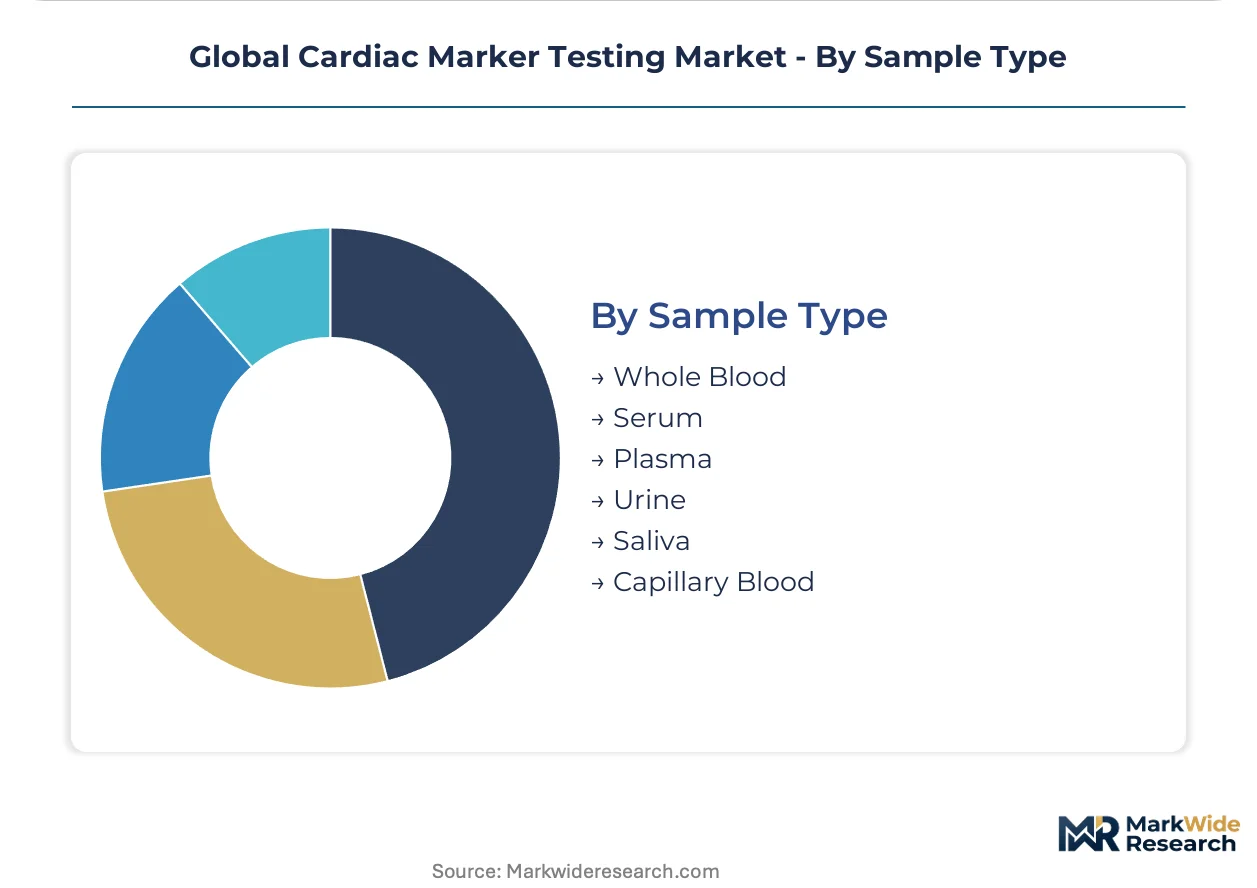
Sample Type:
Collection logistics and analyte stability requirements shape platform engineering and clinical workflow design.
- Serum:Gold-top tube centrifugation yields stable troponin and BNP measurements with established reference ranges. Core laboratories in Germany and Japan standardize on serum for longitudinal patient monitoring and harmonization compliance.
- Whole Blood:Direct cartridge insertion without processing steps enables ambulance and emergency department point-of-care deployment. Lithium heparin and EDTA anticoagulant compatibility varies by platform chemistry.
- Plasma:Separated plasma extends analyte stability for transported samples and reference laboratory batch processing.
- Capillary Blood:Fingerstick collection supports decentralized testing in resource-limited settings and pediatric populations.
- Urine:Limited cardiac marker validation; occasional natriuretic peptide correlation studies in research contexts.
- Saliva:Experimental collection matrix with no routine clinical application in cardiac diagnostics.
Serum dominates validated reference methods; Whole Blood is gaining share fastest as point-of-care platforms displace pre-analytical processing steps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys high-sensitivity troponin protocols at triple the per-capita frequency of Japan, yet Germany achieves faster emergency department turnaround through integrated pre-hospital networks. This divergence reflects how infrastructure configuration shapes testing intensity beyond biomarker availability alone.
United States
Integrated delivery networks in Catholic health systems and academic medical centers drive automated platform consolidation. FDA 510(k) pathway revisions compress assay validation timelines while elevating clinical evidence requirements. The Boston-Cambridge corridor anchors point-of-care innovation clusters where emergency medicine researchers validate one-hour rule-out algorithms.
Germany
University hospital networks standardize on chemiluminescence throughput for troponin and natriuretic peptide panels. EMA IVDR post-market surveillance mandates accelerate quality differentiation among established manufacturers. The Rhine-Ruhr metropolitan region concentrates reference laboratory capacity for harmonization studies across Beckman Coulter, Abbott, and Roche methodologies.
Japan
Ambulance-based point-of-care deployment expands pre-hospital troponin testing beyond traditional laboratory channels. PMDA enforces Japan Industrial Standards for analytical performance that constrain import eligibility. The Kanto region surrounding Tokyo hosts dense concentrations of cardiology clinics performing outpatient BNP monitoring with compact analyzer footprints.
India
Tier-two and tier-three cities present underpenetrated demand for affordable chemiluminescence platforms as cardiovascular disease burden rises. CDSCO streamlines IVD registration pathways to accelerate market entry for multinational manufacturers. Maharashtra and Gujarat industrial corridors attract diagnostic platform assembly operations serving South Asian distribution networks.
Australia
Emergency departments deploy handheld troponin devices to compress door-to-diagnosis intervals for chest pain triage. TGA alignment with FDA and EMA standards reduces duplicative validation burdens for imported assays. Sydney and Melbourne metropolitan hospitals anchor pre-hospital testing research collaborations with ambulance services.
Global Cardiac Marker Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated diagnostic conglomerates commanding premium positioning in high-throughput core laboratory installations while regional distributors capture point-of-care deployment in decentralized settings. The vendor base organizes into three archetypes: full-platform ecosystems with locked consumable contracts, modular instrument specialists enabling workflow flexibility, and antibody raw material suppliers upstream of assay manufacturing. Consolidation pressure manifests through multi-year reagent rental agreements that constrain laboratory switching flexibility, alongside strategic withdrawals of legacy assays from EU distribution to manage IVDR compliance costs.
Within the full-platform ecosystem tier, Abbott Laboratories and Siemens Healthineers exemplify divergent competitive positioning. Abbott leverages its Alinity ecosystem to anchor multi-year consumable contracts across United States integrated delivery networks. Siemens Healthineers occupies a position emphasizing decentralized point-of-care configurations that reduce emergency department turnaround times. Beckman Coulter sits within the high-throughput specialization archetype, competing on immunoassay throughput for core laboratory consolidation strategies. These three entities collectively represent how platform architecture choices—integrated versus modular, centralized versus distributed—segment competitive territory without direct product-for-product confrontation.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Randox Laboratories |
| Roche Diagnostics Corporation |
| bioMérieux |
| Ortho Clinical Diagnostics |
| Abbott Laboratories |
| Beckman Coulter |
| Becton Dickinson and Company |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
EMA IVDR post-market surveillance mandates gate qualified supply access for cardiac marker assays while filtering premium-tier pricing toward manufacturers with robust clinical evidence portfolios. Laboratories in Germany and Japan face elevated compliance investment that stratifies procurement eligibility across reagent rental contract tiers.
Pricing Analysis
Capacity additions in India are reshaping price floors for mid-tier chemiluminescence platforms as CDSCO streamlines IVD registration pathways. Reagent rental and subscription-based instrument placement dominates pricing structure, with differentiation driven by FDA 510(k) clearance tier and after-sales service bundling. Cost compression in standard-tier assays is intensifying because antibody raw material concentration limits supplier switching. Academic medical centers in the United States show least price sensitivity; tier-two hospitals in India demonstrate highest.
Supply Chain Analysis
Specialized troponin antibody production rests on European and North American specialty suppliers, with batch variability risk concentrated among a handful of producers. Raw material dependencies include acridinium-ester conjugates, magnetic bead separation media, and high-affinity monoclonal antibodies. Single-source vulnerability in antibody supply exposes assay manufacturers to qualification delays. Distribution runs through integrated delivery network procurement committees that consolidate previously autonomous hospital laboratory purchasing authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiac marker testing offers margin expansion through high-sensitivity troponin protocol premiumization and automated platform consolidation that reduces per-test labor cost.
For Market Incumbents: Lock in multi-year consumable contracts across United States integrated delivery networks before CLIA complexity revisions elevate validation burdens. Deepen backward integration into antibody raw material production to insulate against European supplier concentration. Anchor competitive position through Alinity ecosystem standardization that constrains laboratory switching flexibility. For New Entrants and Emerging Players: Direct-to-clinic digital procurement channels in India's tier-two cities bypass entrenched distributor relationships that protect Abbott and Siemens positions. Target ambulance-based point-of-care deployment in Japan and Australia where pre-hospital protocols remain underpenetrated. Pursue CDSCO fast-track registration to capture chemiluminescence platform demand ahead of multinational reagent rental contract saturation. For Investors and Strategic Acquirers: Roll-up economics work for regional point-of-care specialists because fragmented emergency department procurement lacks standardization pressure from integrated delivery networks. Five-to-ten year viability hinges on IVDR compliance cost absorption capacity. Watch EMA notified body backlog clearance rates as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| High-Sensitivity Troponin Assay Development | FDA 510(k) clearance for sub-0.01 ng/mL detection thresholds enables one-hour rule-out protocol adoption in United States emergency departments. |
| Point-of-Care Platform Miniaturization | Handheld cartridge-based analyzers compress door-to-diagnosis intervals for Japanese ambulance services and Australian emergency departments. |
| Antibody Raw Material Backward Integration | In-house monoclonal antibody production reduces batch variability exposure from concentrated European and North American suppliers. |
| Integrated Delivery Network Contract Consolidation | Multi-hospital Catholic health system procurement centralization replaces autonomous laboratory purchasing with performance-guaranteed service agreements. |
| EMA IVDR Clinical Evidence Generation | Post-market surveillance compliance investment filters mid-tier assay developers from European distribution, favoring established manufacturers. |
Research Methodology
Bottom-up hospital laboratory and emergency department deployment modeling reconciled against top-down immunoassay platform shipment tracking forms the analytical core. Primary interviews with clinical laboratory directors, emergency medicine physicians, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA IVDR submission databases, hospital procurement records, and PMDA Japan Industrial Standards documentation.
Input-output matrices connect troponin test volume assumptions to platform capacity utilization rates across chemiluminescence and point-of-care configurations. Segmentation dimensions include test type sensitivity tier, technology detection architecture, end-user capital intensity, and regional regulatory cluster. CAGRs derive from instrument placement trajectory analysis and consumable pull-through modeling across the projection horizon. Forecast inputs incorporate CLIA complexity categorization shifts and EMA notified body certification timelines.
The model assumes a particular technology adoption path; alternative pathways for electrochemiluminescence modularization would alter the outlook. Forecasts reflect underlying assumptions about high-sensitivity troponin protocol penetration and integrated delivery network consolidation velocity. Antibody supplier concentration, IVDR implementation delays, and CLIA personnel shortage severity in rural United States markets warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Immune Response Testing Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Blood Group Typing Market