
 Serum Free Light Chain Assays (Sflc) Market | 2026-2036
Serum Free Light Chain Assays (Sflc) Market Size, Share, and Industry Trends Forecast 2026-2036
Serum Free Light Chain Assays (Sflc) Market Intelligence
European reagent manufacturing capacity is hardening as the EU IVDR implementation pressures smaller kit suppliers to consolidate or exit. Thermo Fisher Scientific leverages its mass spectrometry portfolio to anchor high-sensitivity sFLC quantification workflows in reference laboratories. Siemens Healthineers sustains installed-base dominance across nephrology and hematology segments through integrated turbidimetry platforms. The Binding Site specializes in serum protein diagnostics and occupies a defensible position in monoclonal gammopathy testing protocols.
Serum Free Light Chain Assays measure kappa and lambda immunoglobulin free light chains in serum, typically employing polyclonal antisera with analytical sensitivity thresholds below 1 mg/L to detect monoclonal protein elevations associated with plasma cell disorders. These assays serve primary commercial purposes in diagnosing and monitoring multiple myeloma, light chain amyloidosis, and related lymphoproliferative conditions where traditional serum protein electrophoresis lacks adequate sensitivity. Reagent Kits command the largest revenue share due to recurring consumable demand tied to analyzer installed bases, while Mass Spectrometry represents the fastest-expanding technology platform as laboratories seek orthogonal confirmation methods and improved analytical specificity. The Multiple Myeloma application area generates the most test volume, though Chronic Kidney Disease monitoring is emerging as a distinct growth vector as nephrologists adopt sFLC ratios for dialysis patient management.
FDA 510(k) clearance requirements and the EU IVDR framework shape product development timelines and market access costs for sFLC assay manufacturers seeking commercial distribution in the United States and European Economic Area. The Clinical Laboratory Improvement Amendments in the US and ISO 15189 accreditation standards in Europe further constrain test deployment to validated laboratory environments. Stakeholders must monitor evolving reimbursement codes for mass spectrometry-based protein quantification and the pace of EU IVDR notified body capacity, as both factors will determine which technology platforms achieve scalable clinical adoption.
Market Dynamics
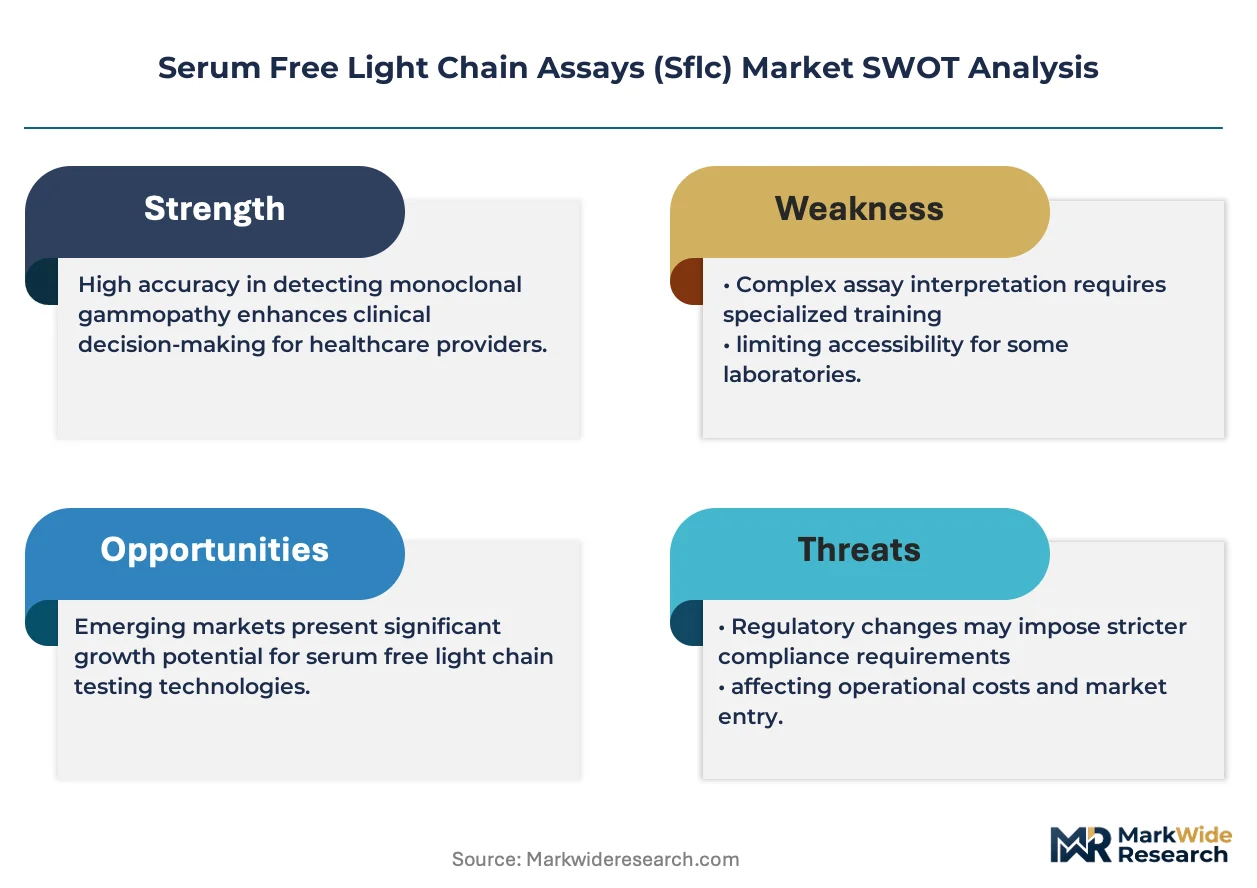
The Serum Free Light Chain Assays market is being fundamentally restructured by the EU IVDR transition, which is compressing the supplier base as smaller reagent manufacturers face unsustainable conformity assessment costs and exit the European Economic Area.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined immunoassay clearance procedures in the United States are accelerating novel platform introductions for monoclonal gammopathy screening.
- Hematology Reference Network Expansion:Germany's university hospital consortia are standardizing sFLC testing protocols across diagnostic laboratories, creating volume pull for automated turbidimetry systems.
- Mass Spectrometry Convergence:Clinical laboratories are adopting LC-MS/MS workflows for orthogonal free light chain confirmation, expanding addressable test menus beyond traditional immunoassay limits.
Market Restraints
- Notified Body Capacity Bottleneck:EU IVDR implementation has created a structural backlog in conformity assessment, delaying product launches and freezing capital deployment for kit manufacturers.
- Polyclonal Antiserum Supply Concentration:Reagent production depends on specialized antibody sourcing from a concentrated supplier base in Western Europe, exposing manufacturers to batch variability and input scarcity.
- Serum Protein Electrophoresis Substitution:Established hospital laboratories retain legacy SPE workflows for initial screening, limiting sFLC assay penetration in cost-constrained settings despite superior analytical sensitivity.
Strategic Opportunities
- Chronic Kidney Disease Monitoring:Nephrology practices in Japan are adopting sFLC ratio monitoring for dialysis patient management, creating a distinct application vertical outside traditional hematology.
- Integrated Diagnostic Platforms:Convergence of turbidimetry and chemiluminescence technologies on single analyzers is enabling laboratory consolidation and test menu expansion without incremental footprint.
- US Medicare Reimbursement Expansion:New molecular pathology billing codes for mass spectrometry-based protein quantification are creating reimbursement tailwinds for reference laboratory adoption.
Industry Challenges
- Analytical Standardization Complexity:Harmonization between polyclonal antisera lots and mass spectrometry calibrators requires continuous cross-method correlation studies, consuming technical resources.
- Legacy Analyzer Integration Friction:Hospital laboratories face workflow disruption when connecting novel sFLC assays to existing laboratory information systems and pre-analytical handling robotics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Serum Free Light Chain Assays (Sflc) Market |
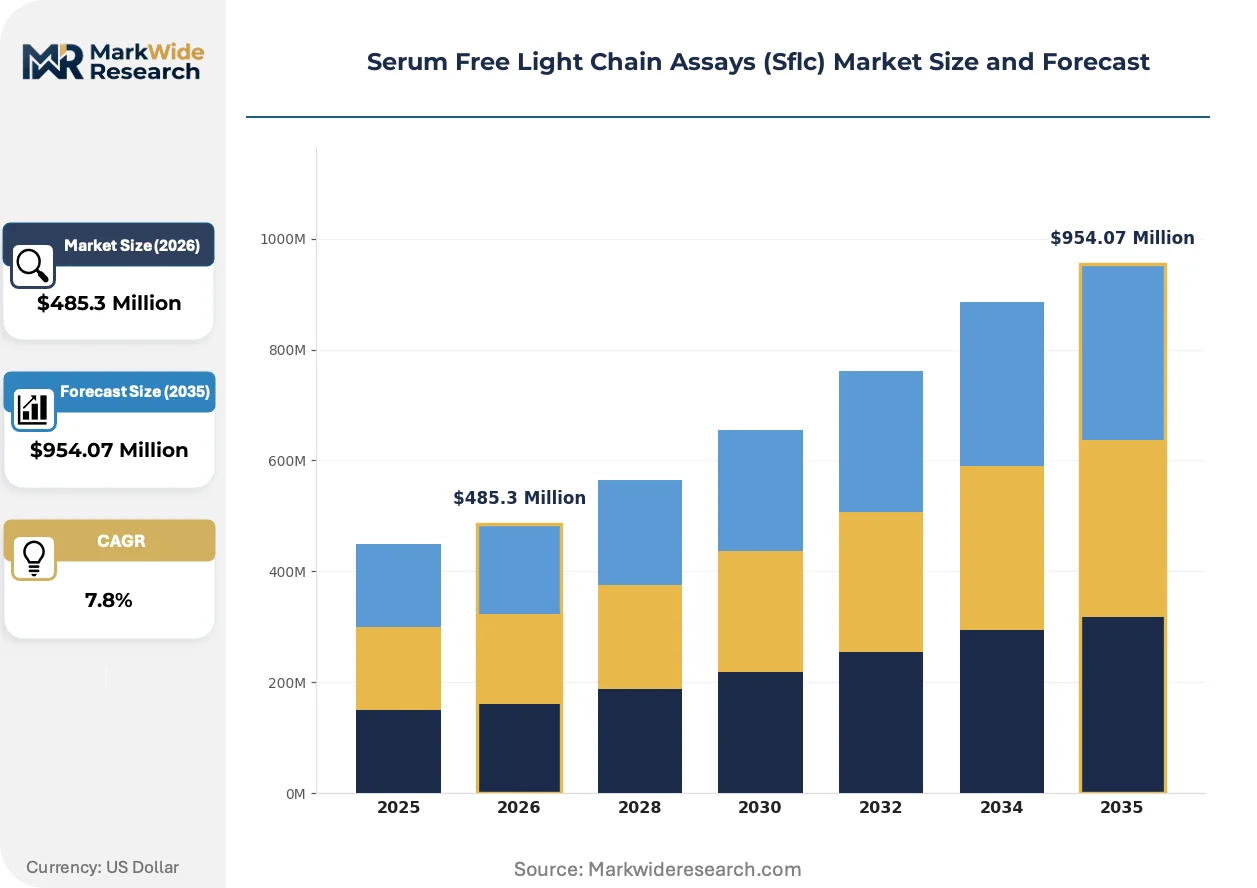
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagent Kits, Analyzer Instruments, Software Solutions, Calibration Standards, Control Materials Application Area: Multiple Myeloma, Light Chain Amyloidosis, Chronic Kidney Disease, Lymphoma, Autoimmune Disorders End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Specialty Clinics, Academic Centers Technology Platform: Immunoassays, Nephelometry, Turbidimetry, Mass Spectrometry, Electrochemiluminescence |
| Companies Covered | Thermo Fisher Scientific, Siemens Healthineers, Sebia, Diazyme Laboratories, The Binding Site, Biomedical Diagnostics, Abingdon Health, Dr Lal PathLabs, KHB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Serum Free Light Chain Assays (Sflc) Market Strategic Shifts & Innovations
Technology convergence and regulatory compression are actively reshaping competitive positioning in the Serum Free Light Chain Assays market, with platform unification and compliance automation emerging as dominant vectors of change.
Mass spectrometry-based free light chain quantification is unifying diagnostic and confirmatory testing workflows into single analytical runs. Reference laboratories in the United States and Germany are adopting LC-MS/MS platforms at accelerating pace to replace sequential immunoassay-electrophoresis protocols. This unification is compressing turnaround times and reducing sample volume requirements, fundamentally altering laboratory staffing and equipment allocation models.
EU IVDR Article 10 technical documentation requirements are forcing reagent manufacturers to rebuild quality management systems from substrate sourcing through post-market surveillance. The industrial consequence is a wave of consolidation as sub-scale kit suppliers sell product lines or exit the European Economic Area entirely. Hematology segments with high test volumes are responding by pre-qualifying fewer, larger suppliers through multi-year exclusive supply agreements.
Laboratory procurement patterns are compressing vendor rosters as health system consolidation accelerates in the United States. Integrated delivery networks are replacing fragmented purchasing across individual hospital laboratories with centralized contracts covering chemistry, immunology, and hematology testing menus. This concentration is most visible in the Southeast and Midwest regions, where Catholic health systems and for-profit chains are aggregating reference laboratory operations into regional hubs.
Serum Free Light Chain Assays (Sflc) Market Segmentation
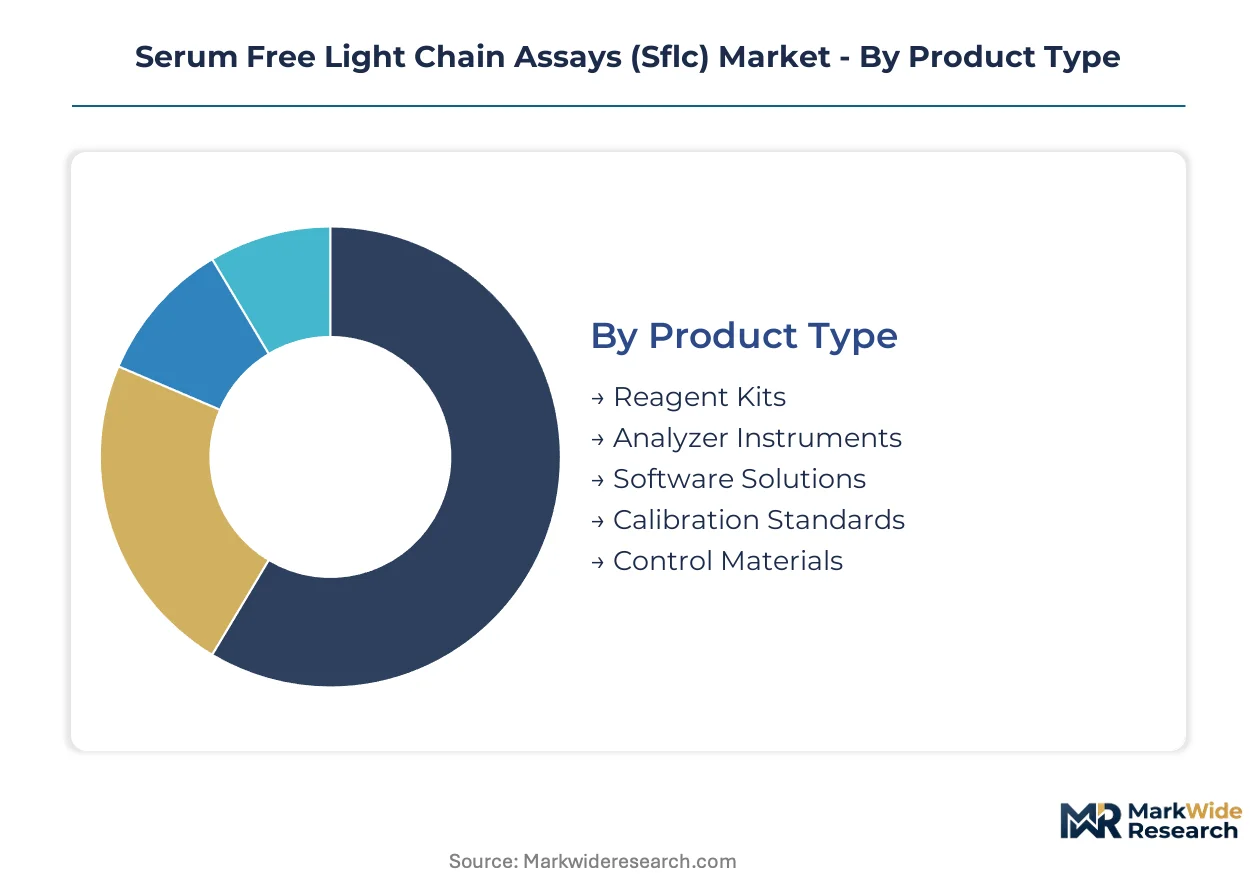
Serum Free Light Chain Assays fragment across product, application, and technology dimensions that determine procurement patterns and margin structures. Each segmentation layer reveals distinct concentration points where suppliers compete on analytical sensitivity, workflow integration, or regulatory compliance.
Product Type:
Volume concentrates in recurring consumables while premium pricing attaches to capital equipment and specialized reference materials.
- Reagent Kits:Polyclonal antisera formulations with lot-to-lot calibration for kappa and lambda quantification. Demand clusters in high-throughput diagnostic laboratories in the United States and Germany where automated platforms process thousands of samples monthly. Recurring purchase obligations lock in multi-year supply relationships.
- Analyzer Instruments:Integrated turbidimetry and nephelometry systems with dedicated sFLC assay protocols. Procurement concentrates in hematology reference networks seeking standardized workflows across hospital consortia. Capital sales cycles extend 12-18 months with extensive validation requirements.
- Software Solutions:Laboratory information system modules for result interpretation and trend monitoring.
- Calibration Standards:Certified reference materials traceable to international protein standards.
- Control Materials:Quality assurance panels for inter-laboratory proficiency testing programs.
Today's leader: Reagent Kits. Tomorrow's challenger: Analyzer Instruments.
Application Area:
Oncology dominates test volume while renal monitoring emerges as a distinct expansion vector.
- Multiple Myeloma:Frontline screening and minimal residual disease monitoring for plasma cell proliferation. Test ordering concentrates in hematology-oncology practices across the United States, Germany, and Japan where reference networks standardize diagnostic protocols. Sensitivity requirements below 1 mg/L drive platform selection.
- Chronic Kidney Disease:sFLC ratio monitoring for dialysis patient management and renal function assessment. Nephrology practices in Japan are adopting serial testing protocols, creating demand outside traditional oncology settings. Reimbursement pathways for renal monitoring remain under development in most markets.
- Light Chain Amyloidosis:Diagnostic confirmation and treatment response evaluation for systemic amyloid deposition.
- Lymphoma:Staging and surveillance for lymphoproliferative disorders with light chain secretion.
- Autoimmune Disorders:Polyclonal free light chain elevation monitoring in inflammatory conditions.
Oncology applications command current volume. Renal monitoring represents the steepest expansion trajectory.
End User:
Customer type determines purchasing authority and technical specification complexity.
- Diagnostic Laboratories:High-volume hospital and commercial laboratories with automated immunoassay platforms. Procurement in the United States flows through integrated delivery network central contracts, while German university hospital consortia negotiate exclusive multi-year agreements. Workflow integration and turnaround time drive vendor selection.
- Research Institutes:Academic and translational research facilities employing mass spectrometry for biomarker discovery. Budget flexibility supports premium LC-MS/MS platforms with custom method development capabilities.
- Blood Banks:Donor screening and plasma derivative quality control operations.
- Specialty Clinics:Hematology and nephrology practices with point-of-care testing requirements.
- Academic Centers:Teaching hospitals with dual clinical and research missions.
Diagnostic Laboratories anchor current revenue. Research Institutes are gaining share fastest.
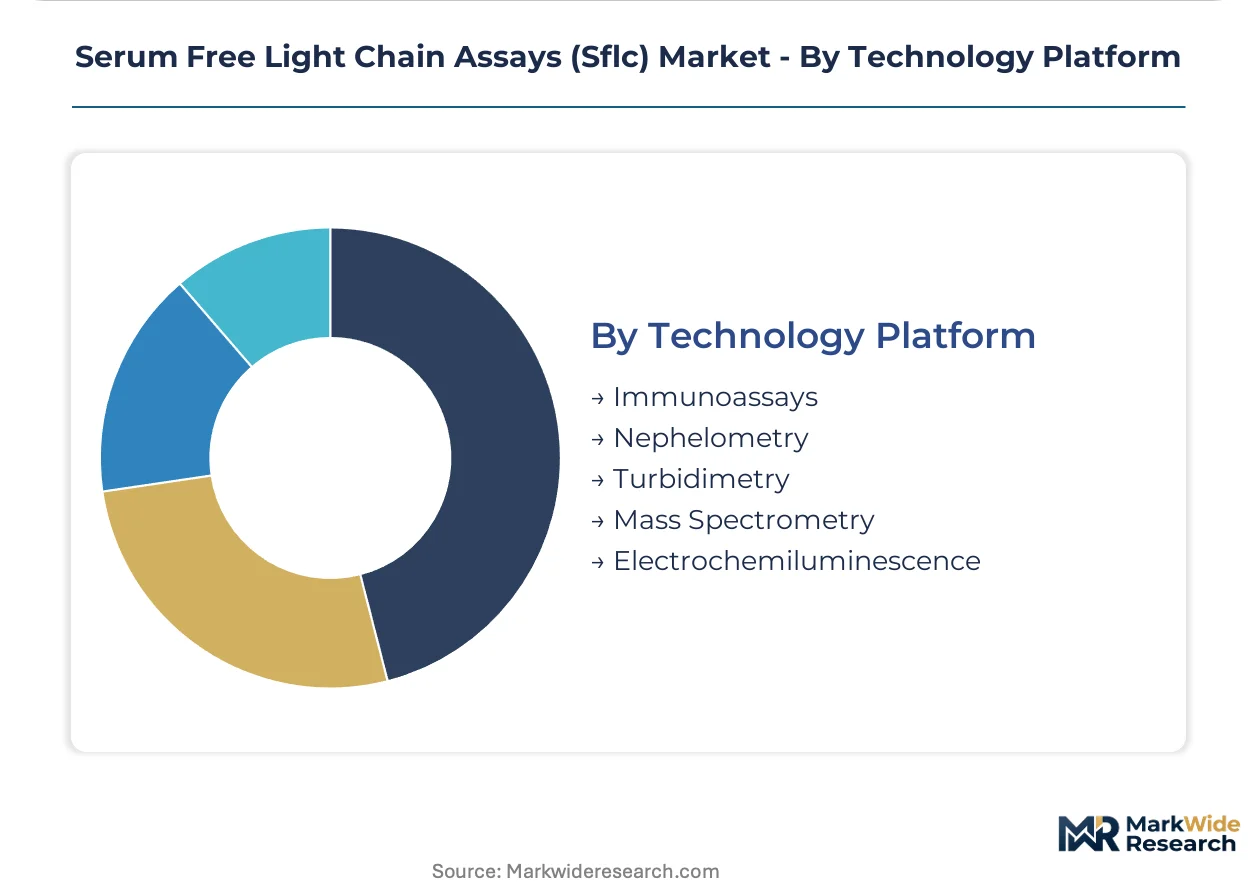
Technology Platform:
Established immunoassay methods face displacement from mass spectrometry in reference settings.
- Immunoassays:Enzyme-linked and chemiluminescent formats with polyclonal antibody detection. Installed base dominance persists in routine clinical laboratories constrained by capital budgets and staff familiarity. FDA 510(k) clearance pathways favor incremental platform improvements over disruptive replacements.
- Mass Spectrometry:LC-MS/MS workflows delivering orthogonal confirmation and improved analytical specificity. Reference laboratories in Germany and the United States are converging diagnostic and confirmatory testing into single analytical runs. EU IVDR technical documentation requirements favor manufacturers with established quality management systems.
- Nephelometry:Light scattering detection for high-sensitivity protein quantification.
- Turbidimetry:Turbidity measurement integrated with clinical chemistry analyzers.
- Electrochemiluminescence:High-dynamic-range detection for broad analytical measurement intervals.
Immunoassays hold installed-base dominance. Mass Spectrometry is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage pressures are shifting manufacturing capacity toward jurisdictions with streamlined conformity pathways and established notified body infrastructure. Kit suppliers facing EU IVDR compliance costs are relocating production to the United States and Switzerland while maintaining European distribution through authorized representatives.
United States
Hematology reference networks in Boston and Houston are expanding sFLC testing menus for monoclonal gammopathy screening. FDA 510(k) clearance modernization is compressing novel immunoassay platform timelines. The Southeast and Midwest regions concentrate procurement authority within integrated delivery networks negotiating centralized contracts.
Germany
University hospital consortia in Bavaria and North Rhine-Westphalia are standardizing diagnostic protocols across laboratory networks. EMA guidance on companion diagnostics is shaping assay validation requirements for plasma cell disorder monitoring. The Rhine-Main cluster anchors reagent manufacturing for European distribution.
Japan
Nephrology practices in the Kanto region are adopting sFLC ratio monitoring for dialysis patient management. PMDA consultation pathways for in vitro diagnostics are accelerating product registration for mass spectrometry platforms. Osaka-based reference laboratories are converging diagnostic and confirmatory workflows.
Switzerland
Swissmedic's alignment with EU IVDR technical documentation requirements is attracting reagent manufacturers seeking European market access without full EEA establishment. The Basel-Zurich corridor concentrates precision diagnostics manufacturing. Cantonal hospital networks are consolidating laboratory procurement under centralized tenders.
United Kingdom
NHS England's specialized commissioning frameworks are standardizing sFLC testing across cancer alliances. The MHRA's post-Brexit regulatory autonomy is creating divergence from EU IVDR implementation timelines. London and Manchester hematology centers are driving volume for automated turbidimetry systems.
Serum Free Light Chain Assays (Sflc) Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue mass spectrometry convergence and nephrology application expansion. The supplier base is compressing as EU IVDR conformity costs eliminate sub-scale kit manufacturers. Three archetypes dominate: integrated diagnostics conglomerates with installed-base leverage, specialized protein diagnostics firms with protocol entrenchment, and mass spectrometry platform vendors with reference laboratory relationships. Competitive moves concentrate on multi-year exclusive supply agreements and technology licensing for LC-MS/MS workflow integration.
Within the integrated diagnostics tier, Thermo Fisher Scientific and Siemens Healthineers exemplify scale-driven platform consolidation. The Binding Site occupies a position as a specialized protein diagnostics firm with entrenched monoclonal gammopathy testing protocols. Among emerging platform vendors, Sebia represents the electrophoresis-to-mass-spectrometry convergence archetype.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Sebia |
| Diazyme Laboratories |
| The Binding Site |
| Biomedical Diagnostics |
| Abingdon Health |
| Dr Lal PathLabs |
| KHB |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EU IVDR-compliant reagent kits and legacy immunoassay consumables manifests in both pricing power and supply chain configuration. Premium-grade manufacturers command pricing premiums through notified body certification while commodity-tier suppliers face margin compression from regulatory exit costs.
Pricing Analysis
Distributor margin layers in the United States absorb 15-25 points before hospital laboratory delivery. Three-tier pricing structure across premium, standard, and economy levels reflects analytical sensitivity thresholds and FDA 510(k) clearance status. Pricing pressure stems from integrated delivery network consolidation in the Southeast and Midwest, where centralized procurement squeezes vendor margins. Reference laboratories exhibit lowest price sensitivity due to reimbursement pass-through, while independent diagnostic laboratories face acute cost compression.
Supply Chain Analysis
Returns and lot-recall flows for expired polyclonal antisera concentrate reagent manufacturing risk in Western European supply nodes. Reagent production draws from antibody sourcing in Germany, the United Kingdom, and the Netherlands, with mass spectrometry platform assembly anchored in the United States and Switzerland. Single-source vulnerability concentrates in specialized polyclonal antiserum suppliers facing batch variability constraints. Distribution runs through authorized representatives for EU IVDR compliance, with direct hospital contracts dominating United States volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU IVDR compliance costs in Europe run 3-4x above FDA 510(k) pathway expenses in the United States, creating geographic-arbitrage incentives for reagent manufacturing relocation.
For Market Incumbents: To counter mass spectrometry platform displacement in reference laboratories, Siemens Healthineers and Thermo Fisher Scientific should deepen turbidimetry-chemiluminescence convergence on single analyzers. Securing multi-year exclusive supply agreements with German university hospital consortia locks in volume against emerging LC-MS/MS entrants. Certification investment in EU IVDR technical documentation preserves European market access as smaller kit suppliers exit. For New Entrants and Emerging Players: Launch via direct-to-reference-laboratory sales models targeting nephrology sFLC ratio monitoring in Japan's Kanto region dialysis networks. Chronic kidney disease monitoring represents the most penetrable application vertical outside saturated multiple myeloma screening. White-space capture requires mass spectrometry workflow integration partnerships with existing LC-MS/MS installed bases rather than capital equipment displacement. For Investors and Strategic Acquirers: Consolidation pressure builds where EU IVDR conformity assessment costs exceed 15% of annual revenue for sub-scale reagent manufacturers. Long-term viability favors specialized protein diagnostics firms with entrenched monoclonal gammopathy protocols and established notified body relationships. Acquisition target archetypes include mass spectrometry platform vendors with reference laboratory validation data. Monitor EU IVDR notified body capacity expansion as inflection signal for European market re-entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Technical Documentation Investment | Notified body certification preserves European Economic Area market access against competitor exits. |
| Mass Spectrometry Workflow Integration | LC-MS/MS convergence unifies diagnostic and confirmatory testing into single analytical runs. |
| Nephrology Application Expansion | Japan's dialysis patient management protocols create distinct revenue vertical outside oncology. |
| Integrated Delivery Network Central Contracts | Southeast and Midwest health system consolidation concentrates procurement authority. |
| Polyclonal Antiserum Supply Diversification | Western European antibody sourcing concentration exposes manufacturers to batch variability risk. |
Research Approach
Bottom-up diagnostic laboratory modeling reconciled against top-down reagent manufacturing tracking forms the analytical core of this study. Primary interviews with hematology reference network directors, nephrology practice administrators, clinical laboratory managers, and IVD regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, EU IVDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement contract registries. Triangulation across stakeholder perspectives and documentary sources ensures cross-verified demand and supply estimates.
Input-output matrices map reagent kit consumption to analyzer installed bases across product type, application area, technology platform, and end user segments. Modeled dimensions include immunoassay versus mass spectrometry technology trajectories, multiple myeloma versus chronic kidney disease application splits, and diagnostic laboratory versus research institute end-user concentrations. CAGRs derive from segment-level volume projections calibrated to regulatory approval timelines and reimbursement pathway developments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU IVDR notified body capacity constraints and polyclonal antiserum supply disruptions. Practitioners should monitor FDA 510(k) clearance modernization pace and Japanese PMDA mass spectrometry platform registrations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
Respiratory Pathogen Testing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market