
 Circulating Biomarkers Market | 2026-2036
Circulating Biomarkers Market Size, Share, and Industry Trends Forecast 2026-2036
Circulating Biomarkers Market Analysis
EU MDR and IVDR requirements for clinical evidence is hardening quality thresholds for in vitro diagnostic kits entering European laboratories. Thermo Fisher Scientific leverages its analytical instrument installed base to sustain revenue attachment rates in sequencing workflows. QIAGEN anchors its position through sample preparation automation that reduces manual variability in circulating nucleic acid extraction.
Circulating biomarkers comprise nucleic acids, proteins, and extracellular vesicles detectable in peripheral blood without invasive tissue sampling; these analytes typically require enrichment from plasma or serum matrices and detection sensitivity down to allelic frequencies below 0.1% for tumor-derived fractions. The technology dimension shows Next-Generation Sequencing commanding the largest installed base while Digital PCR captures margin pools in absolute quantification applications where regulatory submissions demand higher analytical precision. Protein Biomarkers retain the broadest reimbursement coverage among product types, though Circulating Tumor DNA claims the fastest expansion in oncology companion diagnostic contracts.
FDA oversees premarket approval and breakthrough device pathways for liquid biopsy assays in the United States, while EMA coordinates centralized marketing authorization for companion diagnostics across EU member states. China's NMPA has issued technical review guidelines for tumor mutation detection via cell-free DNA that align testing standards with international reference methods. Stakeholders must monitor evolving reimbursement decisions from national health technology assessment bodies, as coverage determinations for circulating biomarker tests increasingly determine commercial adoption velocity beyond regulatory clearance alone.
Market Dynamics
FDA breakthrough device designations and companion diagnostic pathways are compressing commercialization timelines for liquid biopsy developers while academic medical centers expand clinical oncology programs. This regulatory acceleration is restructuring competitive entry barriers and reshaping how diagnostic firms prioritize assay development pipelines.
Growth Catalysts
- Breakthrough Device Pathway:FDA's expedited review mechanism reduces time-to-market for novel circulating tumor DNA assays, attracting venture funding toward oncology liquid biopsy platforms.
- Academic Medical Center Expansion:Clinical oncology departments at major teaching hospitals are building dedicated liquid biopsy programs, creating institutional demand for standardized circulating nucleic acid workflows.
- Cell-Free DNA Guidelines:China's NMPA technical review standards align domestic testing with international reference methods, opening reimbursement pathways for ctDNA-based companion diagnostics.
Market Restraints
- EU IVDR Evidence Requirements:Hardening clinical evidence thresholds for in vitro diagnostic kits entering European laboratories extend certification timelines and raise development costs.
- Allelic Frequency Detection Limits:Technical constraints in detecting tumor-derived fractions below 0.1% sensitivity restrict assay utility in early-stage cancer screening applications.
- Reimbursement Uncertainty:National health technology assessment bodies in Germany and France issue inconsistent coverage determinations for circulating biomarker tests, creating adoption friction.
Strategic Opportunities
- Minimal Residual Disease Monitoring:Post-treatment surveillance applications for circulating tumor DNA remain underpenetrated in solid tumor oncology, offering expansion beyond companion diagnostics.
- Digital PCR Convergence:Absolute quantification capabilities from digital PCR platforms are integrating with next-generation sequencing workflows, creating hybrid analytical solutions for precision oncology.
- Sample Preparation Automation:Automated extraction systems for circulating nucleic acids reduce manual variability, opening clinical laboratory markets previously constrained by technician training gaps.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories face shortages of computational biologists capable of interpreting complex circulating biomarker data outputs and managing variant classification pipelines.
- Legacy LIMS Integration:Hospital information systems require costly middleware development to interface with cloud-based liquid biopsy reporting platforms, delaying deployment timelines.
- Multi-Site Analytical Validation:Circulating biomarker assays demand reproducibility studies across decentralized clinical trial networks, complicating regulatory submissions for multinational sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circulating Biomarkers Market |
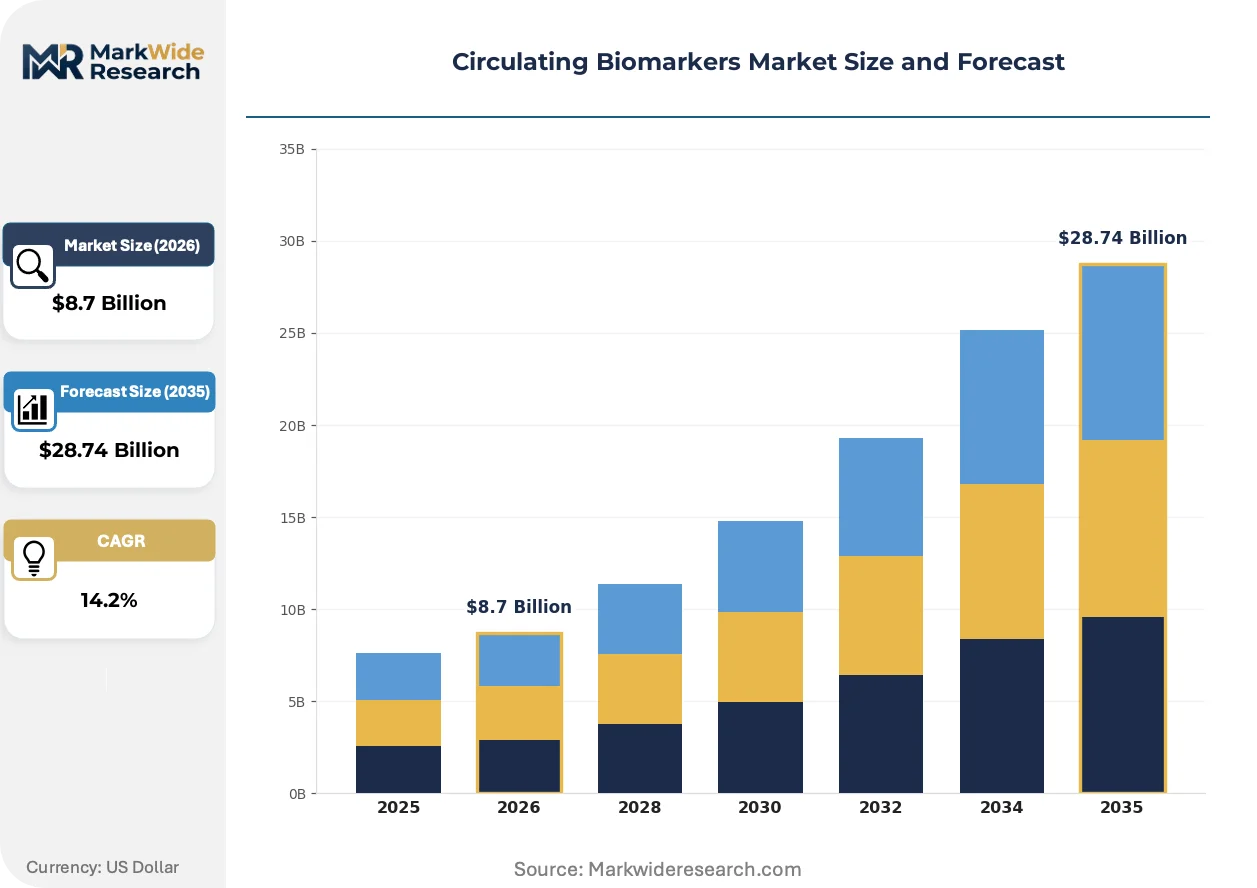
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circulating Tumor DNA, Exosomes, Cell-Free RNA, Protein Biomarkers Application: Oncology, Cardiovascular Disease, Infectious Diseases, Neurological Disorders Technology: Next-Generation Sequencing, Digital PCR, Mass Spectrometry, ELISA End User: Diagnostic Laboratories, Research Institutions, Hospitals, Biopharmaceutical Companies |
| Companies Covered | GE Healthcare, Agilent Technologies, Epigenomics AG, Fluxion Biosciences, Affymetrix, Guardant Health, QIAGEN, Thermo Fisher Scientific, Abbott Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circulating Biomarkers Market Emerging Trajectories
Liquid biopsy technologies are migrating from research use toward clinical standard-of-care, driven by automation advances and regulatory pathway maturation. Three developments are restructuring how circulating biomarkers enter routine oncology practice.
Microfluidic enrichment systems for circulating tumor cells and extracellular vesicles are automating sample preparation workflows previously requiring manual centrifugation and density gradient separation. High-throughput clinical laboratories at academic medical centers in the United States are adopting these platforms to process hundreds of plasma specimens daily. This automation is compressing turnaround times from days to hours while reducing technician-to-technician variability that plagued earlier circulating nucleic acid protocols.
EU MDR and IVDR requirements for clinical evidence are mandating prospective validation studies for in vitro diagnostic kits before European market entry. The regulation forces manufacturers to generate real-world performance data across diverse patient populations rather than relying on retrospective biobank samples. Oncology companion diagnostic firms are responding by embedding clinical utility studies within phase II/III therapeutic trials, using drug development timelines to satisfy regulatory evidence requirements.
Hospital procurement committees are consolidating vendor relationships for circulating biomarker testing around integrated platform providers rather than maintaining multiple point solutions. Academic medical center laboratories in Germany and China are favoring suppliers offering combined analytical instruments, reagent contracts, and bioinformatics support under single-source agreements. This concentration is squeezing specialized assay developers lacking full workflow capabilities and favoring firms with sequencing instrument installed bases.
Circulating Biomarkers Market Segmentation
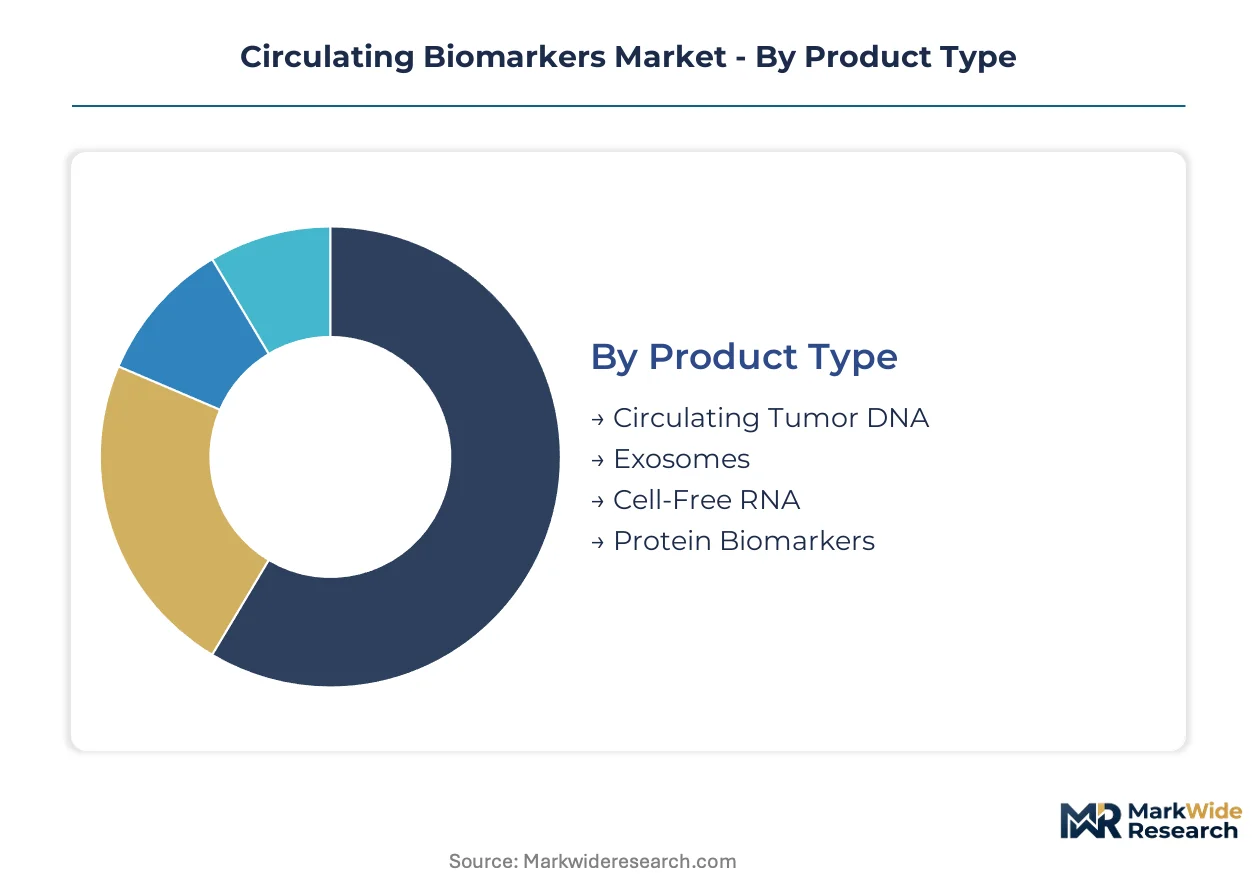
Segmentation in circulating biomarkers reveals how technology specifications, clinical applications, and customer workflows fragment commercial opportunity. Each axis carries distinct margin profiles, regulatory pathways, and vendor competitive dynamics that shape go-to-market strategy.
Product Type:
Technical composition determines extraction complexity, analytical sensitivity requirements, and reimbursement positioning across the four circulating analyte classes.
- Circulating Tumor DNA:Cell-free DNA fragments shed by tumor cells into plasma; detection demands sensitivity below 0.1% allelic frequency for early-stage monitoring. Academic medical centers in the United States are consolidating liquid biopsy programs around ctDNA workflows for companion diagnostic contracts.
- Protein Biomarkers:Established analyte class with broadest reimbursement coverage across Medicare and commercial payers. Clinical laboratories in Germany favor protein assays for cardiovascular risk stratification where regulatory evidence requirements are well-established.
- Exosomes:Membrane-bound extracellular vesicles carrying nucleic acids and proteins; microfluidic enrichment systems are automating isolation workflows previously requiring manual ultracentrifugation.
- Cell-Free RNA:Transcriptomic signatures in plasma reflect real-time gene expression; technical instability complicates clinical validation for routine diagnostic deployment.
Protein Biomarkers leads on scale; Circulating Tumor DNA leads on momentum.
Application:
Clinical utility and regulatory maturity vary sharply across disease areas, with oncology commanding development investment while cardiovascular applications leverage existing infrastructure.
- Oncology:Companion diagnostic contracts and minimal residual disease surveillance drive the deepest pipeline investment. FDA breakthrough device designations are compressing timelines for liquid biopsy assays in solid tumor monitoring.
- Cardiovascular Disease:Troponin and natriuretic peptide assays anchor established reimbursement; hospital laboratories in China are expanding high-sensitivity cardiac biomarker menus under NMPA technical review guidelines.
- Infectious Diseases:Cell-free pathogen DNA detection enables non-invasive sepsis and transplant monitoring; COVID-19 emergency use authorizations accelerated platform validation for viral load quantification.
- Neurological Disorders:Blood-based biomarkers for Alzheimer's disease face analytical sensitivity challenges; EMA centralized pathways are requiring prospective validation studies for neurodegenerative diagnostic claims.
Oncology commands development resources; Cardiovascular Disease offers the clearest reimbursement path.
Technology:
Detection platform selection locks laboratories into instrument ecosystems, reagent supply contracts, and bioinformatics dependencies that persist for capital depreciation cycles.
- Next-Generation Sequencing:Dominant installed base for comprehensive genomic profiling; sequencing instrument vendors capture recurring revenue through consumable pull-through in high-throughput clinical laboratories.
- Digital PCR:Absolute quantification without standard curves satisfies regulatory submissions demanding higher analytical precision; margin pools concentrate in companion diagnostic validation workflows.
- Mass Spectrometry:Proteomics and metabolomics applications require specialized operator training; academic medical centers deploy LC-MS/MS for multiplex protein quantification where ELISA panels prove insufficient.
- ELISA:Enzyme-linked immunosorbent assay retains lowest cost-per-test for high-volume protein biomarker screening; manual workflows face displacement from automated chemiluminescence platforms.
Next-Generation Sequencing anchors installed capacity; Digital PCR captures premium pricing in regulated applications.
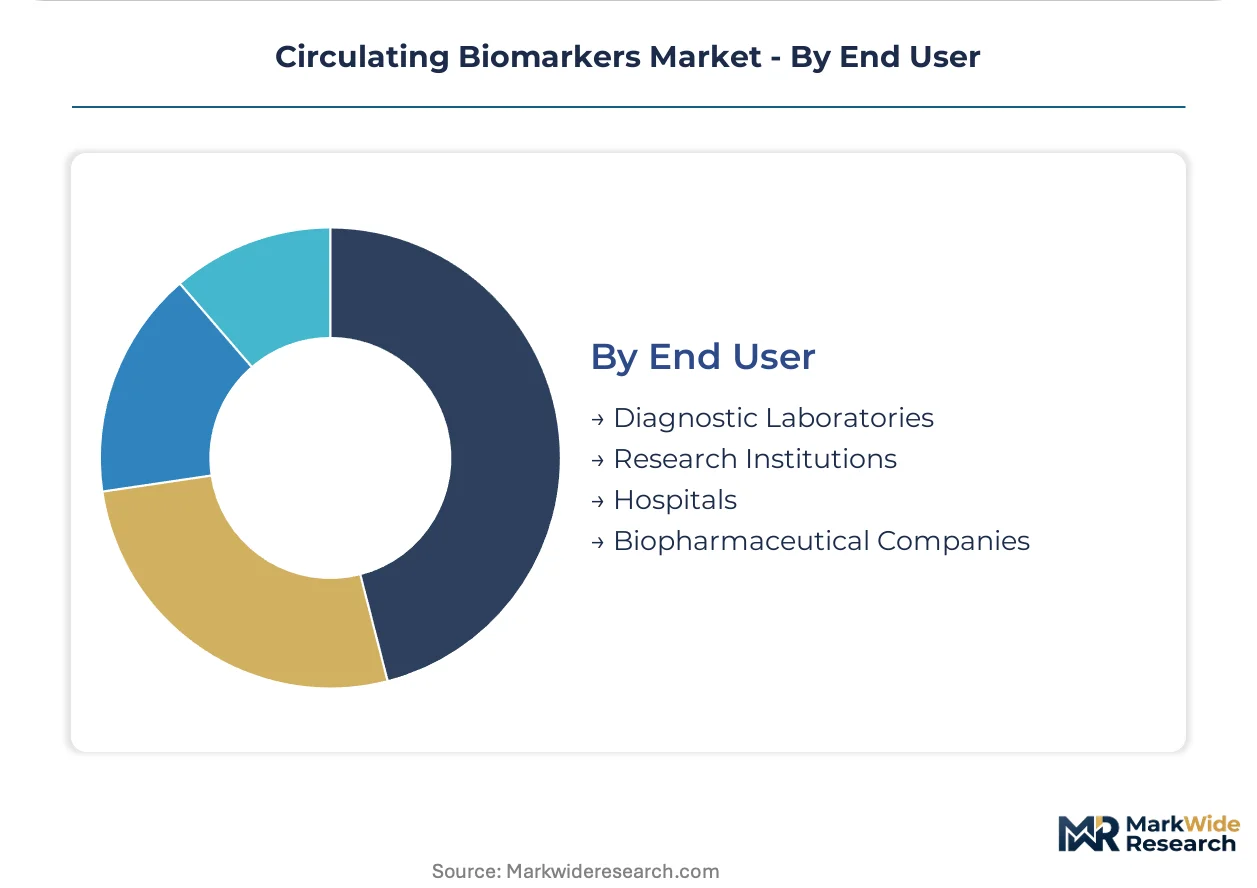
End User:
Customer type dictates purchasing authority, integration complexity, and service requirements that segment vendor go-to-market economics.
- Diagnostic Laboratories:High-throughput processors of reference testing; centralized labs in the United States are consolidating vendor relationships around integrated platform providers offering combined instruments, reagents, and bioinformatics.
- Hospitals:Point-of-care deployment demands rapid turnaround; procurement committees favor single-source agreements reducing middleware development costs for LIMS integration.
- Research Institutions:Early technology adoption with flexible validation requirements; academic laboratories drive protocol optimization before clinical translation.
- Biopharmaceutical Companies:Companion diagnostic co-development partners; sponsors embed circulating biomarker studies within phase II/III therapeutic trials to satisfy regulatory evidence requirements.
Diagnostic Laboratories concentrate testing volume; Biopharmaceutical Companies shape technology roadmaps through co-development investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Liquid biopsy technology originated in United States academic medical centers during the early 2010s, with clinical validation programs subsequently scaling across Germany and China as regulatory pathways matured in each jurisdiction.
United States
FDA breakthrough device designations accelerate commercialization timelines for circulating tumor DNA assays, compressing review periods for oncology liquid biopsy platforms. Academic medical centers in Boston and Houston are consolidating vendor relationships around integrated sequencing workflows. The clinical laboratory market concentrates testing volume in high-throughput reference processors seeking single-source agreements.
China
NMPA technical review guidelines for cell-free DNA testing align domestic standards with international reference methods, opening reimbursement pathways for companion diagnostics. Hospital procurement committees in Shanghai and Beijing favor suppliers offering combined instruments and bioinformatics support. The regulatory clarity is attracting venture funding toward local assay developers.
Germany
EMA centralized marketing authorization requirements for companion diagnostics mandate prospective validation studies across diverse patient populations. Clinical laboratories in Munich and Heidelberg are expanding high-sensitivity cardiac biomarker menus under established protein assay reimbursement. The country's health technology assessment bodies issue coverage determinations that shape adoption velocity for novel circulating biomarker tests.
Japan
PMDA marketing authorization pathways for in vitro diagnostics require analytical validation demonstrating detection sensitivity below 0.1% allelic frequency for tumor-derived fractions. Research institutions in Tokyo and Osaka are driving protocol optimization for extracellular vesicle isolation workflows. The regulatory framework favors manufacturers embedding clinical utility studies within therapeutic trial timelines.
United Kingdom
NICE technology appraisals determine reimbursement access for circulating biomarker tests within the National Health Service, creating adoption friction where evidence thresholds remain unmet. Clinical oncology departments in London and Cambridge are building dedicated liquid biopsy programs for minimal residual disease surveillance. The procurement environment favors integrated platform providers reducing middleware development costs for hospital information systems.
Circulating Biomarkers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology platform and service integration dimensions. The vendor base clusters around three strategic archetypes: analytical instrument manufacturers capturing recurring consumable revenue, sample preparation specialists automating extraction workflows, and assay developers securing companion diagnostic co-development contracts. Consolidation pressure favors firms with sequencing instrument installed bases, while specialized developers face squeeze from hospital procurement committees seeking full workflow capabilities. Competitive moves concentrate on strategic partnerships for bioinformatics integration and vertical control over reagent supply chains.
Among analytical instrument manufacturers, Thermo Fisher Scientific and QIAGEN occupy positions anchoring the premium tier through combined hardware and reagent offerings. Guardant Health exemplifies the assay developer archetype focused on oncology liquid biopsy commercialization. These three firms represent distinct competitive vectors: installed base leverage, sample preparation automation, and companion diagnostic specialization respectively.
| Leading Market Players |
|---|
| GE Healthcare |
| Agilent Technologies |
| Epigenomics AG |
| Fluxion Biosciences |
| Affymetrix |
| Guardant Health |
| QIAGEN |
| Thermo Fisher Scientific |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
Microfluidic automation in sample preparation is compressing per-test costs while concentrating supplier power among integrated platform vendors who control both consumable supply and bioinformatics lock-in. This technology transition simultaneously reduces manual labor overhead and raises switching costs for clinical laboratories locked into proprietary extraction chemistries.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the circulating biomarkers market, with differentiation driven by FDA breakthrough device certification status and bioinformatics bundling depth. Cost compression in economy-tier ELISA workflows is intensifying because hospital procurement committees are consolidating vendor relationships. Academic medical centers in the United States show the least price sensitivity due to companion diagnostic co-development revenue offsets, while independent reference laboratories in Germany face the highest price sensitivity from health technology assessment coverage uncertainty.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and China form hub-and-spoke patterns that feed clinical laboratory networks with temperature-controlled plasma processing reagents. Supply draws from specialized enzyme manufacturers in Switzerland, semiconductor fabrication for digital PCR chips in Taiwan, and synthetic oligonucleotide producers in South Korea. Single-source vulnerability in rare-earth magnetic bead supply creates chokepoint risk for automated nucleic acid extraction systems. Distribution runs through GPO-negotiated contracts in hospital systems and direct-to-laboratory channels in academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The circulating biomarkers market functions as a regulatory compounder where FDA breakthrough device designations and EMA centralized pathways for companion diagnostics continuously validate demand expansion. Each regulatory milestone accelerates reimbursement negotiations and institutional procurement cycles.
For Market Incumbents: Cement installed base leverage by embedding clinical utility studies within phase II/III therapeutic trials, securing multi-year reagent supply contracts that raise switching costs for hospital laboratories. Threats from emerging sample preparation automation specialists require backward integration into proprietary extraction chemistries to defend margin pools in high-sensitivity ctDNA workflows. For New Entrants and Emerging Players: Mid-tier diagnostic laboratories in China's provincial hospital networks represent an underserved buyer archetype with unconsolidated vendor relationships and limited bioinformatics capabilities. White-space targets include minimal residual disease surveillance in solid tumor oncology and automated exosome isolation workflows for transplant monitoring. A service-first go-to-market angle bundling instrument placement with technician training programs lowers capital barriers to entry. For Investors and Strategic Acquirers: Valuations sit cheapest among sample preparation automation specialists lacking full workflow integration but commanding proprietary microfluidic IP. Long-term viability hinges on regulatory pathway maturation across the analysis window, with acquisition targets clustering around digital PCR platform developers and bioinformatics pipeline vendors. The signal to watch is NMPA reimbursement pathway expansion for ctDNA-based companion diagnostics in China, which would validate international standard alignment and trigger institutional capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Expedited review compresses commercialization timelines for novel liquid biopsy assays in oncology monitoring. |
| CE Marking Pathway under IVDR | Prospective clinical evidence requirements harden entry barriers for European laboratory market access. |
| Hospital System Partnership | Single-source agreements reduce middleware development costs for LIMS integration in academic medical centers. |
| Software Companion Development | Cloud-based variant classification pipelines address bioinformatics talent scarcity in clinical laboratories. |
| Reimbursement Strategy | Coverage determinations from Germany's G-BA and France's HAS shape adoption velocity beyond regulatory clearance. |
Methodological Framework
Bottom-up clinical laboratory demand modeling reconciled against top-down instrument manufacturer shipment tracking forms the analytical core of this study. Primary interviews with diagnostic laboratory directors, hospital procurement managers, regulatory affairs specialists at assay developers, and companion diagnostic co-development leads at biopharmaceutical sponsors were cross-validated against FDA 510(k) and breakthrough device filings, EMA centralized marketing authorization submissions, NMPA technical review guidelines, hospital GPO contract databases, and academic medical center liquid biopsy program expansion announcements.
Input-output matrix framing connects installed base expansion in sequencing and digital PCR platforms to consumable pull-through rates across product type, application, technology, and end user segments. The projection horizon spans technology adoption curves, regulatory pathway maturation, and reimbursement coverage expansion patterns. CAGRs were derived from segment-level volume and value build-ups calibrated to instrument placement data and reagent contract values. Industry-specific forecast inputs include companion diagnostic co-development pipeline density and health technology assessment body coverage determination timelines.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-world clinical utility study completion rates introduce uncertainty bands around adoption velocity assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Global Cardiac Biomarkers Testing Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Antenatal Screening Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Lab Automation in Clinical Diagnostics Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
Global Respiratory Disease Testing Market
Clinical Diagnostics
Global Minimal Residual Disease Market