
 US Clinical Chemistry Analyzer Market | 2026-2036
US Clinical Chemistry Analyzer Market Size, Share, and Industry Trends Forecast 2026-2036
US Clinical Chemistry Analyzer Market Analytics
Direct distribution to hospital networks is reshaping how manufacturers allocate field service engineers and reagent supply contracts. Siemens Healthineers leverages its embedded installed base to sustain long-term consumable revenue streams. Danaher Corporation anchors its position through backward integration into reagent chemistry and consumables. Abbott Laboratories differentiates with point-of-care connectivity that bridges core lab and decentralized testing workflows.
Clinical chemistry analyzers are automated instruments that quantitatively measure chemical constituents in biological fluids using photometric, potentiometric, or enzymatic detection methods, typically processing 200 to 2,000 tests per hour with sample volumes of 2 to 50 microliters. These systems serve as the analytical backbone for routine diagnostic panels including metabolic profiles, liver function tests, and therapeutic drug monitoring. Fully automated systems command the largest revenue share due to labor cost savings and error reduction in high-volume settings, while modular configurations represent the fastest-growing segment as laboratories seek incremental capacity expansion without full platform replacement. Immunoassay technology integration into chemistry platforms is expanding test menus and capturing margin pools previously isolated to standalone analyzers.
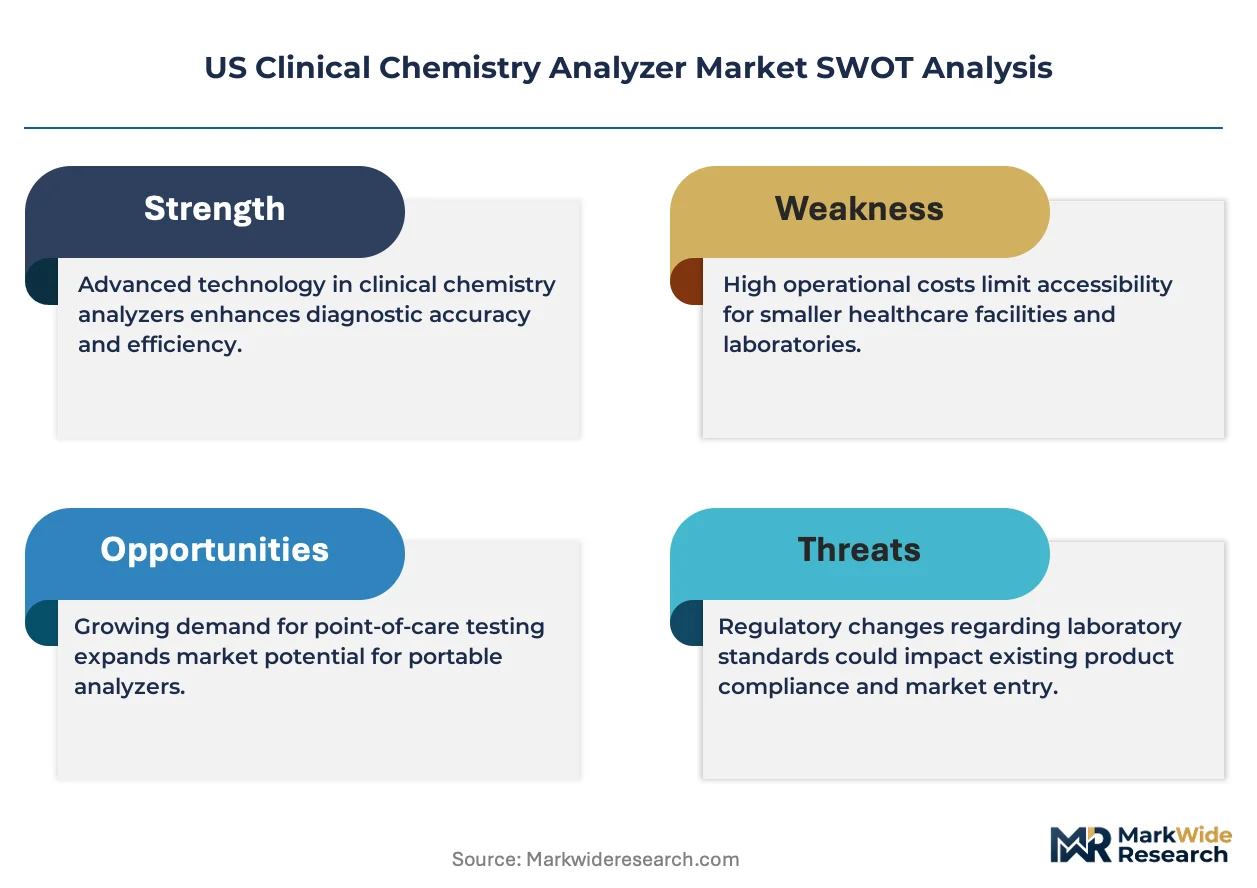
FDA 510(k) clearance requirements and CLIA complexity classifications determine which instruments qualify for moderate versus high-complexity laboratory deployment, directly constraining addressable market scope for each product tier. CAP laboratory accreditation standards and OSHA bloodborne pathogen regulations further shape instrument design specifications, biosafety features, and quality control protocols. Stakeholders must monitor evolving FDA guidance on artificial intelligence-enabled result interpretation and state-level laboratory licensing harmonization as these frameworks will determine next-generation product qualification timelines and competitive positioning.
Market Dynamics
Hospital laboratory consolidation across Texas, California, and Florida is concentrating purchasing power into fewer procurement centers, forcing manufacturers to restructure field service networks and reagent supply contracts around multi-site health system agreements rather than individual facility sales.
Growth Catalysts
- CLIA Moderate Complexity Waivers:FDA clearance pathways for waived testing expand placement of compact analyzers in physician office laboratories and urgent care settings previously restricted to high-complexity facilities.
- Therapeutic Drug Monitoring Expansion:Precision oncology and biologic therapy protocols require frequent blood-level quantification, driving repeat test volume in hospital chemistry departments.
- Enzymatic Detection Methods:Advanced substrate-specific chemistry reduces interference from hemolysis and lipemia, improving result reliability in emergency department stat testing workflows.
Market Restraints
- Reagent Supply Concentration:Proprietary consumable lock-in from dominant installed base manufacturers limits third-party reagent substitution and elevates lifetime cost of ownership.
- Capital Equipment Replacement Cycles:Seven-to-ten-year depreciation schedules for existing chemistry platforms delay upgrade decisions even when throughput demands exceed current capacity.
- CMS Reimbursement Compression:Clinical Laboratory Fee Schedule reductions compress revenue per test, constraining capital allocation for analyzer procurement in independent reference laboratories.
Strategic Opportunities
- AI-Enabled Result Interpretation:FDA draft guidance on machine learning-based flagging systems creates pathway for differentiation through automated anomaly detection and predictive maintenance alerts.
- Modular Incremental Capacity:Add-on analytical modules allow satellite laboratories to expand test menus without full platform replacement, capturing margin from immunoassay integration.
- Point-of-Care Connectivity Bridges:Bidirectional data flow between core lab analyzers and decentralized testing devices supports integrated clinical decision support across health system networks.
Industry Challenges
- Medical Laboratory Scientist Shortage:ASCP certification pipeline constraints limit staffing for high-complexity testing operations, forcing automation investment ahead of optimal replacement timing.
- Legacy LIS Integration Complexity:Proprietary data formats from aging laboratory information systems impede seamless connectivity with next-generation chemistry platforms requiring HL7 FHIR compatibility.
- CAP Accreditation Timeline Pressure:Biennial inspection preparation and proficiency testing documentation demands divert technical staff attention from operational efficiency initiatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Clinical Chemistry Analyzer Market |
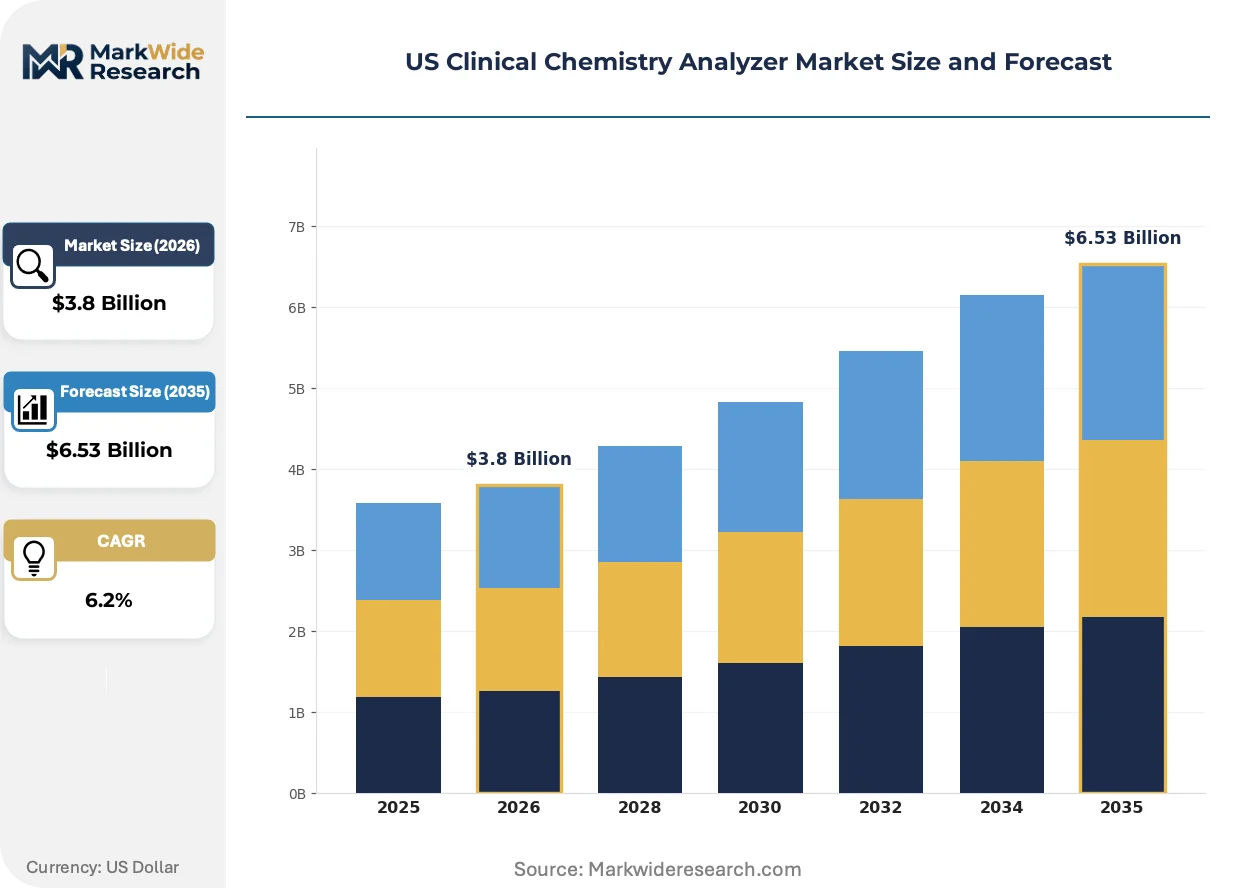
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bench-top, Portable, Modular, Fully Automated Technology: Colorimetric, Fluorescence, Enzymatic, Immunoassay End User: Hospitals, Diagnostic Laboratories, Research Institutes, Clinics Application: Metabolic Disorders, Infectious Diseases, Oncology, Cardiology |
| Companies Covered | Siemens Healthineers, Abbott Laboratories, F. Hoffmann-La Roche Ltd, QuidelOrtho, Danaher Corporation, Thermo Fisher Scientific Inc, ELITechGroup, Horiba Ltd, Mindray Medical International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Clinical Chemistry Analyzer Market Evolving Landscape
Cloud-native instrument architecture is displacing on-premise data management, enabling remote calibration verification and predictive maintenance while reducing laboratory IT infrastructure burden. This shift reconfigures how manufacturers monetize after-sale relationships.
Random-access chemistry analyzers with discrete sample handling are virtualizing traditional batch processing workflows, allowing stat samples to interrupt routine runs without workflow disruption. Academic medical centers in the Northeast and Midwest are deploying these systems to reduce emergency department turnaround times. The technology is virtualizing the historical trade-off between throughput and flexibility that constrained mid-volume laboratory design.
FDA guidance on artificial intelligence-enabled medical devices is tightening validation requirements for algorithm-assisted result interpretation, extending 510(k) review timelines for next-generation chemistry platforms. Manufacturers must now submit clinical performance data across diverse patient populations. Systems targeting oncology therapeutic monitoring face the steepest compliance burden due to narrow therapeutic index implications.
Consolidated procurement by multi-hospital health systems is compressing vendor negotiation cycles from annual to multi-year enterprise agreements. Group purchasing organizations are centralizing chemistry analyzer selection decisions for member institutions. This concentration is most pronounced in Florida and Texas where private equity-backed health system rollups have accelerated since 2022.
US Clinical Chemistry Analyzer Market Segmentation
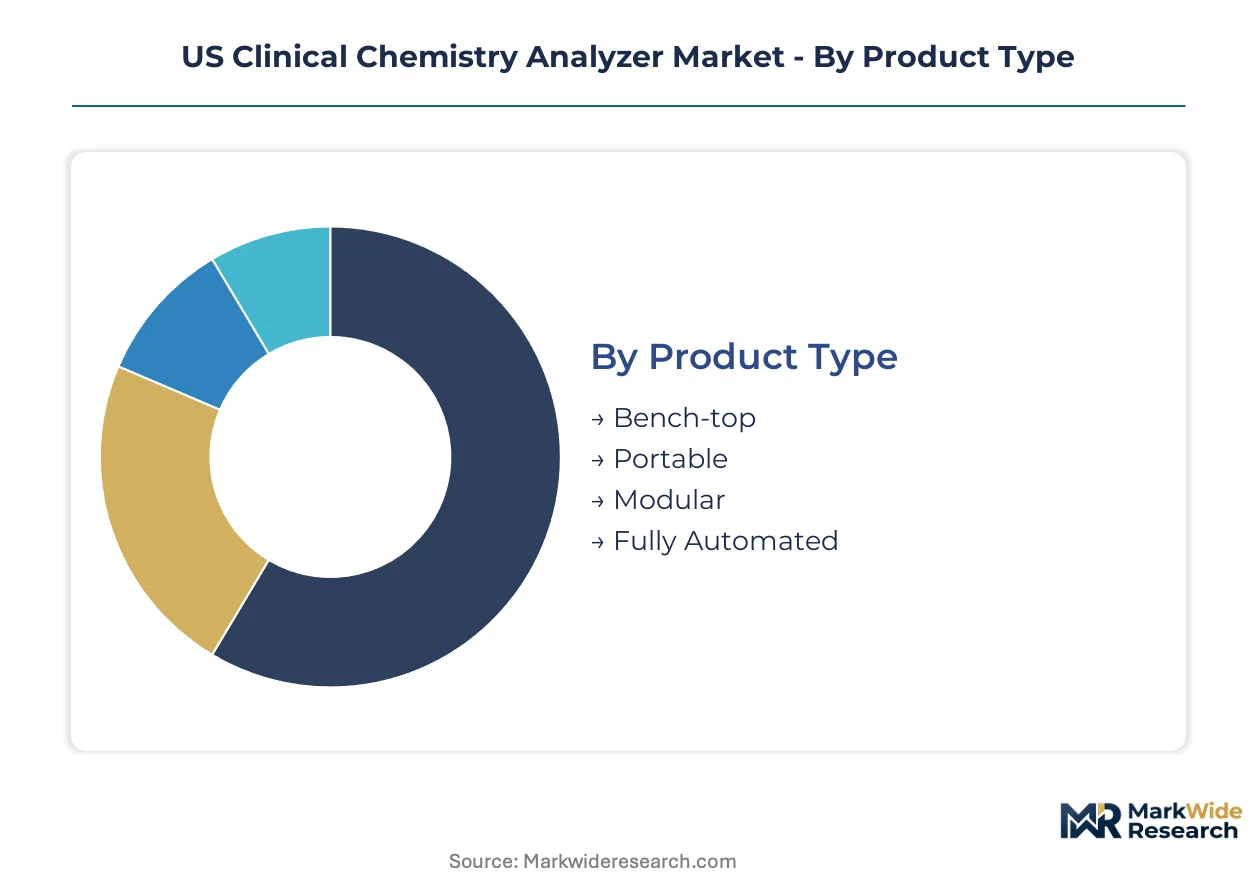
Segmentation in the US Clinical Chemistry Analyzer Market reveals how purchasing decisions split across automation intensity, detection methodology, and care setting economics. Manufacturers must align product development with these distinct demand profiles to secure placement in consolidated health system procurement cycles.
Product Type:
Automation intensity spans from decentralized point-of-care devices to high-throughput core laboratory systems, with each tier serving distinct specimen volumes and staffing constraints.
- Fully Automated:Integrated sample handling, reagent management, and result reporting eliminate manual intervention for routine panels. Hospital laboratories in Texas and California health systems prioritize these systems to offset Medical Laboratory Scientist shortages through reduced hands-on time.
- Modular:Add-on analytical units attach to existing platforms, expanding test menus without full replacement cycles. Satellite laboratories within Florida multi-site networks deploy these configurations to add immunoassay capability incrementally.
- Bench-top:Compact footprint suits physician office laboratories with moderate complexity CLIA waivers. Urgent care chains in suburban markets favor these units for rapid metabolic panels.
- Portable:Battery-operated systems enable testing at bedside or in mobile health units. Rural critical access hospitals deploy these for stat chemistry when core lab transport delays exceed clinical tolerance.
The dominant share belongs to Fully Automated systems, while Modular configurations are closing the gap fastest.
Technology:
Detection methodology selection determines interference resistance, sensitivity thresholds, and reagent cost structures across testing workflows.
- Enzymatic:Substrate-specific reactions reduce hemolysis and lipemia interference in emergency department stat testing. Academic medical centers in the Northeast deploy these methods for reliable potassium and lactate measurements.
- Immunoassay:Antibody-based quantification enables therapeutic drug monitoring and tumor marker detection. Precision oncology protocols in California cancer centers drive repeat test volume for monoclonal antibody level tracking.
- Colorimetric:Photometric absorbance measurement remains the workhorse for liver function panels and basic metabolic profiles. Independent reference laboratories favor these methods for cost-efficient high-volume screening.
- Fluorescence:Enhanced sensitivity supports trace analyte detection in neonatal and research applications. Specialized children's hospitals utilize these systems for metabolic disorder newborn screening programs.
Enzymatic methods command the largest installed base, though Immunoassay integration into chemistry platforms is climbing the fastest.
End User:
Site-of-care economics and regulatory complexity stratify demand across institutional categories with divergent capital allocation timelines.
- Hospitals:Inpatient and emergency department volumes drive 24/7 operational requirements. Consolidated health systems in Florida negotiate multi-year enterprise agreements covering chemistry analyzer standardization across acquired facilities.
- Diagnostic Laboratories:Independent reference labs and hospital outreach programs compete on turnaround time and test menu breadth. CMS Clinical Laboratory Fee Schedule compression constrains capital replacement cycles in this segment.
- Clinics:Physician office laboratories with CLIA moderate complexity waivers seek compact systems with simplified quality control. Urgent care expansion in Texas suburban corridors expands addressable placement for these units.
- Research Institutes:Custom assay development and biomarker discovery require flexible open-architecture platforms. NIH-funded academic centers prioritize systems with programmable reaction conditions.
Hospitals retain the dominant procurement volume, while Clinics are expanding placement most rapidly through waived testing pathways.
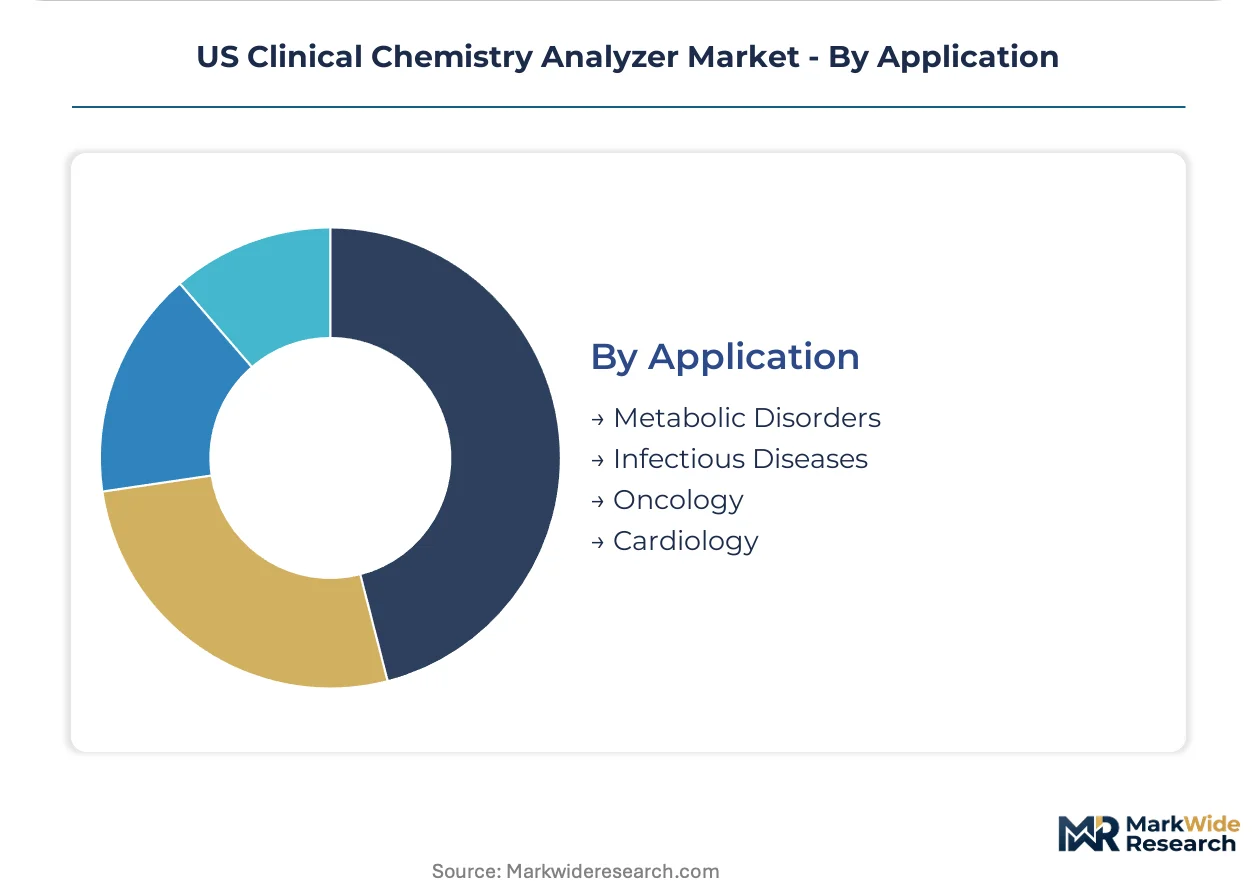
Application:
Clinical indication priority shapes test menu configuration and reagent panel economics across analyzer deployments.
- Metabolic Disorders:Glucose, HbA1c, and lipid panels constitute the highest-frequency testing category. Diabetes prevalence in Florida and Texas drives continuous demand for these routine panels.
- Oncology:Therapeutic drug monitoring for biologics and chemotherapy agents requires precise quantification at narrow therapeutic indices. California cancer centers generate repeat volume for monoclonal antibody pharmacokinetic tracking.
- Cardiology:Troponin, BNP, and lipid panels support emergency department chest pain protocols. Northeast academic medical centers prioritize rapid turnaround for these assays.
- Infectious Diseases:C-reactive protein and procalcitonin guide antibiotic stewardship decisions. Hospital laboratories integrate these markers into sepsis screening protocols.
Metabolic Disorders testing commands the largest test volume, though Oncology applications are gaining share fastest through precision therapy expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Purchasing power in Texas and Florida health systems commands steeper discount structures than independent laboratories in the Northeast corridor. This pricing asymmetry reflects consolidation velocity and procurement centralization rather than underlying technology differentiation.
Texas
Private equity-backed health system rollups in Dallas-Fort Worth and Houston concentrate laboratory procurement into multi-year enterprise agreements. FDA 510(k) clearance timelines for new chemistry platforms factor prominently in capital planning cycles across these networks. The Texas Medical Center in Houston anchors one of the nation's densest clusters of high-throughput automated testing lines.
California
Precision oncology protocols at Los Angeles and San Francisco cancer centers drive repeat therapeutic drug monitoring volume for monoclonal antibody tracking. CLIA high-complexity laboratory licensing requirements shape staffing models and automation investment priorities. The Stanford-Berkeley corridor hosts research institutes demanding open-architecture platforms for biomarker discovery workflows.
Florida
Diabetes prevalence and aging demographics sustain continuous demand for metabolic panel testing throughout the Tampa-Orlando-Miami corridor. CMS Clinical Laboratory Fee Schedule reductions compress margins for independent reference laboratories competing with hospital outreach programs. Health system consolidation since 2022 has centralized chemistry analyzer selection decisions through group purchasing organization contracts.
Northeast Corridor
Academic medical centers in Boston and New York prioritize random-access chemistry analyzers to reduce emergency department turnaround times. CAP accreditation standards and biennial inspection preparation divert technical staff attention from operational efficiency initiatives. The Philadelphia-Baltimore corridor maintains significant independent laboratory capacity serving regional hospital networks.
Midwest
Rural critical access hospitals across Illinois and Ohio deploy portable chemistry systems for stat testing when core lab transport delays exceed clinical tolerance. Medical Laboratory Scientist shortages documented by ASCP certification pipeline constraints force automation investment ahead of optimal replacement timing. The Cleveland Clinic health system anchors standardized instrument platforms across its multi-state network.
US Clinical Chemistry Analyzer Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in reagent and consumable supply. The vendor base organizes around three strategic archetypes: diversified conglomerates with embedded installed bases, mid-scale specialists with backward integration into chemistry, and point-of-care connectivity vendors bridging core lab and decentralized workflows. Consolidated procurement by multi-hospital health systems compresses negotiation cycles and elevates importance of long-term consumable revenue streams. Competitive positioning depends on field service network density and reagent supply contract structures rather than instrument differentiation alone.
Among diversified health technology conglomerates, Siemens Healthineers and Danaher Corporation exemplify contrasting approaches to sustaining market position. Siemens Healthineers leverages its embedded installed base to anchor long-term consumable revenue streams across consolidated health system networks. Danaher Corporation occupies a position defined by backward integration into reagent chemistry and captive supply of consumables. Abbott Laboratories represents the point-of-care connectivity archetype, with instrument interfaces designed to bridge core laboratory and decentralized testing workflows.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| QuidelOrtho |
| Danaher Corporation |
| Thermo Fisher Scientific Inc |
| ELITechGroup |
| Horiba Ltd |
| Mindray Medical International |
| Others |
Value Network & Pricing Analysis
The Texas Medical Center cluster in Houston anchors domestic reagent manufacturing capacity, concentrating supply leverage among incumbent manufacturers who command premium pricing for proprietary consumable contracts tied to multi-year health system agreements.
Pricing Analysis
The customization-premium spread separates configured-to-order modular systems from standard bench-top configurations, with pricing stratifying across premium, standard, and economy tiers based on throughput capacity and CLIA complexity classification. Brand premiums attach to FDA 510(k) clearance timelines and embedded service network density, while volume scale discounts concentrate in consolidated procurement by Florida and Texas health systems. Cost compression in the independent reference laboratory tier intensifies because CMS Clinical Laboratory Fee Schedule reductions constrain capital allocation. Physician office laboratories with moderate complexity waivers exhibit highest price sensitivity; academic medical centers with precision oncology protocols show lowest sensitivity due to therapeutic drug monitoring revenue per test.
Supply Chain Analysis
Upstream feedstock for enzymatic reagents draws from specialized chemical manufacturers concentrated in Germany, Switzerland, and the United States, with optical components for photometric detection resting on Japanese and German precision engineering supply chains. Critical dependencies include substrate-grade enzymes, interference-resistant chromogens, and solid-state photodetectors. Single-source vulnerability concentrates in proprietary reagent formulations locked to specific analyzer platforms, creating lifetime cost escalation for health systems. Distribution runs through direct manufacturer-to-health-system contracts for high-throughput systems, with group purchasing organizations centralizing procurement decisions for member institutions across Florida and Texas networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical Laboratory Scientist certification pipeline constraints create acute capability scarcity, forcing automation investment ahead of optimal replacement timing and reshaping competitive advantage toward service network density over instrument differentiation.
For Market Incumbents: Entrench installed base positions through backward integration into reagent chemistry and predictive maintenance service contracts that extend replacement cycles. Threat from point-of-care connectivity vendors bridging core lab and decentralized workflows demands counterinvestment in bidirectional data architecture. Priority lever: field service engineer density in Texas and Florida health system corridors. For New Entrants and Emerging Players: Rural critical access hospitals in the Midwest present underpenetrated placement opportunity for portable battery-operated systems addressing stat testing gaps. CLIA moderate complexity waiver expansion in urgent care chains offers fastest addressable growth. Go-to-market angle: simplified quality control interfaces reducing Medical Laboratory Scientist dependency. For Investors and Strategic Acquirers: Long-term, this sits as a consumable-recurring-revenue play because proprietary reagent lock-in generates predictable cash flows decoupled from capital equipment replacement volatility. Target acquisition archetype: mid-scale specialists with captive reagent chemistry and GPO contract access. Signal to watch: FDA draft guidance finalization on artificial intelligence-enabled result interpretation creating qualification timeline inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Chemistry Backward Integration | Captive consumable supply secures margin pools against third-party substitution threats in consolidated procurement environments. |
| CLIA Moderate Complexity Waiver Expansion | FDA clearance pathway unlocks physician office laboratory placement previously restricted to high-complexity facility networks. |
| Random-Access Analyzer Deployment | Discrete sample handling technology reduces emergency department turnaround times at Northeast academic medical centers. |
| Cloud-Native Instrument Architecture | Remote calibration verification shifts after-sale monetization from service contracts to subscription-based predictive maintenance. |
| Health System Enterprise Agreement Consolidation | Multi-year procurement centralization in Florida and Texas compresses vendor negotiation cycles and elevates consumable contract importance. |
Research Methodology
A standing panel of hospital laboratory directors, GPO contracts managers, biomedical engineers, and FDA regulatory affairs specialists provided ongoing calibration against market developments, with primary interview findings triangulated against secondary sources including FDA 510(k) clearance databases, CMS Clinical Laboratory Fee Schedule publications, CAP laboratory accreditation records, and health system procurement disclosures. Bottom-up demand modeling across analyzer placements and reagent consumption patterns converged with top-down market sizing through manufacturer revenue segmentation.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning automation intensity, detection methodology, end-user site-of-care economics, and application-specific test menu configuration. CAGRs derived from instrument replacement cycle analysis, reagent consumption per installed unit, and health system consolidation velocity. Forecast inputs incorporated CLIA waiver expansion trajectories and therapeutic drug monitoring protocol adoption in precision oncology centers.
Practitioners should monitor FDA artificial intelligence guidance finalization, state-level laboratory licensing harmonization, and Medical Laboratory Scientist certification pipeline output for early signals requiring forecast revision. Cross-checking against CAP proficiency testing volume trends and health system capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Global Breast Cancer Screening Test Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Clinical Diagnostics Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Circulating Biomarkers Market
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Clinical Trial Kits Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Global Respiratory Disease Testing Market