
 Cystatin C Testing Market | 2026-2036
Cystatin C Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Cystatin C Testing Market Analysis
Software-defined assay calibration and remote result interpretation is shifting how diagnostic platforms capture recurring revenue from cystatin C testing workflows. Roche Diagnostics leverages its integrated cobas analyzer ecosystem to sustain high-throughput laboratory dominance. Abbott Laboratories anchors its position through handheld point-of-care architectures that reduce turnaround time in emergency departments. Siemens Healthineers competes on automated immunoassay throughput, while Randox Laboratories differentiates through multiplexed biomarker panels that incorporate cystatin C alongside complementary renal markers.
Cystatin C testing quantifies serum or plasma levels of a low-molecular-weight cysteine protease inhibitor (13 kDa) produced at a constant rate by all nucleated cells, with assays typically targeting analytical sensitivity below 0.5 mg/L to detect subtle renal function changes. The primary commercial purpose centers on delivering more accurate glomerular filtration rate estimates than creatinine alone, particularly in populations with variable muscle mass. Immunoassay platforms occupy the mature volume core of the market, while point-of-care testing represents the fastest-expanding delivery mode as health systems prioritize decentralized diagnostics. Kidney function assessment commands the largest application share, though cardiovascular risk evaluation is emerging as a higher-margin adjacency where dual biomarker strategies create pricing leverage.
The FDA oversees premarket submission pathways for novel cystatin C assays under its in vitro diagnostics framework, while Clinical Laboratory Improvement Amendments govern analytical performance standards in US laboratories. ISO 15189 accreditation requirements shape quality management expectations for clinical laboratories deploying these tests internationally. Stakeholders must monitor evolving reimbursement codes for confirmatory testing protocols and anticipate how integrated artificial intelligence readouts will reshape competitive positioning in renal diagnostics.
Market Dynamics
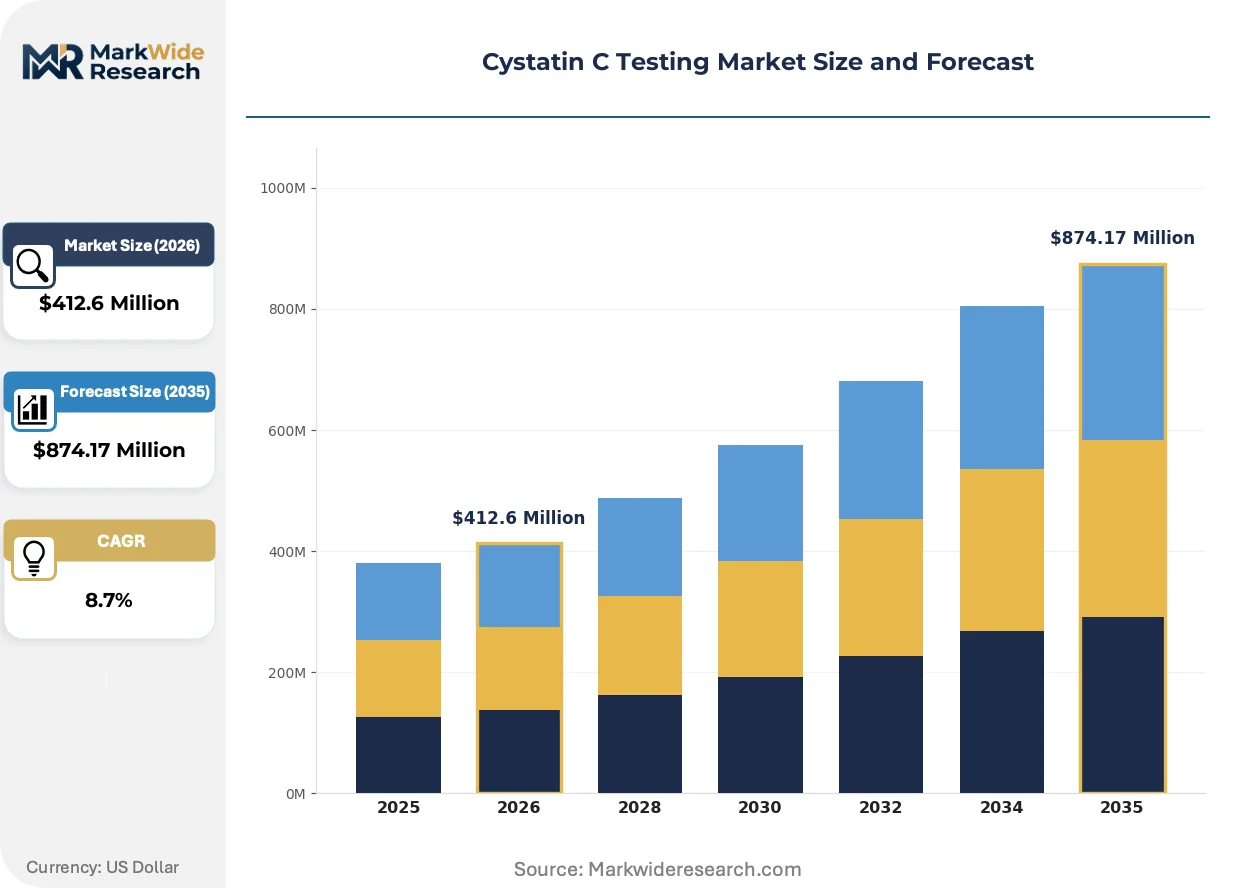
Medicare reimbursement policy is accelerating confirmatory testing protocols, forcing laboratories to reconfigure renal diagnostic workflows around dual-biomarker strategies that elevate cystatin C from secondary to primary diagnostic status.
Growth Catalysts
- CMS reimbursement expansion:Medicare's 2024 decision to cover cystatin C confirmatory testing without prior authorization is driving hospital laboratory adoption across the United States.
- Immunoassay automation:High-throughput clinical chemistry platforms now integrate cystatin C alongside routine metabolic panels, embedding the test into standard care protocols.
- Variable muscle mass populations:Demand concentrates in geriatric and critical care settings where creatinine-based estimates prove unreliable, particularly among patients with sarcopenia or amputations.
Market Restraints
- Antibody supply concentration:Capture and detection antibody production for cystatin C immunoassays depends on a limited supplier base concentrated in Germany and Switzerland.
- Creatinine entrenched infrastructure:Decades of laboratory investment in Jaffe and enzymatic creatinine methods create switching costs that delay cystatin C platform conversion.
- Calibration standard heterogeneity:Lack of harmonized international reference materials forces manufacturers to maintain multiple master lot calibrations, elevating production complexity.
Strategic Opportunities
- Cardiovascular risk stratification:Dual biomarker protocols combining cystatin C with high-sensitivity troponin are penetrating cardiology service lines as payers recognize improved risk prediction value.
- Rural health network deployment:Federally qualified health centers in the United States represent underpenetrated sites where waived point-of-care cystatin C assays could replace referral-based testing.
- Artificial intelligence readout integration:Machine learning algorithms trained on combined creatinine-cystatin C inputs are creating differentiated service offerings for nephrology practices.
Industry Challenges
- Interference substance management:Assay developers must characterize and mitigate confounding from rheumatoid factor heterophilic antibodies and paraproteinemias in patient samples.
- CLIA complexity tier navigation:Point-of-care manufacturers face extended validation timelines as they pursue moderate-complexity certification required for emergency department deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cystatin C Testing Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Method: Immunoassays, Enzyme-Linked Immunosorbent Assays, Lateral Flow Assays, Microfluidic Devices Application: Kidney Function Assessment, Cardiovascular Risk Evaluation, Organ Transplant Monitoring, Diabetes Management End User: Clinical Laboratories, Hospitals, Research Institutions, Homecare Settings Delivery Mode: Traditional Lab Testing, Point-of-Care Testing, At-Home Testing, Remote Monitoring |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Thermo Fisher Scientific, Siemens Healthineers, Randox Laboratories, DiaSys Diagnostic Systems, Diazyme Laboratories, Sysmex Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cystatin C Testing Market Emerging Trajectories
Digital connectivity and assay miniaturization are converging to relocate cystatin C testing from centralized laboratories to distributed care settings, compressing turnaround times and expanding addressable test volume.
Handheld electrochemical biosensors with smartphone-integrated result reporting are decentralizing kidney function assessment from hospital core laboratories to emergency departments and dialysis clinics. Community health systems in the United States are piloting these devices for same-visit medication dosing decisions. The technology is decentralizing diagnostic authority from laboratory medicine specialists to frontline clinicians.
FDA's 2023 guidance on improved glomerular filtration rate estimation is mandating assay manufacturers demonstrate traceability to standardized reference methods before premarket clearance. This regulatory pressure is consolidating the vendor base around platforms with documented metrological rigor. High-complexity reference laboratories are absorbing disproportionate compliance costs as they validate alternative specimen types.
Hospital procurement committees are unbundling renal function testing from bundled chemistry panels, creating standalone cystatin C purchasing decisions that favor specialized assay menus. Integrated delivery networks in the United States are negotiating direct contracts with niche immunoassay manufacturers outside traditional group purchasing organization frameworks. This behavioral shift is most visible in Medicare Advantage-contracted health systems seeking HEDIS quality measure advantages through more accurate chronic kidney disease staging.
Cystatin C Testing Market Segmentation
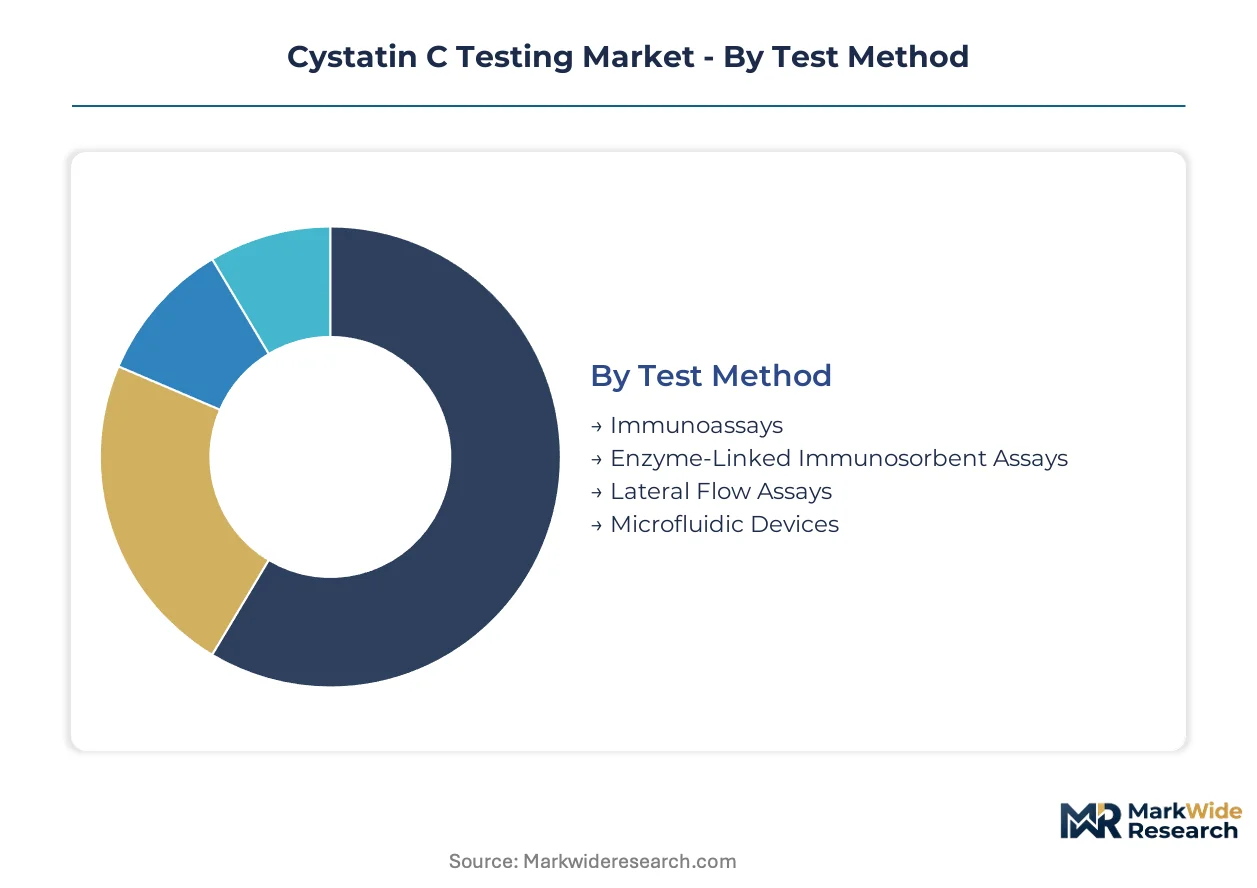
Platform architecture and reimbursement pathways diverge sharply across cystatin C testing modalities, creating distinct margin profiles and competitive dynamics within each segment. Laboratories and manufacturers must align product development with specific workflow integration requirements rather than pursuing undifferentiated market entry.
Test Method:
Clinical laboratories approaching platform refresh cycles weigh automation depth against capital constraints, with mid-volume facilities prioritizing modular upgrade paths over full system replacement.
- Immunoassays:Turbidimetric and nephelometric methods dominate high-throughput chemistry analyzers, with Roche cobas and Abbott Alinity platforms embedding cystatin C into routine metabolic panels. Hospital laboratories in the United States drive replacement demand as Medicare reimbursement validates confirmatory testing protocols.
- Enzyme-Linked Immunosorbent Assays:Manual and semi-automated ELISA formats retain relevance in research and low-volume clinical settings where capital investment in full automation proves uneconomical. Academic medical centers deploy these for specialized nephrology research protocols.
- Lateral Flow Assays:Single-use cartridge designs enable waived-complexity deployment under CLIA regulations.
- Microfluidic Devices:Lab-on-chip architectures integrate sample preparation with electrochemical detection for near-patient settings.
Volume placements concentrate in Immunoassays; the faster expansion belongs to Microfluidic Devices.
Application:
Margin structure varies substantially by clinical use case, with cardiovascular risk stratification commanding premium pricing compared to commoditized kidney function screening.
- Kidney Function Assessment:eGFR calculation represents the foundational use case, with dual biomarker protocols combining cystatin C and creatinine now standard in Medicare Advantage quality measurement programs. Nephrology practices in the United States anchor routine demand.
- Cardiovascular Risk Evaluation:Dual-marker strategies pairing cystatin C with high-sensitivity troponin penetrate cardiology service lines as payers recognize superior risk prediction. Integrated delivery networks negotiate direct contracts for these higher-margin panels outside traditional GPO frameworks.
- Organ Transplant Monitoring:Post-transplant graft function surveillance drives specialized assay menus at transplant centers.
- Diabetes Management:Early renal impairment detection in diabetic populations supports chronic care protocol integration.
Revenue concentration sits with Kidney Function Assessment; Cardiovascular Risk Evaluation climbs the fastest.
End User:
Procurement authority and workflow constraints shape product design requirements, with hospital system consolidation shifting purchasing decisions toward enterprise-level contract structures.
- Clinical Laboratories:Core hospital and reference laboratories process the majority of cystatin C volume, with high-throughput automation and LIS integration as non-negotiable requirements. Quest Diagnostics and LabCorp network expansion in the United States sustains platform refresh cycles.
- Hospitals:Emergency departments and inpatient units drive point-of-care adoption for acute kidney injury triage, with turnaround time reduction as the primary procurement criterion. Health systems prioritize moderate-complexity CLIA certification for STAT testing.
- Research Institutions:Academic medical centers support assay development and biomarker validation studies.
- Homecare Settings:Remote patient monitoring applications remain nascent pending FDA clearance of connected devices.
Test volume aggregates in Clinical Laboratories; Hospitals gain share fastest through point-of-care deployment.
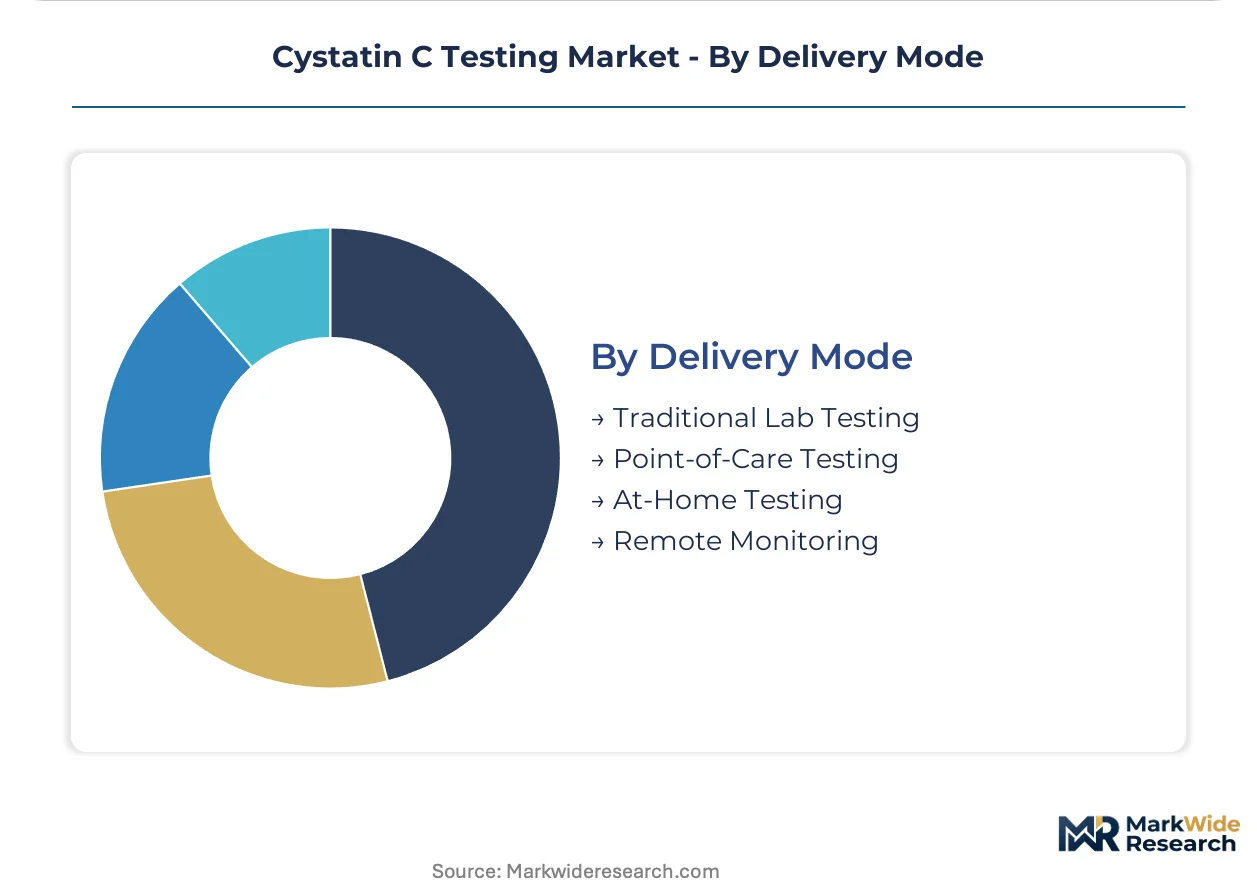
Delivery Mode:
Decentralization pressure from health system cost reduction and patient convenience expectations is redistributing testing volume across physical settings.
- Traditional Lab Testing:Centralized core laboratory processing retains dominance for routine chronic kidney disease staging and confirmatory protocols. Medicare reimbursement structures in the United States reinforce this channel for standard care pathways.
- Point-of-Care Testing:Handheld devices with smartphone connectivity compress turnaround times for emergency department and dialysis clinic workflows. Federally qualified health centers pilot these for same-visit medication dosing in rural networks.
- At-Home Testing:Direct-to-consumer formats face regulatory and reimbursement hurdles limiting near-term penetration.
- Remote Monitoring:Telehealth-integrated result reporting supports chronic disease management programs.
Traditional Lab Testing captures current volume leadership; Point-of-Care Testing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic assay production concentrates in Germany and Switzerland, while clinical consumption tilts toward the United States where Medicare reimbursement drives volume. Manufacturing of cystatin C antibodies and calibrator materials clusters in Central European chemical corridors. Demand generation follows hospital procurement cycles and point-of-care deployment timelines across distinct national health systems.
United States
Hospital laboratories and integrated delivery networks generate the majority of cystatin C test volume through Medicare Advantage quality programs and emergency department triage protocols. The FDA's 2023 guidance on improved glomerular filtration rate estimation mandates traceability standards that filter the vendor base. Boston and the Research Triangle anchor specialized nephrology reference laboratories validating dual-biomarker protocols.
Germany
Antibody production for cystatin C immunoassays concentrates in Baden-Württemberg and Bavaria, supplying capture and detection reagents to global assay manufacturers. The country's national pharmaceutical regulator enforces ISO 15189 accreditation requirements that shape quality management expectations for clinical laboratories deploying these tests. Frankfurt and Munich host high-complexity reference laboratories serving Central European transplant centers.
Switzerland
Specialized biochemical reagent suppliers in Basel and Zurich manufacture master lot calibrators and reference materials for cystatin C standardization. Swissmedic oversees in vitro diagnostic premarket requirements that influence global assay harmonization efforts. The Lake Geneva corridor sustains contract research organizations supporting biomarker validation for renal diagnostic platforms.
Japan
Automated immunoassay analyzer manufacturers in Tokyo and Osaka integrate cystatin C into routine metabolic panels for domestic hospital networks. The PMDA governs premarket submission pathways for novel assays under its in vitro diagnostics framework. The Kansai region hosts clinical laboratories pioneering combined creatinine-cystatin C artificial intelligence readouts for nephrology practices.
China
Domestic diagnostic platform manufacturers in Shanghai and Suzhou develop localized cystatin C assays for hospital laboratory procurement tenders. The NMPA oversees premarket clearance requirements that increasingly reference international harmonization standards. The Yangtze River Delta clusters point-of-care device developers targeting rural health network deployment.
Cystatin C Testing Market Vendor Landscape
Top-tier vendors anchor high-throughput laboratory automation, while mid-tier specialists compete on point-of-care miniaturization and multiplexed biomarker panels. The market structure reflects a bifurcation between integrated chemistry analyzer ecosystems and handheld emergency department devices. Two strategic archetypes dominate: diversified diagnostics conglomerates leveraging installed base lock-in, and niche immunoassay developers capturing standalone purchasing decisions. Consolidation pressure operates through hospital procurement committee unbundling of renal function tests from bundled chemistry panels.
Among diversified diagnostics conglomerates, Roche Diagnostics and Abbott Laboratories exemplify contrasting platform strategies. Roche occupies a position anchored in centralized laboratory automation through its cobas analyzer ecosystem. Abbott represents the point-of-care expansion archetype with handheld architectures reducing turnaround time in emergency departments. Siemens Healthineers sits within the automated immunoassay throughput tier competing on high-volume chemistry analyzer integration.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Siemens Healthineers |
| Randox Laboratories |
| DiaSys Diagnostic Systems |
| Diazyme Laboratories |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Others |
Supply Flow & Price Mechanics
ISO 15189 accreditation requirements gate qualified supply for premium-tier cystatin C assays, concentrating pricing power among manufacturers with documented metrological traceability while excluding uncertified competitors from hospital laboratory procurement shortlists. This regulatory filter elevates production costs for compliant players but simultaneously protects margin structures through reduced price competition.
Pricing Analysis
Cost compression in economy-tier ELISA formats traces to antibody oversupply from German and Swiss reagent manufacturers competing for reference laboratory contracts. Pricing stratifies across premium instrument-integrated immunoassays, standard moderate-complexity platforms, and economy manual kits, with differentiation driven by FDA clearance tier and LIS integration depth. Hospital procurement committees exhibit highest price sensitivity for routine kidney function panels, while transplant centers and cardiology service lines tolerate premium positioning for dual-biomarker protocols.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume analyzer placements at integrated delivery networks, bypassing traditional distribution intermediaries. Antibody production concentrates in Germany, Switzerland, and the United States, drawing from recombinant protein expression systems and hybridoma cell lines. Single-source vulnerability pervades master lot calibrator supply, with Swiss and German reference material producers anchoring global standardization. Distribution runs through specialized diagnostic distributors serving hospital laboratories and point-of-care device vendors targeting emergency departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's 2023 guidance on improved glomerular filtration rate estimation erects a substantial compliance moat, filtering the vendor base to manufacturers with demonstrated traceability to standardized reference methods and absorbing disproportionate validation costs from smaller competitors.
For Market Incumbents: Lock in hospital laboratory loyalty through cobas and Alinity platform ecosystem expansion, embedding cystatin C into routine metabolic panels to raise switching costs against emerging point-of-care entrants. Deepen backward integration into antibody production by acquiring German or Swiss reagent suppliers, insulating margin structures from capture reagent price volatility and supply interruption risks. For New Entrants and Emerging Players: Capture federally qualified health center demand in rural United States networks where waived-complexity point-of-care assays replace referral-based testing and incumbent analyzer footprints remain thin. Pursue moderate-complexity CLIA certification for handheld electrochemical biosensors, enabling emergency department STAT deployment against slower-turnaround laboratory competitors. For Investors and Strategic Acquirers: Medicare Advantage quality program adoption of dual-biomarker protocols is the leading indicator that cystatin C is transitioning from confirmatory to primary diagnostic status, expanding addressable volume and supporting durable pricing power. Target niche immunoassay developers with established ISO 15189 accreditation and documented FDA premarket clearance pathways, avoiding pre-revenue platform ventures facing extended validation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | Medicare coverage expansion for confirmatory testing protocols accelerates hospital laboratory adoption across United States networks. |
| Platform Integration | Embedded cystatin C modules within cobas and Alinity ecosystems create high switching costs and recurring reagent revenue streams. |
| Point-of-Care Miniaturization | Handheld electrochemical biosensors with smartphone connectivity decentralize testing from core laboratories to emergency departments. |
| Antibody Supply Security | Captive production of capture and detection reagents in Germany and Switzerland insulates margins from supplier concentration risk. |
| Artificial Intelligence Readout Development | Machine learning algorithms trained on combined creatinine-cystatin C inputs differentiate nephrology practice service offerings. |
Methodological Framework
Document review covered FDA 510(k) filings, CMS Medicare reimbursement databases, and ISO 15189 accreditation registries, complemented by interviews with nephrology laboratory directors, hospital purchasing committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from Clinical Laboratory Improvement Amendments compliance records, hospital procurement databases, and industry trade association technical standards. Bottom-up test volume modeling and top-down market sizing triangulated segment-level outputs.
Segmentation outputs reflect disaggregation by test method, application, end user, and delivery mode across the projection horizon. Modeled dimensions include immunoassay platform architecture, cardiovascular versus kidney function clinical use case, and point-of-care versus centralized laboratory deployment pattern. CAGRs were derived from regression analysis against Medicare reimbursement policy variables and hospital capital expenditure cycles, incorporating antibody supply constraints and CLIA complexity tier adoption curves as industry-specific demand shapers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA guidance implementation timing and Medicare Advantage quality program design changes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Global Clinical Chemistry Analyzers Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Global Cervical Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Nasopharyngeal Swab Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Renal Function Test Market