
 Prenatal and New-Born Genetic Testing Market | 2026-2036
Prenatal and New-Born Genetic Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Prenatal and New-Born Genetic Testing Market Analysis
The capability gap between sequencing infrastructure-heavy operators and assay-only service providers is rotating competitive advantage toward vertically integrated platforms. Illumina Inc leverages its instrument installed base to capture recurring consumable revenue across clinical and research accounts. Natera Inc anchors its position through proprietary bioinformatics pipelines for cell-free DNA interpretation. Thermo Fisher Scientific Inc extends its reach through end-to-end workflow solutions spanning sample preparation to variant reporting.
Prenatal and new-born genetic testing encompasses molecular diagnostic procedures applied during gestation or immediately after birth to detect chromosomal abnormalities, monogenic disorders, and metabolic conditions through analysis of fetal DNA, amniotic fluid, or neonatal blood spots. These tests functionally enable clinical decision-making around pregnancy management, early therapeutic intervention, and reproductive planning. Non-invasive prenatal testing commands the largest revenue pool among product types due to superior safety profiles compared with invasive sampling methods. Next-generation sequencing represents the fastest-expanding technology segment as throughput gains and declining per-base costs displace microarray analysis in high-volume screening programs. Diagnostic laboratories concentrate margin capture through automated sample-to-report workflows that reduce turnaround times for chromosomal abnormality detection applications.
FDA oversight of laboratory-developed tests and EMA requirements under the In Vitro Diagnostic Regulation shape product validation burdens and market access timelines for assay developers. The EU AI Act introduces additional scrutiny for algorithmic components embedded in variant interpretation software, particularly affecting European deployments. China's NMPA accelerated review pathways for innovative reproductive diagnostics are expanding domestic manufacturer participation. Stakeholders must monitor evolving reimbursement decisions by national health technology assessment bodies as these determine commercial viability of expanded carrier screening panels.
Market Dynamics
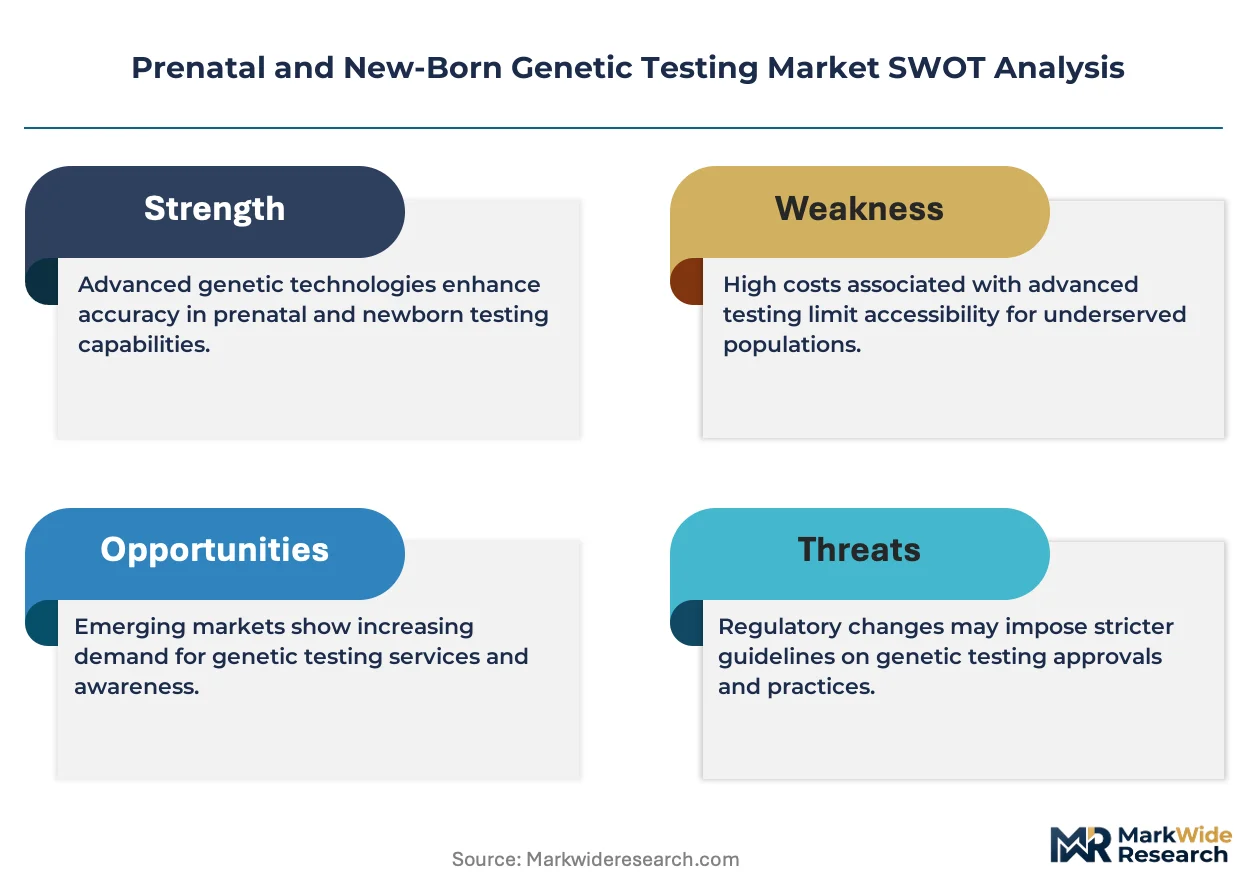
Sequencing platform consolidation is compressing margins for standalone assay developers while rewarding vertically integrated operators with captive instrument bases and recurring consumable revenue streams.
Growth Catalysts
- Cell-free DNA workflow maturation:Non-invasive prenatal testing protocols have achieved clinical-grade sensitivity thresholds that satisfy FDA validation requirements for fetal aneuploidy screening.
- Carrier screening expansion:United States commercial payers are broadening reimbursement for expanded panels covering autosomal recessive and X-linked conditions.
- Metabolic newborn screening mandates:Germany's statutory health insurance framework now covers tandem mass spectrometry for expanded inborn error detection.
Market Restraints
- Sequencing reagent cost volatility:Polymerase and modified nucleotide supply concentrates among three chemical synthesis providers, exposing laboratories to input price swings.
- Interpretation algorithm validation burden:EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements on variant classification software that extend product launch timelines.
- Microarray residual utility:Copy number variant detection for subtelomeric rearrangements retains diagnostic necessity where short-read sequencing coverage gaps persist.
Strategic Opportunities
- China's NMPA accelerated pathways:Domestic manufacturers can secure priority review for reproductive genetic tests that demonstrate substantial equivalence to predicate devices.
- Polygenic risk score integration:Convergence of common variant profiling with rare disease screening enables combined obstetric risk stratification workflows.
- Direct-to-consumer channel emergence:Carrier screening kits distributed through telemedicine platforms bypass traditional obstetric clinic gatekeepers.
Industry Challenges
- Bioinformatics specialist scarcity:Variant curation and ACMG classification interpretation require molecular geneticists with dual training in computational biology and clinical genetics.
- Laboratory information system integration:Legacy electronic health record architectures resist seamless ingestion of structured genomic reports into maternal-fetal medicine workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prenatal and New-Born Genetic Testing Market |
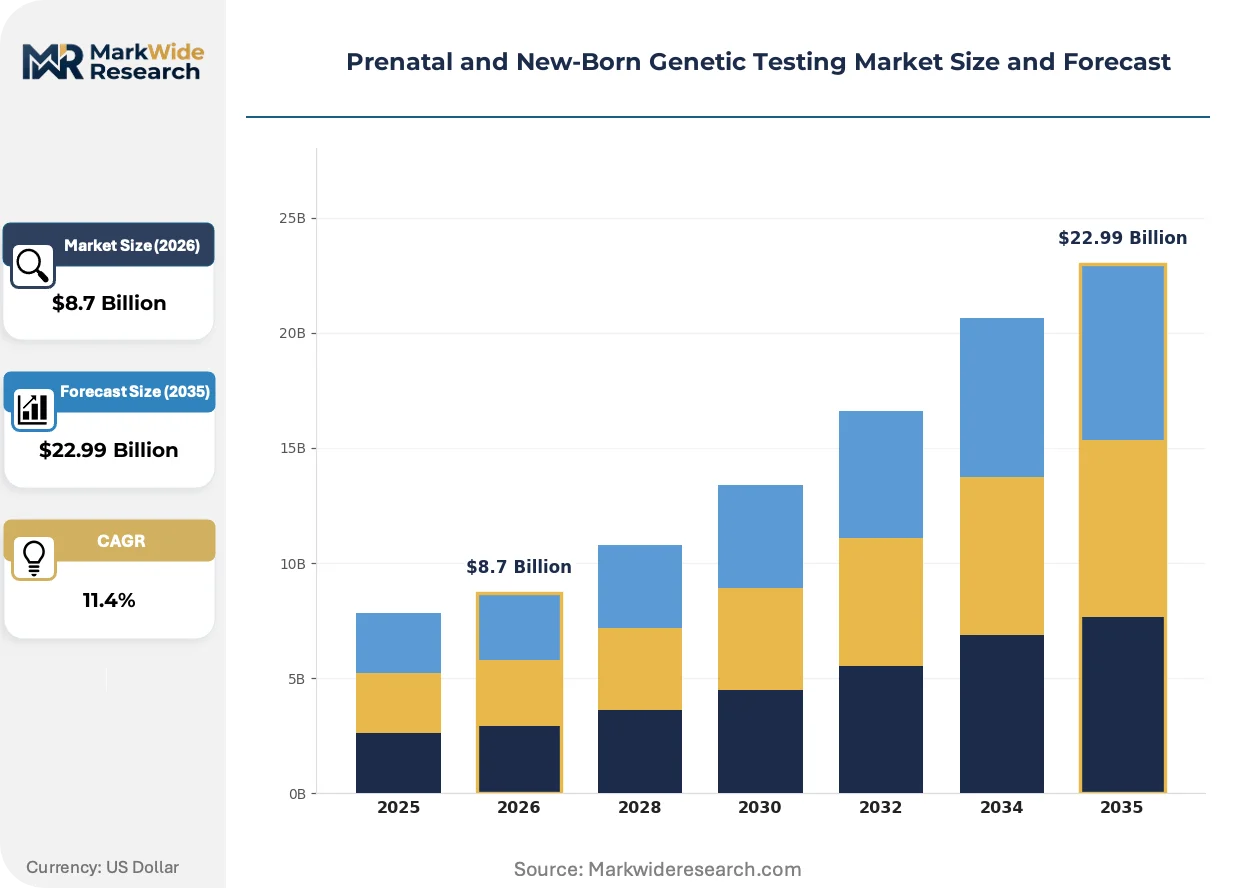
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carrier Testing, Non-Invasive Prenatal Testing, Newborn Screening, Preimplantation Genetic Diagnosis Technology: Next-Generation Sequencing, Polymerase Chain Reaction, Fluorescence In Situ Hybridization, Microarray Analysis End User: Hospitals, Diagnostic Laboratories, Clinics, Research Institutions Application: Chromosomal Abnormality Detection, Genetic Disorder Prediction, Parental Carrier Screening, Fetal Health Assessment |
| Companies Covered | Illumina Inc, Natera Inc, Roche Diagnostics, BGI Genomics, Eurofins Scientific, Agilent Technologies Inc, Revvity Inc, Thermo Fisher Scientific Inc, Laboratory Corporation of America Holdings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prenatal and New-Born Genetic Testing Market Emerging Trajectories
Long-read sequencing platforms are entering clinical validation pipelines while regulatory frameworks adapt to algorithmic decision-support tools. These shifts compress turnaround times and expand detectable variant classes.
Single-molecule real-time sequencing is displacing short-read platforms for structural variant detection in prenatal diagnostic reflex testing. Academic medical centers with high-risk pregnancy programs are piloting these instruments for resolving ambiguous microarray findings. The technology is displacing fluorescence in situ hybridization confirmation steps that previously extended reporting timelines by weeks.
EMA's In Vitro Diagnostic Regulation now classifies variant interpretation software as Class C devices requiring notified body conformity assessment. Assay developers must compile clinical evidence dossiers for algorithm performance across diverse populations. European laboratories are responding by consolidating purchasing decisions toward vendors with established quality management system certifications.
Obstetric practices are consolidating prenatal testing procurement through health system laboratory joint ventures. Independent reference laboratories face exclusion from narrow networks that prioritize captive hospital outreach services. This concentration is most pronounced in United States metropolitan markets where integrated delivery systems control maternal care referral patterns.
Prenatal and New-Born Genetic Testing Market Segmentation
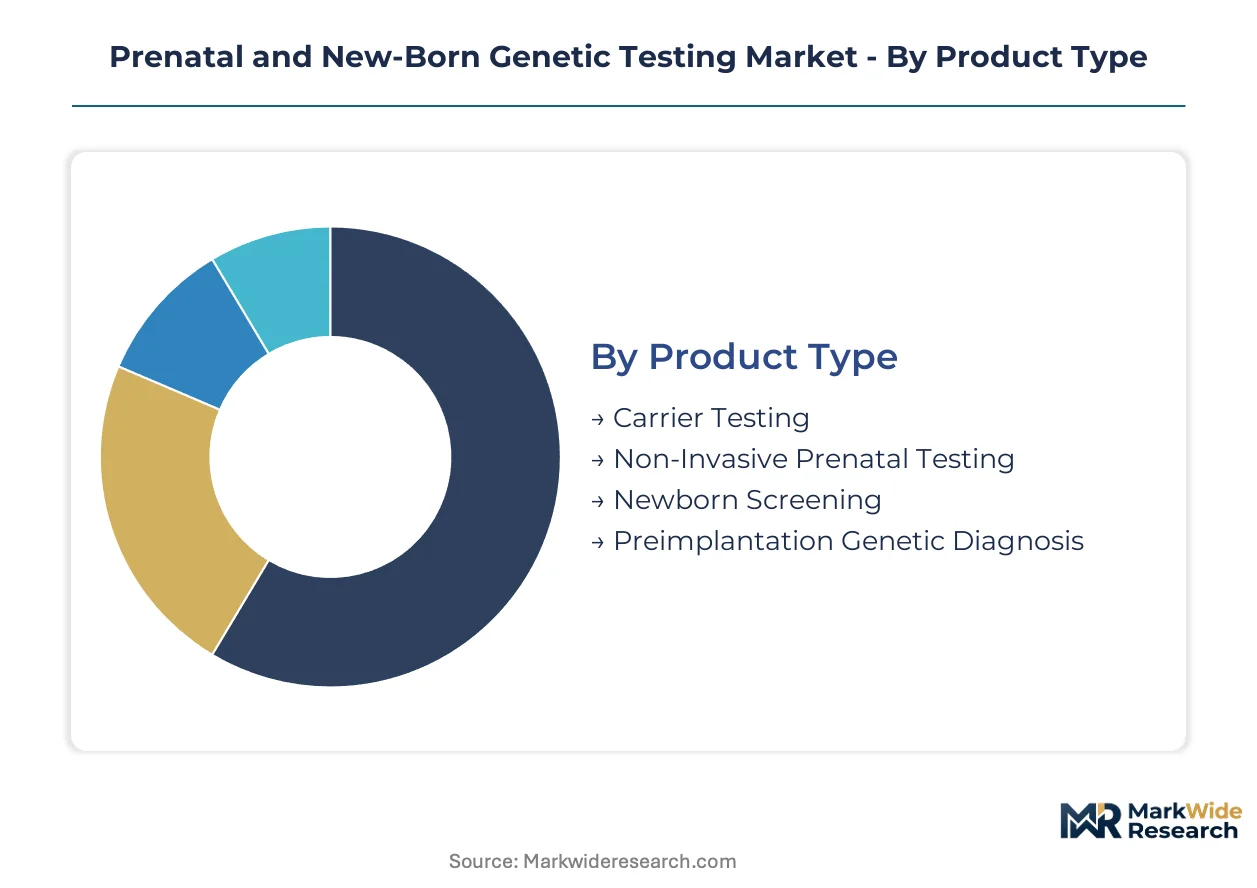
Segmentation reveals how prenatal and newborn genetic testing flows through distinct procurement channels, each with divergent reimbursement pathways and technical requirements. Understanding these splits illuminates where platform vendors capture recurring revenue versus where assay specialists compete on test menu breadth.
Product Type:
Channel mix varies sharply: diagnostic laboratories dominate non-invasive prenatal testing and newborn screening through high-throughput automation, while fertility clinics and hospital genetics departments control carrier testing and preimplantation genetic diagnosis workflows.
- Carrier Testing:Expanded panels covering autosomal recessive and X-linked conditions now reach 200+ gene targets. United States commercial payers have broadened reimbursement coverage, driving demand concentration in employer-sponsored health plans and direct-to-consumer telemedicine channels.
- Non-Invasive Prenatal Testing:Cell-free DNA analysis from maternal plasma achieves clinical-grade sensitivity for fetal aneuploidy screening without invasive sampling risk. China's NMPA accelerated review pathways have expanded domestic manufacturer participation in this highest-volume category.
- Newborn Screening:Tandem mass spectrometry and DNA-based panels detect inborn errors of metabolism from neonatal blood spots. Germany's statutory health insurance framework mandates expanded coverage, anchoring European demand.
- Preimplantation Genetic Diagnosis:Embryo biopsy with genetic analysis prior to implantation serves fertility clinic workflows. Regulatory complexity and specialized laboratory requirements limit this segment to academic medical center and private fertility network channels.
By volume, Non-Invasive Prenatal Testing leads. By growth pace, Carrier Testing is ahead.
Technology:
Cost tier stratification separates capital-intensive sequencing infrastructure from lower-barrier amplification and hybridization methods, with reimbursement rates tracking technical complexity and turnaround time.
- Next-Generation Sequencing:Short-read platforms with declining per-base costs displace microarray analysis in high-volume screening programs. Throughput gains enable combined obstetric risk stratification workflows integrating rare disease and polygenic profiling.
- Polymerase Chain Reaction:Targeted amplification remains cost-advantaged for single-gene carrier screening and rapid newborn screening reflex testing. Point-of-care formats serve clinics lacking centralized laboratory infrastructure.
- Fluorescence In Situ Hybridization:Chromosomal structural analysis retains diagnostic necessity for resolving ambiguous microarray findings. Single-molecule real-time sequencing is displacing this technology in academic medical center pilot programs.
- Microarray Analysis:Copy number variant detection for subtelomeric rearrangements fills coverage gaps where short-read sequencing performs poorly. Residual utility persists in prenatal diagnostic reflex testing despite platform consolidation pressure.
Next-Generation Sequencing commands the steepest expansion trajectory as throughput economics improve.
End User:
Customer type determines purchasing authority: hospital system laboratory joint ventures consolidate procurement decisions, while independent reference laboratories compete for narrow network inclusion.
- Hospitals:Integrated delivery systems in United States metropolitan markets control maternal care referral patterns and prioritize captive outreach laboratory services. Obstetric practice consolidation drives exclusive contracting with health system joint ventures.
- Diagnostic Laboratories:High-throughput operators capture margin through automated sample-to-report workflows reducing turnaround times. EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements that favor vendors with established quality management system certifications.
- Clinics:Fertility and maternal-fetal medicine practices source specialized preimplantation and invasive diagnostic testing. Direct-to-consumer carrier screening distributed through telemedicine platforms bypasses traditional obstetric clinic gatekeepers.
- Research Institutions:Academic medical centers pilot long-read sequencing platforms for structural variant detection and algorithmic decision-support tool validation. EU AI Act scrutiny affects European deployments of variant interpretation software.
Diagnostic Laboratories process the highest test volumes. Research Institutions are expanding fastest as clinical validation pipelines mature.
Application:
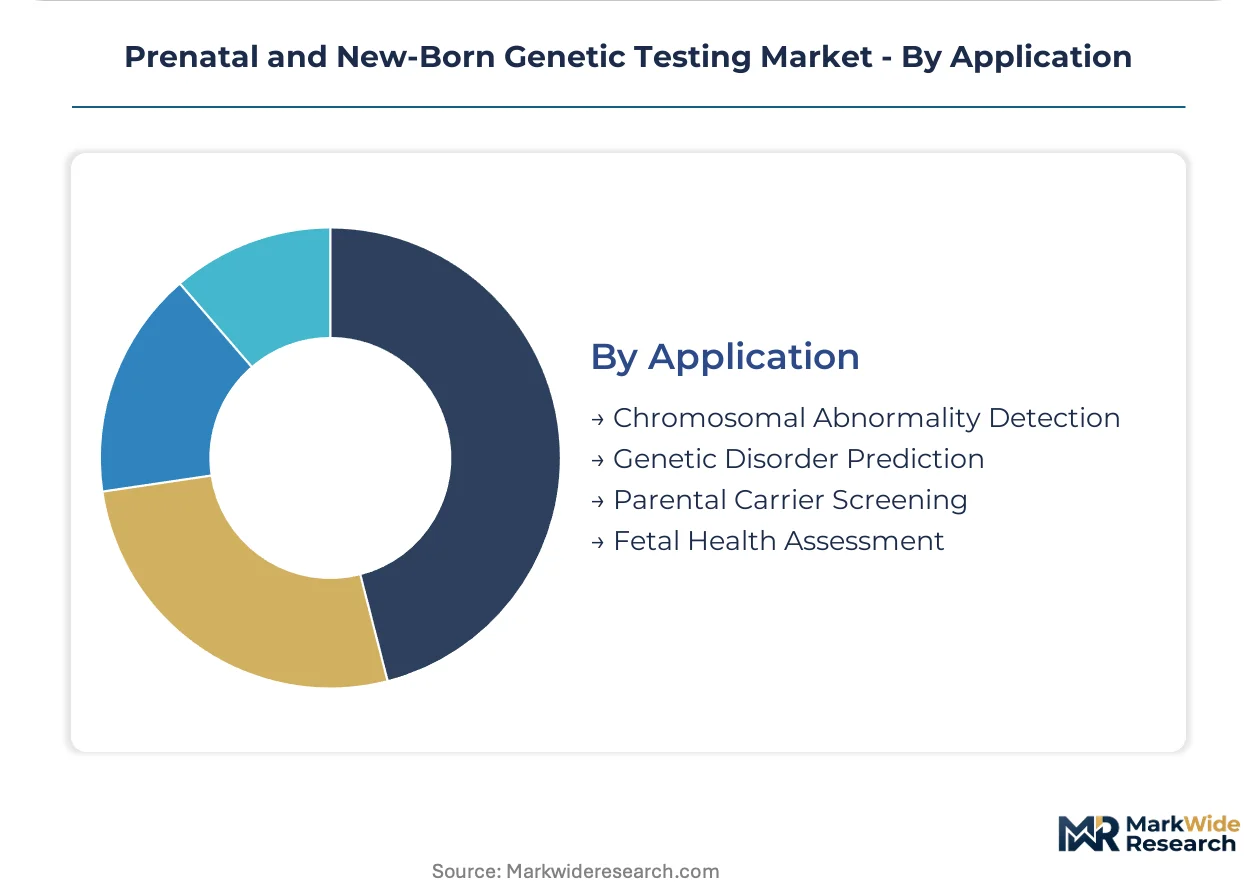
Application focus aligns with reimbursement maturity: chromosomal abnormality detection commands established coverage, while predictive and expanded screening applications face health technology assessment scrutiny.
- Chromosomal Abnormality Detection:Fetal aneuploidy screening satisfies FDA validation requirements for cell-free DNA workflow sensitivity thresholds. This application anchors non-invasive prenatal testing reimbursement in United States and German frameworks.
- Genetic Disorder Prediction:Polygenic risk score integration with rare disease screening enables combined obstetric risk stratification. Algorithmic components face additional EMA scrutiny under EU AI Act provisions for European deployments.
- Parental Carrier Screening:Expanded panels for reproductive planning decisions concentrate demand in employer-sponsored health plans. United States commercial payer coverage broadening drives segment expansion.
- Fetal Health Assessment:Comprehensive metabolic and structural evaluation from multiple analyte classes serves high-risk pregnancy programs. Tandem mass spectrometry mandates in Germany anchor European demand concentration.
Chromosomal Abnormality Detection leads by procedure volume. Genetic Disorder Prediction is climbing the fastest as risk stratification workflows converge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States and Germany where reimbursement frameworks for expanded carrier panels and newborn metabolic screening command premium rates, while Chinese manufacturers compete on sequencing consumable cost efficiency.
United States
Employer-sponsored health plans and commercial payers drive demand for expanded carrier screening panels covering 200-plus gene targets. FDA oversight of laboratory-developed tests shapes validation requirements for cell-free DNA workflows. The Boston-Cambridge biotech corridor anchors clinical validation pipelines for algorithmic decision-support tools.
Germany
Statutory health insurance mandates for tandem mass spectrometry newborn screening anchor European demand concentration. EMA's In Vitro Diagnostic Regulation imposes clinical evidence requirements on variant interpretation software. The Munich-Heidelberg medical technology cluster concentrates diagnostic laboratory automation development.
China
NMPA accelerated review pathways expand domestic manufacturer participation in non-invasive prenatal testing workflows. The country's national pharmaceutical regulator prioritizes reproductive genetic tests demonstrating substantial equivalence to predicate devices. The Yangtze River Delta biotech corridor concentrates cell-free DNA assay production capacity.
United Kingdom
NHS England's genomic medicine service drives centralized procurement for rare disease screening programs. The national health technology assessment body evaluates expanded carrier panel cost-effectiveness against standard care. The London-Oxford-Cambridge golden triangle anchors academic medical center pilot programs for long-read sequencing platforms.
Japan
PMDA streamlined approval pathways for non-invasive prenatal testing stimulate demand from aging demographic profiles seeking reproductive risk assessment. METI industrial policy supports domestic sequencing platform development. The Tokyo-Yokohama metropolitan cluster concentrates fertility clinic networks sourcing preimplantation genetic diagnosis services.
Prenatal and New-Born Genetic Testing Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered market structure where vertically integrated sequencing platform vendors capture recurring consumable revenue while assay specialists compete on test menu breadth. The competitive landscape consolidates around three strategic archetypes: instrument manufacturers with captive installed bases, bioinformatics-centric service providers, and end-to-end workflow solution vendors. Dominant competitive moves include strategic partnerships between platform developers and diagnostic laboratories, plus geographic expansion through regulatory pathway exploitation in priority markets.
Within the instrument-centric tier, Illumina Inc and Thermo Fisher Scientific Inc exemplify vertically integrated operators leveraging sequencing infrastructure to secure recurring revenue streams. Natera Inc occupies a position among bioinformatics-focused specialists, anchoring competitive differentiation through proprietary analytical pipelines. These three entities collectively represent the dominant competitive archetypes shaping procurement dynamics across hospital system laboratory joint ventures and independent reference laboratory channels.
| Leading Market Players |
|---|
| Illumina Inc |
| Natera Inc |
| Roche Diagnostics |
| BGI Genomics |
| Eurofins Scientific |
| Agilent Technologies Inc |
| Revvity Inc |
| Thermo Fisher Scientific Inc |
| Laboratory Corporation of America Holdings |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day reagent lead times for sequencing consumables concentrate margin pressure on diagnostic laboratories lacking long-term offtake agreements with polymerase suppliers. This inventory exposure rotates pricing power toward vertically integrated platform vendors with captive chemical synthesis capabilities.
Pricing Analysis
The customization-premium spread separates standard cell-free DNA panels from configured-to-order expanded carrier screening menus. Per-unit transactional pricing dominates consumable revenue streams, with differentiation driven by FDA validation tier and volume scale commitments. Cost compression in standard aneuploidy screening intensifies because Chinese manufacturers exploit NMPA accelerated pathways to undercut incumbent reagent pricing. Independent reference laboratories exhibit highest price sensitivity, while integrated health system laboratories prioritize turnaround time over per-test cost.
Supply Chain Analysis
Inventory lead-time volatility for modified nucleotides and polymerase enzymes exposes laboratories to margin erosion when spot-market sourcing becomes necessary. Chemical synthesis capacity concentrates in the United States, Germany, and China, with raw material dependencies spanning phosphoramidite precursors, fluorescent dyes, and synthetic oligonucleotides. Single-source vulnerability characterizes high-fidelity polymerase supply, where three providers control enzymatic reagent production. Distribution runs through authorized distributor networks serving hospital system laboratory joint ventures and independent reference laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The prenatal and newborn genetic testing market functions as a service-attach opportunity where bioinformatics interpretation layers expand faster than sequencing hardware sales. Recurring revenue from variant classification software subscriptions outpaces instrument placement growth.
For Market Incumbents: Secure captive consumable revenue through long-term reagent supply contracts with diagnostic laboratory networks. Deepen algorithm validation dossiers for EMA Class C device conformity under EU AI Act provisions. Consolidate position by acquiring specialized variant curation boutiques before regulatory compliance costs escalate. For New Entrants and Emerging Players: Anchor in direct-to-consumer carrier screening distributed through telemedicine platforms, the most penetrable channel bypassing obstetric clinic gatekeepers. Target employer-sponsored health plans with expanded panel offerings. Pursue NMPA priority review pathways for reproductive genetic tests demonstrating substantial equivalence to predicate devices. For Investors and Strategic Acquirers: Carve-out targets emerge from academic medical center spin-offs possessing validated long-read sequencing clinical pipelines. Five-to-ten-year viability hinges on regulatory navigation capabilities rather than technology differentiation alone. Monitor EMA notified body backlog as inflection indicator for European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Proprietary bioinformatics pipelines for cell-free DNA interpretation capture recurring revenue beyond hardware sales. |
| Hospital System Partnership | Exclusive contracting with integrated delivery systems locks out independent reference laboratories from narrow networks. |
| CE Marking Pathway | EMA In Vitro Diagnostic Regulation compliance for variant interpretation software enables European market access. |
| Reimbursement Strategy | Health technology assessment body engagement determines commercial viability of expanded carrier screening panels. |
| Regulatory Approval Pathway | NMPA accelerated review for reproductive genetic tests expands domestic manufacturer participation in China. |
Methodological Framework
A standing panel of molecular geneticists, diagnostic laboratory directors, FDA regulatory consultants, and health system procurement officers provided ongoing calibration against market developments. Primary interview findings combined with secondary validation from FDA 510(k) filings, EMA submission databases, ClinicalTrials.gov reproductive genetic study records, and CMS Medicare reimbursement data. Bottom-up test volume estimates triangulated with top-down sequencing consumable revenue analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation dimensions spanning product type, technology platform, end-user channel, and application focus. CAGRs derived from fitted growth curves incorporating reimbursement expansion trajectories, regulatory pathway timelines, and sequencing cost decline curves. Industry-specific inputs included cell-free DNA test adoption rates and newborn screening mandate expansion schedules.
Decision-makers should treat outputs as directional under assumptions of stable FDA and EMA regulatory frameworks; material deviation would warrant model refresh. Specific risk factors include laboratory-developed test oversight expansion, EU AI Act algorithmic scrutiny intensification, and Chinese domestic manufacturer capacity buildout. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Diagnostic Equipment Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Lactate Dehydrogenase Test Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Cervical Cancer Screening Market
Clinical Diagnostics
Cell-Free Fetal DNA Testing Market
Clinical Diagnostics
Cystatin C Testing Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Global Allergy Diagnostics and Therapeutics Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Adult Hemoglobinopathy Testing Market
Clinical Diagnostics
Genetic Disease Diagnostic Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Tumor Marker Testing Market