
 Global Colposcopy Devices Market | 2026-2036
Global Colposcopy Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Colposcopy Devices Market Foresight
High-definition optical-grade colposcopy is rotating toward digital and video-enabled platforms as the baseline specification for new procurement cycles. Carl Zeiss Meditec AG leverages its precision optics heritage to dominate premium stationary installations in European university hospitals. Olympus Corporation sustains competitive positioning through integrated workstation ecosystems that combine imaging with electronic medical record connectivity. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. anchors volume-tier supply chains across Asia-Pacific and Latin American public health systems.
Colposcopy devices are optical examination instruments employing magnified stereoscopic visualization, typically at 4x to 40x magnification, with integrated green or blue light filters to enhance vascular pattern contrast for cervical tissue assessment. These systems enable directed biopsy sampling and real-time documentation of epithelial abnormalities during gynecological screening protocols. Digital colposcopes now command the fastest-expanding margin pool as cloud-connected deployment architectures permit remote specialist consultation and automated image archiving. Video colposcopes retain structural importance in high-throughput diagnostic laboratories where continuous image capture supports quality assurance workflows. Portable colposcopes represent the emerging volume frontier, particularly in mobile screening programs where battery-powered operation and lightweight chassis design determine procurement decisions.
FDA clearance pathways for optical diagnostic devices govern product entry into the United States, while EMA medical device regulation and CE marking requirements shape European commercialization timelines. WHO cervical cancer elimination guidelines and national screening mandates from India's Ministry of Health and Family Welfare directly expand installed base requirements across divergent health system architectures. Stakeholders must monitor reimbursement code revisions for digital colposcopy with AI adjunct analysis, as these coding decisions will determine whether technology upgrades translate into sustainable revenue per procedure.
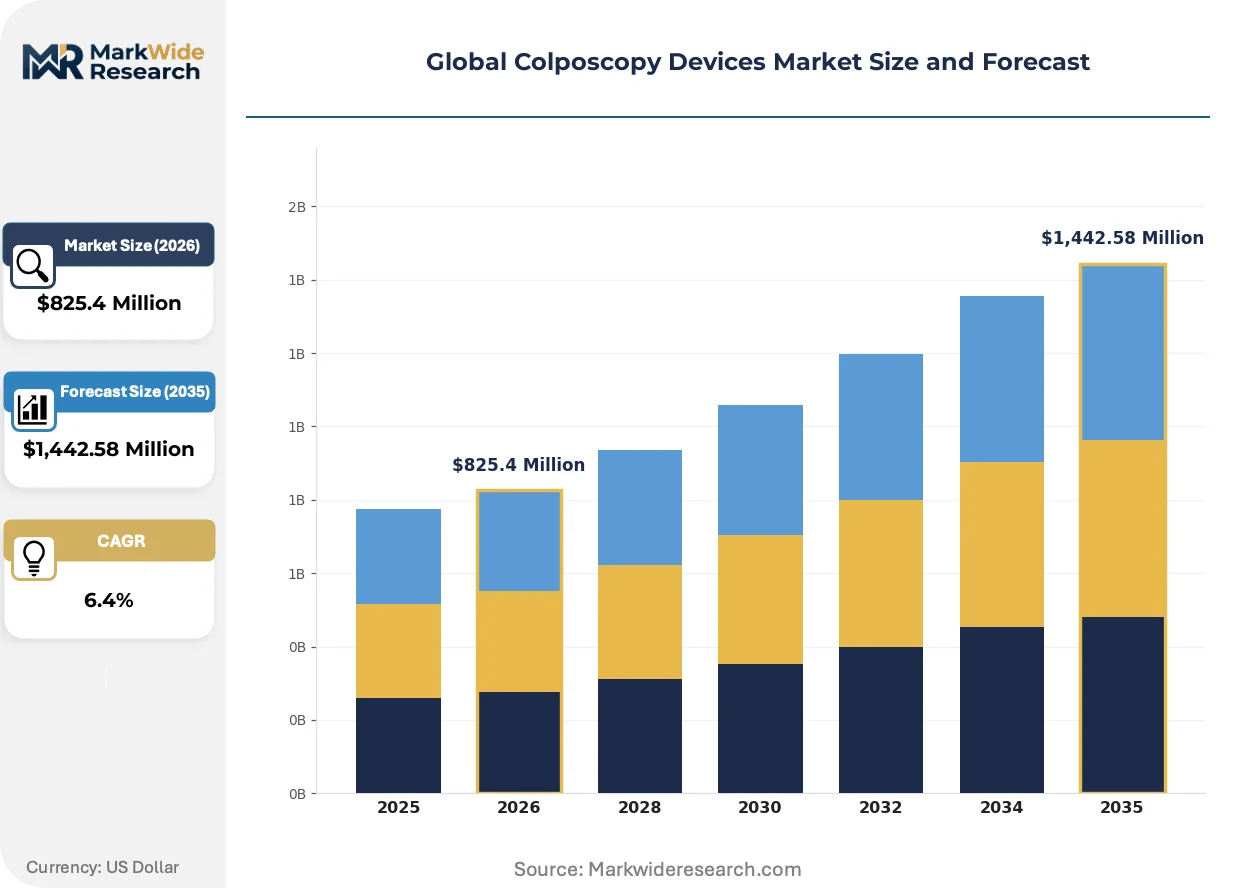
Market Dynamics
Digital colposcopy platforms are compressing replacement cycles as WHO cervical cancer elimination targets force national screening program upgrades across public health procurement channels. This regulatory pressure layer fuses with AI imaging integration to reshape vendor selection criteria.
Growth Catalysts
- WHO Elimination Strategy:The WHO cervical cancer elimination framework mandates 70% screening coverage by 2030, forcing health ministries in Brazil and India to expand colposcopy infrastructure in primary care networks.
- AI-Assisted Imaging Convergence:Machine learning algorithms for cervical lesion classification are embedding directly into digital colposcope firmware, creating upgrade demand from pathology laboratories seeking automated pattern recognition.
- Mobile Screening Programs:Battery-powered portable colposcopes enable outreach clinics in rural Mexico and Nigeria to reach populations outside tertiary hospital catchment zones.
Market Restraints
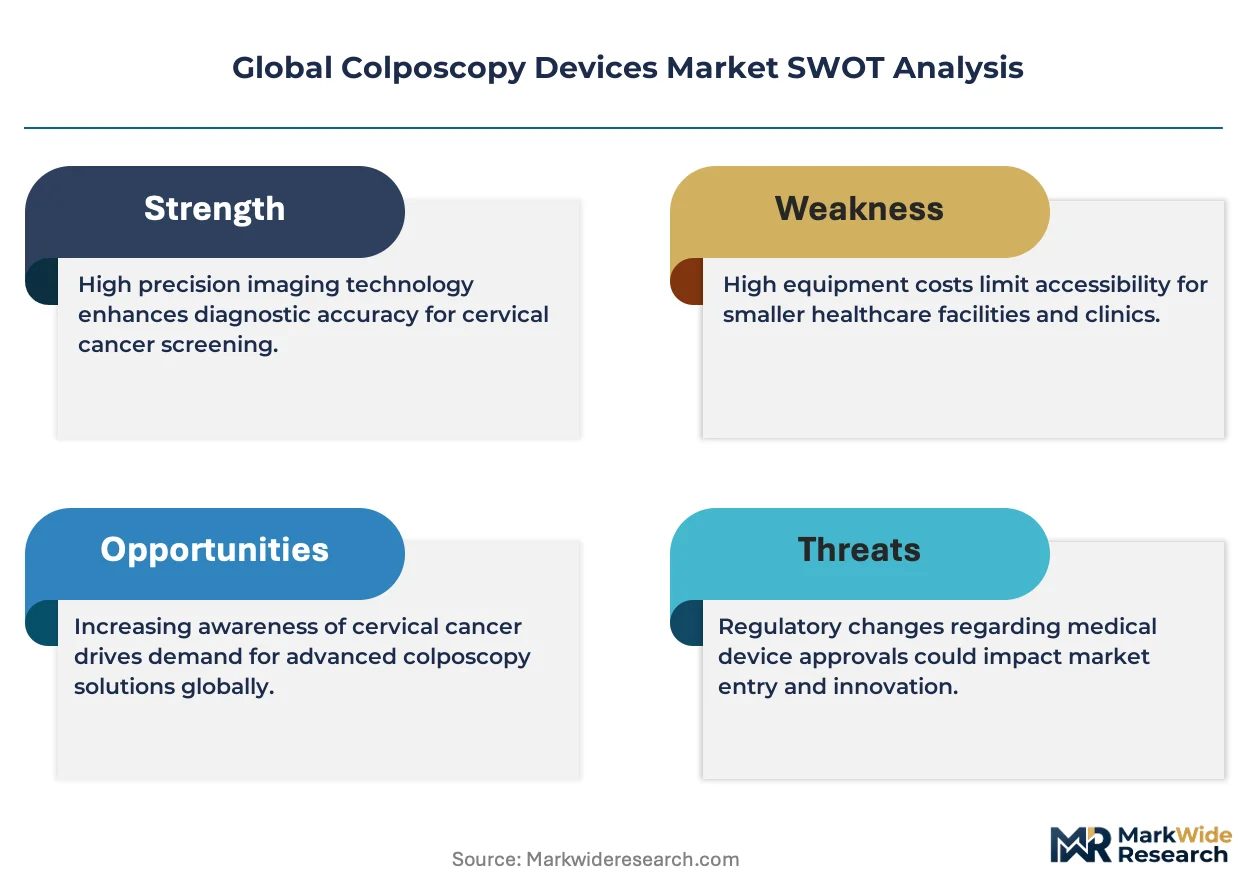
- Optical Component Concentration:Precision lens assemblies for high-magnification systems depend on German and Japanese specialty glass suppliers, creating vulnerability to export control friction.
- Reimbursement Code Lag:CMS and national health insurance schemes in France and Japan maintain legacy coding frameworks that do not separately compensate AI-enhanced colposcopy, compressing upgrade ROI.
- Pathologist Training Bottlenecks:Cervical cytology expertise concentrates in urban academic medical centers, limiting effective utilization of advanced imaging in distributed settings.
Strategic Opportunities
- Telemedicine Integration:Cloud-connected colposcopy architectures enable real-time specialist consultation for community health workers in Indonesia and Vietnam, opening subscription revenue streams.
- Point-of-Care Biopsy Systems:Miniaturized thermal ablation and loop excision devices paired with portable colposcopes create single-visit screening-treatment protocols for high-burden regions.
- CE-IVDR Certification Acceleration:The EU Medical Device Regulation's 2026 enforcement deadline for in vitro diagnostic software creates first-mover advantage for vendors with validated AI algorithms.
Industry Challenges
- Interoperability Fragmentation:Proprietary image formats from Olympus, Carl Zeiss Meditec, and Mindray block seamless integration with hospital information systems, forcing costly middleware development.
- Field Service Network Density:Precision optical alignment requires specialized technicians; sparse coverage in sub-Saharan Africa and Central Asia extends equipment downtime.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Colposcopy Devices Market |
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,442.58 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Colposcopes, Video Colposcopes, Traditional Optical Colposcopes, Binocular Colposcopes, Portable Colposcopes Application: Cervical Cancer Screening, Precancerous Lesion Detection, Post-treatment Follow-up, HPV Detection, Vaginal Disease Diagnosis End User: Gynecology Clinics, Women’s Health Centers, Diagnostic Laboratories, Specialty Hospitals, Private Practices Deployment: Stationary Units, Mobile Units, Cloud-Connected Devices, Standalone Systems, Integrated Workstations |
| Companies Covered | CooperSurgical, Inc., Carl Zeiss Meditec AG, Olympus Corporation, DYSIS Medical Limited, ATMOS MedizinTechnik GmbH & Co. KG, McKesson Medical-Surgical Inc., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., Karl Kaps GmbH & Co. KG, Leisegang Feinmechanik Optik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Colposcopy Devices Market Shifts & Advancements
Colposcopy device architecture is bifurcating between premium AI-integrated stationary systems for academic centers and ruggedized portable platforms for decentralized screening. This split is compressing mid-tier product viability.
Silicon CMOS sensors are replacing traditional CCD imagers in digital colposcope cameras. Community health programs in Kenya and Bangladesh are adopting CMOS-based units for their lower power draw and reduced heat generation. The shift is decomposing the historical premium attached to Japanese CCD supply chains.
MDR Article 10.4 software classification rules in the European Union now regulate AI diagnostic algorithms as medical devices in their own right. Vendors must submit clinical performance data for cervical lesion detection modules separately from hardware clearances. German notified bodies are experiencing 14-18 month queue times, delaying product launches.
Equipment-as-a-service contracts are displacing capital purchase models in US hospital systems facing constrained capital budgets. HCA Healthcare and Kaiser Permanente structures bundle colposcope hardware, maintenance, and AI software licenses into per-procedure fees. This reconfiguration concentrates vendor risk in utilization forecasting.
Global Colposcopy Devices Market Segmentation
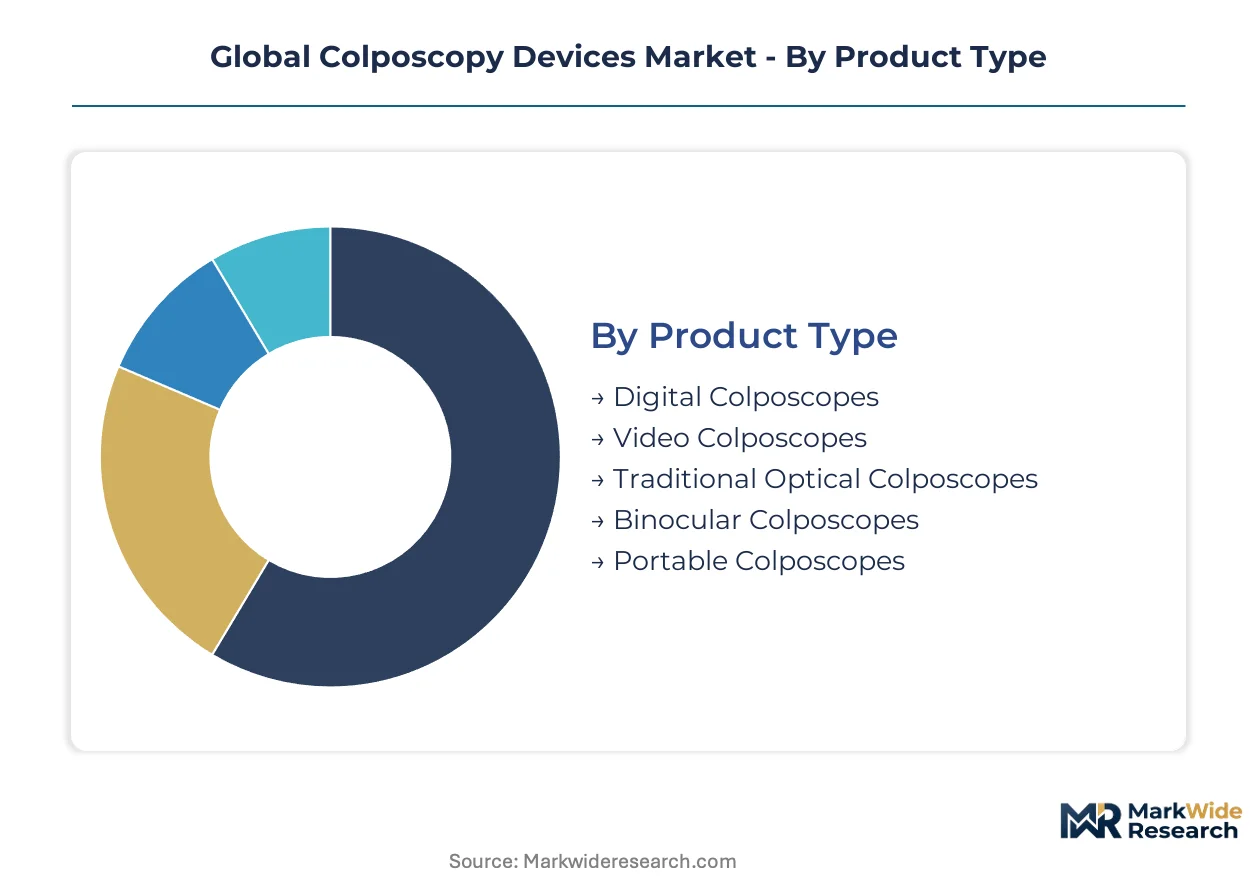
Colposcopy device procurement splits sharply between capital-intensive stationary installations in academic medical centers and volume-driven portable deployments for decentralized screening programs. Understanding these segment boundaries reveals where pricing power concentrates and where scale efficiencies dominate vendor selection.
Product Type:
Domestic production of optical-grade systems clusters in Germany and Japan, while portable and digital platforms increasingly source from contract manufacturers in China and India for export markets.
- Digital Colposcopes:CMOS sensor-based imaging systems with integrated image archiving and AI-ready firmware architectures. Demand concentrates in pathology laboratories across France and the United Kingdom seeking automated lesion classification workflows. WHO elimination targets are compressing replacement cycles for legacy optical systems.
- Video Colposcopes:Continuous-capture systems designed for high-throughput diagnostic laboratories requiring quality assurance documentation. Women's health centers in São Paulo and Mexico City prioritize these units for training resident physicians on vascular pattern recognition.
- Traditional Optical Colposcopes:Stereoscopic visualization systems with halogen or LED illumination sources remain standard in resource-constrained public health systems.
- Binocular Colposcopes:Dual-eyepiece configurations dominate European university hospital installations where teaching requirements mandate direct observer participation.
- Portable Colposcopes:Battery-powered lightweight chassis designs enable outreach screening in rural Kenya and Bangladesh.
Traditional optical systems command the established base. The steepest expansion runs through portable colposcopes.
Application:
Reimbursement coding frameworks determine which applications generate sustainable procedure economics versus which remain cost centers for health systems.
- Cervical Cancer Screening:Population-scale screening programs in India and Brazil drive volume procurement through national health ministry tenders. The 70% coverage mandate under WHO elimination targets is forcing infrastructure buildouts in primary care networks previously without colposcopy capacity.
- Precancerous Lesion Detection:Directed biopsy protocols for CIN2+ identification require high-magnification optical resolution. Academic medical centers in Germany and Switzerland prioritize premium systems for research-validated detection sensitivity.
- Post-treatment Follow-up:Surveillance protocols after LEEP or cone biopsy procedures generate recurring procedure volumes in US integrated delivery networks.
- HPV Detection:Triage of high-risk HPV-positive cytology creates demand for rapid-access colposcopy slots in UK NHS cervical screening program pathways.
- Vaginal Disease Diagnosis:Vulvar and vaginal intraepithelial neoplasia assessment represents a secondary application with limited dedicated reimbursement codes.
Cervical cancer screening absorbs the dominant share of installed base utilization. Post-treatment follow-up is gaining share fastest as survivorship protocols extend surveillance intervals.
End User:
Customer type determines whether procurement flows through centralized hospital capital committees or decentralized clinic operating budgets with constrained financing options.
- Gynecology Clinics:High-volume ambulatory settings in São Paulo and Mumbai are expanding colposcopy capacity to absorb screening program referrals. These clinics prioritize systems with rapid image capture and minimal maintenance requirements.
- Women's Health Centers:Dedicated screening facilities in Indonesia and Vietnam are adopting cloud-connected architectures to enable telemedicine consultation with distant specialists.
- Diagnostic Laboratories:Centralized pathology operations in France and Japan require integrated workstations with electronic medical record connectivity and DICOM compliance.
- Specialty Hospitals:Cancer centers in Germany and the United Kingdom deploy premium stationary systems for complex case management and resident training.
- Private Practices:Solo and small-group gynecology practices in the United States face capital constraints that favor equipment-as-a-service contract structures.
Diagnostic laboratories anchor the premium segment. Women's health centers are expanding most quickly as government screening programs outsource service delivery.
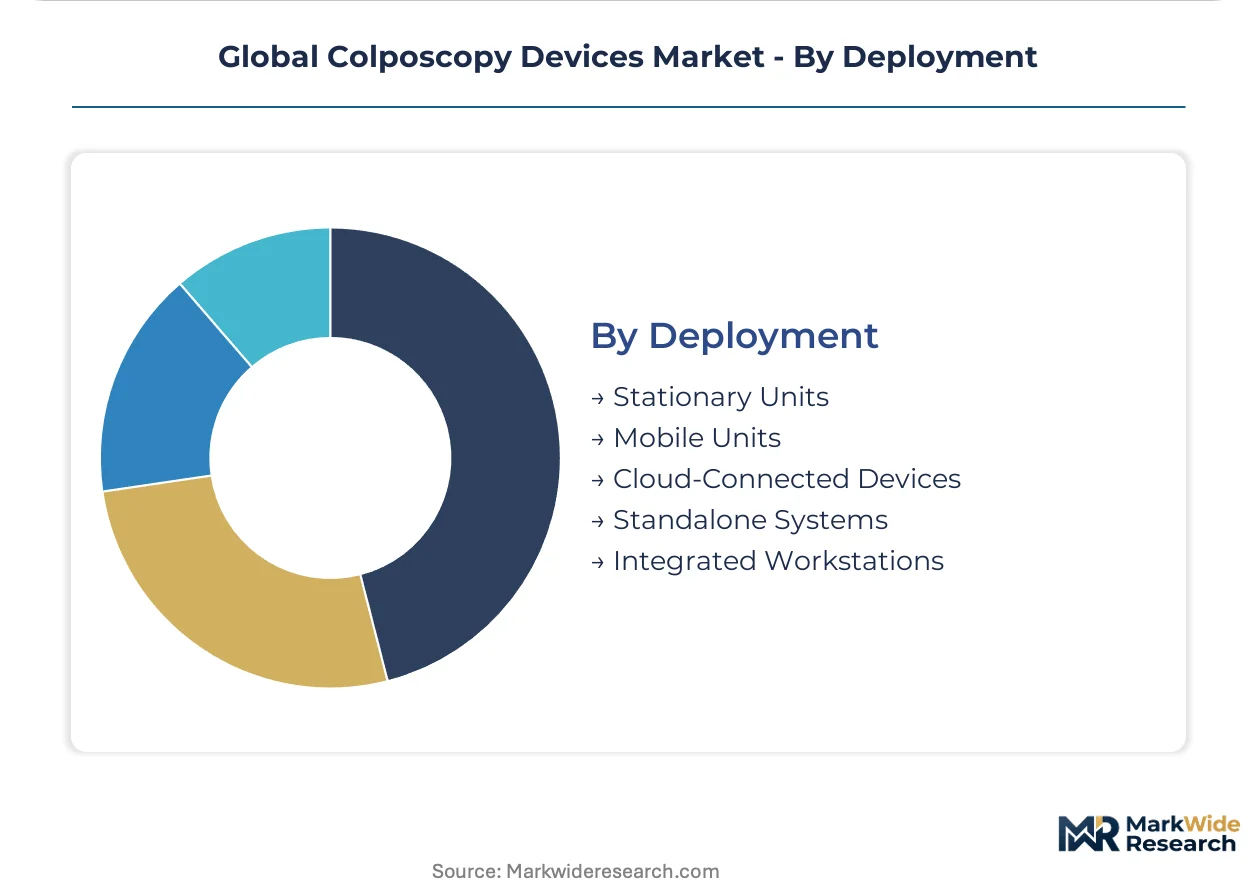
Deployment:
Architecture choices determine total cost of ownership through software licensing, maintenance contracts, and interoperability requirements with hospital information systems.
- Stationary Units:Permanent installation systems with precision optical benches and integrated examination chairs. University hospitals in Switzerland and Germany specify these for research-grade imaging requirements and teaching workflows.
- Mobile Units:Vehicle-mounted screening platforms serving rural catchment areas in Nigeria and Mexico where fixed infrastructure is unavailable. Battery and solar power configurations determine operational autonomy.
- Cloud-Connected Devices:Systems with real-time image transmission to centralized pathology review. Community health workers in Bangladesh and Kenya leverage these for quality assurance and specialist backup.
- Standalone Systems:Offline operation without network dependency suits facilities with unreliable connectivity in Central Asian republics.
- Integrated Workstations:Combined imaging, documentation, and treatment planning platforms with thermal ablation or LEEP compatibility. US hospital systems favor these for single-visit see-and-treat protocols.
Stationary units retain the largest installed base. Cloud-connected devices are climbing the fastest as telemedicine reimbursement frameworks mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in colposcopy devices reveal a pronounced asymmetry: German and Japanese precision optics manufacturers supply high-magnification lens assemblies globally, while portable digital platforms increasingly originate from contract manufacturers in China and India serving public health procurement channels in Latin America and Africa.
United States
FDA 510(k) clearance pathways govern market entry for optical diagnostic platforms, with CMS reimbursement codes shaping upgrade economics for digital colposcopy with AI adjunct analysis. Integrated delivery networks in Texas and Florida are consolidating colposcopy capacity into women's health centers. Equipment-as-a-service contracts are displacing capital purchases in hospital systems facing constrained budgets.
Germany
EMA Medical Device Regulation and CE-IVDR certification timelines are compressing product launch windows for AI-embedded diagnostic software. Precision optics manufacturing clusters in Jena and Oberkochen anchor global supply chains for high-magnification lens assemblies. University hospitals in Bavaria and Baden-Württemberg specify premium stationary systems for research-grade imaging and resident training protocols.
Brazil
ANVISA medical device registration requirements shape commercialization timelines for imported colposcopy platforms. The Ministry of Health's expansion of cervical cancer screening infrastructure under WHO elimination targets is driving volume procurement through national tenders. Gynecology clinics in São Paulo and Rio de Janeiro are scaling capacity to absorb referrals from primary care networks.
India
CDSCO medical device rules and the Ministry of Health's national cervical cancer screening mandates are expanding installed base requirements across primary care networks previously without colposcopy capacity. Women's health centers in Maharashtra and Karnataka are adopting cloud-connected architectures to enable telemedicine consultation with distant specialists. Domestic contract manufacturers are scaling portable digital platform production for export markets.
China
NMPA Class II medical device registration governs market entry for colposcopy systems, with GB standards compliance required for optical performance specifications. Public hospital procurement in Guangdong and Jiangsu provinces is prioritizing integrated workstation ecosystems with electronic medical record connectivity. Shenzhen-based manufacturers are anchoring volume-tier supply chains across Asia-Pacific and Latin American markets.
Global Colposcopy Devices Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D scale dimensions. The vendor base splits between consolidated precision optics heritage players and fragmented portable platform specialists. Three archetypes dominate: German-Japanese precision optics incumbents, Chinese volume-tier contract manufacturers, and AI-integrated digital platform innovators. Competitive moves concentrate on M&A for software capabilities and strategic partnerships for distribution reach in emerging markets.
Within the precision optics tier, Carl Zeiss Meditec AG and Olympus Corporation exemplify heritage positioning through integrated workstation ecosystems. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. occupies a scale-driven position in portable and digital platform supply chains. These three anchors illustrate the market's tripartite structure: premium stationary installations, mid-tier video systems, and emerging volume frontier devices for decentralized screening.
| Leading Market Players |
|---|
| CooperSurgical, Inc. |
| Carl Zeiss Meditec AG |
| Olympus Corporation |
| DYSIS Medical Limited |
| ATMOS MedizinTechnik GmbH & Co. KG |
| McKesson Medical-Surgical Inc. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| Karl Kaps GmbH & Co. KG |
| Leisegang Feinmechanik Optik GmbH |
| Others |
Supply & Pricing Matrix
CMOS sensor substitution for legacy CCD imagers is redrawing supply geography from Japanese precision glass corridors toward Shenzhen and Bangalore contract manufacturing clusters, collapsing component premiums while compressing procurement cycles for portable digital platforms. This displacement simultaneously erodes historical margin pools in optical-grade assemblies and unlocks volume-tier pricing for battery-powered outreach screening programs.
Pricing Analysis
Hospital purchasing committees and women's health center procurement officers anchor three-tier pricing stratification across premium stationary installations, mid-tier video systems, and economy portable units. Price differentiation hinges on FDA clearance tier and bundled AI software licensing, with academic medical centers absorbing premium positioning while rural outreach programs drive cost compression in battery-powered chassis. Pricing softness reflects equipment-as-a-service contract displacement of capital purchases in US integrated delivery networks. Public health ministries in Brazil and India exhibit highest price sensitivity; German university hospitals demonstrate lowest sensitivity due to research-grade imaging mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate precision optics assembly in Jena and Oberkochen, while strategic stockpiling of CMOS sensors and lithium battery packs characterizes portable platform manufacturers in Shenzhen and Dongguan. German and Japanese specialty glass suppliers feed high-magnification lens production, drawing from rare earth processing concentrated in China and refined optical coatings from South Korea. Single-source vulnerability in precision lens assemblies creates exposure to export control friction. Distribution runs through regional medical device distributors with hospital GPO contracts in developed markets and direct ministry tenders in public health procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The colposcopy devices market sits in early-cycle expansion as WHO cervical cancer elimination targets force infrastructure buildouts in primary care networks previously without screening capacity, compressing replacement timelines and opening greenfield installation opportunities.
For Market Incumbents: Compound defensive positioning through backward integration into AI algorithm development and captive CMOS sensor sourcing from Shenzhen contract manufacturers. Carl Zeiss Meditec and Olympus must secure CE-IVDR certification acceleration for embedded diagnostic software before EU enforcement deadlines, while defending premium stationary installations against portable platform erosion in emerging market tenders. Channel control through exclusive GPO contracts with US hospital systems remains the critical lever.
For New Entrants and Emerging Players: Anchor in cloud-connected portable platforms for community health worker deployment in Indonesia, Vietnam, and Bangladesh where telemedicine reimbursement frameworks are maturing. The most penetrable white space sits in single-visit screening-treatment protocols combining miniaturized thermal ablation with battery-powered colposcopy. A direct-to-ministry tender strategy bypassing established distributor networks unlocks volume procurement in Nigeria and Kenya.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed AI imaging specialists holding validated cervical lesion detection algorithms but lacking hardware manufacturing scale. Five-to-ten year viability hinges on reimbursement code expansion for AI-enhanced procedures across CMS and European national health insurance schemes. The signal to watch is FDA breakthrough device designation for autonomous lesion classification modules, which would trigger consolidation premiums for algorithm-first vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVDR Certification Acceleration | German notified body queue times of 14-18 months create first-mover advantage for validated AI algorithms. |
| Hospital System Partnership | HCA Healthcare and Kaiser Permanente equipment-as-a-service contracts concentrate vendor risk in utilization forecasting. |
| Software Companion Development | Machine learning firmware embedding enables automated pattern recognition for pathology laboratory workflow integration. |
| Reimbursement Strategy | CMS code revision for AI-enhanced colposcopy determines whether technology upgrades translate into sustainable procedure economics. |
| Geographic Expansion | ANVISA registration acceleration captures Brazilian Ministry of Health tender volume under WHO elimination targets. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with gynecology clinic directors, hospital biomedical engineers, pathology laboratory managers, and medical device procurement officers at GPOs and national health ministries. Secondary validation drew from FDA 510(k) clearance databases, EMA medical device registration filings, WHO cervical cancer elimination framework documentation, and hospital procurement contract disclosures. Bottom-up installed base estimates triangulated against top-down health system expenditure flows.
Across the analysis window, the forecasting framework modeled segmentation dimensions spanning product architecture, deployment configuration, end-user facility type, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to screening coverage mandates, replacement cycle compression rates, and AI integration adoption curves. Specific inputs included national cervical cancer screening program budget allocations, telemedicine reimbursement code expansion timelines, and precision optics component lead time fluctuations.
Decision-makers should treat outputs as directional under base assumptions of sustained WHO elimination target commitment and stable medical device regulatory pathways; material deviation would warrant model refresh. Revision becomes warranted when AI diagnostic algorithm reimbursement classification crosses threshold clarity in major markets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Ophthalmic Devices Market
Medical Devices
Smart Stairlift Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Cranial Perforator Market
Medical Devices
Cervical Disc Prosthesis Market
Medical Devices
Bowel Irrigation System Market
Medical Devices
Autorefractor Keratometer Market
Medical Devices
Intravaginal Device Market
Medical Devices
Global Joint Replacement Device Market
Medical Devices
Global Capnography Market
Medical Devices
Global Transcatheter Pulmonary Valve Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Electrosurgical Generators Market
Medical Devices
Global Surgical Polypropylene Mesh Market
Medical Devices
Global Extremities Market
Medical Devices
China General Surgical Devices Market