
 Clinical Chemistry Market | 2026-2036
Clinical Chemistry Market Size, Share, and Industry Trends Forecast 2026-2036
Clinical Chemistry Market Intelligence
A widening capital-intensity gap between installed-base incumbents and modular newcomers is bifurcating competitive dynamics in clinical chemistry. F. Hoffmann-La Roche Ltd. anchors its position through captive reagent ecosystems that lock in analyzer placements across centralized labs. Siemens Healthineers AG competes by leveraging imaging-to-laboratory workflow integration that reduces total cost of ownership for health system buyers. Thermo Fisher Scientific Inc. extends its reach through distribution density in research institutes where grant-funded instrument purchases favor flexible financing terms.
Clinical chemistry encompasses quantitative biochemical analysis of blood, serum, plasma, and urine specimens using photometric, electrochemical, and immunoturbidimetric detection principles, typically operating through automated analyzer-reagent systems that process 400–1,600 tests per hour for diagnostic decision support. Reagents constitute the largest recurring revenue pool as consumable attachment rates exceed 85% on closed-system analyzers, while software platforms represent the fastest-expanding margin layer as laboratories seek middleware for quality control and turnaround-time optimization. Diagnostic laboratories dominate end-user demand, though veterinary clinics are emerging as a structurally underpenetrated channel where simplified menu breadth lowers entry barriers.
The FDA's quality system regulation and Clinical Laboratory Improvement Amendments shape instrument validation and personnel certification requirements, while the EU In Vitro Diagnostic Regulation mandates notified-body conformity assessment that extends time-to-market for reagent manufacturers. ISO 15189 accreditation standards drive continuous quality management investments among diagnostic laboratories seeking recognition. Stakeholders must monitor evolving premarket submission pathways and reimbursement coding alignment as laboratory budgets tighten under value-based care contracts.
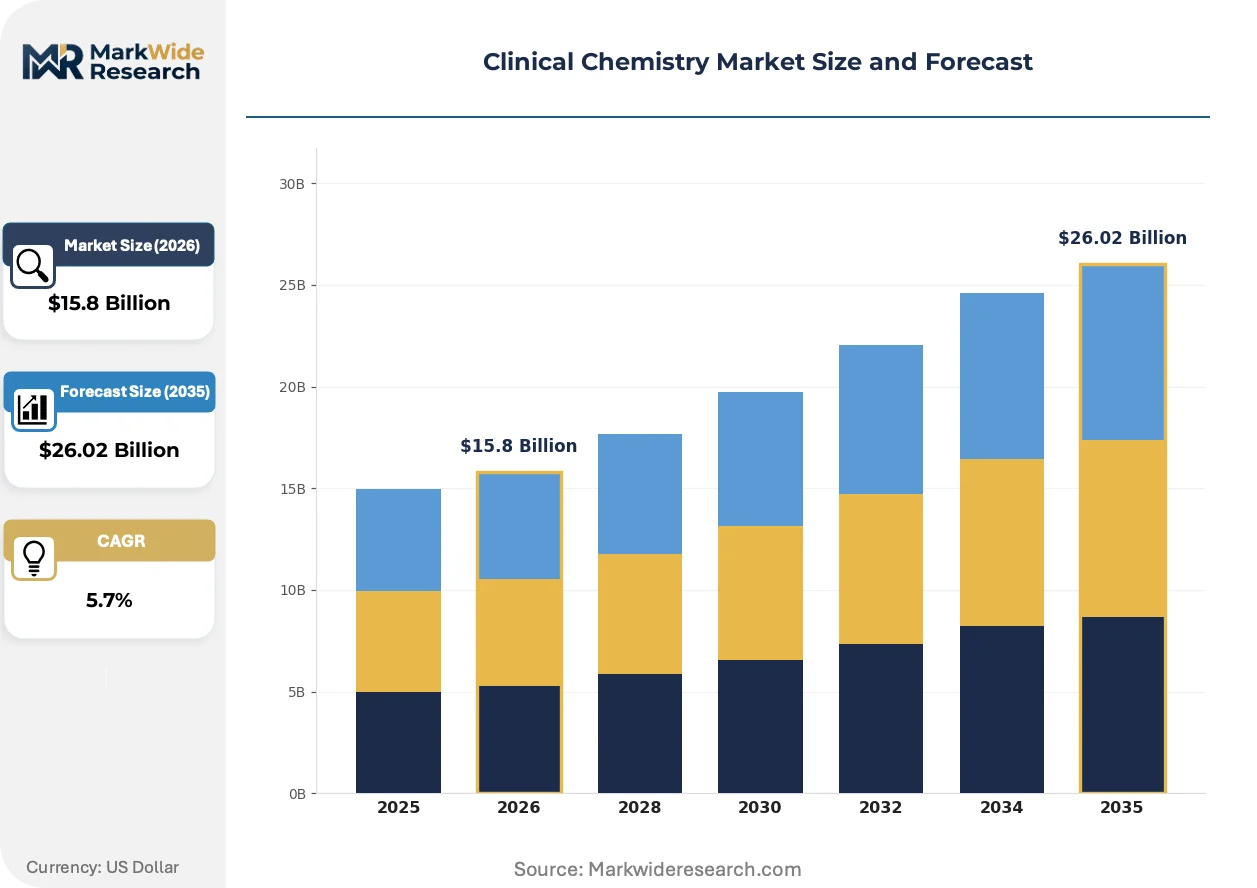
Market Dynamics
Automated analyzer throughput compression is reshaping capital deployment across clinical chemistry, as laboratories consolidate testing lines to offset reimbursement compression under value-based care contracts.
Growth Catalysts
- CLIA personnel certification requirements:The FDA's Clinical Laboratory Improvement Amendments mandate certified technicians for high-complexity testing, institutionalizing demand for training-supported analyzer platforms.
- Point-of-care expansion:Hospital emergency departments are deploying compact chemistry systems to reduce central lab turnaround times for critical care decision-making.
- ISO 15189 accreditation standards:Diagnostic laboratories in Germany and France pursue continuous quality management certification to secure health network contracts.
Market Restraints
- Reagent supply concentration:Captive reagent ecosystems on closed-system analyzers lock buyers into single-source consumable procurement.
- EU IVDR conformity timelines:Notified-body assessment requirements extend time-to-market for reagent manufacturers by 12-24 months.
- Optical component input costs:Photometric detection systems depend on specialized light sources subject to semiconductor supply volatility.
Strategic Opportunities
- Veterinary diagnostic channel:Simplified menu breadth on compact analyzers lowers entry barriers for companion animal clinics.
- Middleware quality control convergence:Software platforms integrating laboratory information systems with analyzer diagnostics create new margin layers.
- Integrated health network procurement consolidation:United States health systems are centralizing laboratory capital budgets under single-vendor frameworks.
Industry Challenges
- Multiplexing assay development complexity:Combining chemistries on single test panels requires extensive cross-reactivity validation.
- Analyzer-reagent interoperability certification:Third-party reagent manufacturers face compatibility testing costs for open-system placements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clinical Chemistry Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $26.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analyzers, Reagents, Controls, Software Platforms Application: Metabolic Panel, Cardiac Markers, Liver Function, Kidney Function, Endocrinology End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Veterinary Clinics Technology: Photometric, Electrochemical, Immunoturbidimetric, Chromatographic |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd., Siemens Healthineers AG, Thermo Fisher Scientific Inc., Danaher Corporation, HORIBA Ltd., Shenzhen Mindray BioMedical Electronics Co. Ltd., Sysmex Corporation, Bio-Rad Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clinical Chemistry Market Strategic Shifts & Innovations
Detection platform miniaturization and regulatory pathway fragmentation are compressing product development cycles while expanding addressable testing venues beyond traditional laboratory infrastructure.
Microfluidic cartridge technology is miniaturizing sample processing volumes from milliliters to microliters while preserving analytical precision. Physician office laboratories and urgent care chains are adopting these systems to bypass central lab logistics. This footprint reduction is miniaturizing the economic threshold for chemistry testing into ambulatory settings previously served by reference laboratories.
The EU In Vitro Diagnostic Regulation's risk-classification restructure redefines clinical evidence requirements for quantitative chemistry assays. Manufacturers must generate clinical performance data for moderate-risk reagents previously cleared through self-certification. Reagent producers targeting European diagnostic laboratories are restructuring quality management systems to accommodate notified-body surveillance audits.
Health system capital committees are bundling analyzer procurement with multi-year reagent supply commitments and service contracts. This total-cost-of-ownership framing displaces standalone instrument purchases in United States integrated delivery networks. The shift pressures independent distributors and elevates direct manufacturer relationships with procurement executives.
Clinical Chemistry Market Segmentation
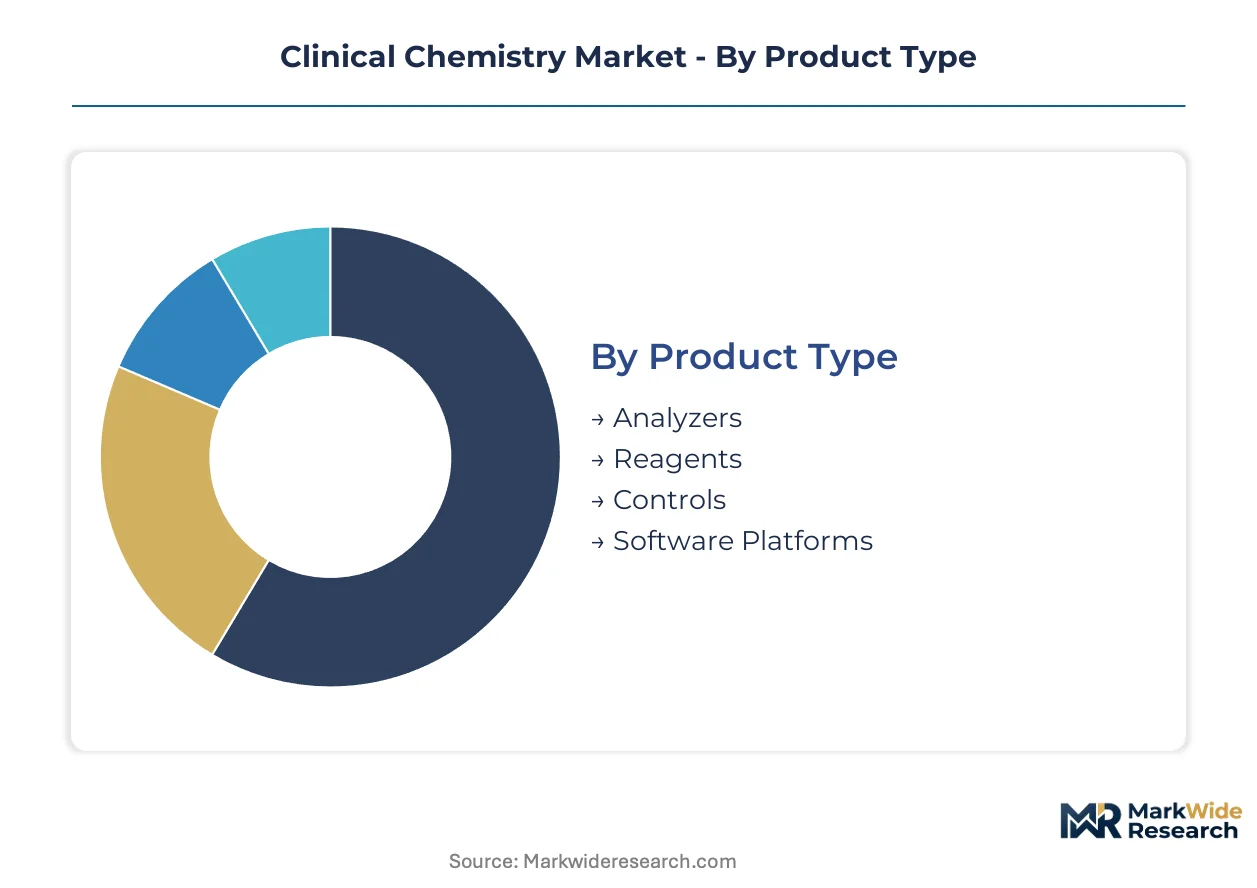
Segmentation in clinical chemistry reveals how capital deployment, consumable attachment rates, and regulatory pathways diverge across product configurations and testing venues. Laboratories prioritize segments that compress turnaround times while satisfying CLIA personnel requirements and ISO 15189 quality mandates.
Product Type:
Domestic procurement dominates analyzer placements in United States hospital laboratories, while reagent exports flow to European diagnostic networks navigating EU IVDR conformity timelines.
- Analyzers:Automated systems process 400–1,600 tests per hour through photometric and electrochemical detection modules. United States integrated health networks consolidate capital budgets under single-vendor frameworks that bundle multi-year service contracts with instrument procurement.
- Reagents:Consumable attachment rates exceed 85% on closed-system analyzers, creating recurring revenue pools that lock buyers into captive supply ecosystems. German and French laboratories pursue continuous quality management certification to secure health network contracts.
- Controls:Quality control materials validate analyzer precision across testing menus. Reference laboratories in research institutes favor flexible financing terms for grant-funded purchases.
- Software Platforms:Middleware integrates laboratory information systems with analyzer diagnostics for turnaround-time optimization. Physician office laboratories adopt these systems to bypass central lab logistics.
Analyzers hold the largest share; momentum sits with software platforms.
Application:
Cost tier stratification separates high-volume screening panels from specialized cardiac and endocrine assays that command premium reimbursement coding.
- Metabolic Panel:Standardized glucose, electrolyte, and renal function chemistries comprise the highest test volume in diagnostic laboratories. United States health systems centralize procurement for these high-frequency assays under value-based care contracts.
- Cardiac Markers:Troponin and BNP quantification demands rapid turnaround for emergency department decision-making. Hospital emergency departments deploy compact chemistry systems to reduce central lab response times.
- Liver Function:Enzyme and protein panels assess hepatic synthetic capacity. Veterinary clinics are emerging as a structurally underpenetrated channel where simplified menu breadth lowers entry barriers.
- Kidney Function:Creatinine and blood urea nitrogen monitoring supports chronic disease management. Blood banks utilize these assays for donor screening protocols.
- Endocrinology:Hormone quantification requires specialized calibration curves and extended analytical ranges. Research institutes drive demand for flexible assay configurations in grant-funded studies.
Metabolic panels dominate test volume; cardiac markers are climbing the fastest.
End User:
Customer type determines financing structure, with diagnostic laboratories favoring reagent rental agreements and research institutes prioritizing capital purchase flexibility.
- Diagnostic Laboratories:Centralized and hospital-affiliated labs process the majority of clinical chemistry test volume. ISO 15189 accreditation standards drive continuous quality management investments among these facilities seeking recognition.
- Research Institutes:Grant-funded instrument purchases favor flexible financing terms and open-system configurations. Distribution density in these accounts extends manufacturer reach beyond clinical settings.
- Blood Banks:Donor screening and component testing require high-throughput platforms with specialized infectious disease assay compatibility.
- Veterinary Clinics:Companion animal diagnostics represent a structurally underpenetrated channel. Simplified menu breadth on compact analyzers lowers entry barriers for these practices.
Diagnostic laboratories command the largest share; veterinary clinics represent the steepest expansion trajectory.
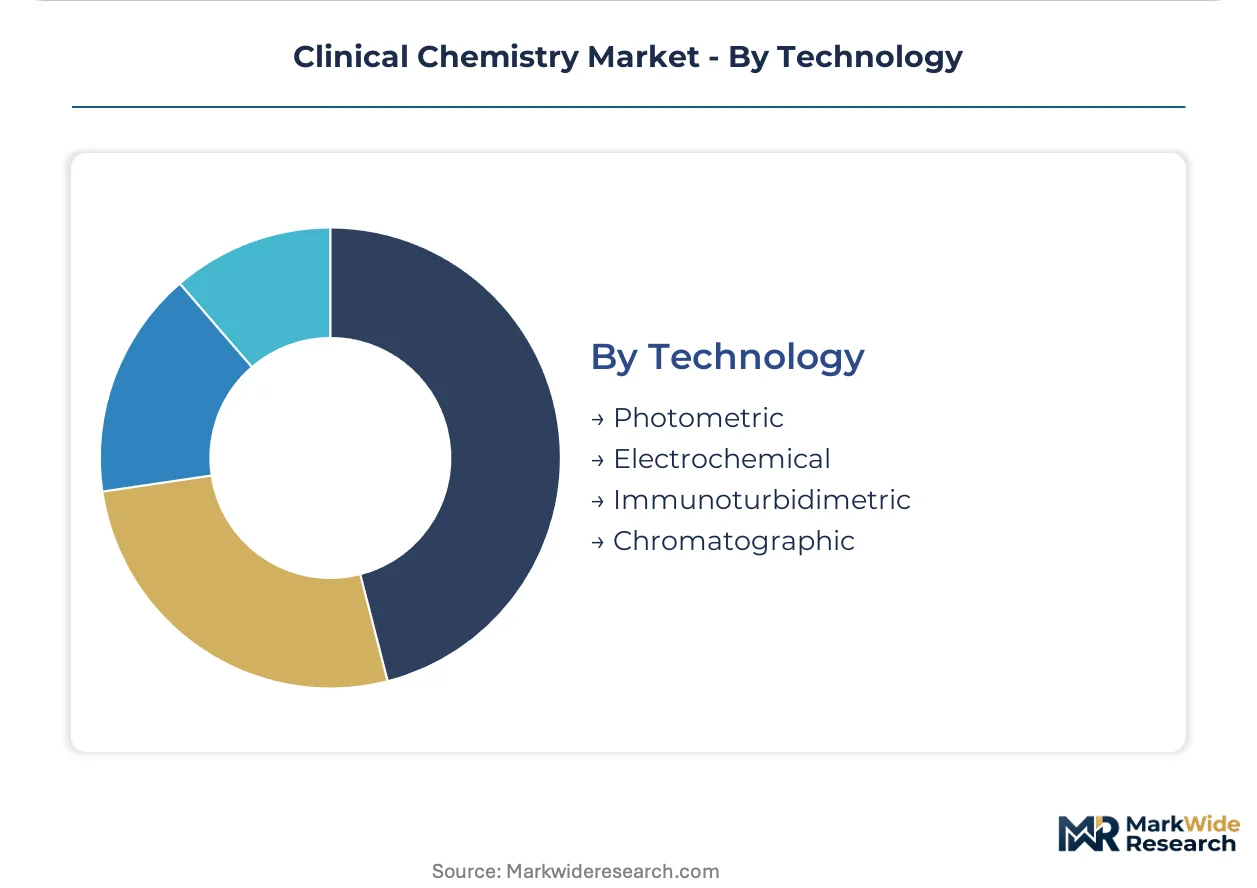
Technology:
Supply concentration in optical component manufacturing creates input cost volatility for photometric systems, while electrochemical platforms benefit from semiconductor process maturity.
- Photometric:Absorbance-based detection at specific wavelengths quantifies chromogenic reactions. Specialized light sources subject to semiconductor supply volatility elevate manufacturing cost exposure.
- Electrochemical:Ion-selective electrodes measure potentiometric signals for electrolyte and blood gas analysis. These platforms achieve higher reagent stability and reduced calibration frequency.
- Immunoturbidimetric:Light scattering quantifies antigen-antibody complexes for protein and therapeutic drug monitoring. Cross-reactivity validation requirements extend development timelines for multiplexed panels.
- Chromatographic:Separation-based methods resolve complex matrices for specialized toxicology and endocrine applications. Research institutes utilize these systems for reference method development.
Photometric detection holds the largest installed base; immunoturbidimetric methods are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospital laboratories demonstrate the lowest price elasticity as integrated health networks consolidate procurement under single-vendor frameworks, while veterinary clinics in emerging markets exhibit high sensitivity to analyzer capital costs. European diagnostic laboratories navigate extended regulatory timelines that compress margin structures. Asian manufacturers compete aggressively on reagent pricing to penetrate price-conscious decentralized testing venues.
United States
Integrated delivery networks in Texas and California centralize laboratory capital budgets under multi-year reagent supply commitments bundled with service contracts. FDA premarket review pathways for in vitro diagnostic devices shape product development timelines for manufacturers targeting hospital emergency departments deploying compact chemistry systems. The Boston-Cambridge corridor hosts research institutes driving grant-funded instrument purchases favoring flexible financing terms.
Germany
Diagnostic laboratories in Bavaria and North Rhine-Westphalia pursue ISO 15189 accreditation standards to secure health network contracts and demonstrate continuous quality management. EU In Vitro Diagnostic Regulation mandates notified-body conformity assessment that extends time-to-market for reagent manufacturers by 12-24 months. The Rhine-Main cluster around Frankfurt concentrates reference laboratory capacity serving centralized testing for regional hospital systems.
China
Domestic manufacturers in Shenzhen and Shanghai compete on analyzer pricing to displace imported systems in provincial hospital laboratories managing higher sample throughput. NMPA regulatory pathways for in vitro diagnostic devices require clinical performance data generation that lengthens registration timelines for multinational reagent producers. The Yangtze River Delta medical device manufacturing base supplies photometric detection components subject to semiconductor supply volatility.
Japan
Metropolitan Tokyo and Osaka diagnostic laboratories prioritize analyzer-reagent interoperability certification to maintain quality control alignment with international accreditation standards. PMDA quality system regulations govern instrument validation requirements for automated testing lines processing 400-1,600 tests per hour. The Kansai biomedical cluster supports specialized endocrinology assay development requiring extended analytical ranges for hormone quantification.
India
Diagnostic laboratory chains in Maharashtra and Karnataka expand automated testing capacity to capture outpatient volume from consolidating hospital networks. CDSCO regulatory frameworks for medical devices establish import licensing requirements that filter analyzer placements toward established distribution partnerships. The Delhi-NCR corridor concentrates reference laboratory infrastructure serving northern Indian states with limited in-house chemistry testing capability.
Clinical Chemistry Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in clinical chemistry, with full-system providers controlling captive reagent ecosystems while modular newcomers compete on flexible procurement terms. The upper tier commands analyzer placements through multi-year consumable lock-in exceeding 85% attachment rates on closed-system configurations. Mid-scale specialists concentrate on open-system reagent compatibility and middleware software integration. Dominant competitive moves include strategic partnerships with health system procurement committees and geographic expansion through distribution density in research-intensive clusters.
Among Switzerland-based and Germany-anchored integrated diagnostics groups, F. Hoffmann-La Roche Ltd. and Siemens Healthineers AG exemplify the full-system archetype through captive reagent ecosystems and imaging-to-laboratory workflow integration respectively. Thermo Fisher Scientific Inc. occupies a position representing distribution-scale specialists extending reach through research institute relationships. These three entities anchor competitive dynamics as laboratories consolidate vendor relationships under total-cost-of-ownership frameworks.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd. |
| Siemens Healthineers AG |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| HORIBA Ltd. |
| Shenzhen Mindray BioMedical Electronics Co. Ltd. |
| Sysmex Corporation |
| Bio-Rad Laboratories Inc. |
| Others |
Cost & Logistics Intelligence
Installed-base scale economies on high-throughput analyzers concentrate manufacturing among a handful of captive-reagent producers, compressing price floors for modular newcomers while elevating margin capture for incumbents bundling multi-year consumable commitments. This concentration dynamics locks hospital laboratories into single-source procurement frameworks that resist pure price competition.
Pricing Analysis
After-sales service contracts and reagent rental tiers drive lifetime value beyond instrument placement, with three-tier pricing structure across premium, standard, and economy levels differentiating by test-menu breadth and ISO 15189 certification alignment. Price differentiation hinges on closed-system consumable attachment rates exceeding 85% and geographic density of field service engineers. Cost compression in standard-tier placements is intensifying because Chinese manufacturers compete aggressively on analyzer capital costs. Veterinary clinics exhibit highest price sensitivity; United States integrated health networks demonstrate lowest elasticity due to bundled total-cost-of-ownership frameworks.
Supply Chain Analysis
Photometric light-source manufacturing concentrates in the Yangtze River Delta, where specialized semiconductor foundries anchor optical component supply for automated detection modules. German and Japanese precision optics producers feed chromatographic and immunoturbidimetric system assembly. Raw material dependencies span rare-earth phosphors for wavelength calibration, ion-selective electrode membranes, and chromatographic-grade solvents. Single-source vulnerability in semiconductor-grade photodiodes exposes manufacturers to foundry allocation volatility. Distribution runs through direct manufacturer relationships with health system procurement committees, displacing independent distributors in United States integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical chemistry rewards service-attach strategies because middleware software platforms and quality-control subscriptions expand recurring-revenue pools faster than hardware replacement cycles. Laboratories prioritize turnkey solutions that compress turnaround times while satisfying personnel certification mandates.
For Market Incumbents: Shield analyzer placements by deepening captive reagent ecosystems and extending multi-year service contracts that raise switching costs for hospital laboratories. Consolidate position through ISO 15189 accreditation support programs that lock in quality-management consulting revenue. Counter modular newcomers by bundling imaging-to-laboratory workflow integration that reduces total cost of ownership for health system buyers. For New Entrants and Emerging Players: Middleware interoperability gaps where incumbents under-serve open-system configurations present white-space entry points for laboratory information system integration specialists. Veterinary diagnostic channels offer lowest competitive density and simplified regulatory pathways compared to human clinical laboratories. Pursue grant-funded research institute placements with flexible financing terms that circumvent capital-committee procurement consolidation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among reagent manufacturers with closed-system analyzer placements exceeding 85% attachment rates, suggesting superior cash-flow quality in full-system providers over modular component suppliers. Target acquisition archetypes include software platforms integrating quality control with laboratory information systems. Watch FDA premarket review pathway streamlining as inflection signal for reagent manufacturer margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Ecosystem Lock-In | Captive consumable contracts on closed-system analyzers secure recurring revenue exceeding 85% attachment rates. |
| Middleware Platform Development | Laboratory information system integration creates software margin layers for turnaround-time optimization. |
| ISO 15189 Accreditation Support | Quality management consulting services deepen customer relationships in German and French diagnostic networks. |
| Veterinary Channel Expansion | Simplified menu breadth on compact analyzers penetrates structurally underpenetrated companion animal clinics. |
| EU IVDR Compliance Infrastructure | Notified-body relationship investments accelerate time-to-market for moderate-risk reagent clearances. |
Research Approach
Desk research of FDA 510(k) filings, EU IVDR notified-body assessment records, and hospital procurement databases preceded structured interviews with clinical laboratory directors, biomedical equipment procurement managers, and in vitro diagnostic regulatory affairs specialists. Secondary validation drew from ISO 15189 accreditation body reports, GPO contract repositories, and CMS Medicare laboratory fee schedule data. Analysts triangulated bottom-up instrument placement counts with top-down reagent revenue estimates.
Variance decomposition across product type, application, end user, technology, and geographic regulatory cluster informed the analytical framework over the projection horizon. Segmentation dimensions modeled include analyzer throughput tier, test-menu breadth, closed versus open system configuration, and health system integration level. CAGRs derived from installed-base growth rates multiplied by consumable attachment assumptions, with price trajectory inputs calibrated to reimbursement compression under value-based care contracts.
Forecasts assume regulatory continuity in FDA quality system regulation and EU IVDR notified-body assessment regimes; material policy shifts would require re-modeling of time-to-market assumptions for reagent manufacturers. Scenario risks include semiconductor supply volatility affecting photometric detection component availability and CLIA personnel certification requirement modifications. Practitioners should keep alternative scenarios live as integrated health network procurement consolidation patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Tumor Marker Testing Market
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
Cytomegalovirus Assay Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Chronic Hepatitis B Virus Testing Market
Clinical Diagnostics
Nitric Oxide Asthma Testing Market
Clinical Diagnostics
Global Cardiac Marker Testing Market
Clinical Diagnostics
Kidney Function Tests Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Circulating Biomarkers Market