
 Cytology Brush Market | 2026-2036
Cytology Brush Market Size, Share, and Industry Trends Forecast 2026-2036
Cytology Brush Market Analysis
EU MDR compliance is hardening material traceability and biocompatibility requirements for cytology brushes entering European clinical channels. Boston Scientific Corporation leverages its endoscopy ecosystem to sustain bundled instrument placement across hospital systems. Cook Medical anchors its position through specialized brush geometries for pulmonary and gastrointestinal sampling. Olympus Corporation dominates the Japanese and Asia-Pacific supply corridors with vertically integrated bronchoscope-compatible designs.
A cytology brush is a slender, flexible sampling instrument with bristles composed of nylon, plastic, or metal filaments affixed to a distal tip, engineered to harvest cellular material from mucosal surfaces during endoscopic or non-endoscopic procedures for pathological examination. Disposable brushes command the largest revenue share due to infection control mandates and elimination of reprocessing liability, while specialized brushes for targeted lesion sampling capture premium pricing through customized tip configurations. Nylon bristle variants lead volume production for their balance of cell yield and tissue trauma minimization, whereas silicone-coated designs are gaining fastest in research institute settings for delicate cytological preservation.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for brush manufacturers. ISO 13485 quality management standards and biocompatibility testing under ISO 10993 further constrain material selection and supplier qualification processes. Stakeholders must monitor evolving sterilization validation protocols and single-use plastic reduction mandates as these forces reshape procurement criteria across hospital and laboratory buyers.
Market Dynamics
Single-use plastic reduction mandates across European and North American health systems are forcing material substitution in cytology brush manufacturing, compressing profit margins for nylon-dependent suppliers while creating first-mover advantages for biopolymer innovators.
Growth Catalysts
- EU MDR compliance deadlines:Hospital procurement departments in Germany, France, and Italy are accelerating replacement cycles for legacy brush inventories to meet biocompatibility documentation requirements.
- Pulmonary screening expansion:United States hospital systems are embedding bronchoscopy-compatible cytology brushes into lung cancer early-detection protocols.
- Nylon bristle optimization:Cell yield engineering is advancing through laser-cut filament geometries that reduce tissue trauma during endoscopic sampling.
Market Restraints
- Petrochemical feedstock volatility:Nylon polymer prices fluctuate with crude oil indices, squeezing margin predictability for disposable brush manufacturers.
- Specialized supplier concentration:Medical-grade filament extrusion capacity clusters in Germany and Japan, creating single-source vulnerability for brush assemblers.
- Reprocessing liability persistence:Reusable brush categories face ISO 17664 sterilization validation burdens that extend regulatory timelines.
Strategic Opportunities
- Indian diagnostic network expansion:Tier-2 and Tier-3 cities are building pathology infrastructure that demands cost-optimized disposable sampling instruments.
- Biodegradable polymer certification:ASTM F6400 and EN 13432 compostability standards offer premium positioning for cellulose-derived brush substrates.
- Direct-to-laboratory e-commerce channels:Specialized distributors are bypassing hospital procurement intermediaries to serve independent pathology clinics.
Industry Challenges
- Polymer science talent scarcity:Medical device manufacturers compete with packaging and automotive sectors for biopolymer formulation specialists.
- ISO 10993-5 cytotoxicity testing backlog:Contract laboratories in the United States and Europe report six-month queues for biocompatibility certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cytology Brush Market |
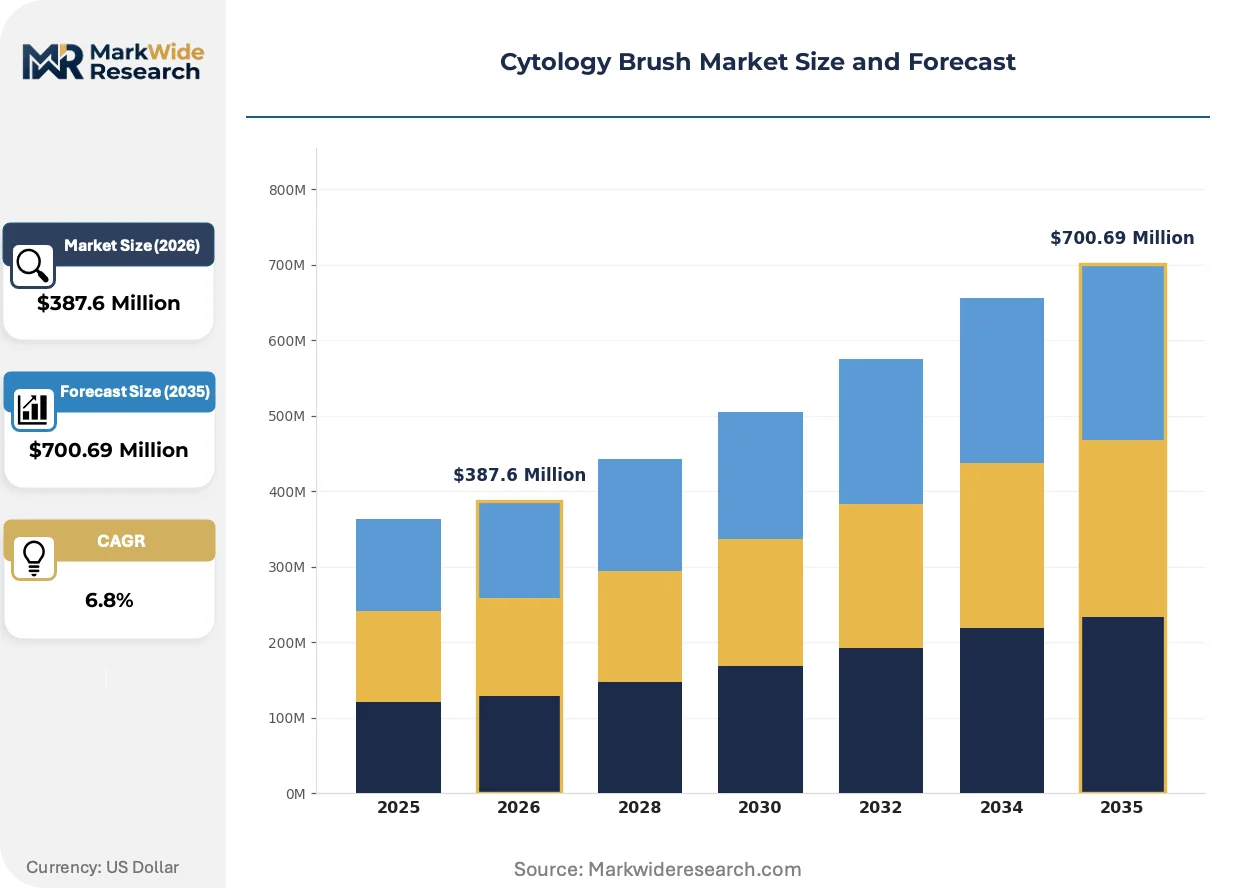
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Disposable Brushes, Reusable Brushes, Specialized Brushes, Customized Brushes End User: Hospitals, Diagnostic Laboratories, Research Institutes, Outpatient Clinics Application: Cancer Screening, Infectious Disease Diagnosis, Routine Checkups, Research Studies Material: Plastic, Nylon, Metal, Silicone |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, Cook Medical, Becton, Dickinson and Company, Thermo Fisher Scientific, ConMed Corporation, Hologic, Inc., U.S. Endoscopy, Teleflex Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cytology Brush Market Emerging Trajectories
Digital pathology integration is compressing the specimen-to-diagnosis timeline, forcing brush manufacturers to engineer collection devices that preserve cellular morphology for automated image analysis systems.
Robotic-assisted bronchoscopy platforms are automating lesion targeting precision, reducing operator-dependent sampling variability in pulmonary cytology. United States academic medical centers are deploying these systems at accelerating rates, creating demand for brush geometries that interface with robotic instrument channels. The technology is automating standardization of cell collection volumes that previously required manual technique calibration.
EU MDR technical documentation requirements are extending product registration timelines for brush manufacturers seeking European market access. The regulation demands comprehensive biocompatibility testing cascades and post-market surveillance protocols that inflate compliance costs. Small-to-mid-sized brush assemblers without captive regulatory affairs teams are outsourcing CE marking preparation to specialized consultancies in Ireland and Switzerland.
Consolidated purchasing organizations in the United States are unbundling cytology brush procurement from endoscope maintenance contracts. Hospital systems in Texas, California, and New York are establishing standalone vendor qualification programs that prioritize unit-cost reduction over bundled service relationships. This behavioral shift is compressing pricing power for manufacturers that historically relied on ecosystem lock-in.
Cytology Brush Market Segmentation
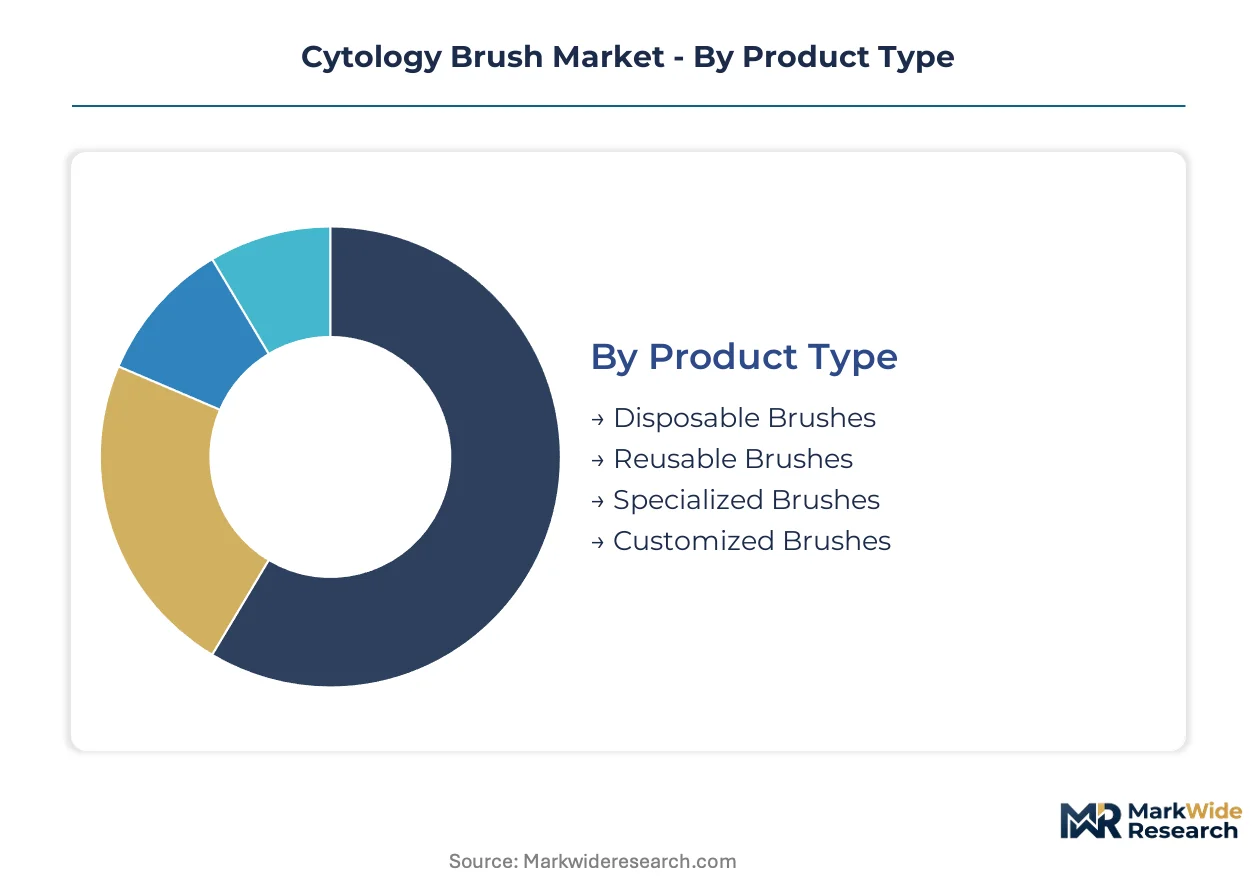
Segmentation in cytology brush procurement reflects divergent risk tolerances across clinical settings. Infection control mandates, sample volume requirements, and regulatory documentation burdens shape purchasing patterns differently across hospital systems versus independent laboratories.
Product Type:
Hospital procurement departments prioritize liability elimination and reprocessing cost avoidance when selecting brush formats.
- Disposable Brushes:Single-use nylon or plastic filament designs eliminate sterilization validation burdens and cross-contamination liability. United States health systems are mandating disposables across bronchoscopy suites to satisfy Joint Commission infection control audits.
- Specialized Brushes:Custom-tip geometries target lesion-specific sampling in pulmonary and gastrointestinal applications. Academic medical centers in Germany and Japan specify these for robotic-assisted bronchoscopy platforms where precision targeting justifies premium positioning.
- Reusable Brushes:Metal filament variants endure repeated sterilization cycles for cost-constrained pathology networks. Reprocessing documentation requirements under ISO 17664 constrain adoption to facilities with captive sterilization infrastructure.
- Customized Brushes:Patient-specific or protocol-specific configurations serve rare disease research consortia. Contract manufacturers in Switzerland produce small-batch runs for European molecular pathology networks.
Disposable brushes lead on scale; specialized brushes lead on momentum.
End User:
Volume concentration and regulatory sophistication vary sharply across buyer categories.
- Hospitals:Integrated health systems command preferential pricing through consolidated purchasing organizations. Texas and California hospital networks are unbundling brush procurement from endoscope maintenance contracts to capture unit-cost savings.
- Diagnostic Laboratories:High-throughput processors prioritize cell yield consistency for automated pathology workflows. Independent labs in India are building direct e-commerce relationships with brush distributors to bypass hospital procurement intermediaries.
- Research Institutes:Silicone-coated and biopolymer variants gain traction for delicate cytological preservation requirements. Cell morphology preservation for digital pathology integration drives specification decisions.
- Outpatient Clinics:Cost-optimized disposables dominate where procedure volume does not justify inventory complexity. Tier-2 and Tier-3 cities in India represent expanding addressable market for economy-tier products.
Hospitals dominate procurement volume; diagnostic laboratories are expanding most quickly.
Application:
Clinical utility and reimbursement pathways determine brush specification intensity.
- Cancer Screening:Lung and cervical cancer early-detection protocols demand high cell-yield designs. United States hospital systems are embedding bronchoscopy-compatible brushes into standardized pulmonary screening pathways.
- Infectious Disease Diagnosis:Respiratory and gastrointestinal pathogen detection requires sterile sampling with minimal tissue trauma. Outbreak response protocols in hospital emergency departments specify single-use disposables exclusively.
- Routine Checkups:Preventive diagnostic procedures in outpatient settings prioritize cost minimization over feature differentiation. Volume procurement contracts compress margins for standard nylon filament designs.
- Research Studies:Protocol-specific sampling requirements drive custom geometry development. Biobanking initiatives in Japan and Germany specify material traceability documentation exceeding clinical-grade standards.
Cancer screening anchors revenue concentration; infectious disease diagnosis shows steepest expansion trajectory.
Material:
Feedstock cost volatility and biocompatibility certification timelines constrain formulation choices.
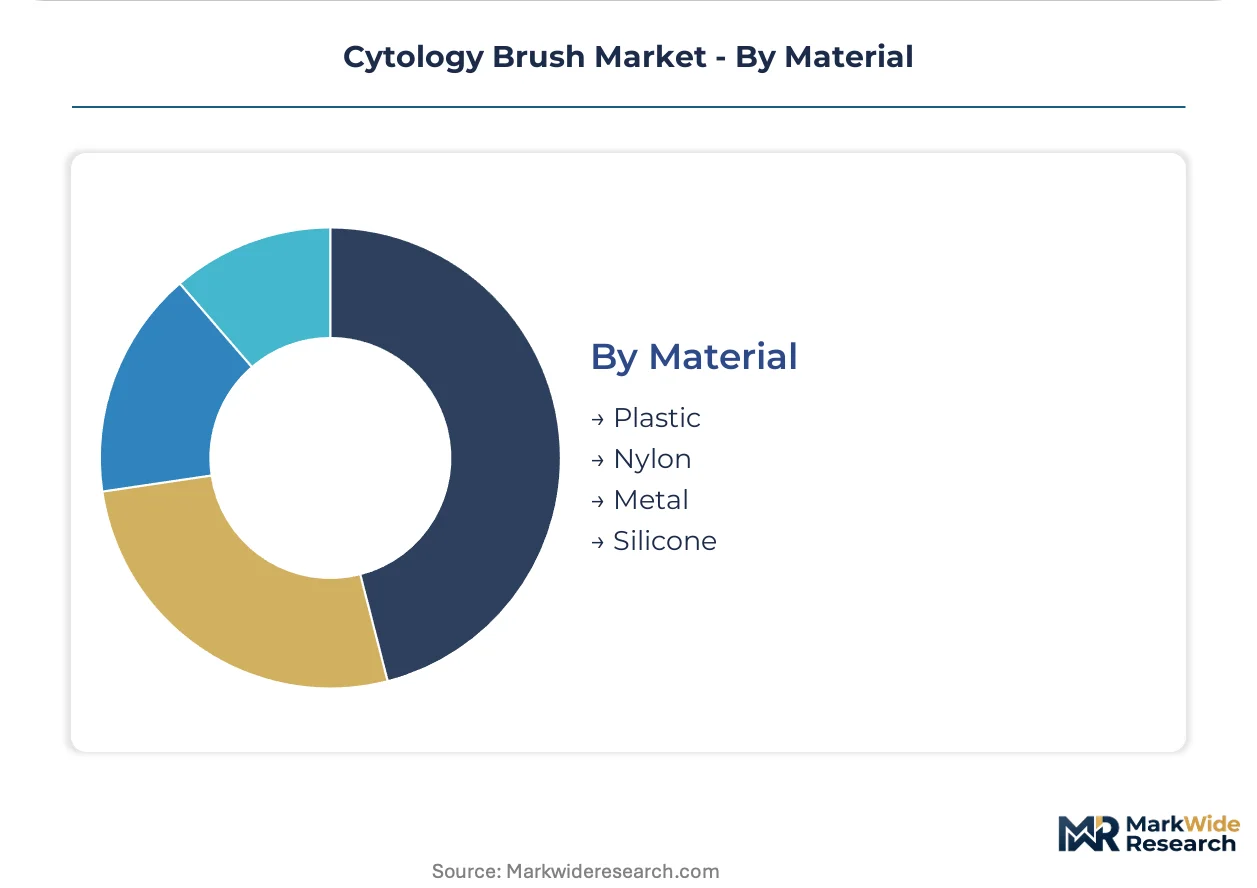
- Nylon:Laser-cut filament geometries balance cell yield against tissue trauma minimization. Petrochemical price indices directly impact margin predictability for manufacturers dependent on polymer supply.
- Plastic:Polypropylene and polyethylene variants serve economy-tier disposable demand. Single-use plastic reduction mandates in Europe are forcing material substitution toward certified biopolymers.
- Metal:Stainless steel filaments withstand repeated sterilization for reusable brush categories. ISO 10993 biocompatibility testing requirements extend regulatory timelines for new alloy introductions.
- Silicone:Coated and solid silicone designs preserve cellular morphology for research and digital pathology applications. ASTM F6400 and EN 13432 compostability standards offer premium positioning for cellulose-derived alternatives.
Nylon dominates production volume; silicone and biopolymer substrates gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medical-grade polymer formulation specialists cluster in Germany and Japan, anchoring filament supply for brush assemblers worldwide. Clinical demand concentrates in hospital systems with expanding cancer screening protocols.
United States
Hospital procurement departments in Texas and California are unbundling cytology brush contracts from endoscope maintenance agreements. FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. The Greater Boston corridor hosts contract research organizations conducting biocompatibility testing under ISO 10993.
Germany
Academic medical centers in Bavaria specify specialized brush geometries for robotic-assisted bronchoscopy platforms. EU MDR technical documentation requirements extend registration timelines for manufacturers seeking CE marking. The Rhine-Ruhr industrial belt concentrates medical-grade nylon extrusion capacity serving European brush assemblers.
Japan
Vertically integrated bronchoscope-compatible designs dominate domestic supply corridors. PMDA regulatory frameworks govern material traceability for devices entering clinical channels. The Kansai region around Osaka maintains precision filament manufacturing clusters for delicate cytological preservation instruments.
India
Tier-2 and Tier-3 cities are building pathology infrastructure demanding cost-optimized disposable sampling instruments. CDSCO medical device regulations tighten quality documentation requirements for imported brush categories. The Maharashtra-Gujarat industrial corridor hosts emerging contract manufacturers serving domestic diagnostic networks.
United Kingdom
Consolidated purchasing organizations in London and the Southeast are establishing standalone vendor qualification programs. MHRA post-Brexit regulatory frameworks diverge from EU MDR compliance pathways for brush manufacturers. The Cambridge-Oxford research triangle drives demand for silicone-coated designs in molecular pathology applications.
Cytology Brush Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the cytology brush supply base. The vendor base stratifies between integrated endoscopy system manufacturers and specialized instrument fabricators. Three archetypes dominate: diversified medical device conglomerates with endoscopy ecosystems, dedicated brush specialists with customized geometry capabilities, and contract manufacturers serving research consortia. M&A activity concentrates on biopolymer formulation capabilities, while strategic partnerships lock in filament supply security.
Among diversified device manufacturers, Boston Scientific Corporation and Olympus Corporation occupy positions anchoring bundled instrument placement across hospital systems. Cook Medical exemplifies the specialized brush archetype with focused expertise in pulmonary and gastrointestinal sampling configurations. These three entities represent distinct competitive vectors—ecosystem integration, application-specific specialization, and vertical manufacturing control—that shape procurement dynamics across United States, Japanese, and European clinical channels.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| Cook Medical |
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| ConMed Corporation |
| Hologic, Inc. |
| U.S. Endoscopy |
| Teleflex Incorporated |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between EU MDR-compliant brushes and legacy inventory creates a bifurcated market where premium documentation standards command 40-60% unit price premiums while non-compliant stock faces forced obsolescence. This tier split manifests in supply chain configurations: certified manufacturers anchor filament sourcing in Germany and Japan, whereas price-pressured assemblers shift toward Indian contract manufacturers with emerging CDSCO documentation capabilities.
Pricing Analysis
Bundled endoscope service contracts historically captured brush procurement, but Texas and California hospital systems now unbundle these agreements to pursue standalone vendor qualification. Three-tier pricing structure across premium, standard, and economy levels reflects EU MDR certification status, filament origin, and sterilization documentation depth. Pricing pressure stems from consolidated purchasing organization volume aggregation, with independent pathology laboratories in India exhibiting highest price sensitivity due to direct e-commerce channel access.
Supply Chain Analysis
Polymer science talent scarcity in Germany and Japan constrains medical-grade filament extrusion capacity expansion despite rising brush assembly demand. Raw material dependencies center on petrochemical-derived nylon, medical-grade polypropylene, and emerging cellulose-based biopolymers. Single-source vulnerability clusters around German and Japanese filament specialists, with distribution running through specialized medical device distributors and direct-to-laboratory e-commerce platforms serving independent diagnostic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cytology brush market functions as a stable compounder anchored by irreversible infection control mandates that permanently displace reusable alternatives. Preventive diagnostic protocol expansion across United States hospital systems sustains predictable demand trajectories.
For Market Incumbents: Extend filament supply security through captive relationships with German and Japanese extrusion specialists before biopolymer transition accelerates. Lock in multi-year GPO contracts with Texas and California hospital systems to defend against unbundling pressure. Prioritize EU MDR technical documentation completion to capture replacement cycle premiums in Bavaria and Rhine-Ruhr procurement corridors. For New Entrants and Emerging Players: Direct-to-laboratory e-commerce channels offer the most penetrable route for bypassing consolidated hospital procurement intermediaries. Target Tier-2 and Tier-3 Indian cities where CDSCO regulatory alignment creates first-mover positioning ahead of domestic manufacturing scale-up. Lead with cost-optimized nylon filament designs that undercut established distributor markups. For Investors and Strategic Acquirers: Consolidation pressure builds where biopolymer formulation capabilities concentrate among packaging and automotive sector competitors. Frame 5-10 year viability around infection control mandate permanence and robotic-assisted bronchoscopy platform integration. Monitor ASTM F6400 and EN 13432 compostability certification progress as the signal for material substitution inflection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | CE marking pathway unlocks premium pricing in German and Italian hospital procurement cycles. |
| Biopolymer Formulation Partnership | Cellulose-derived substrates satisfy single-use plastic reduction mandates in European health systems. |
| Direct E-Commerce Channel Development | Bypassing hospital GPO intermediaries captures margin in Indian diagnostic laboratory expansion. |
| Robotic Bronchoscopy Interface Design | Precision brush geometries align with United States academic medical center automation deployment. |
| Filament Supply Security Agreement | Long-term contracts with Japanese extrusion specialists mitigate single-source vulnerability exposure. |
Methodological Framework
Coverage spans United States, Germany, Japan, India, and United Kingdom clinical channels, with primary inputs from each market's hospital procurement committees, biomedical engineers, GPO contracts managers, and pathology laboratory directors. Secondary validation draws from FDA 510(k) filings, EU MDR technical documentation databases, CDSCO import registration records, and hospital procurement contract disclosures. Bottom-up demand modeling triangulates against top-down macroeconomic healthcare expenditure trends.
Granularity-level framing applies product type, end user category, application, and material composition dimensions at country-level resolution across the analysis window. CAGRs derive from procedure volume elasticity modeling against cancer screening protocol penetration rates. Industry-specific inputs include robotic-assisted bronchoscopy platform deployment trajectories and biopolymer certification timeline assumptions.
The model assumes a particular technology adoption path; alternative pathways for robotic-assisted sampling automation or accelerated biopolymer substitution would alter the outlook. Forecasts reflect documented assumptions about EU MDR compliance deadline adherence and filament supply capacity expansion. Practitioners should monitor CDSCO domestic manufacturing incentive progress and ASTM F6400 certification completion rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bioactive Fillings Market
Medical Devices
Penile Prosthesis Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Patellar Implant Market
Medical Devices
Acellular Dermal Matrix Market
Medical Devices
United States Drug Delivery Devices Market
Medical Devices
Superficial Radiation Therapy System Market
Medical Devices
Illuminating Eye Massagers Market
Medical Devices
Medical Device Complaint Management Market
Medical Devices
Germany Respiratory Devices Market
Medical Devices
Canada General Surgical Devices Market
Medical Devices
Global Gynecological Devices Market
Medical Devices
Peak Flow Meters Market
Medical Devices
Airotar Handpiece Market
Medical Devices
Platelet Concentration Systems Market
Medical Devices
India Hemostats Market