
 Global Allergy Diagnostics and Therapeutics Market | 2026-2036
Global Allergy Diagnostics and Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Allergy Diagnostics and Therapeutics Market Intelligence
Multiplex component-resolved diagnostics is collapsing the traditional, sequential testing pathway for complex polysensitized patients. Thermo Fisher Scientific leverages its broad portfolio in immunoassays and mass spectrometry to lead this advanced diagnostic segment. Siemens Healthineers competes with automated laboratory systems for high-throughput specific IgE testing. ALK-Abelló A/S specializes in allergen immunotherapy, particularly sublingual and subcutaneous treatments.
Allergy diagnostics and therapeutics encompass methods for identifying specific allergens and treatments to mitigate the immune system's hypersensitive response. Diagnostic tools measure levels of allergen-specific Immunoglobulin E (IgE) antibodies. Allergen immunotherapy and specific IgE tests represent the highest value product segments. While respiratory allergies constitute the largest therapy area, the focus on managing food allergies is intensifying within specialized pediatric centers.
Regulatory frameworks from the US FDA, Europe's EMA, and China's NMPA govern the approval of new diagnostic kits and therapeutic agents. These agencies enforce stringent clinical trial requirements for novel immunotherapies, influencing development timelines and market access. Stakeholders must now decide whether to prioritize development of broad-spectrum symptomatic treatments or highly specific, disease-modifying immunotherapies.
Market Dynamics
The market's central dynamic is the technological shift toward precision diagnostics. Multiplex component-resolved platforms are collapsing traditional testing workflows, forcing a re-evaluation of diagnostic strategies and subsequent therapeutic pathways for polysensitized individuals.
Growth Catalysts
- Pediatric Center Demand:The need for non-invasive and less painful diagnostic methods for children is driving adoption of blood-based specific IgE tests over skin-prick tests in specialized pediatric facilities.
- Public Health Initiatives:Government-sponsored programs in countries like China are increasing allergy awareness and funding for public screening, expanding the addressable patient population in urban areas.
- Sublingual Immunotherapy (SLIT):The transition towards at-home, patient-administered SLIT treatments offers greater convenience than traditional injections, improving long-term patient adherence and expanding therapeutic access.
Market Restraints
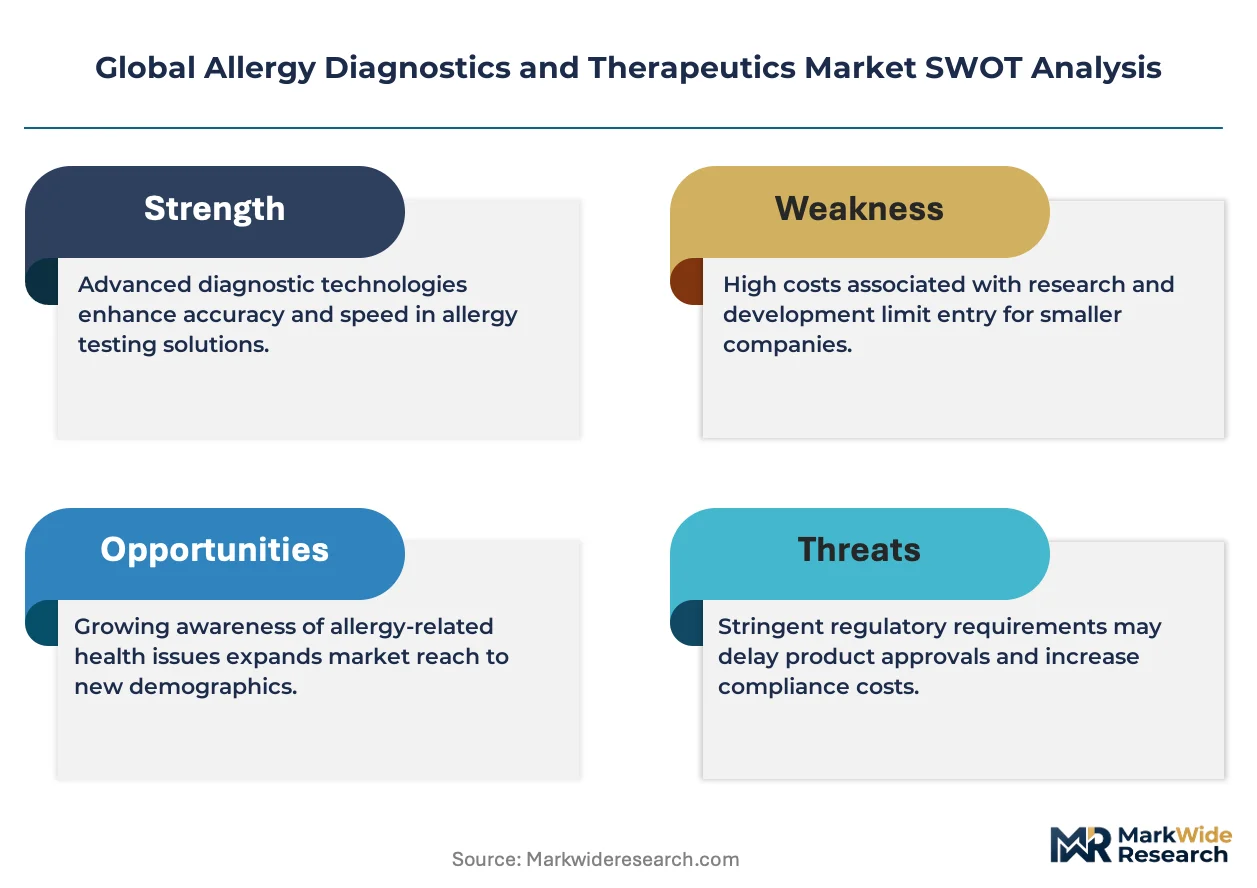
- High Development Costs:Novel disease-modifying immunotherapies, particularly biologics, face substantial research and development expenditures and high manufacturing costs, limiting accessibility and affordability.
- Regulatory Hurdles:Stringent clinical trial requirements enforced by the FDA and EMA for new immunotherapies create long development timelines and significant barriers to market entry.
- Reimbursement Complexity:Inconsistent and often restrictive reimbursement policies for advanced diagnostics and newer therapies across national healthcare systems limit patient access and physician adoption.
Strategic Opportunities
- Food Allergy Management:The escalating prevalence of food allergies creates a significant opportunity for developing targeted diagnostics and specific oral immunotherapies for pediatric and adult populations.
- Digital Health Integration:Combining mobile applications for symptom tracking and adherence monitoring with diagnostic data offers a pathway to personalized allergy management and improved patient outcomes.
- Emerging Market Penetration:Rapid urbanization and rising disposable incomes in countries like India and Brazil present untapped markets for both diagnostic services and therapeutic products.
Industry Challenges
- Allergen Standardization:A lack of global standardization in the manufacturing and characterization of allergen extracts for both diagnostics and therapy leads to variability in product potency and clinical results.
- Specialist Scarcity:A shortage of trained allergists and immunologists, especially in developing regions, constrains the accurate diagnosis and effective management of complex allergic conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Allergy Diagnostics and Therapeutics Market |
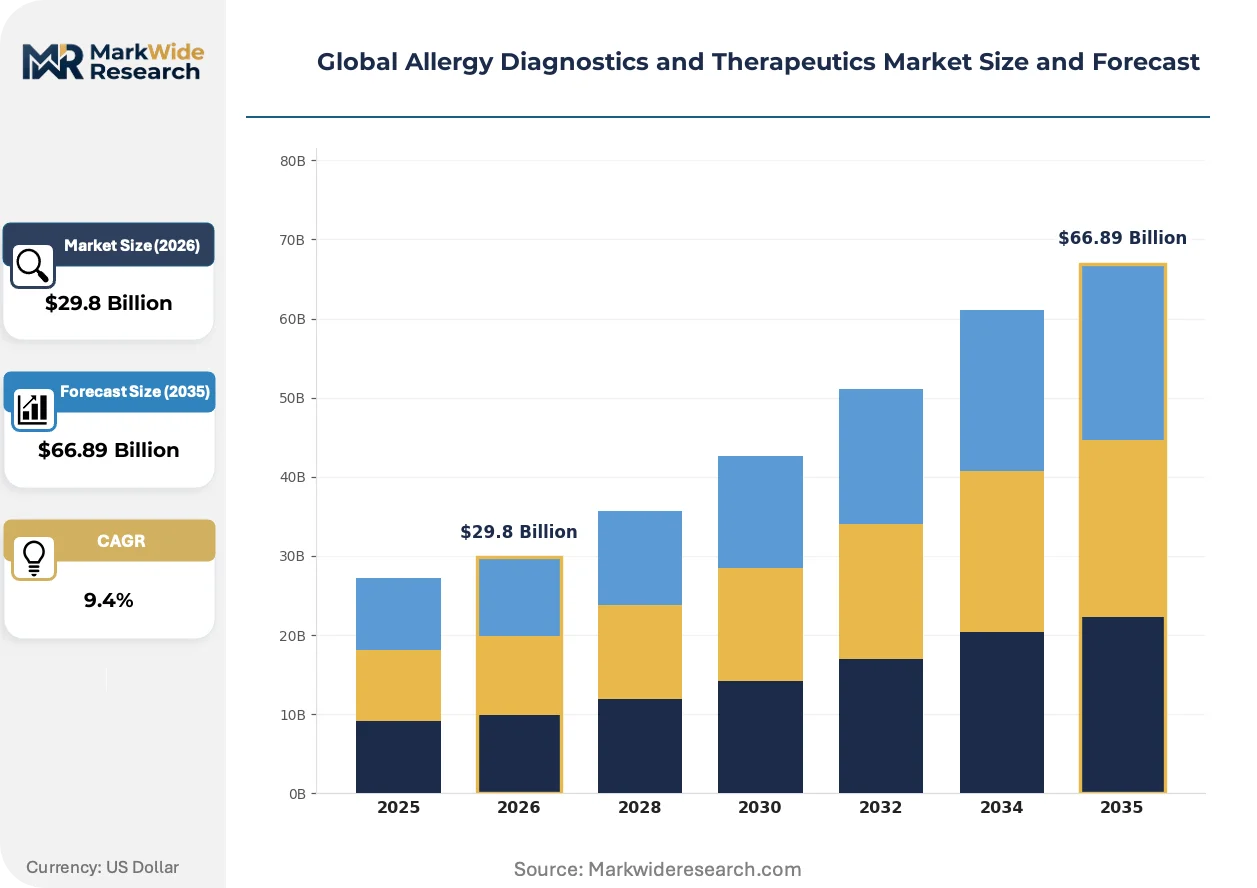
| Market Size in 2026 | $29.8 Billion |
| Market Size in 2035 | $66.89 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skin Prick Test, Specific IgE Test, Patch Test, Allergen Immunotherapy, Antihistamines, Corticosteroids Therapy Area: Respiratory Allergies, Food Allergies, Drug Allergies, Insect Venom Allergies, Atopic Dermatitis, Urticaria End User: Allergy Clinics, Immunology Labs, Specialized Hospitals, Diagnostic Centers, Pediatric Centers, Research Institutes Delivery Mode: In-Vitro Diagnostics, In-Vivo Diagnostics, Subcutaneous Immunotherapy, Sublingual Immunotherapy, Oral Medications, Nasal Sprays |
| Companies Covered | Thermo Fisher Scientific Inc., Siemens Healthineers AG, Danaher Corporation, GSK plc, Sanofi, Allergy Therapeutics, Merck & Co., Inc., Novartis AG, ALK-Abelló A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Allergy Diagnostics and Therapeutics Market Strategic Shifts & Innovations
A fundamental move toward precision and personalization is redefining allergy care. This evolution pivots away from broad, symptomatic treatments toward highly specific, disease-modifying interventions informed by more granular diagnostic insights.
Component-resolved diagnostics (CRD) provide a detailed profile of a patient's sensitization to individual allergenic molecules from a single blood sample. Reference laboratories and specialized allergy clinics are the primary adopters for evaluating complex cases. This multiplex approach is displacing the traditional, often inconclusive, sequential testing of whole allergen extracts for polysensitized patients.
The European Medicines Agency (EMA) enforces specific guidelines for the clinical development of allergen immunotherapy (AIT) products. This framework demands that manufacturers provide strong evidence of long-term, disease-modifying effects, not just symptom reduction. Consequently, the sublingual and subcutaneous immunotherapy segments face elevated R&D standards for market approval in Europe.
Patient preference for at-home administration is reshaping therapeutic delivery. This behavioral shift favors self-administered sublingual immunotherapy (SLIT) tablets and drops over clinician-administered subcutaneous injections. The trend is most visible in North America and Western Europe, where convenience and reduced clinic visits are major factors in treatment choice.
Global Allergy Diagnostics and Therapeutics Market Segmentation
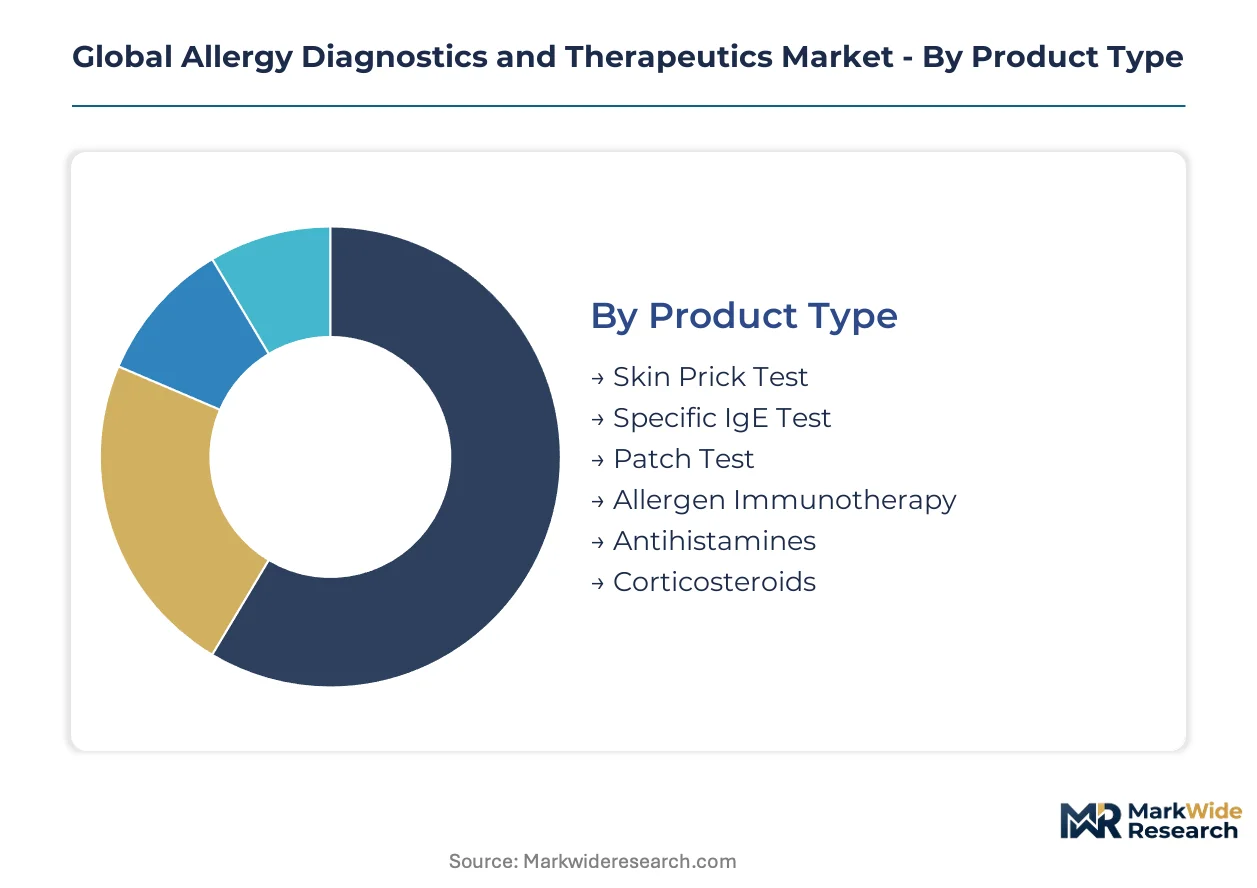
The global allergy diagnostics and therapeutics market is highly segmented, reflecting the diverse nature of allergic conditions and the varied approaches to their management. Understanding these distinct segments is crucial for stakeholders to identify specific market needs and strategic growth areas. This analysis details the market structure across key product types, therapy areas, end users, and delivery modes.
Product Type:
The market for allergy diagnostics and therapeutics exhibits varied product type adoption, with some solutions seeing widespread domestic use while others are optimized for broader global distribution.
- Specific IgE Test:These blood tests quantify allergen-specific Immunoglobulin E antibodies, offering precise, objective measures of sensitization. Demand concentrates in specialized pediatric centers across North America, driven by the need for non-invasive diagnostic options for children.
- Allergen Immunotherapy:This treatment modifies the immune system's response to allergens through controlled exposure, aiming for long-term tolerance. European markets show strong uptake, influenced by EMA guidelines emphasizing disease-modifying effects and improved patient adherence.
- Skin Prick Test:These in-vivo tests involve applying allergen extracts to the skin, providing rapid results for immediate hypersensitivity reactions.
- Patch Test:Patch tests identify delayed hypersensitivity reactions, primarily used for diagnosing contact dermatitis by applying allergens to the skin.
- Antihistamines:These oral medications alleviate allergy symptoms by blocking histamine receptors, offering symptomatic relief for various allergic conditions.
- Corticosteroids:Corticosteroids, available in nasal sprays or oral forms, reduce inflammation associated with severe allergic reactions and respiratory symptoms.
Antihistamines command the established base for symptomatic relief. The steepest expansion runs through Allergen Immunotherapy, driven by disease-modifying potential.
Therapy Area:
The diverse range of allergic conditions drives specific therapeutic and diagnostic application, tailoring interventions to distinct patient populations and clinical needs.
- Respiratory Allergies:This segment includes conditions like allergic rhinitis and asthma, triggered by airborne allergens such as pollen and dust mites. Treatments and diagnostics are widely adopted in North America and Western Europe due to high prevalence and established healthcare infrastructure.
- Food Allergies:Reactions to specific food proteins define this critical therapy area, ranging from mild symptoms to life-threatening anaphylaxis. Specialized pediatric centers globally are intensifying focus on food allergy management, seeking advanced diagnostics and specific oral immunotherapies.
- Drug Allergies:This area focuses on adverse immune responses to pharmaceutical agents, requiring precise diagnostic methods to identify causative medications.
- Insect Venom Allergies:Hypersensitivity to insect stings necessitates specific immunotherapy to prevent severe systemic reactions, particularly in outdoor-heavy regions.
- Atopic Dermatitis:Also known as eczema, this chronic inflammatory skin condition often has allergic triggers, requiring targeted management strategies.
- Urticaria:Characterized by hives and angioedema, urticaria can be acute or chronic, with diagnostics aiming to identify allergic or non-allergic triggers.
Respiratory Allergies constitute the largest therapy area, driving substantial diagnostic and therapeutic demand. Food Allergies are gaining share fastest, propelled by increased prevalence and management focus.
End User:
Different end-user segments exhibit distinct purchasing behaviors and clinical needs, influencing the types of diagnostic and therapeutic solutions procured across the market.
- Allergy Clinics:These specialized outpatient facilities provide comprehensive diagnosis, treatment, and management for various allergic conditions. They represent a primary market for specific IgE testing and allergen immunotherapy products, particularly in developed healthcare systems like Germany.
- Pediatric Centers:Focusing on allergic conditions in children, these centers prioritize non-invasive diagnostics and patient-friendly therapeutic approaches. Demand for blood-based specific IgE tests and oral immunotherapies for food allergies is particularly high here, notably in urban centers across China.
- Immunology Labs:These laboratories perform advanced immunological assays, including multiplex component-resolved diagnostics, supporting complex allergy cases.
- Specialized Hospitals:Hospitals with dedicated allergy departments integrate diagnostic testing with inpatient and outpatient therapeutic interventions for severe allergic reactions.
- Diagnostic Centers:Independent diagnostic centers offer a range of allergy tests, serving as referral points for primary care physicians seeking initial allergy screening.
- Research Institutes:These institutions drive innovation in allergy diagnostics and therapeutics, conducting clinical trials and developing novel disease-modifying interventions.
Allergy Clinics remain central to patient care and product utilization. Pediatric Centers are experiencing significant growth in demand for specialized solutions.
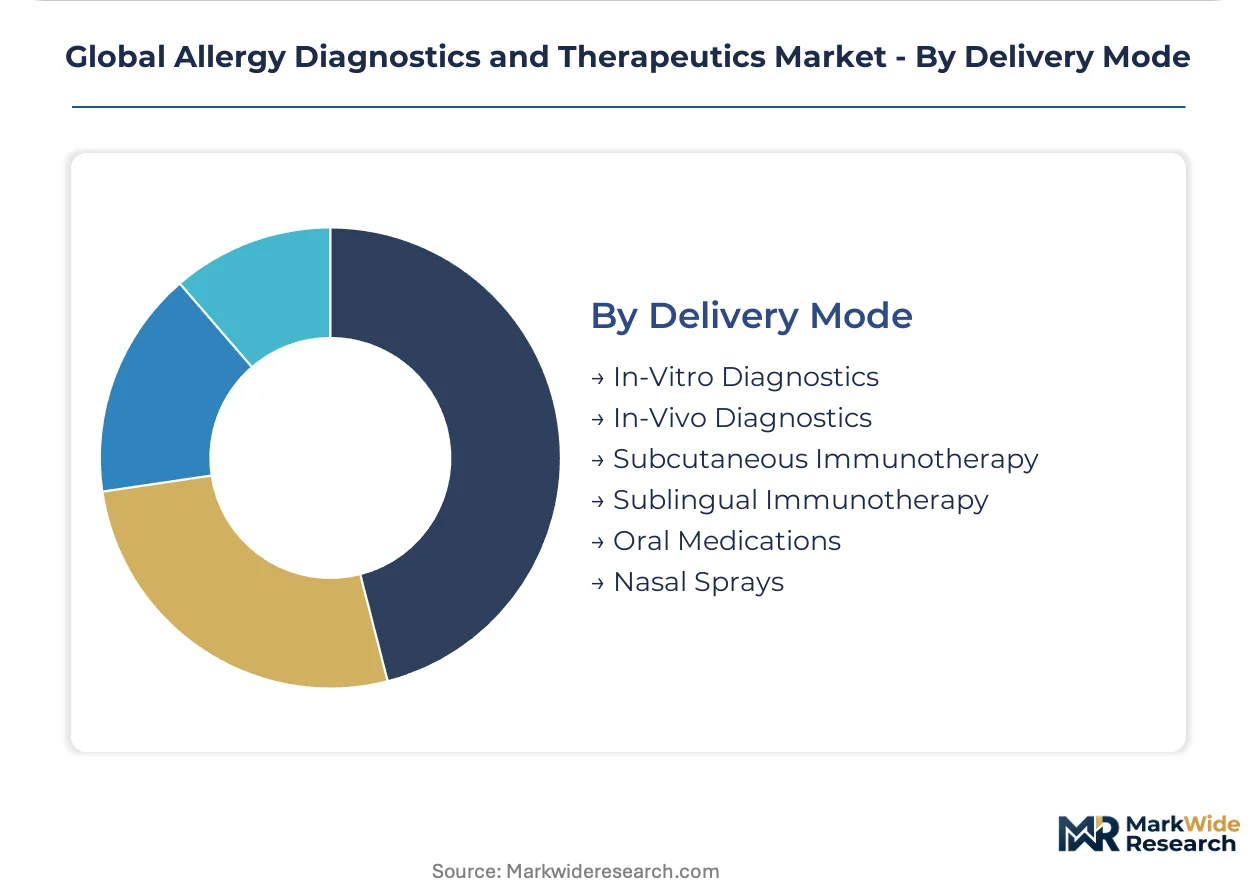
Delivery Mode:
The volume of diagnostic procedures and therapeutic administrations varies significantly across different delivery modes, reflecting diverse patient preferences and clinical protocols.
- In-Vitro Diagnostics:This category encompasses laboratory-based blood tests that measure allergen-specific IgE levels for comprehensive allergy profiling. These diagnostics are increasingly preferred in settings requiring precision and minimal patient discomfort, such as specialized diagnostic centers in the US.
- Sublingual Immunotherapy:SLIT involves self-administering allergen extracts under the tongue, offering a convenient, at-home treatment option for long-term immune modulation. Its adoption is expanding rapidly in Western Europe due to improved patient adherence and reduced need for frequent clinic visits.
- In-Vivo Diagnostics:These methods involve direct patient exposure to allergens, including skin prick tests, for immediate or delayed reaction assessment.
- Subcutaneous Immunotherapy:SCIT involves regular allergen injections administered by a clinician, providing effective long-term treatment for various allergies.
- Oral Medications:This mode includes antihistamines and corticosteroids taken orally, primarily for symptomatic relief of allergic reactions.
- Nasal Sprays:Nasal sprays deliver corticosteroids or antihistamines directly to the nasal passages, targeting respiratory allergy symptoms like congestion.
Oral Medications remain widely used for immediate symptom management. Sublingual Immunotherapy is experiencing the steepest expansion trajectory, driven by convenience and patient preference.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global allergy diagnostics and therapeutics market exhibits a varied trade balance, with some regions acting as net exporters of advanced diagnostic platforms while others primarily import specialized immunotherapies. This dynamic shapes local market development and access to cutting-edge treatments. Demand for these solutions is geographically diverse.
United States
Demand for specific IgE tests remains high in specialized pediatric centers, driven by the need for non-invasive diagnostic options. The FDA's stringent approval processes influence the availability of novel immunotherapies. Biopharmaceutical clusters in Boston and San Francisco are prominent centers for allergy research and development.
Germany
Allergen immunotherapy sees strong uptake, driven by an established healthcare infrastructure and comprehensive reimbursement. EMA guidelines emphasize long-term disease-modifying effects for market approval. Major pharmaceutical hubs like Frankfurt and Munich contribute substantially to therapeutic innovation and manufacturing.
China
Public health initiatives are increasing allergy awareness and funding for public screening, particularly in urban areas. The NMPA actively regulates the approval of new diagnostic kits and therapeutic agents. Urban centers like Shanghai and Beijing are experiencing concentrated demand for pediatric allergy solutions.
Japan
Precision diagnostics, especially component-resolved platforms, are gaining traction for evaluating complex cases. PMDA regulations ensure the safety and efficacy of novel allergy treatments. Research institutes in Tokyo and Osaka are actively advancing component-resolved diagnostics and personalized allergy care.
United Kingdom
Patient preference for at-home administration drives the expansion of self-administered sublingual immunotherapy. The Medicines and Healthcare products Regulatory Agency (MHRA) oversees the approval of allergy therapeutics. Life sciences clusters around London and Cambridge foster significant innovation in allergy management.
Global Allergy Diagnostics and Therapeutics Market Key Industry Players
Listed leaders compete with private specialists across advanced diagnostics and immunotherapy development, creating a dynamic market environment. The market exhibits a tiered structure, with established pharmaceutical giants alongside focused diagnostic solution providers and smaller innovative startups. Strategic archetypes include diversified healthcare conglomerates and niche allergen immunotherapy developers. Dominant competitive moves involve strategic partnerships for technology co-development and portfolio diversification into emerging therapy areas like food allergy management.
Companies like Thermo Fisher Scientific Inc. exemplify the diversified conglomerate archetype, leveraging broad portfolios in immunoassays and mass spectrometry to lead advanced diagnostic segments globally. Siemens Healthineers AG occupies a significant position within automated laboratory systems, providing solutions for high-throughput specific IgE testing across numerous clinical settings worldwide. ALK-Abelló A/S represents the specialized immunotherapy segment, concentrating on sublingual and subcutaneous treatments that aim for long-term immune modulation and improved patient adherence in key markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Siemens Healthineers AG |
| Danaher Corporation |
| GSK plc |
| Sanofi |
| Allergy Therapeutics |
| Merck & Co., Inc. |
| Novartis AG |
| ALK-Abelló A/S |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized reagents and active pharmaceutical ingredients lock in both supply access and price visibility for manufacturers of allergy diagnostics and therapeutics.
Pricing Analysis
Healthcare system procurement teams anchor value-based pricing for advanced immunotherapies, considering long-term patient outcomes. Price differentiation stems from regulatory approval status (e.g., FDA or EMA clearance), diagnostic precision, and the convenience of at-home administration for sublingual treatments. Pricing pressure stems from inconsistent reimbursement policies across national healthcare systems, particularly for novel disease-modifying agents. Payers and patients are most price-sensitive regarding broad symptomatic relief medications, while specialized clinics prioritize advanced diagnostics for complex cases.
Supply Chain Analysis
Port congestion in key trade lanes and container availability challenges impact the inbound logistics costs for diagnostic kits and therapeutic agents. Supply concentration for critical raw materials, such as recombinant allergens and specialized antibodies, primarily resides in Germany, the United States, and China. Manufacturers depend on a consistent supply of active pharmaceutical ingredients (APIs) and diagnostic reagents. Regulatory approval delays across multiple jurisdictions present a structural supply chain risk. Distribution runs through specialized pharmaceutical distributors and direct channels to allergy clinics and hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The allergy diagnostics and therapeutics market is currently undergoing a buyer-power-shift, driven by the consolidation of large hospital networks and group purchasing organizations.
For Market Incumbents:
Consolidate research and development efforts on disease-modifying immunotherapies to counteract the threat of emerging specialized startups. Invest in vertical integration across diagnostic platforms and therapeutic manufacturing to control quality and cost. Expand clinical trial programs for novel biologics in emerging markets to broaden patient access and secure early regulatory approvals. Reinforce existing relationships with key opinion leaders in pediatric allergy to maintain market leadership.
For New Entrants and Emerging Players:
Fast-track certification pathways for novel food allergy oral immunotherapies present a significant entry point into pediatric centers. Target underserved urban areas in China and India with non-invasive diagnostic solutions. Develop digital health platforms for personalized allergy management, integrating symptom tracking with diagnostic data. Focus go-to-market strategies on patient convenience and adherence for self-administered therapies like sublingual immunotherapy.
For Investors and Strategic Acquirers:
Capital is best deployed toward companies specializing in multiplex component-resolved diagnostics or novel disease-modifying immunotherapies. Focus on acquisition targets with strong intellectual property portfolios and robust clinical pipelines in food allergy management. The long-term viability of the market over the next decade hinges on regulatory support for precision medicine. The signal to watch is the approval of new immunotherapies with demonstrated long-term efficacy by the EMA or FDA.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement for Novel Immunotherapies | Accelerates market access for disease-modifying treatments addressing unmet patient needs. |
| Platform Integration of Diagnostics and Therapeutics | Enhances personalized medicine approaches and streamlines patient management pathways. |
| Manufacturing Scale-Up for Recombinant Allergens | Ensures consistent supply of high-quality components for advanced diagnostic and therapeutic products. |
| Strategic Partnership with Digital Health Providers | Expands patient engagement and adherence through remote monitoring and personalized insights. |
| Geographic Expansion into Emerging Urban Centers | Captures new patient populations with rising allergy prevalence and improving healthcare access. |
Research Approach
A standing panel of allergists, immunologists, regulatory affairs leads, and hospital procurement managers provided ongoing calibration for market sizing and forecasting. This analysis combined insights from primary interviews with extensive secondary validation, drawing from regulatory filings with the FDA, EMA, and NMPA, clinical trial databases, and specialized medical journals. The approach utilized both bottom-up and top-down triangulation to ensure comprehensive market coverage.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled market dynamics across product types, therapy areas, end users, and delivery modes, alongside regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from projected market shifts and historical data trends. Forecast inputs included global allergy prevalence rates and evolving reimbursement policies for advanced diagnostics.
Decision-makers should treat outputs as directional under current public health initiatives and regulatory frameworks; material deviation would warrant model refresh. Forecasts reflect assumptions regarding technological advancements in component-resolved diagnostics and the successful development of novel immunotherapies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Latin America Melanoma Diagnostics and Therapeutics Market
Clinical Diagnostics
Cardiology Genomic Testing Market
Clinical Diagnostics
Colorectal Cancer Molecular Diagnostics Market
Clinical Diagnostics
Cell Free DNA Testing Market
Clinical Diagnostics
Bone Metabolism Test Market
Clinical Diagnostics
Blood Urea Nitrogen Testing Market
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Osteoporosis Testing Market
Clinical Diagnostics
ESR1 Mutated Metastatic Breast Cancer Diagnostics Market
Clinical Diagnostics
Blood Group Typing Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
Artificial Intelligence in Cancer Diagnostics Market
Clinical Diagnostics
US Non-Invasive Prenatal Testing (NIPT) Market
Clinical Diagnostics
Lupus Anticoagulant Testing Market
Clinical Diagnostics
Food Allergy Diagnosis and Treatment Market