
 Respiratory Pathogen Testing Market | 2026-2036
Respiratory Pathogen Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Pathogen Testing Market Analytics
The EU Green Deal's health resilience provisions is recalibrating procurement criteria for respiratory diagnostic platforms across European healthcare systems. Abbott Laboratories leverages its integrated point-of-care molecular architecture to sustain channel dominance in decentralized testing environments. Thermo Fisher Scientific anchors its position through captive supply of PCR reagents and thermal cycling instrumentation. bioMérieux SA differentiates via specialized multiplex syndromic panels that target acute respiratory infection differentiation.
Respiratory pathogen testing encompasses molecular, immunological, and culture-based methods that detect viral and bacterial agents causing acute respiratory infections, typically employing nucleic acid amplification with cycle threshold interpretation or antigen-antibody binding assays with defined sensitivity cutoffs to guide clinical treatment decisions and infection control protocols. PCR-based platforms occupy the largest revenue pool given established reimbursement and laboratory familiarity, while sequencing-based approaches represent the fastest-expanding segment as pathogen surveillance and variant tracking applications broaden. Point-of-care deployment is capturing disproportionate investment attention as health systems prioritize rapid turnaround for respiratory triage in emergency and ambulatory settings.
The FDA governs premarket authorization and emergency use pathways for respiratory assays in the United States, while the EMA coordinates centralized conformity assessment for in vitro diagnostic medical devices under the EU MDR transition, and WHO emergency use listing procedures shape procurement eligibility for pandemic countermeasure stockpiles. These frameworks collectively elevate validation burden and quality management requirements, filtering market access toward manufacturers with robust regulatory infrastructure and clinical evidence generation capabilities. Stakeholders must monitor evolving harmonization between regional diagnostic performance standards and emerging multi-pathogen panel reimbursement policies.
Market Dynamics
Multiplex syndromic panel adoption is compressing turnaround times for respiratory diagnostics, forcing laboratories to consolidate testing workflows around integrated molecular platforms that replace sequential single-target assays.
Growth Catalysts
- EUA Framework Flexibility:The FDA's streamlined emergency use authorization pathway accelerates assay deployment during respiratory surges, reducing validation timelines for novel target inclusion.
- Hospital Consolidation:Integrated delivery networks centralize laboratory procurement, favoring vendors with broad respiratory menu coverage and automated sample-to-answer systems.
- PCR Platform Familiarity:Established reimbursement codes and laboratory technician training infrastructure sustain nucleic acid amplification as the default diagnostic modality.
Market Restraints
- Reagent Supply Concentration:Thermal-stable polymerase and fluorescent probe manufacturing clusters in Germany and the United States, creating geographic vulnerability during demand spikes.
- MDR Transition Friction:The EU MDR's elevated clinical evidence requirements delay in vitro diagnostic recertification, freezing product portfolios for mid-tier manufacturers.
- Antigen Test Substitution:Low-cost lateral flow devices capture seasonal screening volume, compressing molecular test reimbursement ceilings in ambulatory settings.
Strategic Opportunities
- Home-Based Collection Infrastructure:Self-sampling kits for respiratory panels bypass clinical site bottlenecks, opening direct-to-consumer channels previously blocked by specimen integrity requirements.
- Wastewater Surveillance Integration:Environmental monitoring programs create institutional demand for high-sensitivity respiratory pathogen detection in municipal utilities and university systems.
- AI-Assisted Ct Interpretation:Machine learning algorithms applied to amplification curves enable semi-quantitative viral load reporting, differentiating routine panels from commodity testing.
Industry Challenges
- Bioinformatics Talent Scarcity:Clinical laboratories lack personnel trained in sequencing data analysis, constraining adoption of targeted next-generation respiratory panels.
- Interoperability Friction:Proprietary instrument software blocks seamless integration with laboratory information systems, forcing manual result transcription and delaying reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Pathogen Testing Market |
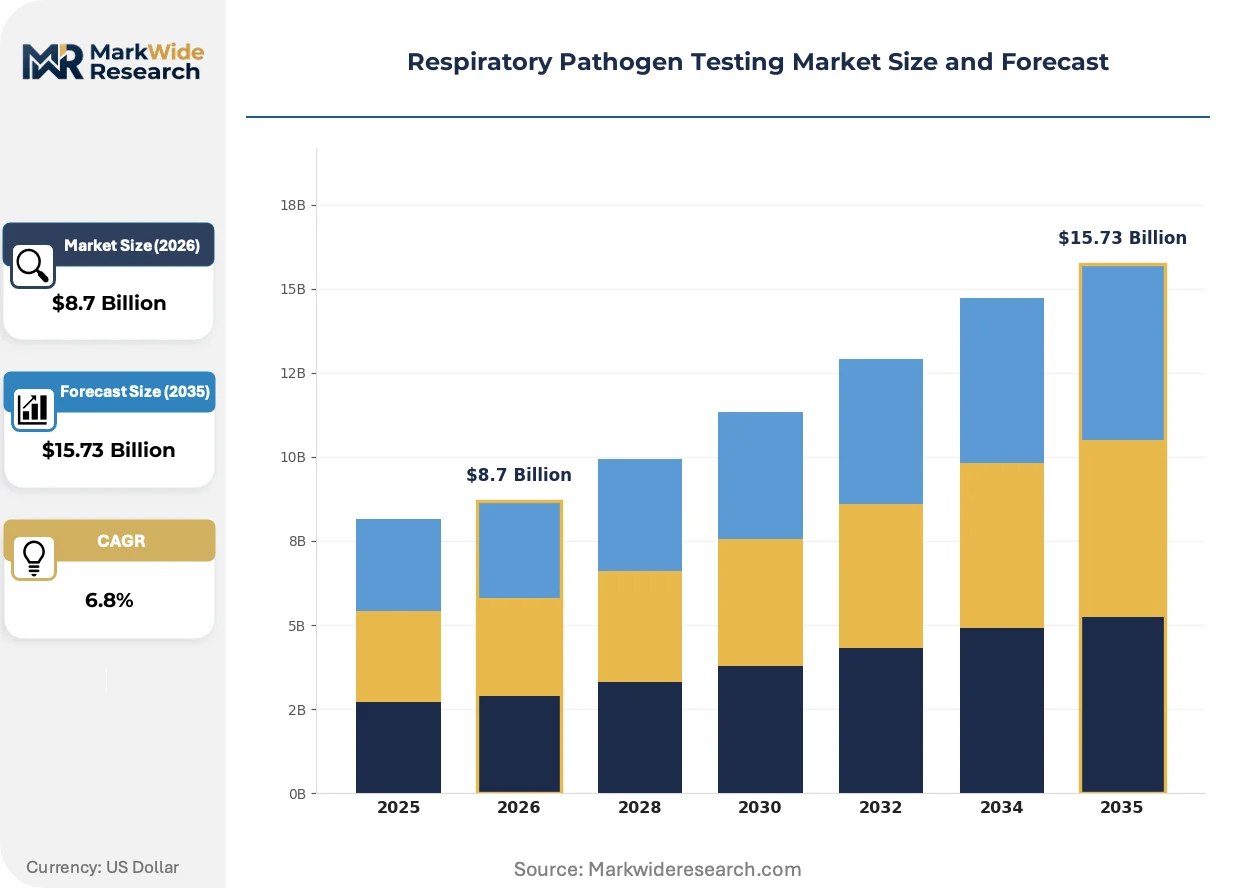
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, Antigen Test, Antibody Test, Sequencing End User: Hospitals, Diagnostic Laboratories, Home Care, Point-of-Care Technology: NAAT, Immunoassay, Microbiological Culture, Mass Spectrometry Application: Influenza, COVID-19, RSV, Adenovirus |
| Companies Covered | Abbott Laboratories, Thermo Fisher Scientific, bioMérieux SA, Roche Diagnostics, QuidelOrtho Corporation, Becton Dickinson and Company, Danaher Corporation, QIAGEN N.V., Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Pathogen Testing Market Evolving Landscape
Respiratory diagnostics is pivoting from single-target confirmation to syndrome-driven multiplex detection, compressing the interval between specimen collection and therapeutic decision-making across acute care settings.
CRISPR-based nucleic acid detection is rewriting the cost-performance frontier for point-of-care molecular testing. Community health centers and urgent care chains are piloting instrument-free respiratory panels that operate without thermal cycling infrastructure. The technology is compressing capital requirements for decentralized testing while challenging established PCR platform economics.
The EU AI Act's risk classification system is reshaping algorithm deployment in diagnostic workflows. Automated Ct threshold interpretation and predictive resistance calling now face conformity assessment requirements that elevate documentation burdens. High-complexity laboratories in France and Germany are restructuring quality management systems to accommodate these algorithm governance standards.
Integrated service contracts are displacing instrument-reagent unbundling in hospital procurement. Health systems in the United States now prioritize total cost-per-reportable-result metrics over capital expenditure minimization, consolidating vendor relationships around comprehensive respiratory testing partnerships that include assay supply, maintenance, and staff training.
Respiratory Pathogen Testing Market Segmentation
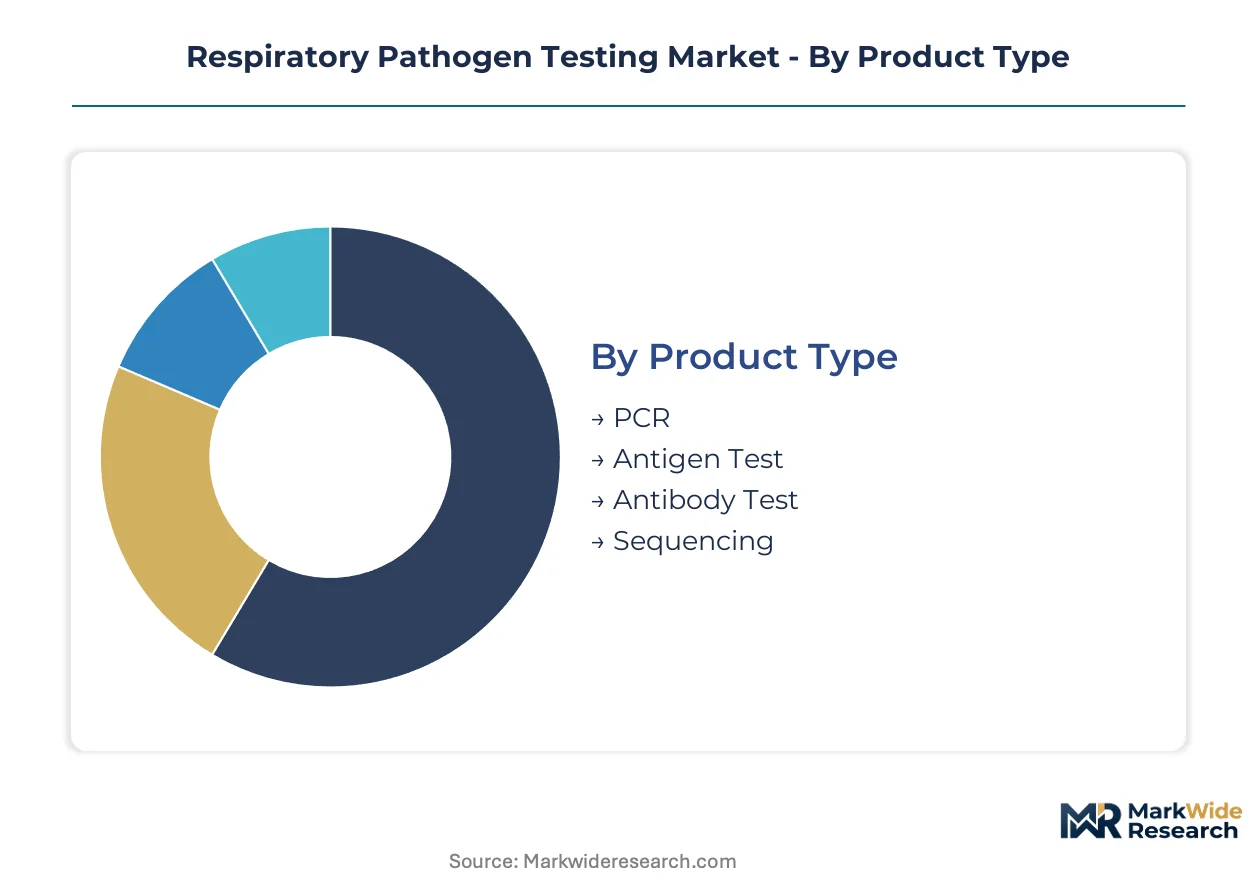
Respiratory pathogen testing segments fragment across detection methodology, care setting, and target pathogen, with upgrade cycles accelerating as laboratories replace aging thermal cyclers and hospitals consolidate around syndromic panels. Each dimension carries distinct procurement logic, reimbursement pathways, and technical validation requirements that shape vendor positioning and customer switching costs.
Product Type:
Replacement cycles for respiratory diagnostic platforms are shortening as laboratories retire first-generation PCR systems and adopt integrated sample-to-answer architectures that compress manual handling steps.
- PCR:Nucleic acid amplification with fluorescent probe detection delivers cycle threshold quantification for viral load assessment. Hospital laboratories in the United States anchor procurement volumes, driven by established CPT reimbursement codes and technician familiarity with thermal cycling workflows.
- Antigen Test:Lateral flow immunochromatography enables rapid visual interpretation without instrumentation. Point-of-care clinics and urgent care chains concentrate demand during seasonal respiratory surges, though sensitivity limitations restrict use to high-viral-load specimens.
- Antibody Test:Serological detection of host immune response indicates prior exposure rather than active infection. Public health surveillance programs and occupational health screening sustain niche procurement volumes.
- Sequencing:Targeted next-generation methods identify novel variants and resistance mutations through whole-genome or amplicon-based approaches. Reference laboratories and academic medical centers drive adoption as pathogen surveillance requirements expand.
PCR sits at the top of the volume ranking, with sequencing climbing the fastest.
End User:
Procurement authority concentrates in integrated delivery networks that negotiate enterprise contracts spanning multiple care sites and standardize respiratory testing menus across affiliated facilities.
- Hospitals:Acute care facilities operate high-complexity laboratories with 24-hour STAT capabilities for emergency department respiratory triage. Centralized microbiology services in the United States favor automated molecular platforms that integrate with laboratory information systems.
- Diagnostic Laboratories:Independent reference labs and commercial testing chains process high specimen volumes through batch workflow optimization. Quest Diagnostics and LabCorp procurement patterns influence reagent pricing and platform standardization across the segment.
- Home Care:Self-collection kits with mail-back logistics bypass clinical site constraints for low-acuity respiratory screening. Direct-to-consumer channels are gaining regulatory clarity as FDA guidance on home specimen stability matures.
- Point-of-Care:Decentralized settings including urgent care, retail clinics, and physician offices prioritize sub-one-hour turnaround for respiratory differential diagnosis. CLIA-waived assay designations determine menu accessibility for non-laboratory personnel.
Hospitals command the largest procurement budgets, while point-of-care is expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive molecular platforms from consumable-heavy immunoassay workflows, with microbiological culture occupying a declining cost position as rapid methods displace gold-standard confirmation.
- NAAT:Nucleic acid amplification technology encompasses PCR, isothermal methods, and transcription-mediated amplification with defined analytical sensitivity thresholds. Multiplex respiratory panels from BioFire and GenMark anchor hospital laboratory adoption.
- Immunoassay:Enzyme-linked and chemiluminescent antibody-antigen binding assays deliver protein-level detection without nucleic acid extraction. Seasonal influenza and COVID-19 screening volumes sustain manufacturing scale for lateral flow and laboratory-based formats.
- Microbiological Culture:Traditional growth-based identification with biochemical confirmation retains regulatory status as definitive reference method. Reference laboratories maintain capacity for antimicrobial susceptibility testing and atypical pathogen recovery.
- Mass Spectrometry:Matrix-assisted laser desorption ionization time-of-flight identifies cultured organisms through protein fingerprint matching. Capital equipment requirements limit deployment to large academic medical centers with specialized technical staff.
NAAT dominates current installed base, with mass spectrometry gaining share fastest among large reference laboratories.
Application:
Test menu breadth determines competitive positioning as vendors bundle respiratory targets into syndromic panels that replace standalone assays and capture differential diagnostic reimbursement.
- Influenza:Seasonal A/B typing with H1N1/H3N2 subtyping supports antiviral stewardship and surveillance reporting. Public health laboratories in the United States coordinate with CDC for strain matching and vaccine effectiveness monitoring.
- COVID-19:SARS-CoV-2 detection with variant discrimination capabilities sustains residual testing volume after pandemic peak. Wastewater surveillance and immunocompromised patient monitoring extend commercial relevance beyond acute diagnostic demand.
- RSV:Respiratory syncytial virus identification in pediatric and elderly populations guides isolation protocols and prophylactic antibody administration. Neonatal intensive care units and long-term care facilities concentrate seasonal procurement.
- Adenovirus:Multi-type detection addresses outbreaks in military barracks, childcare facilities, and transplant units where severe disseminated disease occurs. Niche testing volume limits dedicated assay development, favoring multiplex inclusion.
COVID-19 retains the largest cumulative test volume, with RSV showing the steepest expansion trajectory in pediatric-focused health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The respiratory pathogen testing industry traces its commercial scale to post-World War II virology laboratories in the United States, where standardized influenza surveillance networks established the infrastructure for molecular diagnostic expansion that later spread to European and Asian healthcare systems.
United States
Hospital consolidation into integrated delivery networks concentrates procurement authority among fewer buyers, favoring vendors with comprehensive respiratory menus. The FDA's EUA framework accelerates assay deployment during seasonal surges, reducing validation timelines for novel targets. Boston and Research Triangle Park host dense clusters of molecular diagnostics firms developing syndromic panel technologies.
Germany
Thermal-stable polymerase and fluorescent probe manufacturing clusters create supply-side concentration for European reagent demand. The EU MDR transition imposes elevated clinical evidence requirements that delay in vitro diagnostic recertification for mid-tier manufacturers. Munich and Frankfurt anchor reference laboratory networks that drive adoption of automated sample-to-answer platforms.
China
Domestic health system investment in pandemic preparedness sustains procurement volumes for respiratory surveillance infrastructure. The NMPA governs premarket authorization pathways for molecular assays under evolving technical review standards. Shanghai and Beijing concentrate manufacturing capacity for PCR thermal cyclers and nucleic acid extraction systems.
Japan
Aging demographics and seasonal respiratory burden drive demand for rapid differential diagnosis in outpatient settings. METI coordinates industrial policy supporting point-of-care diagnostic platform development through targeted R&D subsidies. The Kanto region around Tokyo hosts specialized manufacturers of isothermal amplification technologies.
United Kingdom
NHS Test and Trace institutional capacity sustains residual demand for high-throughput respiratory testing infrastructure. MHRA post-Brexit regulatory autonomy enables streamlined approval pathways distinct from EU MDR timelines. The Cambridge-Oxford-London corridor concentrates sequencing-based surveillance expertise and academic-industry partnerships.
Respiratory Pathogen Testing Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the respiratory diagnostics value chain, creating a tiered market structure where integrated platform vendors face pressure from modular assay developers. The vendor base clusters around three strategic archetypes: multinational conglomerates with broad life science portfolios, specialized molecular diagnostics firms with syndromic panel expertise, and emerging point-of-care technology developers. Consolidation through acquisition of complementary assay menus and geographic expansion through distribution partnerships constitute the dominant competitive moves reshaping market boundaries.
Among United States-based conglomerates, Abbott Laboratories and Thermo Fisher Scientific exemplify the integrated platform archetype, while France-based bioMérieux SA occupies a specialized position within the syndromic panel segment. These three firms anchor distinct competitive vectors—Abbott through point-of-care molecular architecture, Thermo Fisher through captive reagent and instrumentation supply, and bioMérieux through differentiated multiplex respiratory panels—representing the primary strategic postures available to market participants.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Thermo Fisher Scientific |
| bioMérieux SA |
| Roche Diagnostics |
| QuidelOrtho Corporation |
| Becton Dickinson and Company |
| Danaher Corporation |
| QIAGEN N.V. |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's health resilience provisions gate both qualified reagent supply and premium-tier pricing access for respiratory diagnostic platforms, forcing manufacturers to demonstrate carbon footprint compliance and circular material flows before procurement committees will approve above-market contract rates.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared multiplex panels from CE-marked equivalents and unvalidated research-use-only assays. Price differentiation hinges on regulatory tier and after-sales service bundling, with integrated service contracts capturing hospital procurement preference. Cost compression in the economy tier intensifies because antigen test substitution erodes molecular test reimbursement ceilings. Point-of-care clinics exhibit highest price sensitivity, while academic medical centers prioritize analytical sensitivity over unit cost.
Supply Chain Analysis
Cold-chain logistics costs for temperature-sensitive enzymes and probes constrain distribution economics for decentralized testing networks. Manufacturing concentrates in Germany, the United States, and China for thermal-stable polymerase, fluorescent probe synthesis, and PCR thermal cycler assembly respectively. Raw material dependencies include recombinant DNA polymerases, modified nucleotides, and optical-grade plastics. Single-source vulnerability clusters around German reagent suppliers create geographic concentration risk. Distribution runs through integrated delivery network procurement offices and specialized laboratory distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in respiratory diagnostics rests on automation-driven labor cost reduction and the shift toward syndromic panel premiums that capture differential diagnostic reimbursement.
For Market Incumbents: Anchor market position through backward integration into reagent manufacturing and exclusive GPO contracting with integrated delivery networks. Antigen test substitution threatens molecular volume in ambulatory settings. Captive supply of PCR enzymes and probes insulates margin structure from raw material volatility. For New Entrants and Emerging Players: Begin with CLIA-waived point-of-care assays targeting urgent care chains and retail clinics where turnaround time commands price premium. Home-based collection infrastructure represents the most penetrable white-space segment. Direct-to-consumer channels with telehealth integration offer lowest regulatory barrier to initial commercial traction. For Investors and Strategic Acquirers: Roll-up economics work for specialized syndromic panel developers because hospital consolidation favors vendors with broad respiratory menu coverage. Five-to-ten year viability hinges on regulatory infrastructure scalability. Target acquisition profile centers on firms with FDA master file submissions and established clinical evidence packages. The signal to watch is EU MDR recertification velocity as a proxy for mid-tier manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Recertification Pathway | EMA conformity assessment timelines determine European market access for mid-tier IVD manufacturers. |
| Hospital System Partnership | Integrated delivery network contracting secures multi-year reagent supply commitments and platform standardization. |
| Software Companion Development | AI-assisted Ct interpretation algorithms differentiate routine panels from commodity testing under EU AI Act governance. |
| Reimbursement Strategy | CPT code maintenance and value demonstration sustain molecular test pricing against antigen substitution pressure. |
| CE Marking Pathway | Notified body clinical evidence requirements filter market access toward manufacturers with robust quality systems. |
Research Methodology
Bottom-up hospital laboratory modeling reconciled against top-down reagent manufacturer tracking forms the analytical core of this study. Primary interviews with clinical laboratory directors, hospital procurement committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA EUA filings, EMA MDR submissions, hospital procurement databases, and CMS Medicare reimbursement data. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map specimen volume flows through detection methodology, care setting, and target pathogen dimensions across the projection horizon. Segmentation modeling captures technology tier, end-user concentration, application menu breadth, and regional regulatory cluster effects. CAGRs derive from installed base replacement cycles, syndromic panel adoption curves, and reimbursement trajectory analysis. Forecast inputs include seasonal respiratory surveillance patterns and pandemic preparedness investment schedules.
Several conditions sit outside the modeled scope, including novel pathogen emergence timelines and radical technology disruption from CRISPR-based detection platforms. Forecasts reflect assumptions about regulatory pathway stability and reimbursement code maintenance. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Clinical Diagnosis Automation Market
Clinical Diagnostics
Global Biomarkers Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Europe Colorectal Cancer Screening Market
Clinical Diagnostics
Heart Failure Testing Market
Clinical Diagnostics
Renal Function Test Market
Clinical Diagnostics
Clinical Microbiology Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Bacterial and Viral Specimen Collection Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
H. Pylori (Helicobacter Pylori) Test Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics and Therapeutics Market
Clinical Diagnostics
Global Minimal Residual Disease Market
Clinical Diagnostics
Pediatric Cardiac Tumor Diagnostics Market
Clinical Diagnostics
Herpes Marker Testing Market
Clinical Diagnostics
Serum Free Light Chain Assays (Sflc) Market