
 Population Screening Market | 2026-2036
Population Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Population Screening Market Intelligence
Next-generation sequencing-grade assay standards is reorganizing competitive dynamics in population screening. Thermo Fisher Scientific leverages its ion semiconductor platform to anchor clinical laboratory workflows. Illumina sustains instrument installed-base dominance across large-scale genomic screening networks. QIAGEN differentiates through sample-to-insight automation that reduces hands-on time for high-throughput facilities.
Population screening comprises systematic testing of asymptomatic cohorts to detect disease precursors or early-stage pathology, typically employing biomarker thresholds, imaging resolution parameters, or variant allele frequency cutoffs to stratify risk and trigger intervention protocols. Molecular diagnostics occupies the highest-margin tier within technology segmentation, driven by companion diagnostic linkages and precision medicine reimbursement tailwinds. Point-of-care testing captures the fastest expansion trajectory as decentralized access models displace centralized laboratory routing for infectious disease screening. Genetic tests within screening type segmentation command premium pricing but face utilization management constraints from payers.
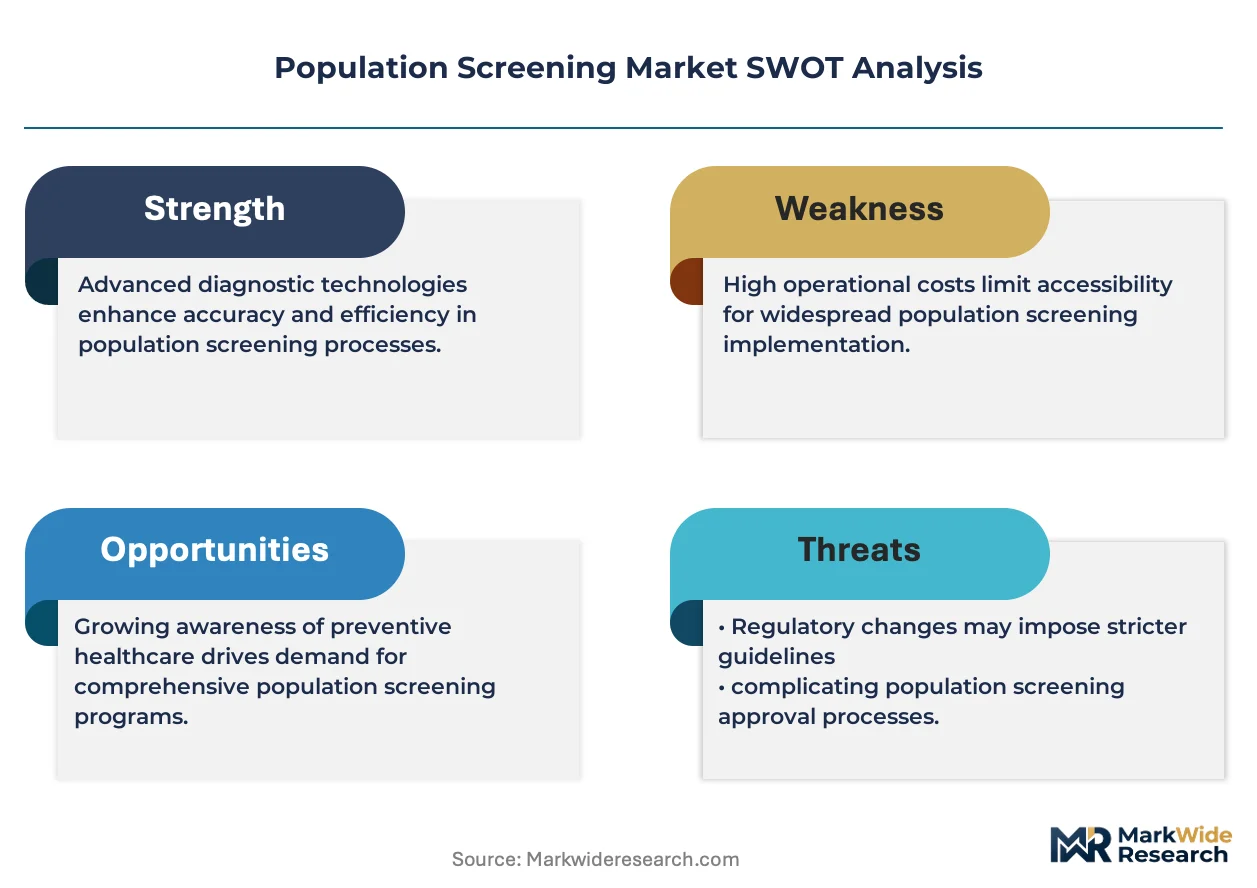
FDA premarket approval and CMS national coverage determination processes govern commercial access for novel screening modalities in the United States, while the EMA's In Vitro Diagnostic Regulation reshapes conformity assessment burdens for European market entry. The Clinical Laboratory Improvement Amendments framework mandates proficiency testing and quality control standards that directly influence laboratory operational costs and platform selection criteria. Stakeholders must monitor evolving multi-cancer early detection coverage decisions by national payers to calibrate portfolio investment priorities between single-analyte and multiplex assay development tracks.
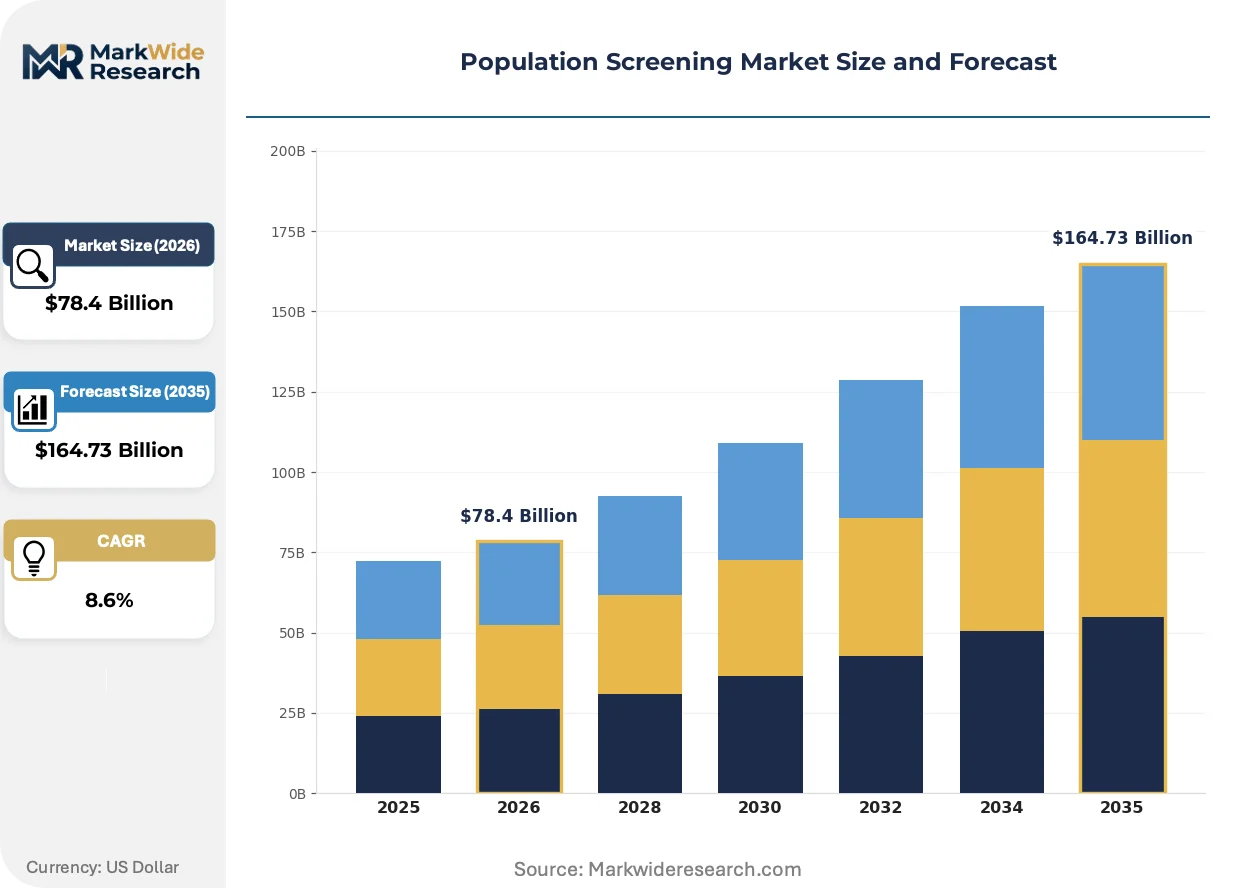
Market Dynamics
The transition from centralized laboratory workflows to decentralized point-of-care testing is restructuring capital deployment and reimbursement patterns across the population screening ecosystem.
Growth Catalysts
- Medicare reimbursement expansion:CMS national coverage determinations for liquid biopsy protocols in the United States are accelerating clinical adoption of multi-cancer early detection assays.
- Hospital network consolidation:Integrated delivery systems are standardizing screening protocols across regional footprints, creating volume commitments that justify platform investments.
- Next-generation sequencing throughput gains:Semiconductor-based sequencing chemistries are compressing per-sample costs below critical reimbursement thresholds.
Market Restraints
- Proficiency testing burdens:CLIA-mandated quality control requirements impose recurring operational costs that disproportionately burden mid-capacity laboratories.
- IVDR conformity assessment bottlenecks:European notified body capacity constraints are extending time-to-market for novel assay developers by 18-24 months.
- Variant interpretation complexity:Ambiguous clinical significance of rare genetic variants generates downstream counseling costs and liability exposure.
Strategic Opportunities
- Rural health clinic penetration:Federally qualified health centers in the United States represent an underpenetrated channel for infectious disease screening decentralization.
- Employer-sponsored wellness integration:Self-insured corporations are piloting annual screening mandates as population health management tools.
- AI-augmented radiology workflows:Machine learning classification algorithms paired with low-dose CT protocols are expanding lung cancer screening eligibility pools.
Industry Challenges
- Bioinformatics specialist scarcity:Variant curation and pipeline validation require hybrid skill sets spanning molecular biology and computational statistics that command premium compensation.
- LIMS integration complexity:Legacy laboratory information management systems require costly middleware development to accommodate multi-omics data structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Population Screening Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $164.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Screening Type: Blood Tests, Imaging Tests, Genetic Tests, Urinalysis End User: Hospitals, Clinics, Laboratories, Community Health Organizations Application Area: Cancer Screening, Infectious Disease Screening, Cardiovascular Screening, Metabolic Disorder Screening Technology: Molecular Diagnostics, Immunoassays, Microarrays, Point-of-Care Testing |
| Companies Covered | Agilent Technologies, Thermo Fisher Scientific, QIAGEN, F. Hoffmann-La Roche Ltd., Quest Diagnostics, Illumina, ARUP Laboratories, Novogene, LGC Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Population Screening Market Strategic Shifts & Innovations
Artificial intelligence is penetrating every layer of the screening value chain, from image interpretation to risk stratification algorithms, compressing both diagnostic timelines and specialist labor requirements.
Multi-cancer early detection assays combining cell-free DNA methylation signatures with machine learning classifiers are supplanting organ-specific screening modalities in commercial development pipelines. Large health systems with captive biobanks are piloting these platforms for asymptomatic cohorts. The shift is compressing addressable market timelines for single-analyte developers while elevating bioinformatics infrastructure requirements.
The FDA's breakthrough device designation pathway for combination diagnostics is accelerating premarket review timelines for assays with companion diagnostic claims. This regulatory tailwind is concentrating venture funding in multiplex platform developers. Oncology therapeutic franchises are responding by internalizing liquid biopsy capabilities to secure biomarker access.
Self-collection specimen workflows are displacing phlebotomy-dependent routing in infectious disease screening, particularly in sexual health and respiratory panels. Retail pharmacy chains are deploying these kits through e-commerce fulfillment models. The United Kingdom and Australia are witnessing the fastest channel migration, driven by national health service backlog pressures and consumer convenience preferences.
Population Screening Market Segmentation
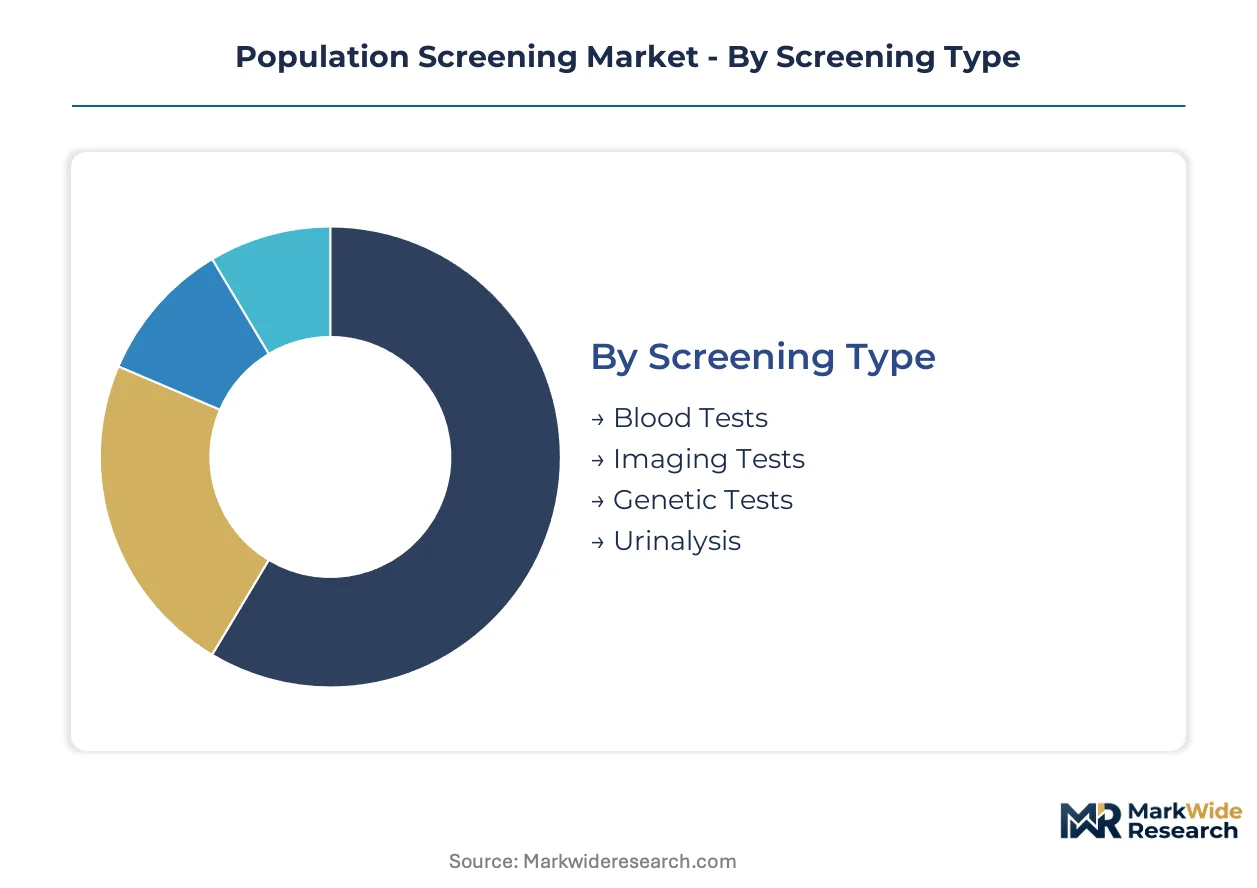
Population screening markets fragment across four critical dimensions that determine reimbursement pathways, capital intensity, and competitive moats. Technology and screening type classifications most directly shape platform economics and regulatory submission strategies.
Screening Type:
Blood tests and genetic tests concentrate commercial investment in the United States, where CMS coverage determinations create domestic demand anchors. Imaging tests and urinalysis retain stronger export orientation toward European and Asia-Pacific health systems.
- Blood Tests:Liquid biopsy platforms analyze cell-free DNA and circulating tumor cells through next-generation sequencing workflows. Medicare reimbursement for multi-cancer early detection assays is accelerating hospital laboratory adoption in the United States.
- Genetic Tests:Germline variant screening employs targeted panels and whole-exome sequencing to stratify hereditary cancer risk. Payer utilization management constraints in the United States limit routine deployment despite premium pricing tiers.
- Imaging Tests:Low-dose CT, mammography, and MRI protocols dominate lung and breast screening programs.
- Urinalysis:Dipstick and automated microscopy methods persist in metabolic and infectious disease detection.
Blood tests hold the largest share; momentum sits with genetic tests as polygenic risk scores mature.
End User:
Capital deployment patterns split between centralized laboratory networks demanding high-throughput automation and decentralized sites prioritizing workflow simplicity.
- Hospitals:Integrated delivery systems consolidate screening protocols across regional footprints, justifying multi-million dollar sequencing platform investments through volume commitments. Hospital networks in the United States are expanding preventive screening programs to capture Medicare reimbursement expansion.
- Laboratories:Reference and clinical laboratories process high-complexity molecular diagnostics under CLIA proficiency testing mandates. Mid-capacity laboratories face disproportionate quality control cost burdens that influence platform selection criteria.
- Clinics:Federally qualified health centers represent underpenetrated channels for infectious disease screening decentralization.
- Community Health Organizations:Nonprofit and municipal health departments target underserved populations through grant-funded screening initiatives.
Hospitals command the highest revenue concentration; clinics are expanding most quickly through point-of-care testing adoption.
Application Area:
Disease-specific screening programs align with distinct reimbursement codes and regulatory review pathways across national health systems.
- Cancer Screening:Multi-cancer early detection assays combining methylation signatures with machine learning classifiers are supplanting organ-specific modalities in commercial pipelines. FDA breakthrough device designations are accelerating premarket review timelines for combination diagnostics.
- Infectious Disease Screening:Self-collection specimen workflows are displacing phlebotomy-dependent routing, particularly in sexual health and respiratory panels. Retail pharmacy chains in the United Kingdom and Australia are deploying e-commerce fulfillment models.
- Cardiovascular Screening:Lipid panels and biomarker assays target asymptomatic cohorts through employer-sponsored wellness programs.
- Metabolic Disorder Screening:Diabetes and thyroid function tests integrate with chronic disease management protocols.
Cancer screening dominates R&D investment; infectious disease screening gains share fastest through decentralized access models.
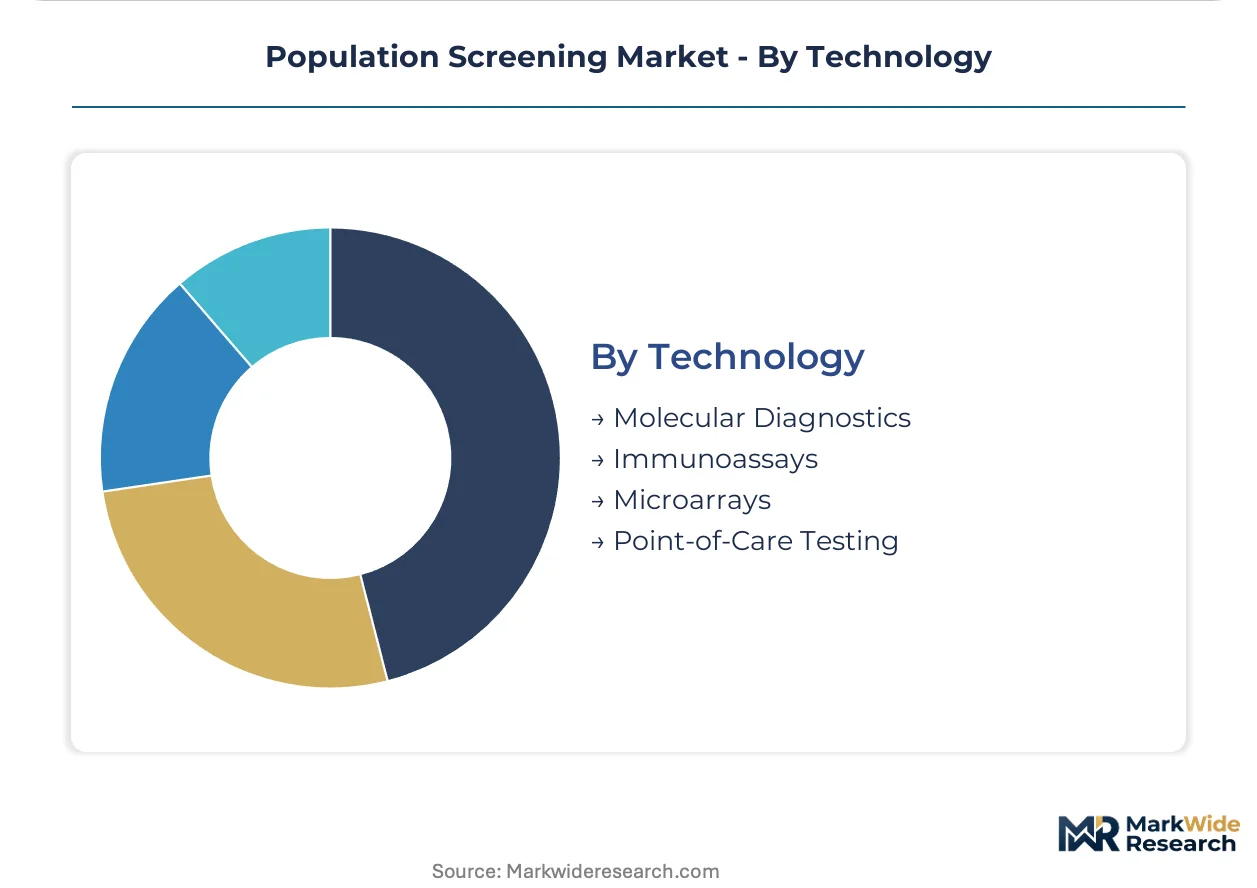
Technology:
Platform selection criteria center on throughput scalability, hands-on time reduction, and bioinformatics infrastructure requirements.
- Molecular Diagnostics:Next-generation sequencing and PCR-based methods occupy the highest-margin tier, driven by companion diagnostic linkages and precision medicine reimbursement tailwinds. Semiconductor-based sequencing chemistries are compressing per-sample costs below critical reimbursement thresholds.
- Point-of-Care Testing:Decentralized access models displace centralized laboratory routing for infectious disease screening, capturing the steepest expansion trajectory across the technology landscape.
- Immunoassays:Enzyme-linked and chemiluminescent methods persist in high-volume protein biomarker detection.
- Microarrays:Genotyping arrays retain cost advantages for targeted variant detection in direct-to-consumer and research applications.
Molecular diagnostics generates the highest margins; point-of-care testing climbs the fastest as workflow decentralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependency for sequencing instruments and assay reagents shapes trade flows across major population screening markets. The United States runs substantial deficits in molecular diagnostics hardware while exporting specialized reference laboratory services. Germany and China maintain more balanced positions through domestic manufacturing of mid-range platforms.
United States
Hospital network consolidation drives demand for high-throughput screening infrastructure. FDA breakthrough device designations accelerate commercialization timelines for multi-cancer early detection assays. The Boston-Cambridge corridor anchors liquid biopsy development clusters where academic medical centers pilot novel screening protocols.
Germany
Precision medicine reimbursement frameworks sustain molecular diagnostics demand across statutory health insurance pools. EMA In Vitro Diagnostic Regulation conformity assessments reshape market entry requirements for assay developers. The Munich-Stuttgart industrial corridor concentrates automated laboratory platform manufacturing for European distribution.
China
National cancer screening program expansion targets rural population coverage gaps through mobile testing units. NMPA regulatory reforms compress premarket review timelines for innovative diagnostics. The Yangtze River Delta biotech cluster incubates domestic liquid biopsy developers competing with imported platforms.
United Kingdom
National Health Service backlog pressures accelerate self-collection specimen workflow adoption for infectious disease screening. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for breakthrough diagnostics. London's research hospital networks pilot AI-augmented radiology screening for lung cancer eligibility expansion.
Japan
Aging demographic profiles expand asymptomatic screening program enrollment through employer-sponsored health insurance. PMDA regulatory harmonization initiatives align domestic approval requirements with FDA precedents. The Kanto region's diagnostic imaging equipment manufacturers supply low-dose CT systems for national cancer screening infrastructure.
Population Screening Market Key Industry Players
Concentration sits with diversified life science conglomerates controlling instrument platforms and reagent supply chains. The vendor landscape organizes around three strategic archetypes: sequencing platform developers anchoring laboratory workflows, sample-to-insight automation specialists reducing operational complexity, and reference laboratory networks capturing screening volume through health system contracts. Competitive moves center on strategic partnerships securing biomarker access and portfolio diversification into companion diagnostic linkages.
Among diversified platform developers, Thermo Fisher Scientific and Illumina occupy positions anchoring clinical laboratory infrastructure. QIAGEN exemplifies the sample-to-insight automation archetype. These three companies represent the dominant competitive anchors shaping technology adoption patterns and procurement criteria across hospital and laboratory end users.
| Leading Market Players |
|---|
| Agilent Technologies |
| Thermo Fisher Scientific |
| QIAGEN |
| F. Hoffmann-La Roche Ltd. |
| Quest Diagnostics |
| Illumina |
| ARUP Laboratories |
| Novogene |
| LGC Limited |
| Others |
Cost & Logistics Intelligence
CLIA proficiency testing mandates and FDA premarket approval pathways gate both supplier qualification and price differentiation simultaneously in the population screening market. Laboratories bearing these compliance burdens pass elevated operational costs downstream, while assay developers with breakthrough device designations command premium positioning through reimbursement security.
Pricing Analysis
Hospital laboratory procurement committees anchor contract-based long-term offtake structures for high-throughput sequencing platforms. Price differentiation separates CLIA-certified reference laboratories from mid-capacity facilities lacking scale economies, with semiconductor-based chemistry tiers compressing per-sample costs. Pricing pressure stems from Medicare reimbursement rate compression for routine screening panels. Federally qualified health centers exhibit highest price sensitivity; integrated delivery systems with captive volume commitments demonstrate lowest.
Supply Chain Analysis
The United States and Germany anchor precision instrument manufacturing for next-generation sequencing platforms, while China incubates domestic liquid biopsy assay development. Sequencing-grade reagents, semiconductor chips, and methylation-specific oligonucleotides constitute critical input dependencies. Single-source vulnerability concentrates in ion semiconductor foundry capacity. Distribution runs through integrated delivery system procurement consortia and reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workflow decentralization fragments demand across point-of-care, hospital laboratory, and centralized reference tiers, creating specialization niches for platform developers and automation specialists alike.
For Market Incumbents: Shield installed-base positions through backward integration into methylation-specific reagent supply and captive bioinformatics pipeline development. Consolidate CLIA laboratory networks to secure volume commitments against emerging decentralized testing entrants. Prioritize FDA breakthrough device pathway investments for multi-cancer early detection assay portfolios. For New Entrants and Emerging Players: Lead with AI-augmented radiology workflows targeting lung cancer screening eligibility expansion in United Kingdom and Australian health systems. Capture rural health clinic infectious disease screening channels through self-collection specimen logistics. Deploy employer-sponsored wellness program pilots as direct-to-corporate go-to-market angles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across point-of-care testing sub-segments as semiconductor manufacturing scales compress hardware costs. Five-to-ten year viability favors sample-to-insight automation specialists with proprietary extraction chemistry IP. Monitor CMS national coverage determination timelines for multi-cancer early detection as primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CLIA Laboratory Network Acquisition | Captures Medicare reimbursement volume through integrated delivery system contracts. |
| FDA Breakthrough Device Designation Pursuit | Accelerates premarket review timelines for multi-cancer early detection assays. |
| Semiconductor Sequencing Chemistry Scale-Up | Compresses per-sample costs below critical reimbursement thresholds. |
| AI-Augmented Radiology Partnership | Expands lung cancer screening eligibility pools through machine learning classifiers. |
| Self-Collection Specimen Workflow Deployment | Displaces phlebotomy-dependent routing in retail pharmacy channels. |
Research Approach
Cross-validation between hospital laboratory directors and CMS reimbursement policy specialists anchors the qualitative findings. Primary interviews with clinical laboratory managers, FDA regulatory affairs leads, GPO contracts managers, and biomedical engineers combined with secondary validation against FDA 510(k) filings, CMS national coverage determination databases, Clinical Laboratory Improvement Amendments proficiency testing records, and hospital procurement databases. Bottom-up assay volume estimates triangulate against top-down health system expenditure models.
Sensitivity analysis tested forecast robustness across screening type, technology platform, end-user facility scale, and application area dimensions over the projection horizon. CAGRs derived from logistic adoption curves for multi-cancer early detection assays and linear extrapolation for mature immunoassay segments. Forecast inputs incorporate Medicare reimbursement rate trajectories and NMPA regulatory reform timelines.
The analysis sits within stated boundaries; outcomes outside sustained CMS coverage expansion or EMA IVDR notified body capacity resolution would require recalibration. Forecasts reflect documented assumptions regarding semiconductor manufacturing scale and liquid biopsy clinical validation timelines. Recalibration cycles align with material shifts in national payer coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostics
Extraction Kits Market
Diagnostics
Antigen Kit Market
Diagnostics
Multiplexed Diagnostics Market
Diagnostics
Middle East and Africa HIV Diagnosis and Treatment Market
Diagnostics
Sexually Transmitted Diseases Diagnostics Market
Diagnostics
Global Cervical Cancer Diagnostics Market
Diagnostics
Cancer IVD Market
Diagnostics
Self-Administered HPV Test Market
Diagnostics
Thrombosis and Hemostasis Biomarkers Market
Diagnostics
Multiple Myeloma Diagnostics Market
Diagnostics
Global Phytopathological Disease Diagnostics Market
Diagnostics
D-Dimer Market
Diagnostics
Antigen Skin Test Market
Diagnostics
Total Iron Binding Capacity Reagents Market
Diagnostics
United States Melanoma Diagnostics & Therapeutics Market
Diagnostics
Global Autoimmune Disease Diagnostics Market