
 Antenatal Screening Market | 2026-2036
Antenatal Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Antenatal Screening Market Outlook
Multi-source procurement of sequencing reagents and assay platforms is expanding as health systems diversify beyond single-vendor dependencies. Illumina leverages its installed base of next-generation sequencing systems to anchor high-throughput non-invasive prenatal testing workflows across major laboratory networks. Thermo Fisher Scientific competes through integrated sample-to-answer workflows that reduce turnaround times for serum biochemistry panels. Natera specializes in proprietary cell-free DNA analytics, differentiating its risk-assessment offerings through algorithmic refinement and clinical validation depth.
Antenatal screening encompasses diagnostic and surveillance protocols applied during gestation to detect fetal anomalies, chromosomal abnormalities, and maternal health risks through biochemical, imaging, and genomic modalities. Cell-free DNA sequencing from maternal plasma enables detection of trisomies with specificity exceeding conventional serum screening, while transabdominal ultrasound remains the foundational modality for structural fetal assessment. Non-invasive prenatal testing commands the fastest expansion trajectory among product categories as reimbursement frameworks broaden and clinical guidelines elevate its role in first-trimester protocols. Diagnostic laboratories represent the most concentrated margin pool within end-user channels, given their scale economies and centralized processing capacity for high-complexity molecular assays.
FDA premarket authorization pathways and CLIA laboratory certification requirements shape market access for novel antenatal assays in the United States, while the EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards for genetic screening kits entering European markets. EMA coordination with national competent authorities creates fragmented but tightening compliance landscapes across member states. Stakeholders must monitor evolving payer coverage determinations for expanded carrier screening panels and prepare for harmonization pressures between decentralized laboratory-developed test frameworks and centralized kit-based regulatory models.
Market Dynamics
The migration from serum-based biochemical screening to cell-free DNA sequencing protocols is compressing diagnostic timelines while elevating accuracy thresholds across maternal-fetal medicine workflows.
Growth Catalysts
- FDA premarket authorization pathways:Streamlined de novo and 510(k) routes for non-invasive prenatal testing assays accelerate commercialization timelines for molecular diagnostic developers targeting high-risk pregnancy populations.
- Cell-free DNA sequencing:Advances in next-generation sequencing chemistries and bioinformatics pipelines enable detection of fetal aneuploidies from maternal plasma with specificity exceeding conventional quad screens.
- Specialized maternal-fetal medicine infrastructure:Concentrated investments in perinatal centers across the United States, China, and Germany expand access to high-complexity prenatal diagnostics for advanced maternal age cohorts.
Market Restraints
- Sequencing reagent cost volatility:Polymerase and library preparation kit pricing fluctuations compress margins for high-throughput diagnostic laboratories processing cell-free DNA panels at scale.
- EU In Vitro Diagnostic Regulation clinical evidence requirements:Stricter performance validation standards for genetic screening kits create extended regulatory timelines and documentation burdens for European market entry.
- Ultrasound accessibility:Transabdominal sonography remains the foundational structural assessment modality, limiting near-term displacement potential for imaging-dependent anomaly detection protocols.
Strategic Opportunities
- Expanded carrier screening panels:Broader reimbursement coverage for preconception and prenatal carrier testing creates white space for autosomal recessive and X-linked condition screening beyond common aneuploidies.
- Algorithmic risk stratification:Integration of machine learning with cell-free DNA analytics enables personalized probability scoring for fetal chromosomal abnormalities.
- Decentralized laboratory-developed test frameworks:CLIA-certified high-complexity laboratories in the United States retain flexibility to validate and deploy proprietary assays outside centralized kit-based regulatory models.
Industry Challenges
- Bioinformatics specialist scarcity:Shortages of computational biologists trained in fetal fraction estimation and chromosomal representation analysis constrain assay development velocity.
- Harmonization between LDT and IVD regulatory models:Diagnostic laboratories face operational complexity navigating divergent compliance requirements for laboratory-developed tests versus FDA-cleared kit-based platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Antenatal Screening Market |
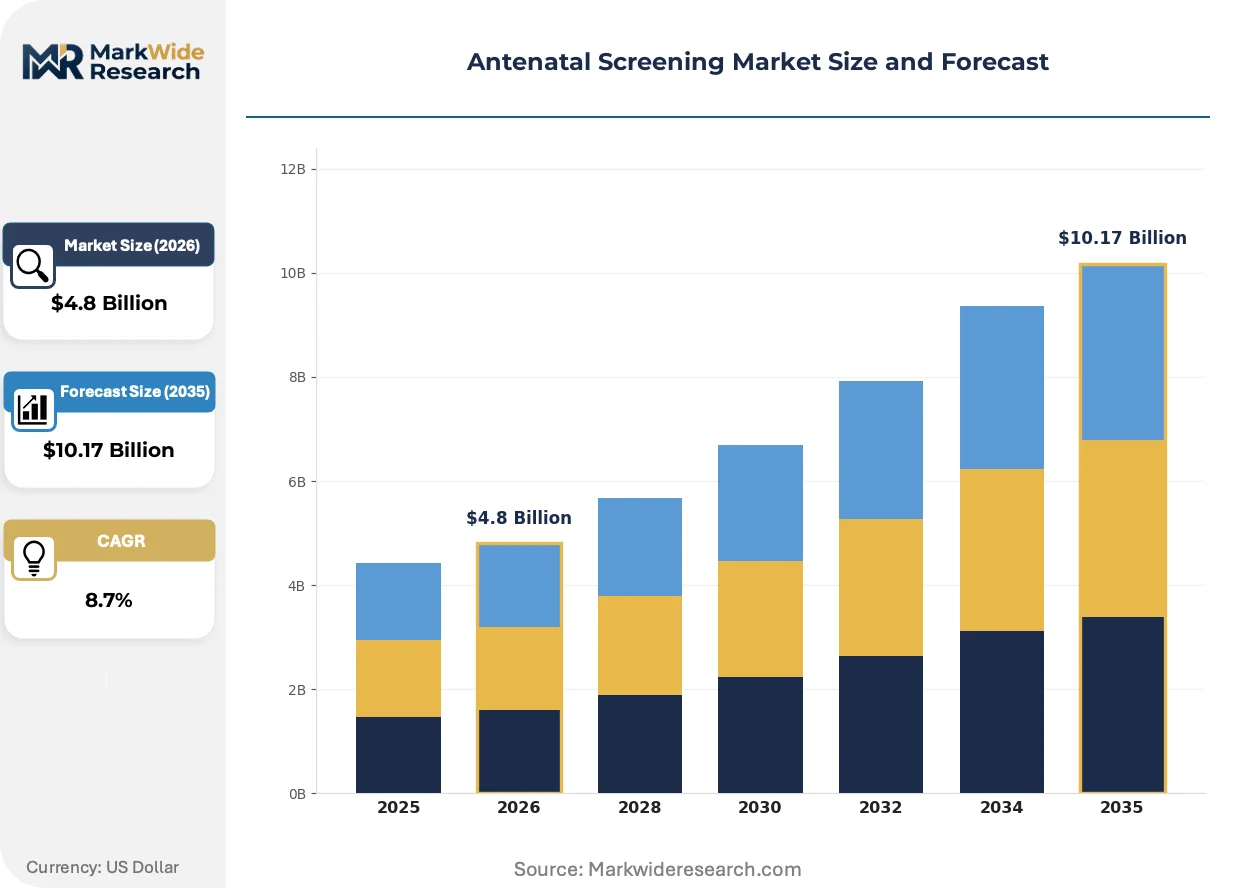
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, Blood Tests, Genetic Testing, Non-Invasive Prenatal Testing Technology: Transabdominal Ultrasound, Digital Imaging, Serum Biochemistry, Cell-Free DNA Sequencing End User: Hospitals, Diagnostic Laboratories, Private Clinics, Home Care Providers Application: Risk Assessment, Fetal Development Monitoring, Genetic Disorder Screening, Maternal Health Evaluation |
| Companies Covered | Guardant Health, Invitae, Illumina, Labcorp, Quest Diagnostics, Thermo Fisher Scientific, Natera, Myriad Genetics, Roche Diagnostics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Antenatal Screening Market Strategic Shifts
Antenatal screening workflows are converging around automated sample-to-answer platforms that compress turnaround times while integrating multi-omic data streams for comprehensive risk assessment.
Microfluidic sample preparation systems are integrating with capillary electrophoresis and mass spectrometry detection modules to automate serum biochemistry panel processing. Hospital laboratories in the United States and Germany are deploying these platforms to reduce manual pipetting steps and standardize pre-analytical variables. This integration is enabling same-day result delivery for first-trimester combined screening protocols.
The EU In Vitro Diagnostic Regulation is imposing stricter clinical evidence standards for genetic screening kits entering European markets, requiring prospective validation studies and enhanced post-market surveillance. Manufacturers must demonstrate analytical validity across diverse fetal fraction ranges and maternal body mass index categories. High-complexity molecular diagnostic laboratories in France and Germany are responding by consolidating validation resources and strengthening quality management systems.
Direct-to-consumer genetic testing channels are disrupting traditional obstetrician-mediated screening pathways, with expectant parents initiating carrier status inquiries prior to clinical consultation. Retail pharmacy and telehealth platforms are capturing initial touchpoints for prenatal risk awareness. This behavioral shift is most visible in the United States, where commercial laboratories are building patient-facing educational infrastructure to support informed decision-making before formal medical referral.
Antenatal Screening Market Segmentation
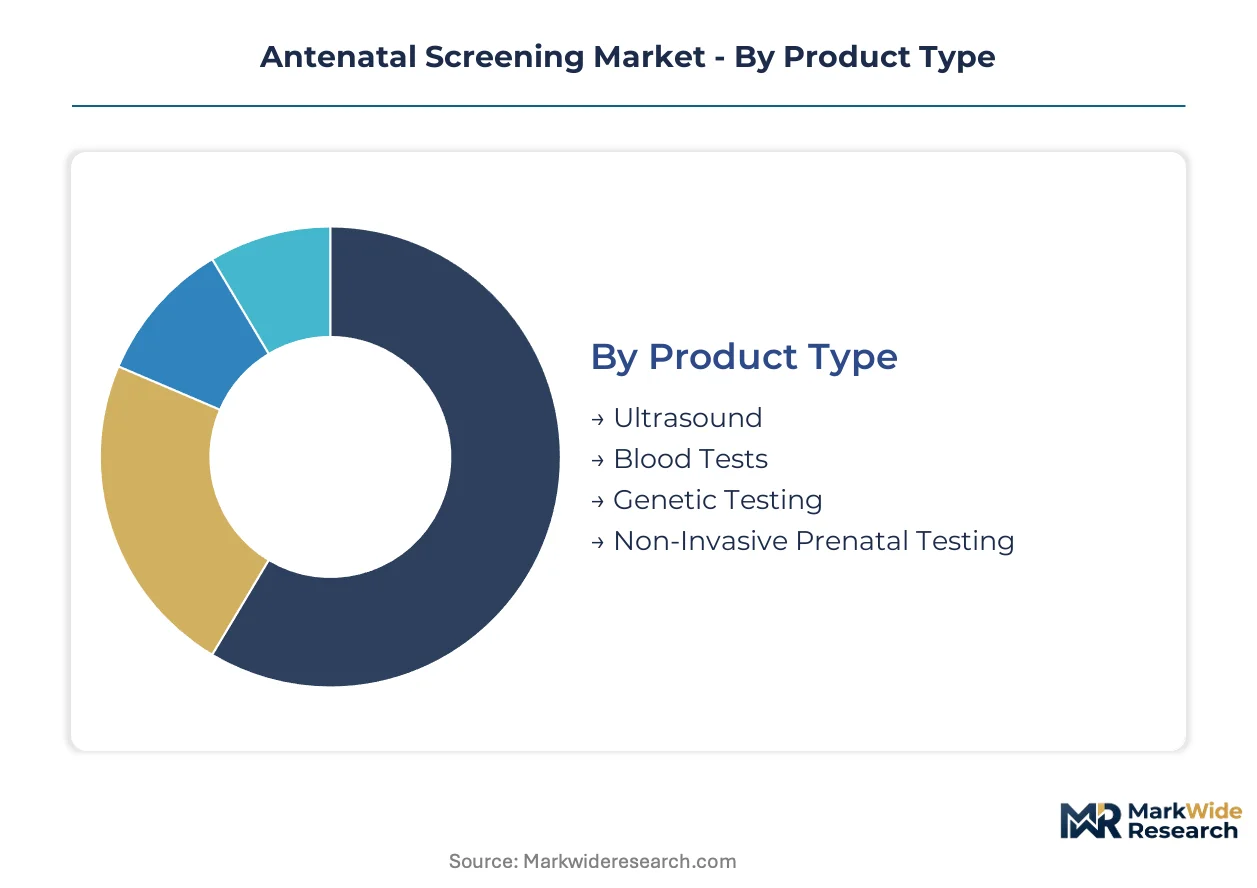
Antenatal screening segments fragment across diagnostic modality, analytical technology, and care delivery setting. Each dimension carries distinct margin profiles, regulatory pathways, and infrastructure requirements that reshape competitive positioning.
Product Type:
Standalone screening products dominate hospital procurement, while embedded multi-modality platforms concentrate in integrated health systems.
- Ultrasound:Transabdominal and transvaginal imaging systems deliver real-time structural fetal assessment. Demand concentrates in Germany and the United States where perinatal centers maintain dedicated sonography suites. Equipment refresh cycles accelerate as 3D/4D imaging capabilities become standard.
- Non-Invasive Prenatal Testing:Cell-free DNA assays from maternal plasma detect fetal aneuploidies with analytical specificity exceeding serum-based alternatives. Chinese laboratories process the highest NIPT volumes globally, driven by large birth cohorts and centralized prenatal care infrastructure.
- Blood Tests:First and second-trimester serum biochemistry panels measure pregnancy-associated plasma protein-A and human chorionic gonadotropin markers.
- Genetic Testing:Expanded carrier screening and diagnostic karyotyping identify autosomal recessive conditions and chromosomal rearrangements.
Ultrasound leads volumes today; Non-Invasive Prenatal Testing is gaining share fastest.
Technology:
Cost tiers separate mature imaging modalities from emerging molecular platforms, with capital intensity and consumable economics driving adoption divergence.
- Cell-Free DNA Sequencing:Next-generation sequencing chemistries analyze circulating fetal DNA fragments in maternal plasma. United States diagnostic laboratories deploy high-throughput Illumina and Thermo Fisher platforms for scaled NIPT processing. Reagent cost volatility and bioinformatics staffing constraints limit penetration in price-sensitive markets.
- Transabdominal Ultrasound:Real-time acoustic imaging remains the foundational structural assessment modality across all geographies. German university hospitals anchor European demand for advanced Doppler and 3D imaging systems. Equipment standardization and sonographer training pipelines sustain installed base expansion.
- Digital Imaging:Picture archiving and communication systems integrate with ultrasound hardware for centralized image management.
- Serum Biochemistry:Automated immunoassay analyzers process maternal serum markers for risk stratification protocols.
Transabdominal Ultrasound commands the largest installed base; Cell-Free DNA Sequencing shows the steepest expansion trajectory.
End User:
Customer type determines procurement scale, with consolidated laboratory networks capturing volume concentration against fragmented clinic distribution.
- Diagnostic Laboratories:High-complexity molecular diagnostic facilities process cell-free DNA panels and serum biochemistry at centralized scale. United States CLIA-certified laboratories and Chinese provincial reference centers anchor global throughput capacity. Automated sample-to-answer platforms compress turnaround times and reduce manual handling errors.
- Hospitals:Integrated health systems coordinate imaging, laboratory, and maternal-fetal medicine specialist resources under single administrative structures. German university hospitals and United States academic medical centers invest in perinatal center certification programs. Capital equipment procurement favors multi-year service contracts and vendor consolidation.
- Private Clinics:Obstetric and gynecology practices perform point-of-care ultrasound and initial risk assessment counseling.
- Home Care Providers:Remote patient monitoring platforms and telehealth-integrated screening services reach rural and underserved populations.
Diagnostic Laboratories concentrate margin pools; Private Clinics are expanding service breadth most rapidly.
Application:
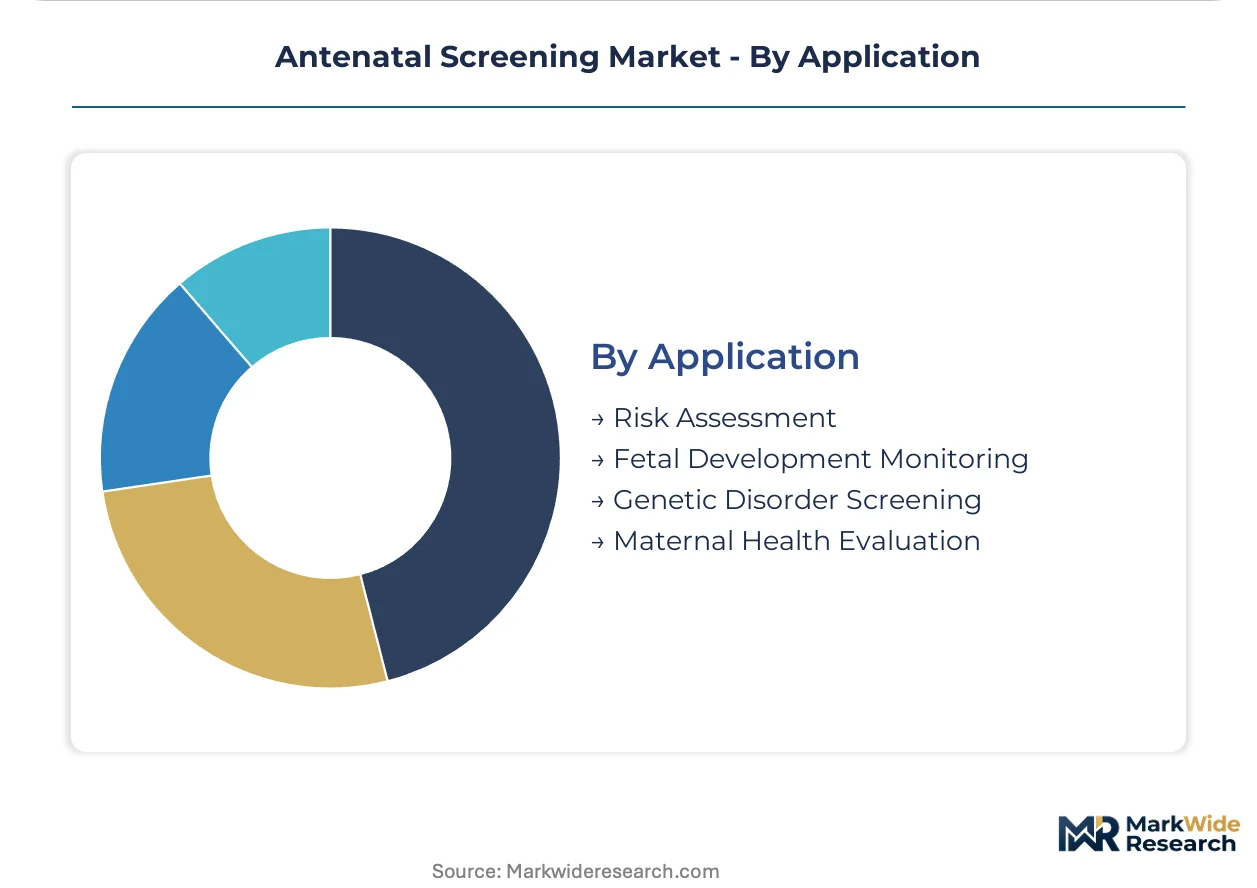
Application maturity varies by clinical guideline endorsement and reimbursement coverage, with risk assessment protocols achieving broadest payer acceptance.
- Risk Assessment:Combined first-trimester screening integrates nuchal translucency ultrasound with serum biochemistry and maternal age factors. United States obstetric practices and United Kingdom National Health Service pathways standardize risk calculation algorithms. Payer coverage determinations increasingly favor cell-free DNA reflex testing for intermediate-risk results.
- Genetic Disorder Screening:Expanded carrier panels and fetal chromosomal analysis identify autosomal recessive conditions and aneuploidies. Chinese prenatal diagnostic centers and United States reference laboratories process the highest screening volumes. Regulatory frameworks differentiate between screening and diagnostic claims, shaping commercial positioning.
- Fetal Development Monitoring:Serial ultrasound examinations track growth parameters, amniotic fluid volume, and placental function.
- Maternal Health Evaluation:Preeclampsia risk stratification and gestational diabetes screening protocols protect maternal outcomes.
Risk Assessment leads procedure volumes today; Genetic Disorder Screening is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping antenatal screening deployment as manufacturers navigate divergent compliance costs between the FDA's de novo pathways and Europe's stricter IVDR evidence requirements. Laboratories in lower-cost jurisdictions are capturing processing volume from price-sensitive health systems.
United States
Advanced maternal age demographics and commercial payer coverage expansion drive NIPT volume concentration. FDA premarket authorization pathways under de novo and 510(k) routes accelerate assay commercialization timelines. CLIA-certified high-complexity laboratories in California and Massachusetts anchor national processing capacity for cell-free DNA panels.
China
Centralized prenatal care infrastructure and large annual birth cohorts sustain the world's highest NIPT processing volumes. NMPA regulatory frameworks differentiate screening claims from diagnostic classifications. Provincial reference centers in Guangdong and Jiangsu provinces deploy automated sample-to-answer platforms at scale.
Germany
Perinatal center certification programs and statutory health insurance reimbursement frameworks elevate screening protocol standardization. EMA coordination with national competent authorities creates fragmented but tightening compliance landscapes. University hospitals in Bavaria and North Rhine-Westphalia maintain dedicated maternal-fetal medicine infrastructure.
United Kingdom
National Health Service integrated screening pathways standardize first-trimester combined screening algorithms across primary and secondary care. MHRA post-Brexit regulatory autonomy maintains alignment with IVDR standards while preserving national flexibility. London and Southeast England academic medical centers pilot expanded carrier screening panel deployment.
India
Rising obstetric specialist density and urban middle-class demand for non-invasive alternatives are compressing traditional serum screening adoption. CDSCO medical device rules govern import and domestic manufacture of prenatal diagnostic kits. Diagnostic laboratory networks in Maharashtra and Karnataka are building NIPT processing partnerships with reference facilities.
Antenatal Screening Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue algorithmic specialization and direct-to-consumer channel development. The market exhibits moderate consolidation around sequencing platform vendors and centralized laboratory networks. Three archetypes dominate: integrated life science conglomerates with reagent-to-analyzer portfolios; molecular diagnostic pure-plays with proprietary bioinformatics; and clinical laboratory networks with scale processing advantages. Competitive moves concentrate on strategic partnerships between assay developers and health system purchasers, plus vertical integration into sample preparation automation.
Among platform-anchored conglomerates, Thermo Fisher Scientific and Illumina exemplify the capital-intensive tier where installed base scale determines reagent pull-through economics. Natera occupies a position within the molecular diagnostic pure-play archetype, representing algorithmic risk-stratification specialization. These three entities anchor distinct competitive vectors: Thermo Fisher Scientific through integrated workflow breadth, Illumina through sequencing chemistry dominance, and Natera through clinical validation depth in cell-free DNA analytics.
| Leading Market Players |
|---|
| Guardant Health |
| Invitae |
| Illumina |
| Labcorp |
| Quest Diagnostics |
| Thermo Fisher Scientific |
| Natera |
| Myriad Genetics |
| Roche Diagnostics |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up diagnostic laboratory networks in the United States and China exercise consolidated purchasing power over sequencing reagent suppliers, translating volume concentration into preferential pricing tiers that compress margins for smaller regional competitors while sustaining premium positioning for FDA-cleared assay platforms.
Pricing Analysis
Distributor margins on cell-free DNA sequencing reagents typically absorb 15-25 percent of end-user pricing, with direct-to-laboratory contracts from Illumina and Thermo Fisher Scientific bypassing intermediary markups for high-throughput NIPT processors. Three-tier pricing structure across premium, standard, and economy levels separates CLIA-validated LDT workflows from kit-based FDA-cleared platforms and research-use-only reagent grades. Pricing pressure stems from Chinese provincial reference centers demanding volume discounts that outpace reagent cost deflation. Private clinics and rural hospital laboratories exhibit highest price sensitivity, while integrated health systems with captive laboratory networks demonstrate lowest sensitivity due to bundled service economics.
Supply Chain Analysis
Cold-chain logistics costs for fetal plasma samples and temperature-sensitive sequencing reagents add 8-12 percent to landed costs for laboratories without regional distribution hubs, with freight volatility particularly acute for European laboratories sourcing polymerases from United States manufacturers. Sequencing instrument manufacturing concentrates in the United States, Singapore, and China, while specialized library preparation chemistries draw from single-source suppliers in California and Massachusetts. Raw material dependencies include semiconductor-grade optical components, modified nucleotides, and fetal fraction stabilization buffers. Single-source vulnerability for next-generation sequencing flow cells creates supply continuity exposure. Distribution runs through authorized distributor networks for capital equipment and direct fulfillment for consumable reagents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA de novo clearance pathways and EU IVDR implementation timelines create accelerating compliance investments that consolidate demand around validated platform providers.
For Market Incumbents: Anchor market position through backward integration into sample preparation automation and proprietary bioinformatics pipelines that lock in laboratory switching costs. Defend against algorithmic specialist entrants by accelerating clinical validation depth for expanded carrier screening panels. Prioritize certification investment in EU IVDR technical documentation to capture European market share as smaller competitors exit under compliance burden. For New Entrants and Emerging Players: Begin with algorithmic risk stratification software that layers onto existing Illumina and Thermo Fisher Scientific installed bases rather than competing at capital equipment tier. Target underpenetrated rural hospital laboratories in India and Southeast Asia where price sensitivity outpaces brand loyalty and regulatory requirements remain less stringent. Pursue telehealth-integrated direct-to-consumer channel development as initial touchpoint before clinical referral. For Investors and Strategic Acquirers: Valuations sit cheapest among molecular diagnostic pure-plays with proprietary cell-free DNA analytics but limited geographic footprint, offering acquisition platforms for regional laboratory network roll-ups. Long-term viability hinges on regulatory navigation capabilities across FDA, EMA, and NMPA frameworks rather than single-jurisdiction clearance. Monitor EU IVDR notified body capacity constraints as inflection signal for European market access timelines and competitive shakeout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA De Novo Submission Pathway | Accelerates commercialization timelines for novel NIPT assays targeting high-risk pregnancy populations. |
| EU IVDR Technical Documentation | Enables European market access as stricter clinical evidence standards filter out undercapitalized competitors. |
| Hospital System Partnership | Secures multi-year reagent supply contracts and preferred vendor status within integrated perinatal networks. |
| Software Companion Development | Integrates machine learning risk stratification with existing laboratory information management systems. |
| Reimbursement Strategy | Expands payer coverage for expanded carrier screening panels beyond conventional aneuploidy detection. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with maternal-fetal medicine specialists, diagnostic laboratory directors, regulatory affairs leads at assay developers, and health system procurement officers with secondary validation against FDA 510(k) and de novo clearance databases, EMA centralized procedure outcomes, ClinicalTrials.gov NIPT study registrations, and CMS Medicare coverage determinations. Bottom-up laboratory throughput estimates and top-down market sizing triangulated across manufacturer reagent shipment disclosures and health system capital expenditure filings.
Comparable historical periods anchored the projection framework across the analysis window, with segmentation modeling across diagnostic modality, analytical technology platform, care delivery setting, and geographic regulatory cluster. CAGRs derived from weighted average of laboratory expansion trajectories, reimbursement coverage evolution, and birth cohort demographics. Industry-specific forecast inputs incorporated NIPT test volume per birth, serum screening displacement rates, and perinatal center certification program expansion timelines.
Several conditions sit outside the modeled scope, including disruptive non-invasive fetal whole genome sequencing technologies, radical reimbursement policy shifts toward universal NIPT coverage, and geopolitical trade restrictions affecting sequencing instrument component sourcing. Forecasts reflect assumptions about regulatory pathway stability and laboratory consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Clinical Diagnostics
Cardiolipin Antibodies Test Market
Clinical Diagnostics
North America Liver Cancer Diagnostics Market
Clinical Diagnostics
Chromosomal Aberration Test Market
Clinical Diagnostics
Next-Generation Cancer Diagnostics Market
Clinical Diagnostics
In-Vitro Colorectal Cancer Screening Tests Market
Clinical Diagnostics
Global Electronic Clinical Outcome Assessment Solutions Market
Clinical Diagnostics
Global Colorectal Cancer Diagnostics Market
Clinical Diagnostics
Mitochondrial Myopathy Diagnosis and Treatment Market
Clinical Diagnostics
Oral Cancer Diagnostics Market
Clinical Diagnostics
Global Hepatitis C Testing Market
Clinical Diagnostics
Global Monocyte Activation Tests Market
Clinical Diagnostics
Global Apoptosis Assays Market
Clinical Diagnostics
Clinical Chemistry Market
Clinical Diagnostics
US Clinical Chemistry Analyzer Market
Clinical Diagnostics
Asia-Pacific Circulating Tumor Cells (CTC) Liquid Biopsy Market
Clinical Diagnostics
Clinical Microbiology Market