
 Cell Lysis and Disruption Market | 2026-2036
Cell Lysis and Disruption Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Lysis and Disruption Market Intelligence
The Cell Lysis and Disruption Market is pivoting between premium high-shear mechanical systems and commodity chemical detergent kits as biopharma producers split their procurement strategies by molecule complexity. Thermo Fisher Scientific leverages its chromatography-integrated workflow portfolio to dominate upstream sample preparation for biologics. Danaher Corporation sustains competitive positioning through Beckman Coulter's centrifugation and sonication platforms that anchor high-throughput cell disruption for vaccine manufacturing.
Cell lysis and disruption encompasses the deliberate rupture of cell membranes to release intracellular proteins, nucleic acids, organelles, or metabolites using chemical detergents, mechanical shear, enzymatic digestion, or physical osmotic shock, typically operating at controlled temperatures between four and twenty-five degrees Celsius to preserve biomolecular integrity. The primary industrial purpose centers on enabling downstream purification of recombinant proteins, monoclonal antibodies, and nucleic acid templates for therapeutic, diagnostic, and research applications. Mechanical devices command the highest capital investment per unit but capture durable margin pools from biopharmaceutical contract manufacturers running continuous campaigns. Enzymatic methods expand fastest among academic gene editing workflows where CRISPR template preparation demands gentle, scalable lysis without detergent interference.
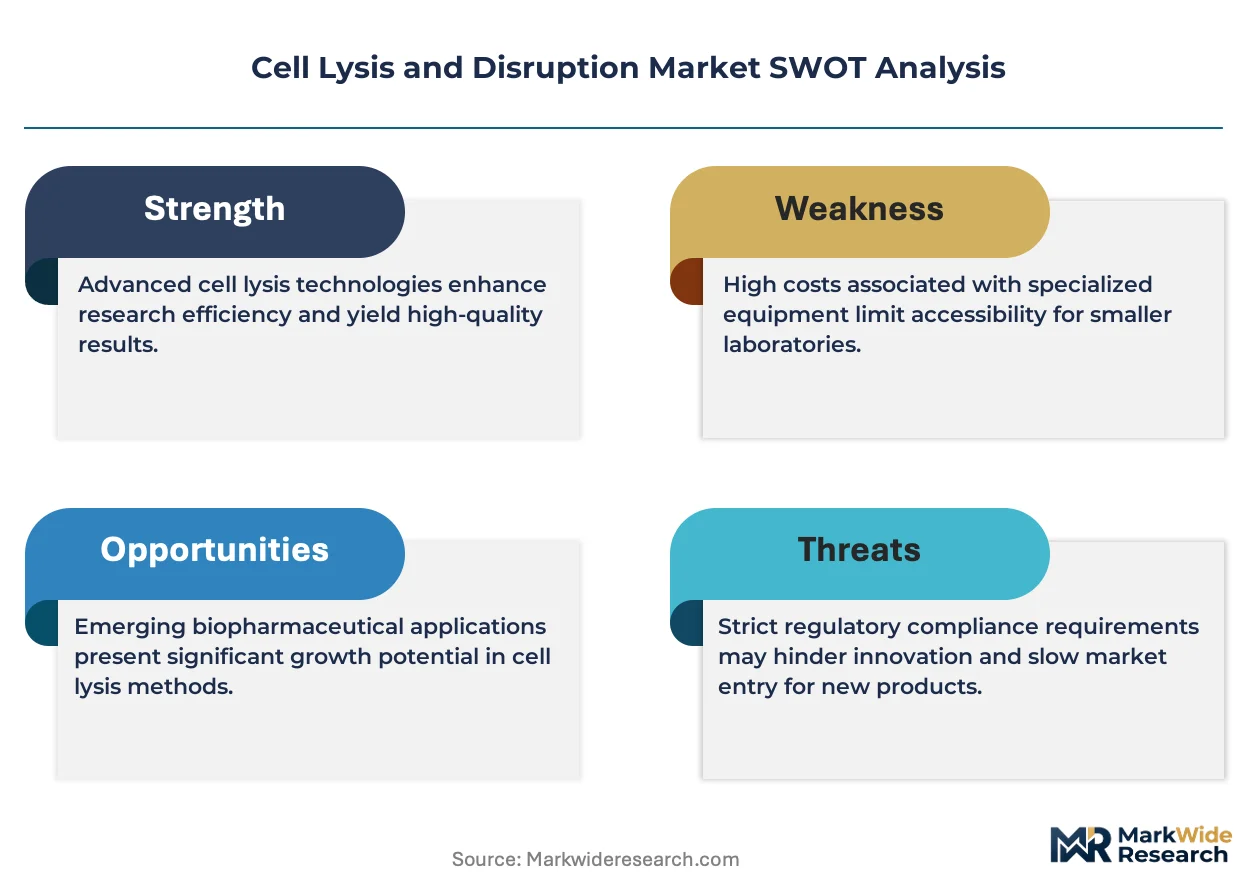
FDA cGMP guidelines and EMA's Annex 1 sterile manufacturing standards shape equipment validation requirements for cell disruption systems used in commercial biologics production, forcing vendors to supply comprehensive qualification documentation. ISO 13485 quality management systems and REACH chemical registration protocols in Europe further constrain detergent formulation choices and material traceability. Stakeholders must monitor evolving gene therapy regulatory pathways as autologous cell processing demands novel disruption methods compatible with living therapeutic payloads.
Market Dynamics
The Cell Lysis and Disruption Market is bifurcating between high-throughput mechanical platforms for commercial biologics and flexible enzymatic workflows for cell and gene therapy manufacturing, as FDA gene therapy guidance accelerates demand for gentle, scalable lysis methods that preserve living therapeutic payloads.
Growth Catalysts
- EMA Annex 1 sterile manufacturing standards:The 2022 revision mandates closed-system cell disruption for commercial biologics, forcing equipment upgrades across European contract manufacturing organizations and driving premium system adoption.
- CRISPR template preparation workflows:Academic and clinical research labs require detergent-free enzymatic lysis to avoid nucleic acid contamination, expanding demand for lysozyme and proprietary enzyme blends in gene editing applications.
- United States biologics production clusters:Concentrated investment in Boston, San Francisco, and Research Triangle Park gene therapy facilities creates sustained procurement volume for validated disruption systems.
Market Restraints
- Stainless steel and specialty alloy input costs:Mechanical disruption equipment relies on pharmaceutical-grade 316L stainless steel and titanium alloys for cGMP compliance, exposing manufacturers to commodity price volatility.
- Single-use consumables supply concentration:Bioprocessing bags and sterile filtration assemblies for cell lysis workflows concentrate among a limited supplier base in Germany and the United States, creating bottleneck risk.
- Detergent interference limitations:Sodium dodecyl sulfate and Triton X-100 residues compromise downstream chromatography and mass spectrometry, restricting chemical lysis adoption in high-purity therapeutic protein workflows.
Strategic Opportunities
- China NMPA biologics pathway expansion:Domestic biosimilar and innovative biologic approvals are accelerating, creating demand for cGMP-validated disruption equipment among emerging contract manufacturers in Shanghai and Suzhou.
- Microfluidic lysis technology convergence:Integration of lab-on-chip architectures with acoustic shear mechanisms enables continuous-flow cell disruption at single-cell resolution for precision medicine applications.
- Japan PMDA regenerative medicine framework:Accelerated approval pathways for autologous cell therapies create procurement pull for gentle disruption systems compatible with iPSC-derived therapeutic cells.
Industry Challenges
- Bioprocess engineer talent scarcity:Qualified personnel capable of validating mechanical disruption systems under FDA cGMP and EMA Annex 1 standards remain concentrated in established United States and European manufacturing hubs.
- Equipment qualification timeline compression:Installation, operational, and performance qualification documentation for cell disruption platforms now extends 12-18 months, delaying manufacturing campaign start dates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Lysis and Disruption Market |
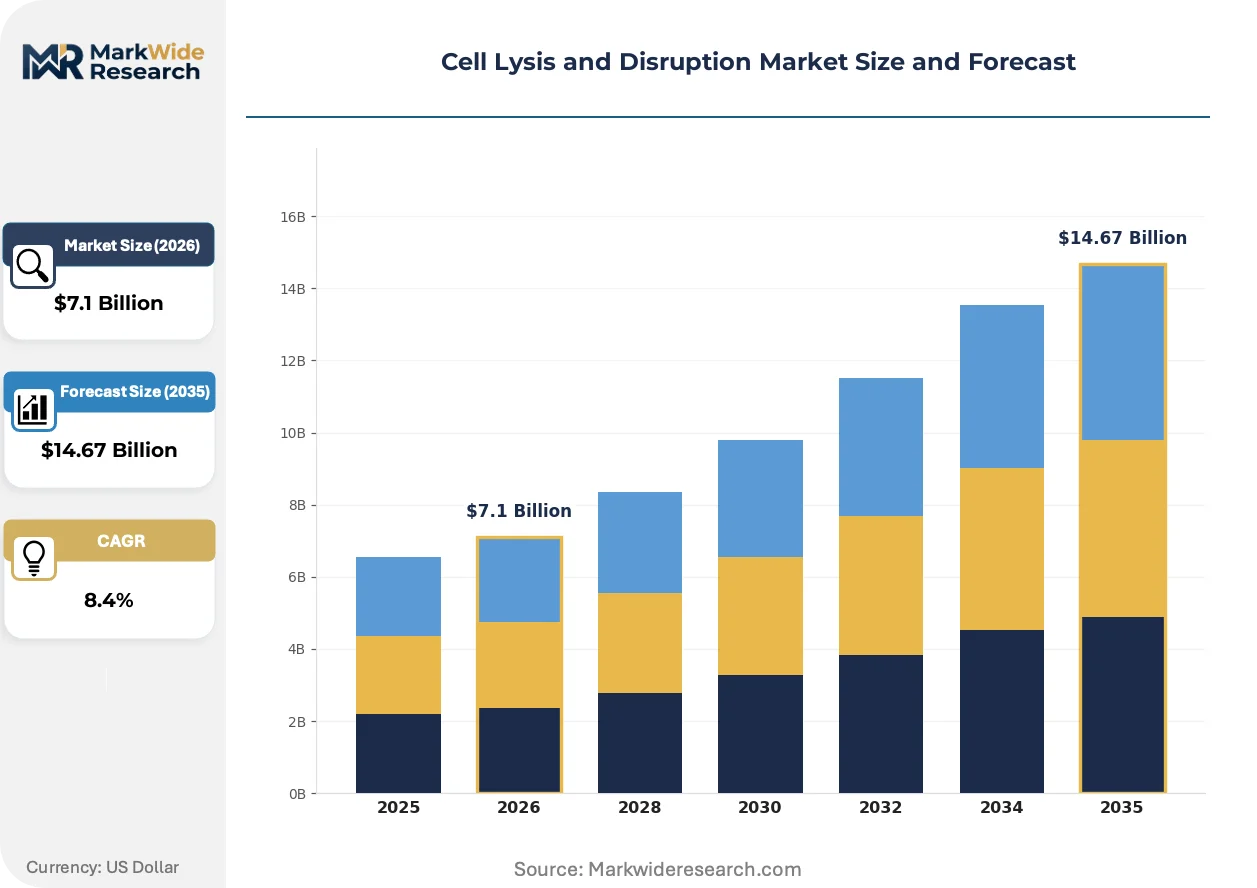
| Market Size in 2026 | $7.1 Billion |
| Market Size in 2035 | $14.67 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Enzymes, Beads, Mechanical Devices Application: Biotechnology, Pharmaceuticals, Diagnostics, Research Labs End User: Academic Institutions, Pharmaceutical Companies, Contract Research Organizations, Clinical Laboratories Method: Chemical, Mechanical, Enzymatic, Physical |
| Companies Covered | Thermo Fisher Scientific, Inc., Danaher Corporation, Merck KGaA, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd., Qiagen NV, Becton Dickinson & Company, Covaris, Inc., Parr Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Lysis and Disruption Market Strategic Shifts & Innovations
Continuous processing architectures and single-use system integration are displacing batch-mode mechanical disruption in commercial biologics manufacturing, while regulatory pressure for closed-system operation accelerates equipment redesign across all vendor portfolios.
Acoustic resonator arrays for cell lysis are integrating frequency-tuned piezoelectric transducers with real-time biomass monitoring to enable gentle, scalable membrane disruption without mechanical shear stress. Gene therapy contract manufacturers in the United States and Germany are piloting these systems for autologous cell processing workflows. This convergence is integrating precision control over lysis kinetics with reduced downstream purification burden, compressing total process time for viral vector manufacturing.
REACH chemical registration protocols in Europe are restricting Triton X-100 and other nonylphenol ethoxylate detergents in bioprocessing applications, forcing detergent kit reformulation toward biodegradable alternatives. The regulation is compelling vendors to revalidate entire chemical lysis product lines and resubmit regulatory documentation for EMA-compliant manufacturing. Biopharmaceutical producers in Germany, Switzerland, and the Netherlands are accelerating qualification of enzyme-based substitutes to avoid supply disruption.
Outcome-based service contracts for cell disruption equipment are displacing traditional capital purchase models among mid-sized contract development and manufacturing organizations. Equipment vendors now bundle preventive maintenance, consumable replenishment, and regulatory documentation support into multi-year performance agreements. This restructuring is most visible in United States biotech clusters where cash-constrained gene therapy startups prioritize operational expenditure flexibility over balance sheet asset ownership.
Cell Lysis and Disruption Market Segmentation
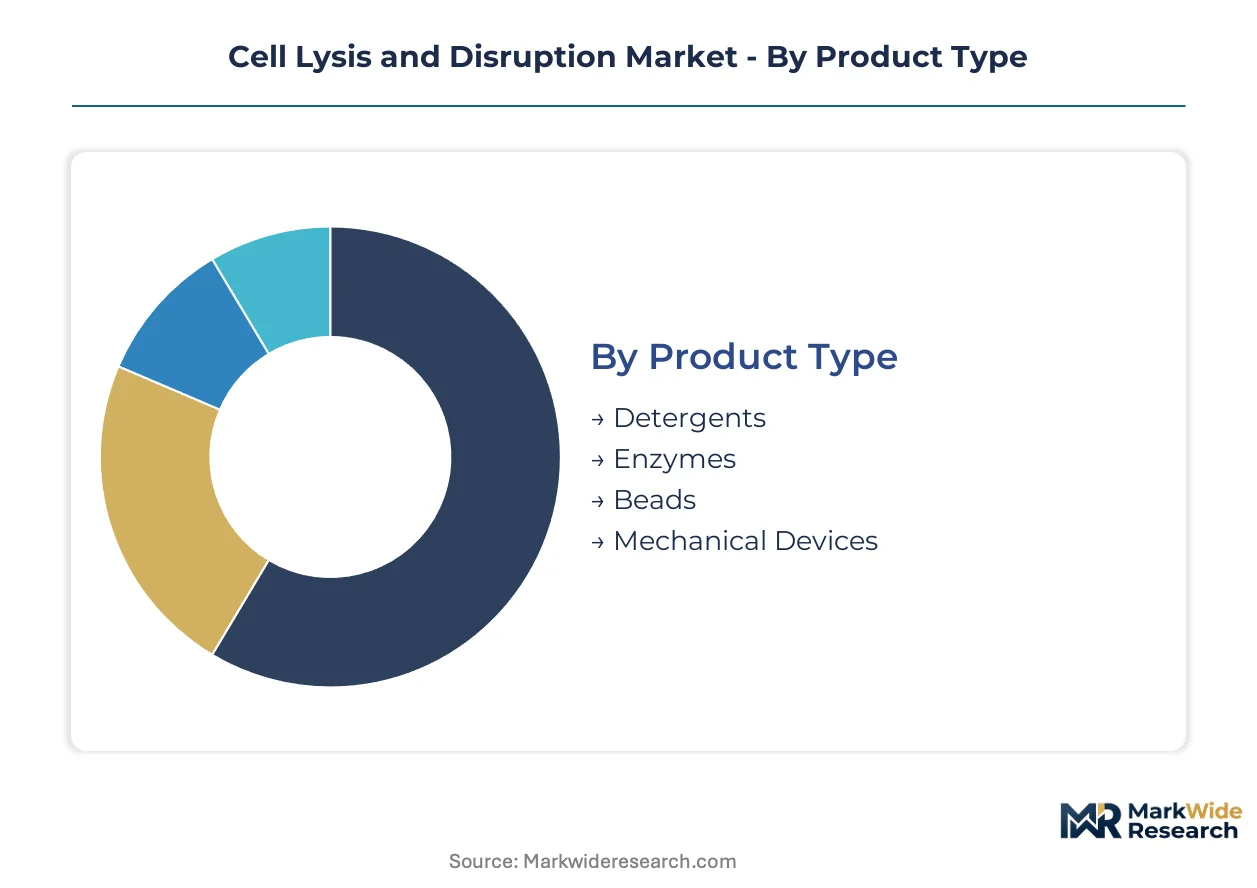
Cell lysis and disruption procurement splits sharply between validated biopharmaceutical manufacturing systems and flexible research-grade consumables. Equipment buyers prioritize regulatory documentation and closed-system architecture, while reagent purchasers optimize for protocol compatibility and per-sample cost.
Product Type:
Standardization dominates detergent and enzyme supply chains, whereas mechanical devices demand extensive customization for cGMP compliance and facility integration.
- Detergents:Surfactant formulations including sodium dodecyl sulfate and Triton X-100 derivatives disrupt lipid bilayers through micelle insertion. European bioprocessors in Germany and the Netherlands are accelerating qualification of biodegradable alternatives as REACH protocols restrict nonylphenol ethoxylates.
- Mechanical Devices:High-shear homogenizers, bead mills, and sonication systems operate at controlled temperatures to preserve biomolecular integrity. Contract manufacturers in the United States running continuous monoclonal antibody campaigns drive premium system adoption for their durability under 24-hour operation.
- Enzymes:Lysozyme and proprietary recombinant enzyme blends enable detergent-free lysis for nucleic acid workflows.
- Beads:Silica-coated and paramagnetic microspheres facilitate high-throughput mechanical disruption in automated platforms.
Growing fastest: Mechanical Devices. Leading the category by volume: Detergents.
Application:
Margin structures diverge between therapeutic manufacturing with its exhaustive validation requirements and research applications prioritizing throughput flexibility.
- Pharmaceuticals:Commercial biologics production demands FDA-validated disruption systems with comprehensive IQ/OQ/PQ documentation. EMA Annex 1 sterile manufacturing standards are forcing equipment upgrades across European contract manufacturing organizations.
- Research Labs:Academic and clinical research facilities optimize for protocol adaptability across diverse cell types. CRISPR template preparation workflows in United States gene editing hubs are expanding demand for gentle enzymatic lysis without detergent interference.
- Biotechnology:Cell and gene therapy developers require scalable methods compatible with living therapeutic payloads.
- Diagnostics:Clinical laboratories prioritize rapid nucleic acid extraction for infectious disease testing.
Expanding most quickly: Biotechnology. Dominating current procurement: Pharmaceuticals.
End User:
Capital deployment patterns separate asset-heavy pharmaceutical manufacturers from service-based research organizations seeking operational expenditure structures.
- Pharmaceutical Companies:Integrated biologics manufacturers invest in captive mechanical disruption infrastructure for pipeline continuity. Boston and San Francisco gene therapy facilities sustain concentrated procurement volume for validated systems.
- Contract Research Organizations:CDMOs serving mid-sized biotech clients favor outcome-based service contracts bundling equipment, maintenance, and regulatory documentation. Cash-constrained gene therapy startups in United States clusters prioritize this flexibility over balance sheet ownership.
- Academic Institutions:University labs drive enzyme and detergent volume through grant-funded gene editing research.
- Clinical Laboratories:Hospital and reference labs automate sample processing for diagnostic workflows.
Steepest expansion trajectory: Contract Research Organizations. Largest installed base: Pharmaceutical Companies.
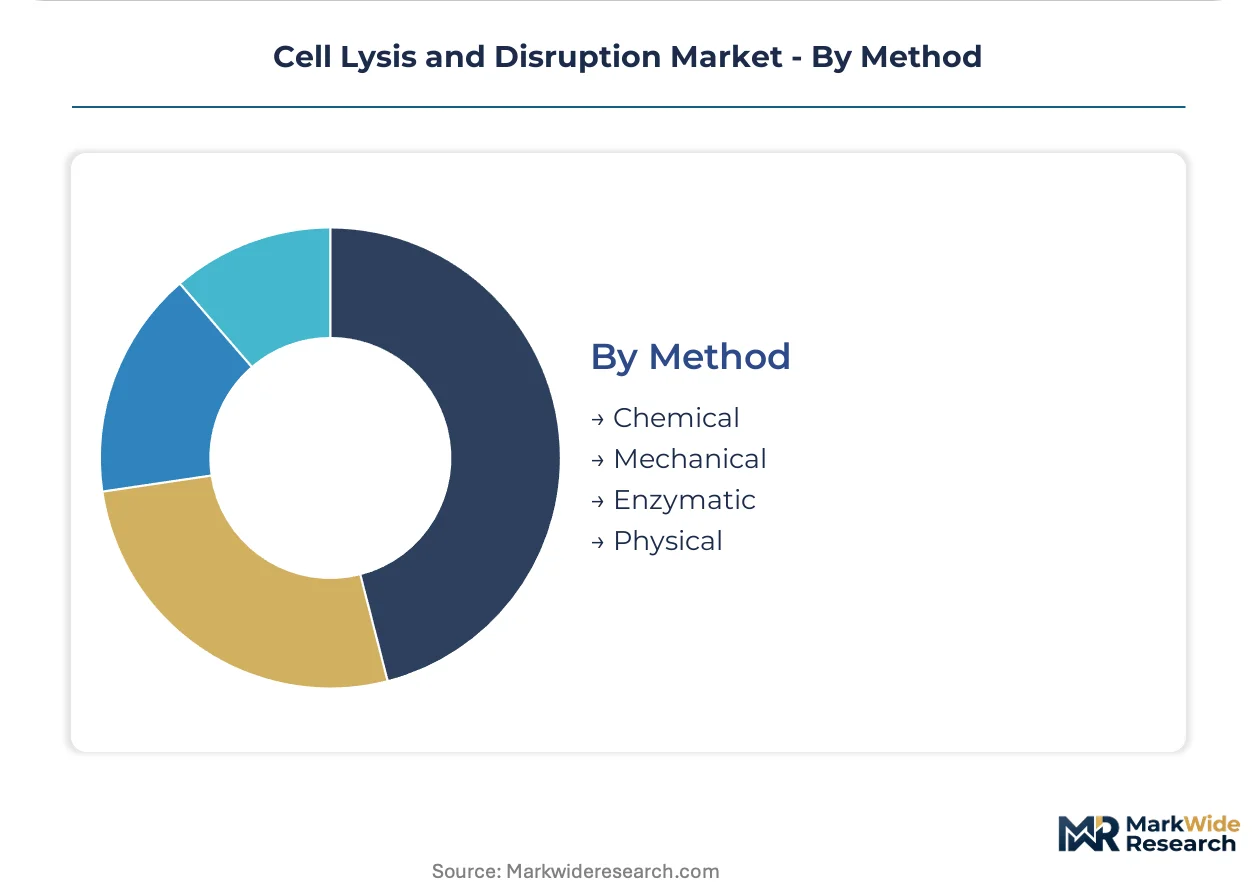
Method:
Physical disruption techniques concentrate in specialized applications while chemical and enzymatic approaches capture broad research adoption.
- Mechanical:Shear-based, bead-based, and acoustic systems achieve membrane rupture without chemical residue. Acoustic resonator arrays integrating piezoelectric transducers with real-time biomass monitoring are piloting in United States and German gene therapy facilities for autologous cell processing.
- Enzymatic:Cell wall digestion using lysozyme, cellulase, or proprietary blends preserves nucleic acid integrity. CRISPR workflows across academic and clinical research labs require this detergent-free approach to avoid contamination.
- Chemical:Detergent solubilization remains cost-effective for bulk protein extraction where downstream purity requirements permit.
- Physical:Osmotic shock and freeze-thaw cycles serve niche applications in fragile cell types.
Gaining share fastest: Enzymatic. Highest throughput deployment: Mechanical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boston's gene therapy corridor commands concentrated procurement for validated cell disruption systems serving autologous cell processing workflows. San Francisco's biologics manufacturing cluster sustains premium mechanical equipment demand for continuous monoclonal antibody campaigns. Germany's Rhine-Main biotechnology belt anchors European cGMP equipment qualification timelines.
United States
FDA gene therapy guidance accelerates demand for gentle lysis methods preserving living therapeutic payloads. The agency's cGMP guidelines mandate comprehensive IQ/OQ/PQ documentation for commercial biologics production. Research Triangle Park gene therapy facilities in North Carolina pilot acoustic resonator arrays for autologous cell processing workflows.
Germany
EMA Annex 1 sterile manufacturing standards force equipment upgrades across contract manufacturing organizations. REACH chemical registration protocols restrict Triton X-100 and nonylphenol ethoxylate detergents in bioprocessing applications. Rhine-Main biotechnology belt manufacturers accelerate qualification of enzyme-based substitutes to avoid supply disruption.
China
NMPA biologics pathway expansion creates demand for cGMP-validated disruption equipment among emerging contract manufacturers. The regulator's accelerated biosimilar and innovative biologic approvals reshape procurement patterns. Shanghai and Suzhou manufacturing clusters host expanding gene therapy research hubs requiring validated mechanical systems.
Japan
PMDA regenerative medicine framework accelerates approval pathways for autologous cell therapies. METI industrial policy supports precision medicine infrastructure investments. Kanto region biopharmaceutical producers create procurement pull for gentle disruption systems compatible with iPSC-derived therapeutic cells.
Switzerland
Swissmedic gene therapy regulations align with EMA standards while maintaining distinct qualification requirements for autologous cell processing. The country's pharmaceutical quality management systems enforce stringent material traceability. Basel biologics manufacturing corridor sustains demand for closed-system cell disruption architectures.
Cell Lysis and Disruption Market Key Industry Players
Capital-heavy producers compete with asset-light designers across the cell lysis and disruption market, creating a tiered structure where integrated life science conglomerates anchor premium segments while specialized instrument fabricators occupy mid-market niches. The vendor base stratifies between chromatography-integrated workflow providers, centrifugation and sonication platform specialists, and detergent kit standardizers. Three archetypes dominate: diversified conglomerates with regulatory documentation depth, mid-cap mechanical equipment specialists with cGMP validation expertise, and commodity reagent suppliers competing on per-sample cost. Consolidation pressure intensifies through strategic partnerships bundling equipment with consumable replenishment, while geographic expansion into Chinese contract manufacturing clusters accelerates among Western vendors.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Danaher Corporation exemplify integrated workflow dominance. Thermo Fisher leverages chromatography-integrated portfolios to anchor upstream sample preparation for biologics manufacturing. Danaher sustains positioning through Beckman Coulter centrifugation and sonication platforms serving high-throughput vaccine manufacturing workflows. Merck KGaA occupies a distinct position bridging chemical detergent supply with enzyme-based alternatives, reflecting REACH-driven formulation pivots across European bioprocessing markets.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Danaher Corporation |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd. |
| Qiagen NV |
| Becton Dickinson & Company |
| Covaris, Inc. |
| Parr Instrument Company |
| Others |
Cost & Logistics Intelligence
Specialty alloy price indices for pharmaceutical-grade 316L stainless steel and titanium feed directly into equipment pricing tiers, compressing margins for mechanical disruption system vendors while forcing buyers toward outcome-based service contracts that convert capital expenditure to operational flexibility.
Pricing Analysis
Throughput-guarantee contracts anchor value-based pricing for high-shear homogenizers and bead mill systems, with contract manufacturers paying premiums tied to validated uptime and batch yield performance. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated cGMP systems from research-grade equipment and commodity detergent kits. Pricing pressure stems from REACH-driven detergent reformulation costs and stainless steel commodity volatility. Academic institutions exhibit highest price sensitivity, while biopharmaceutical contract manufacturers prioritize total cost of ownership over unit price.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and Singapore coordinate hub-and-spoke delivery of single-use bioprocessing bags and sterile filtration assemblies to contract manufacturing clusters. Manufacturing concentrates in Germany for precision mechanical components, the United States for chromatography-integrated platforms, and China for commodity detergent formulations. Raw material dependencies include pharmaceutical-grade stainless steel, piezoelectric ceramics for acoustic systems, and recombinant enzyme feedstocks. Single-source vulnerability in sterile consumables creates bottleneck exposure. Distribution runs through authorized distributor networks with direct-to-manufacturer channels for large capital equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into consumable supply and captive service capacity is accelerating as vendors seek margin defense against commodity chemical price swings and equipment qualification timeline compression.
For Market Incumbents: Deploy regulatory documentation depth as a switching-cost mechanism against emerging microfluidic lysis entrants. Consolidate position through strategic partnerships bundling preventive maintenance with consumable replenishment in multi-year performance agreements. Capacity addition in China's NMPA-compliant manufacturing clusters counters regional procurement localization. Certification investment in Japan's PMDA regenerative medicine framework captures autologous cell therapy demand. For New Entrants and Emerging Players: Begin with acoustic resonator arrays for gene therapy contract manufacturing, where gentle lysis requirements and limited vendor penetration create accessible white space. Target enzyme-based detergent substitutes in Germany and the Netherlands as REACH restrictions force rapid qualification cycles. Position through outcome-based pricing that converts capital-averse biotech startups from equipment purchase to service subscription. For Investors and Strategic Acquirers: The window for entry favors mid-cap mechanical equipment specialists with cGMP validation expertise and established IQ/OQ/PQ documentation libraries. Long-term viability hinges on consolidation into integrated workflow portfolios spanning upstream lysis through downstream purification. Signal to monitor: NMPA approval velocity for domestic Chinese biosimilars, which would trigger procurement pull for validated disruption infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Bundling | Comprehensive IQ/OQ/PQ packages reduce EMA Annex 1 compliance timelines for European CDMOs. |
| Enzyme-Based Detergent Substitution | REACH-compliant formulations capture reformulation mandates across German and Dutch bioprocessing facilities. |
| Acoustic Resonator Platform Development | Piezoelectric lysis systems address autologous cell therapy payload preservation requirements in FDA gene therapy workflows. |
| Outcome-Based Service Contract Expansion | Performance agreements convert cash-constrained United States gene therapy startups from capital to operational expenditure. |
| China NMPA Manufacturing Footprint | Domestic cGMP validation capabilities position vendors for biosimilar and innovative biologic approval acceleration. |
Research Approach
Multi-period observation of equipment procurement cycles, regulatory submission timelines, and consumable utilization rates anchored the trend analysis, supplemented by interviews with bioprocess engineers, regulatory affairs specialists at contract manufacturing organizations, CDMO procurement directors, and academic lab managers. Secondary validation drew from FDA cGMP guidance documents, EMA Annex 1 revision texts, NMPA biologics approval databases, and REACH chemical restriction notices. Bottom-up triangulation across vendor shipment records and top-down reconciliation against biopharmaceutical capital expenditure disclosures ensured cross-verification.
Segment-weighting approaches applied differential growth coefficients across mechanical devices, enzymatic reagents, chemical detergents, and bead-based systems, with further stratification by end-use application and geographic regulatory cluster. CAGRs were derived from regression analysis of historical procurement patterns projected across the analysis window. Industry-specific inputs included gene therapy clinical trial enrollment trajectories, monoclonal antibody manufacturing capacity expansion announcements, and CRISPR template preparation workflow adoption curves in academic research settings.
Underlying measurement precision varies by segment; validated pharmaceutical manufacturing systems carry tighter precision than research-grade consumables due to transparent procurement documentation requirements. Forecasts reflect documented assumptions regarding regulatory pathway stability, commodity input price trajectories, and bioprocess engineer labor availability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Polymerase Chain Reaction Reagent Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
GMO Testing Services Market