
 Bio-Pharma Logistics Market | 2026-2036
Bio-Pharma Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Pharma Logistics Market Analysis
Real-time temperature monitoring is fragmenting legacy cold chain architectures into modular, sensor-driven networks. Deutsche Post DHL Group leverages its PharmaHub footprint to anchor temperature-validated corridors across multiple continents. Kuehne + Nagel sustains competitive density through specialized GMP-certified warehousing adjacent to biotech manufacturing zones. FedEx differentiates via its SenseAware platform, which controls visibility parameters for high-value biologics shipments.
Bio-pharma logistics encompasses the specialized movement, storage, and handling of temperature-sensitive biological materials, pharmaceutical products, and clinical trial supplies, typically requiring validated cold chains maintaining 2-8°C for refrigerated products and -20°C to -80°C for frozen biologics, with real-time environmental monitoring to preserve molecular integrity. Cold chain management leads service type demand as cell therapies and mRNA vaccines require uninterrupted cryogenic or ultra-low temperature custody. Air freight dominates delivery mode value due to speed requirements for short-shelf-life biologics, though sea freight grows for bulk active pharmaceutical ingredients with extended stability windows.
FDA enforcement of Drug Supply Chain Security Act serialization deadlines and EU Good Distribution Practice guidelines compel logistics providers to upgrade track-and-trace infrastructure, while WHO prequalification standards shape access for temperature-sensitive vaccines in lower-income markets. Stakeholders must weigh capital deployment between autonomous cold chain robotics and redundant backup infrastructure as product portfolios shift toward personalized medicine with patient-specific batch sizes.
Market Dynamics
Cell and gene therapy commercialization is forcing logistics networks to reconfigure around patient-specific batch sizes, dismantling economies of scale that governed pharmaceutical distribution for decades. This shift from bulk manufacturing to individualized therapeutics demands modular cold chain nodes capable of handling single-dose cryogenic shipments.
Growth Catalysts
- EU Good Distribution Practice (GDP) guidelines:These standards mandate temperature-validated transport documentation, compelling logistics providers to upgrade qualification protocols and expand certified warehouse footprints across member states.
- Cell therapy manufacturing clusters:Dense biotech production zones in Germany, Massachusetts, and Singapore generate concentrated demand for specialized cold chain corridors with validated handoff points.
- Cryogenic packaging innovation:Advanced phase-change materials and vacuum-insulated containers now maintain ultra-low temperatures for 96+ hours without active refrigeration, extending reach into emerging markets.
Market Restraints
- Dry ice supply volatility:Carbon dioxide capture constraints and regional production bottlenecks create input cost instability for cryogenic shippers dependent on solid CO2 for -78°C maintenance.
- Qualified personnel scarcity:The intersection of pharmaceutical science, cold chain engineering, and regulatory compliance creates a narrow talent pool that limits network expansion velocity.
- Validation timeline compression:FDA enforcement of Drug Supply Chain Security Act serialization deadlines accelerates compliance spending without proportional revenue recovery windows.
Strategic Opportunities
- Indian pharmaceutical export corridors:CDSCO alignment with WHO prequalification standards opens temperature-sensitive vaccine distribution into African and Southeast Asian markets previously served by European hubs.
- Autonomous mobile refrigeration:Convergence of robotics and IoT-enabled cold boxes enables last-mile delivery without human intervention, reducing temperature excursion risk in remote locations.
- Japan's regenerative medicine framework:PMDA accelerated approval pathways for iPSC-derived therapies create dedicated demand for cryogenic logistics serving domestic cell banking networks.
Industry Challenges
- Serialization system integration:Legacy warehouse management platforms require costly middleware development to interface with track-and-trace databases mandated by FDA and EMA.
- Temperature excursion documentation:Investigators and sponsors demand granular environmental data packages that strain data storage infrastructure and extend release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Pharma Logistics Market |
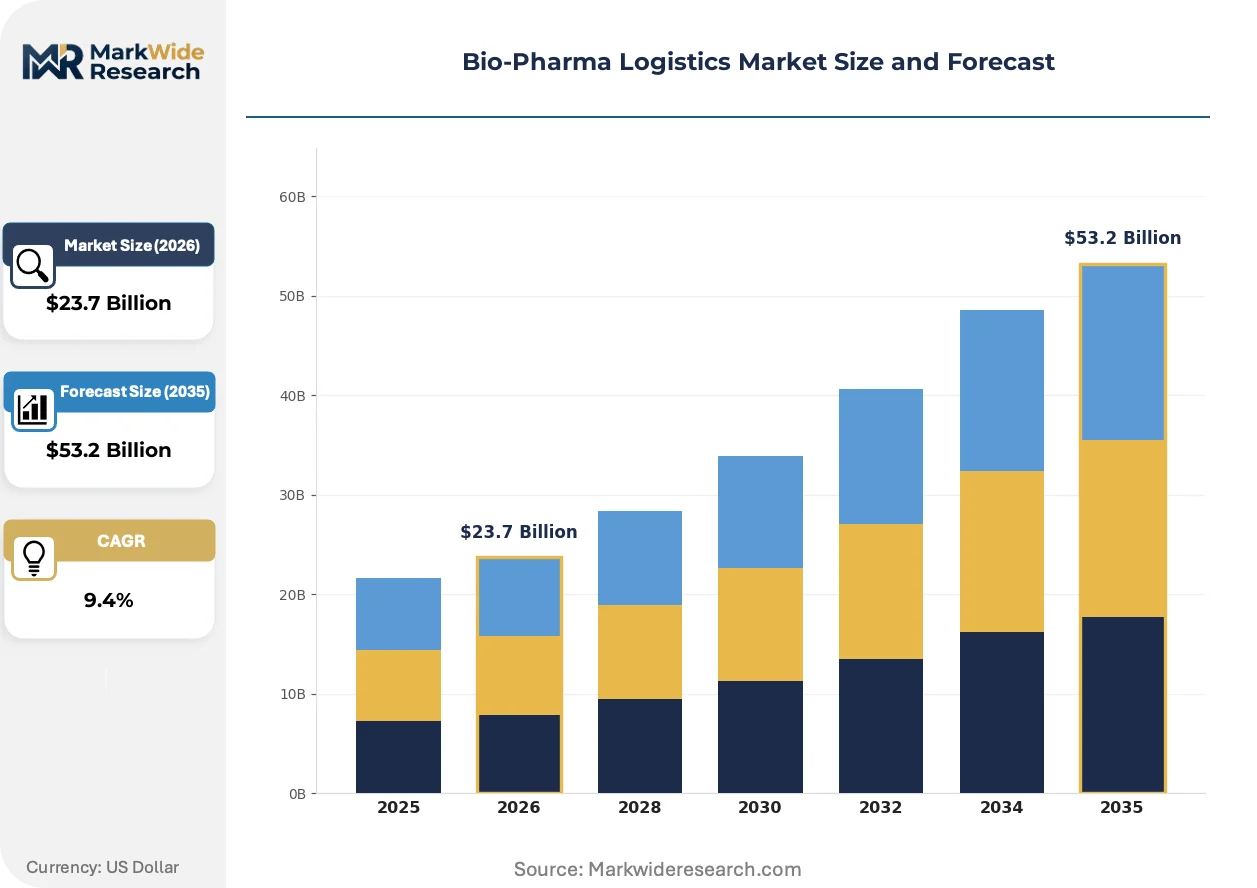
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $53.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Cold Chain Management, Packaging End User: Pharmaceutical Companies, Biotech Firms, Healthcare Providers, Research Institutions Temperature Control: Ambient, Refrigerated, Frozen, Controlled Room Temperature Delivery Mode: Air Freight, Sea Freight, Ground Transportation, Courier Services |
| Companies Covered | Deutsche Post DHL Group, Kuehne + Nagel, UPS Healthcare, FedEx, DB Schenker, DSV, CEVA Logistics, AmerisourceBergen, Kerry Logistics Network, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Pharma Logistics Market Emerging Trajectories
Digital twin technology is compressing validation cycles and enabling predictive intervention before temperature deviations occur. This convergence of physical infrastructure and virtual modeling represents the dominant architectural shift in pharmaceutical supply chain management.
Blockchain-enabled chain-of-custody platforms are digitizing handoff verification across multimodal shipments. Biotech sponsors and contract manufacturers are adopting these systems fastest in cell therapy trials, where provenance documentation supports regulatory submissions. The technology is digitizing audit trails that previously required manual paper reconciliation, reducing release timeline variability by standardizing data formats across carriers.
EMA's Annex 1 revision on sterile manufacturing extends environmental monitoring requirements into logistics operations, not just production facilities. This regulatory expansion treats transport as an extension of the cleanroom, requiring particulate and microbial monitoring in temperature-controlled vehicles. Cold chain providers serving European markets are responding by retrofitting vehicle fleets with integrated environmental monitoring suites that stream data to quality management systems.
Buyers are consolidating vendor relationships around integrated service platforms that combine international freight, domestic distribution, and clinical trial logistics under single accountability structures. This procurement compression displaces point-solution providers who specialize only in air freight or warehousing. The shift is most visible among mid-cap biotech firms in the Boston-Cambridge corridor, where lean supply chain organizations prefer single-source contracts with penalty-backed service level agreements.
Bio-Pharma Logistics Market Segmentation
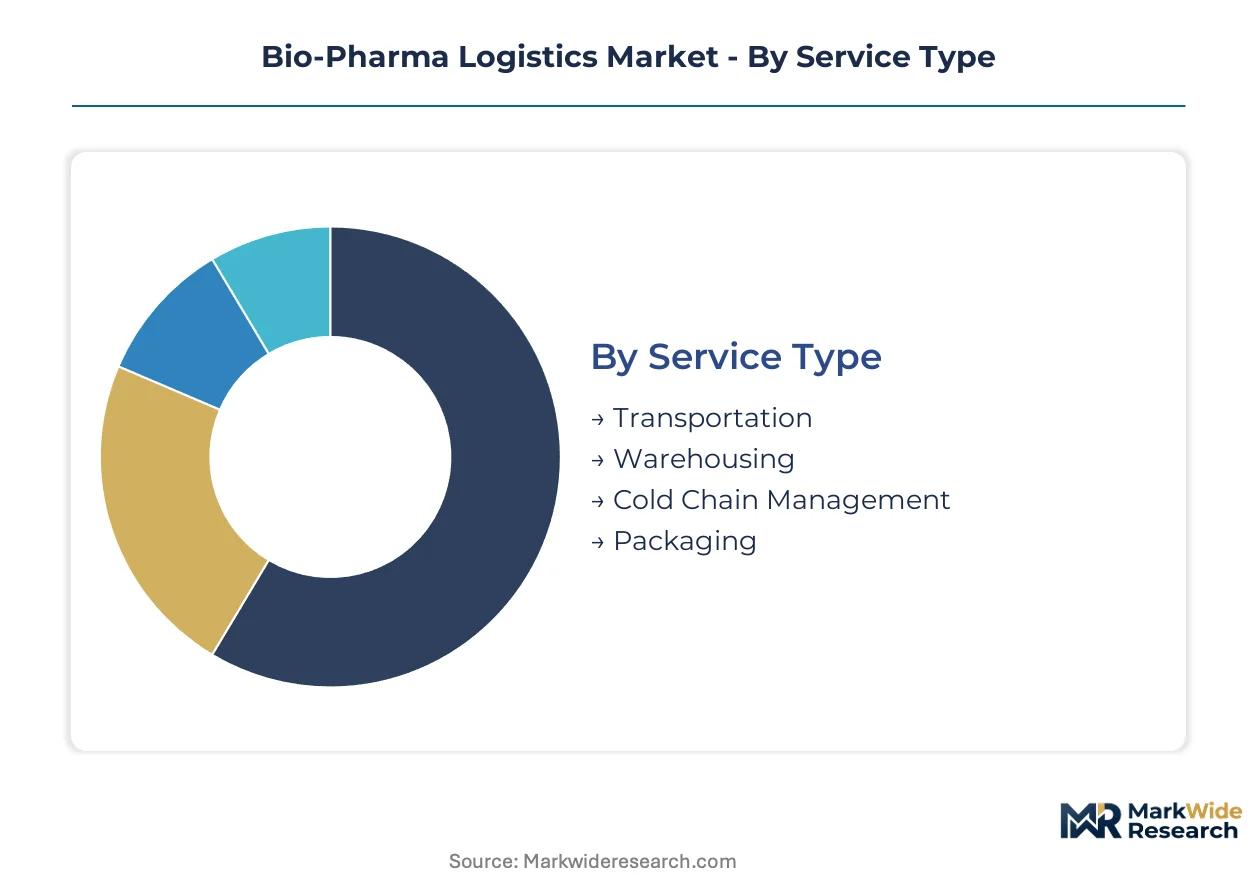
Segmentation in bio-pharma logistics reveals how service intensity varies dramatically across temperature requirements and custody complexity. Each dimension carries distinct qualification burdens, capital requirements, and margin structures that shape provider specialization.
Service Type:
After-sales service intensity peaks with cold chain management, where validation documentation and excursion response protocols demand dedicated quality teams long after initial delivery.
- Cold Chain Management:Maintains validated temperature corridors through continuous monitoring, redundant backup systems, and real-time intervention protocols. Demand concentrates among cell therapy developers in Germany and Massachusetts, where single-dose shipments require cryogenic custody chains with zero excursion tolerance.
- Transportation:Encompasses multimodal freight coordination, customs brokerage, and time-critical routing for temperature-sensitive cargo. Biotech firms in Singapore and the Boston-Cambridge corridor drive specialized demand for validated handoff points between air and ground modes.
- Warehousing:GMP-certified storage facilities with environmental monitoring and segregation protocols for different product classes.
- Packaging:Qualification of insulated containers, phase-change materials, and vacuum-flask systems for specific temperature bands and duration requirements.
Cold chain management holds the largest share; momentum sits with packaging innovation as cryogenic duration capabilities extend into emerging markets.
End User:
Cost tier stratification separates enterprise pharmaceutical companies with captive logistics operations from biotech firms dependent on outsourced specialized services.
- Biotech Firms:Emerging and mid-cap developers of cell therapies, gene therapies, and mRNA platforms. These organizations lack internal distribution infrastructure and demand modular, patient-specific logistics solutions. Concentrated demand in Massachusetts and Germany reflects manufacturing cluster density.
- Pharmaceutical Companies:Established manufacturers with global product portfolios spanning small molecules to biologics. These buyers consolidate vendor relationships around integrated platforms combining international freight, domestic distribution, and clinical trial logistics under single accountability structures.
- Healthcare Providers:Hospitals and specialty clinics receiving direct-to-patient shipments, particularly for CAR-T therapies requiring bedside infusion within narrow time windows.
- Research Institutions:Academic medical centers and contract research organizations managing clinical trial supply chains with investigator-site distribution requirements.
Pharmaceutical companies command the largest procurement volumes; biotech firms are expanding most quickly as cell therapy commercialization accelerates.
Temperature Control:
Application requirements dictate infrastructure investment, with frozen and cryogenic segments demanding specialized equipment that ambient chains cannot retrofit.
- Frozen:Ultra-low temperature custody at -20°C to -80°C for biologics, vaccines, and cell therapy materials. mRNA vaccine distribution established this as the fastest-expanding segment, with dry ice and liquid nitrogen systems now standard across major logistics hubs.
- Refrigerated:Validated 2-8°C corridors for insulin, monoclonal antibodies, and most biologics. This remains the workhorse segment with the broadest carrier participation and most mature qualification protocols.
- Ambient:Standard pharmaceutical distribution for stable small-molecule drugs without temperature sensitivity.
- Controlled Room Temperature:15-25°C bands for products requiring protection from heat excursions without active refrigeration.
Refrigerated maintains dominant volume share; frozen categories are gaining share fastest as biologics displace small molecules in development pipelines.
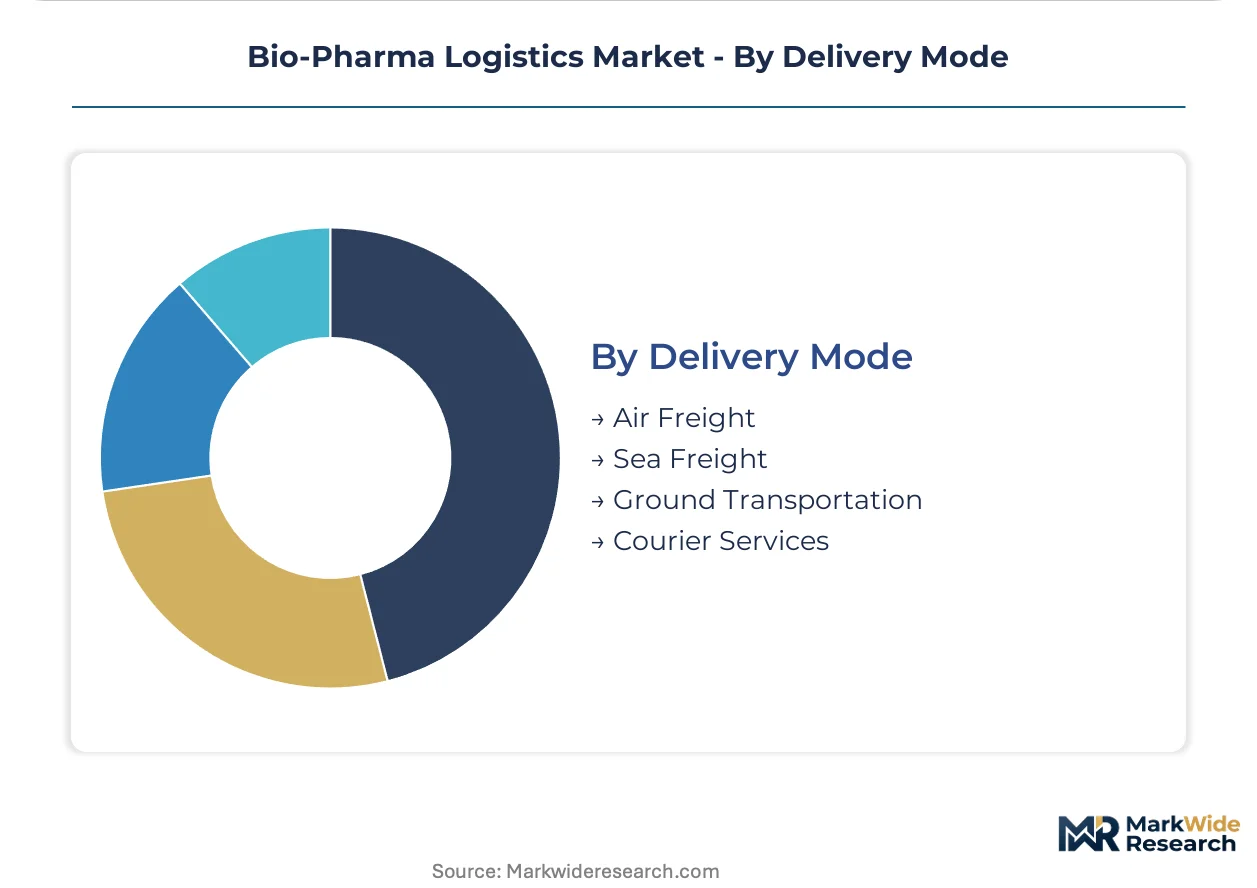
Delivery Mode:
Customer type determines mode selection, with speed-critical biotech sponsors paying air freight premiums while mature pharmaceutical products migrate to slower, cost-optimized sea lanes.
- Air Freight:Speed-critical transport for short-shelf-life biologics, cell therapies, and temperature-sensitive clinical supplies. Dominates value capture due to premium pricing for validated cold chain custody in flight and on tarmac.
- Sea Freight:Bulk transport for active pharmaceutical ingredients with extended stability windows. Expanding for large-volume biologics as container refrigeration and monitoring capabilities mature.
- Ground Transportation:Regional distribution networks with validated refrigerated vehicles for domestic and cross-border corridors within continental markets.
- Courier Services:Last-mile and clinical trial logistics with time-definite delivery and direct-to-patient capabilities.
Air freight leads by value; sea freight is climbing the fastest as biologics manufacturing scales and stability data supports longer transit windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's pharmaceutical manufacturing clusters export temperature-sensitive biologics to North American and Asian markets through validated cold chain corridors. These trade flows concentrate demand for specialized logistics services in dense production zones. Regulatory divergence between FDA serialization mandates and EU GDP guidelines shapes infrastructure investment priorities across destination markets.
United States
Massachusetts and the Boston-Cambridge corridor generate concentrated demand for cell therapy logistics with patient-specific batch requirements. FDA enforcement of Drug Supply Chain Security Act serialization deadlines compels logistics providers to upgrade track-and-trace infrastructure. Biotech manufacturing clusters in Greater Boston anchor cryogenic cold chain networks serving domestic distribution and export markets.
Germany
Pharmaceutical production density in Baden-Württemberg and North Rhine-Westphalia creates Europe's deepest logistics corridors for temperature-sensitive exports. EU Good Distribution Practice guidelines mandate temperature-validated transport documentation across member states. The Rhine-Main and Rhine-Ruhr industrial zones host specialized GMP-certified warehousing adjacent to biotech manufacturing facilities.
Singapore
Biopharmaceutical manufacturing investments from multinational sponsors drive demand for multimodal cold chain handoff points between air and sea modes. The national pharmaceutical regulator aligns with WHO prequalification standards for temperature-sensitive vaccine distribution into Southeast Asian markets. The Tuas biomedical hub anchors regional logistics infrastructure for cryogenic and ultra-low temperature custody.
India
Pharmaceutical export growth from Maharashtra and Gujarat creates demand for temperature-validated corridors serving African and Southeast Asian markets previously served by European hubs. CDSCO alignment with WHO prequalification standards opens access for vaccine distribution into lower-income markets. The Mumbai-Pune pharmaceutical belt concentrates specialized cold chain investment for biologics and active pharmaceutical ingredients.
Japan
Regenerative medicine commercialization under PMDA accelerated approval pathways generates dedicated demand for cryogenic logistics serving domestic cell banking networks. The national pharmaceutical regulator's iPSC-derived therapy framework creates specialized requirements for ultra-low temperature custody chains. The Kanto region around Tokyo anchors logistics infrastructure for personalized medicine distribution with narrow therapeutic windows.
Bio-Pharma Logistics Market Vendor Landscape
On the supply side, the industry is consolidating around integrated service platforms that combine international freight, domestic distribution, and clinical trial logistics under single accountability structures. Tiered competitive positioning separates global integrators with validated cold chain networks from regional specialists and point-solution providers. Three archetypes dominate: scale-driven integrators with pharmaceutical-certified infrastructure, regional specialists with dense corridor coverage, and technology-enabled platforms with real-time visibility systems. Competitive moves concentrate on strategic partnerships with biotech sponsors and capacity expansion in manufacturing cluster adjacencies.
Within the scale-driven integrator tier, Deutsche Post DHL Group and FedEx exemplify archetypes built on validated temperature corridors and digital visibility platforms. Kuehne + Nagel occupies a position representing the specialized warehousing and GMP-certified facility segment. These entities anchor competitive dynamics through infrastructure density in pharmaceutical manufacturing zones rather than pure geographic coverage breadth.
| Leading Market Players |
|---|
| Deutsche Post DHL Group |
| Kuehne + Nagel |
| UPS Healthcare |
| FedEx |
| DB Schenker |
| DSV |
| CEVA Logistics |
| AmerisourceBergen |
| Kerry Logistics Network |
| Others |
Supply Flow & Price Mechanics
Dry ice manufacturing concentration in the US Gulf Coast and industrial CO2 capture corridors in Germany directly determines where margin pools accumulate in cryogenic logistics tiers. These upstream bottlenecks force logistics providers to absorb input volatility or pass through costs to biotech sponsors with limited alternative sourcing.
Pricing Analysis
Legacy passive-cooling packaging, current-generation IoT-enabled active containers, and next-gen autonomous mobile refrigeration units command divergent price bands. Contract-based long-term offtake dominates enterprise pharmaceutical procurement, while biotech firms favor project-based pricing for patient-specific cell therapy shipments. Price differentiation rests on GDP certification tier and after-sales excursion response service. Pricing pressure stems from dry ice supply volatility as carbon dioxide capture constraints tighten input markets. Mid-cap biotech sponsors exhibit highest price sensitivity due to limited procurement scale, whereas multinational pharmaceutical companies prioritize reliability over unit cost.
Supply Chain Analysis
Upstream feedstock for cryogenic packaging draws from industrial CO2 capture facilities concentrated in Germany, the United States, and China. Phase-change materials, vacuum-insulated panels, and solid CO2 supplies feed container manufacturing networks. Single-source vulnerability pervades liquid nitrogen distribution infrastructure serving cell therapy corridors. Distribution runs through hub-and-spoke models anchored at Frankfurt, Memphis, and Singapore air cargo clusters, with last-mile courier networks completing patient-specific delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell therapy commercialization is disrupting pharmaceutical logistics faster than infrastructure adaptation cycles permit, with FDA serialization mandates compressing compliance timelines simultaneously.
For Market Incumbents: Build regulatory certification moats by securing EMA Annex 1 compliant vehicle fleets ahead of enforcement waves. Incumbent logistics providers should deepen backward integration into cryogenic packaging manufacturing to capture margin pools currently held by specialized container suppliers. Autonomous cold chain robotics from technology vendors threaten traditional labor-intensive handoff protocols. Capacity addition in the Boston-Cambridge corridor anchors defensive positioning against regional specialists. For New Entrants and Emerging Players: Pursue white-space opportunities in Indian pharmaceutical export corridors where CDSCO-WHO alignment opens vaccine distribution previously served by European hubs. Autonomous mobile refrigeration for last-mile delivery in Southeast Asian markets represents the most penetrable segment, given limited incumbent footprint. A go-to-market angle partnering with domestic cell banking networks in Japan leverages PMDA accelerated approval pathways for iPSC-derived therapies. For Investors and Strategic Acquirers: Capital is best deployed toward technology-enabled logistics platforms with real-time visibility systems rather than asset-heavy warehousing specialists. Long-term viability across the projection horizon favors providers integrating digital twin validation capabilities with physical cold chain infrastructure. Acquisition targets should demonstrate density in manufacturing cluster adjacencies. The signal to watch is biotech sponsor consolidation of vendor relationships around single-accountability platforms, which accelerates displacement of point-solution providers.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA Annex 1 compliance opens European cell therapy corridors to qualified providers. |
| Autonomous Mobile Refrigeration Deployment | IoT-enabled cold boxes reduce temperature excursion risk in remote last-mile locations. |
| Digital Twin Platform Integration | Virtual modeling compresses validation cycles for cryogenic custody chains. |
| Backward Integration into Packaging | In-house phase-change material production captures margin from specialized container suppliers. |
| Manufacturing Cluster Capacity Expansion | GMP-certified warehousing adjacency in Massachusetts and Baden-Württemberg anchors biotech sponsor relationships. |
Methodological Framework
A standing panel of cold chain operations directors, regulatory affairs leads at logistics providers, biotech supply chain executives, and hospital pharmacy procurement managers provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA DSCSA enforcement documentation, EMA GDP inspection reports, WHO prequalification standards, and IATA CEIV Pharma certification databases. Bottom-up service-type segmentation triangulated against top-down regional demand modeling.
Scenario-bracketing framed analytical outputs across the analysis window, with volume and value projections derived from treatment-line expansion in cell therapy pipelines and mRNA platform stability data. Segmentation dimensions modeled encompassed service intensity, temperature control tier, delivery mode, and regional regulatory cluster alignment. CAGRs were computed from validated cold chain capacity expansion trajectories and biotech manufacturing cluster investment flows.
The forecast holds incumbent behavior within observed patterns; aggressive moves by autonomous robotics specialists or carbon capture technology disruptors would shift outcomes beyond modeled ranges. Cross-checking against IATA CEIV Pharma certification growth rates and biotech sponsor RFP volume indices is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Global Culture Media Market