
 Bioartificial Renal Assist Devices Market | 2026-2036
Bioartificial Renal Assist Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Bioartificial Renal Assist Devices Market Outlook
Buyer concentration among hospital networks is expanding as integrated delivery systems consolidate procurement decisions across multiple facilities. Fresenius Medical Care leverages its vertically integrated dialysis service network to secure preferred placement for advanced renal devices. Baxter International anchors its position through sustained investment in membrane bioreactor technology for extracorporeal applications. B. Braun Melsungen competes by specializing in precision fluid management systems that integrate with next-generation artificial kidneys.
Bioartificial renal assist devices combine living tubular epithelial cells with synthetic hemofiltration membranes to replicate glomerular and tubular functions lost in renal failure, operating at blood flow rates of 100-400 mL/minute while maintaining selective solute transport across semipermeable barriers. These systems serve patients with end-stage renal disease who require metabolic regulation beyond conventional dialysis. Continuous hemodialysis systems command the largest installed base due to established reimbursement codes and clinician familiarity, though hybrid systems integrating cell-based bioreactors represent the fastest-expanding segment as transplant waitlists lengthen. Dialysis centers constitute the dominant end-user channel, capturing the majority of procedure volumes through centralized high-utilization models.
FDA breakthrough device designation pathways compress premarket timelines for bioartificial kidney platforms, while EMA's adaptive licensing frameworks enable conditional European market entry based on surrogate endpoints. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on cell-containing devices, elevating documentation burdens for manufacturers seeking CE marking. Japan's PMDA offers priority review consultations for regenerative medicine products, creating accelerated access for cell-based renal therapies. Stakeholders must monitor evolving reimbursement thresholds for combination device-biologic products across major health technology assessment bodies.
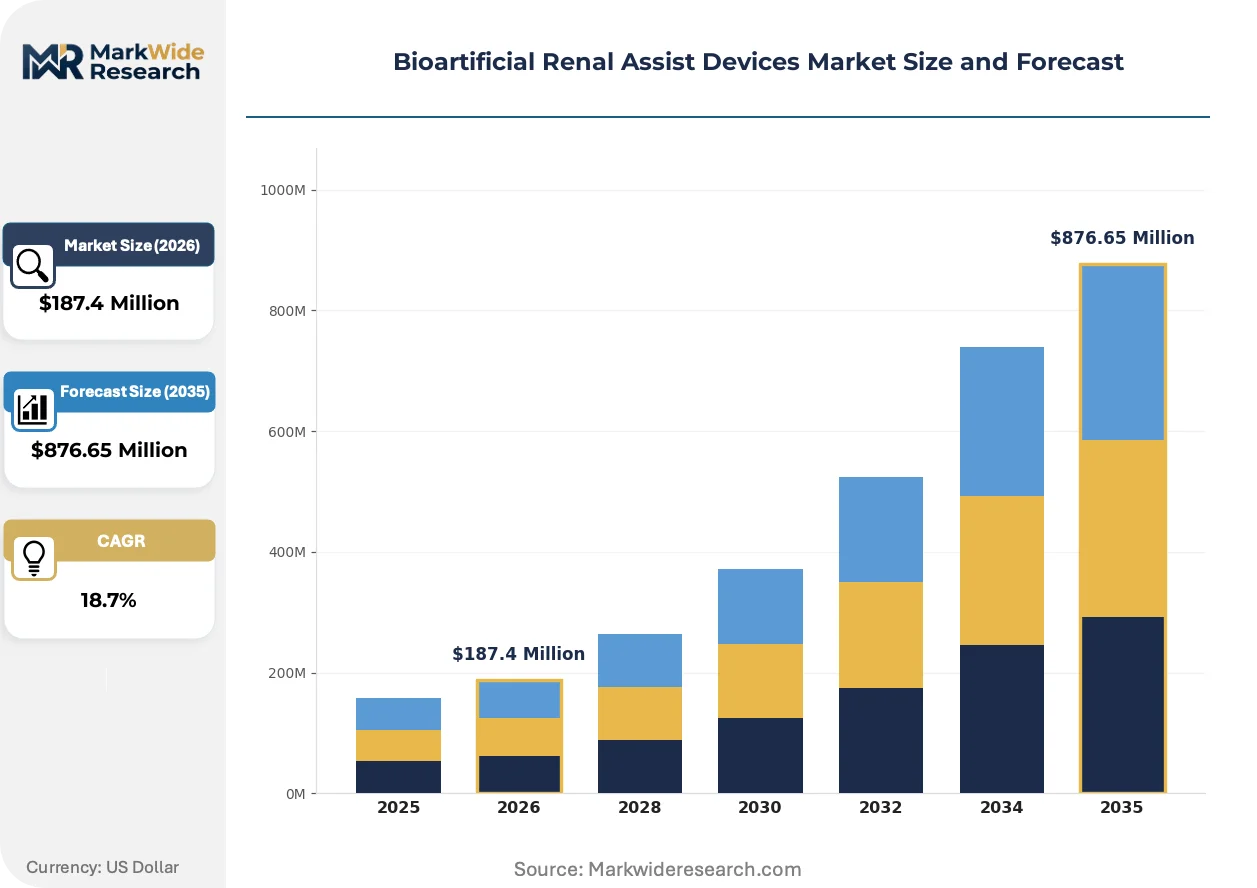
Market Dynamics
Cell-based bioreactor integration is compressing development timelines for next-generation renal replacement platforms, forcing manufacturers to restructure clinical validation strategies around living-tissue compatibility rather than purely mechanical performance metrics.
Growth Catalysts
- FDA Breakthrough Device Designation:The pathway accelerates premarket review for bioartificial kidney platforms, reducing time-to-revenue for cell-synthetic hybrid systems targeting end-stage renal disease populations.
- Transplant waitlist expansion:Dialysis centers in the United States, Germany, and Japan are scaling procurement of advanced renal assist devices as deceased-donor kidney availability fails to match incident patient volumes.
- Membrane bioreactor advances:Precision fluid management systems now achieve selective solute transport at 100-400 mL/minute blood flow rates, enabling metabolic regulation beyond conventional hemodialysis capabilities.
Market Restraints
- Silicon membrane supply concentration:Specialized semipermeable barrier production clusters in East Asia create input vulnerability for manufacturers dependent on high-purity synthetic substrates.
- EU MDR clinical evidence burdens:The Medical Device Regulation imposes strengthened documentation requirements on cell-containing devices, elevating CE marking costs and timeline uncertainty for European market entry.
- Living cell logistics complexity:Cold-chain requirements for viable tubular epithelial cell preservation limit distribution radius and create spoilage risk across decentralized healthcare networks.
Strategic Opportunities
- Japan PMDA priority review:The regenerative medicine product pathway offers accelerated market access for cell-based renal therapies, creating first-mover positioning in a reimbursement-favorable jurisdiction.
- Hybrid system convergence:Integration of continuous hemodialysis infrastructure with bioreactor modules presents white space between established reimbursement codes and emerging cell-therapy platforms.
- Home-based renal replacement:Miniaturized bioartificial systems targeting ambulatory care settings bypass dialysis center capacity constraints and capture patient preference for treatment location flexibility.
Industry Challenges
- Cell viability certification timelines:Demonstrating 30-day shelf stability for living bioreactor components extends FDA premarket approval phases beyond traditional device review periods.
- Cross-functional talent scarcity:Manufacturers compete for specialists bridging nephrology, tissue engineering, and extracorporeal system design, compressing R&D throughput across development pipelines.
- Legacy dialysis infrastructure lock-in:Existing clinic capital investment in conventional hemodialysis stations creates switching friction for integrated delivery systems evaluating bioartificial platform conversions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioartificial Renal Assist Devices Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermittent Hemodialysis, Continuous Hemodialysis, Peritoneal Dialysis, Hybrid Systems End User: Hospitals, Dialysis Centers, Home Care, Specialty Clinics Technology: Membrane Technology, Microfiltration, Nanofiltration, Bioengineering Solutions Application: Acute Kidney Injury, Chronic Kidney Disease, Transplant Support, Toxicology Studies |
| Companies Covered | Fresenius Medical Care, Baxter International, B. Braun Melsungen, Medtronic, Asahi Kasei Medical, Nipro Corporation, Boston Scientific Corporation, NxStage Medical, DaVita, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioartificial Renal Assist Devices Market Strategic Shifts
Living-cell integration is displacing purely synthetic filtration architectures across renal replacement platforms, redefining competitive advantage around biocompatibility engineering rather than membrane pore-size optimization alone.
Electrifying membrane-electrode assemblies are enabling real-time metabolite sensing within bioartificial kidney circuits. Dialysis centers in Germany are piloting these systems for glucose and urea dynamic monitoring. The technology is electrifying clinical workflow design by collapsing separate laboratory testing intervals into continuous intra-procedure feedback loops.
EMA adaptive licensing frameworks are enabling conditional European market entry for renal assist devices based on surrogate efficacy endpoints rather than full mortality outcome data. Manufacturers are restructuring clinical trial protocols to prioritize biomarker validation over extended follow-up periods. Cell-based hybrid systems face the steepest documentation adjustments under this policy rotation.
Hospital network procurement consolidation is compressing vendor negotiation cycles across integrated delivery systems. Large United States health systems now mandate bioartificial platform compatibility with existing electronic health record infrastructure as a threshold qualification. Purchasing committees in tertiary academic medical centers are driving standardization around interoperable fluid management architectures.
Bioartificial Renal Assist Devices Market Segmentation
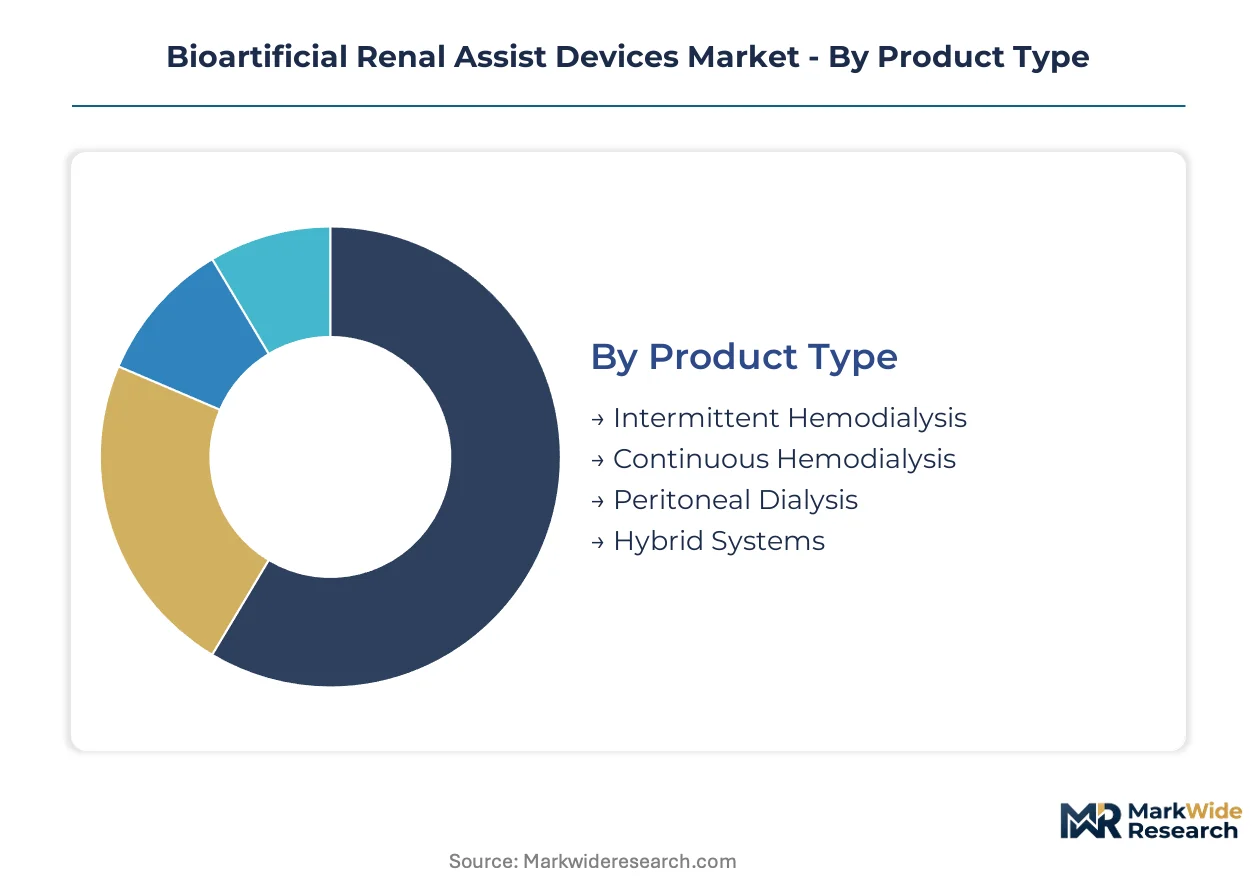
Procurement committees in integrated delivery systems prioritize compatibility across product architectures when selecting bioartificial renal platforms. Technology differentiation and reimbursement pathway clarity drive vendor selection more than unit economics alone in this capital-intensive category.
Product Type:
Capital deployment cycles and reimbursement code maturity determine facility-level purchasing decisions across renal replacement modalities.
- Continuous Hemodialysis:These systems operate at sustained blood flow rates of 100-400 mL/minute through synthetic hemofiltration membranes, delivering metabolic regulation for hemodynamically unstable patients. Dialysis centers in the United States concentrate installed base expansion here due to established CPT reimbursement codes and clinician training infrastructure.
- Hybrid Systems:Integration of living tubular epithelial cell bioreactors with conventional extracorporeal circuits replicates both glomerular filtration and tubular reabsorption functions. Procurement is accelerating in Germany and Japan as transplant waitlists lengthen and regulators fast-track cell-therapy platforms through adaptive pathways.
- Intermittent Hemodialysis:Scheduled treatment sessions utilizing purely synthetic membranes dominate legacy infrastructure.
- Peritoneal Dialysis:Intraperitoneal fluid exchange systems serve ambulatory patient populations with residual renal function.
Volume sits with Continuous Hemodialysis; growth tilts toward Hybrid Systems.
End User:
Patient acuity and procedure complexity dictate channel-specific device specifications and service contract structures.
- Dialysis Centers:Centralized high-utilization facilities capture the majority of procedure volumes through economies of scale in consumable procurement and technical staffing. Germany's outpatient dialysis networks are expanding bioreactor-compatible infrastructure to address rising ESRD incidence.
- Hospitals:Acute care settings require ICU-integrated systems with real-time metabolite sensing for hemodynamically unstable patients. Japanese tertiary academic medical centers are piloting electrified membrane-electrode assemblies for continuous glucose and urea monitoring.
- Home Care:Miniaturized ambulatory systems target patient preference for treatment location flexibility.
- Specialty Clinics:Nephrology-focused outpatient facilities concentrate stable chronic patient management.
Procedure concentration favors Dialysis Centers; expansion velocity is highest in Home Care.
Technology:
Intellectual property positioning around selective solute transport mechanisms is restructuring competitive advantage in renal replacement.
- Membrane Technology:Semi-permeable synthetic barriers with precision pore-size distribution enable selective ultrafiltration across molecular weight ranges. Supply concentration for high-purity silicon substrates in East Asia creates input vulnerability for manufacturers dependent on these specialized materials.
- Bioengineering Solutions:Living-cell integration with synthetic scaffolds replicates tubular epithelial function lost in renal failure. FDA breakthrough device designations are compressing premarket timelines for platforms demonstrating 30-day shelf stability for viable bioreactor components.
- Microfiltration:Pore-size exclusion removes cellular debris and large protein aggregates from blood circuits.
- Nanofiltration:Molecular-weight cutoff precision targets middle-molecule uremic toxin clearance.
Installed base clusters around Membrane Technology; patent filing velocity concentrates in Bioengineering Solutions.
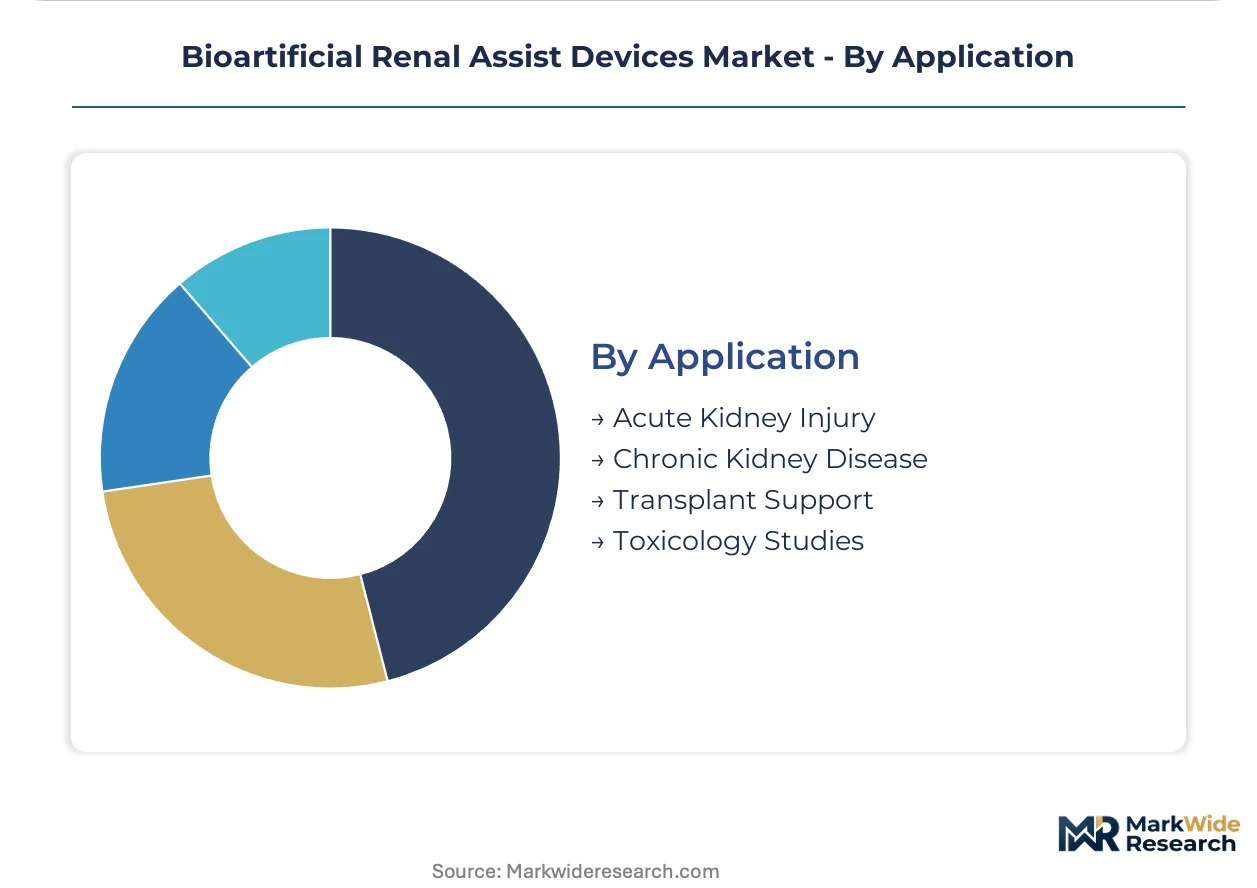
Application:
Clinical endpoint requirements and trial design complexity segment addressable populations across acute and chronic indications.
- Chronic Kidney Disease:Long-term renal replacement for end-stage populations drives recurring revenue through disposable consumables and maintenance contracts. The United States dominates addressable volume given ESRD prevalence and favorable Medicare reimbursement for advanced replacement platforms.
- Acute Kidney Injury:Critical care applications demand rapid deployment capability and hemodynamic tolerance for unstable patients. Japanese ICU networks are standardizing around continuous modalities with integrated bioreactor backup for prolonged organ support.
- Transplant Support:Bridge-to-transplant and organ preservation applications leverage cell-based metabolic regulation.
- Toxicology Studies:Extracorporeal drug clearance and poison elimination utilize high-flux membrane configurations.
Recurring revenue concentrates in Chronic Kidney Disease; trial enrollment velocity is highest in Transplant Support.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Patient demand concentrates in three reimbursement-favorable jurisdictions where transplant waitlists outpace deceased-donor availability. Regulatory acceleration pathways in these markets compress clinical validation timelines for cell-synthetic hybrid systems.
United States
Medicare reimbursement for advanced renal replacement platforms drives dialysis center procurement of bioartificial systems. The FDA breakthrough device designation compresses premarket review timelines for platforms demonstrating 30-day bioreactor shelf stability. Boston and the San Francisco Bay Area anchor venture financing clusters for cell-therapy renal platforms.
Germany
Outpatient dialysis networks scale bioreactor-compatible infrastructure to address rising ESRD incidence among aging populations. The EU Medical Device Regulation imposes strengthened clinical evidence requirements on cell-containing devices seeking CE marking. Baden-Württemberg's precision engineering clusters supply membrane-electrode assemblies for real-time metabolite sensing circuits.
Japan
PMDA priority review consultations for regenerative medicine products accelerate market access for cell-based renal therapies. National health insurance coverage decisions favor platforms reducing dialysis center capacity constraints. Tokyo and Osaka academic medical centers pilot electrified membrane systems for continuous glucose and urea monitoring.
United Kingdom
NICE health technology assessments evaluate cost-effectiveness thresholds for combination device-biologic renal products. Post-Brexit regulatory divergence from EU MDR creates timeline uncertainty for CE-marked device recognition. London's tertiary hospital networks consolidate procurement decisions across integrated delivery systems.
Switzerland
Swissmedic's streamlined review processes attract manufacturers seeking European market entry with reduced documentation burdens. Private reimbursement frameworks support premium pricing for advanced renal replacement platforms. Basel's pharmaceutical-industrial corridor hosts membrane technology R&D facilities serving adjacent device manufacturers.
Bioartificial Renal Assist Devices Market Competitive Environment
German producers anchor one tier; United States specialists hold another in a market structured around vertically integrated dialysis service networks and component technology providers. Three strategic archetypes dominate: full-service dialysis operators controlling downstream placement, precision fluid management specialists, and membrane-electrode technology developers. Competitive moves concentrate on backward integration into bioreactor cell sourcing and strategic partnerships bridging nephrology and tissue engineering capabilities.
Within the integrated service provider tier, Fresenius Medical Care and DaVita exemplify archetypes leveraging captive dialysis center networks to secure preferred device placement. Baxter International occupies a position representing membrane bioreactor technology developers targeting extracorporeal applications. Among precision fluid management specialists, B. Braun Melsungen and Nipro Corporation exemplify European and Japanese fabricators respectively, each anchoring regional supply relationships with academic medical centers.
| Leading Market Players |
|---|
| Fresenius Medical Care |
| Baxter International |
| B. Braun Melsungen |
| Medtronic |
| Asahi Kasei Medical |
| Nipro Corporation |
| Boston Scientific Corporation |
| NxStage Medical |
| DaVita |
| Others |
Value Chain & Pricing Dynamics
Tissue engineering specialists concentrated in Boston and the San Francisco Bay Area command wage premiums that widen pricing spreads between premium cell-integrated systems and conventional membrane devices. Labor-cost differentials between these bioreactor engineering clusters and standard medical device manufacturing regions directly stratify end-product tiers.
Pricing Analysis
Volume concentrates in continuous hemodialysis systems with established reimbursement codes, while margins concentrate in hybrid bioreactor platforms where FDA breakthrough designation commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates cell-based systems with 30-day shelf stability from synthetic membrane alternatives and legacy intermittent platforms. Price differentiation hinges on certification tier—FDA breakthrough pathway versus standard 510(k) clearance—and geographic delivery cost for cold-chain bioreactor components. Pricing pressure stems from Medicare reimbursement compression on conventional dialysis, squeezing standard-tier margins while premium cell-therapy platforms retain pricing power through transplant-waitlist demand. Dialysis center procurement committees exhibit highest price sensitivity, whereas academic medical centers prioritize clinical outcomes over unit economics.
Supply Chain Analysis
Domestic-content mandates in Japan's regenerative medicine framework and Germany's precision engineering procurement policies are reshaping sourcing patterns for bioreactor components. High-purity silicon membrane production clusters in Japan, Germany, and select East Asian manufacturing hubs anchor upstream supply. Living tubular epithelial cell sourcing draws from domestic tissue engineering facilities in the United States, Japan, and Germany, with cold-chain logistics tethered to regional bioreactor assembly sites. Single-source vulnerability concentrates in specialized semipermeable barrier substrates, where tariff exposure on East Asian silicon inputs threatens margin stability. Distribution runs through vertically integrated dialysis service networks and hospital system GPO contracts, with direct-to-clinic bioreactor logistics bypassing traditional device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bioartificial renal assist devices occupy a technology-transition phase where living-cell bioreactors are displacing purely synthetic filtration architectures. Cell-based metabolic regulation platforms are replacing legacy membrane-only systems across transplant-waitlist populations.
For Market Incumbents: Anchor market position through backward integration into bioreactor cell sourcing and captive supply of tubular epithelial cell lines. Incumbents must secure FDA breakthrough designation for next-generation platforms before emerging cell-therapy specialists achieve comparable regulatory positioning. Capacity addition in Japan's PMDA-priority-review corridor and Germany's precision engineering clusters reinforces geographic moats against new entrant disruption.
For New Entrants and Emerging Players: Capture white space in home-based ambulatory systems bypassing dialysis center infrastructure lock-in. The most penetrable segment sits in miniaturized bioartificial platforms for chronic kidney disease patients seeking treatment location flexibility. Go-to-market positioning through direct reimbursement strategy—targeting Medicare Advantage plans and Japanese national health insurance coverage decisions—sidesteps incumbent GPO contract barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with precision fluid management specialists given membrane-electrode assembly convergence with real-time metabolite sensing. Long-term viability over the projection horizon favors platforms bridging nephrology and tissue engineering capabilities. Acquisition target archetype: mid-cap membrane technology developers with FDA breakthrough pathway experience and existing hospital system pilot contracts. The signal to watch as inflection indicator is Japan PMDA priority review consultation awards for cell-based renal therapies.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated premarket review compresses time-to-revenue for cell-synthetic hybrid platforms. |
| CE Marking Pathway | EU MDR compliance for cell-containing devices enables German outpatient dialysis network expansion. |
| Hospital System Partnership | Integrated delivery system procurement consolidation secures preferred placement across multi-facility networks. |
| Software Companion Development | Real-time metabolite sensing integration electrifies clinical workflow design for continuous monitoring. |
| Reimbursement Strategy | Medicare and Japanese national health insurance coverage decisions determine addressable patient volume. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this bioartificial renal assist devices analysis. Primary interviews with nephrology clinicians, hospital purchasing committee directors, biomedical engineers, and GPO contracts managers combined with FDA 510(k) and breakthrough designation databases, EMA adaptive pathway submissions, and Japanese PMDA regenerative medicine consultation records. Bottom-up installed base modeling across dialysis centers and acute care settings triangulated against top-down market sizing from reimbursement code analysis and procedure volume estimates.
Data-stream reconciliation across continuous hemodialysis, hybrid bioreactor, and intermittent platform segments produced volume and value outputs throughout the forecast period. Segmentation dimensions modeled include product architecture, end-user channel, technology type, and application indication, with regional regulatory cluster differentiation for FDA, EMA, and PMDA pathways. CAGRs derived from procedure volume growth rates, reimbursement expansion trajectories, and cell-therapy platform adoption curves. Forecast inputs incorporated transplant waitlist expansion rates and silicon membrane supply capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA breakthrough designation award timing, EU MDR clinical evidence requirement evolution, and living cell logistics standardization. Forecasts reflect documented assumptions regarding reimbursement pathway maturation and bioreactor shelf stability certification timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Engineering
Global Biomedical Tester Market
Biomedical Engineering
Bioabsorbable Osteosynthesis Devices Market
Biomedical Engineering
Biological Derived Devices Market
Biomedical Engineering
Next-Generation Biomanufacturing Market
Biomedical Engineering
Medical Biomimetics Market
Biomedical Engineering
Biological Implants Market
Biomedical Engineering
Global Continuous Bioprocessing Market
Biomedical Engineering
3D Bioprinting Market
Biomedical Engineering
3D Bioprinted Organ Transplants Market
Biomedical Engineering
Tissue Engineering Market
Biomedical Engineering
Global Bovine-Based Collagen for Biomedical Applications Market
Biomedical Engineering
Topical Bioadhesives Market
Biomedical Engineering
Non-Surgical Bio-Implants Market
Biomedical Engineering
Bioactive Bone Grafts Market
Biomedical Engineering
Global Bionic Ear Market
Biomedical Engineering
Argentina Artificial Organs and Bionic Implants Market