
 In-Vitro Fertilization Services Market | 2026-2036
In-Vitro Fertilization Services Market Size, Share, and Industry Trends Forecast 2026-2036
In-Vitro Fertilization Services Market Intelligence
A shift in patient demographics, particularly the inclusion of employer-sponsored benefits, is repositioning how services are procured and delivered. Progyny Inc. specializes in this benefits management model, altering the traditional patient-clinic financial relationship. In contrast, IVIRMA Global leverages its extensive international clinic network to achieve scale and research leadership. Monash IVF Group sustains its market presence through a focus on scientific innovation and patient care within the Australian market.
In-vitro fertilization services encompass a series of complex medical procedures used to assist with conception. The core process involves the controlled stimulation of ovaries, retrieval of eggs, and their subsequent fertilization with sperm in a laboratory setting. While Fresh IVF Cycles remain a foundational service, Frozen IVF Cycles are gaining share due to improved cryopreservation techniques and scheduling flexibility. The delivery model is also evolving, with specialized Private Fertility Centers capturing volume from traditional Hospital-Based Clinics through enhanced patient experience and focused expertise.
Regulatory frameworks from bodies like the FDA in the United States and the EMA in Europe govern the drugs and medical devices used in IVF procedures. National authorities, such as the UK's HFEA, also set stringent standards for clinic licensing, data reporting, and ethical practices. This complex oversight directly influences service accessibility and operational protocols. Future market development will hinge on navigating the evolving ethical debates surrounding genetic technologies and reproductive rights.
Market Dynamics
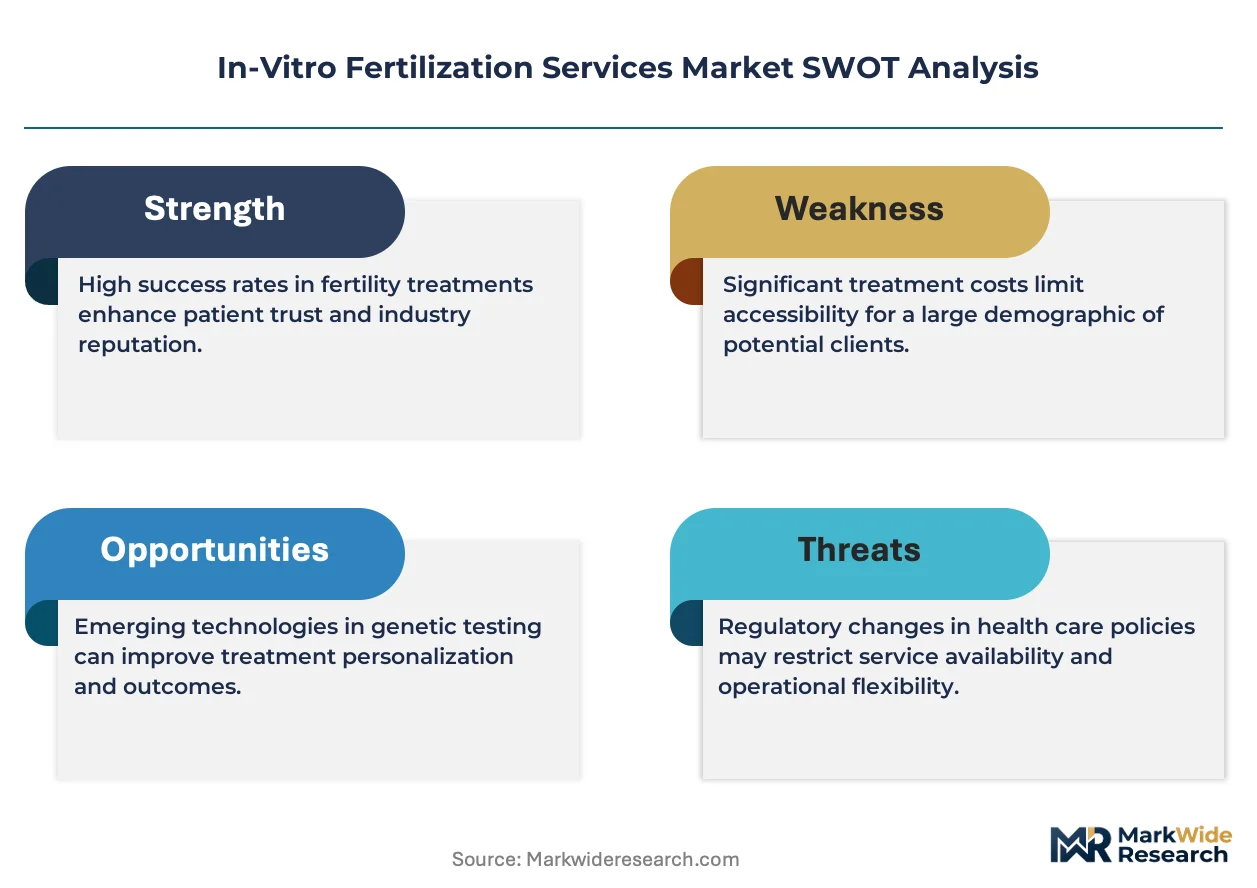
The market's structure is being reshaped by the convergence of advanced genetic testing technologies and the rise of employer-sponsored benefits programs. This dual force alters both clinical protocols and the financial pathways for patient access to care.
Growth Catalysts
- Preimplantation Genetic Testing (PGT):The integration of PGT for aneuploidy is improving embryo selection, leading to higher implantation rates and reducing miscarriage risks, thereby encouraging cycle uptake among patients with a history of failed cycles.
- Demographic Shifts:A global trend of delayed parenthood increases the age-related infertility population, while greater public awareness and destigmatization of fertility treatments drive more individuals and couples to seek assistance.
- Inclusive Service Demand:Growing utilization by LGBTQ+ individuals and single parents, supported by more inclusive insurance policies and evolving social norms, opens a significant and expanding patient cohort for fertility clinics.
Market Restraints
- High Cycle Costs:The substantial out-of-pocket expense for a single IVF cycle, often with no guarantee of success, remains the primary barrier to access for a large segment of the potential patient population.
- Regulatory Complexity:Clinics must navigate a complex web of rules from bodies like the UK's HFEA and the US FDA, which govern lab standards and data reporting, increasing operational overhead and compliance costs.
- Ethical and Social Opposition:Persistent ethical debates over embryo disposition and genetic selection create social and sometimes legislative resistance that can constrain service availability and adoption in certain conservative regions.
Strategic Opportunities
- Artificial Intelligence Integration:Applying AI algorithms to analyze embryology data offers an opportunity to improve the accuracy of embryo selection and personalize treatment protocols, potentially boosting success rates and reducing costs.
- Geographic Expansion:There is potential for growth in affluent urban centers within Latin America and Southeast Asia, where rising incomes and declining fertility rates create new demand for advanced reproductive technologies.
- Ancillary Wellness Services:Developing and bundling services such as nutritional counseling and mental health support creates a more holistic patient journey, improving outcomes and building loyalty beyond the core medical procedure.
Industry Challenges
- Specialized Talent Scarcity:A global shortage of experienced embryologists and reproductive endocrinologists creates a bottleneck for clinic expansion and can compromise quality of care, especially in non-metropolitan areas.
- Data Management and Security:Protecting highly sensitive patient health and genetic information in compliance with regulations like HIPAA requires significant investment in secure IT infrastructure and protocols against cyber threats.
- Outcome Standardization Gaps:The absence of a universally accepted methodology for reporting clinic success rates makes it difficult for patients to make informed comparisons, leading to market confusion and mistrust.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Vitro Fertilization Services Market |
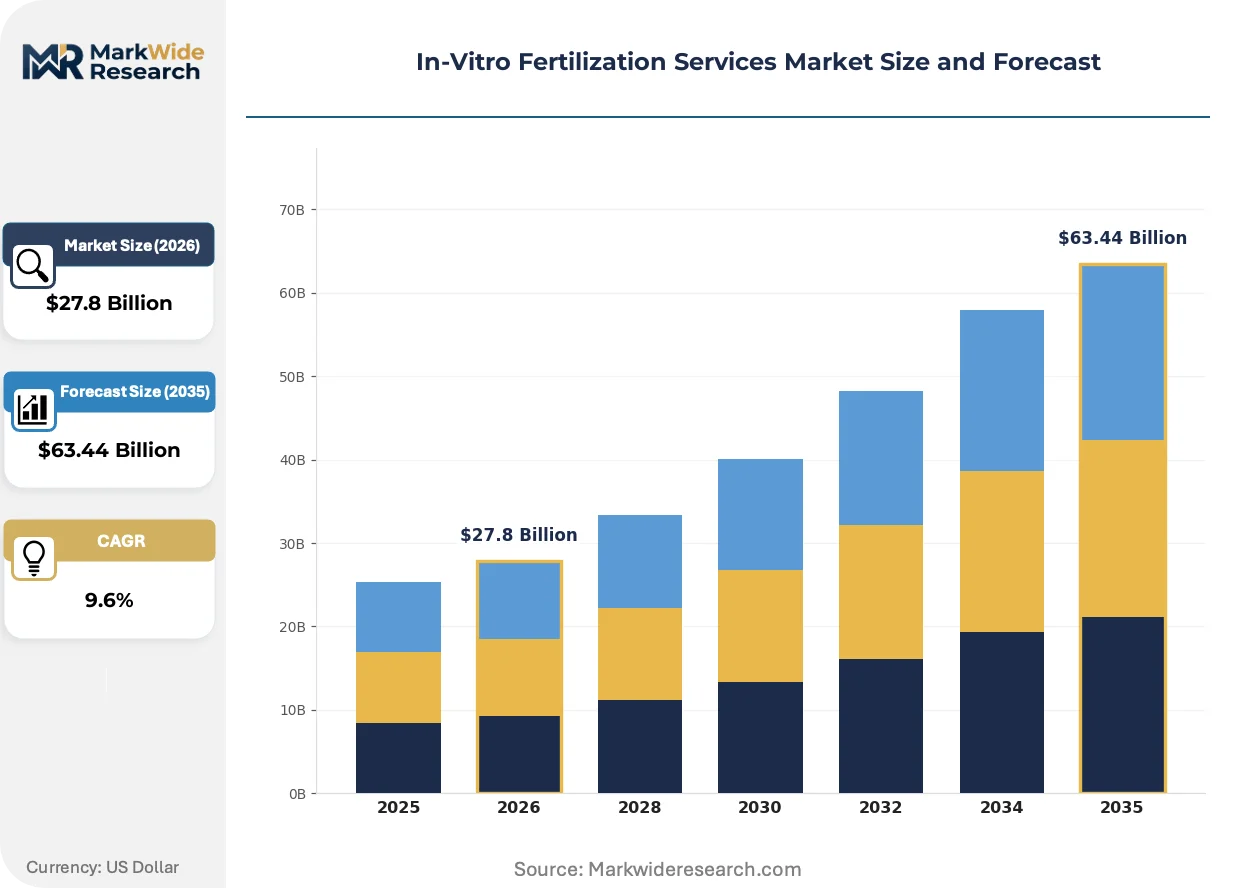
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $63.44 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fresh IVF Cycle, Frozen IVF Cycle, Donor Egg IVF, Surrogacy Services Patient Demographic: Infertile Couples, Single Women, LGBTQ+ Individuals, Advanced Maternal Age Delivery Model: Hospital-Based Clinics, Private Fertility Centers, Mobile Clinics, Telehealth Solutions Pricing Model: Fixed Package, Pay-Per-Cycle, Insurance Covered, Subscription-Based Plans |
| Companies Covered | IVIRMA Global, Monash IVF Group, Reproductive Medicine Associates, Shady Grove Fertility Center, CCRM Fertility, Progyny Inc., Virtus Health, New Hope Fertility Clinic, Houston Fertility Institute, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Vitro Fertilization Services Market Strategic Shifts & Innovations
The convergence of data-driven personalization and new service delivery frameworks is defining the market's next phase. These shifts are moving the industry beyond procedural repetition toward more tailored and accessible patient care pathways.
Technology-Assisted Embryo Selection
Time-lapse imaging systems provide continuous, non-invasive monitoring of embryo development inside an incubator, generating vast amounts of morphological data. Advanced private fertility centers are adopting this technology to improve selection accuracy for patients. The technology is expanding into the standard of care for complex cases, offering granular data that informs both embryo selection and future treatment cycle adjustments.
Stricter Device and Consumable Oversight
Europe's Medical Device Regulation (MDR) imposes significantly stricter requirements for clinical evidence and post-market surveillance on all devices used in IVF. This directly impacts the cost and availability of essential lab supplies like culture media and catheters. Clinics in EU countries, including Spain, now face higher compliance costs and potential supply chain disruptions from device manufacturers adjusting to the new rules.
Evolving Procurement Models
A significant behavioral change is the increasing use of employer-sponsored benefits managers to finance fertility treatments. This model disrupts the direct patient-to-clinic payment system, as third-party managers negotiate service bundles and pricing on behalf of large employee groups. This procurement pattern is most advanced in the competitive corporate landscape of the United States, particularly within the technology and finance sectors.
In-Vitro Fertilization Services Market Segmentation
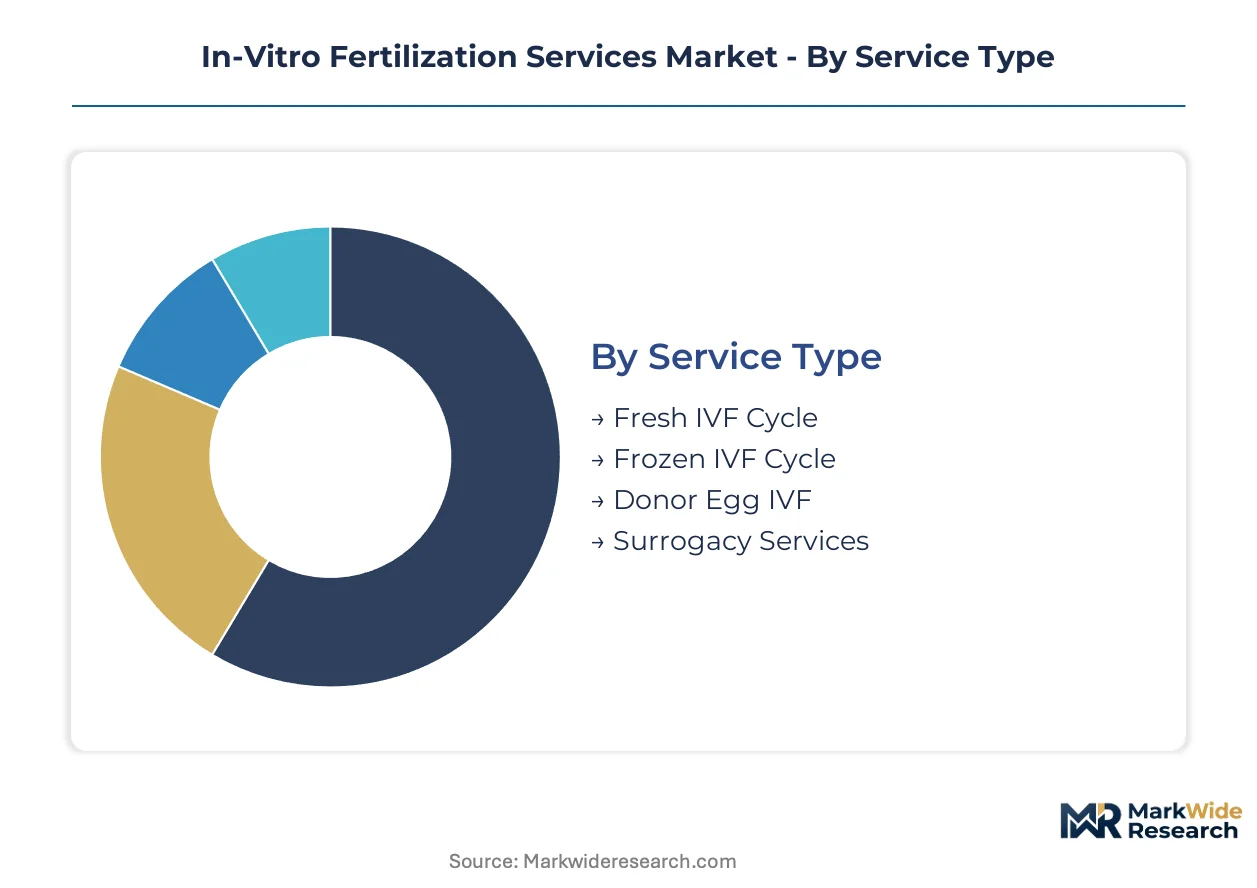
Understanding the segmentation of the In-Vitro Fertilization Services Market is crucial for identifying distinct patient needs and optimizing service delivery models. This detailed breakdown highlights how different treatment approaches, patient profiles, and operational structures shape market dynamics and commercial opportunities.
Service Type:
The service type segmentation reveals a clear distinction between high-volume foundational procedures and specialized, often premium, interventions.
- Fresh IVF Cycle:This foundational service involves immediate embryo transfer after fertilization, typically within days of egg retrieval. Demand is consistent among patients seeking direct and immediate treatment, particularly in countries like the United States where success rates are closely tracked.
- Frozen IVF Cycle:This process utilizes cryopreserved embryos from a previous fresh cycle or donor eggs, offering greater scheduling flexibility and reducing ovarian stimulation risks. Its growing share is driven by improved cryopreservation techniques and patient preference for staggered treatment, especially in clinics across Spain.
- Donor Egg IVF:This service caters to individuals or couples using eggs from a donor, often due to ovarian reserve issues or genetic concerns.
- Surrogacy Services:These services involve a gestational carrier carrying a pregnancy for intended parents, representing a complex and often legally intricate pathway to parenthood.
Today's leader: Fresh IVF Cycle. Tomorrow's challenger: Frozen IVF Cycle.
Patient Demographic:
Patient demographics highlight the diverse needs and evolving social contexts driving individuals and couples to seek fertility assistance.
- Infertile Couples:This segment comprises heterosexual couples facing challenges in conceiving naturally, representing the largest historical patient base for IVF services. Their demand is often driven by physiological infertility factors, making them a primary target for established fertility centers globally.
- LGBTQ+ Individuals:This expanding demographic includes same-sex couples and single individuals utilizing IVF with donor gametes or surrogacy to build families. Inclusive insurance policies and evolving social norms in countries such as the United States and Japan are significantly boosting utilization within this cohort.
- Single Women:This group seeks IVF services, often with donor sperm, to achieve motherhood independently, reflecting changing societal views on family structures.
- Advanced Maternal Age:Women delaying childbirth into their late 30s and 40s often experience age-related fertility decline, leading them to seek IVF to overcome conception difficulties.
Utilization among LGBTQ+ individuals represents the fastest-growing trajectory within this segment.
Delivery Model:
The delivery model segment outlines the operational structures through which fertility treatments are provided, ranging from established institutions to innovative remote solutions.
- Private Fertility Centers:These specialized clinics offer focused expertise, advanced technology, and a patient-centric experience, often capturing significant volume from traditional hospital settings. Their agility allows for quicker adoption of innovations like time-lapse imaging systems.
- Hospital-Based Clinics:Integrated within larger healthcare systems, these clinics benefit from comprehensive medical support and established infrastructure. They often serve as referral centers for complex cases and are prevalent in systems like those found in Europe.
- Mobile Clinics:These portable units aim to improve access to fertility consultations and certain diagnostic services in underserved or rural areas, reducing geographic barriers.
- Telehealth Solutions:Virtual consultations and remote monitoring offer convenience and accessibility for initial assessments, follow-ups, and counseling, particularly for patients in remote locations.
The market is witnessing a shift towards specialized Private Fertility Centers, which are gaining traction over traditional hospital settings.
Pricing Model:
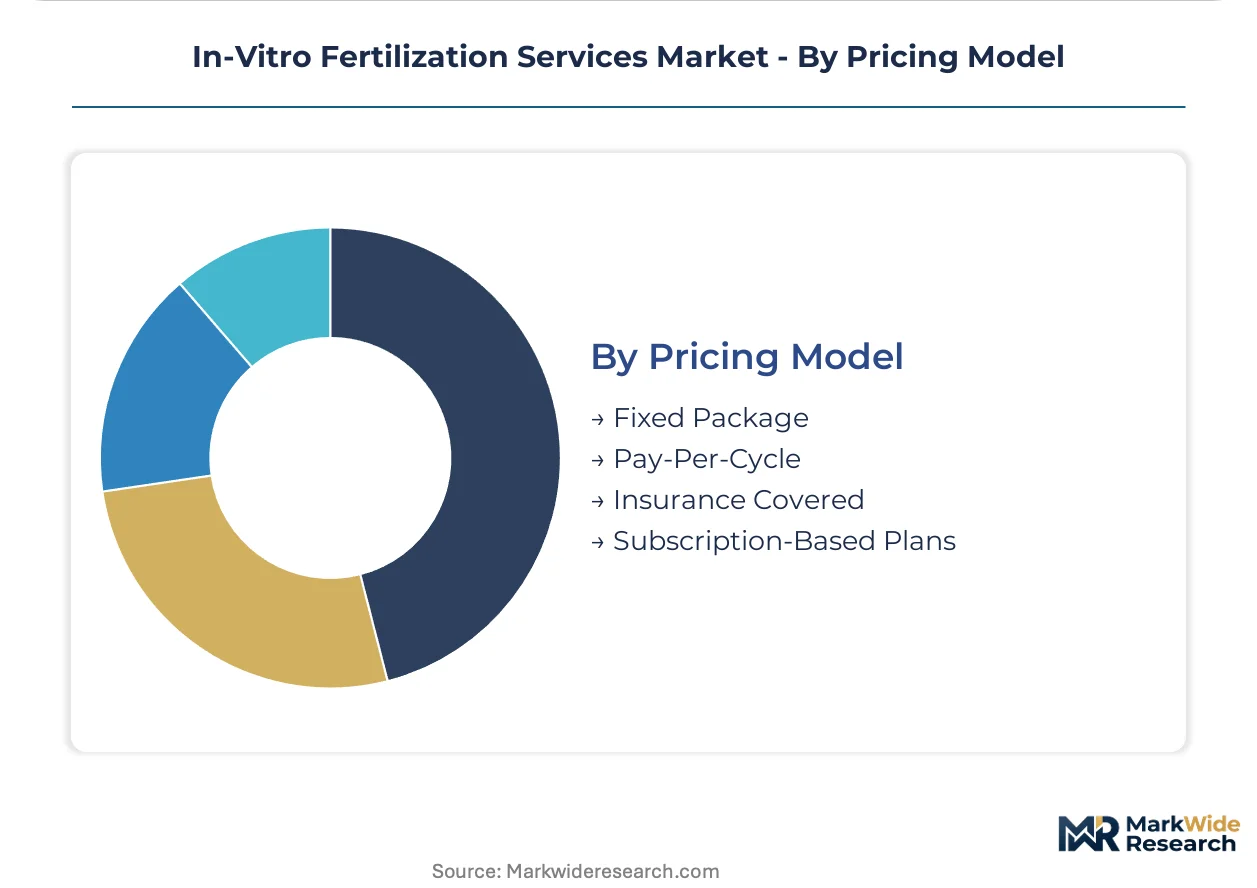
Pricing models reflect the varied financial pathways patients navigate, from direct payments to employer-backed benefits and flexible plans.
- Insurance Covered:This model involves partial or full reimbursement for IVF services through health insurance plans, significantly increasing patient access and reducing out-of-pocket expenses. Employer-sponsored benefits in the United States exemplify this model, altering traditional patient-clinic financial relationships.
- Fixed Package:Patients pay a predetermined lump sum for a defined set of IVF services, offering cost predictability. This model is common in many international markets, including parts of Asia, where transparency is valued.
- Pay-Per-Cycle:Patients pay for each individual IVF cycle performed, allowing for flexibility but potentially higher cumulative costs if multiple cycles are needed.
- Subscription-Based Plans:These emerging models offer ongoing access to services or discounted rates for multiple cycles through a recurring payment structure, aiming to reduce upfront financial burden.
The evolution of insurance coverage and employer-sponsored benefits significantly influences patient access and procurement patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States and Spain exhibit distinct yet significant demand for in-vitro fertilization services, driven by differing regulatory environments and patient preferences. Japan's market is also expanding, reflecting evolving societal norms and advanced medical capabilities. Australia and Germany contribute to European and APAC market dynamics with specialized clinics.
United States
Delayed parenthood and inclusive service demand from LGBTQ+ individuals drive significant utilization in the United States. The FDA regulates drugs and medical devices, while HIPAA ensures patient data security across clinics. Employer-sponsored benefits programs are reshaping procurement patterns in metropolitan areas like New York City.
Spain
Spain experiences high demand for frozen IVF cycles, supported by advanced cryopreservation techniques and patient scheduling flexibility. The EMA's Medical Device Regulation (MDR) influences device availability and compliance costs for clinics. Clinics in cities like Barcelona and Madrid leverage extensive international networks for scale and research.
Japan
Japan's market sees demand from delayed parenthood and a growing number of LGBTQ+ individuals seeking fertility assistance. The PMDA oversees medical devices and pharmaceuticals used in procedures, ensuring safety standards. Advanced fertility centers in Tokyo and Osaka are integrating preimplantation genetic testing.
Australia
Australia maintains market presence through a strong focus on scientific innovation and patient-centric care models. The TGA regulates medical devices and drugs, while national guidelines ensure ethical practices and data reporting. Clinics in Melbourne and Sydney are known for their research leadership and patient outcomes.
Germany
Germany's demand stems from an aging population experiencing age-related infertility, supported by a comprehensive healthcare system. EMA regulations impact the availability and cost of IVF devices and consumables within the country. Hospital-based clinics in Berlin and Munich offer integrated medical support and established infrastructure.
In-Vitro Fertilization Services Market Key Industry Players
United States producers anchor one tier; European specialists hold another, creating a tiered market structure. The market exhibits a fragmented structure with a mix of large international networks and specialized local clinics. Three strategic archetypes include global clinic chains, benefits management providers, and regional specialists focused on scientific innovation. Companies are increasingly pursuing geographic expansion and strategic partnerships to broaden their patient reach. Portfolio diversification, especially into ancillary wellness services, is also a notable competitive move.
Within the global clinic chain archetype, IVIRMA Global leverages its extensive international network to achieve scale and research leadership across multiple continents. Monash IVF Group, an Australian-based entity, exemplifies regional specialists, sustaining market presence through a focus on scientific innovation and patient care within its home market. Progyny Inc. represents the emerging benefits management model, altering the traditional patient-clinic financial relationship, particularly within the competitive corporate landscape of the United States. These organizations collectively shape service delivery and patient access patterns, pushing for efficiency and improved patient outcomes.
| Leading Market Players |
|---|
| IVIRMA Global |
| Monash IVF Group |
| Reproductive Medicine Associates |
| Shady Grove Fertility Center |
| CCRM Fertility |
| Progyny Inc. |
| Virtus Health |
| New Hope Fertility Clinic |
| Houston Fertility Institute |
| Others |
Cost & Logistics Intelligence
Specialized culture media and cryopreservation agents, sourced from a limited number of biotech suppliers, directly influence the cost structure for fertility clinics and ultimately patient package pricing.
Pricing Analysis
Capacity additions in metropolitan areas of the United States are reshaping price floors for IVF services, particularly for fixed package options. The market primarily utilizes insurance-covered models, especially through employer-sponsored benefits in the US, alongside fixed package pricing in other regions. Price differentiation stems from clinic success rates and the integration of advanced technologies like time-lapse imaging systems. Pricing softness is not observed; instead, costs are driven upward by the integration of preimplantation genetic testing and the scarcity of experienced embryologists. Patients relying on out-of-pocket payments, such as infertile couples without insurance, exhibit the highest price sensitivity.
Supply Chain Analysis
Workforce availability in specialized manufacturing geographies, particularly for complex medical devices and consumables, significantly impacts the IVF supply chain. The supply chain draws from specialized manufacturers primarily in Europe and the United States for essential items like culture media and cryopreservation solutions. Clinics rely on these concentrated sources for high-quality diagnostic reagents and catheters. Regulatory complexity, such as Europe's Medical Device Regulation, presents a structural risk by influencing device availability and increasing compliance costs. Distribution runs through direct procurement channels to private fertility centers and hospital-based clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The In-Vitro Fertilization Services Market presents a geographic-arbitrage play, driven by differing regulatory frameworks and cost structures between regions like the United States and Spain.
For Market Incumbents: Acquire specialized fertility centers and advanced genetic testing laboratories to consolidate market share and integrate new technologies. Incumbents must expand their geographic footprint in underserved affluent urban centers, leveraging established brand recognition. This strategy helps counter the threat from emerging benefits management providers altering patient procurement. Invest in artificial intelligence integration for personalized treatment protocols, enhancing success rates and patient outcomes. Focus on research leadership to maintain a competitive edge against smaller, agile clinics.
For New Entrants and Emerging Players: Capture niche segments by offering bundled ancillary wellness services, including nutritional counseling and mental health support, to create a holistic patient journey. Target affluent urban centers in Latin America and Southeast Asia, where rising incomes create new demand. The LGBTQ+ individual segment represents a highly penetrable demographic due to evolving social norms and inclusive policies. A digital-first go-to-market angle, leveraging telehealth for initial assessments and remote monitoring, reduces geographic barriers and enhances accessibility. Focus on patient experience to differentiate from established hospital-based clinics.
For Investors and Strategic Acquirers: Consolidation pressure builds where specialized talent scarcity limits clinic expansion and operational overheads increase due to regulatory complexity. The market offers long-term viability over the next decade, driven by delayed parenthood and inclusive service demand. Target acquisition archetypes include specialized private fertility centers demonstrating strong success rates and advanced technological integration. A key signal to watch is the evolution of ethical debates surrounding genetic technologies, which could impact market development. Evaluate firms with robust data management and security protocols for sensitive patient information.
| Strategic Initiative | Industry Significance |
|---|---|
| Geographic Expansion | Broadens patient reach in high-demand urban centers like those in Latin America and Southeast Asia. |
| Artificial Intelligence Integration | Improves embryo selection accuracy and personalizes treatment protocols, boosting success rates. |
| Acquisition of Specialist Clinics | Consolidates market share and integrates advanced technologies, such as PGT, into existing networks. |
| Ancillary Wellness Services | Creates a holistic patient journey and builds loyalty beyond core medical procedures. |
| Enhanced Data Security | Ensures compliance with regulations like HIPAA, protecting sensitive patient health and genetic information. |
Research Approach
Bottom-up patient demographic modeling reconciled against top-down fertility clinic network tracking forms the analytical core of this study. This approach integrated primary interviews with reproductive endocrinologists, embryologists, clinic administrators, and insurance benefits managers for qualitative insights. Secondary validation drew from FDA filings, EMA submissions, national fertility registries like the UK's HFEA, and peer-reviewed medical journals. This triangulated data ensured comprehensive market understanding.
Historical trendline analysis established foundational growth trajectories for each market segment across the analysis window. The analytical framework modeled market dynamics across service type, patient demographic, delivery model, pricing model, and regional prevalence. Compound annual growth rates were derived through regression analysis of historical data and projected impact from growth catalysts. Forecast inputs included evolving fertility success rates influenced by PGT and expanding employer-sponsored insurance coverage.
Regulatory shifts, ethical debates, and specialized talent availability are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding current policy environments and technological adoption rates. Significant changes in national healthcare policies or public acceptance of genetic technologies could alter projections. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Phospho-Specific Antibodies Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Global Bioprocess Validation Market