
 GMO Testing Services Market | 2026-2036
GMO Testing Services Market Size, Share, and Industry Trends Forecast 2026-2036
GMO Testing Services Market Foresight
North American laboratory capacity is fragmenting as third-party providers race to absorb overflow from in-house agricultural testing programs. Eurofins Scientific leverages its distributed laboratory footprint to anchor multi-jurisdiction compliance workflows for commodity traders. SGS SA competes through specialized GMO identity preservation protocols that extend across soybean export corridors. Bureau Veritas differentiates by controlling certification workflows that bridge farm-level sampling and port-of-entry clearance.
GMO testing services encompass analytical protocols that detect, identify, and quantify genetically modified organisms in agricultural and food matrices through DNA-based, protein-based, or sequencing methodologies. Polymerase Chain Reaction remains the dominant technology platform due to its established sensitivity thresholds for low-level presence detection, while Next-Generation Sequencing is displacing legacy methods for unauthorized event screening. Laboratory Testing occupies the largest revenue pool given the capital intensity of controlled-environment analysis, though Field Testing is expanding fastest among on-farm verification programs. Agricultural Producers constitute the most price-sensitive end-user segment, whereas Government Agencies command premium service tiers tied to enforcement mandates.
The USDA's Grain Inspection, Packers and Stockyards Administration shapes domestic market access through official sampling protocols, while the EU's European Commission Directorate-General for Health and Food Safety enforces zero-tolerance thresholds for unapproved events. China's SAMR maintains separate approval catalogs that fragment testing requirements for exporters serving multiple jurisdictions. Stakeholders must monitor divergence between authorization regimes as the primary determinant of testing scope and cost structure.
Market Dynamics
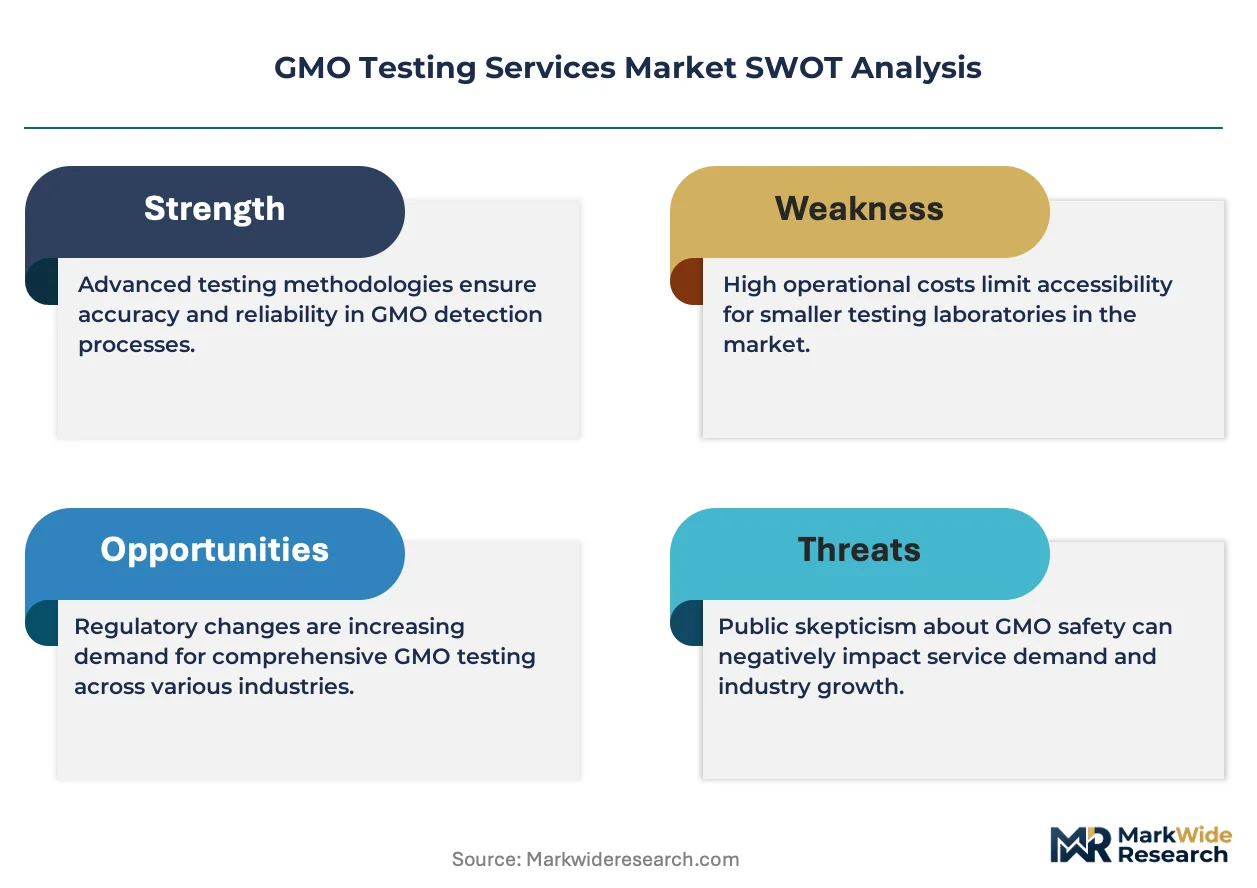
The divergence between authorization regimes across major importing blocs is fragmenting testing protocols and multiplying compliance costs for agricultural commodity traders.
Growth Catalysts
- EU Regulation 1830/2003 traceability mandates:Food manufacturers in Germany face the strictest labeling enforcement, compelling laboratories to upgrade detection sensitivity and expand service capacity.
- Brazilian seed sector expansion:Seed companies are accelerating GMO verification protocols ahead of export deadlines, creating sustained demand for third-party analytical services.
- Next-Generation Sequencing adoption:Unauthorized event screening requirements are pulling laboratories toward higher-resolution detection platforms that command premium pricing tiers.
Market Restraints
- Capital intensity of controlled-environment facilities:Laboratory infrastructure requires substantial upfront investment in climate-controlled spaces and precision instrumentation, elevating barriers to entry.
- Reagent supply concentration:Specialty PCR primers and probe chemistries concentrate among a limited supplier base, exposing testing providers to input cost volatility and availability constraints.
- Regulatory fragmentation across jurisdictions:China's SAMR maintains separate approval catalogs from the EU and US, forcing exporters to duplicate testing workflows and absorb redundant certification costs.
Strategic Opportunities
- On-farm verification programs:Field Testing segments are expanding fastest among agricultural producers seeking point-of-origin documentation that reduces downstream rejection risk.
- Multi-jurisdiction compliance workflows:Commodity traders require integrated sampling-to-clearance protocols that bridge farm-level collection and port-of-entry release across divergent regulatory systems.
- Digital chain-of-custody integration:Blockchain-enabled sample tracking is emerging as a value-add service that differentiates providers serving identity preservation markets.
Industry Challenges
- Specialized molecular biology talent scarcity:PCR and sequencing expertise concentrates in urban research clusters, constraining laboratory expansion into agricultural production regions.
- Certification timeline compression:Rapid regulatory updates require continuous method validation cycles that strain quality assurance resources and delay service line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GMO Testing Services Market |
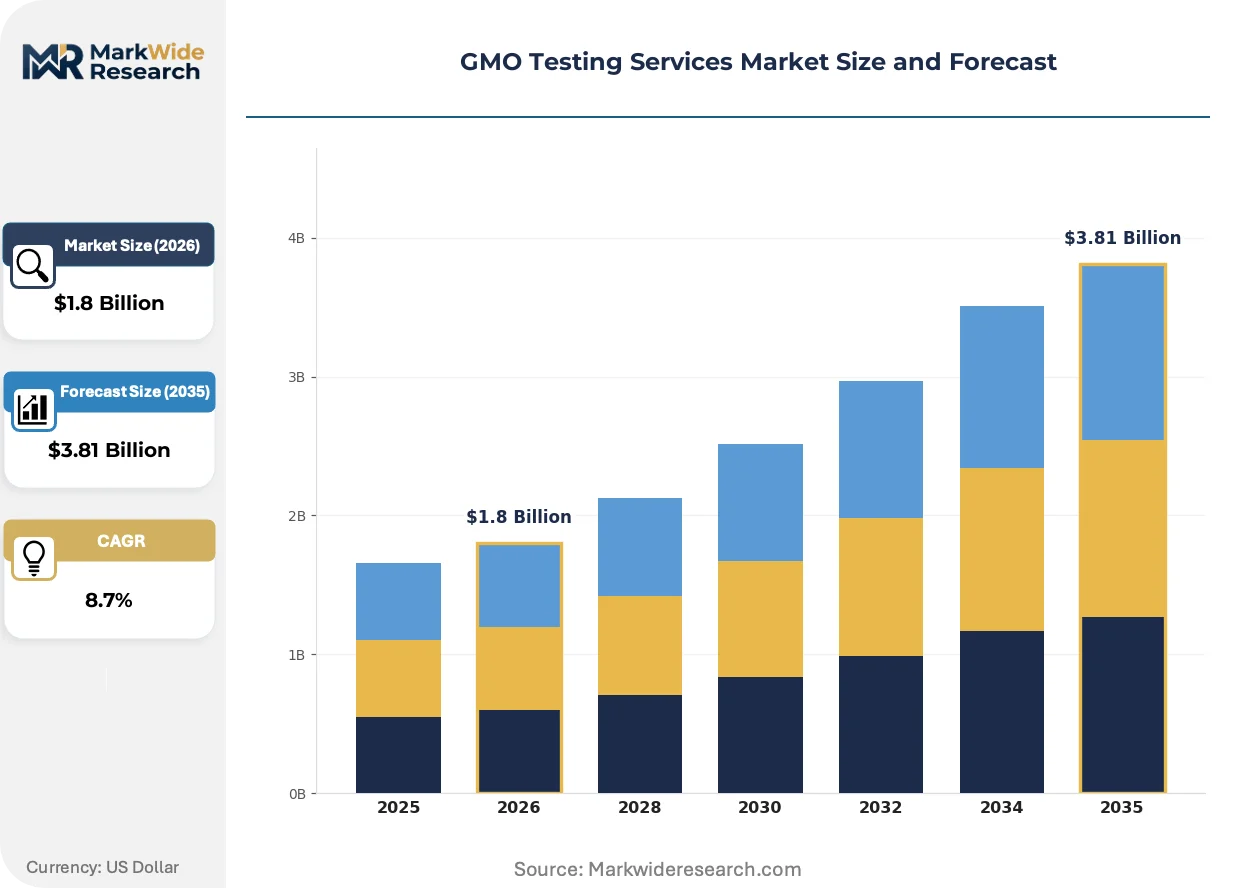
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Testing, Field Testing, Genetic Analysis, Risk Assessment Technology: Polymerase Chain Reaction, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing, Biosensor Technology End User: Agricultural Producers, Food Manufacturers, Research Institutions, Government Agencies Sample Type: Crops, Processed Food, Animal Feed, Environmental Samples |
| Companies Covered | SGS SA, Eurofins Scientific, Intertek Group plc, Bureau Veritas, ALS Limited, TÜV SÜD, Thermo Fisher Scientific, Bio-Rad Laboratories, Mérieux NutriSciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GMO Testing Services Market Shifts & Advancements
Detection methodologies are bifurcating between standardized low-cost screening and premium unauthorized-event identification, reshaping how laboratories configure their technology portfolios and price their service tiers.
Next-Generation Sequencing is collapsing the cost structure for detecting novel genetic constructs in complex agricultural matrices. Government Agencies with enforcement mandates are adopting these platforms fastest, replacing legacy event-specific PCR panels with comprehensive genomic surveys. This shift is compressing the window between unauthorized trait emergence and regulatory detection from months to weeks.
The EU's tightening implementation of zero-tolerance thresholds for unapproved events is forcing laboratories to demonstrate detection capabilities at progressively lower presence levels. Eurofins Scientific and Bureau Veritas are restructuring their European laboratory networks to anchor multi-step verification workflows that satisfy both pre-market authorization and post-market surveillance requirements. German food manufacturers now require dual-technology confirmation for any positive screening result, doubling analytical throughput per sample.
Buyer concentration among large commodity traders is consolidating procurement decisions into centralized vendor qualification programs. Agricultural producers are responding by forming cooperative sampling arrangements that aggregate volume sufficient to access tiered pricing structures previously reserved for multinational exporters. This pattern is most visible in Brazil's soybean belt, where producer associations negotiate block contracts with third-party providers.
GMO Testing Services Market Segmentation
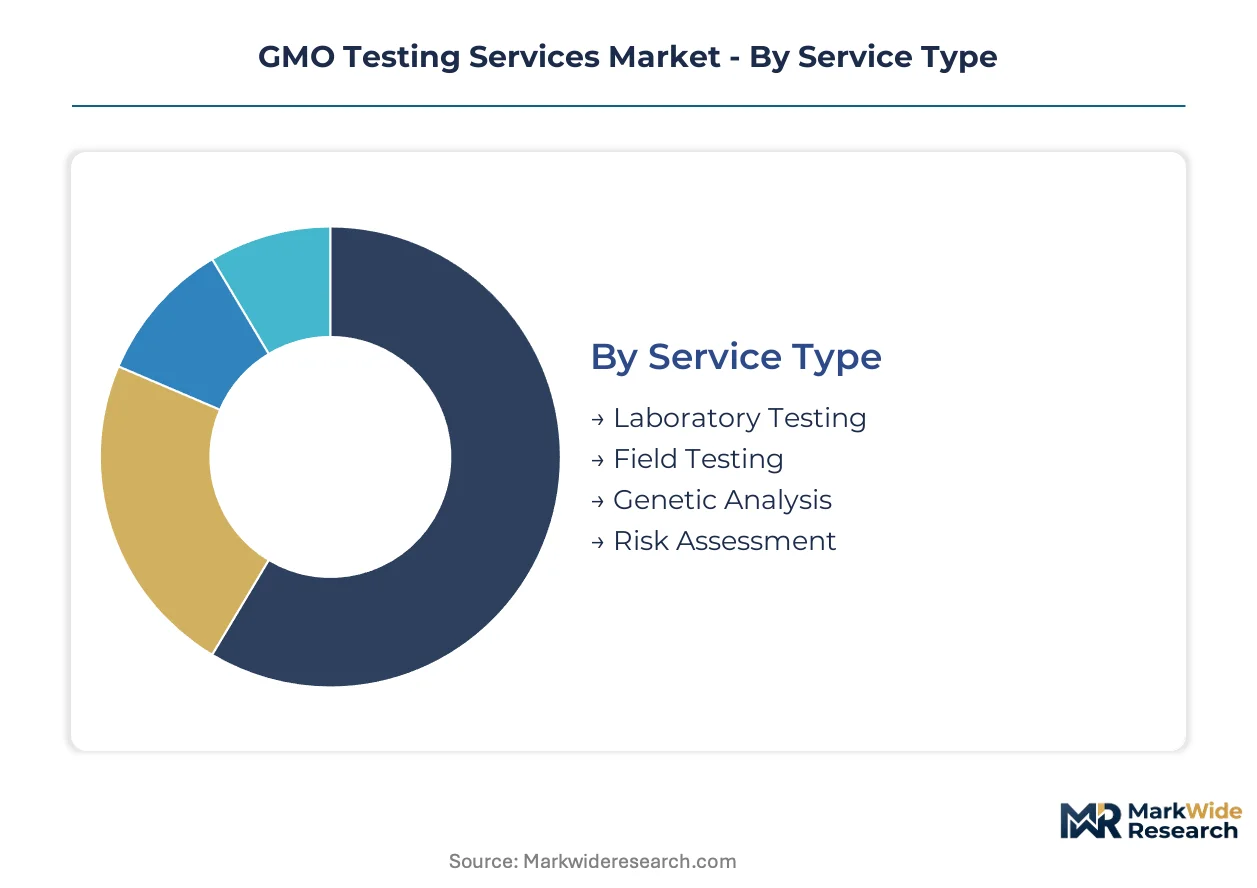
GMO testing services fragment across four distinct category axes, each with divergent margin profiles and capital requirements. Service type and technology selection determine cycle times ranging from same-day field results to multi-week sequencing protocols.
Service Type:
Laboratory Testing commands the longest validation cycles but anchors recurring revenue streams, while Field Testing compresses turnaround to hours for on-farm decisions.
- Laboratory Testing:Controlled-environment analysis utilizing climate-controlled facilities and precision instrumentation for regulatory-grade documentation. Demand concentrates among German food manufacturers facing EFSA enforcement mandates under zero-tolerance thresholds. Capital intensity elevates barriers to entry but secures multi-year contracts with commodity traders.
- Field Testing:Portable diagnostic protocols deployed at point of origin for rapid presence-absence screening. Brazilian seed companies in Mato Grosso and Paraná are expanding verification programs ahead of export deadlines, compressing procurement timelines from weeks to days. Equipment mobility reduces infrastructure overhead but limits detection sensitivity.
- Genetic Analysis:Specialized screening for unauthorized events and novel construct identification using reference database comparisons.
- Risk Assessment:Documentary review and supply chain auditing services that evaluate contamination probability across commodity flows.
Laboratory Testing anchors the volume base while Field Testing gains share at the steepest rate.
Technology:
Cost tiers separate legacy screening methods from premium sequencing platforms, with capital requirements spanning three orders of magnitude.
- Polymerase Chain Reaction:Dominant platform leveraging DNA amplification for established sensitivity thresholds at low per-sample cost. USDA official sampling protocols standardize PCR workflows for domestic grain inspection, entrenching incumbent providers with validated primer libraries. Method familiarity supports rapid technician training but constrains detection of novel events.
- Next-Generation Sequencing:High-resolution genomic surveys displacing event-specific panels for comprehensive unauthorized trait detection. China's SAMR enforcement divisions are adopting these platforms fastest, replacing legacy workflows with whole-genome approaches that compress detection windows from months to weeks. Instrumentation and bioinformatics investments command premium pricing tiers.
- Enzyme-Linked Immunosorbent Assay:Protein-based detection utilizing antibody binding for rapid qualitative screening in field conditions.
- Biosensor Technology:Emerging electrochemical and optical platforms targeting point-of-use deployment with reduced sample preparation.
PCR anchors the volume base while Next-Generation Sequencing climbs the fastest.
End User:
Customer type determines pricing power, with enforcement mandates supporting premium tiers and agricultural producers driving commoditization.
- Government Agencies:Regulatory enforcement and surveillance programs requiring certified methods with full chain-of-custody documentation. EU member state laboratories under DG SANTE oversight command highest service premiums tied to zero-tolerance implementation. Procurement centralization into multi-year framework agreements reduces vendor switching.
- Food Manufacturers:Labeling compliance and supplier verification programs across packaged goods and ingredient supply chains. German manufacturers face strictest enforcement, compelling dual-technology confirmation protocols that double analytical throughput per positive screening result. Liability exposure elevates willingness to pay for accredited providers.
- Agricultural Producers:Price-sensitive verification for export eligibility and identity preservation certification.
- Research Institutions:Method development and validation studies supporting regulatory submission packages for novel trait approvals.
Government Agencies anchor the volume base while Food Manufacturers expand most quickly.
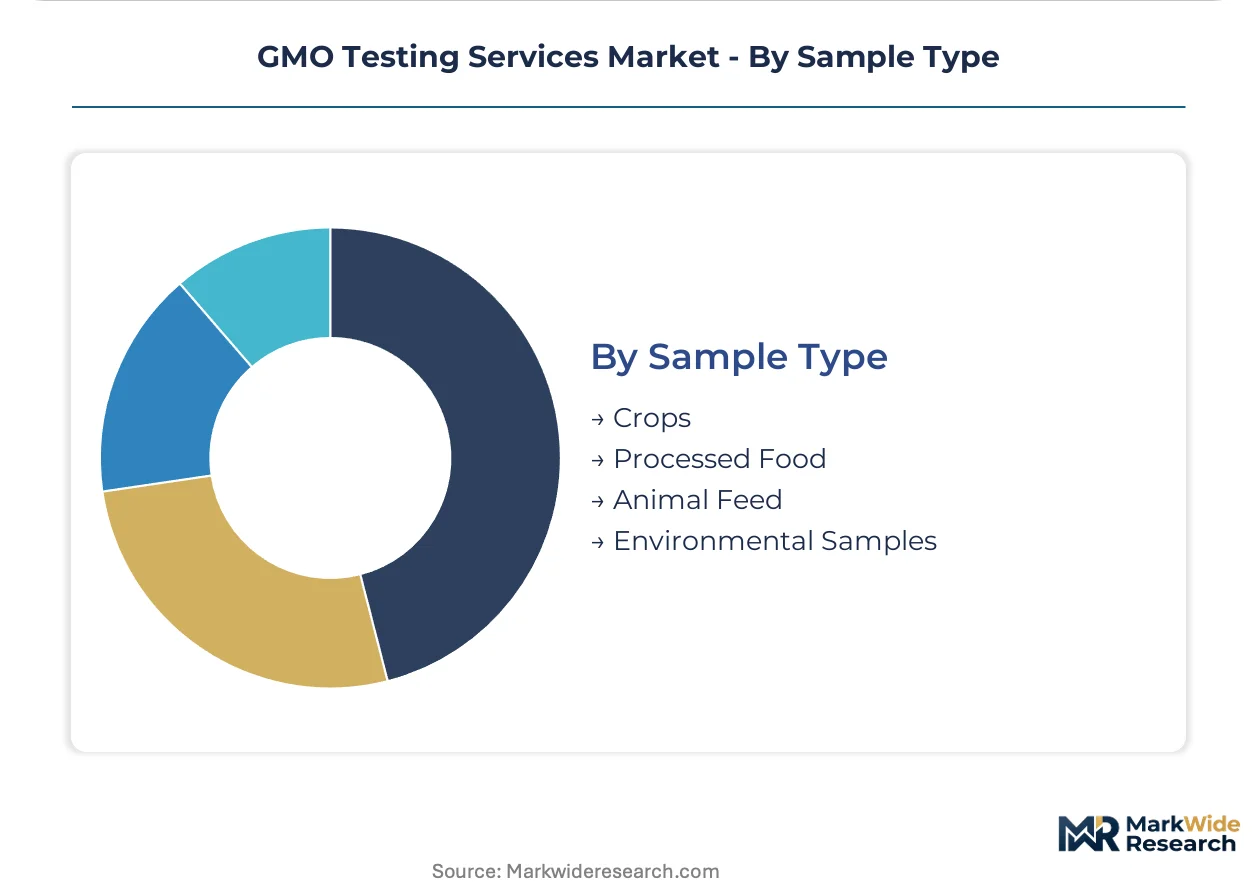
Sample Type:
Matrix complexity drives method selection, with unprocessed agricultural materials presenting lower interference than formulated products.
- Crops:Raw agricultural commodities including soybeans, maize, and canola requiring pre-export verification for multiple jurisdiction approvals. Brazilian soybean belt cooperatives are aggregating volume to access tiered pricing previously reserved for multinational exporters. Seasonal harvest concentration creates capacity utilization challenges.
- Processed Food:Multi-ingredient matrices with degraded DNA and protein content demanding extraction optimization and method validation. EU Regulation 1830/2003 traceability mandates compel manufacturers to document GMO presence through processing stages, expanding testing scope beyond raw material intake. Detection limits degrade with thermal and mechanical processing intensity.
- Animal Feed:Compound formulations with ingredient substitution practices that complicate supply chain documentation.
- Environmental Samples:Soil and water monitoring for adventitious presence and gene flow assessment in research contexts.
Crops anchor the volume base while Processed Food gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA enforces zero-tolerance thresholds across the European Union, compelling laboratories to demonstrate detection capabilities at progressively lower presence levels. This regulatory architecture fragments testing protocols and multiplies compliance costs for agricultural commodity traders serving multiple jurisdictions.
United States
USDA's Grain Inspection, Packers and Stockyards Administration shapes domestic market access through official sampling protocols that standardize PCR workflows for grain inspection. The agency's validation requirements entrench incumbent providers with certified primer libraries across the Midwest grain belt. Chicago and Minneapolis laboratories anchor multi-step verification workflows for soybean and maize exporters.
Germany
DG SANTE oversight commands highest service premiums tied to strictest labeling enforcement under EU Regulation 1830/2003. Food manufacturers in Bavaria and North Rhine-Westphalia now require dual-technology confirmation for positive screening results. Berlin-Brandenburg laboratory networks are restructuring to anchor pre-market authorization and post-market surveillance requirements.
Brazil
ANVISA maintains separate approval catalogs that fragment testing requirements for seed companies accelerating verification protocols ahead of export deadlines. Mato Grosso and Paraná producer associations negotiate block contracts with third-party providers. São Paulo laboratories absorb overflow from in-house agricultural testing programs across the soybean belt.
China
SAMR enforcement divisions are adopting Next-Generation Sequencing platforms fastest, replacing legacy event-specific PCR panels with whole-genome approaches. The regulator's separate approval catalogs force exporters to duplicate testing workflows and absorb redundant certification costs. Shanghai and Beijing laboratory clusters concentrate molecular biology talent for unauthorized event screening.
GMO Testing Services Market Competitive Landscape
Full-service testing conglomerates and specialized analytical laboratories split the market into distinct capability tiers. Consolidation pressure intensifies as buyer concentration among large commodity traders centralizes procurement decisions into vendor qualification programs. Three archetypes dominate: distributed-network compliance providers, identity-preservation specialists, and precision instrumentation suppliers. Capacity expansion and multi-jurisdiction certification partnerships represent the dominant competitive moves as laboratories race to bridge farm-level sampling and port-of-entry clearance.
Within the distributed-network tier, Eurofins Scientific and SGS SA exemplify providers leveraging geographic footprint to anchor compliance workflows across divergent regulatory systems. Bureau Veritas occupies a position among certification-focused specialists controlling workflows that integrate farm-level documentation with customs release protocols. These three entities represent how scale and regulatory intimacy combine to secure multi-year framework agreements with commodity traders and government enforcement agencies.
| Leading Market Players |
|---|
| SGS SA |
| Eurofins Scientific |
| Intertek Group plc |
| Bureau Veritas |
| ALS Limited |
| TÜV SÜD |
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Mérieux NutriSciences |
| Others |
Supply & Pricing Matrix
Overcapacity in São Paulo laboratory clusters is compressing margins for PCR-based screening services while simultaneously pushing providers toward premium NGS positioning. This utilization imbalance forces tiered pricing strategies that separate commodity grain exporters from enforcement-grade government contracts.
Pricing Analysis
Price spreads between German and Brazilian testing markets exceed threefold for equivalent PCR panels, reflecting divergent regulatory stringency under EFSA versus ANVISA mandates. Three-tier pricing structure across enforcement-grade, export-certification, and field-screening levels anchors the market, with dual-technology confirmation protocols in Germany commanding substantial premiums. Cost compression in standard PCR screening is intensifying because Brazilian seed cooperatives aggregate volume through block contracting. Agricultural producers in Mato Grosso exhibit highest price sensitivity, whereas DG SANTE-affiliated laboratories face lowest bargaining leverage due to liability exposure.
Supply Chain Analysis
Extended payment terms from commodity traders are forcing reagent suppliers to expand supply-chain finance facilities, particularly for specialty PCR primer inventories. Laboratory instrumentation concentrates in Germany, the United States, and China, while specialty chemistries draw from concentrated biotech suppliers in Switzerland and Singapore. Single-source vulnerability for NGS flow-cell production creates chokepoint risk for unauthorized-event screening capacity. Distribution runs through certified third-party logistics networks with temperature-controlled chain-of-custody documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GMO testing services market is entering a cyclical recovery phase as Brazilian export deadlines and EU traceability mandates synchronize demand waves. This cyclicality stems from harvest-season concentration overlaid with regulatory implementation calendars.
For Market Incumbents: Build regulatory-intimacy moats through multi-jurisdiction certification partnerships that pre-validate methods across USDA, EFSA, and SAMR protocols simultaneously. Incumbents should anchor laboratory networks in Mato Grosso and Paraná to capture Brazilian seed sector overflow, while investing in NGS bioinformatics talent pools that emerging entrants cannot replicate quickly. Substitution risk from portable biosensor platforms demands continuous PCR sensitivity upgrades.
For New Entrants and Emerging Players: Field Testing penetration in India's agricultural export corridors offers the most accessible white-space target, as domestic laboratories lack ISO 17025 accreditation density for EU-bound shipments. New entrants should pursue cooperative sampling arrangements with producer associations to aggregate sufficient volume for tiered pricing access, mirroring Brazilian cooperative models. A go-to-market angle targeting blockchain-enabled chain-of-custody documentation differentiates against incumbent paper-based workflows.
For Investors and Strategic Acquirers: Capital is best deployed toward precision-instrumentation suppliers with captive reagent chemistries, as vertical integration into probe libraries secures margin protection against input volatility. Long-term viability rests on laboratories that bridge farm-level sampling to port-of-entry clearance through integrated digital workflows. The inflection signal to watch is SAMR's pace of NGS platform adoption, which would accelerate replacement demand for legacy PCR infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Certification Partnership | Pre-validated methods across USDA, EFSA, and SAMR protocols reduce redundant testing costs for commodity traders. |
| NGS Platform Migration | Whole-genome approaches compress unauthorized-event detection windows from months to weeks for enforcement agencies. |
| Blockchain Chain-of-Custody Integration | Digital sample tracking differentiates providers serving identity preservation markets with tamper-evident documentation. |
| Cooperative Sampling Aggregation | Producer association block contracts unlock tiered pricing structures previously reserved for multinational exporters. |
| Field Testing Capacity Expansion | Portable diagnostic deployment at point of origin reduces downstream rejection risk for Brazilian seed companies. |
Research Methodology
Desk research of regulatory filing databases, customs trade records, and laboratory accreditation registries preceded structured interviews with PCR platform directors, seed company quality managers, third-party laboratory procurement leads, and DG SANTE enforcement officers. Primary fieldwork across Berlin-Brandenburg, São Paulo, and Shanghai laboratory clusters was cross-validated against USDA GIPSA protocol documentation and ANVISA approval catalogs. Bottom-up service-line revenue estimates were triangulated with top-down market sizing from capital expenditure disclosures.
Assumptions regarding regulatory divergence persistence and NGS cost-curve trajectories were held fixed across baseline scenarios, while Brazilian export volume elasticity and EU zero-tolerance implementation timing were stress-tested. Segmentation modeling spanned service type, technology platform, end-user category, and sample matrix complexity across the projection horizon. CAGRs were derived from fitted growth curves anchored to capacity utilization rates and method-validation timeline compression. Forecast inputs included reagent supplier pricing indices and laboratory technician wage differentials by geography.
Practitioners should monitor SAMR approval catalog updates and EFSA detection-limit guidance revisions for early signals of demand inflection. Forecasts reflect documented assumptions regarding regulatory fragmentation continuity and sequencing platform adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Plasma Feed Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
US Digital PCR Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market