
 Aptamers Market | 2026-2036
Aptamers Market Size, Share, and Industry Trends Forecast 2026-2036
Aptamers Market Intelligence
The rise of venture capital-backed, asset-light research models is fragmenting the competitive landscape previously dominated by large, integrated pharmaceutical firms. This shift enables specialized companies to innovate rapidly. SomaLogic Inc. leverages its large-scale proteomic platform for biomarker discovery. Aptamer Group specializes in custom aptamer development services for research and diagnostic clients. Meanwhile, NOXXON Pharma AG focuses its resources on advancing its clinical-stage therapeutic pipeline.
Aptamers are short, single-stranded nucleic acid or peptide molecules engineered through repeated rounds of in vitro selection, such as SELEX. These synthetic antibodies bind to specific target molecules, such as proteins or small molecules, with high affinity. DNA Aptamers currently lead the market in volume due to their superior chemical stability and lower production cost compared to RNA counterparts. While the Diagnostics segment constitutes the largest application area, Therapeutics is poised for significant expansion.
Regulatory pathways defined by the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) are critical for therapeutic aptamer commercialization. For diagnostic applications, compliance with the EU's Medical Device Regulation (MDR) and similar frameworks in Japan is mandatory. Future success for market participants hinges on navigating the complex intellectual property landscape and securing strategic partnerships for clinical development and commercial scale-up.
Market Dynamics
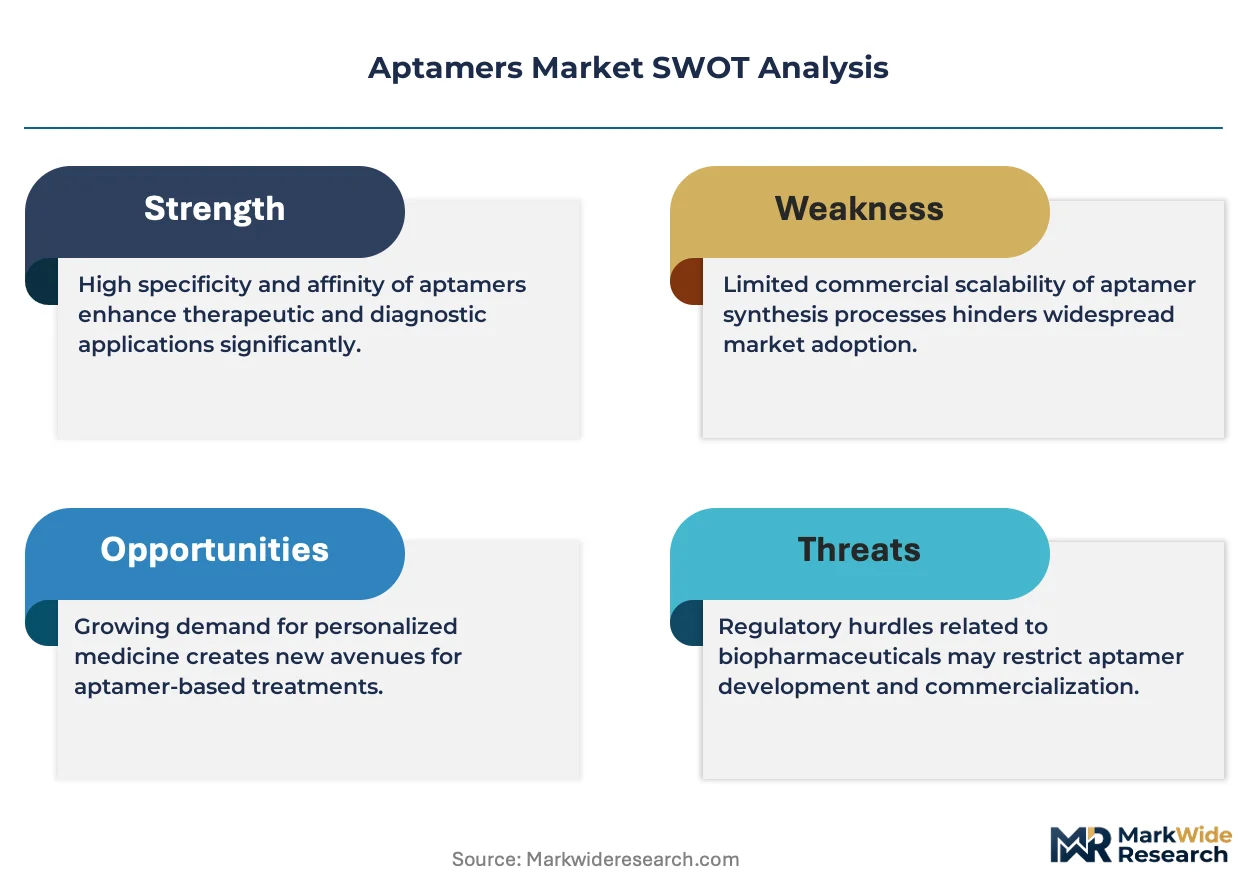
The rapid evolution of SELEX (Systematic Evolution of Ligands by Exponential Enrichment) technology is the central force shaping aptamer development. This advancement shortens discovery timelines and enables a focus on complex therapeutic targets previously considered undruggable by other modalities.
Growth Catalysts
- SELEX Automation:The integration of microfluidics and high-throughput screening into SELEX platforms accelerates the identification of high-affinity aptamers, reducing development costs for therapeutic and diagnostic applications across the biopharmaceutical industry.
- Defined Regulatory Pathways:Clear guidance from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) on oligonucleotide-based therapeutics provides a predictable development process, de-risking investment in clinical-stage aptamer candidates.
- Oncology Drug Development:The persistent need for highly specific, low-immunogenicity targeting agents for cancer therapies drives significant R&D investment into aptamers as alternatives to monoclonal antibodies for drug delivery and direct therapeutic use.
Market Restraints
- Nuclease Degradation:The inherent susceptibility of unmodified aptamers to degradation by nucleases in vivo necessitates complex chemical modifications, which can increase production costs and potentially alter binding affinity or specificity.
- High Synthesis Cost:The expense of synthesizing chemically modified oligonucleotides at the scale required for therapeutic applications remains a significant barrier, limiting their commercial viability primarily to high-value indications compared to small molecule drugs.
- Monoclonal Antibody Dominance:The established manufacturing infrastructure, extensive clinical validation, and deep-rooted market acceptance of monoclonal antibodies create a high barrier to entry for aptamers in many lucrative therapeutic areas.
Strategic Opportunities
- Biosensing and Environmental Monitoring:Aptamers' stability and specificity offer opportunities in developing robust biosensors for detecting pathogens, toxins, and pollutants, an area with less stringent regulatory hurdles than human therapeutics. *Asia-Pacific Research Markets: Expanding biopharmaceutical R&D activities in countries like South Korea and China, supported by government funding, create new markets for custom aptamer development services and diagnostic reagents.
- Aptamer-Drug Conjugates (ApDCs):Combining the targeting precision of aptamers with the cytotoxic payload of small molecule drugs presents an opportunity to create next-generation cancer therapies with improved efficacy and reduced side effects.
Industry Challenges
- Navigating SELEX Patents:The dense and often overlapping intellectual property landscape surrounding SELEX and related selection technologies creates significant legal and licensing challenges for new entrants aiming to develop novel aptamers.
- GMP Production Hurdles:Transitioning from lab-scale synthesis to large-scale, cost-effective Good Manufacturing Practice (GMP) production of therapeutic-grade aptamers presents a major technical and capital-intensive challenge for many firms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aptamers Market |
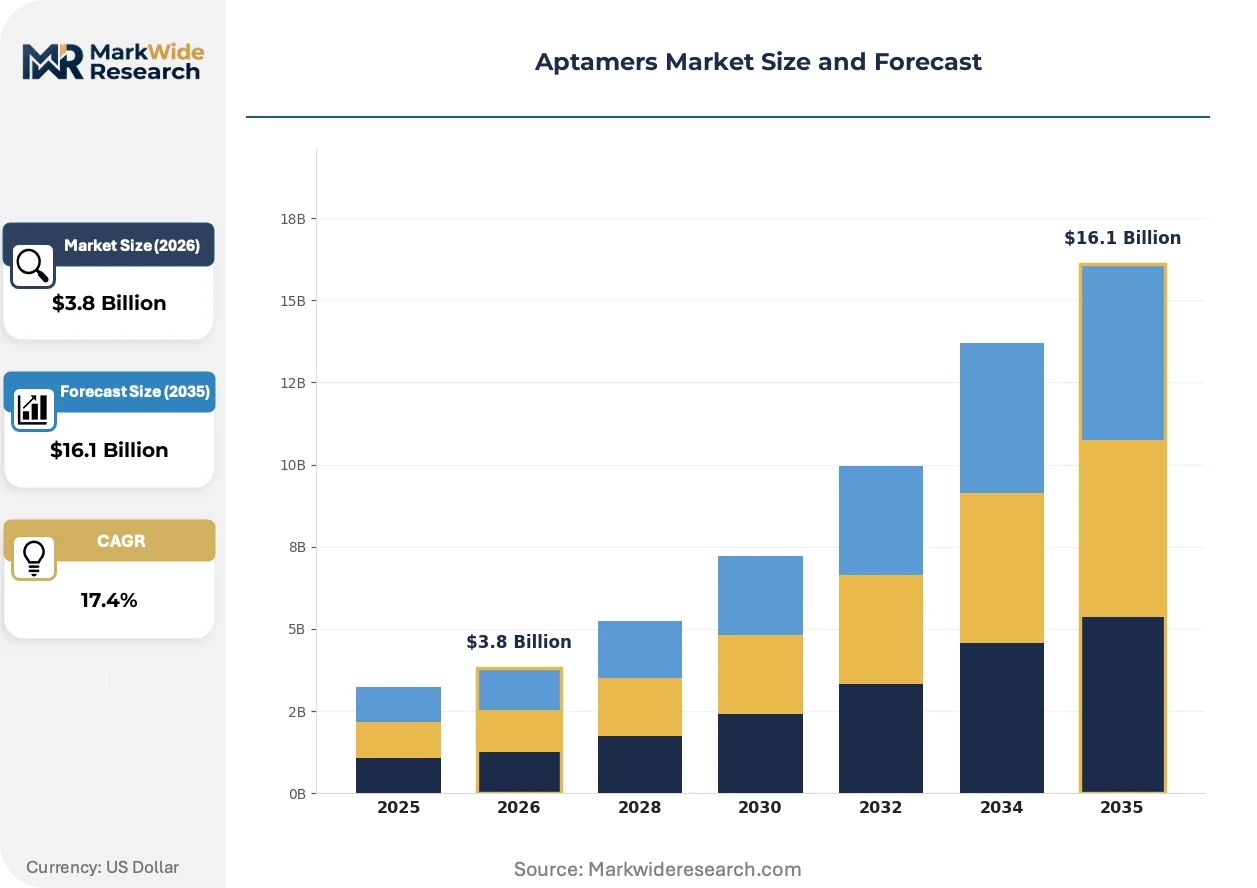
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $16.1 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Aptamers, RNA Aptamers, Peptide Aptamers, Spiegelmers, X-Aptamers Application: Diagnostics, Therapeutics, Drug Delivery, Food Safety Testing, Environmental Monitoring End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutes, Clinical Laboratories, Contract Research Organizations Technology: SELEX, Cell-SELEX, In vitro Selection, Microfluidic SELEX, Capillary Electrophoresis SELEX |
| Companies Covered | SomaLogic Inc., Aptagen LLC, Aptamer Group, Aptamer Sciences Inc., NOXXON Pharma AG, Base Pair Biotechnologies, Aptus Biotech, NeoVentures Biotechnology Inc., Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aptamers Market Strategic Shifts & Innovations
A fundamental shift from aptamers as niche research reagents to validated components in diagnostics and therapeutics is underway. This transition is defined by innovations in molecular engineering and the establishment of clearer commercialization pathways for nucleic acid-based medicines.
Xeno-Nucleic Acid (XNA) aptamers incorporate synthetic nucleotide building blocks to enhance stability and resistance to enzymatic degradation. Therapeutic developers are increasingly adopting XNAs to improve the in vivo half-life and bioavailability of drug candidates. This advancement is rendering obsolete many first-generation unmodified aptamers that suffered from poor stability and required complex formulation strategies.
The European Union's Medical Device Regulation (MDR 2017/745) imposes stricter requirements for clinical evidence and post-market surveillance on diagnostic products. This directly impacts developers of aptamer-based in vitro diagnostics, compelling them to conduct more rigorous validation studies. Diagnostic firms targeting the EU market are now investing more heavily in performance evaluation to meet the elevated compliance standards.
Client engagement models are evolving from transactional, fee-for-service aptamer synthesis to strategic, multi-year partnerships focused on proteomic biomarker discovery. Large biopharmaceutical companies are outsourcing entire discovery and validation workflows to specialized aptamer platform providers. This collaborative procurement model is most prominent within the biopharma ecosystems of the United States and Germany.
Aptamers Market Segmentation
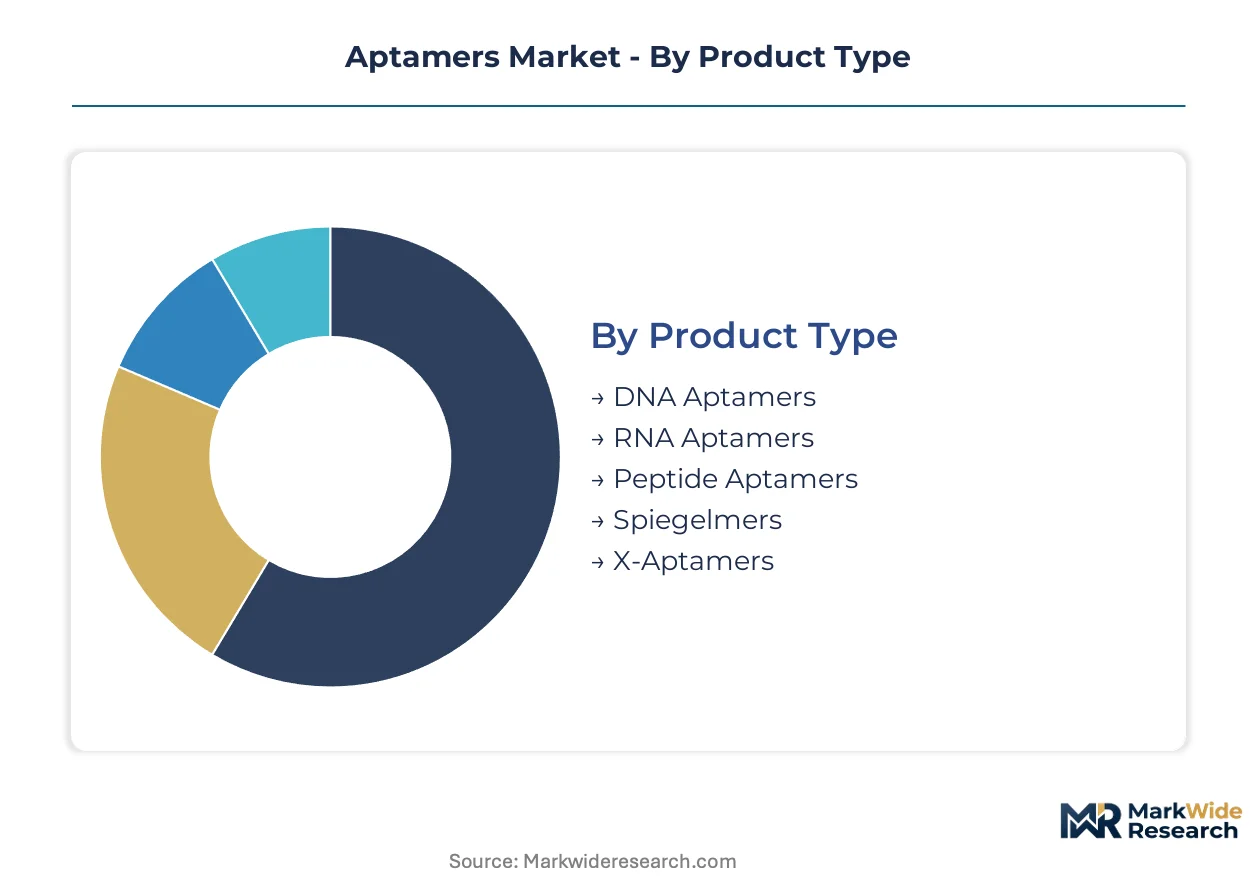
The Aptamers Market segmentation highlights distinct product types, applications, end users, and underlying technologies. This analysis reveals varied growth drivers and adoption patterns across the biopharmaceutical landscape, reflecting unique development cycles and market maturities within each segment.
Product Type:
Product types exhibit varying development cycle times, from established nucleic acid forms to novel synthetics requiring extensive validation.
- DNA Aptamers:These single-stranded DNA molecules offer superior chemical stability and lower production costs, binding targets with high affinity. Demand concentrates in diagnostics and early therapeutic research due to their robust nature.
- X-Aptamers:Xeno-Nucleic Acid aptamers incorporate synthetic nucleotide building blocks, enhancing resistance to enzymatic degradation and improving in vivo half-life. Therapeutic developers adopt XNAs for drug candidates.
- RNA Aptamers:Single-stranded RNA molecules offer high specificity but are susceptible to nuclease degradation, limiting therapeutic use without complex modifications.
- Peptide Aptamers:Composed of short variable peptide sequences constrained by a scaffold protein, these aptamers modulate intracellular protein-protein interactions.
- Spiegelmers:L-enantiomeric RNA or DNA aptamers are highly resistant to nuclease degradation and exhibit low immunogenicity for therapeutic development.
DNA Aptamers dominate the installed base. X-Aptamers are where expansion concentrates for next-generation therapeutics.
Application:
Application segments demonstrate distinct volume concentrations, reflecting varying market maturity and regulatory burdens across end-use areas.
- Diagnostics:Aptamers are used in biosensors and molecular diagnostics for detecting biomarkers or pathogens. Demand concentrates in point-of-care testing and companion diagnostics due to aptamer specificity.
- Therapeutics:Aptamers serve as active pharmaceutical ingredients or targeting agents for drug delivery, treating diseases like cancer. Expansion concentrates in oncology drug development due to specific targeting.
- Drug Delivery:Aptamers target therapeutic agents to diseased cells, minimizing off-target effects and improving drug efficacy.
- Food Safety Testing:Aptamers detect contaminants, allergens, and pathogens in food, offering rapid, sensitive alternatives to traditional methods.
- Environmental Monitoring:Aptamer-based sensors detect pollutants, heavy metals, and toxins in water, soil, and air, providing real-time data.
Market expansion is driven by Therapeutics and Drug Delivery, capitalizing on aptamers' precision targeting.
End User:
End user segments represent diverse customer types with varying procurement models and research priorities for aptamer products.
- Pharmaceutical Companies:These entities invest heavily in aptamer research for drug discovery and novel therapeutic modalities, often seeking partnerships for specialized platforms. Their demand focuses on high-affinity candidates.
- Biotechnology Firms:Specialized firms develop aptamer-based diagnostics, therapeutics, and research tools, leveraging proprietary SELEX technologies. These firms drive innovation in custom aptamer development.
- Research Institutes:Academic and government institutions utilize aptamers as versatile tools for basic scientific discovery and biomarker identification.
- Clinical Laboratories:These laboratories adopt aptamer-based diagnostic assays for disease detection, valuing specificity and integration into existing workflows.
- Contract Research Organizations:CROs provide specialized services for aptamer discovery, optimization, and preclinical testing to support client R&D pipelines.
Pharmaceutical Companies represent the largest customer base, while Biotechnology Firms exhibit the steepest expansion trajectory in specialized service provision.
Technology:
Technology segments showcase different maturity levels, from foundational aptamer selection methods to advanced, automated discovery platforms.
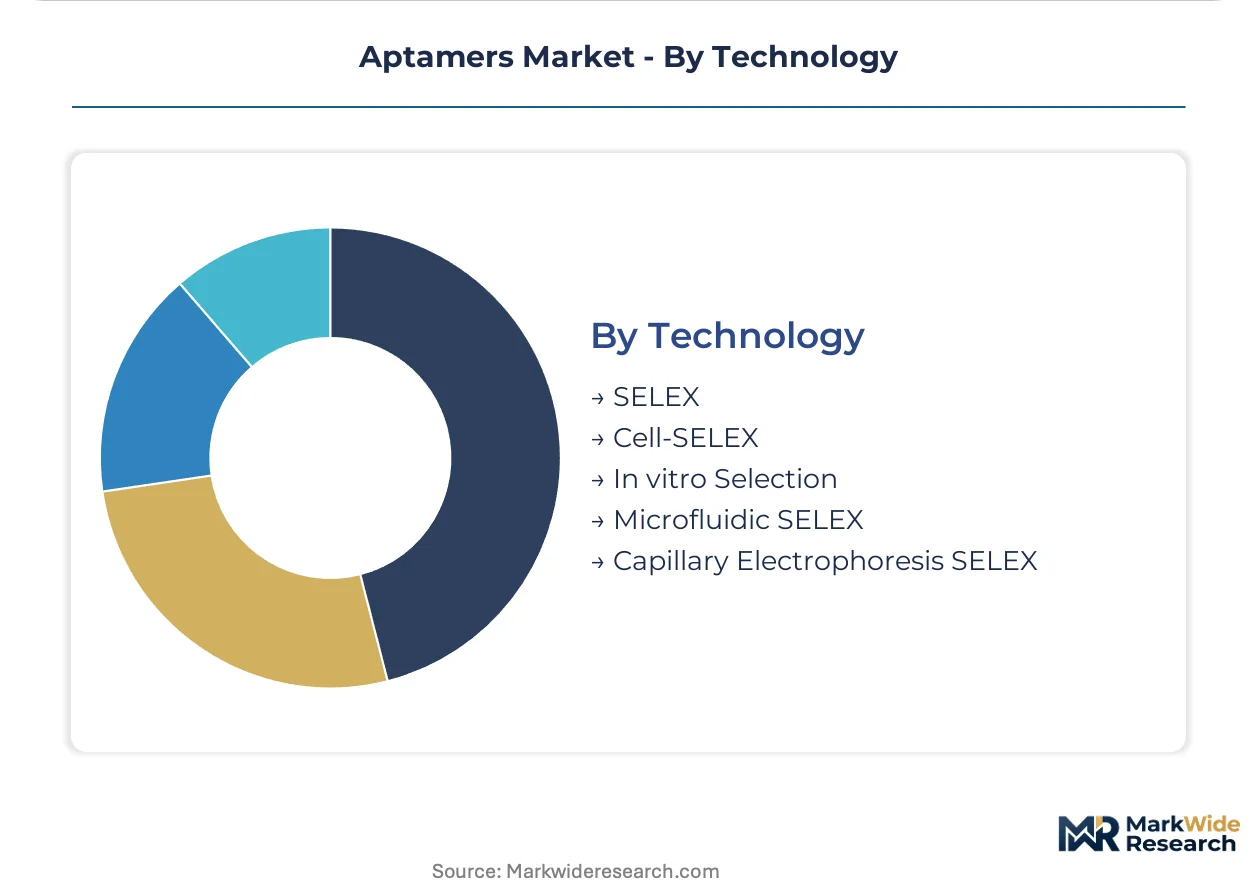
- SELEX:Systematic Evolution of Ligands by Exponential Enrichment is the foundational in vitro selection method for aptamer discovery, identifying high-affinity binders. This core technology continues to evolve with automation.
- Microfluidic SELEX:This advanced variant integrates microfluidic devices to automate and miniaturize aptamer selection, accelerating discovery timelines and reducing sample requirements. Demand concentrates in high-throughput screening.
- Cell-SELEX:This method selects aptamers binding specifically to cell surface targets in native conformation, crucial for cell-specific agents.
- In vitro Selection:A broad term for laboratory-based methods isolating specific aptamers from random oligonucleotide libraries based on binding.
- Capillary Electrophoresis SELEX:This technique uses capillary electrophoresis to separate aptamer-target complexes, offering high resolution and rapid selection cycles.
The foundational technology of SELEX underpins most current aptamer applications, with Microfluidic SELEX and Cell-SELEX enabling next-generation capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clear guidance from the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA) on oligonucleotide-based therapeutics provides a predictable development process. This regulatory clarity de-risks investment in clinical-stage aptamer candidates. Such frameworks are critical for therapeutic aptamer commercialization globally, fostering regional growth.
United States
The United States drives significant demand for aptamers due to its advanced biopharmaceutical research infrastructure and extensive oncology R&D. The US Food and Drug Administration (FDA) provides well-defined pathways for novel drug approvals, encouraging therapeutic innovation. Major biotech clusters in Boston and the San Francisco Bay Area continue to accelerate aptamer discovery and clinical development.
Germany
Germany exhibits strong demand for aptamer technologies, supported by its robust biotechnology and pharmaceutical R&D sectors. The European Medicines Agency (EMA) sets comprehensive regulatory standards for therapeutic aptamers, facilitating market access across the EU. Research hubs in Munich and Heidelberg are actively engaged in aptamer-based diagnostic and therapeutic advancements.
Japan
Japan's demand for aptamers stems from its focus on precision medicine and an aging population requiring advanced diagnostics. The Pharmaceuticals and Medical Devices Agency (PMDA) oversees stringent approval processes for new medical products, ensuring high quality. Major research institutions in Tokyo and Osaka are concentrating on aptamer applications for early disease detection and targeted therapies.
China
China's expanding healthcare market and substantial government investment in biopharmaceutical R&D fuel a growing demand for aptamers. The National Medical Products Administration (NMPA) is streamlining regulatory approvals for innovative drugs, supporting domestic development. Biopharmaceutical parks in Shanghai and Beijing are emerging as key centers for aptamer research and manufacturing.
South Korea
South Korea demonstrates increasing demand for aptamers in advanced diagnostics and personalized medicine applications. The Ministry of Food and Drug Safety (MFDS) provides regulatory oversight for novel medical devices and therapeutics. Biotech startups and research institutes in Seoul are actively developing aptamer-based biosensors and therapeutic candidates.
Aptamers Market Key Industry Players
Channel-controlling players compete with product-specialist players across the Aptamers Market, creating a dynamic competitive environment. The market structure exhibits fragmentation, with numerous smaller firms focusing on niche applications or technology platforms. Strategic archetypes include specialized aptamer discovery service providers, clinical-stage therapeutic developers, and platform technology licensors. Dominant competitive moves involve strategic partnerships for clinical development and technology licensing agreements to expand market reach.
SomaLogic Inc. exemplifies a platform-centric approach, leveraging large-scale proteomic platforms for biomarker discovery services that integrate aptamer technology. These entities often focus on high-throughput screening and data analysis to identify novel targets. Aptamer Group represents a specialized service provider, concentrating on custom aptamer development for diverse research and diagnostic clients globally. Such firms provide tailored solutions, from initial selection to optimization. Meanwhile, NOXXON Pharma AG occupies a position as a clinical-stage therapeutic developer, advancing its pipeline of aptamer-based drug candidates through rigorous trial phases. These companies prioritize regulatory navigation and clinical validation for their proprietary assets.
| Leading Market Players |
|---|
| SomaLogic Inc. |
| Aptagen LLC |
| Aptamer Group |
| Aptamer Sciences Inc. |
| NOXXON Pharma AG |
| Base Pair Biotechnologies |
| Aptus Biotech |
| NeoVentures Biotechnology Inc. |
| Kaneka Corporation |
| Others |
Cost & Logistics Intelligence
Specialized GMP production facilities for aptamers currently face undercapacity, directly influencing supplier investment strategies and maintaining elevated pricing for clinical-stage candidates. This scarcity encourages investment in new manufacturing technologies.
Pricing Analysis
Certification level (GMP-grade for therapeutic use) creates the primary pricing spread, differentiating high-value clinical candidates from research-grade reagents. The market employs a hybrid pricing model, combining project-based fees for custom aptamer development with per-unit transactional pricing for standardized diagnostic components. Pricing pressure stems from increasing automation in SELEX technology, particularly for research applications. Pharmaceutical companies exhibit lower price sensitivity for therapeutic aptamers compared to academic research institutes.
Supply Chain Analysis
Upstream feedstock for aptamer production, primarily high-purity oligonucleotides and specialized chemical modification agents, draws heavily from a concentrated global supplier base. China and the United States anchor the supply of essential chemical intermediates and custom synthesis services. The supply chain faces structural risk from single-source reliance for unique chemical modifications. Distribution runs through direct sales channels from specialized aptamer developers to pharmaceutical companies and academic research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aptamers market requires specialized expertise in large-scale GMP production for modified nucleic acid therapeutics, creating a significant capability gap. This scarcity of advanced manufacturing capacity limits broader commercialization of clinical-stage candidates.
For Market Incumbents:
Harden proprietary manufacturing processes for therapeutic-grade aptamers to mitigate high synthesis costs and reduce reliance on external contract manufacturing organizations. Expand intellectual property portfolios around advanced SELEX technologies and novel aptamer chemical modifications. This strengthens market position against emerging competitors and the established dominance of monoclonal antibodies. Invest in R&D for Xeno-Nucleic Acid (XNA) aptamers to enhance stability and therapeutic efficacy.
For New Entrants and Emerging Players:
Pursue niche applications in biosensing and environmental monitoring, where regulatory hurdles are less stringent than human therapeutics. Target Asia-Pacific research markets for custom aptamer development services, leveraging government funding for biopharmaceutical R&D. Develop proprietary microfluidic SELEX platforms to offer rapid, cost-effective aptamer discovery services. Focus on ApDCs as a high-value entry point into oncology therapeutics.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upward across therapeutic aptamer manufacturing due to GMP production requirements. The market presents a strong 5-10 year viability for precision oncology and advanced diagnostic applications. Identify specialized platform technology providers with robust intellectual property in SELEX automation or XNA aptamers as prime acquisition targets. Successful Phase II/III clinical trial readouts for aptamer-based therapeutics remain a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Accelerates validation of aptamer efficacy and safety for therapeutic applications. |
| GMP Manufacturing Scale-Up | Reduces production costs and ensures supply for commercial therapeutic aptamer products. |
| Strategic Technology Licensing | Expands market reach for proprietary SELEX platforms and novel aptamer chemistries. |
| Aptamer-Drug Conjugate (ApDC) Development | Creates next-generation targeted therapies for oncology with improved specificity. |
| Regulatory Pathway Engagement | Secures clear approval routes with the FDA and EMA for novel aptamer drugs. |
Research Approach
The analysis maps therapeutic aptamers, diagnostic aptamers, and custom aptamer services, each validated through extensive primary interviews with R&D directors and regulatory affairs specialists. This combines insights from clinical trial managers and procurement leads in biopharmaceutical firms. Secondary data sources included FDA filings, EMA submissions, and relevant scientific publications. A robust bottom-up and top-down triangulation approach ensured data consistency.
Assumptions regarding regulatory stability and sustained biopharmaceutical R&D investment were held fixed across the analysis window, while technological advancements were varied. The forecast modeled segmentation dimensions including product type, application, end user, technology, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected market drivers. Key inputs included R&D investment in oncology and anticipated regulatory approval timelines for nucleic acid therapeutics.
Sensitivities concentrate around unforeseen regulatory changes for novel nucleic acid therapies and major shifts in biopharmaceutical R&D priorities. Forecasts reflect documented assumptions, but high synthesis costs and nuclease degradation risks could impact commercial viability. Cross-checking against industry association reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Immunoassays in R & D Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
3D Ready Organoid Expansion Service Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market