
 Bead-Based Flow Cytometry Market | 2026-2036
Bead-Based Flow Cytometry Market Size, Share, and Industry Trends Forecast 2026-2036
Bead-Based Flow Cytometry Market Insights
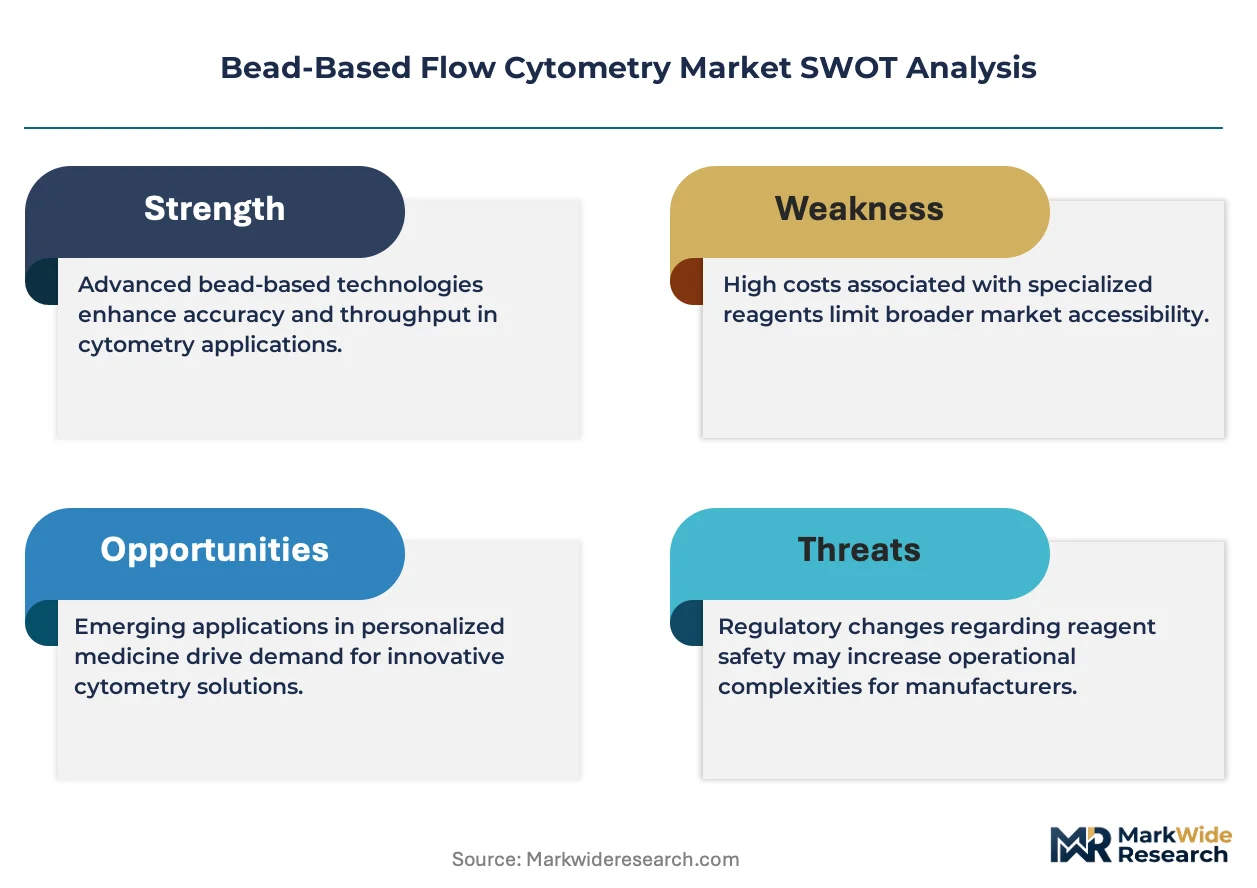
The EU In Vitro Diagnostic Regulation is expanding compliance costs for bead-based flow cytometry manufacturers seeking CE marking in European markets. BD leverages its vertically integrated reagent-instrument ecosystem to sustain pricing power across multiplexing workflows. Bio-Rad Laboratories anchors its position through specialized bead chemistry platforms that dominate immunophenotyping segments in research laboratories. Thermo Fisher Scientific competes by extending its distribution infrastructure into emerging diagnostic markets.
Bead-based flow cytometry employs microsphere populations distinguished by size and fluorescence intensity to enable simultaneous detection of multiple analytes in a single sample, typically resolving 50-500 distinct bead regions through laser excitation at 488 nm and 635 nm wavelengths. The technology serves primarily as a high-throughput analytical platform for quantitative immunoassays in clinical diagnostics and drug development pipelines. Reagents command the largest revenue share within product categories due to recurring purchase cycles tied to assay protocols. Immunophenotyping applications lead clinical adoption while biomarker discovery represents the fastest-expanding segment as pharmaceutical companies integrate multiplexed protein profiling into early-stage screening. Diagnostic laboratories constitute the most concentrated end-user channel, though academic institutes drive instrument innovation through grant-funded technology access programs.
The FDA regulates bead-based flow cytometry systems as Class II medical devices requiring 510(k) premarket notification, while the EMA's In Vitro Diagnostic Regulation mandates performance studies and post-market surveillance for European market access. ISO 13485 certification shapes supplier qualification criteria for diagnostic OEMs seeking integrated bead manufacturing partnerships. Clinical Laboratory Improvement Amendments govern analytical validation standards that directly determine assay menu expansion timelines in US reference laboratories. Stakeholders must monitor evolving harmonization efforts between FDA and EMA guidance documents to anticipate parallel submission requirements that will shape competitive positioning in transatlantic markets.
Market Dynamics
Multiplexing depth expansion is compressing assay timelines across pharmaceutical biomarker discovery pipelines, forcing instrument manufacturers to resolve 500+ bead regions while maintaining clinical-grade precision standards.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation mandates performance studies and post-market surveillance, accelerating replacement cycles for legacy systems in European diagnostic laboratories.
- Immunophenotyping Workload Surge:Academic medical centers are expanding bead-based panels for immune monitoring in cell therapy trials, driving recurring reagent consumption at scale.
- Companion Diagnostic Mandates:FDA guidance on co-developed biomarker assays is embedding multiplexed protein profiling into oncology drug development workflows from Phase I stages.
Market Restraints
- Laser Component Concentration:Solid-state laser supply chains concentrate in German and Japanese specialty optics manufacturers, creating vulnerability to 18-24 month lead times for 488 nm and 635 nm wavelength modules.
- Fluorophore Cost Volatility:Phycoerythrin and allophycocyanin conjugates depend on algal cultivation and marine bioprocessing inputs subject to climate-driven harvest variability.
- Flow Cytometry Substitution:Mass spectrometry-based proteomics platforms are capturing high-plex biomarker discovery contracts previously served by bead-based multiplexing.
Strategic Opportunities
- Point-of-Care Expansion:Miniaturized bead-based readers for cytokine storm monitoring in emergency departments represent an underpenetrated channel beyond centralized reference laboratories.
- ISO 13485 Partnerships:Diagnostic OEMs seek integrated bead manufacturing partners with certified quality systems, creating captive supply arrangements for custom microsphere populations.
- AI-Assisted Gating Convergence:Machine learning algorithms for automated population identification are reducing analysis bottlenecks and enabling technician-independent deployment in resource-limited settings.
Industry Challenges
- Multicolor Panel Design Expertise:Compensation matrix construction for 12+ color experiments requires specialized cytometry knowledge scarce in clinical pathology training programs.
- CLIA Validation Timelines:Analytical validation under Clinical Laboratory Improvement Amendments extends assay menu expansion timelines by 14-18 months for US reference laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bead-Based Flow Cytometry Market |
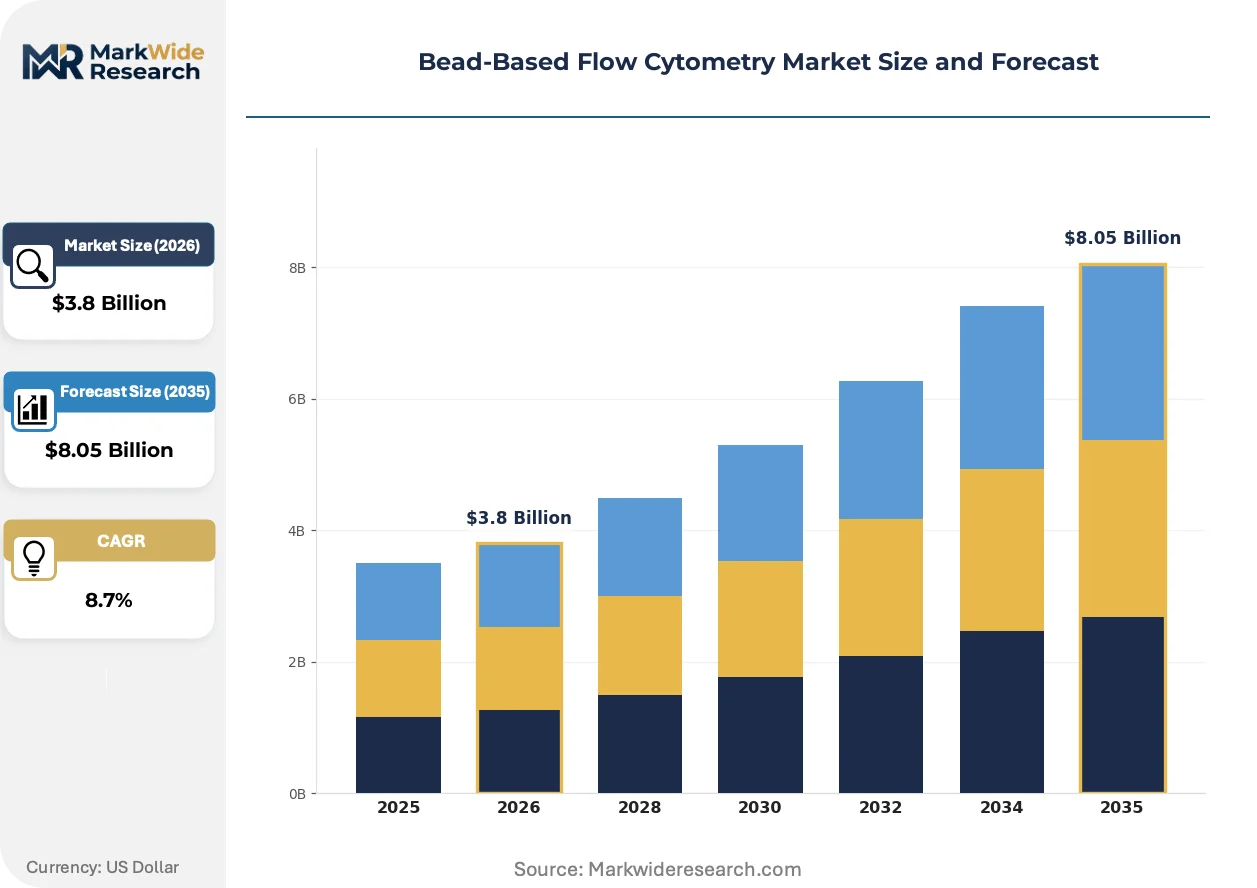
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Instruments, Software, Consumables Application: Cell Analysis, Immunophenotyping, Biomarker Discovery, Drug Development End User: Research Laboratories, Diagnostic Laboratories, Pharmaceutical Companies, Academic Institutes Technology: Multiplexing, Laser Scanning, Microfluidics, Image Acquisition |
| Companies Covered | BD, Bio-Rad Laboratories, Inc., BIOMÉRIEUX, Sony Biotechnology Inc., Merck KGaA, Luminex Corporation, Miltenyi Biotec, Thermo Fisher Scientific Inc., Danaher, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bead-Based Flow Cytometry Market Trends and Innovations
Spectral unmixing algorithms and LED excitation sources are decoupling hardware configurations from traditional laser-wavelength constraints, enabling instrument architectures that diverge from three-decade-old optical designs.
Semiconductor quantum dots with narrow emission profiles and resistance to photobleaching are rewriting fluorophore selection criteria in high-plex panels. Pharmaceutical toxicology groups are adopting Qdot-conjugated bead sets for longitudinal studies requiring extended signal stability. This shift is compressing the performance gap between research-grade flexibility and clinical diagnostic durability.
The EU Medical Device Regulation's classification of multiplex assay software as Class IIa devices is forcing manufacturers to submit algorithm validation packages alongside hardware 510(k) equivalents. European notified bodies are demanding clinical evidence for automated gating algorithms previously cleared as laboratory-developed tests. This regulatory friction is diverting R&D resources toward documentation rather than feature expansion.
Consolidated purchasing by hospital system laboratory networks is displacing independent instrument procurement decisions previously made by individual principal investigators. Academic medical centers in the United States are centralizing cytometry core facilities under single vendor contracts with standardized reagent menus. This concentration is compressing pricing power for specialized bead chemistry suppliers outside preferred vendor lists.
Bead-Based Flow Cytometry Market Segmentation
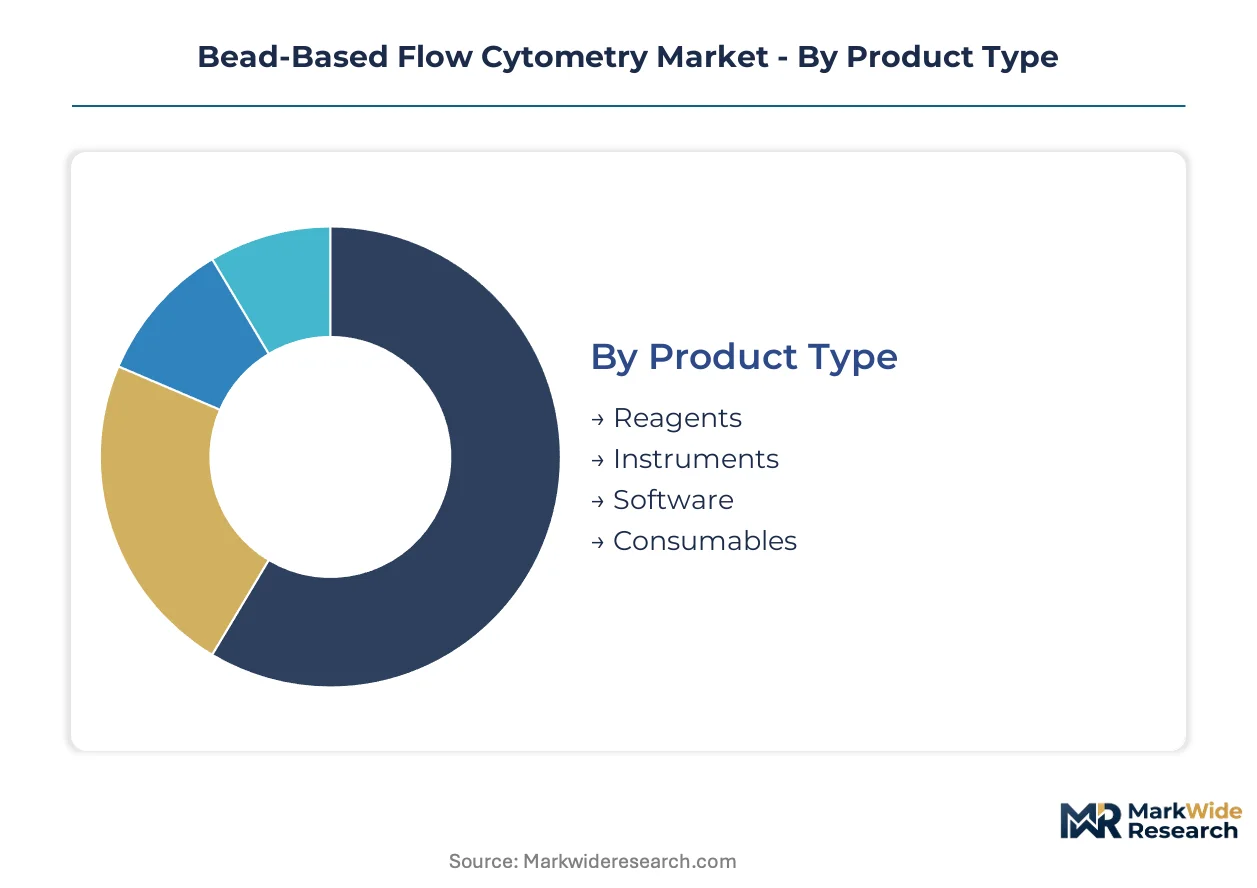
Bead-based flow cytometry exhibits distinct demand patterns across product, application, and end-user dimensions. Procurement priorities vary sharply between research laboratories seeking experimental flexibility and diagnostic facilities requiring regulatory-validated workflows.
Product Type:
Purchasing cycles and margin structures diverge most dramatically between capital equipment and recurring consumables in this category.
- Reagents:Fluorophore-conjugated antibodies and specialized bead populations constitute the largest revenue stream due to protocol-driven replenishment schedules. Diagnostic laboratories in the United States drive concentrated demand as CLIA-validated assay menus expand.
- Instruments:Laser-based detection systems with 488 nm and 635 nm excitation capabilities anchor laboratory infrastructure investments. Academic medical centers prioritize grant-funded instrument placements with multi-user core facility access.
- Software:Population gating algorithms and compensation matrix tools enable automated analysis workflows. FDA scrutiny of algorithm validation packages is extending procurement timelines for clinical deployments.
- Consumables:Sheath fluids, cleaning reagents, and calibration beads support ongoing instrument operations. Pharmaceutical companies maintain strategic inventory buffers to prevent biomarker discovery pipeline interruptions.
Reagents lead volumes today; software is gaining share fastest as automated gating reduces technician dependency.
Application:
Technical complexity and regulatory burden separate clinical diagnostic deployments from exploratory research use cases.
- Immunophenotyping:Multi-parameter lymphocyte subset enumeration dominates clinical adoption with established reimbursement codes. Cell therapy trials at academic medical centers are expanding panel complexity beyond standard 6-color configurations.
- Biomarker Discovery:High-plex protein profiling integrates into pharmaceutical early-stage screening workflows. Mass spectrometry competition is forcing bead-based platforms to demonstrate superior throughput economics.
- Cell Analysis:Apoptosis detection and proliferation assays serve toxicology and basic research applications. Contract research organizations in the United States standardize on vendor-locked bead chemistries for cross-site comparability.
- Drug Development:Pharmacodynamic monitoring and receptor occupancy studies guide dose-escalation decisions. FDA companion diagnostic guidance is embedding multiplexed assays into Phase I oncology protocols.
Immunophenotyping leads volumes today; biomarker discovery is expanding most quickly as pharmaceutical integration deepens.
End User:
Funding mechanisms and decision-making authority create fundamentally different sales cycles across institutional types.
- Diagnostic Laboratories:CLIA-regulated reference laboratories command standardized reagent menus through consolidated purchasing agreements. Hospital system networks in the United States are displacing independent procurement decisions.
- Pharmaceutical Companies:Biomarker discovery groups and clinical trial operations drive multiplexing depth requirements. Toxicology departments are adopting quantum-dot conjugates for longitudinal signal stability.
- Research Laboratories:Principal investigator autonomy supports specialized bead chemistry procurement outside preferred vendor contracts. Grant-funded technology access programs enable instrument innovation.
- Academic Institutes:Cytometry core facilities centralize resource allocation under single-vendor frameworks. Graduate training programs generate sustained demand for educational reagent packages.
Diagnostic laboratories lead volumes today; pharmaceutical companies are climbing the fastest as companion diagnostic mandates expand.
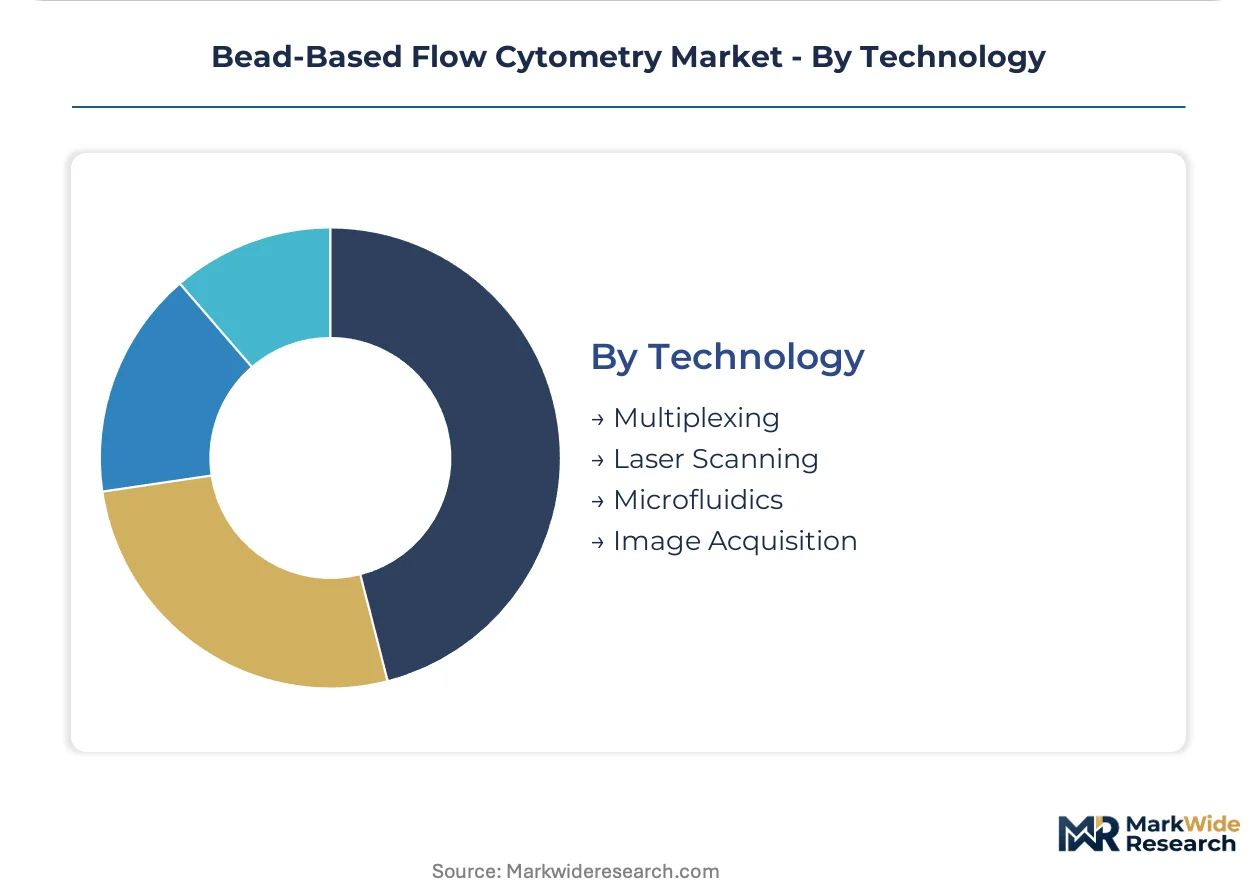
Technology:
Hardware architecture choices determine optical flexibility, throughput ceiling, and regulatory classification complexity.
- Multiplexing:Simultaneous detection of 50-500 bead regions enables high-plex protein quantification. Pharmaceutical toxicology groups demand 500+ region resolution with maintained precision standards.
- Laser Scanning:Solid-state laser excitation at defined wavelengths remains the dominant detection modality. German and Japanese specialty optics manufacturers concentrate supply chains with 18-24 month lead times.
- Microfluidics:Miniaturized fluid handling reduces sample volume requirements for pediatric and precious specimen applications. Point-of-care cytokine storm monitoring represents an underpenetrated deployment channel.
- Image Acquisition:Imaging flow cytometry combines morphometric analysis with traditional fluorescence detection. Spectral unmixing algorithms are decoupling hardware from legacy wavelength constraints.
Laser scanning leads volumes today; microfluidics is advancing most rapidly as miniaturization enables decentralized testing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cytometry technicians and flow cytometry specialists concentrate in the United States, Germany, and Japan, anchoring regional capability clusters that shape instrument deployment and assay development patterns worldwide.
United States
Academic medical centers in Boston and San Diego expand bead-based panels for CAR-T cell therapy monitoring, while reference laboratories in North Carolina and California scale CLIA-validated multiplex menus. FDA companion diagnostic guidance for oncology co-development is embedding protein profiling into Phase I protocols. The Research Triangle Park cluster hosts contract research organizations standardizing on vendor-locked bead chemistries for cross-site comparability.
Germany
Specialty optics manufacturers in Jena and Munich concentrate solid-state laser production for 488 nm and 635 nm wavelength modules, creating 18-24 month lead time vulnerabilities. The EU In Vitro Diagnostic Regulation mandates performance studies and post-market surveillance for CE marking, accelerating replacement cycles in diagnostic laboratories. The Munich biotech corridor anchors immunophenotyping service expansion for European pharmaceutical trials.
Japan
Pharmaceutical toxicology groups in Kobe and Osaka adopt quantum-dot conjugated bead sets for longitudinal signal stability studies. METI funding programs support miniaturized reader development for point-of-care cytokine monitoring. The Kansai biomedical cluster integrates bead-based multiplexing into domestic drug development pipelines with rigorous analytical validation standards.
China
Domestic instrument manufacturers in Suzhou and Shenzhen develop localized bead-based platforms for immunophenotyping applications. NMPA regulatory pathways for Class II medical devices are streamlining 510(k)-equivalent submissions for multiplex assay systems. The Yangtze River Delta biopharma corridor is expanding biomarker discovery infrastructure with grant-funded technology access programs.
United Kingdom
London and Cambridge academic institutes centralize cytometry core facilities under single-vendor contracts with standardized reagent menus. The Medicines and Healthcare products Regulatory Agency alignment with FDA guidance on algorithm validation is extending software procurement timelines. The Golden Triangle research cluster drives instrument innovation through multi-user core facility access models.
Bead-Based Flow Cytometry Market Competitive Landscape
The competitive structure tilts toward vertically integrated conglomerates with captive reagent-instrument ecosystems. Three to five diversified life science conglomerates command pricing power through bundled procurement contracts, while specialized bead chemistry houses defend positions through proprietary microsphere formulations. Mid-scale regional players compete on customized assay development services for pharmaceutical toxicology groups. Dominant competitive moves include strategic partnerships for ISO 13485-certified bead manufacturing and portfolio diversification into point-of-care miniaturization.
Within the integrated conglomerate tier, BD and Thermo Fisher Scientific exemplify archetypes combining instrument platforms with recurring reagent revenue streams. Bio-Rad Laboratories occupies a specialist position anchored in immunophenotyping bead chemistries for research laboratory segments. These three entities represent distinct strategic postures: full-stack vertical integration, distribution infrastructure extension, and specialized chemistry dominance respectively.
| Leading Market Players |
|---|
| BD |
| Bio-Rad Laboratories, Inc. |
| BIOMÉRIEUX |
| Sony Biotechnology Inc. |
| Merck KGaA |
| Luminex Corporation |
| Miltenyi Biotec |
| Thermo Fisher Scientific Inc. |
| Danaher |
| Others |
Pricing and Supply Chain Analysis
Spectral unmixing algorithms and LED excitation sources are decoupling hardware from legacy laser-wavelength constraints, simultaneously compressing manufacturing cost structures for instrument producers while concentrating optical component supply among German and Japanese specialty manufacturers. This technological transition feeds pricing power asymmetries between integrated conglomerates with captive reagent ecosystems and specialized bead chemistry houses dependent on external laser module procurement.
Pricing Analysis
Bundled instrument-reagent contracts dominate enterprise procurement at academic medical centers and hospital system networks, while unbundled reagent-only purchasing persists in research laboratories with principal investigator autonomy. Price differentiation rests on ISO 13485 certification tier and multiplexing depth capability, with CLIA-validated assay menus commanding substantial premiums over research-use-only configurations. Pricing pressure stems from consolidated purchasing by hospital system laboratory networks displacing independent procurement decisions. Diagnostic laboratories exhibit highest price sensitivity due to standardized menu requirements, while pharmaceutical toxicology groups demonstrate lowest sensitivity given longitudinal signal stability demands.
Supply Chain Analysis
Freight cost escalation for temperature-sensitive fluorophore conjugates is amplifying regional sourcing strategies, with algal cultivation facilities in coastal zones and marine bioprocessing inputs subject to climate-driven harvest variability. Solid-state laser production concentrates in Germany and Japan, while specialized bead chemistry manufacturing anchors in the United States. Raw material dependencies encompass phycoerythrin and allophycocyanin conjugates, sheath fluid formulations, and semiconductor quantum dot precursors. Single-source vulnerability pervades 488 nm and 635 nm wavelength module supply. Distribution runs through diagnostic OEM partnerships, direct sales to reference laboratories, and grant-funded academic core facility placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bead-based flow cytometry has matured into a late-cycle quality market where pharmaceutical companion diagnostic mandates and IVDR compliance deadlines are shifting procurement criteria toward validated, premium-grade assay systems. This demand migration favors suppliers with certified quality infrastructure and regulatory documentation depth.
For Market Incumbents: Deepen backward integration into ISO 13485-certified bead manufacturing to secure captive supply arrangements for custom microsphere populations. Fortify algorithm validation documentation capabilities to satisfy FDA and EMA scrutiny of automated gating software as Class IIa medical devices. These moves counter mass spectrometry-based proteomics platforms capturing high-plex biomarker discovery contracts.
For New Entrants and Emerging Players: The premium-economy tier gap in point-of-care miniaturization represents accessible white space, as centralized reference laboratory concentration leaves emergency department cytokine storm monitoring underpenetrated. Target pharmaceutical toxicology departments with quantum-dot conjugate offerings for longitudinal study applications. Pursue strategic partnerships with domestic instrument manufacturers in China and Japan to leverage localized NMPA and PMDA regulatory pathways.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized bead chemistry houses with proprietary microsphere formulations but limited distribution infrastructure. Long-term viability over the next decade hinges on regulatory documentation depth rather than raw multiplexing capability. Acquisition candidates should demonstrate validated algorithm packages and CE marking progress under IVDR. The signal to watch is consolidation velocity among hospital system laboratory networks, which will determine pricing power compression timelines for non-preferred vendors.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Diagnostic OEMs demand certified quality systems for integrated bead manufacturing partnerships under IVDR. |
| Algorithm Validation Documentation | FDA and EMA classification of multiplex assay software as Class IIa devices requires clinical evidence packages. |
| Point-of-Care Miniaturization | METI funding programs in Japan support decentralized cytokine monitoring beyond centralized laboratories. |
| Quantum-Dot Conjugate Development | Pharmaceutical toxicology groups adopt Qdot-conjugated bead sets for extended signal stability in longitudinal studies. |
| Academic Core Facility Partnerships | Grant-funded technology access programs at Boston and San Diego medical centers drive instrument innovation pipelines. |
Research Methodology
Coverage spans the United States, Germany, Japan, China, and the United Kingdom, with primary inputs from each market cluster. The analysis combines structured interviews with cytometry core facility directors, diagnostic laboratory managers, pharmaceutical biomarker discovery leads, regulatory affairs specialists, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA IVDR submission databases, hospital procurement records, and academic grant award repositories. Bottom-up instrument placement and reagent consumption estimates triangulate against top-down market sizing derived from manufacturer revenue disclosures.
Granularity-level modeling disaggregates the analysis window across product type, application, end user, and technology dimensions, with additional segmentation by regulatory validation tier and multiplexing depth capability. CAGRs derive from fitted growth curves applied to base-year estimates, cross-referenced against pharmaceutical pipeline expansion rates and diagnostic laboratory accreditation trends. Forecast inputs incorporate CLIA validation timeline assumptions, IVDR compliance deadline impacts, and companion diagnostic guidance embedding patterns.
Caveats apply where mass spectrometry proteomics platform advancement, solid-state laser supply disruption, or fluorophore harvest variability could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
3D Cell Culture Market
Biomedical Technology
Subcutaneous Biologics Market
Biomedical Technology
Live Cell Analysis System Market
Biomedical Technology
In Vitro Protein Expression Market
Biomedical Technology
Nucleic Acid Isolation, Quantitation, and Purification Market
Biomedical Technology
Mammalian Transient Protein Expression Market
Biomedical Technology
Ligases Enzyme Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Biomarker Detection Systems Market
Biomedical Technology
Cell Disrupters Market
Biomedical Technology
France Flow Cytometry Market
Biomedical Technology
Polymerase Chain Reaction (PCR) Market
Biomedical Technology
Exosomes Market
Biomedical Technology
Cell Tracing and Tracking Test Market
Biomedical Technology
Asia-Pacific Biomedical Sensors Market
Biomedical Technology
DNA Synthesis Market