
 Cell Disruption Market | 2026-2036
Cell Disruption Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Disruption Market Outlook
Specialized distributor networks serving biopharmaceutical equipment is reconfiguring as manufacturers pursue direct relationships with end users. Thermo Fisher Scientific leverages its consumables-recurring-revenue model to lock in long-term instrument placements. Merck KGaA anchors its position through integrated supply chains spanning reagents, systems, and validation services. Bio-Rad Laboratories differentiates via droplet digital PCR adjacencies that create pull-through for sample-prep disruption hardware.
Cell disruption encompasses mechanical, chemical, and physical methods to rupture cell walls and release intracellular biomolecules such as proteins, nucleic acids, and organelles, with operating parameters including pressure ratings up to 30,000 psi and tip speeds exceeding 50 m/s for industrial homogenizers. The technology serves biopharmaceutical upstream processing, diagnostic assay development, and food-grade extract production where yield integrity determines downstream purification economics. Ultrasonic and high-pressure homogenization technologies command premium positioning due to scalability from bench to production bioreactors, while enzymatic methods occupy niche applications requiring gentle membrane preservation. Among end users, contract research organizations represent the fastest-expanding segment as outsourced biologics development shifts capacity planning risk away from sponsor companies.
FDA current Good Manufacturing Practice guidelines and EMA Annex 1 sterile manufacturing revisions shape equipment validation protocols and documentation burdens for cell disruption system suppliers. ISO 13485 quality management requirements and REACH chemical safety registrations further constrain material selection and supplier qualification pathways in Europe. Stakeholders must monitor evolving biosafety classification standards for genetically modified organism handling, as these classifications determine containment specifications that cascade into equipment pressure-boundary and seal-design requirements.
Market Dynamics
Single-use bioprocessing technologies are compressing validation timelines and forcing equipment suppliers to redesign pressure-boundary components for disposable fluid paths, altering how cell disruption systems integrate with upstream bioreactor operations.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:The 2022 update mandates closed-system processing for biologics, driving replacement demand for sealed high-pressure homogenizers across European manufacturing facilities.
- Contract research organization expansion:Outsourced biologics development shifts capacity planning risk away from sponsor companies, accelerating instrument placements at CRO sites in the United States and Germany.
- High-pressure homogenization scalability:Bench-to-production continuity enables platform standardization that reduces process development costs for monoclonal antibody workflows.
Market Restraints
- Stainless steel component cost volatility:Pressure-vessel-grade 316L stainless steel price fluctuations compress margins for fixed-vessel homogenizer manufacturers.
- Seal and gasket supply concentration:Specialized fluoroelastomer seals for 30,000 psi operation source primarily from German and Japanese chemical suppliers, creating single-source vulnerability.
- Enzymatic disruption substitution:Gentle lysis methods preserve membrane protein integrity for certain diagnostic applications, displacing mechanical methods in niche high-value segments.
Strategic Opportunities
- India biopharmaceutical manufacturing:CDSCO production-linked incentive schemes attract global biologics sponsors, creating demand for validated disruption equipment in emerging clusters near Hyderabad and Bengaluru.
- Cell and gene therapy vector production:Viral vector manufacturing requires scalable lysis for downstream purification, opening adjacent demand beyond traditional protein therapeutics.
- Continuous processing integration:Convergence of perfusion bioreactor technology with in-line homogenization enables real-time harvest operations that reduce facility footprint requirements.
Industry Challenges
- Bioprocess engineer talent scarcity:Specialized expertise in scale-up physics for high-shear cell lysis concentrates at established manufacturing clusters, constraining facility expansion timelines.
- ISO 13485 certification duration:Quality management system audits for diagnostic-grade equipment extend supplier qualification cycles by 12-18 months for new market entrants.
- Legacy DCS integration complexity:Digital control system retrofits for existing stainless steel homogenizer fleets require custom protocol bridges that delay automation upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Disruption Market |
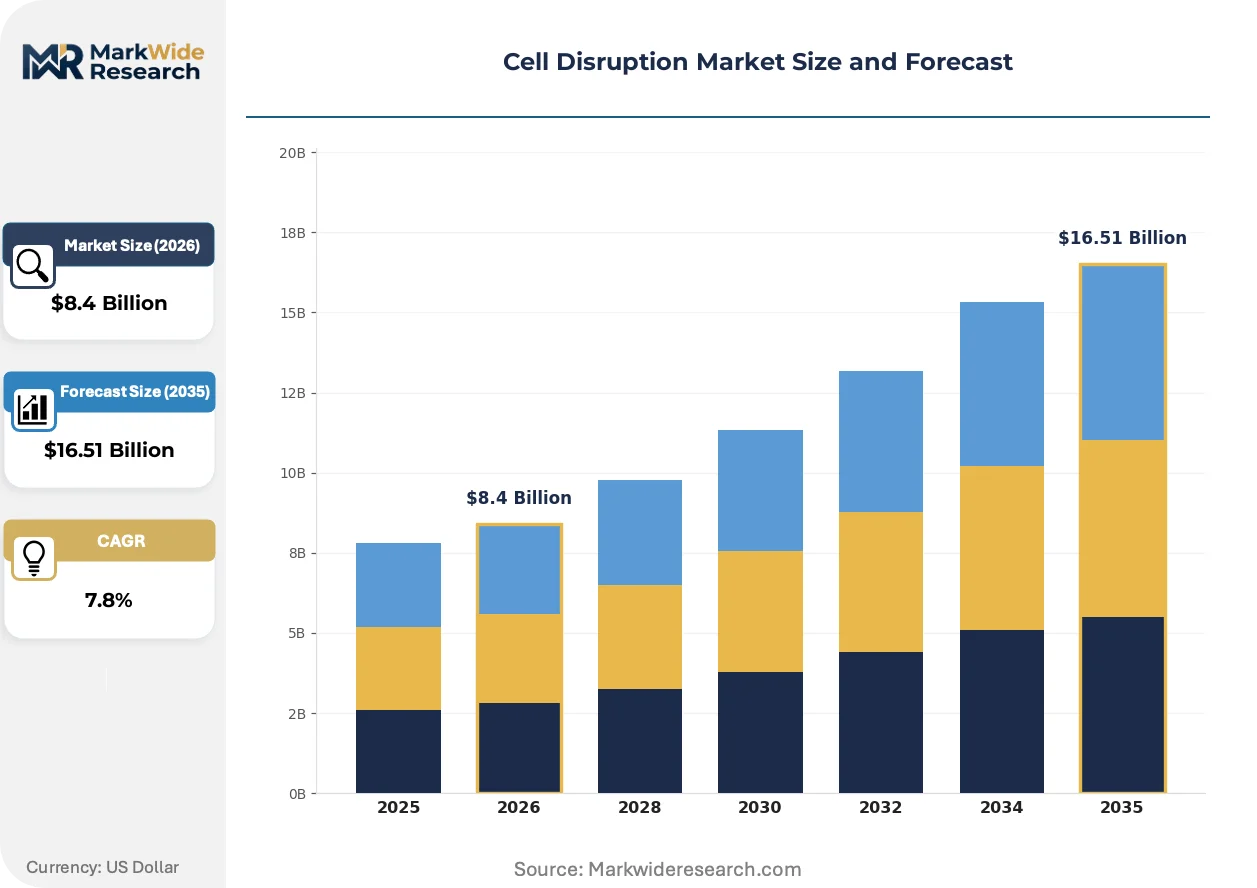
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Mechanical Bead Mill, High-Pressure Homogenization, Enzymatic Application: Biotechnology, Pharmaceutical, Food Processing, Environmental End User: Academic Research Institutes, Pharmaceutical Companies, Food Manufacturers, Contract Research Organizations Product Type: Microfluidizers, Homogenizers, Sonicators, Bead Mills |
| Companies Covered | Thermo Fisher Scientific, Inc., Merck KGaA, Bio-Rad Laboratories, Inc., F. Hoffmann-La Roche Ltd., QIAGEN, Danaher Corporation, Becton Dickinson & Company, Covaris, LLC, Parr Instrument Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Disruption Market Strategic Shifts
Equipment architectures are converging around modularity and data connectivity, with suppliers competing on integration depth rather than standalone performance specifications. This shift rewards platform ecosystems over point-product vendors.
Microfluidic processing technology is migrating from analytical sample preparation into pilot-scale biopharmaceutical manufacturing. CDMOs in Massachusetts and Basel are adopting chip-based disruption for lipid nanoparticle encapsulation workflows. The technology is migrating from bench-scale R&D into GMP environments by compressing process development cycles from months to weeks.
FDA guidance on process analytical technology implementation now requires real-time release testing capabilities for certain biologics license applications. This mandate forces homogenizer suppliers to embed in-line turbidity and particle-size sensors directly into pressure vessels. United States-based manufacturers are responding by pre-qualifying sensor integration packages that reduce customer validation burdens.
Service contract unbundling is fragmenting how end users procure maintenance and consumables. Large biopharmaceutical sponsors in Germany now separate hardware acquisition from validation support and spare parts agreements, treating each as distinct procurement categories. This pattern is most visible among top-twenty global biologics manufacturers with centralized sourcing functions.
Cell Disruption Market Segmentation
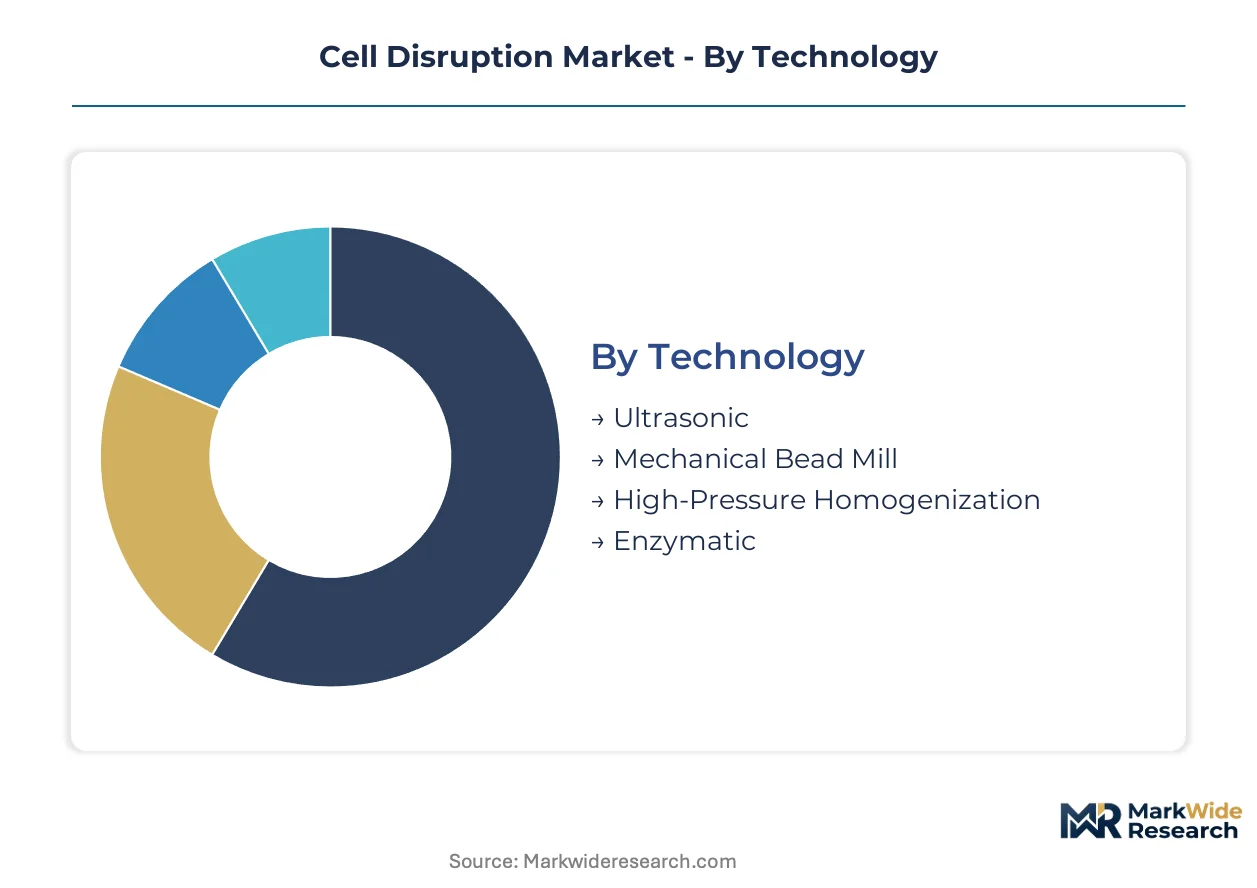
Cell disruption equipment selection hinges on biomolecule sensitivity, throughput requirements, and regulatory compliance pathways. Each segmentation dimension reveals distinct procurement patterns across biopharmaceutical manufacturing, academic research, and industrial processing environments.
Technology:
The use-case spectrum spans gentle enzymatic lysis for membrane protein preservation to aggressive mechanical methods for total cellular destruction.
- High-Pressure Homogenization:Pressure-vessel systems operating up to 30,000 psi achieve scalable lysis for monoclonal antibody production. Demand concentrates at contract manufacturing organizations in Germany and the United States where FDA and EMA validation requirements favor platform standardization across development and commercial stages.
- Ultrasonic:Probe sonicators generate cavitation through high-frequency acoustic energy, excelling at small-volume sample preparation. Academic research institutes in China represent expanding placements driven by government funding for biologics research infrastructure.
- Mechanical Bead Mill:Rotating chambers with grinding beads achieve lysis through shear and collision forces, serving cell culture harvest operations where heat generation remains manageable.
- Enzymatic:Cell wall-degrading enzymes preserve native protein conformations for structural biology applications requiring intact membrane complexes.
Established volume favors High-Pressure Homogenization; emerging adoption favors Ultrasonic as distributed research funding expands instrument access.
Application:
Cost tier differentiation separates GMP-validated pharmaceutical systems from laboratory-grade research equipment and commodity food processing machinery.
- Pharmaceutical:cGMP-compliant systems demand 316L stainless steel construction, clean-in-place protocols, and extensive documentation packages. CDSCO production-linked incentive schemes in India are accelerating validated equipment procurement near Hyderabad and Bengaluru manufacturing clusters.
- Biotechnology:Research-scale instruments prioritize flexibility over validation depth, serving process development and analytical sample preparation workflows.
- Food Processing:High-throughput homogenizers for nutraceutical extraction operate under FSSAI and FDA food safety frameworks with reduced documentation burdens compared to pharmaceutical equivalents.
- Environmental:Cell lysis for biofuel feedstock processing and wastewater microbial analysis employs robust, corrosion-resistant designs for field deployment.
Pharmaceutical applications command premium pricing tiers; biotechnology represents the steepest expansion trajectory as preclinical pipeline volumes climb.
End User:
Customer type determines procurement authority structure, with centralized sourcing functions at large sponsors diverging from principal-investigator-driven academic purchases.
- Contract Research Organizations:Outsourced biologics development shifts capacity planning risk away from sponsor companies, accelerating instrument placements at CRO sites in the United States and Germany where EMA Annex 1 sterile manufacturing revisions mandate closed-system processing.
- Pharmaceutical Companies:Internal manufacturing organizations prioritize platform standardization and long-term service agreements over upfront capital expenditure minimization.
- Academic Research Institutes:Grant-funded procurement favors modular, multi-application instruments with lower per-unit capital requirements.
- Food Manufacturers:Operational expenditure sensitivity drives preference for durable, low-maintenance mechanical systems with minimal consumable dependencies.
Contract Research Organizations are gaining share fastest; Pharmaceutical Companies retain the largest installed base for high-pressure production systems.
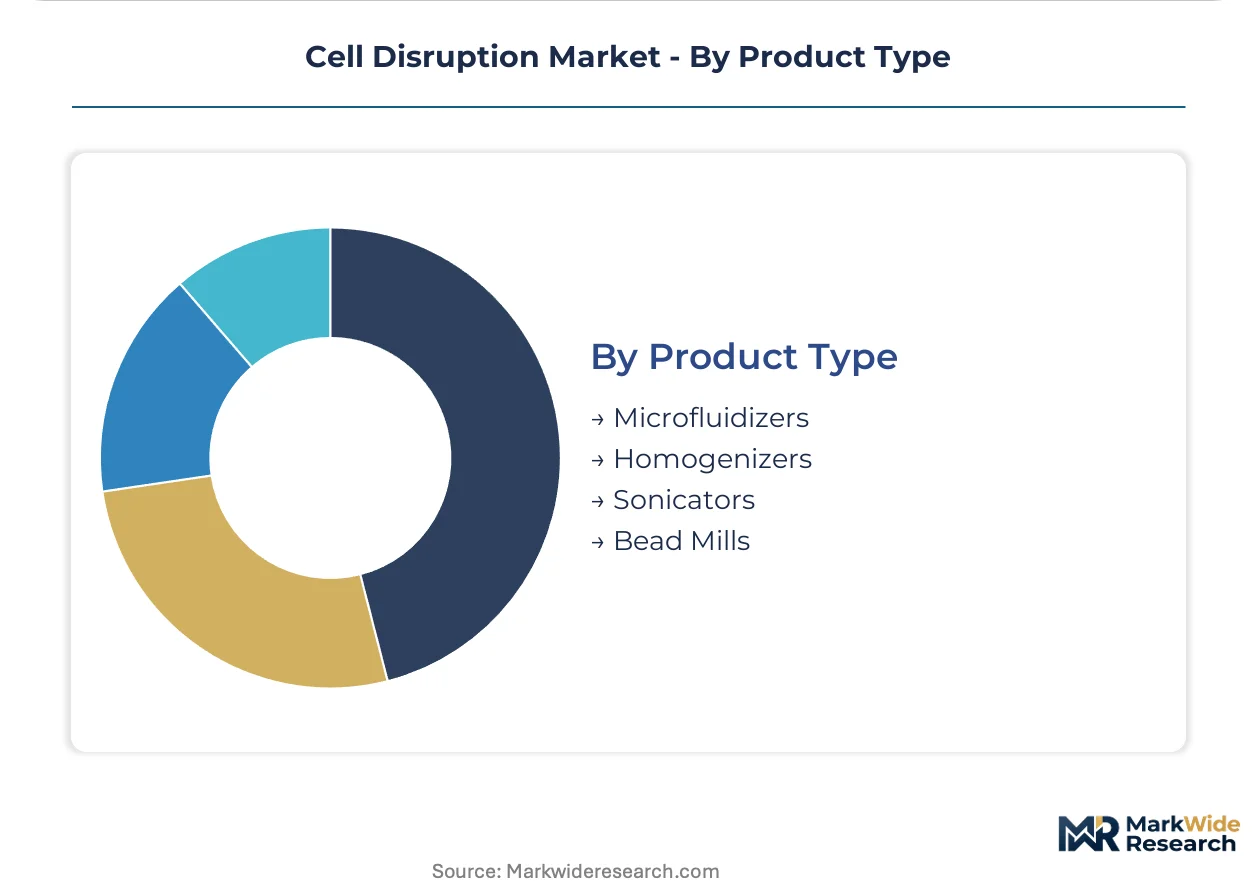
Product Type:
Supply concentration clusters around specialized pressure-vessel fabricators and precision pump manufacturers with ISO 13485 certification.
- Homogenizers:Piston-gap and microfluidic designs dominate biopharmaceutical manufacturing, with validation packages determining competitive positioning.
- Microfluidizers:Fixed-geometry interaction chambers achieve controlled shear for lipid nanoparticle encapsulation, serving cell and gene therapy vector production workflows.
- Sonicators:Probe and bath configurations address sample preparation volumes from microliters to liters, with horn material selection critical for nucleic acid applications.
- Bead Mills:Continuous-flow designs enable high-throughput cell disruption for industrial enzyme production and yeast extract manufacturing.
Homogenizers anchor pharmaceutical revenue; Microfluidizers are climbing the fastest as mRNA and viral vector manufacturing scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA cGMP guidelines anchor the United States as the dominant geography, with EMA Annex 1 sterile manufacturing revisions and CDSCO production-linked incentives shaping procurement across Germany and India respectively.
United States
Contract manufacturing organizations in Massachusetts and North Carolina drive validated equipment procurement for monoclonal antibody production. FDA process analytical technology mandates now require real-time release testing capabilities for biologics license applications. The Greater Boston biotech corridor concentrates microfluidizer placements for lipid nanoparticle encapsulation workflows serving cell and gene therapy vector manufacturing.
Germany
EMA Annex 1 sterile manufacturing revisions mandate closed-system processing, accelerating replacement demand for sealed high-pressure homogenizers across Baden-Württemberg and Bavaria manufacturing clusters. REACH chemical safety registrations constrain fluoroelastomer seal material selection for 30,000 psi operation. The Rhine-Main biopharmaceutical corridor near Frankfurt anchors European demand for platform-standardized disruption systems.
China
Government funding for biologics research infrastructure expands ultrasonic probe sonicator placements at academic institutes in Shanghai and Beijing. NMPA biologics manufacturing standards increasingly align with ICH Q5A viral safety guidelines. The Yangtze River Delta biotech cluster near Suzhou attracts CDMO investments requiring scalable cell disruption equipment for export-oriented production.
India
CDSCO production-linked incentive schemes attract global biologics sponsors, creating demand for validated disruption equipment near Hyderabad and Bengaluru manufacturing clusters. FSSAI food safety frameworks govern nutraceutical extraction applications with reduced documentation burdens compared to pharmaceutical equivalents. The Genome Valley biotech corridor concentrates contract research organization expansion for outsourced biologics development.
Japan
PMDA quality management requirements extend supplier qualification cycles for diagnostic-grade equipment entering the Kanto and Kansai manufacturing regions. METI technology roadmaps emphasize continuous processing integration with perfusion bioreactor operations. The Osaka pharmaceutical cluster drives adoption of in-line homogenization for real-time harvest operations reducing facility footprint requirements.
Cell Disruption Market Competitive Environment
Integrated life science conglomerates and specialized bioprocessing equipment fabricators split the market between platform ecosystems and point-product positioning. Thermo Fisher Scientific leverages consumables-recurring-revenue models to lock in long-term instrument placements, while Merck KGaA anchors through integrated supply chains spanning reagents, systems, and validation services. Three strategic archetypes dominate: diversified conglomerates with consumables pull-through, specialized pressure-vessel fabricators with ISO 13485 certification, and microfluidic technology specialists serving cell and gene therapy adjacencies. Competitive moves concentrate on strategic partnerships for sensor integration packages and geographic expansion into emerging biopharmaceutical manufacturing clusters.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc., Merck KGaA, and Danaher Corporation exemplify platform-ecosystem positioning that rewards integration depth over standalone performance specifications. Among specialized equipment fabricators, Bio-Rad Laboratories Inc. occupies a position defined by droplet digital PCR adjacencies that create pull-through for sample-prep disruption hardware. Covaris LLC represents the microfluidic technology archetype migrating from analytical sample preparation into pilot-scale GMP environments. These company patterns illustrate how equipment architectures converge around modularity and data connectivity, with competitive differentiation shifting toward pre-qualified sensor integration packages that reduce customer validation burdens.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Merck KGaA |
| Bio-Rad Laboratories, Inc. |
| F. Hoffmann-La Roche Ltd. |
| QIAGEN |
| Danaher Corporation |
| Becton Dickinson & Company |
| Covaris, LLC |
| Parr Instrument Company |
| Others |
Value Chain & Pricing Dynamics
The Rhine-Main freight corridor's energy cost dynamics amplify both supply concentration effects and downstream price differentiation for cell disruption equipment, as German pressure-vessel fabricators pass through stainless steel volatility while Asian ultrasonic manufacturers exploit lower logistics exposure.
Pricing Analysis
The customization-premium spread separates configured-to-order high-pressure homogenizers from standard catalog ultrasonic systems by a factor reflecting validation depth and pressure-boundary engineering. Pharmaceutical-grade systems command premium positioning through FDA cGMP and EMA Annex 1 certification tiers, while research-scale instruments compete on capital efficiency. Price compression runs through the mid-tier as contract research organizations unbundle service contracts and drive procurement toward commoditized hardware. Biotechnology end users exhibit highest price sensitivity due to grant-funded capital constraints, whereas pharmaceutical manufacturing organizations prioritize total cost of ownership over upfront expenditure.
Supply Chain Analysis
Export-control regimes limiting microfluidic precision-manufacturing technology flows from Germany and Japan constrain supply diversification for fixed-geometry interaction chambers. Pressure-vessel-grade 316L stainless steel draws from German and Japanese metallurgical suppliers, while specialized fluoroelastomer seals for 30,000 psi operation source primarily from German and Japanese chemical fabricators. Single-source vulnerability in seal and gasket supply creates structural risk exposure. Distribution runs through specialized biopharmaceutical equipment distributors and direct manufacturer relationships with large biologics sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as enzymatic lysis methods displace mechanical disruption in high-value membrane protein applications requiring gentle handling.
For Market Incumbents: Harden platform ecosystem positioning by deepening captive supply of consumables and validation services that lock in instrument placements. Anchor backward integration into pressure-vessel fabrication to buffer 316L stainless steel cost volatility. Counter enzymatic substitution threats through embedded sensor packages that demonstrate real-time process analytical technology compliance for FDA submissions.
For New Entrants and Emerging Players: Pursue white-space opportunities in India's CDSCO production-linked incentive corridors near Hyderabad and Bengaluru, where validated equipment demand outpaces established supplier presence. Target cell and gene therapy vector manufacturing workflows for microfluidizer placements, as lipid nanoparticle encapsulation expertise concentrates at Massachusetts and Basel CDMOs. Differentiate through pre-qualified sensor integration packages that compress customer validation timelines.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core bioprocessing equipment divisions. Long-term viability hinges on platform ecosystem depth rather than standalone hardware performance. Monitor FDA process analytical technology guidance expansion as the inflection signal indicating which sensor-integrated suppliers will capture biologics license application pull-through.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | FDA process analytical technology mandates force embedded turbidity and particle-size sensor pre-qualification. |
| Single-Use Fluid Path Redesign | EMA Annex 1 sterile manufacturing revisions compress validation timelines for disposable pressure-boundary components. |
| India Manufacturing Cluster Expansion | CDSCO production-linked incentive schemes attract global biologics sponsors requiring validated disruption equipment. |
| Continuous Processing Convergence | Perfusion bioreactor integration with in-line homogenization enables real-time harvest operations reducing facility footprints. |
| Service Contract Unbundling Response | German top-twenty biologics manufacturers now separate hardware acquisition from validation support and spare parts procurement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with bioprocess engineers, regulatory affairs specialists at contract manufacturing organizations, procurement directors at pharmaceutical sponsors, and aftermarket service heads at equipment distributors. Secondary validation drew from FDA biologics license application filings, EMA Annex 1 revision documentation, CDSCO production-linked incentive scheme disclosures, and ISO 13485 certification registries. Bottom-up instrument placement data triangulated against top-down biopharmaceutical manufacturing capacity expansion announcements.
Calibration against historical validation cycle durations and replacement demand patterns from EMA Annex 1 sterile manufacturing revisions anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include technology type, application tier, end-user category, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted adoption curves incorporating biologics pipeline volumes and outsourced development shifts. Industry-specific inputs encompassed stainless steel price indices and fluoroelastomer seal supply lead times.
The forecast holds incumbent behavior within observed patterns; aggressive moves by enzymatic lysis technology developers or microfluidic precision-manufacturing entrants would shift outcomes. Material shifts in FDA process analytical technology implementation scope or REACH chemical safety registration expansions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Cell Separation Bead Market
Biotechnology Equipment
Cellbag Bioreactor Chambers Market
Biotechnology Equipment
Single-Use Bioprocess Sensor Calibration and Validation Test Systems Market
Biotechnology Equipment
Cellular Localization Kits Market
Biotechnology Equipment
Global Single-Use Bioreactor Market
Biotechnology Equipment
Tissue Processor Equipment Market
Biotechnology Equipment
Global Biotechnology Instruments Market
Biotechnology Equipment
Measurement Technologies in Downstream Processing Market
Biotechnology Equipment
ELISA POT Assay Kits Market
Biotechnology Equipment
Rocking Bioreactors Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Plasmid Kits Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Single Use Bioprocessing Market
Biotechnology Equipment
Qpcr Instruments Market
Biotechnology Equipment
Middle East and Africa Transfection Reagent and Equipment Market