
 Spain Specialty Enzymes Market | 2026-2036
Spain Specialty Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Specialty Enzymes Market Insights
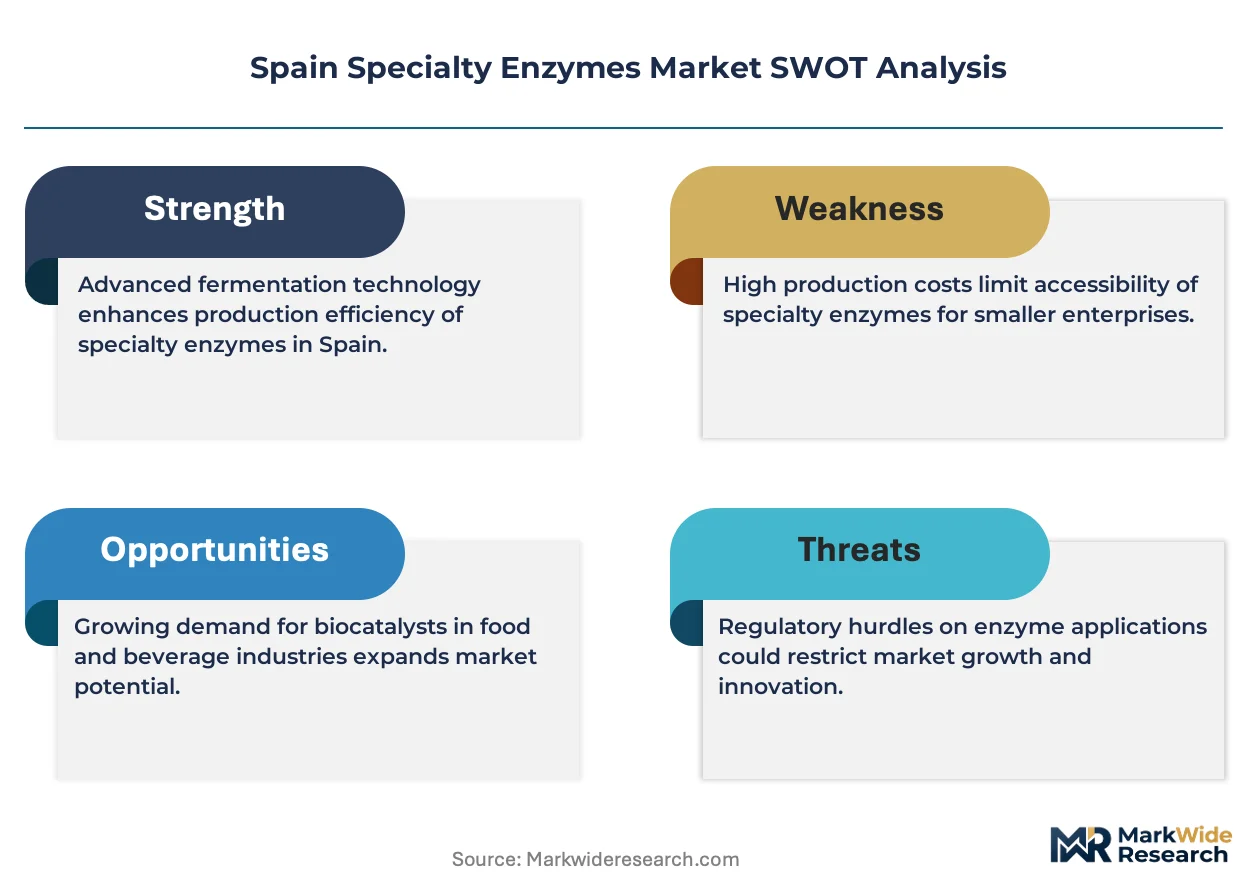
The Spain specialty enzymes landscape is rebalancing between pharmaceutical-grade biocatalysts and commodity food-processing enzymes as margin pools diverge sharply. Novonesis AS leverages its fermentation technology leadership to dominate high-purity pharmaceutical applications. BASF anchors its position through backward integration into proprietary recombinant strain development. DSM differentiates by occupying the premium immobilized enzyme tier for continuous manufacturing processes.
Specialty enzymes are protein-based biocatalysts engineered for specific substrate conversion under controlled temperature and pH conditions, typically manufactured through submerged fermentation of genetically optimized microbial strains. Their primary commercial purpose is to enable selective chemical transformations that reduce energy input and solvent waste in pharmaceutical, food, and biofuel production. Proteases lead application revenue in pharmaceutical manufacturing where enantioselective synthesis commands premium pricing. Recombinant DNA technology represents the fastest-expanding technology segment as Spanish biotech facilities adopt CRISPR-optimized production strains. Immobilization techniques sustain mature margins in beverage production where enzyme recovery and reuse cycles determine unit economics.
Spain's national pharmaceutical regulator and the European Medicines Agency enforce Good Manufacturing Practice standards that mandate documented enzyme purity and traceability for drug applications. The European Chemicals Agency's REACH framework shapes market access by requiring toxicity dossiers for novel biocatalytic intermediates. Stakeholders must monitor evolving EMA guidance on biosimilar manufacturing enzymes and anticipate how Spain's transposition of the EU Green Deal industrial emissions rules will reshape fermentation facility permitting.
Market Dynamics
Spain's specialty enzymes sector is rebalancing around pharmaceutical-grade biocatalytic demand as Madrid and Barcelona manufacturers scale enzyme procurement for active pharmaceutical ingredient synthesis. This structural shift concentrates margin capture in certified high-purity grades while compressing commodity food-processing enzyme returns.
Growth Catalysts
- EMA GMP enforcement:Documented enzyme purity and traceability mandates for drug applications favor certified specialty grades over commodity alternatives, tightening procurement standards across Catalonia's biotechnology corridor.
- CRISPR-optimized production strains:Recombinant DNA technology adoption accelerates as Spanish biotech facilities deploy gene-edited microbial platforms for enhanced catalytic efficiency.
- Basque Country industrial cluster:Concentrated enzyme manufacturing infrastructure supports backward integration into proprietary strain development and captive fermentation capacity.
Market Restraints
- Fermentation feedstock volatility:Corn syrup and yeast extract price swings compress margins for submerged fermentation processes dependent on agricultural commodity inputs.
- Single-source supplier concentration:Immobilized enzyme matrices for continuous manufacturing rely on limited German and Dutch specialty chemical suppliers, creating input bottlenecks.
- REACH toxicity dossier requirements:ECHA's novel biocatalytic intermediate registration demands extensive safety data, extending time-to-market for new enzyme variants.
Strategic Opportunities
- Andalusia biotech expansion:Underdeveloped southern regions offer greenfield fermentation facility sites with favorable permitting timelines compared to saturated Catalonia infrastructure.
- EU Green Deal industrial emissions rules:Spain's transposition of fermentation facility emission standards creates first-mover advantage for carbon-capture-integrated enzyme production.
- Continuous manufacturing adoption:Pharmaceutical producers in Barcelona are retrofitting batch synthesis lines with immobilized enzyme flow reactors, opening premium service contracts.
Industry Challenges
- CRISPR strain engineering talent scarcity:Spanish universities produce insufficient metabolic engineering PhDs to staff expanding biotech R&D facilities in Madrid and Barcelona.
- EMA biosimilar manufacturing enzyme guidance uncertainty:Pending regulatory clarity on enzyme interchangeability in generic drug production delays capital commitment to dedicated biocatalytic lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Specialty Enzymes Market |
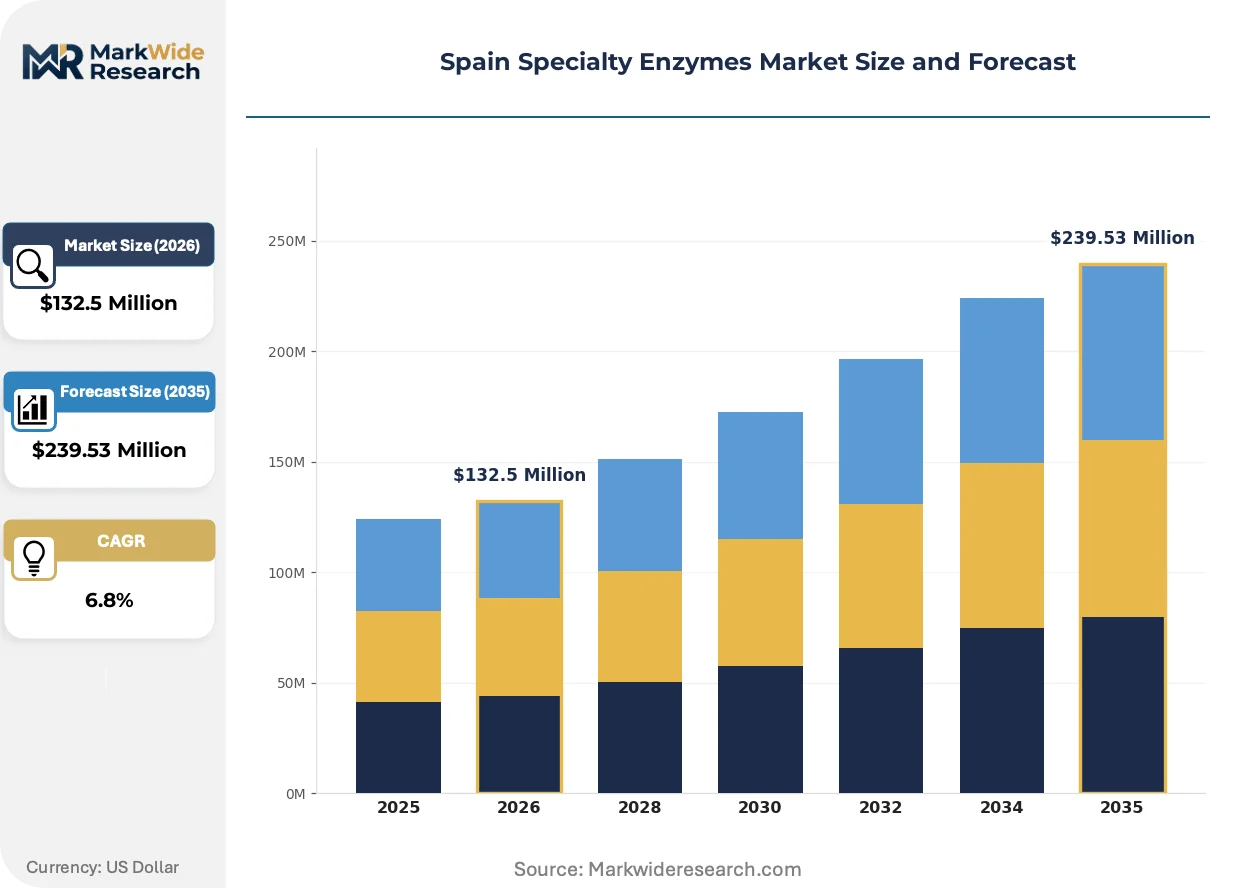
| Market Size in 2026 | $132.5 Million |
| Market Size in 2035 | $239.53 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylases, Proteases, Lipases, Cellulases Application: Beverage Production, Food Processing, Pharmaceutical Manufacturing, Biotechnology End User: Food & Beverage Industry, Pharmaceuticals, Animal Feed Manufacturers, Bioenergy Sector Technology: Recombinant DNA Technology, Fermentation Technology, Biocatalysis, Immobilization Techniques |
| Companies Covered | Novonesis AS, BASF, DuPont de Nemours Inc, DSM, Chr. Hansen, Lesaffre, Advanced Enzymes, Bluestar Adisseo Co., Novus Holdings Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Specialty Enzymes Market Trends and Innovations
Biocatalytic process integration is actively displacing traditional chemical synthesis in Spanish pharmaceutical manufacturing, driven by solvent waste reduction mandates and energy efficiency targets. This technological pivot reshapes enzyme specification requirements and supplier qualification protocols.
Computational enzyme design is converging with directed evolution workflows to accelerate novel biocatalyst discovery. Barcelona-based contract research organizations deploy machine learning models to predict substrate specificity, compressing strain optimization cycles from months to weeks. Pharmaceutical manufacturers in Madrid are integrating these predictive platforms into early-stage drug development, reducing reliance on empirical screening and enabling customized enzyme engineering for complex chiral intermediates.
Spain's transposition of the EU Green Deal industrial emissions framework is tightening fermentation facility permitting requirements. The national environmental regulator now mandates carbon intensity disclosures for enzyme production sites exceeding 500 kiloton annual capacity. Catalonia's biotechnology corridor faces retrofit deadlines for anaerobic digestion waste treatment systems, while Basque Country facilities pursue biogas capture integration to maintain operating licenses under the revised rules.
Buyer consolidation among Madrid and Barcelona pharmaceutical manufacturers is compressing supplier negotiation cycles and unbundling technical service contracts from enzyme supply agreements. Large-scale biocatalytic drug producers now separate process optimization consulting from bulk enzyme procurement, forcing specialty enzyme vendors to compete on standalone product performance metrics. This disaggregation is most pronounced among generic drug manufacturers seeking to reduce total cost of ownership through direct enzyme sourcing without bundled technical support.
Spain Specialty Enzymes Market Segmentation
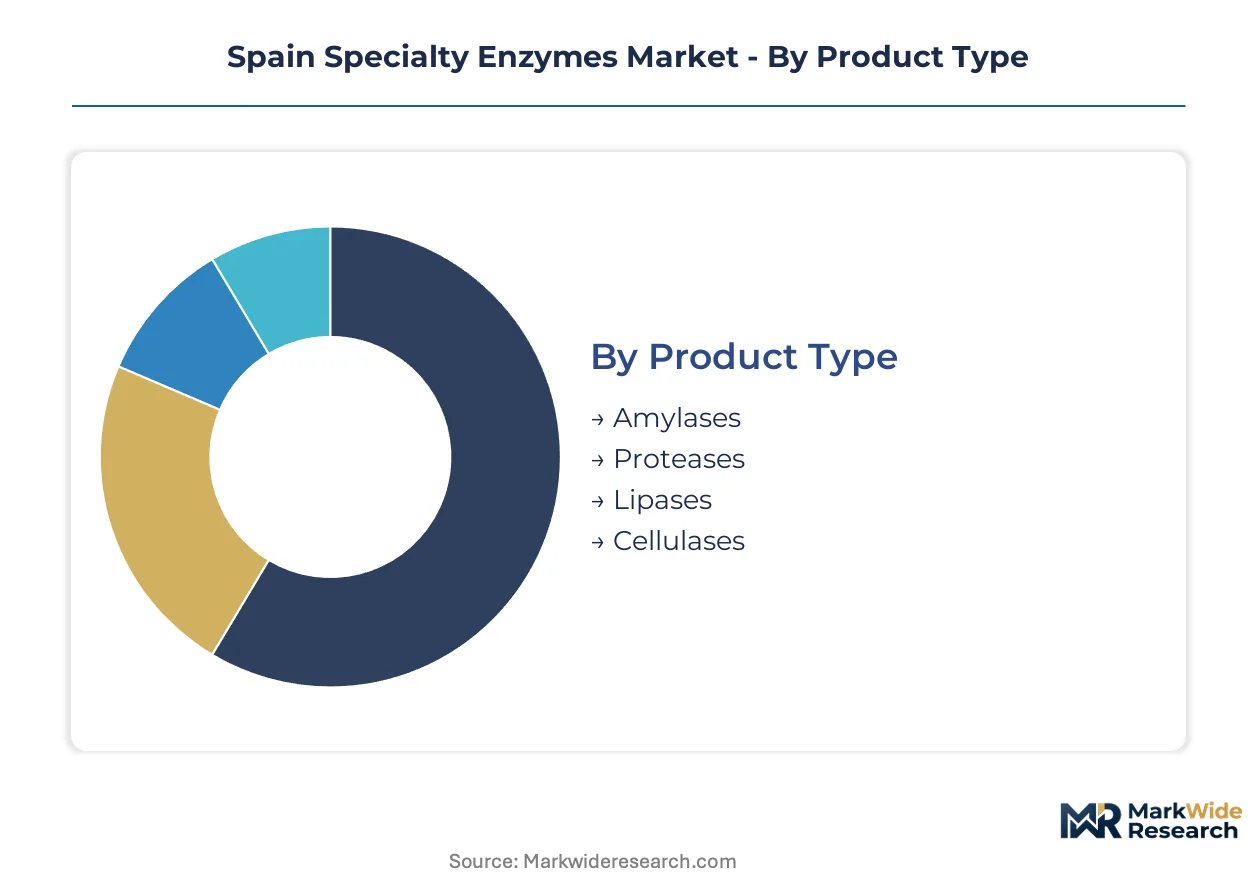
Specialty enzyme procurement in Spain stratifies sharply across purity grades, application protocols, and regulatory compliance tiers. Understanding these segment boundaries reveals where margin pools concentrate and which technology investments command strategic priority.
Product Type:
Capital intensity varies dramatically across enzyme classes, with pharmaceutical-grade biocatalysts requiring multi-million-euro fermentation infrastructure while commodity food-grade enzymes deploy standardized equipment.
- Proteases:These protein-cleaving enzymes dominate pharmaceutical manufacturing specifications in Madrid and Barcelona, where enantioselective synthesis commands premium pricing. EMA GMP certification requirements for drug applications enforce documented purity and traceability that commodity grades cannot satisfy.
- Amylases:Starch-degrading enzymes anchor beverage production in Catalonia's biotechnology corridor, where enzyme recovery and reuse cycles determine unit economics. Immobilization techniques sustain mature margins as Basque Country facilities optimize continuous manufacturing throughput.
- Lipases:Fat-modifying enzymes serve niche pharmaceutical intermediate synthesis and specialty food applications.
- Cellulases:Cellulose-breaking enzymes find limited deployment in Spanish bioenergy preprocessing and research-scale biorefinery pilots.
Proteases absorb the bulk of installed capacity; amylases are expanding most quickly in beverage sector retrofit contracts.
Application:
Customer procurement patterns diverge between process-integrated continuous manufacturing and batch synthesis operations.
- Pharmaceutical Manufacturing:Biocatalytic drug synthesis in Madrid and Barcelona facilities demands certified high-purity grades with full regulatory documentation. CRISPR-optimized production strains accelerate adoption as manufacturers scale enzyme procurement for active pharmaceutical ingredient synthesis.
- Beverage Production:Wine and beer processing in La Rioja and Catalonia relies on immobilized enzyme matrices for flow reactor applications. Spanish producers separate technical service contracts from bulk procurement, compressing supplier negotiation cycles.
- Food Processing:Bakery and dairy applications in Valencia and Galicia operate on volume-driven specifications with thinner margins.
- Biotechnology:Research-grade enzyme supply supports Barcelona-based contract research organizations and university laboratories.
Pharmaceutical manufacturing captures the steepest margin expansion; beverage production offers the most predictable volume throughput.
End User:
Buyer consolidation trends reshape contract structures differently across sector concentration levels.
- Pharmaceuticals:Large-scale biocatalytic drug producers in Madrid and Barcelona unbundle technical service contracts from enzyme supply agreements. Generic drug manufacturers now source directly without bundled process optimization consulting to reduce total cost of ownership.
- Food & Beverage Industry:Consolidated beverage conglomerates in Catalonia negotiate centralized procurement for multiple production sites.
- Animal Feed Manufacturers:Extremadura and Castile-La Mancha operations deploy phytase and carbohydrase blends for livestock nutrition optimization.
- Bioenergy Sector:Emerging cellulosic ethanol pilots in Andalusia test enzyme loading rates for agricultural residue conversion.
Pharmaceuticals concentrate the highest-value contracts; animal feed manufacturers represent the most price-sensitive volume segment.
Technology:
Intellectual property intensity and talent scarcity differentiate competitive positioning across production platforms.
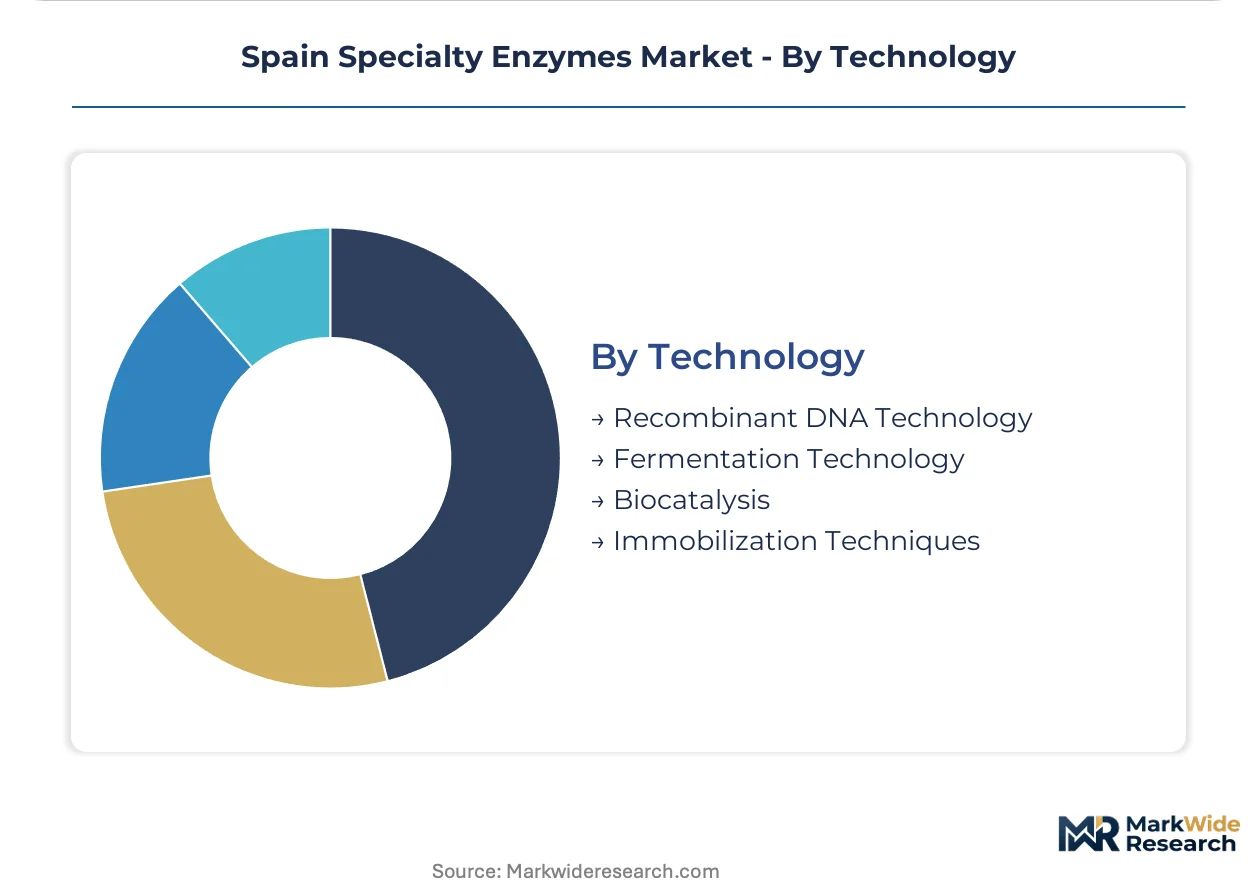
- Recombinant DNA Technology:CRISPR-optimized microbial strains command the steepest R&D investment but deliver enhanced catalytic efficiency. Spanish universities produce insufficient metabolic engineering PhDs to staff expanding Madrid and Barcelona biotech R&D facilities.
- Immobilization Techniques:Enzyme recovery and reuse systems for continuous manufacturing rely on limited German and Dutch specialty chemical suppliers, creating input bottlenecks.
- Fermentation Technology:Submerged fermentation processes in the Basque Country industrial cluster depend on corn syrup and yeast extract feedstocks vulnerable to agricultural commodity price swings.
- Biocatalysis:Process integration expertise separates qualified pharmaceutical suppliers from commodity enzyme vendors.
Recombinant DNA technology attracts the most venture capital deployment; immobilization techniques sustain the most defensible incumbent margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia's biotechnology corridor anchors Spain's specialty enzyme demand, with Barcelona facilities driving pharmaceutical-grade biocatalyst procurement. Madrid's pharmaceutical manufacturers scale enzyme sourcing for active pharmaceutical ingredient synthesis. Regional concentration spans industrial clusters in the Basque Country, emerging biotech infrastructure in Andalusia, and consolidated food-processing operations across Valencia.
Catalonia
Barcelona-based pharmaceutical manufacturers deploy CRISPR-optimized production strains for enantioselective drug synthesis. The European Medicines Agency enforces Good Manufacturing Practice standards that mandate documented enzyme purity and traceability. The biotechnology corridor concentrates immobilized enzyme flow reactor installations as facilities retrofit batch synthesis lines.
Madrid
Large-scale biocatalytic drug producers unbundle technical service contracts from enzyme supply agreements to reduce total cost of ownership. Spain's national pharmaceutical regulator enforces strict purity standards that favor certified specialty grades. The metropolitan area hosts expanding biotech R&D facilities facing metabolic engineering PhD talent scarcity.
Basque Country
Industrial enzyme manufacturing infrastructure supports backward integration into proprietary recombinant strain development. The European Chemicals Agency's REACH framework requires toxicity dossiers for novel biocatalytic intermediates. Captive fermentation capacity concentrates in this northern cluster as facilities pursue biogas capture integration.
Andalusia
Underdeveloped southern regions offer greenfield fermentation facility sites with favorable permitting timelines. Spain's transposition of the EU Green Deal industrial emissions rules mandates carbon intensity disclosures for large production sites. Emerging cellulosic ethanol pilots test enzyme loading rates for agricultural residue conversion.
Valencia
Food-processing operations in bakery and dairy applications operate on volume-driven specifications with thinner margins. Consolidated beverage conglomerates negotiate centralized procurement for multiple production sites. The region sustains mature amylase demand for enzyme recovery and reuse cycle optimization.
Spain Specialty Enzymes Market Competitive Landscape
Capital-heavy producers compete with asset-light designers as fermentation technology leaders anchor high-purity pharmaceutical applications while contract research organizations deploy computational enzyme design platforms. The market structures around three strategic archetypes: integrated fermentation technology specialists, premium immobilized enzyme tier occupants, and commodity food-grade volume suppliers. Dominant competitive moves include backward integration into proprietary recombinant strain development and geographic expansion into underdeveloped southern regions with favorable permitting timelines.
Within the integrated fermentation tier, Novonesis AS and BASF represent capital-intensive producers leveraging submerged fermentation infrastructure for pharmaceutical-grade supply. DSM occupies a position in the premium immobilized enzyme segment for continuous manufacturing processes. DuPont de Nemours Inc exemplifies the diversified chemical conglomerate archetype with cross-sector enzyme portfolio exposure.
| Leading Market Players |
|---|
| Novonesis AS |
| BASF |
| DuPont de Nemours Inc |
| DSM |
| Chr. Hansen |
| Lesaffre |
| Advanced Enzymes |
| Bluestar Adisseo Co. |
| Novus Holdings Ltd |
| Others |
Pricing and Supply Chain Analysis
EMA-mandated GMP certification requirements for pharmaceutical-grade biocatalysts force Spanish manufacturers to source exclusively from audited fermentation facilities with documented purity traceability, compressing procurement options and anchoring price premiums to regulatory compliance tiers rather than commodity feedstock costs.
Pricing Analysis
Yield-linked performance guarantees anchor pharmaceutical-grade enzyme contracts, with pricing stratifying across premium, standard, and economy tiers based on EMA certification depth and batch-to-batch consistency metrics. Price differentiation stems from immobilization matrix quality and dedicated technical service bundling. Cost compression in commodity food-grade tiers intensifies as consolidated beverage conglomerates unbundle consulting from bulk procurement. Generic drug manufacturers exhibit highest price sensitivity; continuous manufacturing adopters in Barcelona accept premium positioning for uptime guarantees.
Supply Chain Analysis
Metabolic engineering PhD scarcity in Madrid and Barcelona constrains strain development capacity expansion, forcing Spanish biotech facilities to compete for talent against German and Dutch fermentation hubs. Supply concentrates in the Basque Country's industrial cluster and Catalonia's biotechnology corridor, with critical inputs drawing from German and Dutch specialty chemical suppliers for immobilization matrices. Single-source vulnerability for flow reactor components creates input bottlenecks. Distribution runs through direct pharmaceutical procurement channels and consolidated beverage conglomerate central buying desks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing captive fermentation capacity to secure strain development control and insulate margin capture from feedstock volatility.
For Market Incumbents: Extend proprietary recombinant strain libraries through CRISPR-optimized platform investments, locking in catalytic efficiency advantages that commodity suppliers cannot replicate. Secure dedicated biogas capture infrastructure ahead of EU Green Deal emission rule deadlines in Andalusia greenfield sites. Consolidate position against emerging contract research organizations deploying computational enzyme design platforms. For New Entrants and Emerging Players: Enter via Andalusia's underdeveloped fermentation corridor, where permitting timelines favor greenfield construction against saturated Catalonia infrastructure. Target cellulosic ethanol pilot operators with customized cellulase loading rate optimization services, bypassing entrenched pharmaceutical-grade certification barriers. Lead with outcome-based pricing tied to agricultural residue conversion yields. For Investors and Strategic Acquirers: The window for entry favors integrated fermentation technology specialists with captive strain development capabilities and established EMA regulatory dossiers. Long-term viability hinges on biocatalytic process integration depth rather than standalone enzyme commodity supply. Monitor EMA biosimilar manufacturing enzyme guidance clarity as the inflection signal for dedicated biocatalytic line capital commitment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | Captive CRISPR-optimized microbial platforms reduce dependency on external metabolic engineering talent pools. |
| Greenfield Fermentation Facility Expansion | Andalusia sites offer favorable EU Green Deal permitting timelines versus saturated Catalonia infrastructure. |
| Immobilized Enzyme Flow Reactor Deployment | Continuous manufacturing retrofits in Barcelona pharmaceutical facilities open premium service contract opportunities. |
| Computational Enzyme Design Platform Investment | Machine learning substrate specificity prediction compresses strain optimization cycles for contract research organizations. |
| Biogas Capture Integration | Anaerobic digestion waste treatment retrofits maintain operating licenses under Spain's transposed EU emission rules. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across fermentation technology directors, pharmaceutical procurement leads, EMA regulatory affairs specialists, and Basque Country plant managers. Secondary validation drew from EMA GMP inspection reports, ECHA REACH registration dossiers, European Chemicals Agency toxicity data, and Spain's national environmental regulator emission disclosures. Bottom-up enzyme procurement volume estimates triangulated against top-down pharmaceutical manufacturing capacity assessments.
Reconciliation of production capacity data, import-export flows, and end-use consumption patterns shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application protocol, end-user concentration level, and regional regulatory compliance tier. CAGRs derived from fitted growth curves anchored in documented facility expansion announcements and patent filing trajectories. CRISPR strain engineering adoption rates and continuous manufacturing retrofit timelines served as enzyme-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EMA biosimilar guidance delays or corn syrup feedstock price spikes. Forecasts reflect assumptions on regulatory clarity timelines and metabolic engineering talent pipeline recovery. Material deviation in EU Green Deal enforcement intensity or REACH toxicity dossier approval velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
TSG6 Antibody Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Acetylglucosamine Market