
 Vaccine and Biologic Product Distribution Optimization Services Market | 2026-2036
Vaccine and Biologic Product Distribution Optimization Services Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine and Biologic Product Distribution Optimization Services Market Insights
WHO temperature excursion guidelines for vaccine distribution is consolidating procurement standards across national health systems. DHL Supply Chain leverages its pharmaceutical-certified network to sustain compliance across multiple climate zones. FedEx anchors its position through specialized cold chain infrastructure at major air hubs. McKesson competes by controlling distribution channels that connect manufacturers directly to vaccination centers.
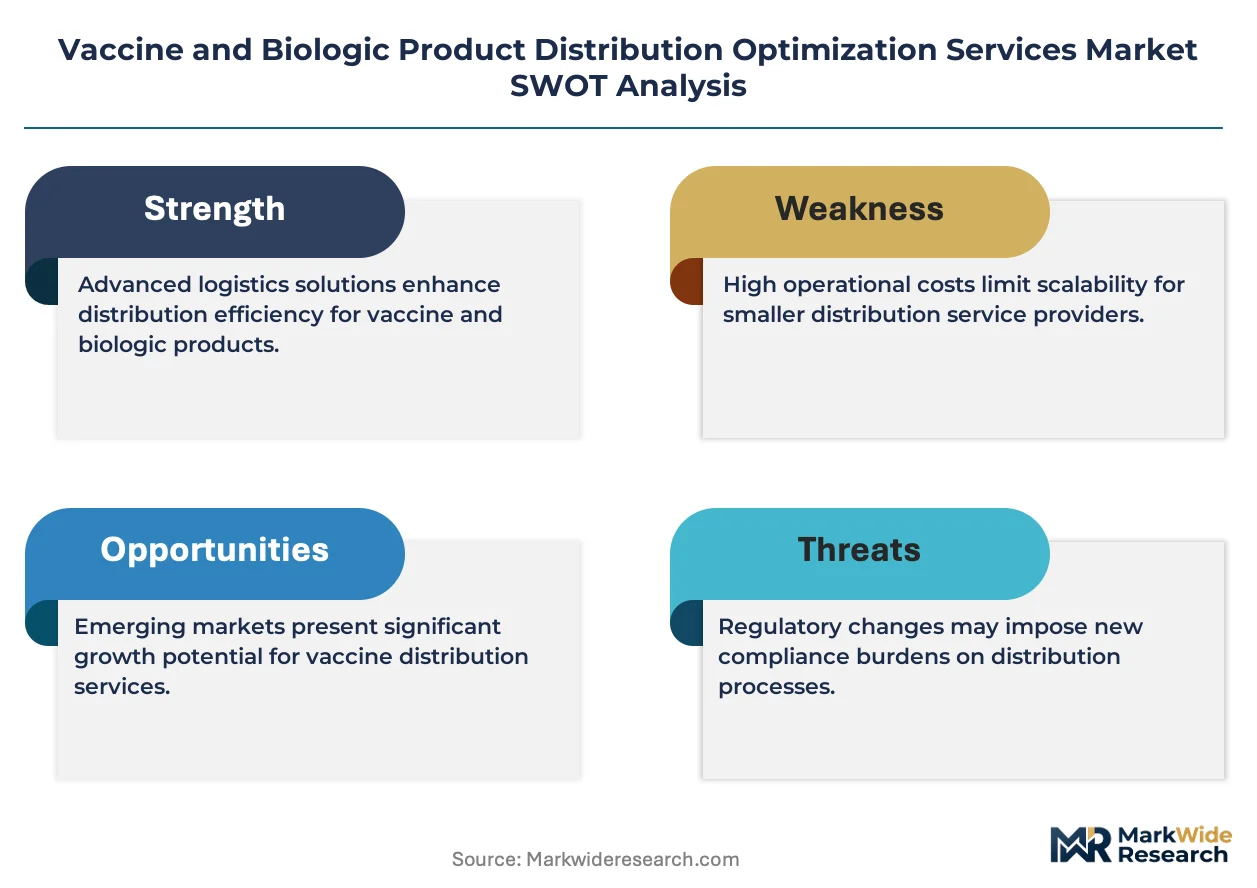
Vaccine and biologic product distribution optimization services encompass temperature-controlled logistics, inventory synchronization, and regulatory compliance orchestration for time-sensitive biologics requiring maintenance between 2°C and 8°C or ultra-frozen states below -70°C. These services prevent potency loss during transit, enable just-in-time delivery to immunization sites, and document chain-of-custody for pharmacovigilance requirements. Cold chain management dominates service revenue due to capital-intensive refrigeration infrastructure and energy costs, while AI analytics within the technology dimension represents the fastest-expanding segment as predictive demand models reduce wastage from expired doses. Blockchain applications remain nascent but attract investment where counterfeit detection and batch traceability carry premium value.
FDA validation requirements for Good Distribution Practice shape facility qualifications and transport documentation across US corridors. EMA guidelines on temperature monitoring and GDP enforcement in Europe create parallel compliance obligations for cross-border vaccine movements. India's CDSCO cold chain protocols and PLI scheme incentives for biologics manufacturing both expand the addressable base for optimization services. Stakeholders must evaluate whether to build captive distribution networks or outsource to specialized third-party logistics providers as regulatory granularity intensifies.
Market Dynamics
WHO temperature excursion guideline revisions are compressing acceptable variance windows for vaccine transit, forcing logistics providers to retrofit existing cold chain infrastructure with continuous monitoring systems and automated alert protocols.
Growth Catalysts
- Ultra-cold infrastructure mandates:EMA GDP enforcement now requires validated -70°C transport documentation for mRNA biologics, expanding qualification requirements across European distribution networks.
- India PLI scheme expansion:India's production-linked incentive scheme for biologics manufacturing is generating captive demand for domestic cold chain capacity upgrades and last-mile optimization services.
- AI-powered demand forecasting:Predictive analytics platforms are reducing expiry-related wastage at immunization centers by synchronizing inventory levels with appointment scheduling systems.
Market Restraints
- Dry ice supply volatility:Carbon dioxide capture constraints and industrial gas allocation priorities are creating input cost instability for ultra-cold shipment conditioning.
- Refrigeration equipment concentration:Compressor and cold plate manufacturing concentrates in East Asian supply chains, exposing procurement timelines to single-source dependencies.
- Cross-border GDP harmonization gaps:Divergent FDA and EMA documentation requirements for temperature excursion investigations create regulatory friction for multi-jurisdictional vaccine movements.
Strategic Opportunities
- Sub-Saharan last-mile gaps:Underpenetrated rural immunization networks in Nigeria and Kenya present white space for drone-enabled cold chain delivery and solar-powered refrigeration nodes.
- Blockchain batch traceability:Immutable ledger systems for counterfeit detection are attracting investment where pharmacovigilance requirements carry premium compliance value.
- Convergence of IoT sensors and edge computing:Real-time temperature analytics at shipment level is enabling autonomous intervention protocols before excursion thresholds breach.
Industry Challenges
- Qualified personnel scarcity:GDP certification programs and cold chain engineering specializations face training pipeline bottlenecks that extend facility qualification timelines.
- Refrigeration asset capex intensity:Validated cold rooms and refrigerated vehicle fleets require capital deployment cycles that strain mid-scale logistics providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine and Biologic Product Distribution Optimization Services Market |
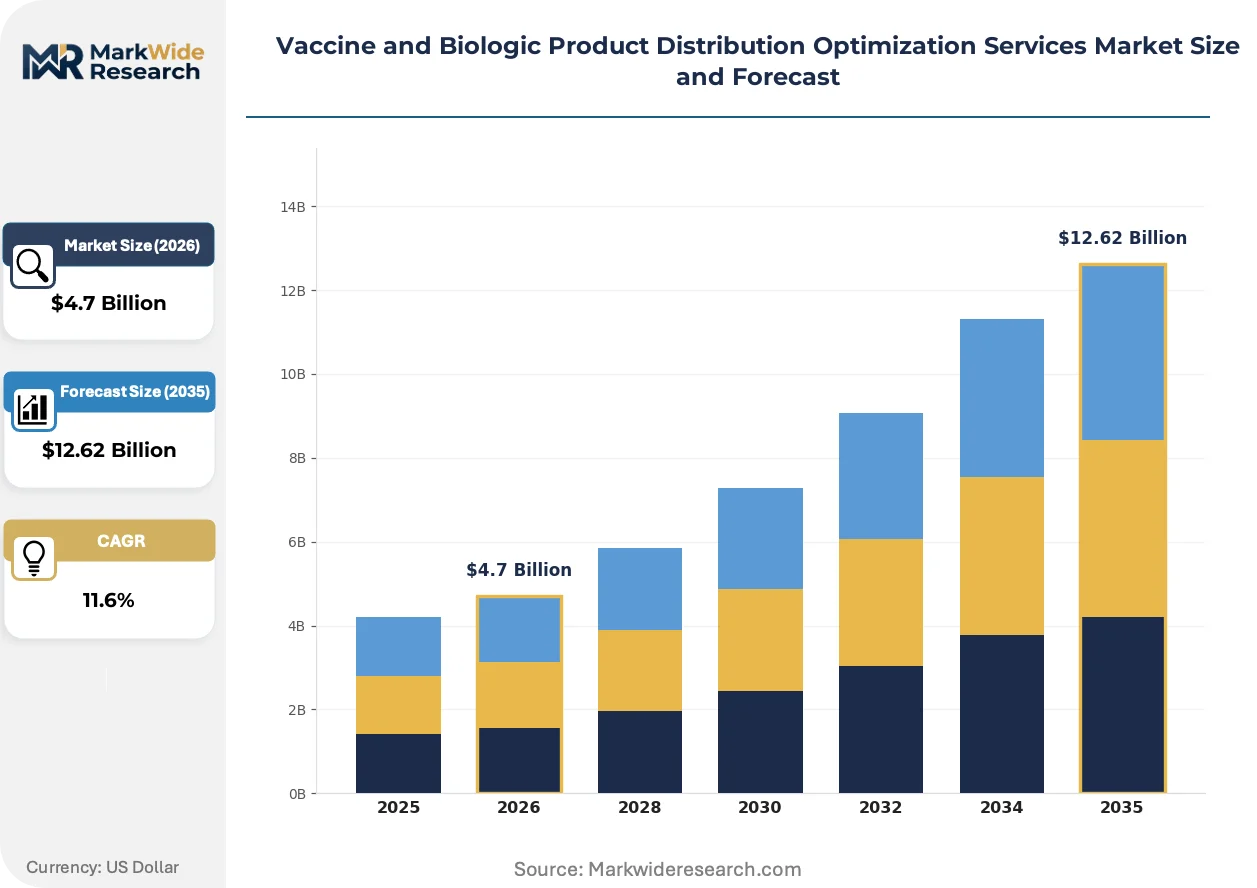
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $12.62 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cold Chain Management, Inventory Forecasting, Route Optimization, Compliance Monitoring, Demand Planning Application: Healthcare Providers, Clinical Research, Government Immunization Programs, Pharmaceutical Manufacturers, Private Clinics End User: Hospitals, Diagnostic Laboratories, Vaccination Centers, Specialty Pharmacies, Community Health Centers Technology: Real-Time Tracking, Blockchain, AI Analytics, IoT Sensors, Cloud Platforms, Data Integration |
| Companies Covered | UPS Healthcare, DHL Supply Chain, Kuehne+Nagel, World Courier, FedEx, Cryoport Systems, McKesson, DB Schenker, CEVA Logistics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine and Biologic Product Distribution Optimization Services Market Trends and Innovations
Digital twin modeling of vaccine distribution networks is compressing scenario planning cycles, while regulatory digitization and buyer-side consolidation are restructuring how optimization services are procured and priced.
Modular containerization systems with embedded phase-change materials are decentralizing ultra-cold storage from centralized hubs to regional distribution points. Regional health authorities in Southeast Asia are piloting these units for island-hopping vaccine delivery. The technology is decentralizing the traditional hub-and-spoke cold chain architecture by enabling point-to-point shipment without intermediary re-icing.
EMA's forthcoming revision to Good Distribution Practice guidelines will mandate blockchain-verified chain-of-custody records for temperature-sensitive biologics crossing European borders. Pharmaceutical distributors are pre-emptively upgrading documentation systems to avoid qualification gaps. Small-scale national immunization programs in Eastern Europe face the steepest compliance cost increases as they lack existing digital infrastructure.
Consolidated procurement by Gavi-eligible country coalitions is compressing vendor selection cycles and unbundling after-sales service from equipment supply contracts. UNICEF's vaccine prequalification program now evaluates distribution partner capabilities alongside product dossiers. This behavioral shift is most visible across West African immunization programs where pooled purchasing has displaced single-country tender processes.
Vaccine and Biologic Product Distribution Optimization Services Market Segmentation
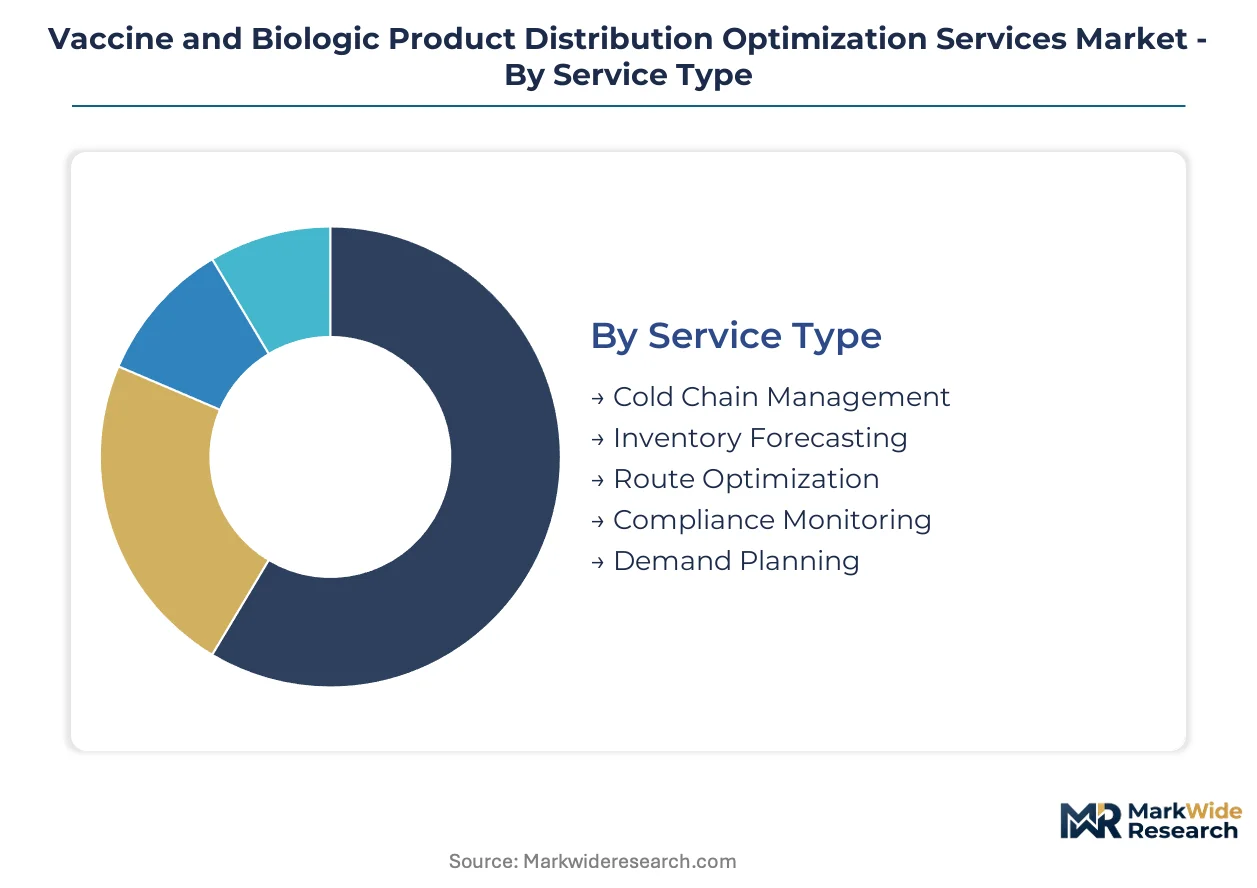
Vaccine and biologic distribution optimization services fragment across service capabilities, application contexts, and enabling technologies. Each segmentation dimension carries distinct procurement patterns and capability requirements that shape vendor positioning and customer switching costs.
Service Type:
Upgrade cycles in cold chain infrastructure are accelerating as WHO temperature excursion guidelines compress acceptable variance windows, forcing logistics providers to retrofit monitoring systems and automate alert protocols.
- Cold Chain Management:Temperature-controlled logistics infrastructure maintains 2°C to 8°C or ultra-frozen states below -70°C through validated refrigeration, thermal packaging, and continuous environmental monitoring. Government immunization programs in India and private vaccine distribution networks both drive capacity expansion as CDSCO protocols tighten. Capital intensity and energy costs concentrate revenue in this segment.
- Inventory Forecasting:Predictive analytics platforms synchronize stock levels with appointment scheduling systems to reduce expiry-related wastage at immunization centers. AI-powered demand models represent the fastest-expanding technology application within service portfolios as wastage reduction delivers measurable ROI.
- Route Optimization:Algorithmic planning tools minimize transit time and thermal exposure for time-sensitive biologics through dynamic rerouting based on traffic, weather, and facility readiness signals.
- Compliance Monitoring:Documentation systems capture chain-of-custody records and temperature excursion investigations to satisfy FDA Good Distribution Practice and EMA enforcement requirements.
- Demand Planning:Long-range capacity modeling aligns distribution network investments with manufacturer production schedules and immunization campaign calendars.
Cold Chain Management sits at the top of the volume ranking, with Inventory Forecasting climbing the fastest.
Application:
Cost tier differentiation separates high-complexity regulated environments from standardized commercial distribution, with procurement authority concentrating in government and large institutional buyers.
- Healthcare Providers:Hospital systems and integrated delivery networks require just-in-time delivery coordination for patient-specific biologic therapies with narrow administration windows.
- Clinical Research:Trial sponsors demand validated cold chain documentation for investigational products with protocol-defined temperature ranges and audit-ready chain-of-custody records.
- Government Immunization Programs:National health systems operate the largest volume corridors, with India's Universal Immunization Program and Gavi-eligible country coalitions consolidating procurement and unbundling after-sales service from equipment contracts.
- Pharmaceutical Manufacturers:Biologics producers face EMA GDP mandates for -70°C transport documentation of mRNA products, expanding qualification requirements across European distribution networks.
- Private Clinics:Smaller-scale buyers prioritize modular containerization systems with embedded phase-change materials for decentralized ultra-cold storage without centralized hub dependency.
Government Immunization Programs anchor volume concentration, while Clinical Research commands premium pricing tiers.
End User:
Customer type fragmentation reflects divergent technical sophistication, with large institutions operating captive logistics capabilities and smaller endpoints relying on third-party service integration.
- Hospitals:Acute care facilities manage high-value biologic inventories for oncology and immunology departments with specialized pharmacy infrastructure.
- Diagnostic Laboratories:Reference labs require specimen transport optimization for companion diagnostic testing tied to biologic therapy selection.
- Vaccination Centers:Mass immunization sites need surge capacity handling for campaign-driven volume spikes with rapid cold chain deployment.
- Specialty Pharmacies:Limited distribution drug networks coordinate direct-to-patient delivery for self-administered biologics with home refrigeration requirements.
- Community Health Centers:Federally qualified health centers in underserved areas present last-mile optimization challenges with intermittent power and remote geography.
Hospitals dominate current service consumption, though Vaccination Centers show steepest expansion trajectory from pandemic infrastructure retention.
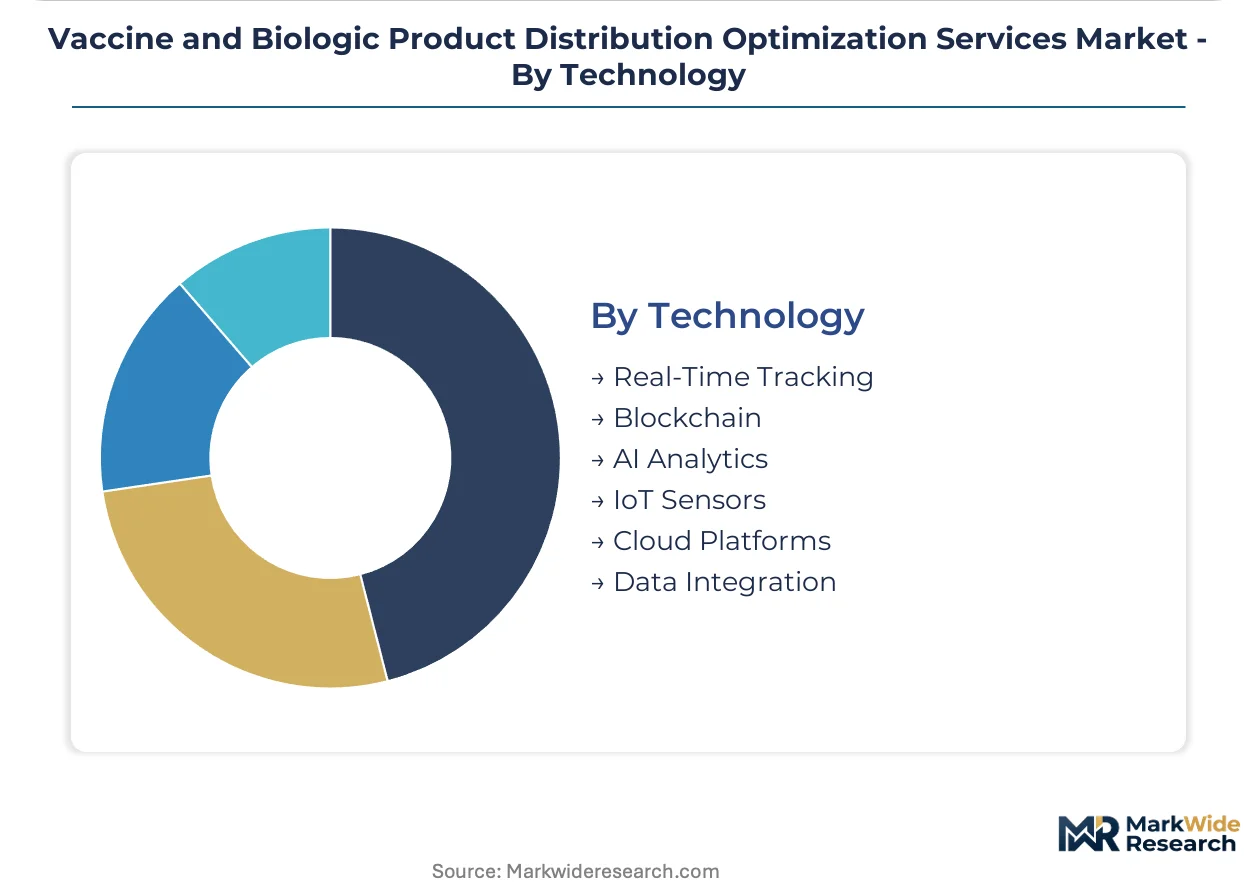
Technology:
Technology maturity curves separate proven tracking infrastructure from emerging platforms still seeking scaled deployment economics and regulatory acceptance.
- Real-Time Tracking:GPS and cellular-enabled shipment visibility provides location and environmental status updates to dispatch centers and receiving facilities.
- Blockchain:Immutable ledger systems for counterfeit detection and batch traceability attract investment where pharmacovigilance requirements carry premium compliance value, though applications remain nascent.
- AI Analytics:Machine learning models process historical demand patterns, weather data, and population health signals to predict inventory requirements and optimize distribution network flows.
- IoT Sensors:Connected temperature and humidity loggers enable continuous monitoring with automated excursion alerts and autonomous intervention protocols before threshold breaches.
- Cloud Platforms:Centralized data architecture supports multi-facility coordination and regulatory audit access across distributed stakeholder networks.
- Data Integration:API connectivity bridges manufacturer ERP systems, logistics provider TMS platforms, and healthcare provider inventory management for synchronized visibility.
Real-Time Tracking holds installed base leadership, with IoT Sensors gaining share fastest from edge computing convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold chain logistics for vaccines originated in military medical supply networks during the mid-20th century before expanding into civilian public health infrastructure. WHO immunization programs subsequently standardized temperature protocols across national health systems. Distribution optimization services now concentrate where biologics manufacturing, regulatory stringency, and immunization program scale intersect.
United States
FDA Good Distribution Practice validation requirements shape facility qualifications and transport documentation across domestic corridors. Pharmaceutical distributors operate specialized cold chain networks connecting manufacturers directly to hospital systems and vaccination centers. The Greater Boston and Research Triangle Park clusters host concentrated biologics manufacturing that generates captive demand for ultra-cold logistics services.
Germany
EMA enforcement of GDP guidelines for temperature monitoring creates compliance obligations for cross-border vaccine movements throughout European distribution networks. Frankfurt and Munich anchor pharmaceutical logistics hubs with validated -70°C infrastructure for mRNA biologics. Industrial gas suppliers in the Rhine-Main region face carbon dioxide allocation pressures affecting dry ice availability for ultra-cold shipment conditioning.
India
CDSCO cold chain protocols and the PLI scheme for biologics manufacturing expand the addressable base for optimization services across both public and private distribution networks. The Universal Immunization Program drives volume concentration while private vaccine networks require upgraded infrastructure. Hyderabad and Bengaluru clusters concentrate biologics production that generates demand for domestic cold chain capacity upgrades.
Switzerland
Swissmedic regulatory standards for temperature-sensitive biologics enforcement attract pharmaceutical manufacturers seeking high-integrity distribution corridors. Basel anchors a dense cluster of biologics manufacturing that feeds specialized logistics networks across Alpine transit routes. The country's central European positioning enables hub-and-spoke distribution architectures serving EMA-compliant markets.
Japan
PMDA guidelines for vaccine distribution documentation align with WHO temperature excursion standards while maintaining distinct national validation requirements. Tokyo and Osaka metropolitan areas concentrate hospital systems requiring just-in-time delivery coordination for patient-specific biologic therapies. Domestic logistics providers face qualified personnel scarcity for GDP certification programs and cold chain engineering specializations.
Vaccine and Biologic Product Distribution Optimization Services Market Competitive Landscape
Capital-heavy cold chain infrastructure operators compete with asset-light technology platforms in a bifurcated market structure. Consolidation concentrates among integrated logistics providers with pharmaceutical-certified networks, while fragmentation persists among regional specialists serving single-country immunization programs. Three archetypes dominate: global integrators with multi-climate zone capabilities, healthcare-dedicated subsidiaries of express carriers, and pharmaceutical-focused third-party logistics providers. Competitive dynamics center on capacity expansion through refrigeration asset deployment and strategic partnerships with biologics manufacturers seeking captive distribution assurance.
Within the global integrator tier, DHL Supply Chain and FedEx exemplify divergent approaches to pharmaceutical network architecture. DHL leverages pharmaceutical-certified infrastructure across multiple climate zones to sustain compliance with tightening WHO guidelines. FedEx anchors its positioning through specialized cold chain facilities at major air hubs that enable rapid transit for time-sensitive biologics. McKesson occupies a distinct position controlling distribution channels that connect manufacturers directly to vaccination centers, representing the healthcare-dedicated logistics archetype with embedded regulatory expertise.
| Leading Market Players |
|---|
| UPS Healthcare |
| DHL Supply Chain |
| Kuehne+Nagel |
| World Courier |
| FedEx |
| Cryoport Systems |
| McKesson |
| DB Schenker |
| CEVA Logistics |
| Others |
Pricing and Supply Chain Analysis
Captive distribution networks anchor supply positioning and pricing power for biologics manufacturers navigating tightening WHO temperature excursion guidelines. India's PLI scheme incentives and CDSCO protocol upgrades are accelerating domestic cold chain capacity builds, compressing margins for third-party logistics providers while rewarding vertically integrated operators with captive manufacturing demand.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by GDP certification grade and after-sales service bundling. Premium tiers capture government immunization program contracts requiring validated -70°C documentation and continuous monitoring systems. Price differentiation stems from EMA compliance overhead and compressor manufacturing concentration in East Asian supply chains. Cost compression in standard tiers is intensifying because dry ice supply volatility from carbon dioxide capture constraints erodes conditioning economics. Private clinics and community health centers exhibit highest price sensitivity, while pharmaceutical manufacturers and clinical research sponsors prioritize certification reliability over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Gavi-eligible country coalitions and UNICEF prequalification programs require logistics providers to qualify multiple refrigeration equipment suppliers and industrial gas distributors. Manufacturing concentrates in China, Germany, and Japan for compressor systems, cold plates, and phase-change material formulations. Component sourcing draws from Taiwan for IoT sensors, Belgium for specialized refrigerants, and the United States for cloud platform infrastructure. Single-source vulnerability in carbon dioxide capture infrastructure exposes ultra-cold shipment conditioning to allocation priority shifts. Distribution runs through hub-and-spoke architectures anchored at Frankfurt, Mumbai, and Memphis, with modular containerization enabling point-to-point decentralization for last-mile island networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in AI-powered inventory forecasting and blockchain batch traceability as premium-tier services, with dry ice supply volatility and qualified personnel scarcity compressing cost structures for standardized cold chain management.
For Market Incumbents: Acquire specialized cold chain engineering firms to compress GDP certification timelines and qualified personnel bottlenecks. DHL Supply Chain and FedEx should expand pharmaceutical-certified infrastructure in Hyderabad and Bengaluru clusters to capture PLI scheme biologics manufacturing demand. Defensive consolidation through backward integration into compressor and phase-change material production mitigates East Asian supply chain concentration risk. For New Entrants and Emerging Players: Enter via drone-enabled delivery partnerships with Nigerian and Kenyan rural immunization networks where last-mile gaps remain underpenetrated. Solar-powered refrigeration nodes present white-space deployment for decentralized ultra-cold storage without centralized hub dependency. Target government immunization program coalitions in West Africa where pooled purchasing has displaced single-country tender processes and unbundled after-sales service from equipment contracts. For Investors and Strategic Acquirers: Roll-up economics work for regional cold chain specialists with existing GDP certification and government contract relationships because regulatory granularity intensifies switching costs and extends facility qualification timelines. Mid-scale logistics providers facing refrigeration asset capex intensity strain represent consolidation targets. Watch EMA forthcoming GDP guideline revisions mandating blockchain-verified chain-of-custody as inflection indicator for documentation system upgrade demand.| Strategic Initiative | Industry Significance |
|---|---|
| Cold Chain Infrastructure Expansion | Validated -70°C capacity builds in India and Germany capture PLI scheme and EMA GDP enforcement demand. |
| AI Analytics Platform Deployment | Predictive demand models reduce expiry-related wastage at immunization centers with measurable ROI documentation. |
| Blockchain Documentation Upgrade | Immutable ledger systems satisfy forthcoming EMA chain-of-custody mandates for cross-border biologics movements. |
| Modular Containerization Pilot | Phase-change material units enable island-hopping delivery in Southeast Asia without intermediary re-icing. |
| Dual-Sourcing Qualification Program | Multiple compressor and industrial gas suppliers mitigate carbon dioxide allocation and East Asian concentration risks. |
Research Methodology
Direct dialogue with cold chain logistics executives, regulatory affairs specialists at pharmaceutical distributors, government immunization program procurement officers, and biomedical engineering consultants grounded qualitative findings. Secondary validation drew from FDA Good Distribution Practice guidance documents, EMA GDP inspection reports, CDSCO cold chain protocols, WHO temperature excursion guidelines, and UNICEF vaccine prequalification assessments. Bottom-up service provider capacity modeling and top-down national immunization program expenditure analysis were triangulated to constrain estimate variance.
Segment-level outputs across cold chain management, inventory forecasting, route optimization, compliance monitoring, and demand planning service types were generated through the projection horizon. Geographic clusters modeled included United States pharmaceutical distribution corridors, European EMA-compliant networks, Indian public and private vaccine channels, Swiss biologics transit routes, and Japanese hospital system logistics. CAGRs were derived from capacity expansion announcements, regulatory mandate implementation schedules, and biologics manufacturing facility commissioning timelines across the analysis window.
Inputs from cold chain equipment manufacturers and industrial gas distributors were available through the study window; gaps in real-time dry ice pricing transparency and qualified personnel training pipeline data introduce uncertainty bands around cost structure projections. Deviation in carbon dioxide capture allocation priorities or WHO temperature excursion guideline revision timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Feruloyl Esterase Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Serine Protease Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
In Vivo CRO Market