
 Precast Agarose Gel Market | 2026-2036
Precast Agarose Gel Market Size, Share, and Industry Trends Forecast 2026-2036
Precast Agarose Gel Market Insights
Modular kit configurations bundling precast gels with buffer systems and ladders is rebalancing procurement patterns in molecular biology labs. Thermo Fisher Scientific leverages its channel density to sustain dominant positions in North American academic accounts. Bio-Rad Laboratories anchors its portfolio with specialized high-performance gel formats for protein separation workflows. Lonza Group competes through geographic diversification across European biopharma clusters.
Precast agarose gels are factory-cast separation matrices, typically manufactured at 0.8% to 2% agarose concentrations with defined gel strengths of 800 to 1,200 g/cm², designed to eliminate manual pouring variability in nucleic acid and protein electrophoresis. Standard gel formats remain the volume backbone due to their cost position in routine DNA electrophoresis, while high-performance gels command premium positioning in pharmaceutical quality control where resolution thresholds are stringent. Academic institutions and research laboratories represent the structural demand anchor, though biotechnology firms are shifting procurement toward direct sales channels to secure lot-to-lot consistency for regulated workflows.
FDA diagnostic reagent guidelines and EMA IVD quality system requirements shape purity documentation and traceability standards for gel manufacturers seeking clinical market access. ISO 13485 certification and CE marking under EU MDR frameworks increasingly determine supplier eligibility for European diagnostic and research procurement tenders. Stakeholders must monitor evolving regulatory convergence between US and European quality benchmarks as molecular diagnostics manufacturers consolidate supplier bases.
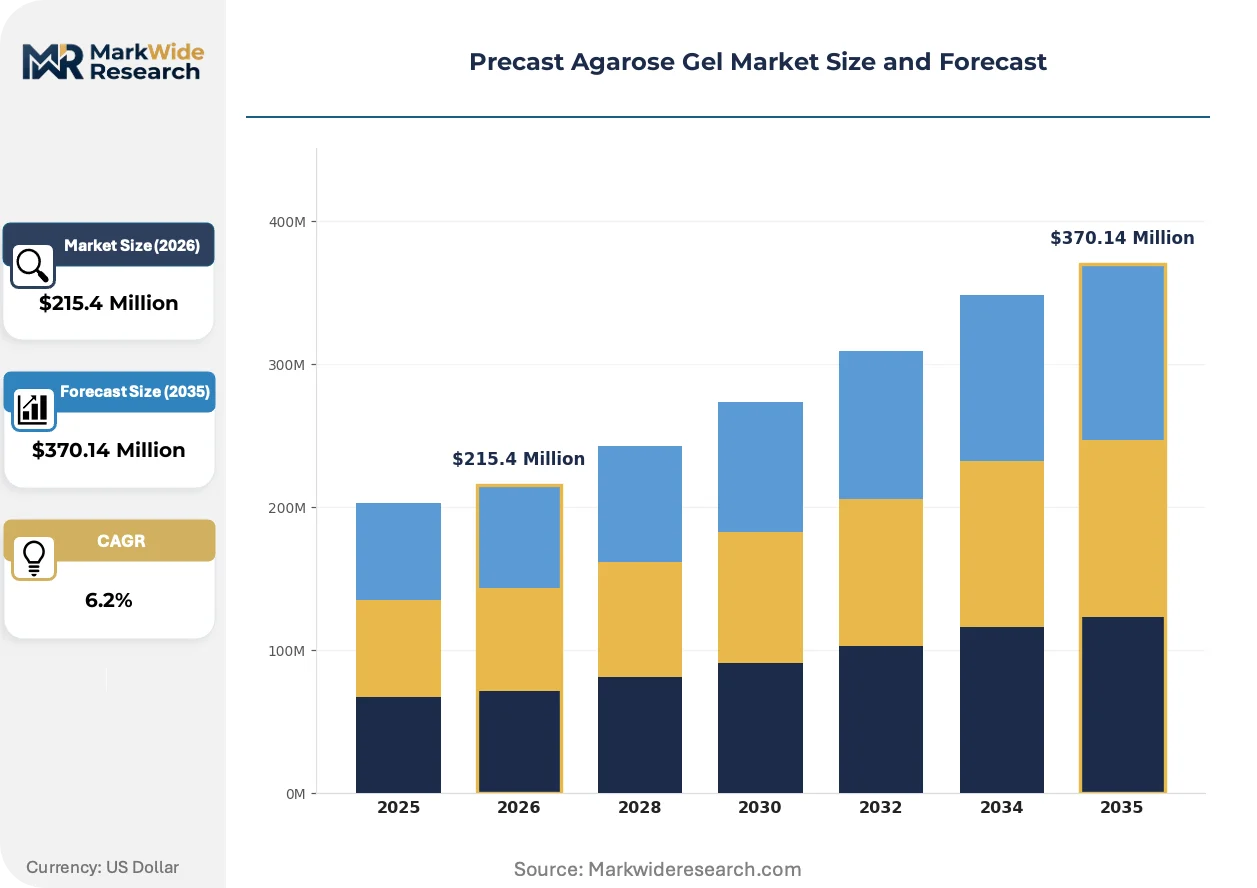
Market Dynamics
Standardization of molecular diagnostics workflows is compressing lot-to-lot variability tolerance, forcing gel manufacturers to reconfigure quality systems around ISO 13485 documentation and EMA MDR traceability requirements.
Growth Catalysts
- FDA diagnostic reagent guidelines:Tightening purity benchmarks for clinical-grade gel matrices are accelerating supplier consolidation toward certified manufacturers. Diagnostic laboratories in the United States now mandate documented agarose sourcing.
- Biotechnology firms:Direct sales channel migration for regulated workflows is pulling volume away from distributor networks. These buyers prioritize lot-to-lot consistency over unit cost.
- Centralized research funding:High-throughput laboratory infrastructure investments in Germany and the United States are standardizing precast gel procurement across academic consortia.
Market Restraints
- Agarose raw material concentration:Seaweed harvesting volatility in Southeast Asian supply corridors creates input cost instability for gel manufacturers.
- Manual pouring substitution:Cast-your-own gel protocols persist in cost-constrained teaching laboratories, capping premium precast penetration.
- EMA MDR compliance timelines:Extended certification cycles for CE-marked diagnostic gels are delaying European market entry for newer suppliers.
Strategic Opportunities
- Modular kit bundling:Buffer systems and DNA ladders packaged with precast gels are capturing workflow consolidation budgets in mid-sized research facilities.
- Protein separation workflows:Specialized high-performance gel formats for pharmaceutical quality control command pricing premiums above standard DNA electrophoresis products.
- EU Green Deal procurement criteria:Sustainable sourcing documentation is becoming a scored element in European academic tender evaluations.
Industry Challenges
- ISO 13485 certification gaps:Smaller regional manufacturers lack quality management infrastructure to serve clinical diagnostic accounts.
- Legacy electrophoresis system integration:New gel formats must maintain dimensional compatibility with installed base equipment across multi-site research networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precast Agarose Gel Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $370.14 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Gel, High-Performance Gel, Premium Gel, Low-Electroendosmosis Gel Application: DNA Electrophoresis, RNA Electrophoresis, Protein Separation, Gel Imaging End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Biotechnology Firms Distribution Channel: Online Retail, Distributors, Direct Sales, Laboratory Supply Stores |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Lonza Group, Merck KGaA, GE Healthcare, Agilent Technologies, Sartorius AG, Sigma-Aldrich, Qiagen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precast Agarose Gel Market Trends and Innovations
Factory-cast separation matrices are displacing manual preparation protocols through precision manufacturing controls that eliminate operator-dependent variability in gel strength and concentration.
Capillary electrophoresis microfluidics is converging with precast agarose workflows as pharmaceutical quality control laboratories adopt hybrid separation platforms. Large-molecule biopharma manufacturers in Switzerland and Massachusetts are piloting these integrated systems. The convergence is compressing standalone gel demand in high-value analytical segments while opening specification windows for specialized high-performance formats.
EU MDR technical documentation requirements are mandating expanded purity testing for gel matrices entering in-vitro diagnostic supply chains. Manufacturers must now maintain batch records traceable to raw agarose harvesting coordinates. European diagnostic reagent assemblers are consolidating supplier bases to reduce audit burden, favoring incumbent certified producers over emerging competitors.
Research procurement officers are unbundling after-sales technical support from product pricing, negotiating standalone service contracts for electrophoresis troubleshooting. Academic core facilities in Germany and the United States are leading this shift, treating gel supply as commodity while purchasing application expertise separately. The model is displacing traditional bundled pricing in multi-year framework agreements.
Precast Agarose Gel Market Segmentation
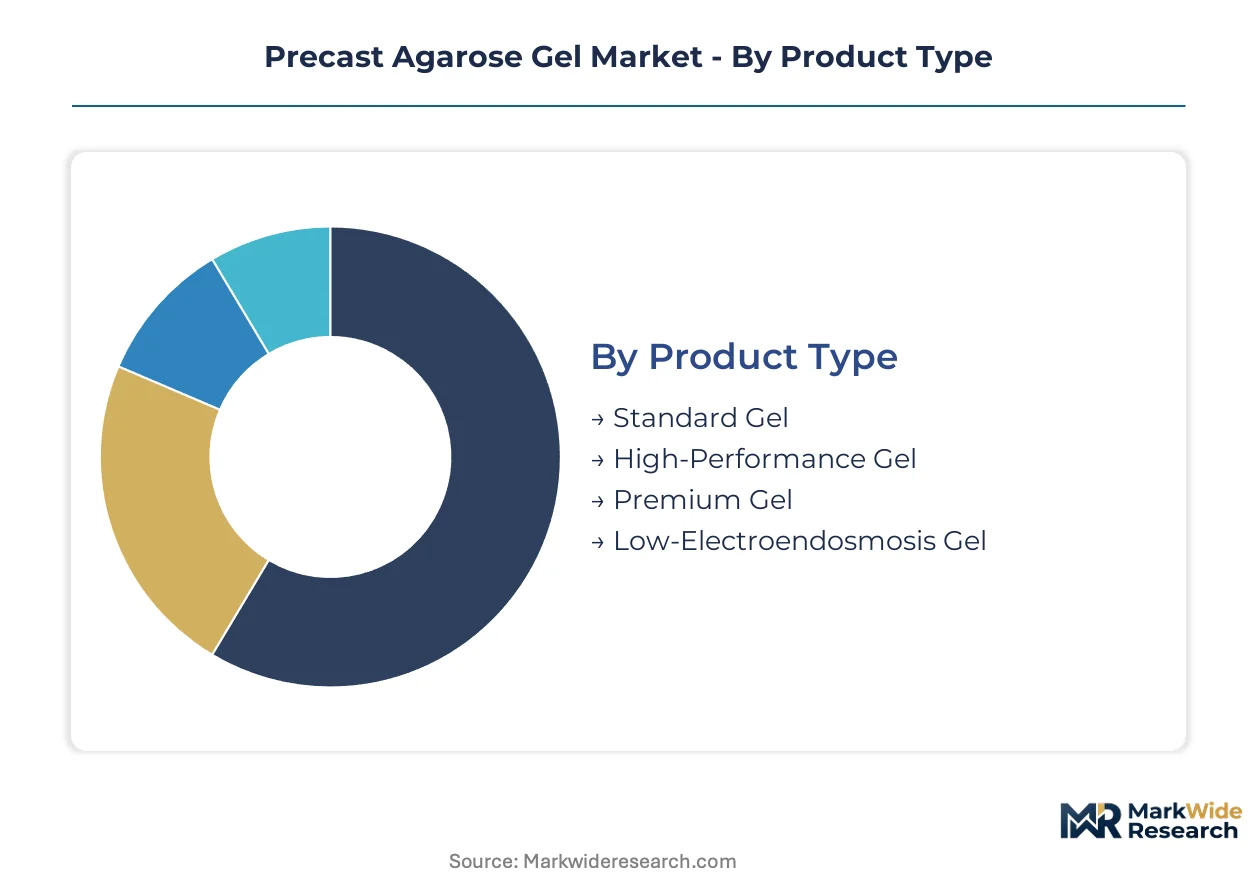
Precast agarose gel segmentation reveals how manufacturing precision, workflow integration, and procurement authority fragment demand across molecular biology supply chains. Gel concentration specifications and end-use regulatory requirements create distinct competitive arenas with divergent margin structures.
Product Type:
Concentration gradients and gel strength specifications define performance boundaries across electrophoresis workflows.
- Standard Gel:Manufactured at 0.8% to 1.2% agarose concentrations with gel strengths of 800 to 1,000 g/cm², these formats serve high-volume DNA electrophoresis in academic core facilities. Demand concentrates in United States public university systems where cost-per-run metrics dominate procurement evaluations.
- High-Performance Gel:Engineered at 1.5% to 2.0% concentrations with defined gel strengths exceeding 1,200 g/cm² for resolution-critical separations. Pharmaceutical quality control laboratories in Germany and Switzerland specify these formats for lot release testing of nucleic acid therapeutics.
- Premium Gel:Ultra-pure agarose matrices with documented endotoxin levels below 0.1 EU/mL for sensitive cell-based applications. Biotechnology firms in Massachusetts specify these for regulatory filing support.
- Low-Electroendosmosis Gel:Chemically modified agarose with reduced EEO coefficients for protein separation workflows. Protein electrophoresis specialists in academic medical centers favor these for native PAGE compatibility.
Mature deployment sits with Standard Gel formats across teaching laboratories. Newer deployment is concentrated in High-Performance Gel segments serving biopharma quality control.
Application:
Workflow standardization and analytical throughput requirements reshape gel specification priorities across molecular biology disciplines.
- DNA Electrophoresis:The foundational application consuming precast formats for PCR product verification and plasmid analysis. Research laboratories in Germany standardize these workflows through framework procurement agreements.
- RNA Electrophoresis:Demands RNase-free manufacturing environments with documented nuclease absence. Biotechnology firms developing mRNA therapeutics in the United States drive specification tightening for integrity assessment protocols.
- Protein Separation:Native and denaturing PAGE applications requiring specialized gel chemistries. Pharmaceutical companies in Switzerland deploy these for biologics characterization under ICH Q6B guidelines.
- Gel Imaging:Companion workflows for documentation and quantification driving bundled procurement with imaging systems. Academic core facilities negotiate combined gel and imager service contracts.
DNA Electrophoresis retains the largest installed base. RNA Electrophoresis is climbing the fastest as mRNA therapeutic development accelerates.
End User:
Procurement authority and regulatory exposure create distinct customer segments with divergent supplier relationship models.
- Academic Institutions:Public universities and medical schools with centralized purchasing offices negotiating multi-year framework agreements. United States NIH-funded consortia standardize precast gel specifications across member laboratories.
- Research Laboratories:Independent and institutional core facilities with flexible procurement authority. German Max Planck institutes favor direct manufacturer relationships for lot-to-lot consistency documentation.
- Pharmaceutical Companies:Regulated environments requiring ISO 13485-certified suppliers with full batch traceability. FDA diagnostic reagent guidelines mandate documented agarose sourcing for clinical-grade applications.
- Biotechnology Firms:Venture-funded developers prioritizing speed-to-result over unit cost. Massachusetts and California clusters migrate toward direct sales channels to secure dedicated manufacturing lots.
Academic Institutions anchor volume demand through aggregated purchasing. Biotechnology Firms represent the steepest expansion trajectory as cell and gene therapy pipelines mature.
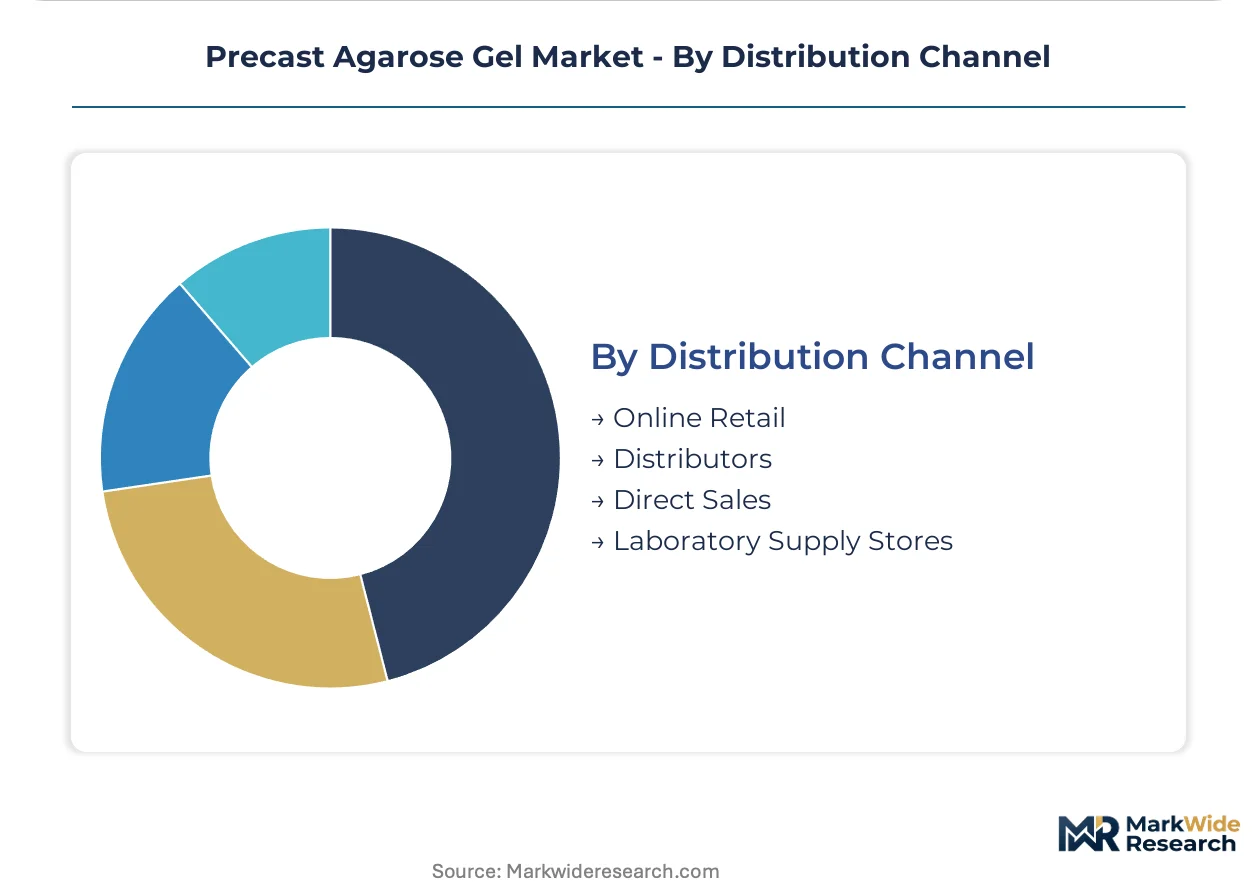
Distribution Channel:
Channel selection reflects customer scale, regulatory requirements, and technical support needs across the buyer base.
- Online Retail:E-commerce platforms serving small-volume researchers with immediate fulfillment needs. Individual principal investigators in United States academic departments favor these for emergency reagent procurement.
- Distributors:Regional laboratory supply houses with local inventory and field sales support. European academic consortia leverage distributor networks for consolidated tender compliance.
- Direct Sales:Manufacturer-managed relationships for high-volume or regulated accounts. Pharmaceutical quality control departments in Germany mandate direct channels for audit trail integrity.
- Laboratory Supply Stores:Campus-based or local physical retail for immediate pickup. Teaching laboratories in United States undergraduate programs maintain these relationships for curriculum support.
Direct Sales capture the highest-value regulated accounts. Online Retail is gaining share fastest among decentralized research organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research parks in Massachusetts and Bavaria concentrate precast agarose gel demand through clustered biotechnology investment. FDA diagnostic reagent guidelines and EMA MDR traceability requirements shape procurement patterns across these zones.
United States
NIH-funded academic consortia standardize precast gel procurement across member laboratories. FDA diagnostic reagent guidelines mandate documented agarose sourcing for clinical-grade applications. The Greater Boston cluster anchors biotechnology firm demand for lot-to-lot consistency documentation.
Germany
Max Planck institutes favor direct manufacturer relationships for quality assurance. EMA MDR technical documentation requirements mandate expanded purity testing for diagnostic supply chains. The Munich biotech corridor concentrates pharmaceutical quality control laboratory demand.
Switzerland
Large-molecule biopharma manufacturers pilot hybrid capillary electrophoresis microfluidics systems. Swissmedic quality benchmarks exceed standard ISO certification for therapeutic nucleic acid applications. Basel anchors protein separation workflow specialization under ICH Q6B guidelines.
United Kingdom
Research councils consolidate framework agreements for academic core facility procurement. MHRA alignment with EMA MDR post-Brexit maintains CE marking relevance for diagnostic reagent tenders. The Cambridge life sciences cluster drives high-performance gel specification for gene therapy development.
Japan
PMDA quality system requirements for in-vitro diagnostics tighten supplier certification standards. METI funding for genomic medicine infrastructure expands centralized laboratory procurement. The Kanto region concentrates pharmaceutical company demand for ISO 13485-certified gel matrices.
Precast Agarose Gel Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Thermo Fisher Scientific and Merck KGaA anchor the consolidated upper tier through channel density and life sciences portfolio breadth. Mid-tier specialists compete on application-specific gel formats. Competitive moves concentrate on modular kit bundling and direct sales channel migration for regulated accounts.
Within the diversified conglomerate tier, Thermo Fisher Scientific occupies a position exemplifying channel-driven market presence. Bio-Rad Laboratories and Lonza Group represent specialization archetypes, with the former anchoring high-performance protein separation positioning and the latter exemplifying geographic diversification across European biopharma clusters. These three companies collectively illustrate the competitive spectrum from scale-driven distribution to workflow-specific technical positioning.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Lonza Group |
| Merck KGaA |
| GE Healthcare |
| Agilent Technologies |
| Sartorius AG |
| Sigma-Aldrich |
| Qiagen |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap gel manufacturers in Southeast Asia anchor raw agarose supply, translating seaweed harvesting volatility into asymmetric pricing power for certified European and North American producers who command premium positioning in diagnostic-grade segments.
Pricing Analysis
Margin tightening in standard gel tiers reflects agarose input cost instability from Philippine and Indonesian seaweed harvest fluctuations. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 13485 certification grade and documented traceability depth. Biotechnology firms in Massachusetts and pharmaceutical quality control laboratories in Germany exhibit lowest price sensitivity, prioritizing lot-to-lot consistency over unit cost. Teaching laboratories in United States undergraduate programs face acute cost-down pressure, perpetuating manual-pour substitution.
Supply Chain Analysis
Ocean freight cost volatility from Southeast Asian ports to Rotterdam and Long Beach compresses landed margins for agarose raw material shipments. Factory-cast gel manufacturing concentrates in Germany, Switzerland, and the United States, drawing from seaweed-derived agarose processed in the Philippines, Indonesia, and Chile. Single-source vulnerability in Southeast Asian seaweed harvesting corridors exposes gel manufacturers to climate-driven supply interruptions. Distribution runs through direct sales channels for regulated pharmaceutical accounts and distributor networks for European academic consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capillary electrophoresis microfluidics is displacing standalone precast agarose workflows in pharmaceutical quality control, compressing demand for traditional gel formats while opening specification windows for specialized high-performance products.
For Market Incumbents: Deploy certification investment as the primary lever. Accelerate ISO 13485 documentation depth and EMA MDR traceability infrastructure to defend against emerging competitors lacking quality management systems. Consolidate supplier relationships with seaweed processors in the Philippines and Indonesia to secure captive agarose supply against harvest volatility. Channel control through direct sales relationships with biotechnology firms in Massachusetts and Germany anchors high-margin regulated accounts. For New Entrants and Emerging Players: Enter via modular kit bundling as the primary wedge. Target mid-sized research facilities in United States public university systems where workflow consolidation budgets favor packaged gel-buffer-ladder configurations. White-space exists in sustainable sourcing documentation for European academic tenders under EU Green Deal procurement criteria. Online retail channels serve decentralized principal investigators with immediate fulfillment needs, bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor ISO 13485-certified mid-cap specialists with established EMA MDR technical documentation in Germany and Switzerland. Long-term viability hinges on regulatory convergence between FDA diagnostic reagent guidelines and European quality benchmarks as molecular diagnostics manufacturers consolidate supplier bases. Watch biotechnology firm procurement migration toward direct sales channels as the inflection signal for premium pricing power consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EMA MDR Certification Investment | CE marking under EU MDR frameworks determines supplier eligibility for European diagnostic tenders. |
| Seaweed Processor Backward Integration | Upstream control over Philippine and Indonesian agarose sourcing mitigates raw material cost volatility. |
| Modular Kit Bundling Launch | Packaged gel-buffer-ladder configurations capture workflow consolidation budgets in mid-sized research facilities. |
| Direct Sales Channel Expansion | Manufacturer-managed relationships with biotechnology firms secure dedicated manufacturing lots for regulated workflows. |
| Capillary Electrophoresis Microfluidics Partnership | Hybrid platform integration with Swiss and Massachusetts biopharma manufacturers opens high-performance gel specification windows. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with gel manufacturing quality directors, diagnostic laboratory procurement managers, biotechnology firm R&D leads, and academic core facility directors combined with FDA 510(k) submissions, EMA MDR technical documentation, and ISO 13485 certification databases. Bottom-up demand modeling across end-user segments triangulated against top-down manufacturer capacity assessments.
Granularity-level modeling tracked gel concentration specifications, certification tiers, and distribution channel splits across the projection horizon. Segmentation dimensions included product type, application workflow, end-user regulatory exposure, and geographic procurement cluster. CAGRs derived from trend extrapolation of academic funding patterns, biotechnology investment flows, and diagnostic regulatory filing volumes. Forecast inputs incorporated seaweed harvest yield variability and EMA MDR compliance timeline delays.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended EMA MDR certification cycles or acute agarose supply disruption. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Research Antibodies and Reagents Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Riboflavin Kinase Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Antibody Purification Service Market
Biotechnology Services
Plasmid DNA Preparation Market
Biotechnology Services
Peptide and Oligonucleotide CDMO Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Global Digital PCR (Dpcr) and Real-Time PCR (Qpcr) Market
Biotechnology Services
Global Custom Antibody Market
Biotechnology Services
Global Bioprocess Validation Market
Biotechnology Services
Monoclonal Antibody Custom Service Market