
 Global Bioprocess Validation Market | 2026-2036
Global Bioprocess Validation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioprocess Validation Market Foresight
Single-use bioreactor technology is narrowing the gap between stainless-steel and disposable manufacturing economics, compelling validation providers to rewrite extractables and leachables protocols. Merck KGaA leverages its filtration and chromatography portfolio to anchor integrated validation workflows across mAb production lines. Sartorius AG competes through deep specialization in single-use assembly validation, while Eurofins Scientific extends analytical testing capabilities into viral clearance and cell-banking verification.
Bioprocess validation encompasses the documented evidence that manufacturing processes consistently yield products meeting predetermined specifications and quality attributes, spanning sterility assurance, viral inactivation kinetics, and container closure integrity testing. The discipline ensures that biologics manufacturing—from cell culture through final fill-finish—maintains parametric control within validated ranges to prevent batch failure and patient harm. Validation services capture the largest margin pools as sponsors outsource complex protocol execution, while software solutions for electronic batch records and statistical process control represent the fastest-expanding segment as digitalization penetrates quality management systems. Cloud-based deployment is gaining traction among mid-tier biotech companies seeking to avoid on-premise infrastructure capital.
FDA process validation guidance, EMA Annex 15, and ISO 13485 standards collectively mandate lifecycle-based process validation, forcing biomanufacturers to maintain continuous process verification rather than static three-batch qualification. These frameworks elevate demand for real-time analytical instruments and documentation tools that generate audit-ready data trails. Stakeholders must weigh the capital efficiency of outsourced validation against the intellectual property control of in-house capability development as therapy modalities diversify beyond conventional monoclonal antibodies.
Market Dynamics
Single-use bioreactor adoption is collapsing the validation economics that once favored stainless-steel infrastructure, forcing service providers to rebuild extractables and leachables protocols around disposable supply chains while sponsors demand faster facility turnaround.
Growth Catalysts
- Cell and gene therapy pipeline expansion:Advanced therapy medicinal products require novel viral clearance and cell-banking verification protocols that validation providers are racing to standardize.
- FDA process validation guidance lifecycle mandate:Continuous process verification requirements are driving recurring revenue streams for real-time analytical instrumentation and documentation services.
- CDMO facility investments in the United States:Contract manufacturers are outsourcing complex validation execution to avoid captive capability costs while accelerating biologics commercialization timelines.
Market Restraints
- Specialized resin and film supply concentration:Single-use assembly validation depends on polymer inputs sourced from a narrow base of German and Japanese material suppliers.
- EMA Annex 15 documentation stringency:European regulatory revisions are extending protocol approval timelines and inflating compliance labor costs for cross-border filings.
- Stainless-steel facility sunk costs:Existing biomanufacturing infrastructure creates asset-stranded risk that slows sponsor migration to disposable validation frameworks.
Strategic Opportunities
- Indian biologics manufacturing emergence:CDSCO regulatory alignment with ICH guidelines is attracting validation service investment as domestic biopharma capacity scales.
- Cloud-based electronic batch record deployment:Mid-tier biotechnology companies are bypassing on-premise infrastructure capital through software-as-a-service quality management adoption.
- ISO 13485 convergence with FDA QSR:Harmonized medical device quality standards are enabling validation providers to serve dual-use biologics-device combination products.
Industry Challenges
- Statistical process control specialist scarcity:Biomanufacturers struggle to hire personnel capable of designing acceptance criteria for continuous process verification datasets.
- Legacy paper batch record integration:Hybrid validation environments create data integrity audit risks during electronic system migration.
- Viral clearance study capacity bottlenecks:Spiking study throughput limitations at contract testing organizations are extending timeline commitments for gene therapy sponsors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioprocess Validation Market |
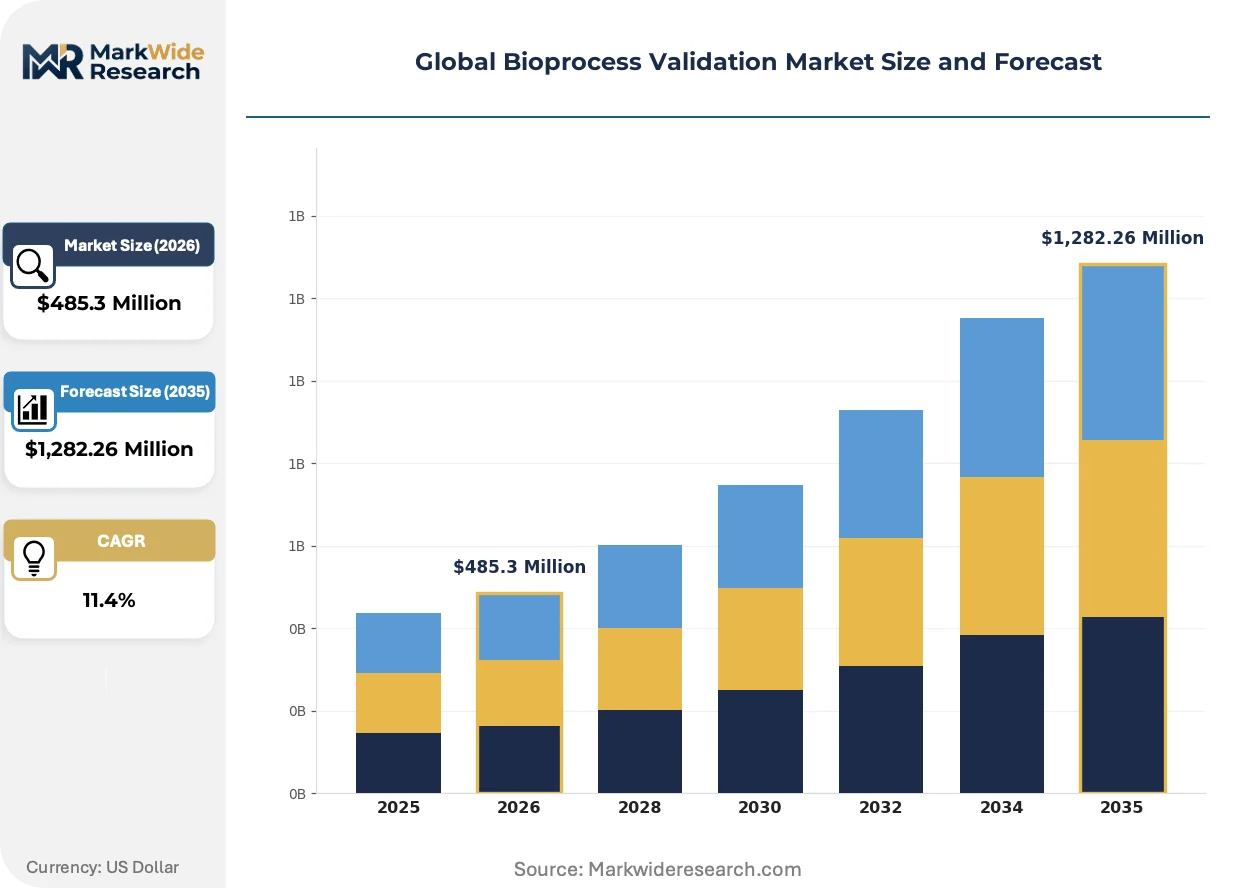
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $1,282.26 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software Solutions, Validation Services, Equipment, Analytical Instruments, Documentation Tools Application: Clinical Manufacturing, Research & Development, Quality Control, Process Optimization, Regulatory Compliance End User: Pharmaceutical Firms, Biotech Companies, Contract Research Organizations, Academic Institutions, Biomanufacturers Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Platforms, Web-Based Interfaces |
| Companies Covered | Merck KGaA, SGS, Eurofins Scientific, Thermo Fisher Scientific, Sartorius AG, Pall Corporation, Lonza, Danaher Corporation, Charles River Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioprocess Validation Market Shifts & Advancements
Digitalization is penetrating quality management systems through cloud-deployed statistical tools, while regulatory convergence and modality diversification are compressing validation protocol development cycles across the biopharmaceutical value chain.
Process analytical technology is migrating from offline at-line testing to real-time in-line monitoring of critical quality attributes. Gene therapy manufacturers are adopting Raman spectroscopy and capacitance probes at pilot scale. This capability compression is collapsing batch release timelines from weeks to days.
EMA Annex 15 revisions are mandating enhanced data integrity controls for computerized systems supporting sterile bioprocessing. The framework requires audit trail review as a batch release criterion. European monoclonal antibody manufacturers are responding by embedding validation engineers earlier in facility design phases.
Biotechnology sponsors are consolidating validation procurement under single-source master service agreements with integrated testing organizations. Discrete analytical testing contracts are giving way to multi-year platform validation partnerships. This concentration is most visible among mid-cap companies in the United States seeking to reduce vendor management overhead.
Global Bioprocess Validation Market Segmentation
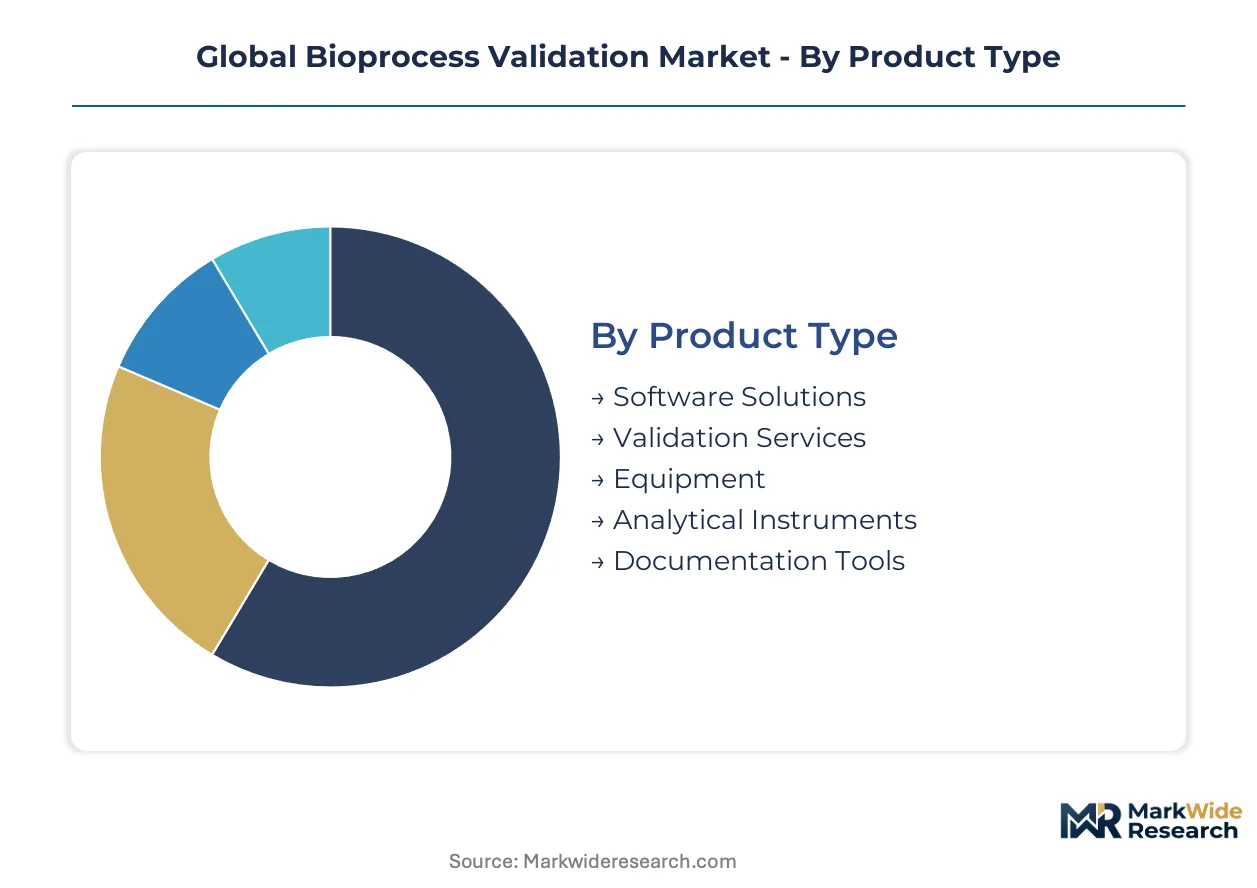
Bioprocess validation vendors design service intensity around segment-specific technical complexity. Software deployments demand continuous calibration support, while validation services require embedded personnel at client facilities.
Product Type:
After-sales service intensity varies dramatically across product categories, with analytical instruments requiring field engineering presence and software solutions shifting toward remote subscription support.
- Software Solutions:Electronic batch record platforms and statistical process control modules deploy through cloud architectures, reducing on-site validation labor. Mid-tier biotech companies in the United States bypass infrastructure capital through software-as-a-service adoption. By volume, Validation Services leads. By growth pace, Software Solutions is ahead.
- Validation Services:Contract execution of protocol development, extractables and leachables studies, and viral clearance verification commands premium pricing due to specialized personnel requirements. CDMO facility investments in the United States drive outsourcing concentration.
- Equipment:Bioreactor qualification and sterilization validation hardware requires installation qualification and operational qualification execution.
- Analytical Instruments:Process analytical technology tools for real-time critical quality attribute monitoring demand calibration contracts.
- Documentation Tools:Audit trail management and electronic signature systems support FDA process validation guidance compliance.
Service margins compress most severely in equipment while expanding fastest in software recurring revenue streams.
Application:
Cost tier stratification separates clinical manufacturing validation from research-phase protocols, with commercial-stage applications commanding triple the service expenditure per batch.
- Clinical Manufacturing:Phase-appropriate validation frameworks balance regulatory rigor against development speed, with sponsors demanding flexible protocol execution for investigational products. Cell and gene therapy pipeline expansion in the United States concentrates demand for novel viral clearance verification.
- Quality Control:Release testing validation and stability protocol execution require continuous method transfer support from contract testing organizations. EMA Annex 15 documentation stringency extends European protocol approval timelines.
- Research & Development:Early-phase process characterization studies establish design space boundaries for subsequent commercial validation.
- Process Optimization:Continuous process verification mandates under FDA guidance drive recurring analytical instrumentation demand.
- Regulatory Compliance:Audit preparation and inspection response services address FDA warning letter remediation.
Clinical applications absorb the largest absolute spending while quality control protocols expand most quickly under lifecycle validation mandates.
End User:
Customer type determines procurement centralization, with pharmaceutical firms consolidating under master service agreements while biotech companies maintain discrete vendor relationships.
- Pharmaceutical Firms:Large-scale monoclonal antibody manufacturers embed validation engineers in facility design phases, demanding integrated testing organization partnerships spanning multiple modalities. FDA process validation guidance lifecycle mandates drive platform standardization investments.
- Contract Research Organizations:Validation service providers themselves face capacity bottlenecks in viral clearance study throughput, constraining gene therapy sponsor timelines.
- Biotech Companies:Mid-cap sponsors seek single-source agreements to reduce vendor management overhead.
- Biomanufacturers:CDMOs outsource complex validation execution to avoid captive capability costs.
- Academic Institutions:Cell and gene therapy research programs require GMP-adjacent validation support for technology transfer.
Pharmaceutical firms dominate current procurement volume while CROs represent the steepest expansion trajectory as outsourcing accelerates.
Deployment:
Supply concentration in German and Japanese polymer inputs shapes hybrid deployment architectures, with sponsors reluctant to migrate fully from validated on-premise systems.
- Cloud-Based:Software-as-a-service quality management systems enable mid-tier biotechnology companies to avoid on-premise infrastructure capital while maintaining audit-ready data trails. Cloud deployment is gaining traction among United States sponsors seeking parametric control without facility investment.
- On-Premise:Validated server installations persist among large pharmaceutical firms prioritizing intellectual property control over capital efficiency.
- Hybrid:Mixed environments create data integrity audit risks during electronic system migration.
- Web-Based Interfaces:Browser-accessible dashboards support remote batch release review.
- Mobile Platforms:Tablet-based execution for cleanroom documentation remains nascent.
On-premise installations retain the largest installed base while cloud-based deployment climbs the fastest among new quality management system implementations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in bioprocess validation services, exporting protocol execution expertise to European and Asian biomanufacturers while importing specialized polymer films and chromatography resins from Germany and Japan.
United States
CDMO facility investments in Massachusetts and North Carolina concentrate demand for viral clearance verification and cell-banking protocols. FDA process validation guidance lifecycle mandates drive continuous process verification spending among monoclonal antibody manufacturers. The Greater Boston biotech corridor anchors domestic outsourcing volume as mid-cap sponsors consolidate validation procurement under integrated testing partnerships.
Germany
Specialized resin and film supply concentration in the Rhine-Main and Upper Bavaria regions positions German material suppliers at the center of single-use assembly validation workflows. EMA Annex 15 documentation stringency extends protocol approval timelines for cross-border filings into European markets. The Frankfurt-Rhine-Main metropolitan area hosts filtration and chromatography validation engineering clusters serving mAb production lines.
Switzerland
Swissmedic regulatory alignment with ICH guidelines attracts biologics manufacturers seeking streamlined multi-jurisdictional approvals for advanced therapy medicinal products. The Basel biotech triangle concentrates gene therapy validation demand as sponsors adopt novel viral clearance protocols. Cantonal economic development programs subsidize facility qualification costs for cell and gene therapy manufacturing sites.
India
CDSCO regulatory convergence with ICH standards accelerates validation service investment as domestic biopharma capacity scales in Hyderabad and Bangalore. The country's national pharmaceutical regulator mandates lifecycle-based process verification for export-oriented biologics manufacturing. The Genome Valley life sciences cluster in Telangana attracts contract testing organizations addressing viral clearance study capacity bottlenecks.
Japan
PMDA guidance on continuous manufacturing validation drives adoption of real-time analytical instrumentation among Osaka and Tokyo biomanufacturers. METI industrial policy supports domestic single-use technology adoption to reduce stainless-steel facility sunk cost exposure. The Kansai biomedical innovation corridor concentrates process analytical technology deployment for biologics batch release acceleration.
Global Bioprocess Validation Market Competitive Landscape
On the supply side, the industry is consolidating around integrated testing organizations capable of spanning multiple validation modalities from extractables studies to viral clearance verification. Tiered competition separates full-service contract research organizations with embedded facility personnel from specialized analytical testing laboratories and equipment-anchored validation workflow providers. Strategic differentiation centers on multi-year platform validation partnerships versus discrete project execution, with geographic proximity to major biomanufacturing clusters serving as a secondary sorting mechanism.
Within the integrated service tier, Merck KGaA and Eurofins Scientific exemplify archetypes of equipment-anchored and analytically-driven validation provision respectively. Sartorius AG occupies a position representing deep specialization in single-use assembly validation workflows. These three entities collectively illustrate the competitive spectrum from filtration and chromatography portfolio integration through analytical testing capability extension into viral clearance and cell-banking verification domains.
| Leading Market Players |
|---|
| Merck KGaA |
| SGS |
| Eurofins Scientific |
| Thermo Fisher Scientific |
| Sartorius AG |
| Pall Corporation |
| Lonza |
| Danaher Corporation |
| Charles River Laboratories |
| Others |
Supply & Pricing Matrix
Overcapacity in United States CDMO facilities is compressing validation service margins while simultaneously elevating pricing power for specialized polymer suppliers in Germany and Japan. This utilization asymmetry forces biomanufacturers to accept longer contract terms for single-use assemblies while negotiating harder on routine protocol execution fees.
Pricing Analysis
Stainless-steel validation protocols carry a 40-60% cost premium over single-use equivalents, yet next-generation continuous process verification bundles command premium positioning against both legacy approaches. Three-tier pricing structure across integrated platform partnerships, discrete analytical testing, and commodity equipment qualification separates CDMOs from mid-tier biotech sponsors. Cost compression in routine extractables studies is intensifying because automated documentation tools are displacing manual protocol labor. Mid-tier biotechnology companies exhibit the highest price sensitivity, while pharmaceutical firms prioritize audit-ready data trails over per-project economics.
Supply Chain Analysis
Tariff exposure between the United States and China for analytical instrumentation components dominates supply chain risk planning among validation service providers. Specialized resin and film inputs draw from concentrated manufacturing bases in Germany, Japan, and the United States, with chromatography media and single-use assembly polymers resting on petrochemical feedstocks from the Rhine-Main and Gulf Coast regions. Single-source vulnerability in viral clearance study capacity at contract testing organizations is extending timeline commitments for gene therapy sponsors. Distribution runs through validated cold-chain logistics partners serving biomanufacturing clusters in Massachusetts, North Carolina, and Basel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-cap biotechnology sponsors consolidating validation procurement under integrated testing organization master service agreements. This procurement centralization fragments pricing leverage for discrete analytical testing laboratories.
For Market Incumbents: Harden platform validation partnerships through embedded personnel deployments at CDMO facilities in Massachusetts and North Carolina, neutralizing emerging single-use technology specialists. Deepen analytical instrumentation calibration contracts to capture recurring revenue streams as cloud-based electronic batch record adoption accelerates. Prioritize ISO 13485 certification investments to serve dual-use biologics-device combination products against regulatory convergence pressures.
For New Entrants and Emerging Players: Viral clearance study capacity bottlenecks at established contract testing organizations represent the most penetrable entry point for gene therapy-focused validation specialists. Indian biologics manufacturing emergence in Hyderabad and Bangalore offers geographic white-space for lifecycle-based process verification services ahead of CDSCO regulatory alignment completion. A go-to-market angle anchored in Raman spectroscopy and capacitance probe validation for cell and gene therapy manufacturers bypasses direct competition with incumbent filtration portfolios.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-as-a-service quality management platforms serving mid-tier biotechnology companies, with validation services exhibiting stronger cyclicality tied to biologics pipeline funding windows. Long-term viability over a multi-year horizon favors analytical testing organizations with viral clearance and cell-banking verification capabilities as advanced therapy medicinal products scale. The signal to watch is FDA warning letter volume targeting data integrity violations in hybrid paper-electronic batch record environments, which would accelerate cloud-based validation software procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | EMA Annex 15 compliance investments open European market access for United States-based CDMO validation services. |
| Manufacturing Scale-Up | Single-use bioreactor validation protocols reduce facility turnaround time for cell and gene therapy commercialization. |
| Platform Integration | Electronic batch record and statistical process control module bundling captures recurring revenue from mid-tier biotech sponsors. |
| Acquisition of Specialist Firm | Viral clearance study capability addresses capacity bottlenecks constraining gene therapy sponsor timelines. |
| Geographic Expansion | Indian biologics manufacturing clusters in Genome Valley attract validation service investment ahead of export-oriented capacity scaling. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with bioprocess validation executives, regulatory affairs leads at CDMOs, and quality management officers at biotechnology sponsors; and secondary validation through FDA guidance documents, EMA Annex 15 revisions, ISO 13485 certification databases, and biologics facility investment disclosures. Bottom-up triangulation across protocol execution volumes and top-down reconciliation against CDMO capital expenditure patterns anchored market sizing.
Forecast inputs span product type segmentation across software solutions, validation services, equipment, analytical instruments, and documentation tools; deployment models including cloud-based, on-premise, and hybrid architectures; and end-user categories from pharmaceutical firms through contract research organizations. CAGRs were derived through regression analysis of historical biologics pipeline expansion rates and regulatory mandate implementation timelines, with continuous process verification spending and single-use technology adoption curves serving as primary demand drivers across the projection horizon.
Practitioners should monitor FDA process validation guidance enforcement patterns and EMA Annex 15 documentation stringency revisions for early signals of compliance cost inflation that could alter outsourcing economics. Forecasts embed assumptions regarding polymer supply concentration stability and viral clearance study capacity expansion that warrant continuous validation against operating reality.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Custom Assays Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Riboflavin Kinase Market