
 Italy Insulin Drugs and Delivery Devices Market | 2026-2036
Italy Insulin Drugs and Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Insulin Drugs and Delivery Devices Market Foresight
Italian pharmaceutical manufacturing capacity for biologic active ingredients is rebalancing toward higher-margin analog insulin production. Novo Nordisk A/S anchors its southern European supply operations through established Italian distribution infrastructure. Sanofi competes in the pen device segment with differentiated ergonomic designs for elderly patients. Eli Lilly and Company extends its presence via partnerships with regional diabetes clinic networks across the peninsula.
Insulin drugs and delivery devices comprise recombinant human and analog insulin formulations packaged with mechanical or electronic administration systems, typically requiring cold-chain storage between two and eight degrees Celsius and subcutaneous delivery via precision-calibrated dosing mechanisms. The primary purpose centers on glycemic control for diabetic patients through exogenous hormone replacement. Insulin pumps and continuous glucose monitors are capturing margin pools as integrated closed-loop systems displace conventional syringe-based regimens in Italy's reimbursed device pathways. Subcutaneous injection remains the dominant delivery mode, though inhalation and jet injector alternatives are gaining traction among needle-averse patient cohorts.
AIFA governs national reimbursement classifications for diabetes devices, while the Ministry of Health enforces CE-marked conformity under the EU Medical Device Regulation for all pump and monitor imports. These frameworks shape market access timelines and pricing negotiations for manufacturers seeking formulary inclusion. Stakeholders must monitor how Italy's planned National Recovery and Resilience Plan investments in chronic disease digital infrastructure will reshape homecare reimbursement tiers and connected device procurement criteria.
Market Dynamics
Italy's insulin market restructuring centers on AIFA's reimbursement recalibration for closed-loop systems, which is compressing traditional pen-and-syringe procurement cycles while accelerating pump migration into homecare settings across the peninsula.
Growth Catalysts
- Regional diabetes clinic density:Northern Italy's Lombardy and Emilia-Romagna regions host concentrated specialist networks that drive advanced delivery system penetration through prescriber familiarity with pump protocols.
- AIFA device upgrade pathways:The national reimbursement framework's expanded coverage tiers for continuous glucose monitors reduce patient out-of-pocket burdens and accelerate technology turnover.
- Biologic cold-chain infrastructure:Temperature-controlled logistics networks spanning Milan, Bologna, and Naples distribution hubs enable analog insulin stability for extended rural delivery routes.
Market Restraints
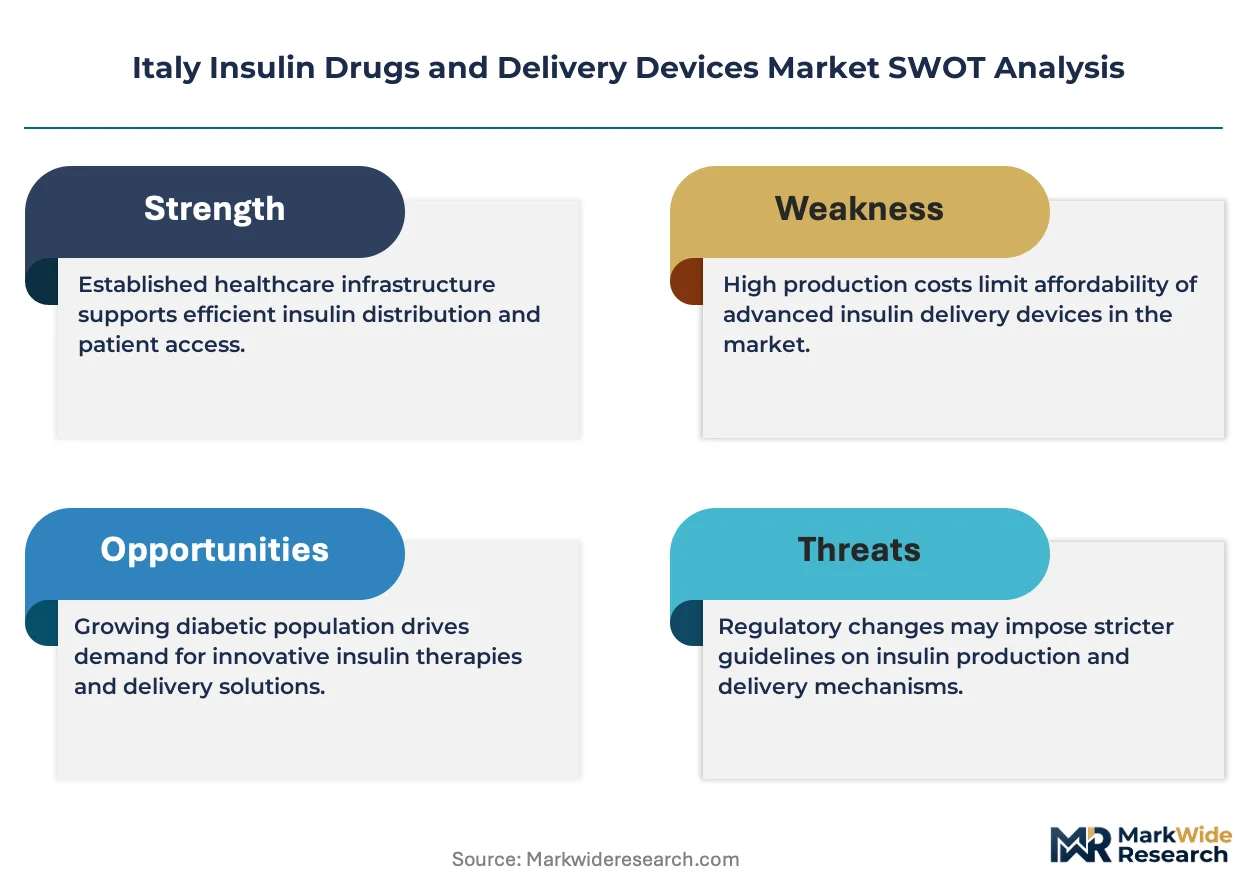
- Active pharmaceutical ingredient concentration:Recombinant insulin bulk manufacturing concentrates among three global suppliers, creating vulnerability for Italian formulation plants dependent on imported biologic feedstock.
- EU Medical Device Regulation compliance costs:CE-marked conformity assessment timelines for new pump submissions extend market access windows by 12-18 months versus prior directive periods.
- Needle-free delivery substitution:Jet injector and inhalation alternatives capture needle-averse patient cohorts in private-pay segments outside AIFA reimbursement.
Strategic Opportunities
- Southern Italy underpenetration:Campania, Puglia, and Sicily regions exhibit pump adoption rates roughly half those of northern counterparts, creating whitespace for clinic network expansion.
- National Recovery and Resilience Plan digital infrastructure:Chronic disease telehealth investments will reshape homecare reimbursement tiers and connected device procurement criteria through 2026.
- Pump-CGM convergence:Integrated closed-loop artificial pancreas systems are capturing margin pools as automated insulin delivery algorithms displace manual dosing regimens.
Industry Challenges
- Diabetes technology specialist scarcity:Certified pump trainer availability constrains patient onboarding capacity in rural Marche and Abruzzo provinces.
- Legacy system integration friction:Hospital electronic health record architectures in aging Tuscany and Veneto facilities resist seamless CGM data ingestion.
- Biologic manufacturing capex intensity:Analog insulin production requires single-use bioreactor investments that strain mid-cap Italian pharmaceutical manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Insulin Drugs and Delivery Devices Market |
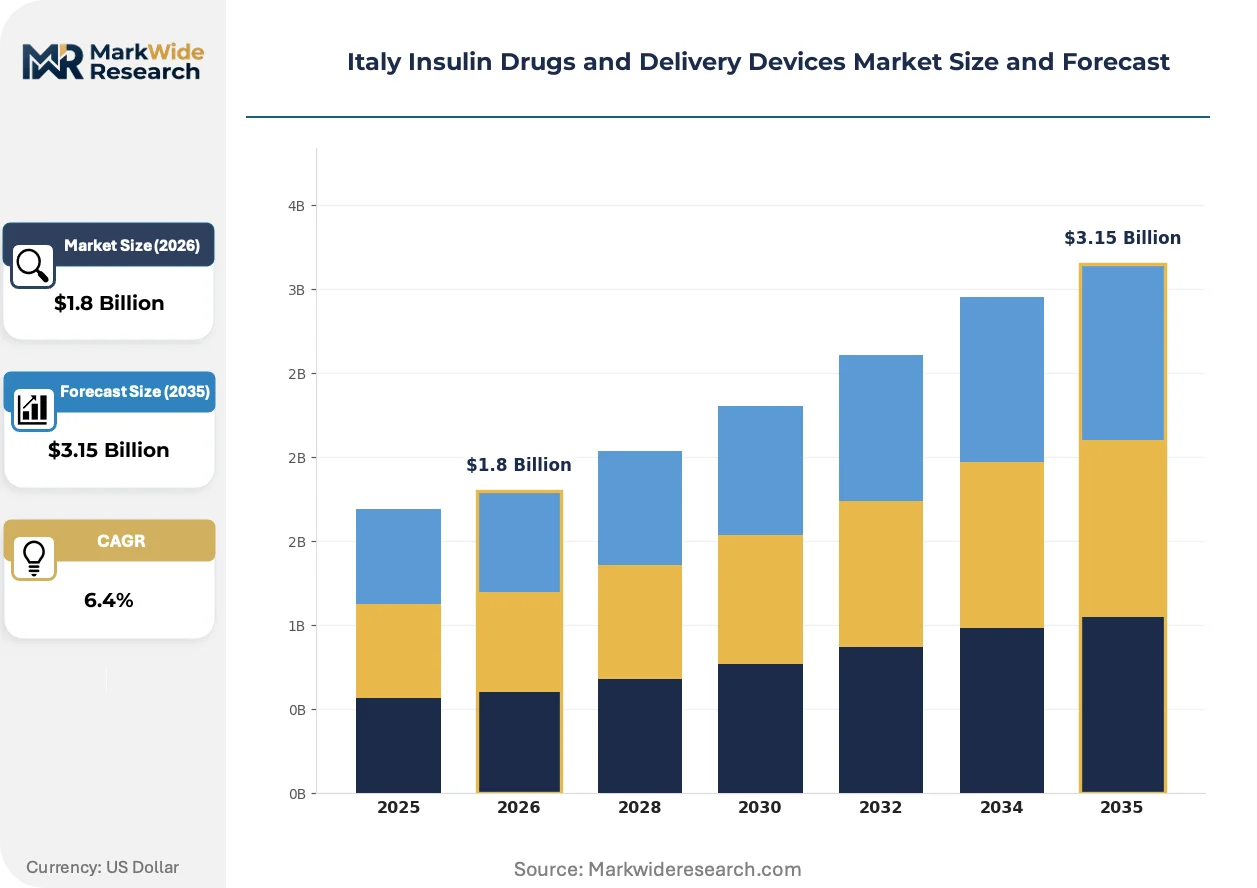
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Insulin Syringes, Insulin Pens, Insulin Pumps, Continuous Glucose Monitors Delivery Mode: Subcutaneous Injection, Intravenous Injection, Jet Injectors, Inhalation End User: Hospitals, Homecare, Diabetes Clinics, Pharmacies Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetes Management |
| Companies Covered | Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Medtronic, Becton, Dickinson and Company, F. Hoffmann-La Roche Ltd, Ypsomed Holding AG, Biocon Biologics Ltd, Insulet Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Insulin Drugs and Delivery Devices Market Shifts & Advancements
Digital integration is compressing the boundary between glucose sensing and insulin delivery, creating closed-loop architectures that reduce patient cognitive burden while shifting competitive advantage toward algorithm sophistication.
Interoperable pump platforms are modularizing hardware from software control layers. Regional diabetes clinics in Lombardy adopt these systems at twice the national average pace. This architecture enables third-party algorithm licensing and compresses device replacement cycles from five years to three.
AIFA's 2024 reimbursement recalibration for continuous glucose monitors tightens clinical evidence requirements for formulary inclusion. Italian pump manufacturers face extended health technology assessment timelines. The southern European supply chain responds by consolidating clinical trial operations within Emilia-Romagna's medical device corridor.
Patients in northern Italy's reimbursed device pathways increasingly demand unbundled after-sales service contracts separate from hardware acquisition. Traditional distributor models face margin compression. This pattern concentrates most visibly in Milan's private endocrinology practices where switching costs between pump brands have collapsed.
Italy Insulin Drugs and Delivery Devices Market Segmentation
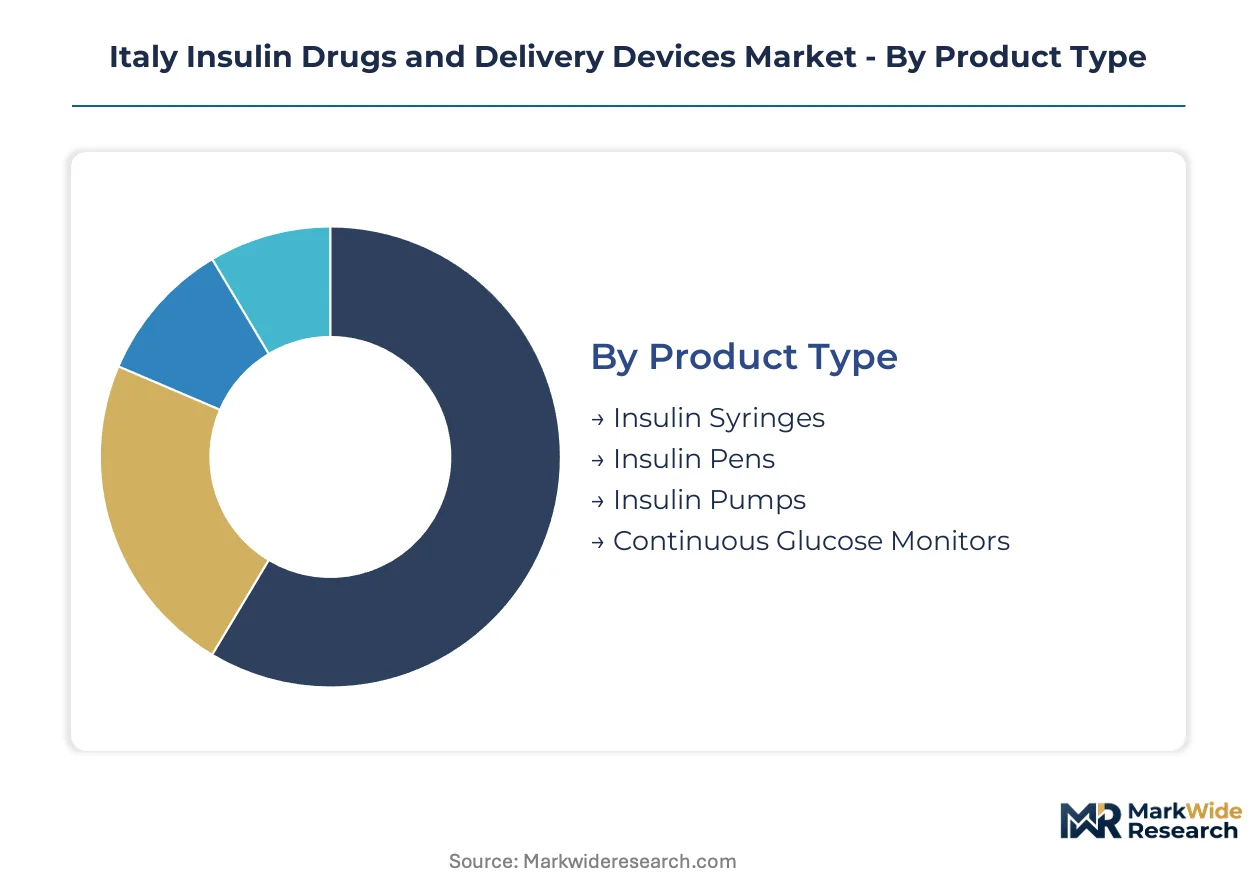
Insulin therapy segmentation in Italy reflects AIFA's reimbursement tiers and the peninsula's stark regional disparities in diabetes technology access. Device procurement patterns diverge sharply between Lombardy's reimbursed pump pathways and southern regions where syringe-based regimens persist.
Product Type:
Technology sophistication determines margin capture, with electronic systems displacing mechanical alternatives across AIFA's expanded coverage framework.
- Insulin Syringes:Conventional glass or plastic barrels with fixed needles deliver human and analog insulin via manual draw-and-inject protocols. Demand concentrates in Campania and Sicily pharmacies where pump reimbursement gaps persist and elderly patients rely on familiar administration routines.
- Insulin Pumps:Battery-powered devices with programmable basal-bolus algorithms enable continuous subcutaneous insulin infusion. Lombardy and Emilia-Romagna diabetes clinics drive adoption through certified trainer networks and streamlined AIFA authorization pathways.
- Insulin Pens:Disposable or reusable cartridge systems with dial-dose mechanisms and micro-fine needles. Penetration is deepest in Veneto's aging population where ergonomic designs reduce dexterity barriers for self-injection.
- Continuous Glucose Monitors:Factory-calibrated sensors with transmitter-receiver pairs provide real-time interstitial glucose data. Tuscany hospital systems resist seamless electronic health record integration, constraining inpatient deployment despite expanding homecare eligibility.
Mature deployment sits with insulin syringes. Newer deployment is concentrated in continuous glucose monitors.
Delivery Mode:
Route selection hinges on patient needle tolerance, reimbursement status, and clinical supervision intensity across Italy's fragmented care settings.
- Subcutaneous Injection:Abdominal, thigh, or deltoid tissue deposition via syringe, pen, or pump cannula. Homecare settings across the peninsula default to this route for its established AIFA coverage and minimal training requirements.
- Intravenous Injection:Direct bloodstream delivery reserved for perioperative glycemic control and diabetic ketoacidosis management. Hospital adoption concentrates in Rome's academic medical centers with dedicated infusion protocols.
- Jet Injectors:Needle-free liquid insulin propulsion through pressurized gas or spring mechanisms. Private-pay segments in Milan's affluent districts absorb premium pricing outside AIFA reimbursement.
- Inhalation:Pulmonary insulin absorption via dry powder or aerosolized formulations. Limited Italian availability constrains uptake despite needle-averse patient interest.
Subcutaneous injection dominates volume. Inhalation and jet alternatives are climbing the fastest in private reimbursement tiers.
End User:
Care setting determines device complexity ceiling, with institutional procurement favoring integrated systems and retail channels pushing simplicity.
- Hospitals:Acute care facilities with endocrinology wards and surgical diabetes management protocols. Tuscany and Veneto facilities struggle with legacy electronic health record architectures that resist continuous glucose monitor data ingestion.
- Homecare:Patient-directed administration with remote clinical oversight. AIFA's 2024 reimbursement recalibration accelerates pump and monitor migration into this setting across northern Italy.
- Diabetes Clinics:Specialist-led centers with certified pump trainers and structured education programs. Lombardy hosts the densest network, driving advanced delivery system penetration through prescriber familiarity with closed-loop protocols.
- Pharmacies:Community dispensaries with limited counseling capacity. Southern regions rely heavily on this channel where specialist clinic access is sparse.
Pharmacies handle the highest transaction volumes. Diabetes clinics are gaining share fastest as AIFA steers complex therapy toward specialist oversight.
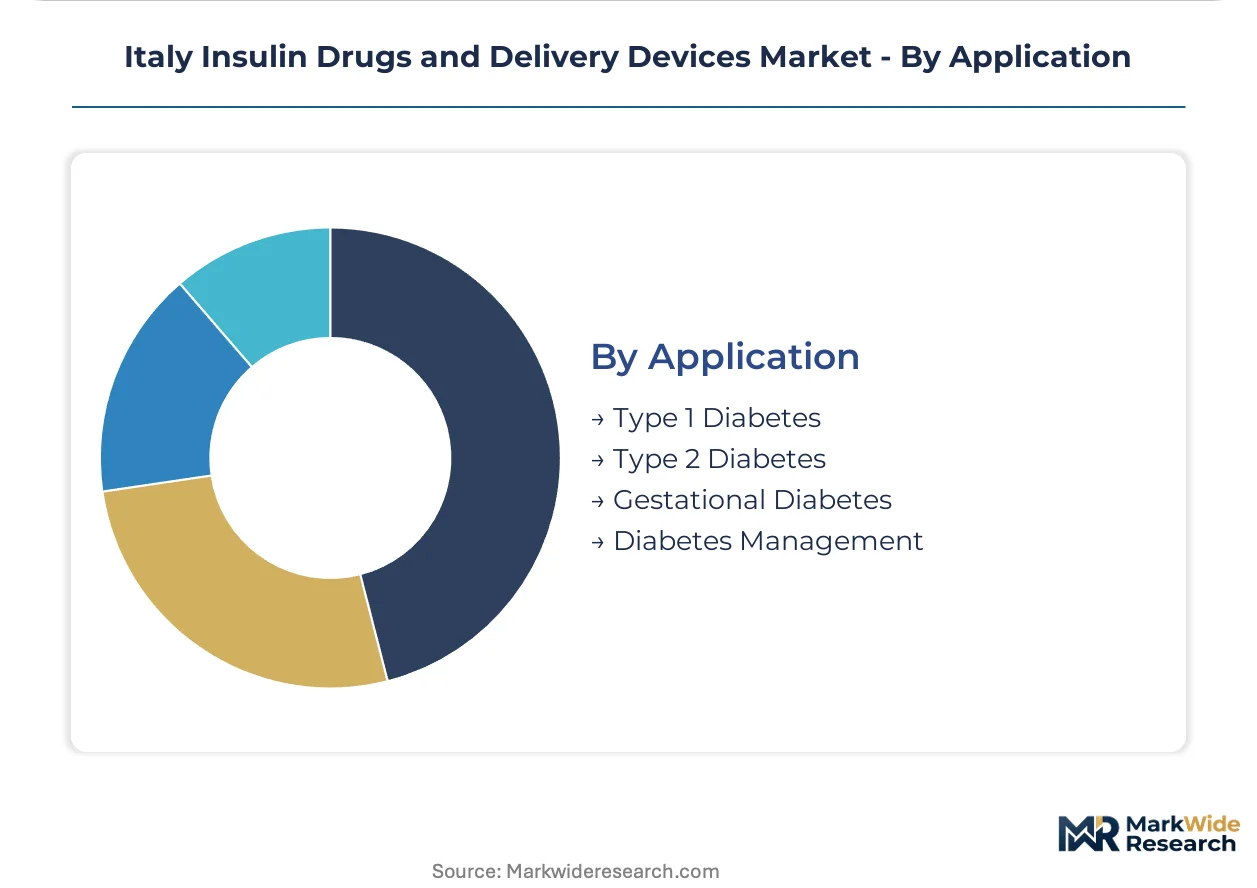
Application:
Disease severity and treatment intensity dictate device selection, with autoimmune etiology mandating intensive insulin replacement.
- Type 1 Diabetes:Absolute insulin deficiency requiring exogenous replacement throughout life. Pump-CGM closed-loop integration captures margin pools as automated delivery algorithms displace manual dosing in AIFA-reimbursed pathways.
- Type 2 Diabetes:Progressive insulin resistance with variable pharmacologic escalation. Pen-based basal insulin dominates early intensification, with pump consideration reserved for advanced cases in specialist centers.
- Gestational Diabetes:Glucose intolerance during pregnancy requiring tight glycemic targets. Short-duration therapy favors pen simplicity over pump complexity despite comparable reimbursement eligibility.
- Diabetes Management:Comprehensive care coordination encompassing screening, education, and complication prevention. Telehealth investments under Italy's National Recovery and Resilience Plan reshape procurement criteria for connected devices in this category.
Type 2 diabetes generates the largest patient volume. Type 1 diabetes shows the steepest expansion trajectory for advanced delivery system revenue per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recombinant insulin bulk manufacturing concentrates among three global suppliers, creating feedstock dependency for Italian formulation plants. Northern Italy's Lombardy region anchors domestic demand through dense specialist clinic networks. Southern distribution corridors rely on cold-chain infrastructure spanning Milan, Bologna, and Naples hubs.
Lombardy
Milan's specialist diabetes clinics drive pump adoption through certified trainer networks and streamlined AIFA authorization pathways. The regional health system reimburses continuous glucose monitors under expanded 2024 coverage tiers. Pharmaceutical distribution clusters around Milan's biologic cold-chain infrastructure enable analog insulin stability for extended rural routes.
Emilia-Romagna
Bologna anchors Italy's medical device corridor where clinical trial operations consolidate to meet tightened AIFA evidence requirements. The region hosts concentrated specialist networks that accelerate closed-loop protocol familiarity among prescribers. Temperature-controlled logistics hubs here bridge northern manufacturing capacity with central Italian patient populations.
Veneto
Aging demographics in Veneto favor ergonomic pen designs that reduce dexterity barriers for self-injection among elderly patients. Legacy electronic health record architectures in regional hospitals resist seamless CGM data ingestion, constraining inpatient deployment. Venice-Mestre distribution nodes handle substantial pen device volumes for retail pharmacy channels.
Tuscany
Florence and Siena hospital systems struggle with aging IT infrastructure that fragments continuous glucose monitor integration into electronic health records. Homecare migration accelerates despite institutional friction, driven by AIFA's reimbursement recalibration for remote patient monitoring. Regional diabetes management programs emphasize telehealth investments under Italy's National Recovery and Resilience Plan.
Campania
Naples anchors southern distribution for analog insulin formulations, though pump adoption rates lag northern counterparts by roughly half. Pharmacy channels dominate where specialist clinic access remains sparse. The port city's logistics infrastructure enables cold-chain continuity for biologic active ingredients imported from global bulk suppliers.
Italy Insulin Drugs and Delivery Devices Market Competitive Landscape
Global majors compete with regional champions across AIFA reimbursement pathways and specialist clinic relationships. The vendor base stratifies into three tiers: multinational pharmaceutical conglomerates with integrated device portfolios, mid-cap European device specialists, and emerging biosimilar manufacturers. Competitive moves center on algorithm licensing for closed-loop integration and backward integration into biologic active ingredient supply.
Among Nordic-anchored pharmaceutical conglomerates, Novo Nordisk A/S exemplifies the integrated device-drug archetype through southern European supply operations. Sanofi occupies a position within the ergonomic design specialization tier for elderly-accessible delivery systems. Eli Lilly and Company represents the partnership-driven expansion model through regional diabetes clinic network relationships across the Italian peninsula.
| Leading Market Players |
|---|
| Novo Nordisk A/S |
| Sanofi |
| Eli Lilly and Company |
| Medtronic |
| Becton, Dickinson and Company |
| F. Hoffmann-La Roche Ltd |
| Ypsomed Holding AG |
| Biocon Biologics Ltd |
| Insulet Corporation |
| Others |
Supply & Pricing Matrix
Certified pump trainer concentration in Lombardy and Emilia-Romagna creates labor-cost differentials that widen pricing-tier spreads between northern reimbursed pathways and southern pharmacy-reliant regions. AIFA's reimbursement bands compress these spreads for covered devices while private-pay segments absorb premium service bundling.
Pricing Analysis
Warranty and after-sales service unbundling from hardware acquisition is reshaping contract structures in Milan's private endocrinology practices. Three-tier pricing structure across premium, standard, and economy levels separates integrated closed-loop systems from standalone pumps and basic pen devices. Price differentiation rests on AIFA reimbursement eligibility and certified trainer network proximity. Cost compression in economy-tier syringes is intensifying because pharmacy channel consolidation in southern regions limits patient switching leverage.
Supply Chain Analysis
Dual-sourcing requirements for biologic active ingredients mandate multi-supplier qualification among Italian formulation plants dependent on imported recombinant insulin feedstock. Manufacturing concentrates in Denmark, the United States, and France for analog insulin bulk supply. Production hinges on single-use bioreactor components and temperature-controlled packaging materials. Single-source vulnerability in cold-chain logistics creates exposure for rural delivery routes. Distribution runs through Milan, Bologna, and Naples hub-and-spoke networks serving regional pharmacy and clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's insulin market reads as supply-constrained through biologic manufacturing capacity scarcity, where analog insulin production bottlenecks prop pricing power for integrated device-drug portfolios.
For Market Incumbents: To counter biosimilar erosion in human insulin segments, anchor position through backward integration into continuous glucose monitor sensor manufacturing and deepen certified trainer network density in Campania and Sicily. Lock in AIFA formulary positioning via algorithm licensing partnerships for closed-loop integration. For New Entrants and Emerging Players: Needle-averse patient cohorts in private-pay Milan districts represent the most penetrable buyer archetype for jet injector and inhalation alternatives outside AIFA reimbursement. Capture whitespace through direct-to-patient subscription models bypassing traditional distributor markups. Prioritize ergonomic design differentiation for Veneto's aging self-injection population. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-specialist software firms given AIFA's tightened clinical evidence requirements for pump-CGM integration. Five-to-ten-year viability favors targets with proprietary artificial pancreas control layers rather than commodity hardware manufacturers. Watch AIFA reimbursement recalibration timing for connected device procurement criteria as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU Medical Device Regulation compliance compresses market access timelines for new pump submissions by 12-18 months. |
| Hospital System Partnership | Tuscany and Veneto EHR integration projects unlock inpatient continuous glucose monitor deployment despite legacy architecture friction. |
| Reimbursement Strategy | AIFA's 2024 coverage tier expansion for remote patient monitoring accelerates homecare pump migration in northern regions. |
| Software Companion Development | Interoperable pump platforms enabling third-party algorithm licensing compress device replacement cycles from five years to three. |
| Manufacturing Scale-Up | Analog insulin bioreactor investments strain mid-cap Italian pharmaceutical manufacturers seeking margin expansion. |
Research Methodology
Independent corroboration across formulary database reviews, cold-chain logistics operator interviews, and AIFA reimbursement schedule analysis underwrites the qualitative findings. Primary fieldwork encompassed device development executives at multinational pharmaceutical conglomerates, regulatory affairs specialists navigating EU Medical Device Regulation transition, hospital biomedical engineers managing EHR integration projects, and GPO contracts managers at Lombardy regional health systems. Secondary validation drew from EMA medical device guidance documents, AIFA determinazioni di rimborso archives, ClinicalTrials.gov entries for closed-loop systems, and customs records for biologic active ingredient imports. Bottom-up patient population modeling triangulated against top-down pharmaceutical manufacturer revenue attribution.
Rate-of-change decomposition across the analysis window separates volume expansion from price-mix effects and technology substitution patterns. Segmentation dimensions encompassed delivery device category, reimbursement pathway status, regional clinic density cluster, and patient diabetes type. CAGRs were derived from logistic diffusion curves for pump adoption and linear extrapolation for mature syringe segments. Forecast inputs included AIFA budget impact assessments for diabetes technology and National Recovery and Resilience Plan telehealth infrastructure deployment schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to AIFA reimbursement recalibration timing and biologic manufacturing capacity expansion decisions. Deviation in EU Medical Device Regulation notified body capacity or analog insulin bulk supply concentration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Global Antibody Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
India Insulin Drug and Delivery Device Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Single-Domain Antibody Platforms Market
Biopharmaceuticals
Bioequivalence Studies Market
Biopharmaceuticals
Sodium-Dependent Glucose Co-Transporter 2 (SGLT 2) Market
Biopharmaceuticals
Prokaryotic Recombinant Protein Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Global Levofloxacin Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market