
 Isothermal Nucleic Acid Amplification Technology (INAAT) Market | 2026-2036
Isothermal Nucleic Acid Amplification Technology (INAAT) Market Size, Share, and Industry Trends Forecast 2026-2036
Isothermal Nucleic Acid Amplification Technology (INAAT) Market Analysis
Biotechnology manufacturing clusters in the United States and Germany is recalibrating instrument output to meet diagnostic lab demand for decentralized nucleic acid testing. Abbott Laboratories leverages its established point-of-care channel infrastructure to sustain placement momentum in emergency departments. Thermo Fisher Scientific anchors its position through integrated reagent-instrument bundles that lock in recurring consumable revenue. bioMerieux SA differentiates via blood culture and sepsis detection applications where speed-to-result commands premium positioning.
Isothermal Nucleic Acid Amplification Technology enables nucleic acid detection at constant temperature, eliminating thermal cycler hardware through enzymatic strand displacement mechanisms operating between 60°C and 65°C; this architecture suits resource-limited settings and field-deployable diagnostics where electricity stability remains unpredictable. LAMP-based assays occupy the dominant technology position due to primer design simplicity and inhibitor tolerance in crude sample matrices. Diagnostic Labs represent the highest-margin end user segment, while Research applications compete on volume through grant-funded instrument acquisitions across academic consortia.
FDA clearance pathways and CLIA complexity categories shape product development priorities, with manufacturers optimizing assay designs for waived or moderate-complexity status to maximize addressable site eligibility. ISO 13485 quality management systems and EU IVDR technical documentation requirements constrain market entry timelines for new platform entrants. Stakeholders must monitor regulatory divergence between FDA template guidance and notified body interpretations under the EU IVDR, as harmonization gaps will determine which platforms achieve simultaneous transatlantic commercialization.
Market Dynamics
Diagnostic laboratories are dismantling PCR-dependent workflows as enzymatic strand displacement mechanisms enable constant-temperature amplification without thermal cyclers, compressing capital requirements and expanding site eligibility for nucleic acid testing.
Growth Catalysts
- CLIA-waived test expansion:FDA's evolving point-of-care framework accelerates platform approvals for moderate-complexity laboratories, unlocking placement in physician offices and emergency departments previously excluded from molecular diagnostics.
- LAMP primer architecture:Loop-mediated isothermal amplification tolerates crude sample matrices with simpler primer design than recombinase polymerase amplification, reducing assay development timelines for infectious disease panels.
- Hospital-acquired infection surveillance:United States acute care facilities deploy decentralized testing to compress time-to-result for sepsis and bloodstream pathogen detection, bypassing centralized lab bottlenecks during outbreak response.
Market Restraints
- Enzyme supply concentration:Bst DNA polymerase production concentrates among specialized fermentation suppliers in Germany and the United States, exposing assay manufacturers to batch variability and qualification delays.
- EU IVDR technical documentation:Notified body capacity constraints under the 2017/746 regulation extend conformity assessment timelines for new platform entrants, compressing addressable market windows.
- PCR instrument installed base:Existing thermal cycler infrastructure in academic and reference laboratories creates switching friction, particularly for high-throughput workflows where marginal cost advantages favor legacy platforms.
Strategic Opportunities
- One Health veterinary diagnostics:Unpenetrated livestock and companion animal testing markets in Brazil and Australia present white space for field-deployable platforms targeting avian influenza and foot-and-mouth disease surveillance.
- Reagent rental instrument placement:Bundled consumable-locked contracts displace capital purchase models in United States diagnostic labs, capturing recurring revenue streams and lowering customer acquisition costs.
- CRISPR-LAMP convergence:Guide RNA-enhanced isothermal amplification combines specificity improvements with constant-temperature operation, opening tuberculosis and antimicrobial resistance detection applications where single-nucleotide discrimination commands premium positioning.
Industry Challenges
- Assay design bioinformatics talent:Primer architecture optimization for inhibitor-tolerant LAMP reactions requires specialized expertise scarce in contract research organizations serving mid-tier diagnostic manufacturers.
- ISO 13485 quality management implementation:Small platform developers face 12-18 month system certification timelines before EU IVDR technical file submission, consuming runway prior to revenue generation.
- Interoperability with laboratory information systems:Point-of-care instruments require HL7 FHIR integration pathways that fragment across United States health system electronic medical record vendors, complicating enterprise deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Isothermal Nucleic Acid Amplification Technology (INAAT) Market |
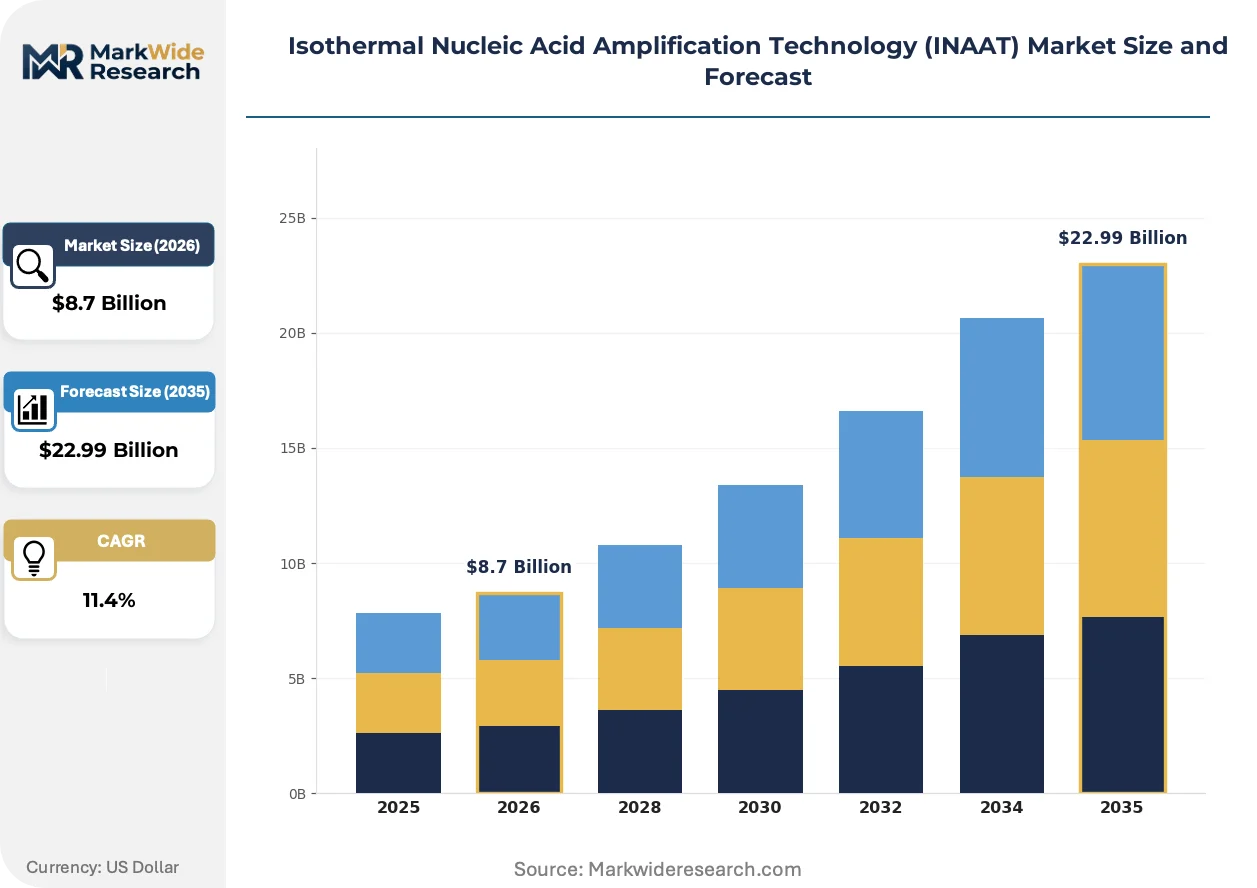
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Diagnostics, Research, Food Safety Testing, Environmental Monitoring End User: Hospitals, Academic Institutions, Diagnostic Labs, Pharmaceutical Companies Technology: LAMP, RPA, HDA, NASBA Product Type: Assays, Instruments, Reagents, Kits |
| Companies Covered | Becton Dickinson and Company, Meridian Bioscience, Abbott Laboratories, Thermo Fisher Scientific, Hologic Inc., Roche Diagnostics, bioMerieux SA, Eiken Chemical Co., Ltd., QIAGEN N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Isothermal Nucleic Acid Amplification Technology (INAAT) Market Emerging Trajectories
Enzymatic amplification architectures are fragmenting into application-specific configurations as manufacturers optimize primer chemistry, detection modalities, and sample preparation integration for distinct use cases rather than universal platforms.
Digital microfluidic cartridge design is modularizing LAMP assay execution by partitioning reagent storage, thermal control, and fluorescence detection into interchangeable subcomponents. United States point-of-care manufacturers adopt this architecture to compress development cycles for emerging pathogen panels. The approach enables rapid reconfiguration for respiratory, bloodstream, or sexually transmitted infection targets without instrument redesign.
FDA template guidance for point-of-care nucleic acid tests is tightening analytical validation requirements for self-collection and home-use scenarios, elevating clinical study burden for waived-status applications. Manufacturers now front-load usability engineering and layperson instruction validation to preempt 510(k) deficiency letters. Emergency department and urgent care segments absorb the compliance cost premium more readily than retail pharmacy channels.
Consolidated procurement by United States health system integrated delivery networks is unbundling instrument service contracts from reagent supply agreements, forcing manufacturers to compete separately on uptime guarantees and consumable pricing. Reference laboratories leverage this fragmentation to negotiate volume-tiered reagent discounts while sourcing maintenance from third-party field service organizations. The shift compresses margin capture for manufacturers dependent on bundled annuity streams.
Isothermal Nucleic Acid Amplification Technology (INAAT) Market Segmentation
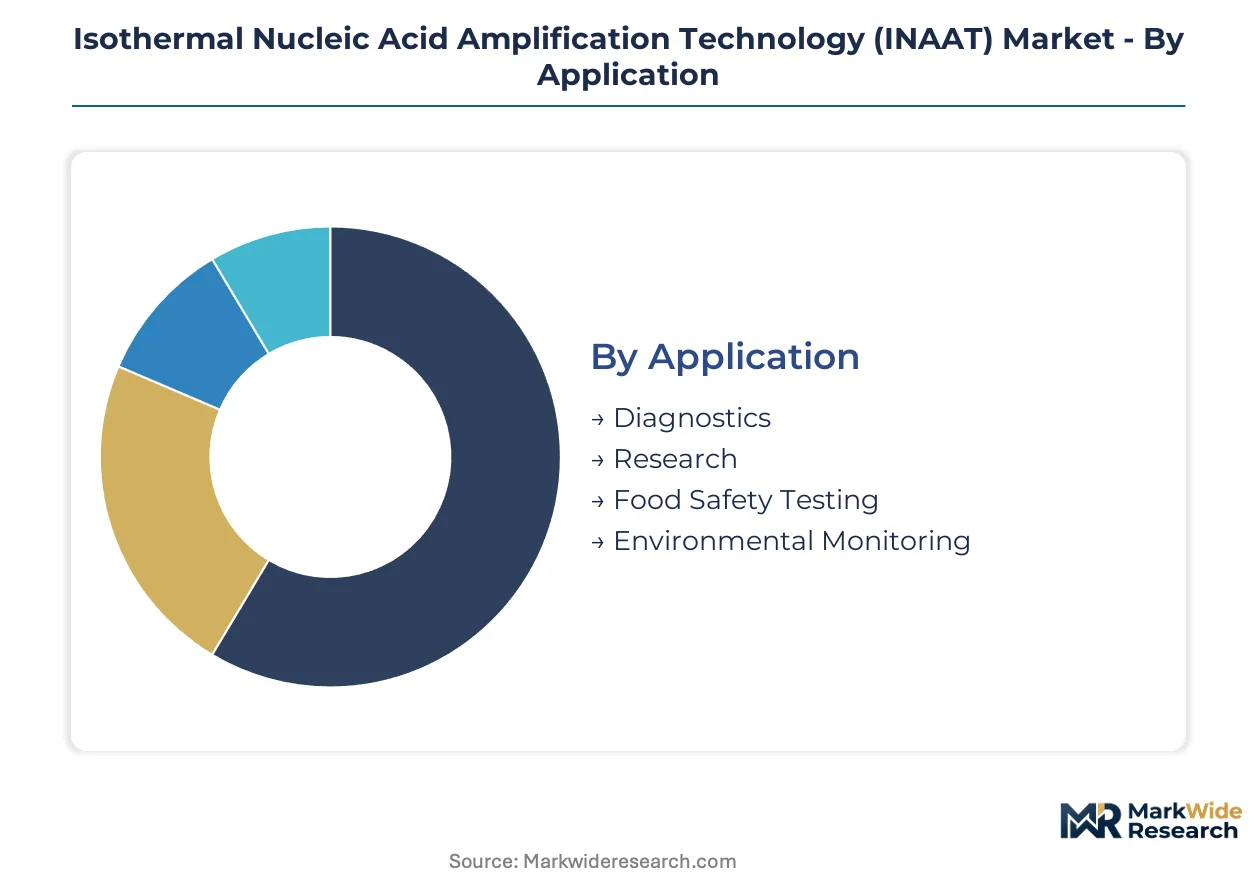
INAAT market segmentation reveals distinct margin profiles and regulatory pathways across technology architectures and use cases. Manufacturers optimize platform configurations differently depending on whether the target customer prioritizes throughput, speed, or field-deployability.
Technology:
Enzymatic amplification architectures define thermal requirements, primer complexity, and inhibitor tolerance thresholds.
- LAMP:Loop-mediated isothermal amplification employs four to six primers targeting eight distinct regions, delivering robust performance in crude lysates without nucleic acid purification. United States point-of-care manufacturers standardize on Bst DNA polymerase variants for CLIA-waived respiratory panels.
- RPA:Recombinase polymerase amplification operates at lower temperatures (37-42°C) through recombinase-mediated primer targeting, suiting battery-powered instruments for veterinary field diagnostics in Australia and Brazil.
- HDA:Helicase-dependent amplification unwinds DNA strands enzymatically rather than thermally, enabling simpler instrument design but exhibiting sensitivity to sample inhibitors.
- NASBA:Nucleic acid sequence-based amplification targets RNA through T7 polymerase-driven transcription, occupying niche applications in viral load monitoring where RNA quantification commands premium positioning.
LAMP leads on scale; RPA leads on momentum.
Application:
End-use requirements fragment platform specifications between regulated clinical environments and non-clinical surveillance contexts.
- Diagnostics:Infectious disease detection dominates instrument placements, with FDA-cleared panels for SARS-CoV-2, influenza, and respiratory syncytial virus driving United States hospital procurement cycles.
- Research:Grant-funded academic consortia acquire instruments through National Institutes of Health equipment programs, prioritizing multiplexing flexibility over regulatory certification.
- Food Safety Testing:Salmonella and Listeria detection in poultry processing facilities employs LAMP-based assays with same-shift result turnaround, bypassing 24-48 hour culture bottlenecks.
- Environmental Monitoring:Wastewater surveillance for pathogen RNA employs field-deployable RPA platforms in German municipal utilities, compressing sample-to-answer intervals for public health early warning systems.
Diagnostics commands revenue concentration; Environmental Monitoring exhibits steepest expansion trajectory.
End User:
Procurement authority and reimbursement pathways determine pricing elasticity and contract structure across customer types.
- Diagnostic Labs:High-throughput reference laboratories negotiate reagent-locked contracts with annual volume commitments, capturing favorable per-test economics through centralized batch processing.
- Hospitals:Emergency departments and intensive care units prioritize waived-status instruments for bloodstream infection panels, accepting premium pricing for CLIA complexity reduction.
- Academic Institutions:Core facilities amortize capital costs across multiple principal investigator grants, tolerating higher instrument maintenance burden for experimental protocol flexibility.
- Pharmaceutical Companies:Contract manufacturing organizations deploy isothermal platforms for rapid mycoplasma detection in cell culture, replacing 28-day culture methods with same-day molecular confirmation.
Diagnostic Labs anchor consumable pull-through; Hospitals drive placement velocity.
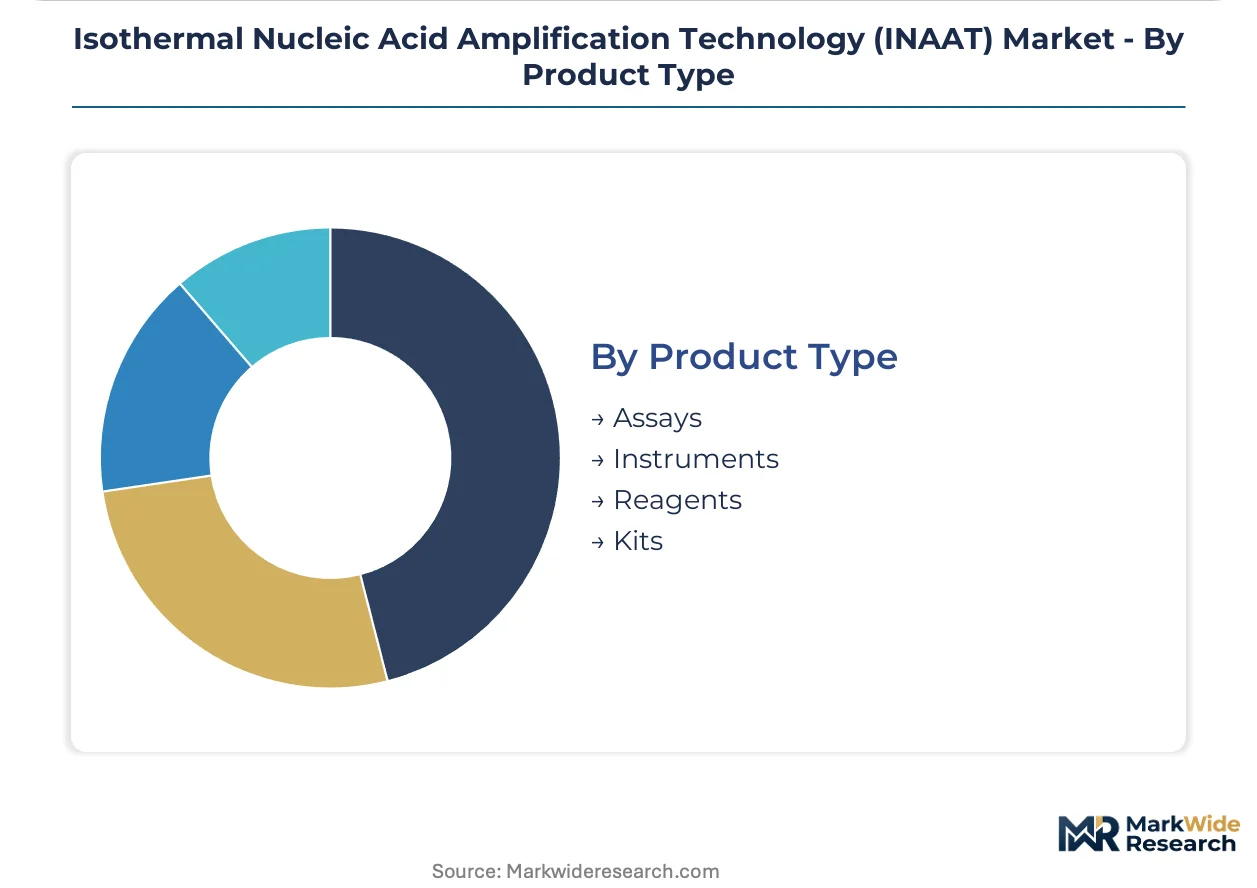
Product Type:
Revenue model architecture diverges between capital equipment, recurring consumables, and bundled assay formats.
- Reagents:Bst DNA polymerase, reverse transcriptase, and fluorescent intercalating dyes constitute the highest-margin recurring revenue stream, with enzyme batch qualification timelines constraining manufacturer agility.
- Assays:Lyophilized master mix formulations in single-use cartridges command premium positioning in point-of-care channels, eliminating cold chain requirements for decentralized deployment.
- Instruments:Fluorescence detection modules and thermal control hardware face pricing pressure from United States health system procurement consolidation, compressing upfront margin capture.
- Kits:Research-use-only configurations bundle primers, enzymes, and controls for protocol development, competing on turnaround time from order placement to bench delivery.
Reagents sustain annuity economics; Assays capture pricing power in regulated channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting instrument manufacturing toward jurisdictions with streamlined quality management certification, while diagnostic demand concentrates in markets with mature point-of-care reimbursement frameworks and active hospital-acquired infection surveillance programs.
United States
FDA's evolving template guidance for point-of-care nucleic acid tests accelerates 510(k) clearance pathways for CLIA-waived instruments, compressing time-to-market for emergency department and urgent care placements. The Centers for Medicare & Medicaid Services reimbursement policies for molecular diagnostics sustain instrument pull-through in acute care settings. Biotechnology manufacturing clusters in Massachusetts and California recalibrate production lines to meet decentralized testing demand from integrated delivery networks.
Germany
Notified body capacity constraints under EU IVDR 2017/746 extend conformity assessment timelines, creating compliance bottlenecks for new platform entrants seeking CE marking. The country's national pharmaceutical regulator maintains stringent technical documentation requirements for in vitro diagnostic devices. Industrial concentration in Baden-Württemberg and Bavaria anchors Bst DNA polymerase fermentation supply chains serving European assay manufacturers.
China
NMPA's streamlined registration pathways for innovative diagnostic devices attract domestic platform developers targeting lower-tier hospital networks with cost-optimized isothermal instruments. The country's dual carbon goals incentivize energy-efficient constant-temperature amplification over thermal cycler-dependent workflows. Manufacturing agglomeration in the Yangtze River Delta supports cartridge production for veterinary and food safety testing exports.
Japan
PMDA's priority review designation for infectious disease diagnostics accelerates regulatory timelines for tuberculosis and antimicrobial resistance detection platforms. METI's industrial policy supports miniaturized instrument development for aging-population point-of-care screening. Tokyo-Osaka corridor headquarters anchor R&D investment for LAMP-based assay automation targeting home-use scenarios.
Brazil
ANVISA's harmonization efforts with FDA technical standards reduce duplicative clinical study requirements for imported platform registrations. Foot-and-mouth disease surveillance programs in São Paulo and Minas Gerais states generate field-deployable instrument demand from agricultural inspection services. Local manufacturing partnerships with multinational diagnostics firms concentrate assembly operations in the São Paulo industrial belt.
Isothermal Nucleic Acid Amplification Technology (INAAT) Market Vendor Landscape
United States producers anchor the premium instrument tier; European specialists hold position in reagent supply and blood culture applications. Market structure consolidates around integrated reagent-instrument bundles that lock in recurring consumable revenue, with mid-tier challengers competing on assay menu breadth rather than platform performance. Three archetypes dominate: diversified life science conglomerates with point-of-care channel infrastructure, specialized molecular diagnostics firms with regulatory certification depth, and regional contract manufacturers serving research-use-only segments. Competitive moves center on reagent rental contract structures displacing capital purchases, and strategic partnerships with laboratory information system vendors to resolve interoperability fragmentation.
Among United States-based diversified manufacturers, Abbott Laboratories, Thermo Fisher Scientific, and Becton Dickinson and Company occupy positions representing distinct strategic archetypes within the competitive structure. Abbott exemplifies point-of-care channel leverage through established emergency department placement networks. Thermo Fisher Scientific anchors the integrated bundle approach, capturing recurring revenue through consumable-locked instrument contracts. Becton Dickinson and Company represents the hospital system consolidation play, targeting bloodstream infection and sepsis detection workflows where speed-to-result commands premium positioning.
| Leading Market Players |
|---|
| Becton Dickinson and Company |
| Meridian Bioscience |
| Abbott Laboratories |
| Thermo Fisher Scientific |
| Hologic Inc. |
| Roche Diagnostics |
| bioMerieux SA |
| Eiken Chemical Co., Ltd. |
| QIAGEN N.V. |
| Others |
Supply Flow & Price Mechanics
Bst DNA polymerase fermentation costs cascade through assay manufacturing tiers, with enzyme batch qualification expenses compressing margins at the reagent level while CLIA-waived instrument placements command premium pricing in United States emergency departments. The cost structure concentrates pricing power among specialized fermentation suppliers in Germany and the United States, forcing assay manufacturers to absorb upstream volatility or pass through via consumable-locked contracts.
Pricing Analysis
Distributor margins on lyophilized cartridge assays compress as United States health system integrated delivery networks unbundle instrument service contracts from reagent supply agreements. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared waived-status instruments from research-use-only kits and unvalidated components. Pricing pressure stems from consolidated procurement leveraging volume-tiered reagent discounts against third-party field service alternatives. Reference laboratories exhibit highest price sensitivity due to centralized batch processing economies, while hospital emergency departments accept premium positioning for speed-to-result sepsis panels.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from United States diagnostic laboratory networks, while specialized distributors serve mid-tier research consortia with grant-funded instrument acquisitions. Bst DNA polymerase production concentrates in Germany and the United States, with thermostable reverse transcriptase sourcing tethered to Japanese fermentation specialists. Raw material dependencies span magnesium sulfate, dNTP blends, and fluorescent intercalating dyes. Single-source vulnerability around enzyme batch qualification exposes assay manufacturers to 12-18 month certification timelines. Distribution runs through regional cold-chain logistics for lyophilized reagents, with ambient-stable cartridge formats bypassing infrastructure constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA's evolving point-of-care nucleic acid test framework accelerates platform approvals, creating sustained demand pull-through for CLIA-waived instrument placements.
For Market Incumbents: Anticipate recombinase polymerase amplification challengers eroding LAMP's technology dominance by optimizing battery-powered veterinary field platforms for Brazil and Australia. Defensive positioning requires backward integration into Bst DNA polymerase fermentation capacity in Baden-Württemberg to secure enzyme supply continuity. Channel control investments should target HL7 FHIR interoperability pathways with United States electronic medical record vendors to preempt enterprise deployment friction. For New Entrants and Emerging Players: The price-point gap between premium waived-status instruments and economy research-use-only kits offers entry leverage for moderate-complexity platforms targeting physician office laboratories. White-space concentration sits with One Health veterinary diagnostics in São Paulo state and Australian agricultural inspection services. Foot-and-mouth disease surveillance contracts provide the most penetrable procurement channel, with reagent rental contract structures displacing capital purchase models as the optimal go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 13485 quality management implementation timelines consume 12-18 month runway prior to EU IVDR technical file submission, straining small platform developers. Long-term viability centers on integrated reagent-instrument bundles capturing recurring consumable revenue across the analysis window. Acquisition targets include specialized LAMP primer design boutiques with inhibitor-tolerance expertise. The signal to monitor is notified body capacity constraints under EU IVDR 2017/746 extending conformity assessment timelines, compressing addressable market windows for non-integrated entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Rental Contract Expansion | Bundled consumable-locked agreements displace capital purchases in United States diagnostic labs. |
| CRISPR-LAMP Convergence Development | Guide RNA-enhanced amplification opens tuberculosis detection with single-nucleotide discrimination premium. |
| EU IVDR Technical File Acceleration | Notified body capacity constraints demand front-loaded quality management certification timelines. |
| Digital Microfluidic Cartridge Modularization | Interchangeable subcomponents compress development cycles for emerging pathogen respiratory panels. |
| One Health Veterinary Partnership | ANVISA-harmonized platforms target foot-and-mouth disease surveillance in São Paulo state. |
Methodological Framework
Direct dialogue with diagnostic laboratory directors, point-of-care instrument product managers, FDA regulatory affairs consultants, and CLIA compliance officers grounded qualitative assessment of platform approval pathways and procurement dynamics. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, EU IVDR notified body technical documentation, and ISO 13485 certification registries. Bottom-up instrument placement estimates triangulated against top-down molecular diagnostics spending projections across the analysis window.
Bottom-up modeling segmented volume and value outputs by technology architecture, application use case, end-user procurement authority, and product type revenue model. The analytical framework incorporated LAMP primer design complexity, RPA temperature requirements, and NASBA RNA quantification premiums as technology-specific forecast inputs. CAGRs derived from instrument placement velocity in United States hospital-acquired infection surveillance programs and reagent pull-through assumptions in diagnostic laboratory networks.
The model assumes a particular technology adoption path; alternative pathways for recombinase polymerase amplification battery-powered platforms would alter the outlook for field-deployable veterinary diagnostics. Forecasts reflect assumptions around FDA template guidance stability and EU IVDR notified body capacity normalization. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Protein Purification and Isolation Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Global Cell Isolation/Cell Separation Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Cell Culture Media Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Global DNA and RNA Banking Services Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Biobank Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Global Downstream Processing Market
Biotechnology Services
Precast Agarose Gel Market
Biotechnology Services
Molecular Methods Market