
 Global DNA and RNA Banking Services Market | 2026-2036
Global DNA and RNA Banking Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global DNA and RNA Banking Services Market Foresight
Buyer concentration among pharmaceutical companies is shifting as large sponsors consolidate vendor relationships while biotech startups fragment demand across specialized providers. Thermo Fisher Scientific dominates cold-chain logistics and automated biorepository infrastructure through its integrated instrument-to-service model. DNA Genotek Inc. specializes in saliva-based collection devices that streamline upstream sample acquisition for banking workflows. Infinity Biologix competes on flexible storage tiers designed for emerging cell-and-gene therapy developers with variable sample volumes.
DNA and RNA banking services encompass the controlled collection, processing, quality-assured preservation, and retrieval of nucleic acid specimens under documented chain-of-custody protocols, typically maintained at temperatures below minus 150 degrees Celsius in vapor-phase liquid nitrogen to prevent degradation. These services enable longitudinal genomic research, reproducible clinical biomarker validation, and regulatory-compliant specimen lifecycle management for therapeutic development. Long-term storage and automated storage systems anchor current revenue pools where capital intensity creates barriers to entry and sustains incumbent margin structures. Sample processing and cryopreservation segments are capturing accelerated demand as cell therapy developers require viable nucleic acid extraction from complex matrices.
The FDA enforces current Good Tissue Practice and informed consent documentation for human specimen banking, while the EMA's General Data Protection Regulation overlays genetic data privacy obligations that constrain cross-border sample transfer architectures. ISO 20387 biobanking standards and OECD guidelines on human biobanks shape accreditation requirements that filter market access for service providers. Stakeholders must monitor evolving jurisdictional fragmentation in genetic data sovereignty rules as biobank networks expand across multinational research consortia.
Market Dynamics
Pharmaceutical sponsor consolidation is restructuring vendor relationships, with large biopharma firms reducing biorepository partners to three-to-five preferred providers while demanding integrated informatics and automated retrieval capabilities that smaller operators cannot finance.
Growth Catalysts
- NIH-funded biobank infrastructure:The United States maintains the world's densest network of federally supported biorepositories, creating anchor demand for specialized nucleic acid processing and vapor-phase liquid nitrogen storage services.
- Cell therapy developers:CAR-T and gene therapy pipelines require viable nucleic acid extraction from complex biological matrices, accelerating demand for sample processing and cryopreservation segments.
- ISO 20387 accreditation mandates:Research consortia increasingly require certified biobanking partners, filtering market access toward providers with documented chain-of-custody protocols and quality management systems.
Market Restraints
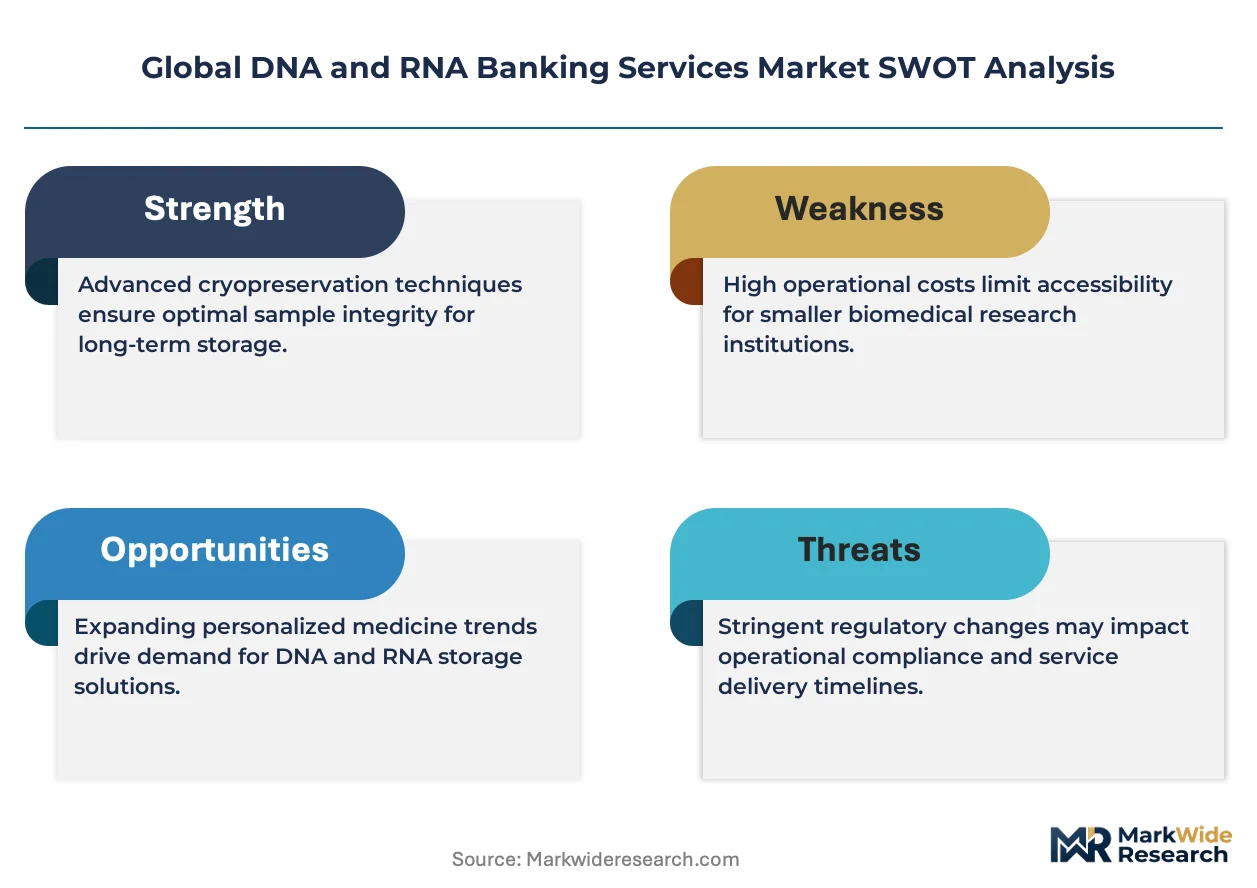
- Liquid nitrogen supply concentration:Industrial gas production clusters in the United States, Germany, and China create vulnerability for cross-border specimen movement when regional shortages occur.
- FDA-EU regulatory misalignment:Divergent informed consent documentation requirements between FDA current Good Tissue Practice and EMA GDPR genetic data privacy obligations complicate multinational biobank network architectures.
- Capital intensity barriers:Automated storage systems and cryogenic infrastructure demand seven-to-eight figure upfront investment, freezing out regional entrants and sustaining incumbent margin structures.
Strategic Opportunities
- Saudi Arabia's biobank initiatives:SFDA investment in national genomic medicine programs creates first-mover advantage for service providers establishing localized cold-chain and processing capabilities.
- Blockchain-integrated custody tracking:Distributed ledger technology convergence with biobank informatics enables immutable specimen provenance records that differentiate premium service tiers.
- Direct-to-researcher distribution:Digital platforms connecting academic investigators with remnant clinical samples bypass traditional CRO intermediaries, opening new channel economics for specialized banks.
Industry Challenges
- Cryogenic engineering talent scarcity:Qualified technicians for vapor-phase liquid nitrogen system maintenance and troubleshooting remain concentrated at incumbent providers, constraining operational scaling.
- Legacy informatics integration:Biopharma sponsors operate heterogeneous laboratory information management systems that resist standardized API connections, delaying automated retrieval deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global DNA and RNA Banking Services Market |
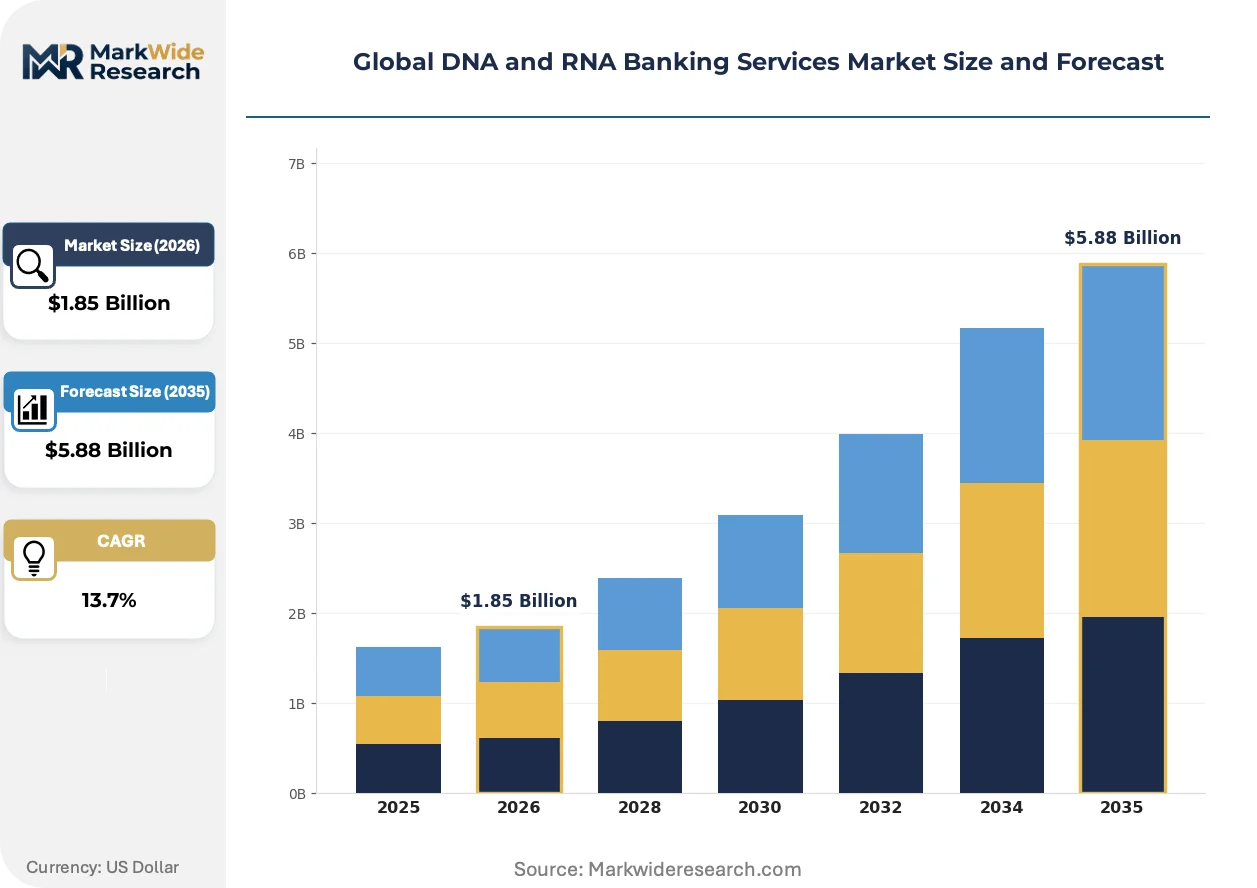
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Long-term Storage, Sample Processing, Quality Control, Data Management, Genetic Material Preservation Application: Genomic Research, Clinical Trials, Personalized Medicine, Agricultural Biotechnology, Forensic Analysis End User: Research Institutions, Pharmaceutical Companies, Forensic Labs, Agriculture Firms, Biotech Startups Storage Technology: Ultra-low Temperature Freezing, Cryopreservation, Lyophilization, Vapor Phase Storage, Automated Storage Systems |
| Companies Covered | EasyDNA, DNA Genotek Inc., 23andMe, Inc., GoodCell, ProteoGenex, Infinity Biologix, Thermo Fisher Scientific, Inc., deCODE genetics, Brooks Life Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global DNA and RNA Banking Services Market Shifts & Advancements
Automation and digitization are compressing specimen retrieval timelines while regulatory pressure on genetic data sovereignty is fragmenting cross-border biobank architectures. Three developments merit close monitoring.
Automated robotic retrieval systems is overtaking manual vapor-phase liquid nitrogen vault access in large-scale biorepositories. Pharmaceutical sponsors with longitudinal precision medicine programs now mandate sub-24-hour retrieval SLAs that only robotic systems can reliably deliver. This compression of retrieval timelines is enabling just-in-time clinical biomarker validation workflows that previously required months of advance planning.
EMA's General Data Protection Regulation enforcement against genetic data transfers is tightening cross-border sample architectures. Biobank operators must now maintain physically segregated EU data infrastructure or obtain explicit research-participant consent for international transfers. Cell therapy developers with multinational trials are responding by establishing redundant storage nodes in Ireland, the Netherlands, and Germany.
Consolidated vendor contracts are displacing fragmented multi-provider arrangements among large pharmaceutical sponsors. Biotech startups retain fragmented demand across specialized providers, but top-20 biopharma firms now require single-source accountability for chain-of-custody documentation. This bifurcation is most visible in the United States, where NIH-funded academic medical centers mirror sponsor consolidation patterns in their own biobank outsourcing decisions.
Global DNA and RNA Banking Services Market Segmentation
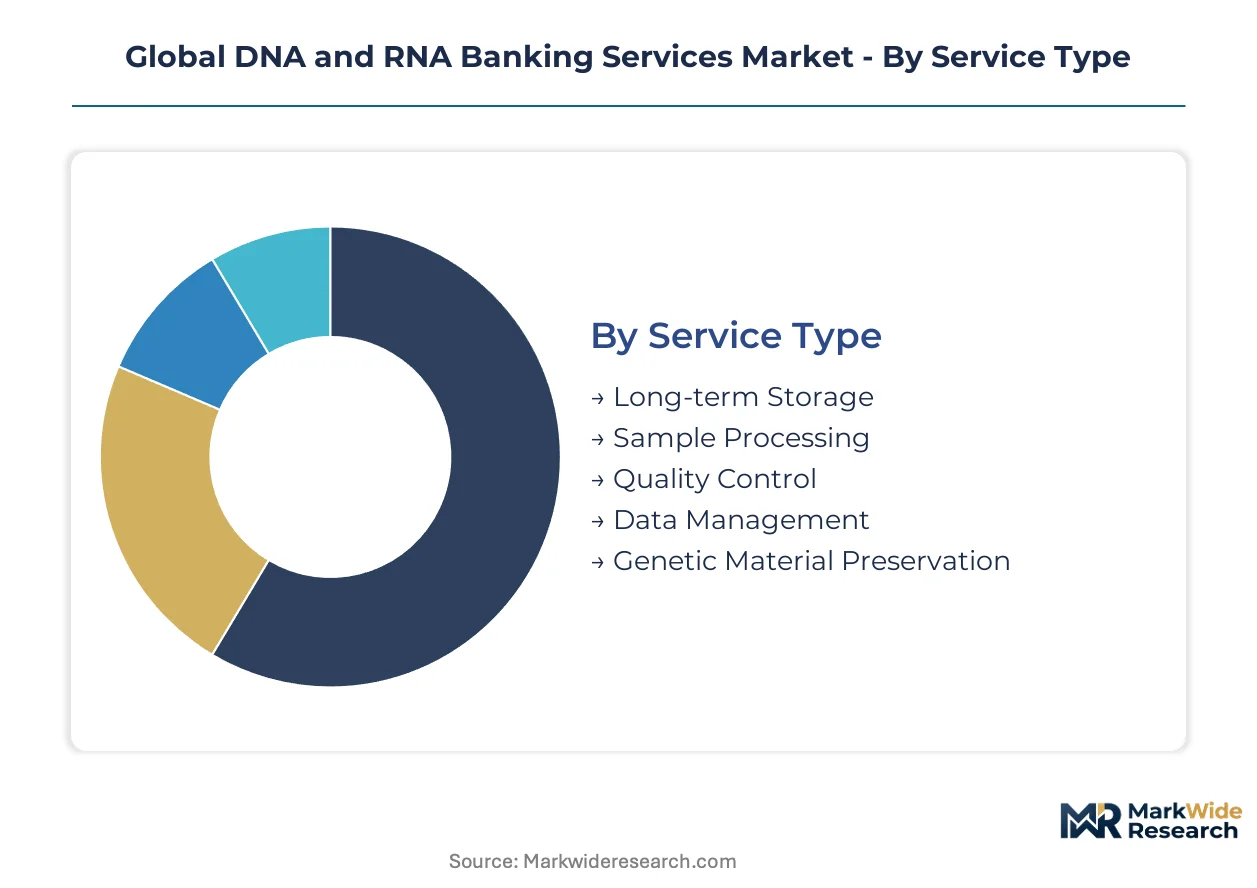
DNA and RNA banking services fragment across service modalities, application domains, and storage technologies that each impose distinct capital requirements and regulatory burdens. Understanding segment boundaries reveals where margin pools concentrate and which technology transitions are reshaping competitive positioning.
Service Type:
Supply concentration in vapor-phase liquid nitrogen infrastructure anchors revenue in long-term storage operations, while processing and data services fragment across specialized providers.
- Long-term Storage:Vapor-phase liquid nitrogen systems maintain specimens below minus 150 degrees Celsius for decades, requiring seven-figure capital deployment that sustains incumbent margin structures. Pharmaceutical sponsors in the United States consolidate contracts with three-to-five preferred providers who can demonstrate documented chain-of-custody protocols.
- Sample Processing:Nucleic acid extraction from complex biological matrices demands qualified technicians for viable cell recovery, with CAR-T developers driving demand for same-day processing SLAs. Cryogenic engineering talent scarcity constrains operational scaling at regional entrants.
- Quality Control:ISO 20387 accreditation mandates filter market access toward certified laboratories with documented quality management systems.
- Data Management:Biopharma sponsors operate heterogeneous laboratory information management systems that resist standardized API connections.
- Genetic Material Preservation:Lyophilization and alternative stabilization methods serve field collection workflows where cold-chain continuity cannot be guaranteed.
Long-term Storage absorbs the bulk of installed capacity; Sample Processing is expanding most quickly.
Application:
Cost tier differentiation separates precision medicine pipelines with longitudinal sample requirements from episodic forensic or agricultural engagements.
- Genomic Research:NIH-funded academic medical centers in the United States anchor baseline demand for population-scale biobank infrastructure with multi-decade retention horizons.
- Clinical Trials:Multinational pharmaceutical sponsors now mandate sub-24-hour retrieval SLAs that only robotic systems can reliably deliver for biomarker validation workflows.
- Personalized Medicine:Cell therapy developers require viable nucleic acid extraction from complex matrices, accelerating demand for specialized processing capabilities.
- Agricultural Biotechnology:Seed banks and crop improvement programs utilize lower-cost lyophilization methods for germplasm preservation.
- Forensic Analysis:Criminal justice system procurement operates on fixed-price contracts with standardized retention periods.
Clinical Trials command premium pricing tiers; Personalized Medicine shows the steepest expansion trajectory.
End User:
Customer type bifurcation concentrates high-value contracts among consolidated pharmaceutical sponsors while fragmenting smaller engagements across research and forensic channels.
- Research Institutions:NIH-funded biobank infrastructure in the United States creates anchor demand for specialized nucleic acid processing services with federal compliance requirements.
- Pharmaceutical Companies:Top-20 biopharma firms now require single-source accountability for chain-of-custody documentation, displacing fragmented multi-provider arrangements.
- Forensic Labs:Government procurement cycles and budget constraints limit contract values and retention period flexibility.
- Agriculture Firms:Germplasm preservation contracts emphasize cost efficiency over retrieval speed or processing sophistication.
- Biotech Startups:Variable sample volumes and uncertain funding timelines favor flexible storage tier arrangements with pay-as-you-grow pricing.
Pharmaceutical Companies dominate contract value concentration; Biotech Startups are gaining share fastest among new account formations.
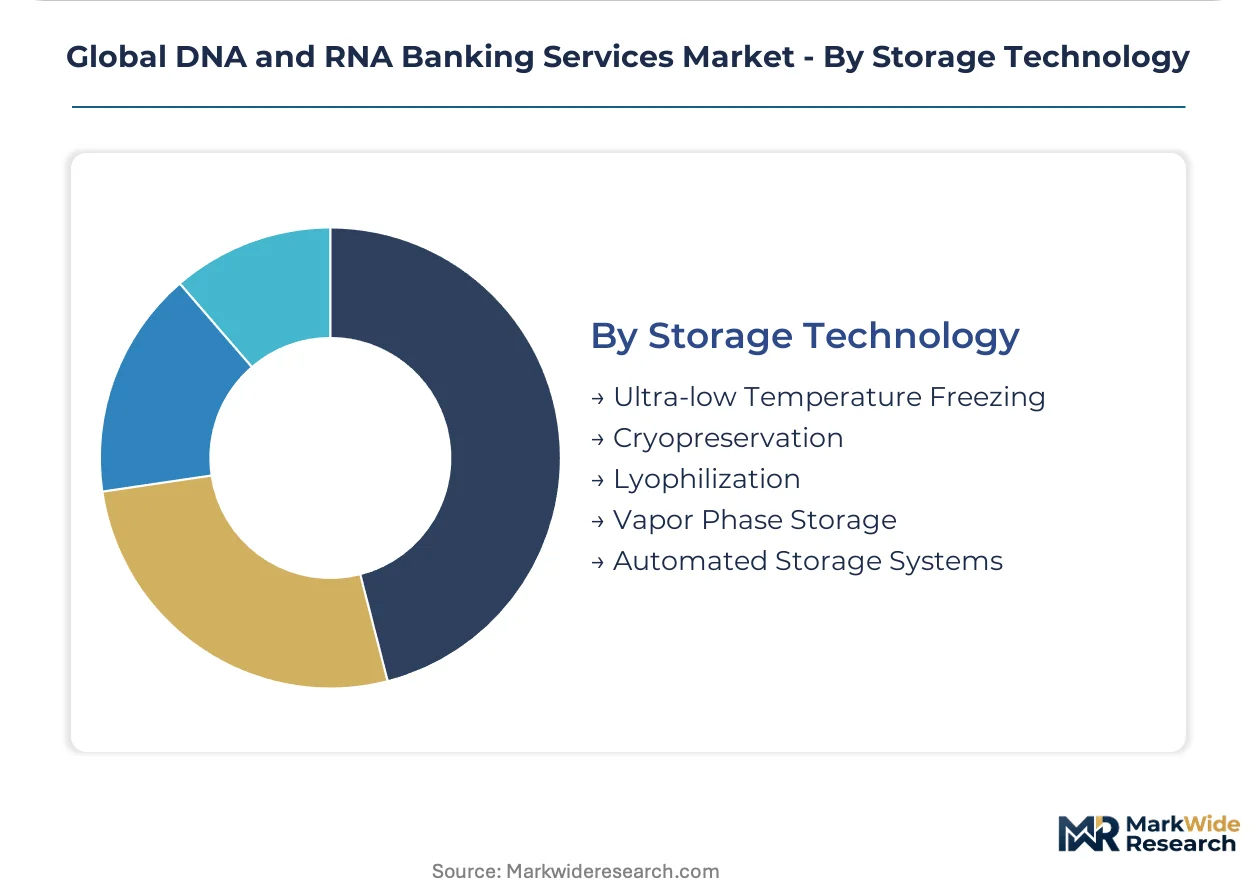
Storage Technology:
Technology maturity separates established ultra-low temperature methods from emerging automation platforms that compress retrieval timelines.
- Ultra-low Temperature Freezing:Mechanical freezer systems operate at minus 80 degrees Celsius for shorter-term nucleic acid retention, serving as an entry point for budget-constrained operations.
- Cryopreservation:Vapor-phase liquid nitrogen remains the gold standard for viable cell and tissue preservation, with industrial gas production concentration in the United States, Germany, and China creating supply vulnerability.
- Lyophilization:Freeze-drying enables ambient-temperature transport and storage for field collection workflows.
- Vapor Phase Storage:Minimizes cross-contamination risk while maintaining minus 150 degrees Celsius thermal stability for decades.
- Automated Storage Systems:Robotic retrieval enables sub-24-hour SLAs that pharmaceutical sponsors now mandate for longitudinal precision medicine programs.
Cryopreservation retains the largest installed base; Automated Storage Systems are climbing the fastest as retrieval speed becomes a competitive differentiator.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsor consolidation concentrates contract value in the United States, while regulatory fragmentation around genetic data sovereignty is forcing redundant infrastructure investments across multiple jurisdictions.
United States
NIH-funded biobank infrastructure anchors global demand for vapor-phase liquid nitrogen storage and automated retrieval systems. FDA current Good Tissue Practice enforcement tightens chain-of-custody documentation requirements for cross-border specimen movement. The Boston-Cambridge corridor concentrates cell therapy developer activity, driving demand for same-day nucleic acid processing services.
Germany
EMA GDPR genetic data privacy obligations constrain international sample transfers from EU-based biorepositories. Industrial gas production clusters in the Rhine-Ruhr region create localized supply security for cryogenic infrastructure operators. Heidelberg and Munich academic medical centers anchor population-scale biobank networks with multi-decade retention mandates.
United Kingdom
UK Biobank longitudinal cohort studies sustain baseline demand for nucleic acid preservation services with 30-plus year horizons. NHS digital transformation programs integrate biobank informatics with electronic health record systems. London-Oxford-Cambridge golden triangle concentrates precision medicine startup formation requiring flexible storage tier arrangements.
China
NMPA evolving guidance on human genetic sample retention tightens documentation requirements for biorepository operators. National genomic medicine initiatives in Beijing and Shanghai drive capital deployment toward automated storage systems. Yangtze River Delta biotech parks attract multinational pharmaceutical sponsors establishing redundant Asian storage nodes.
Saudi Arabia
SFDA investment in national genomic medicine programs creates first-mover opportunity for localized cold-chain infrastructure. Vision 2030 healthcare transformation prioritizes biobank capacity as foundational for precision medicine delivery. Riyadh and Jeddah medical cities anchor public-private partnership frameworks for nucleic acid banking service procurement.
Global DNA and RNA Banking Services Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized niches in cell therapy processing and blockchain-integrated custody tracking. The vendor base separates into three-to-five preferred providers serving consolidated pharmaceutical sponsors and fragmented specialists addressing biotech startup demand. Three archetypes dominate: integrated instrument-to-service conglomerates, saliva-based collection device specialists, and flexible storage tier operators. Competitive dynamics center on M&A consolidation of regional cryogenic facilities and strategic partnerships for automated informatics integration.
Among integrated service providers, Thermo Fisher Scientific, Inc. and Brooks Life Sciences exemplify the capital-intensive infrastructure archetype with end-to-end cold-chain control. DNA Genotek Inc. occupies a distinct position upstream, anchoring the sample collection specialization tier with streamlined acquisition workflows. Infinity Biologix represents the emerging flexible-tier entrant, serving variable-volume demand from cell-and-gene therapy developers with pay-as-you-grow structures.
| Leading Market Players |
|---|
| EasyDNA |
| DNA Genotek Inc. |
| 23andMe, Inc. |
| GoodCell |
| ProteoGenex |
| Infinity Biologix |
| Thermo Fisher Scientific, Inc. |
| deCODE genetics |
| Brooks Life Sciences |
| Others |
Supply & Pricing Matrix
Liquid nitrogen procurement costs cascade from industrial gas production clusters through three distinct pricing tiers for biobanking services. Pharmaceutical sponsors with consolidated vendor contracts absorb premium rates for automated retrieval capabilities, while academic medical centers negotiate standard-tier processing fees and biotech startups access economy-tier flexible storage arrangements.
Pricing Analysis
Volume concentration among top-20 biopharma firms splits the market into margin-rich long-term storage contracts and price-competitive processing services. Pricing stratifies across premium, standard, and economy tiers based on ISO 20387 certification status and retrieval SLA guarantees. Cost compression in sample processing is intensifying as CAR-T developers demand same-day nucleic acid extraction. Research institutions exhibit highest price sensitivity due to federal funding constraints, while cell therapy developers prioritize retrieval speed over unit cost.
Supply Chain Analysis
Vapor-phase liquid nitrogen supply rests on industrial gas production concentration in the United States, Germany, and China. Cryogenic infrastructure components draw from German precision engineering suppliers and Chinese steel fabrication. Single-source vulnerability in specialized cryogenic engineering talent constrains operational scaling. Distribution runs through cold-chain logistics partnerships with temperature-validated transport networks serving biorepository facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic engineering talent scarcity props pricing power for incumbent operators with qualified technician pipelines. Capacity bottlenecks in automated storage system deployment sustain margin structures despite processing segment competition.
For Market Incumbents: Anticipate blockchain-integrated custody tracking as a differentiation requirement from consolidated pharmaceutical sponsors. Defend market position by deepening ISO 20387 accreditation investment and securing exclusive cryogenic engineering talent pipelines. Automated informatics integration partnerships address legacy LIMS connectivity barriers that delay contract renewals.
For New Entrants and Emerging Players: Cell therapy contract research organizations represent the most penetrable channel partner type for specialized processing capabilities. Target Saudi Arabia's SFDA-funded genomic medicine programs for first-mover infrastructure deployment. Direct-to-researcher digital platforms bypass traditional CRO intermediaries with remnant clinical sample access.
For Investors and Strategic Acquirers: FDA-EU regulatory misalignment deepening is the leading indicator that redundant storage node strategies will drive acquisition premiums. Five-to-ten year viability favors automated storage system operators with established vapor-phase liquid nitrogen infrastructure. Watch for EMA GDPR enforcement actions against cross-border genetic data transfers as the signal for regional consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain-Integrated Custody Tracking | Immutable specimen provenance records differentiate premium service tiers for pharmaceutical sponsors. |
| Automated Storage System Deployment | Robotic retrieval enables sub-24-hour SLAs mandated by longitudinal precision medicine programs. |
| Cryogenic Engineering Talent Acquisition | Qualified technician pipelines constrain operational scaling and sustain incumbent margin structures. |
| Regional Redundant Node Establishment | Ireland, Netherlands, and Germany storage addresses EMA GDPR genetic data transfer restrictions. |
| ISO 20387 Accreditation Investment | Certified quality management systems filter market access for research consortium contracts. |
Research Methodology
FDA guidance documents, EMA regulatory filings, and ISO 20387 accreditation records formed the secondary backbone for compliance framework analysis. Primary interviews with biorepository operations directors, cryogenic engineering specialists, pharmaceutical procurement managers, and cell therapy development executives combined with secondary validation. ClinicalTrials.gov biobank infrastructure disclosures and NIH funding databases anchored demand-side quantification. Bottom-up service provider capacity estimates and top-down pharmaceutical R&D spending allocation triangulated market sizing.
Historical trendline analysis of vapor-phase liquid nitrogen storage deployment and automated system adoption informed projection modeling across service type, application domain, storage technology, and end-user category dimensions. CAGRs derived from segment-level growth rate reconciliation with macro pharmaceutical pipeline indicators. Cell therapy clinical trial expansion rates and precision medicine program formation counts served as DNA and RNA banking-specific forecast inputs throughout the projection horizon.
Caveats apply where FDA-EU regulatory convergence or liquid nitrogen supply disruption could materially shift the outlook. Forecasts reflect assumptions regarding sustained NIH funding levels and pharmaceutical sponsor consolidation patterns. A small set of named triggers—cryogenic engineering wage inflation, EMA GDPR enforcement intensity, and SFDA procurement timeline acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Global Culture Media Market
Biotechnology Services
Acetylglucosamine Market
Biotechnology Services
Biologics CDMO Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Global Protein Binding Assay Market
Biotechnology Services
Biobanking Market
Biotechnology Services
Global Molecular Biology Enzymes and Kits and Reagents Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Mirna Tools and Services Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Recombinant Proteins Manufacturing Services Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market