
 Cell Analysis Market | 2026-2036
Cell Analysis Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Analysis Market Intelligence
The bundling of analytical instruments with proprietary reagents and software is shifting buyer procurement towards integrated ecosystem solutions. Thermo Fisher Scientific leverages its extensive portfolio to provide these comprehensive workflow packages. Becton, Dickinson and Company specializes in high-throughput flow cytometry platforms, a critical component in immunology and oncology research. Danaher Corporation competes through a multi-brand strategy, offering specialized instruments across various cell analysis modalities, from imaging to sorting.
Cell analysis encompasses the quantitative and qualitative measurement of cellular characteristics, often on a single-cell basis. Techniques frequently employ light scattering, fluorescence detection, or electrical impedance to profile cell populations with high precision. The primary purpose is to elucidate biological processes, support drug discovery, and advance clinical diagnostics. Flow Cytometers continue to be a foundational product category, while the Cancer Research application segment commands significant investment. Use in academic institutions represents a mature and stable end-user base.
Regulatory frameworks, including the US FDA's 21 CFR Part 11 and the EU's In Vitro Diagnostic Regulation (IVDR), govern instrument software and data integrity. Adherence to ISO 13485 quality management standards is also critical for manufacturers selling into clinical and diagnostic settings. These regulations mandate stringent validation, influencing instrument design and market access. Future vendor selection will hinge on providing robust compliance support across key international jurisdictions.
Market Dynamics
The convergence of high-throughput instrumentation with advanced bioinformatics is the central force shaping the cell analysis market. Demand for deeper biological insights at a single-cell level, particularly from personalized medicine and oncology research, is driving innovation in integrated analytical systems.
Growth Catalysts
- Single-Cell Multi-Omics:The ability to simultaneously measure multiple analytes like DNA, RNA, and proteins from a single cell provides unprecedented resolution for disease mechanism studies, accelerating drug discovery pipelines in the pharmaceutical industry.
- Personalized Medicine Expansion:Intensified investment in oncology and immunology research creates sustained demand for advanced cell characterization tools, particularly flow cytometers and high-content imagers, to develop targeted therapies and companion diagnostics.
- Government Research Funding:National initiatives, such as the Cancer Moonshot in the United States, provide significant capital for academic and research institutions, supporting the procurement of cutting-edge cell analysis platforms and sustaining a core end-user base.
Market Restraints
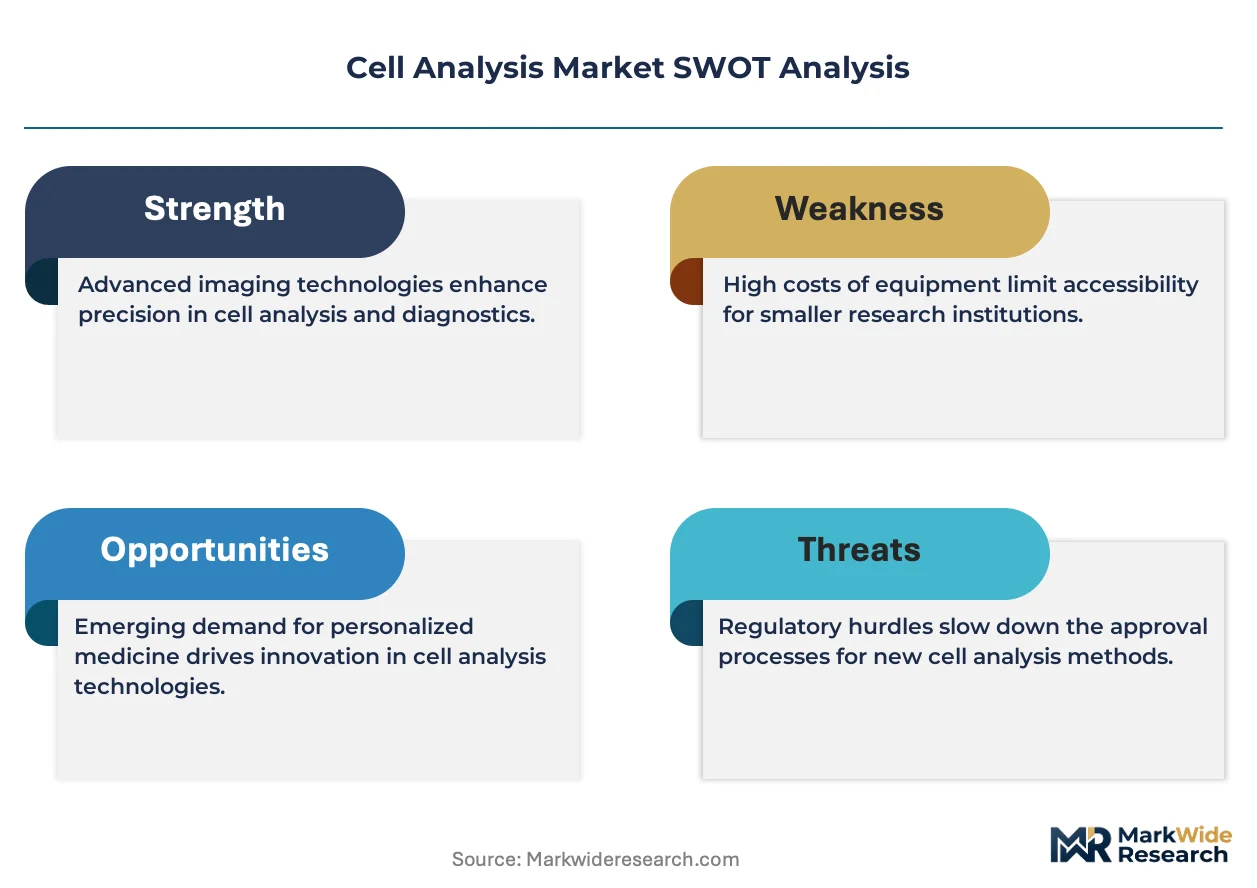
- High Capital Investment:The substantial upfront cost of sophisticated instruments, such as high-parameter spectral flow cytometers and automated microscopy systems, presents a significant barrier to adoption for smaller academic labs and biotech startups with limited budgets.
- Computational and Storage Bottlenecks:Generating vast datasets from high-throughput single-cell experiments creates significant challenges in data storage, processing power, and bioinformatics infrastructure, limiting the scale of research projects.
- Regulatory Compliance Burden:The stringent validation and documentation requirements mandated by regulations like the European Union's In Vitro Diagnostic Regulation (IVDR) increase development costs and extend timelines for bringing new clinical instruments to market.
Strategic Opportunities
- Expansion into Agricultural Biotech:Applying cell analysis techniques for plant genomics, such as protoplast sorting and analysis, opens new application frontiers in crop improvement, disease resistance research, and biofuel development.
- AI-Powered Image Analysis:The convergence of artificial intelligence with high-content imaging enables automated, quantitative analysis of complex cellular phenotypes, offering opportunities to enhance drug screening efficiency and diagnostic accuracy.
- Clinical Laboratory Penetration:Developing more compact, user-friendly, and automated flow cytometers tailored for routine clinical diagnostics can capture significant value in hospital laboratories and decentralized testing sites, especially in emerging economies.
Industry Challenges
- Bioinformatics Talent Scarcity:A pronounced shortage of data scientists and bioinformaticians with the specialized skills to analyze and interpret complex, multi-modal single-cell datasets hinders the ability of organizations to extract maximum value from their instrument investments.
- Lack of Data Standardization:The absence of universally accepted standards for data formats and experimental protocols across different instrument platforms complicates data comparison and reproducibility, particularly for large, multi-center clinical trials and collaborative research.
- Legacy System Integration:Integrating new, advanced cell analysis instruments with existing Laboratory Information Management Systems (LIMS) and data archives often requires custom software development, creating operational friction and delaying deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Analysis Market |
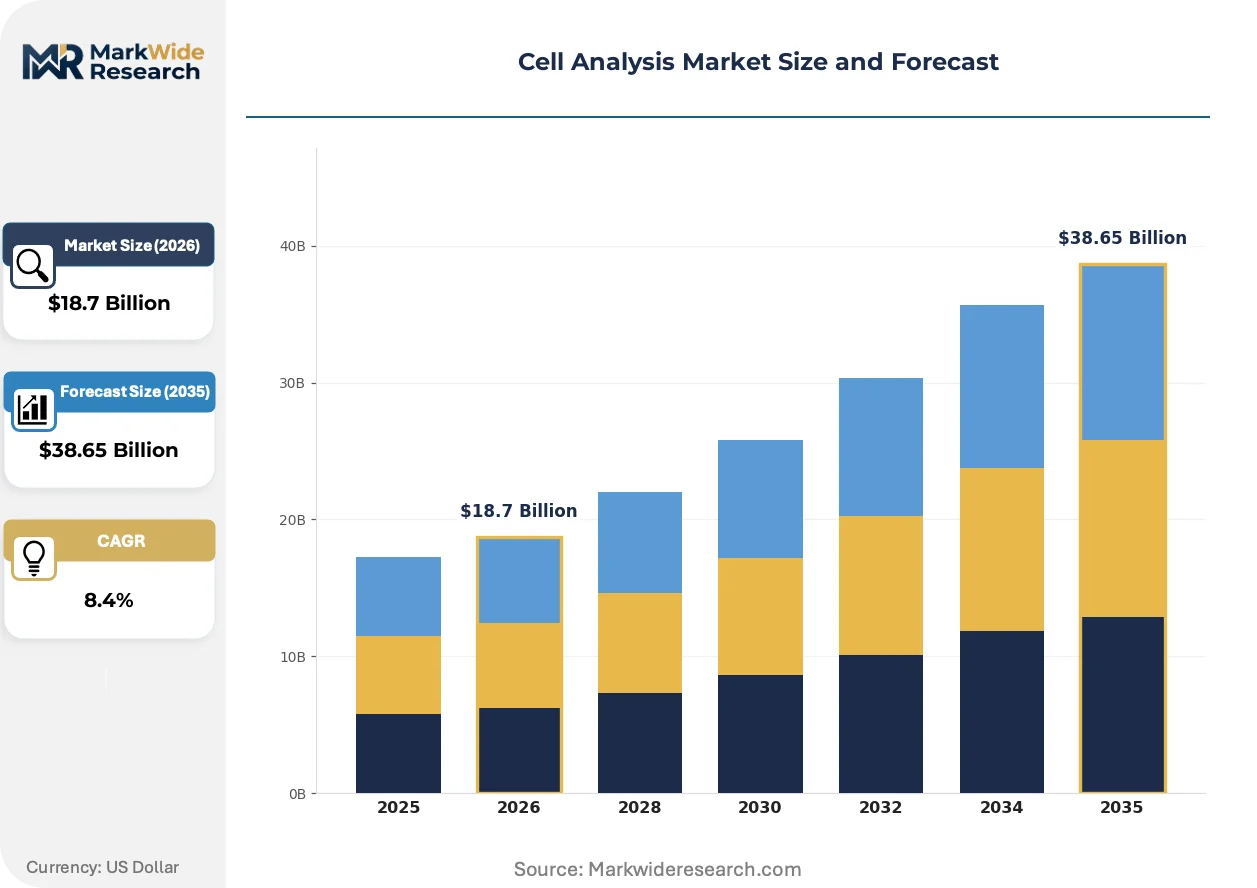
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Cytometers, Cell Counters, Cell Imaging Systems, Cell Sorters, Microplates, Microfluidic Devices Technology: Fluorescence, Imaging, Electrical Impedance, Label-Free, Microfluidics, Spectroscopy Application: Cancer Research, Immunology, Drug Discovery, Microbiology, Stem Cell Research, Toxicology End User: Academic Institutions, Biotechnology Firms, Pharmaceutical Manufacturers, Clinical Research Organizations, Contract Research Organizations |
| Companies Covered | Thermo Fisher Scientific, Becton, Dickinson and Company, Danaher Corporation, Merck KGaA, Agilent Technologies, Bio-Rad Laboratories, 10X Genomics, Miltenyi Biotec, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Analysis Market Strategic Shifts & Innovations
The market's evolution is defined by a technological push towards spatial context and a commercial pull towards integrated, workflow-centric solutions. Automation and software are becoming as critical as the core instrumentation, shifting the basis of competition toward data quality and analytical power.
Spatial transcriptomics is a transformative technology that visualizes gene expression patterns within the intact tissue environment. Pharmaceutical and academic researchers in oncology and neurodegenerative disease are rapidly adopting this method to understand cellular interactions in their native context. This technology is integrating single-cell resolution with spatial data, creating a more complete picture of tissue biology and disease pathology.
Regulatory frameworks governing data integrity, such as the US FDA's 21 CFR Part 11, are heavily influencing instrument software design. This rule requires electronic records to be trustworthy and reliable, mandating features like secure audit trails and electronic signatures for systems used in clinical trials and manufacturing. Consequently, instrument vendors serving the pharmaceutical and clinical diagnostics segments must invest heavily in developing compliant software to ensure market access.
A notable behavioral change is the move toward procuring complete ecosystems that bundle instruments with proprietary reagents and dedicated software. This model is supplanting the piecemeal acquisition of components, as it offers users standardized workflows, simplified support, and reduced validation overhead. This trend is most visible within large biotechnology firms and contract research organizations in the United States and China.
Cell Analysis Market Segmentation
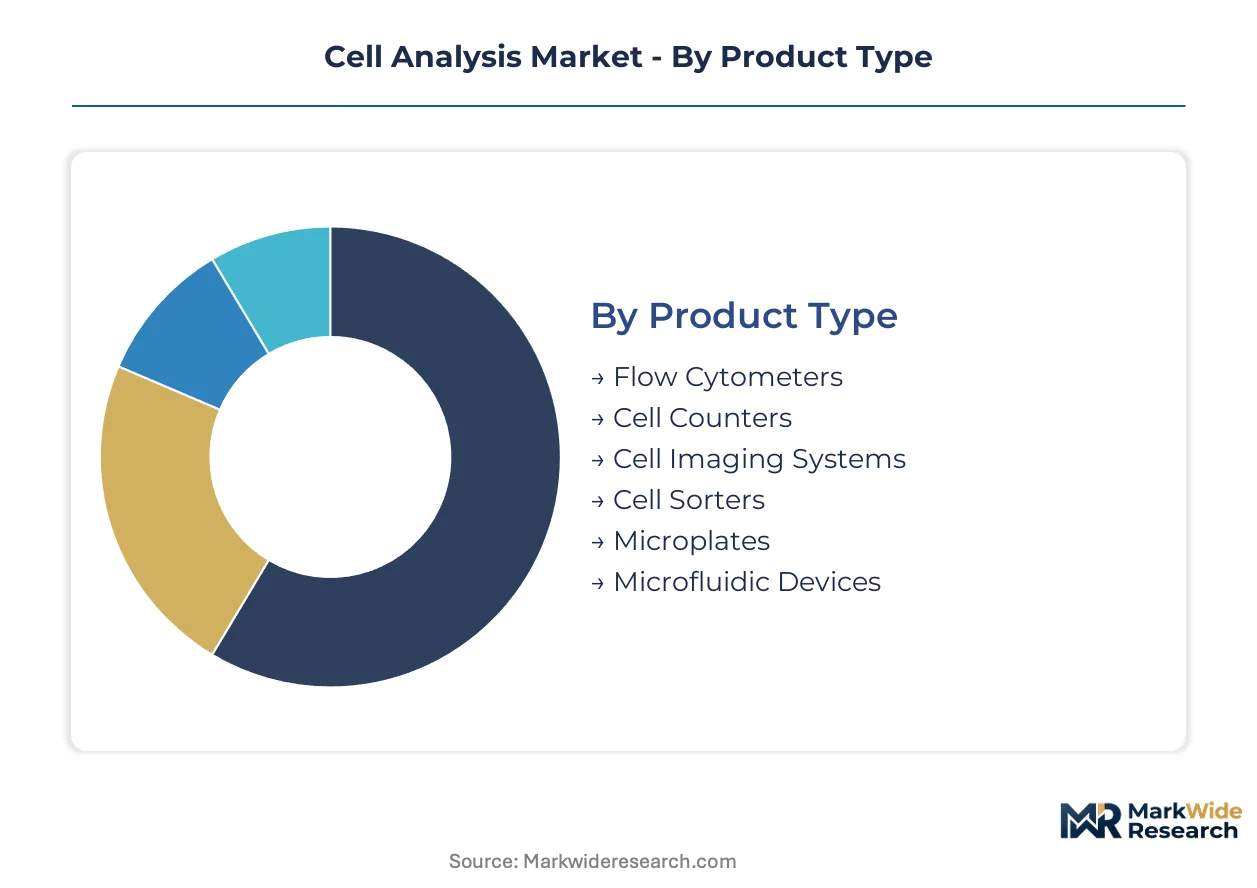
The Cell Analysis Market is highly diversified, reflecting varied research needs and operational scales. Understanding market segmentation reveals where innovation is concentrating and how procurement strategies are evolving across different user groups. This segmentation provides clarity on the distinct demands driving product development and end-user adoption.
Product Type:
The upgrade and replacement cycles for cell analysis instruments significantly influence product type segmentation, driving demand for advanced capabilities. New platforms often integrate multiple functionalities, appealing to researchers seeking comprehensive workflow solutions.
- Flow Cytometers:These foundational instruments quantify and sort cells based on light scattering and fluorescence properties, critical for immunology and oncology research applications. High-throughput spectral flow cytometers are seeing increased adoption in academic and pharmaceutical settings.
- Cell Imaging Systems:These systems capture high-resolution images of cells and tissues, often integrating AI for automated analysis of complex phenotypes. Demand is driven by drug screening efficiency and the need for spatial context in oncology research.
- Cell Counters:These devices provide rapid, accurate enumeration of cell populations, essential for cell culture quality control and basic research.
- Cell Sorters:Specialized instruments isolate specific cell populations with high purity, crucial for downstream genomic and proteomic analyses.
- Microplates:Standardized multi-well plates facilitate high-throughput assays and cell culture, widely used in drug discovery and screening.
- Microfluidic Devices:These miniaturized platforms enable precise control over small fluid volumes for single-cell analysis and rare cell detection.
Volume placements concentrate in Flow Cytometers; the faster expansion belongs to Cell Imaging Systems.
Technology:
Technology segmentation highlights the diverse analytical principles applied across various cell analysis applications, each offering distinct advantages for cellular characterization. The choice of technology often depends on the desired resolution, throughput, and biological question.
- Fluorescence:This established technology uses fluorescent probes to detect specific cellular components, offering high precision for profiling cell populations. It remains a cornerstone for many cell analysis workflows in academic institutions.
- Imaging:Encompassing brightfield, confocal, and high-content microscopy, imaging provides spatial and morphological data, integrating with multi-omics for tissue biology insights. AI-powered image analysis is transforming drug discovery and diagnostics.
- Electrical Impedance:This label-free method measures changes in electrical properties as cells pass through a microchannel, used for cell counting and viability assessment.
- Label-Free:Technologies like Raman spectroscopy or quantitative phase imaging analyze cells without exogenous labels, reducing sample perturbation and workflow complexity.
- Microfluidics:Miniaturized systems manipulate fluids at the microscale for precise single-cell handling, enabling advanced biological studies and diagnostics.
- Spectroscopy:Techniques such as mass spectrometry or Raman spectroscopy provide detailed molecular composition analysis of cells, supporting biomarker discovery.
Fluorescence remains a core technology; Imaging techniques are gaining share fastest.
Application:
The maturity of research areas heavily shapes the application segmentation within cell analysis, influencing investment priorities and technological advancements. Specialized tools are developed to meet the unique requirements of each research domain.
- Cancer Research:This segment commands significant investment, driving demand for advanced single-cell analysis tools to understand tumor heterogeneity and develop personalized therapies. National initiatives like the Cancer Moonshot in the United States provide substantial funding.
- Drug Discovery:Cell analysis accelerates drug discovery pipelines by enabling high-throughput screening, target validation, and toxicity assessment. Single-cell multi-omics provides unprecedented resolution for mechanism of action studies in pharmaceutical manufacturers.
- Immunology:Flow cytometry is foundational for profiling immune cell populations, essential for vaccine development, autoimmune disease research, and immunotherapy monitoring.
- Microbiology:Cell analysis techniques are used to study microbial growth, antibiotic resistance, and host-pathogen interactions in academic and biotechnology firms.
- Stem Cell Research:Advanced cell sorting and imaging tools are critical for isolating, characterizing, and monitoring stem cell differentiation for regenerative medicine.
- Toxicology:Cellular assays assess the cytotoxic effects of compounds, supporting preclinical safety evaluations for new pharmaceutical candidates.
Cancer Research drives substantial investment; Drug Discovery demonstrates the steepest expansion trajectory.
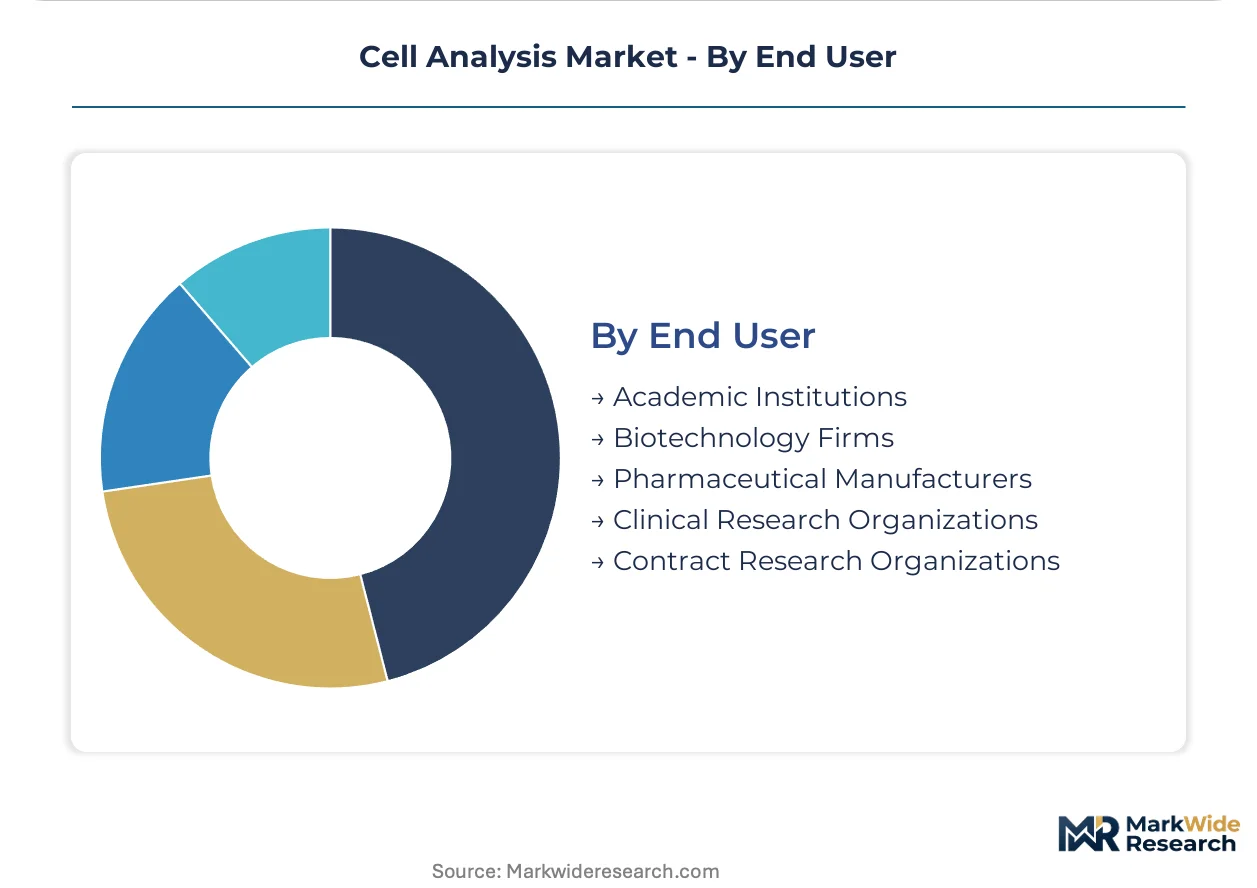
End User:
Different customer types exhibit distinct procurement patterns, defining the end-user segmentation and influencing vendor strategies. Regulatory compliance and scale of operations are key considerations for each group.
- Academic Institutions:These institutions represent a mature and stable end-user base, driven by government research funding and the pursuit of fundamental biological insights. They often prioritize cutting-edge technologies.
- Biotechnology Firms:These firms are key adopters of integrated ecosystem solutions, leveraging advanced cell analysis for drug development and diagnostics. They seek comprehensive workflow packages from vendors like Thermo Fisher Scientific.
- Pharmaceutical Manufacturers:This segment requires high-throughput, compliant instruments for drug discovery, development, and clinical trials. Adherence to regulations like the US FDA's 21 CFR Part 11 is critical.
- Clinical Research Organizations:CROs utilize cell analysis for managing clinical trials, requiring robust and validated instruments for consistent data generation.
- Contract Research Organizations:CROs provide specialized research services, often investing in diverse cell analysis platforms to support multiple client projects across various therapeutic areas.
Academic Institutions form a stable base; Biotechnology Firms lead in new technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global cell analysis market exhibits a notable production-consumption divide, with advanced research and manufacturing capabilities concentrated in specific geographies. Demand for deeper biological insights, especially from personalized medicine and oncology research, drives procurement in these key regions. This geographic concentration influences innovation and regulatory adherence across the industry.
United States
The United States anchors significant demand for cell analysis tools, driven by intensified investment in oncology and immunology research. National initiatives, such as the Cancer Moonshot, provide substantial funding for academic and research institutions. Major biotechnology and pharmaceutical research clusters in Boston and the San Francisco Bay Area lead in advanced cellular studies and integrated ecosystem solutions.
China
China demonstrates robust demand for cell analysis, particularly within its expanding biotechnology and pharmaceutical sectors. The country's regulatory bodies are increasingly aligning with international standards, influencing instrument validation protocols. Research and development hubs in Shanghai and Beijing are key centers for advanced cellular studies, fostering innovation in integrated analytical systems.
Germany
Germany represents a strong European market for cell analysis, fueled by a mature academic base and a thriving pharmaceutical industry. The European Union's In Vitro Diagnostic Regulation (IVDR) critically impacts instrument design and market access for clinical applications. Biotechnology clusters in Munich and Heidelberg drive the adoption of high-throughput flow cytometers and advanced imaging systems.
Japan
Japan maintains a high demand for sophisticated cell analysis platforms, especially for drug discovery and stem cell research. Adherence to PMDA regulations ensures stringent quality and validation for instruments used in clinical and diagnostic settings. Research institutions and pharmaceutical companies in Tokyo and Osaka actively pursue single-cell multi-omics and AI-powered image analysis.
Cell Analysis Market Key Industry Players
The competitive structure tilts toward integrated solution providers, reflecting a market where comprehensive workflow packages are increasingly preferred. This landscape features a blend of large, diversified corporations offering broad portfolios and specialized technology developers focusing on specific analytical needs. Companies strategically engage in portfolio diversification to offer end-to-end solutions and pursue targeted platform development to capture high-value segments like single-cell analysis.
Integrated ecosystem providers, such as Thermo Fisher Scientific, leverage extensive portfolios to deliver comprehensive workflow packages, meeting diverse research and clinical needs. These solutions often bundle instruments with proprietary reagents and dedicated software, appealing to biotechnology firms and contract research organizations seeking standardized workflows. Becton, Dickinson and Company exemplifies specialization in high-throughput flow cytometry platforms, critical for immunology and oncology research applications, driving innovation in single-cell analysis. Danaher Corporation, through its multi-brand strategy, offers specialized instruments across various cell analysis modalities, from imaging to sorting, catering to a broad spectrum of scientific requirements and ensuring a strong market presence.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies |
| Bio-Rad Laboratories |
| 10X Genomics |
| Miltenyi Biotec |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
Regulatory compliance requirements create a distinct certification ladder, which significantly influences pricing power for compliant instruments and shapes the specialized component sourcing within the cell analysis supply chain. This divergence favors integrated ecosystem providers.
Pricing Analysis
Cost-down pressure on basic cell counters accelerates because of increased competition from diverse manufacturers and the commoditization of simpler technologies. The dominant pricing model favors bundled ecosystem solutions, where instruments, proprietary reagents, and software are sold as integrated packages. Price differentiation stems from regulatory compliance, advanced analytical capabilities like single-cell multi-omics, and comprehensive after-sales service. Academic institutions and smaller biotech startups exhibit higher price sensitivity compared to large pharmaceutical manufacturers who prioritize validated, compliant systems for drug discovery.
Supply Chain Analysis
Direct sales teams and specialized distributors manage the complex distribution of high-end cell analysis instruments to research clusters. Supply concentration for advanced components, such as optical sensors and microfluidic chips, centers in the United States, Germany, and Japan. The market relies heavily on proprietary reagents and high-precision electronics as key inputs. Single-source vulnerability for these specialized components presents a structural risk for manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell analysis market is engaged in a vertical-integration race, as leading players pursue the downstream lever of bundling proprietary software and reagents with core instrumentation. This strategy aims to create comprehensive, integrated ecosystem solutions.
For Market Incumbents:
Deploy integrated workflow development to counter the fragmentation from niche technology developers and emerging software-as-a-service providers. Incumbents should expand their bioinformatics talent pool and acquire specialized AI imaging firms to maintain a competitive edge. Investing in robust regulatory compliance support, particularly for the EU's IVDR, reinforces market access against less compliant offerings. This strategy addresses the threat of new entrants offering point solutions.
For New Entrants and Emerging Players:
Capture underpenetrated segments by developing user-friendly, compact instruments tailored for routine clinical diagnostics in hospital laboratories. Focus on agricultural biotech applications, such as plant genomics analysis, to open new application frontiers. The most penetrable segment remains smaller academic labs seeking cost-effective, specialized tools with strong customer support. A go-to-market angle emphasizing ease-of-use and lower capital investment will differentiate offerings.
For Investors and Strategic Acquirers:
Exit pathways concentrate in specialized technology developers offering unique single-cell multi-omics capabilities or advanced AI-powered image analysis platforms. The long-term viability of the cell analysis market is strong, driven by sustained investment in personalized medicine and oncology research. Target acquisition archetypes include firms providing robust regulatory compliance software and integrated workflow solutions. Increased M&A activity for bioinformatics talent serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Image Analysis Integration | Enhances diagnostic accuracy and drug screening efficiency for pharmaceutical manufacturers. |
| Single-Cell Multi-Omics Expansion | Provides unprecedented resolution for disease mechanism studies, accelerating drug discovery pipelines. |
| Regulatory Compliance Software Development | Ensures market access in clinical and diagnostic settings under stringent frameworks like IVDR. |
| Compact Flow Cytometer Development | Facilitates penetration into routine clinical diagnostics for hospital laboratories and decentralized testing. |
| Agricultural Biotech Application Development | Unlocks new market frontiers in crop improvement and disease resistance research. |
Research Approach
Multi-period observation of funding trends, patent filings, and product launches anchored the trend analysis, supplemented by interviews with R&D directors, lab managers, and regulatory affairs leads. This primary research was validated against secondary sources, including scientific literature databases and government research grant records. The approach employed bottom-up and top-down triangulation to ensure data consistency across diverse sources.
An input-output matrix integrated historical data with projected market drivers across the analysis window. Segmentation dimensions modeled included product type, technology, application, end-user, and the impact of single-cell multi-omics. Compound annual growth rates were derived through regression analysis and market share projections, factoring in research funding allocations and personalized medicine adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen technological breakthroughs and shifts in government research funding. Forecasts reflect assumptions regarding regulatory stability and sustained investment in oncology. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biomedical Technology
Enzymatic DNA Synthesis Market
Biomedical Technology
Bacteriophage Market
Biomedical Technology
Latin America Digital Biology Market
Biomedical Technology
Europe Exosome Research Products Market
Biomedical Technology
Global Biological Stains Market
Biomedical Technology
Human Biobanking Ownership Market
Biomedical Technology
Fluorescence in-Situ Hybridization Probe Market
Biomedical Technology
Global Cell Sorting Market
Biomedical Technology
Immunofluorescence Analyzers Market
Biomedical Technology
Global Transcriptomics Market
Biomedical Technology
Single Cell Multiomics Market
Biomedical Technology
Global Drug Discovery Technologies Market
Biomedical Technology
Global Oncology Based in-Vivo CRO Market
Biomedical Technology
Global Ligation Market
Biomedical Technology
Global Serological Transplant Diagnostics Market
Biomedical Technology
Ocular Drug Delivery Technology Market