
 Global Protein Binding Assay Market | 2026-2036
Global Protein Binding Assay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Binding Assay Market Foresight
The split between premium label-free detection platforms and commodity radioactive tracer kits is realigning procurement patterns across pharmaceutical R&D budgets. Thermo Fisher Scientific leverages its ion trap mass spectrometry portfolio to dominate high-sensitivity pharmacokinetics workflows. Charles River anchors its position through integrated preclinical services that bundle protein binding data with toxicology screening. Bio-Rad Laboratories competes on modular fluorescence polarization readers priced for mid-tier contract research organizations.
Protein binding assays quantify the fraction of a drug compound bound to plasma proteins, typically using equilibrium dialysis with 48-hour incubation at 37 degrees Celsius or surface plasmon resonance with real-time association-dissociation kinetics to predict free drug concentration and tissue distribution. Fluorescence polarization and surface plasmon resonance command the widest installed bases, though mass spectrometry-linked approaches are gaining share where label-free operation eliminates radioligand handling costs. Equilibrium dialysis retains its role as the regulatory reference method, while biosensor platforms attract investment from biotechnology firms seeking throughput gains in lead optimization.
The FDA's Bioanalytical Method Validation guidance and the EMA's ICH M10 guidelines both mandate documented protein binding recovery rates for small-molecule submissions, pushing vendors toward automated equilibrium dialysis and validated chromatography protocols. China's NMPA has adopted similar bioequivalence standards for generic drug approvals, expanding the addressable market for assay kits meeting multi-regulatory specifications. Stakeholders must weigh capital intensity against workflow integration when selecting between modular benchtop systems and enterprise-scale robotic platforms.
Market Dynamics
Automated equilibrium dialysis systems are compressing assay turnaround times from 48 hours to under 6 hours, forcing vendors to reengineer hardware-software bundles or surrender high-throughput contracts to integrated platform suppliers.
Growth Catalysts
- FDA Bioanalytical Method Validation:Tightened recovery rate documentation requirements for IND submissions drive replacement of manual dialysis with validated automated workstations.
- Fluorescence polarization:Mid-tier contract research organizations in India and Brazil adopt modular plate readers to meet bioequivalence standards without capital-intensive SPR infrastructure.
- China NMPA alignment:Adoption of ICH M10-equivalent guidelines for generic drug approvals expands demand for multi-regulatory assay kits.
Market Restraints
- Radioisotope supply concentration:Tritium and carbon-14 tracer production concentrates in three US Department of Energy facilities, creating single-source vulnerability for legacy radioligand workflows.
- SPR consumable lock-in:Biosensor chip chemistries remain proprietary to platform vendors, raising lifetime cost of ownership 40-60% above initial hardware purchase.
- Equilibrium dialysis throughput ceiling:48-hour incubation protocols cannot compress further without violating thermodynamic equilibrium assumptions, capping productivity gains.
Strategic Opportunities
- Mass spectrometry convergence:Label-free quantification via LC-MS/MS eliminates radioligand handling while satisfying FDA validation criteria for protein binding recovery.
- Saudi SFDA biosimilar pathway:New bioequivalence requirements for monoclonal antibody copies create demand for high-precision binding assays in Gulf Cooperation Council markets.
- Cloud-connected instrumentation:Remote method validation and audit trail synchronization reduce regulatory compliance labor for distributed CRO networks.
Industry Challenges
- Cross-trained analytical chemists:Shortage of personnel proficient in both SPR kinetics modeling and mass spectrometry method development delays platform migration projects.
- Legacy LIMS integration:Robotic sample handlers from 2015-2019 lack API compatibility with modern cloud-based data management systems, forcing middleware expenditures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Binding Assay Market |
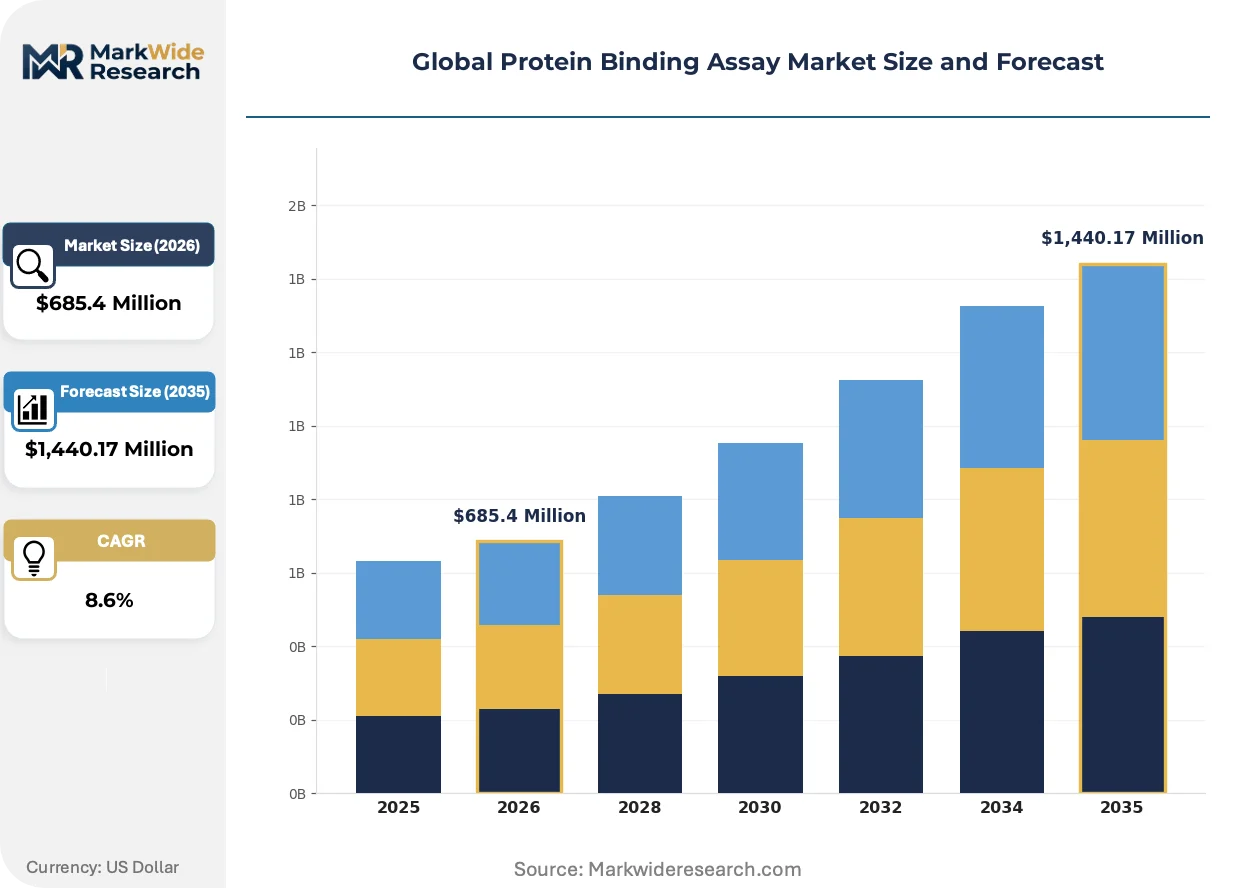
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,440.17 Million |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Equilibrium Dialysis, Ultrafiltration, Surface Plasmon Resonance, Capillary Electrophoresis, Chromatography, Fluorescence Polarization Technology: Label-Free Detection, Radioactive Tracer, Spectroscopy, Mass Spectrometry, Electrochemical Sensing, Biosensor Platforms Application: Drug Discovery, Pharmacokinetics, Clinical Diagnostics, Toxicology Screening, Biomarker Identification, Protein Interaction Studies End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Research Centers, Diagnostic Laboratories, Government Agencies |
| Companies Covered | Bio-Rad Laboratories, Charles River, Thermo Fisher Scientific, Merck KGaA, Sartorius, Agilent Technologies, Lonza, Promega, PerkinElmer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Binding Assay Market Shifts & Advancements
Microfluidic sample handling is displacing conventional 96-well formats across early-stage screening, while regulatory data integrity requirements accelerate cloud-native instrument control adoption.
Microfluidic equilibrium dialysis cartridges is integrating nanoliter-scale chambers with temperature-controlled incubation to reduce plasma sample volumes from 500 microliters to 50 microliters. Biotechnology firms in Boston and Basel adopt these systems for precious compound libraries. The technology is integrating low-volume consumption with parallel processing, compressing per-assay reagent costs while maintaining correlation with regulatory reference methods.
EMA ICH M10 implementation mandates electronic raw data capture and audit trails for protein binding studies submitted after January 2025. Contract research organizations in Germany and the Netherlands retrofit existing HPLC-UV systems with compliant software modules. Small-molecule generic sponsors face the steepest compliance burden, accelerating outsourcing to specialized bioanalytical providers.
Consolidated procurement through centralized laboratory services departments displaces decentralized instrument purchasing by individual therapeutic area teams. Large pharmaceutical companies in New Jersey and California negotiate enterprise-scale service contracts bundling hardware, consumables, and regulatory documentation support. This concentration shifts vendor sales resources from technical specialists toward contract negotiation teams.
Global Protein Binding Assay Market Segmentation
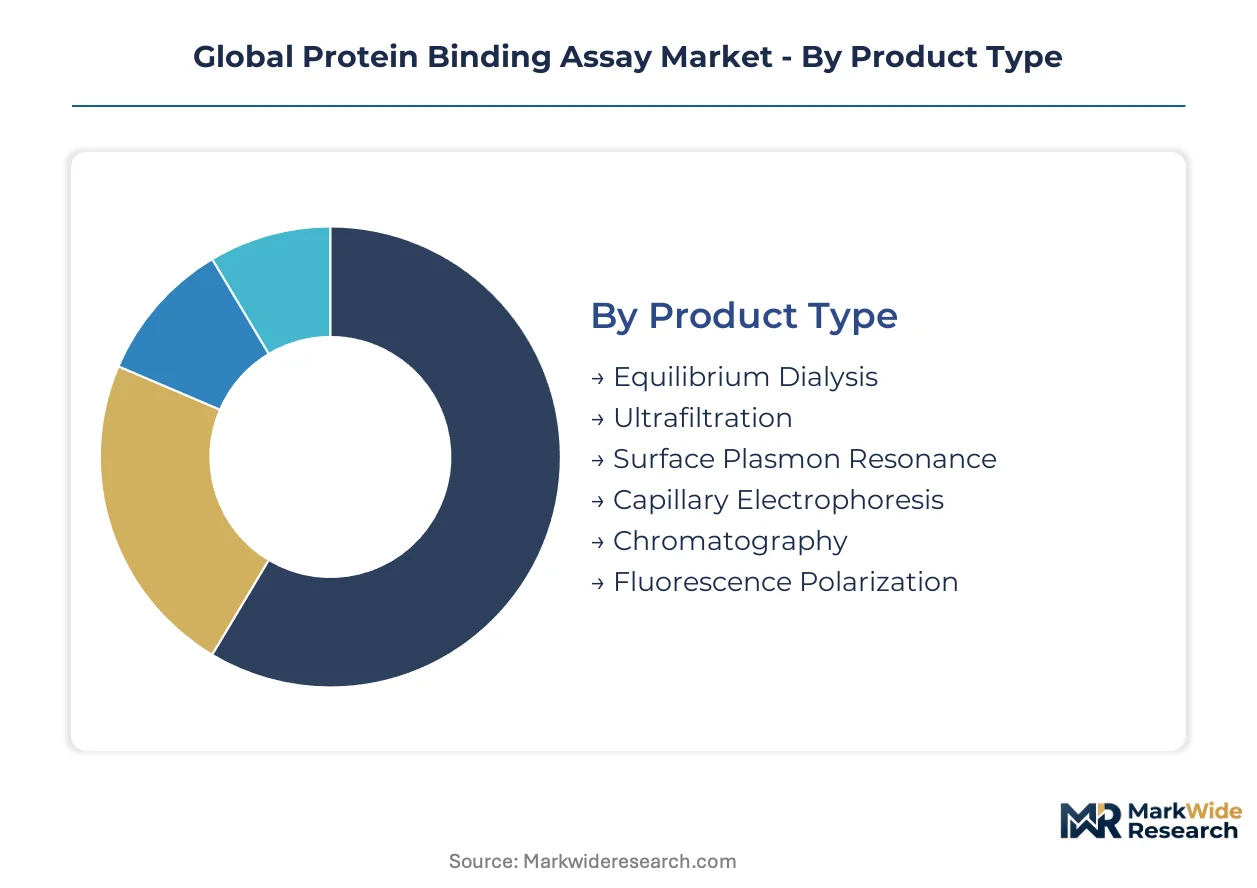
Protein binding assay segmentation reveals distinct regulatory compliance burdens across product types, with automated platforms demanding FDA bioanalytical validation while manual kits face lighter documentation requirements. Technology choices directly determine capital intensity and radioligand handling protocols, shaping procurement patterns across pharmaceutical R&D budgets.
Product Type:
Equilibrium dialysis systems carry the heaviest certification load, requiring documented recovery rates under FDA Bioanalytical Method Validation guidance, while fluorescence polarization readers operate under lighter GLP standards.
- Equilibrium Dialysis:The 48-hour incubation protocol at 37 degrees Celsius remains the regulatory reference method for plasma protein binding quantification. Pharmaceutical sponsors in New Jersey and California specify automated workstations to satisfy IND submission requirements for small-molecule candidates.
- Surface Plasmon Resonance:Real-time association-dissociation kinetics enable label-free detection of binding interactions without radioligand handling. Boston biotech clusters drive installed base expansion for lead optimization throughput gains.
- Ultrafiltration:Membrane-based separation offers faster turnaround than dialysis but suffers from non-specific binding artifacts that complicate regulatory submissions.
- Capillary Electrophoresis:Separation-based quantification suits highly polar compounds with poor dialysis membrane permeability.
- Chromatography:HPLC-UV and LC-MS/MS integration supports method development for complex biologics formulations.
- Fluorescence Polarization:Modular plate readers priced for mid-tier contract research organizations in India and Brazil meet bioequivalence standards without SPR infrastructure investment.
Equilibrium dialysis sits at the top of the volume ranking, with surface plasmon resonance climbing the fastest.
Technology:
Cost tiering separates capital-intensive label-free platforms from consumable-heavy radioactive workflows, with mass spectrometry convergence capturing mid-market migration.
- Label-Free Detection:SPR and bio-layer interferometry eliminate radioligand costs but lock users into proprietary sensor chip chemistries. Large pharmaceutical companies negotiate enterprise service contracts bundling hardware and consumables to control lifetime ownership costs.
- Mass Spectrometry:LC-MS/MS quantification satisfies FDA validation criteria for protein binding recovery while eliminating tritium handling requirements. Thermo Fisher Scientific leverages ion trap portfolios to dominate high-sensitivity pharmacokinetics workflows.
- Radioactive Tracer:Tritium and carbon-14 assays retain regulatory acceptance but concentrate supply risk in three US Department of Energy production facilities.
- Spectroscopy:UV-Vis and fluorescence detection support high-throughput screening with lower capital barriers than mass spectrometry.
- Electrochemical Sensing:Emerging platforms target point-of-care diagnostic applications with miniaturized electrode arrays.
- Biosensor Platforms:Integrated hardware-software bundles attract biotechnology firms seeking compressed assay turnaround times below six hours.
Label-free detection commands the steepest expansion trajectory, with mass spectrometry gaining share fastest among regulated bioanalytical laboratories.
Application:
Application segmentation tracks the drug development pipeline, with pharmacokinetics studies demanding the most rigorous validation documentation.
- Pharmacokinetics:Free drug concentration prediction drives regulatory submission requirements across FDA, EMA, and China NMPA jurisdictions. Contract research organizations in Germany and the Netherlands retrofit HPLC-UV systems with compliant software modules for ICH M10 electronic data capture mandates.
- Drug Discovery:Early-stage screening prioritizes throughput over validation, favoring microfluidic formats and 384-well automation. Boston and Basel biotechnology clusters adopt nanoliter-scale equilibrium dialysis cartridges for precious compound libraries.
- Clinical Diagnostics:Therapeutic drug monitoring applications require CLIA-compliant workflows with documented precision and accuracy.
- Toxicology Screening:Charles River bundles protein binding data with preclinical safety assessment services.
- Biomarker Identification:Protein interaction studies support companion diagnostic development for precision oncology programs.
- Protein Interaction Studies:Academic research centers leverage open-access biosensor facilities for fundamental mechanistic research.
Pharmacokinetics sits at the top of the volume ranking, with drug discovery climbing the fastest.
End User:
Customer type determines procurement centralization, with pharmaceutical companies consolidating through enterprise contracts while academic centers rely on shared instrumentation cores.
- Pharmaceutical Companies:Centralized laboratory services departments in New Jersey and California negotiate bundled hardware, consumables, and regulatory documentation support. Vendor sales resources shift from technical specialists toward contract negotiation teams.
- Contract Research Organizations:Mid-tier CROs in India and Brazil adopt modular fluorescence polarization readers to capture bioequivalence study outsourcing from generic sponsors.
- Biotechnology Firms:Boston and San Diego clusters drive procurement of high-throughput equilibrium dialysis and SPR systems for lead optimization.
- Academic Research Centers:Shared core facilities balance capital constraints against multi-investigator access requirements.
- Diagnostic Laboratories:Clinical reference laboratories integrate protein binding assays into therapeutic drug monitoring menus.
- Government Agencies:National pharmaceutical regulators in Saudi Arabia and the Gulf Cooperation Council establish reference laboratories for biosimilar bioequivalence verification.
Pharmaceutical companies sit at the top of the volume ranking, with contract research organizations climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists cluster in Boston, San Diego, Basel, and Shanghai, anchoring regional demand for protein binding assay infrastructure. These talent concentrations align with biopharmaceutical R&D investment patterns and regulatory submission volumes. Procurement decisions in each geography reflect distinct compliance frameworks and therapeutic development priorities.
United States
FDA Bioanalytical Method Validation guidance drives replacement of manual equilibrium dialysis with automated workstations in New Jersey and California pharmaceutical headquarters. The Boston biotech cluster sustains demand for surface plasmon resonance systems in lead optimization workflows. San Diego contract research organizations expand high-throughput screening capacity to capture IND-stage outsourcing.
Germany
EMA ICH M10 electronic data capture mandates accelerate retrofitting of HPLC-UV systems in Frankfurt and Munich bioanalytical laboratories. The country's national pharmaceutical regulator enforces stringent audit trail requirements for protein binding studies submitted after January 2025. Heidelberg and Berlin research institutes adopt microfluidic equilibrium dialysis cartridges for precious compound libraries.
China
NMPA alignment with ICH M10 bioequivalence standards expands demand for multi-regulatory assay kits in Shanghai and Suzhou pharmaceutical manufacturing zones. Generic drug sponsors in Jiangsu and Zhejiang provinces outsource protein binding validation to specialized CROs. Beijing biotechnology firms invest in label-free detection platforms to accelerate biosimilar development timelines.
India
Mid-tier contract research organizations in Hyderabad and Bangalore adopt modular fluorescence polarization readers to capture bioequivalence study outsourcing from generic sponsors. CDSCO tightened bioanalytical guidance pushes manual workflow replacement in Mumbai and Ahmedabad analytical laboratories. The country's national pharmaceutical regulator mandates documented recovery rates for ANDA submissions.
Switzerland
Swissmedic reference laboratory standards attract protein binding assay investment from Basel-headquartered pharmaceutical companies. Roche and Novartis procurement centralization drives enterprise-scale service contracts bundling hardware, consumables, and regulatory documentation. Geneva CROs specialize in high-precision binding assays for monoclonal antibody biosimilar development.
Global Protein Binding Assay Market Competitive Landscape
Capital-heavy instrument manufacturers compete with asset-light reagent suppliers across the protein binding assay value chain. The market structure concentrates around integrated platform vendors controlling proprietary sensor chemistries and modular kit providers serving price-sensitive segments. Three archetypes dominate: diversified life science conglomerates with mass spectrometry portfolios, specialized preclinical service providers bundling binding data with toxicology, and mid-tier analytical instrument specialists competing on fluorescence polarization modularity. Competitive moves center on cloud-connected instrumentation for distributed CRO networks and mass spectrometry convergence to eliminate radioligand handling.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Agilent Technologies occupy positions leveraging ion trap and LC-MS/MS portfolios for high-sensitivity pharmacokinetics workflows. Among preclinical service specialists, Charles River exemplifies the integrated model bundling protein binding data with toxicology screening. Bio-Rad Laboratories represents the modular specialist archetype, competing on fluorescence polarization reader pricing for mid-tier contract research organizations.
| Leading Market Players |
|---|
| Bio-Rad Laboratories |
| Charles River |
| Thermo Fisher Scientific |
| Merck KGaA |
| Sartorius |
| Agilent Technologies |
| Lonza |
| Promega |
| PerkinElmer |
| Others |
Supply & Pricing Matrix
Analytical chemists with SPR kinetics and mass spectrometry dual proficiency cluster in Boston, Basel, and San Diego, creating labor-cost differentials that widen pricing-tier spreads between premium automated platforms and modular benchtop systems. Their scarcity in India and Brazil compresses margins for mid-tier fluorescence polarization deployments while inflating service premiums for validated equilibrium dialysis in US pharmaceutical headquarters.
Pricing Analysis
Bundled enterprise service contracts versus unbundled instrument-only procurement splits the market into divergent cost structures. Large pharmaceutical companies in New Jersey and California negotiate three-tier pricing structures across premium, standard, and economy levels, with FDA-validated automated workstations commanding substantial premiums over GLP-tier manual kits. Price differentiation hinges on certification grade—ICH M10-compliant electronic data capture modules add substantial cost—and volume scale, with consolidated procurement extracting 15-25% discounts. Pricing pressure stems from CDSCO and NMPA alignment with international bioequivalence standards, which expands addressable demand but intensifies competition among CROs in Hyderabad and Bangalore. Mid-tier contract research organizations exhibit highest price sensitivity, while biotechnology firms in Boston prioritize throughput gains over capital constraints.
Supply Chain Analysis
Warehouse-distribution networks for equilibrium dialysis consumables and SPR sensor chips operate through regional distribution centers in Massachusetts, Baden-Württemberg, and Jiangsu province, with hub-and-spoke patterns radiating to satellite analytical laboratories. Manufacturing concentrates in the United States, Germany, and China, with proprietary biosensor chip chemistries anchored in US and Swiss facilities while plastic consumables and microfluidic cartridges source from precision molding operations in Suzhou and Shenzhen. Raw material dependencies include high-purity dialysis membranes, gold-coated sensor surfaces, and tritium-labeled tracer compounds. Single-source vulnerability pervades radioisotope supply, with tritium production concentrated in three US Department of Energy facilities. Distribution runs through direct vendor relationships for enterprise pharmaceutical accounts and distributor networks serving fragmented CRO segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA ICH M10 electronic data capture mandates in Germany and the Netherlands create compliance-cost premiums that Indian and Brazilian CROs can undercut through modular fluorescence polarization adoption.
For Market Incumbents: Hedge against mass spectrometry convergence by deepening LC-MS/MS method development capabilities and securing exclusive reagent supply agreements with tritium production facilities. Lock in pharmaceutical accounts through cloud-connected instrumentation with remote audit trail synchronization, addressing the legacy LIMS integration bottleneck that delays platform migrations. Prioritize certification investment for automated equilibrium dialysis workstations to maintain regulatory reference method positioning against faster but less validated ultrafiltration alternatives. For New Entrants and Emerging Players: Enter via Saudi SFDA biosimilar pathway requirements and Gulf Cooperation Council reference laboratory buildouts, where high-precision binding assay demand outpaces established vendor presence. Target mid-tier CROs in São Paulo and Mexico City with fluorescence polarization reader leasing models that bypass capital expenditure barriers. Pursue a consumables-recurring-revenue go-to-market angle, as proprietary SPR chip chemistries lock users into 40-60% lifetime cost premiums above initial hardware purchase. For Investors and Strategic Acquirers: Preclinical service providers are the most active acquirer in this space, seeking to bundle protein binding data with toxicology screening per the Charles River model. Long-term viability hinges on regulatory validation moats rather than throughput specifications alone, favoring targets with documented FDA Bioanalytical Method Validation recovery rates across multiple compound classes. Watch for CDSCO enforcement of documented recovery rates for ANDA submissions as the inflection signal for Indian CRO consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Instrumentation | Remote method validation reduces compliance labor for distributed CRO networks in Germany and the Netherlands. |
| Mass Spectrometry Convergence | Label-free LC-MS/MS quantification eliminates tritium handling while satisfying FDA protein binding recovery criteria. |
| Microfluidic Cartridge Development | Nanoliter-scale equilibrium dialysis reduces plasma volumes from 500 microliters to 50 microliters for Basel compound libraries. |
| Regulatory Documentation Bundling | Enterprise contracts combining hardware, consumables, and validation support capture centralized pharmaceutical procurement. |
| Multi-Regulatory Assay Kit Certification | ICH M10-equivalent compliance for FDA, EMA, and NMPA jurisdictions expands addressable market for generic sponsors. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation across regulatory filings and trade data. Primary interviews engaged drug development executives at biotechnology firms in Boston and San Diego, regulatory affairs leads at pharmaceutical headquarters in New Jersey and California, and procurement managers at contract research organizations in Hyderabad and Bangalore. Secondary sources included FDA Bioanalytical Method Validation guidance documents, EMA ICH M10 implementation notices, NMPA bioequivalence standards, CDSCO tightened guidance circulars, and SEC 10-K filings from diversified life science conglomerates. Bottom-up instrument shipment data triangulated against top-down pharmaceutical R&D expenditure allocations.
Granularity-level modeling disaggregated revenue across product type, technology, application, and end user dimensions, with additional stratification by regional regulatory cluster and certification tier. CAGRs derived from regression analysis of historical adoption curves for equilibrium dialysis, surface plasmon resonance, and mass spectrometry platforms, cross-referenced against IND submission volumes and generic drug approval pipelines. Forecast inputs incorporated bioequivalence study outsourcing trends, cloud-native instrument control adoption rates, and microfluidic cartridge penetration in precious compound library screening.
The model holds under stable regulatory convergence timelines; deviation in FDA guidance revision schedules or NMPA enforcement intensity would shift instrument replacement cycles and CRO outsourcing volumes. Forecasts reflect stated assumptions regarding ICH M10 implementation adherence and radioisotope supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Stable Cell Line Development Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Transport Protein Assays Kits Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
Antibody Drug Conjugates Contract Manufacturing Market
Biotechnology Services
Global Western Blotting Market
Biotechnology Services
Cdna Synthesis Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Global Cell Banking Outsourcing Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Vaccine and Biologic Product Distribution Optimization Services Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market