
 Niemann-Pick Disease Type C (NPC) Market | 2026-2036
Niemann-Pick Disease Type C (NPC) Market Size, Share, and Industry Trends Forecast 2026-2036
Niemann-Pick Disease Type C (NPC) Market Insights
The United States is rewriting competitive dynamics in Niemann-Pick Type C therapeutics through expanded rare disease manufacturing infrastructure. Mallinckrodt Pharmaceuticals leverages its hospital channel relationships to sustain access across academic medical centers. Alexion Pharmaceuticals, Inc. anchors its position through complement pathway expertise applied to lipid trafficking modulation. Cyclo Therapeutics, Inc. differentiates via cyclodextrin-based blood-brain barrier penetration technology.
Niemann-Pick Disease Type C is a rare autosomal recessive lysosomal storage disorder caused by NPC1 or NPC2 gene mutations, characterized by impaired intracellular cholesterol and lipid trafficking that leads to progressive neurodegeneration and visceral organ dysfunction. The condition primarily serves pediatric and adult patient populations requiring disease-modifying or supportive interventions. Gene therapies represent the fastest-expanding segment as viral vector delivery platforms mature, while small molecules retain the largest current revenue pool due to existing regulatory approvals and clinical familiarity. Enzyme replacement therapies face structural constraints from blood-brain barrier limitations, concentrating margin pools in delivery mode innovations.
FDA orphan drug designation and EMA priority medicines pathways shape development economics by extending exclusivity periods and reducing regulatory fees for sponsors. The EU AI Act and FDA's evolving framework for gene therapy CMC requirements are tightening manufacturing and post-market surveillance standards. Stakeholders must monitor reimbursement negotiations for one-time gene therapies versus chronic small molecule administration models.
Market Dynamics
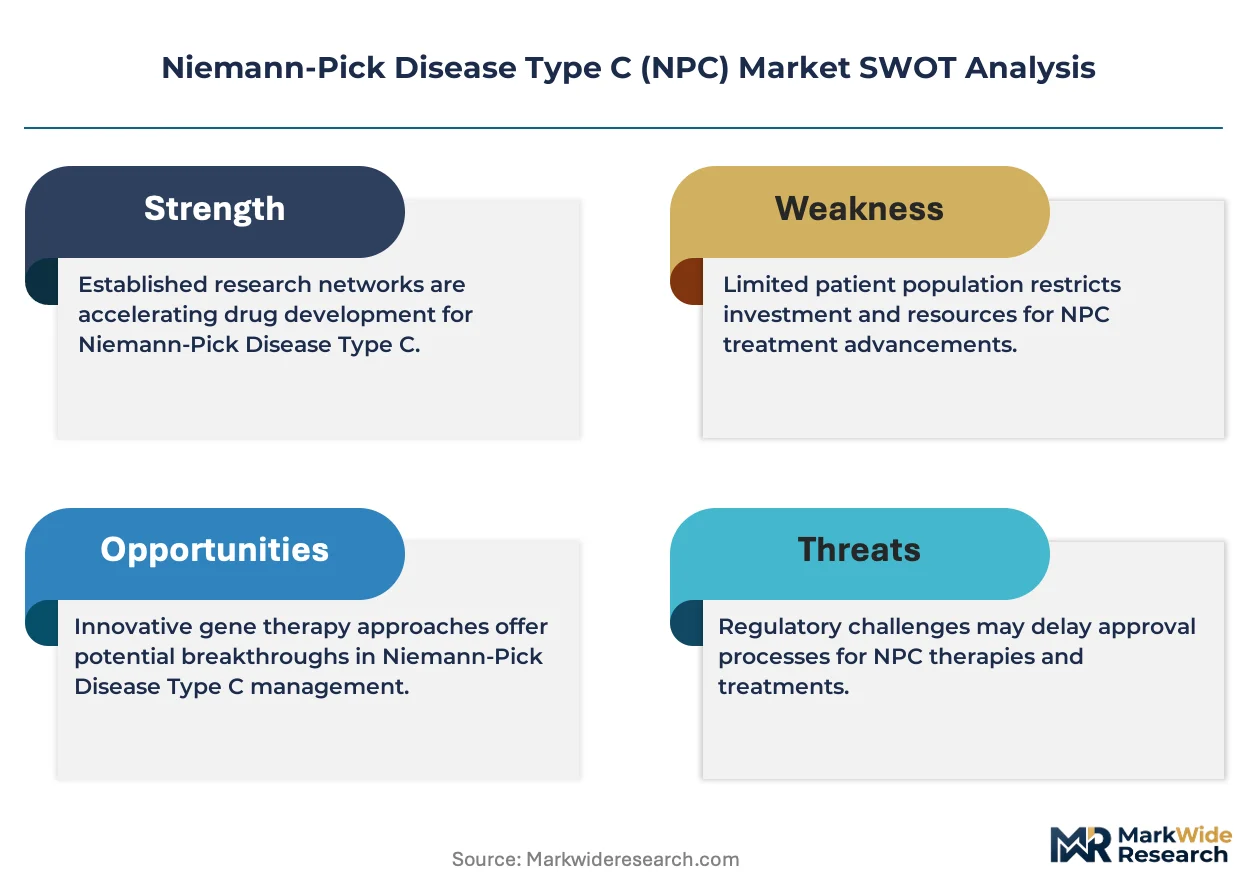
Gene therapy manufacturing scale-up is compressing development timelines for Niemann-Pick Type C interventions, as viral vector production platforms mature and regulatory pathways for one-time disease-modifying treatments solidify across multiple jurisdictions.
Growth Catalysts
- FDA Orphan Drug Incentives:Extended market exclusivity periods and waived regulatory fees accelerate sponsor commitment to rare lysosomal storage disorder programs.
- Academic Medical Center Networks:Concentrated referral pathways in the United States streamline patient identification and clinical trial enrollment for ultra-rare indications.
- Cyclodextrin Blood-Brain Barrier Technology:Novel delivery mechanisms enabling intrathecal administration of therapeutic compounds directly to central nervous system pathology sites.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector manufacturing depends on a limited pool of qualified plasmid suppliers, creating single-source vulnerability for gene therapy developers.
- Small Molecule Substitution Pressure:Chronic oral administration of miglustat and arimoclomol competes with high-cost gene therapy value propositions in reimbursement negotiations.
- Blood-Brain Barrier Technical Limitation:Enzyme replacement therapies face fundamental delivery constraints that restrict therapeutic efficacy for neurological manifestations.
Strategic Opportunities
- Neonatal Screening Expansion:Several US states are piloting lysosomal storage disorder newborn screening panels that would dramatically compress diagnostic delays.
- Japan's Sakigake Designation:Priority review pathways for regenerative medicines and gene therapies reduce time-to-market for innovative modalities.
- Direct-to-Patient Digital Channels:Telemedicine platforms connecting specialized metabolic centers with geographically dispersed rare disease populations.
Industry Challenges
- Gene Therapy Manufacturing Talent Scarcity:Viral vector production requires specialized bioprocess engineers with experience in adherent cell culture and downstream purification at clinical scale.
- Companion Diagnostic Complexity:NPC1 and NPC2 mutation profiling demands sophisticated sequencing infrastructure that many community hospitals lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Niemann-Pick Disease Type C (NPC) Market |
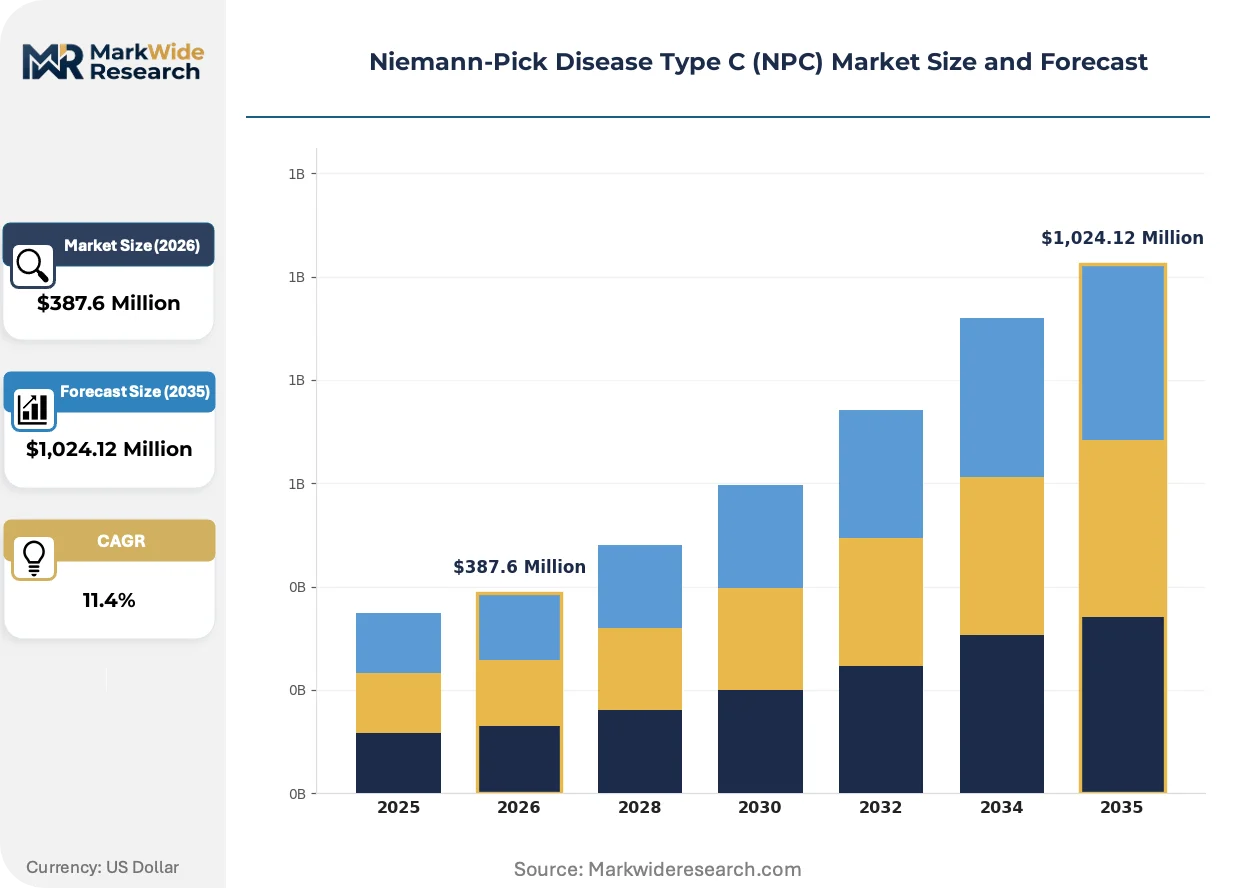
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Small Molecules, Gene Therapies, Enzyme Replacement Therapies, Nutraceuticals Application: Pediatric Treatment, Adult Treatment, Off-label Use, Supportive Care End User: Hospitals, Specialty Clinics, Home Care, Research Institutions Delivery Mode: Intravenous, Subcutaneous, Oral, Intraosseous |
| Companies Covered | Mallinckrodt Pharmaceuticals, Alexion Pharmaceuticals, Inc., Cyclo Therapeutics, Inc., BioMarin Pharmaceutical Inc., Amicus Therapeutics, Inc., IntraBio Inc., Actelion Pharmaceuticals Ltd, CTD Holdings, Inc., Orphazyme A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Niemann-Pick Disease Type C (NPC) Market Trends and Innovations
Biomanufacturing modality diversification is fragmenting competitive advantage sources, as sponsors pivot from small molecule chemistry expertise toward viral vector engineering and cell therapy platform capabilities.
Adeno-associated viral vector delivery for neurological applications is migrating from preclinical proof-of-concept studies toward registrational trials, with academic medical centers in the United States and Germany establishing dedicated GMP facilities for central nervous system-targeted gene transfer. Sponsors are consolidating manufacturing partnerships with CDMOs possessing specialized expertise in intrathecal administration protocols and neurosurgical coordination.
The EU AI Act's risk classification framework for AI-enabled diagnostic tools is tightening validation requirements for machine learning algorithms used in NPC biomarker interpretation, forcing developers to establish comprehensive post-market performance monitoring systems. European sponsors are restructuring clinical data management infrastructure to accommodate continuous algorithmic performance reporting to national competent authorities.
Payer contracting for one-time gene therapies is displacing traditional chronic therapy reimbursement models, with US commercial insurers and Medicaid programs piloting outcomes-based installment structures tied to demonstrated clinical milestones. Massachusetts and California Medicaid programs are negotiating value-based agreements that spread gene therapy costs across multiple fiscal years contingent on patient functional status preservation.
Niemann-Pick Disease Type C (NPC) Market Segmentation
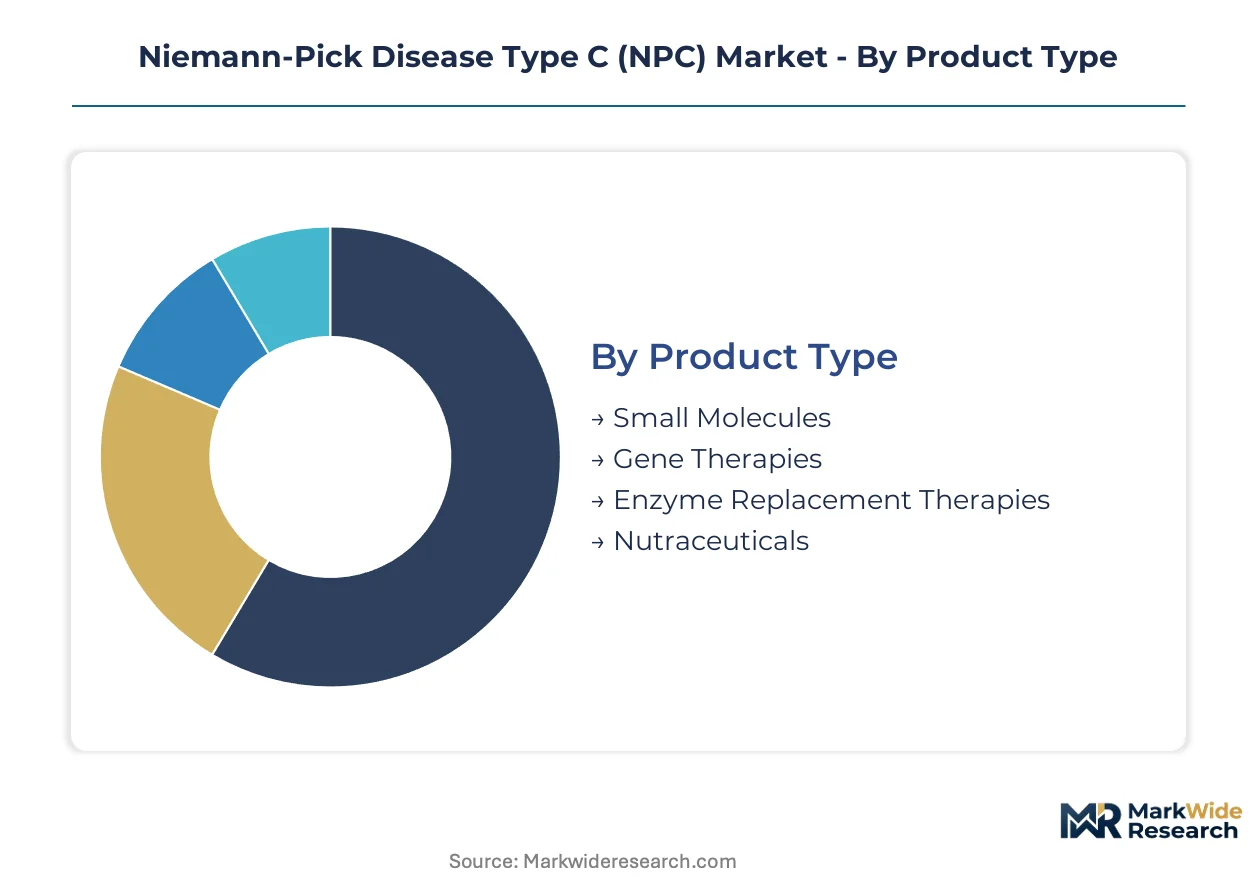
Niemann-Pick Type C therapeutics fragment across four distinct dimensions that govern pricing power, regulatory pathway selection, and manufacturing investment priorities. Product type and application segments command disproportionate strategic attention due to their direct impact on reimbursement negotiations and clinical trial design.
Product Type:
Mature small molecule platforms anchor current revenue pools while emerging gene therapy modalities attract development capital.
- Small Molecules:Oral miglustat and arimoclomol formulations dominate prescription volumes through established FDA and EMA approvals. Chronic administration models concentrate demand in United States academic medical centers with reimbursed access programs.
- Gene Therapies:Adeno-associated viral vector delivery platforms target one-time disease modification through NPC1/NPC2 gene correction. Manufacturing scale-up constraints limit supply to specialized GMP facilities in Boston and Heidelberg.
- Enzyme Replacement Therapies:Intravenous enzyme infusions address visceral manifestations with limited central nervous system penetration.
- Nutraceuticals:Cyclodextrin-based dietary supplements serve pre-symptomatic patients outside formal therapeutic pathways.
Small molecules retain volume leadership; gene therapies hold the steepest expansion curve.
Application:
Patient age stratification determines treatment intensity, endpoint selection, and regulatory submission strategy.
- Pediatric Treatment:Early intervention protocols target neurodevelopmental preservation before irreversible neuronal loss. United States newborn screening pilots in New York and Illinois are compressing diagnostic delays.
- Adult Treatment:Late-onset presentations require modified dosing regimens addressing slower disease progression patterns. European reference centers in London and Amsterdam coordinate multinational compassionate access programs.
- Off-label Use:Investigational applications outside approved indications demand expanded access regulatory frameworks.
- Supportive Care:Symptomatic management of hepatosplenomegaly and neurological complications runs parallel to disease-modifying approaches.
Pediatric applications concentrate clinical trial enrollment; adult treatment shows the fastest volume climb as diagnostic awareness spreads.
End User:
Care setting selection hinges on therapy complexity, monitoring requirements, and reimbursement infrastructure.
- Hospitals:Tertiary centers manage acute neurological decompensation and surgical interventions for portal hypertension.
- Specialty Clinics:Dedicated metabolic disease units coordinate multidisciplinary care across neurology, hepatology, and genetics.
- Home Care:Oral small molecule administration shifts treatment burden from institutional to domestic settings.
- Research Institutions:Academic medical centers in the United States and Germany host gene therapy clinical trials requiring specialized neurosurgical coordination.
Specialty clinics anchor patient volume; home care delivery is expanding most quickly as oral therapies proliferate.
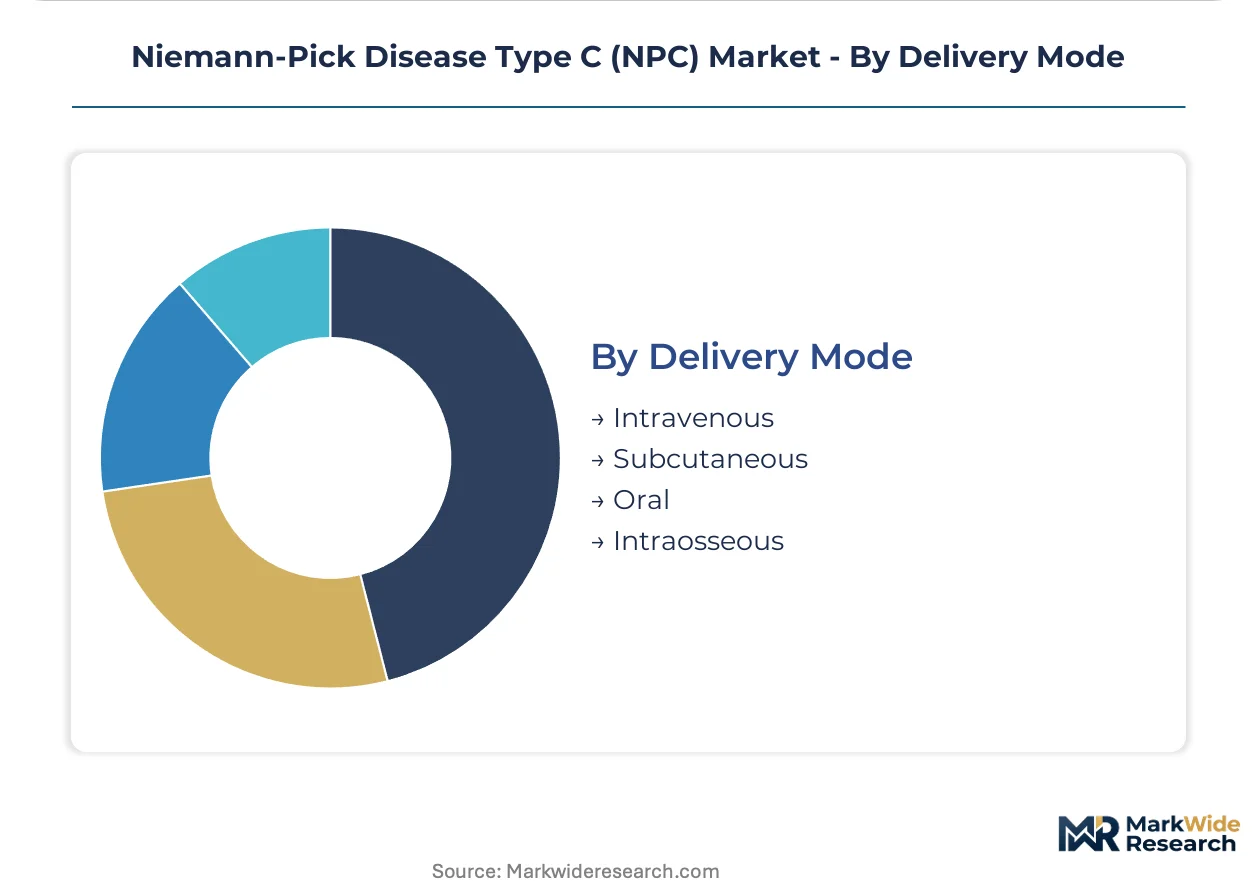
Delivery Mode:
Route selection directly constrains which therapeutic modalities can address central nervous system pathology.
- Intravenous:Systemic enzyme replacement and small molecule infusions require hospital-based administration infrastructure.
- Subcutaneous:Home-administered injections reduce institutional dependency for chronic maintenance regimens.
- Oral:Small molecule bioavailability limitations restrict efficacy against neurological manifestations despite patient convenience advantages.
- Intraosseous:Intrathecal cyclodextrin delivery via lumbar puncture or intraventricular reservoir enables direct central nervous system drug distribution.
Oral delivery dominates prescription counts; intraosseous administration is gaining share fastest through blood-brain barrier penetration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing clusters concentrate in three jurisdictions with specialized GMP infrastructure for viral vector production. Academic medical centers in these countries coordinate multinational clinical trial networks for ultra-rare lysosomal storage disorders.
United States
FDA orphan drug incentives and newborn screening pilots in New York and Illinois compress diagnostic delays for pediatric patients. The agency's regenerative medicine advanced therapy designation accelerates gene therapy review timelines. Boston's Longwood Medical Area anchors viral vector manufacturing with dedicated CNS-targeted GMP facilities.
Germany
EMA priority medicines pathways and the EU AI Act's diagnostic algorithm requirements shape development economics for European sponsors. Heidelberg's University Hospital hosts specialized neurosurgical coordination for intrathecal gene transfer trials. Baden-Württemberg's biotech corridor concentrates cyclodextrin formulation expertise.
United Kingdom
NHS England's specialized commissioning framework funds ultra-orphan therapies through national centers of excellence. The MHRA's innovative licensing pathway reduces time-to-market for one-time disease-modifying treatments. London's Great Ormond Street Hospital coordinates pediatric metabolic disease referral pathways across the Commonwealth.
Japan
PMDA's Sakigake designation for regenerative medicines prioritizes review resources for gene therapy developers. METI's healthcare technology export initiatives support domestic biomanufacturing scale-up. The Kobe Biomedical Innovation Cluster houses dedicated facilities for rare disease clinical trial coordination.
Niemann-Pick Disease Type C (NPC) Market Competitive Landscape
Large-cap diversified pharmaceutics and emerging biotech specialists split the market across chronic small molecules and one-time gene therapies. Mallinckrodt Pharmaceuticals leverages hospital channel relationships while Alexion Pharmaceuticals applies complement pathway expertise to lipid trafficking modulation. Cyclodextrin-based delivery innovators occupy a distinct technology tier. Competitive moves concentrate on manufacturing partnerships with specialized CDMOs and outcomes-based payer contracting structures.
Within the delivery technology tier, Cyclo Therapeutics, Inc. exemplifies blood-brain barrier penetration approaches through cyclodextrin chemistry. Mallinckrodt Pharmaceuticals anchors the established hospital access archetype with academic medical center relationships. Alexion Pharmaceuticals, Inc. occupies a position translating rare disease commercialization infrastructure from complement-mediated disorders to lysosomal storage conditions.
| Leading Market Players |
|---|
| Mallinckrodt Pharmaceuticals |
| Alexion Pharmaceuticals, Inc. |
| Cyclo Therapeutics, Inc. |
| BioMarin Pharmaceutical Inc. |
| Amicus Therapeutics, Inc. |
| IntraBio Inc. |
| Actelion Pharmaceuticals Ltd |
| CTD Holdings, Inc. |
| Orphazyme A/S |
| Others |
Pricing and Supply Chain Analysis
Plasmid DNA manufacturing concentration in the United States and Europe funnels margin pools toward viral vector producers with qualified supplier relationships and GMP certification. Gene therapy developers face asymmetric pricing power as single-source dependencies for critical raw materials limit negotiation leverage.
Pricing Analysis
FDA orphan drug exclusivity dictates the pricing tier structure for Niemann-Pick Type C therapeutics, creating protected revenue streams for approved modalities against generic substitution. Three-tier pricing structure across premium gene therapies, standard small molecules, and economy supportive care segments reflects delivery complexity and reimbursement risk. Cost compression in the small molecule tier is intensifying because miglustat and arimoclomol face therapeutic substitution pressure from emerging disease-modifying alternatives. Medicaid programs demonstrate highest price sensitivity due to budget cap constraints, while commercial insurers with specialty pharmacy networks absorb premium gene therapy costs through outcomes-based installment structures.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for plasmid DNA and cell culture media inputs. Viral vector manufacturing draws from specialized GMP facilities in Boston, Heidelberg, and Kobe, with raw material dependencies on fetal bovine serum, transfection reagents, and purification resins. Single-source vulnerability for qualified plasmid suppliers creates bottleneck risk that concentrates procurement power with incumbent CDMOs. Distribution runs through academic medical center specialty pharmacies and hospital-based infusion centers with cold-chain logistics requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy manufacturing scale-up represents a high-growth disruption as viral vector production platforms mature and one-time disease-modifying treatments displace chronic administration models. PMDA's Sakigake designation and FDA's regenerative medicine advanced therapy pathway accelerate regulatory timelines for innovative modalities.
For Market Incumbents: Entrench market position through backward integration into plasmid DNA manufacturing and captive viral vector production capacity in Boston or Heidelberg clusters. Secure long-term supplier agreements with fetal bovine serum and transfection reagent producers to defend against emerging biotech entrants with platform licensing strategies. Prioritize outcomes-based payer contracting infrastructure to differentiate from small molecule substitution threats. For New Entrants and Emerging Players: Japan and select European markets with nascent newborn screening programs offer the most penetrable geographic entry points for cyclodextrin-based delivery platforms. Target adult late-onset patient populations outside pediatric academic medical center networks where diagnostic awareness remains underdeveloped. Pursue direct-to-patient digital channel partnerships with telemedicine platforms connecting specialized metabolic centers to geographically dispersed rare disease populations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed CDMOs possessing specialized viral vector GMP expertise and intrathecal administration capabilities. Long-term viability centers on manufacturing platform durability rather than single-product pipelines, with five-to-ten year windows favoring assets with multi-indication viral vector applications. Monitor neonatal screening expansion legislation across US states as the critical inflection signal for addressable market expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Boston and Heidelberg GMP facilities expand viral vector capacity for CNS-targeted gene transfer trials. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses review timelines for one-time disease-modifying treatments. |
| Licensing Agreement | Cyclodextrin chemistry partnerships enable blood-brain barrier penetration for lipid trafficking modulation programs. |
| Clinical Trial Advancement | Intrathecal administration protocols with neurosurgical coordination advance registrational trials for pediatric neurodegeneration. |
| Pipeline Diversification | Gene correction platforms for NPC1 and NPC2 mutations extend manufacturing infrastructure across lysosomal storage disorders. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists; and secondary validation through FDA orphan drug filings, EMA priority medicines submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up prescription volume modeling triangulated against top-down market sizing from reimbursed access program disclosures and academic medical center capacity reports.
Forecast inputs considered treatment modality segmentation by product type, patient age stratification, administration route complexity, and regional regulatory cluster across the analysis window. CAGRs derived from patient prevalence epidemiology, newborn screening expansion scenarios, and gene therapy manufacturing capacity buildout trajectories. Modeled assumptions incorporated viral vector production yield improvements, cyclodextrin formulation scale-up economics, and payer contracting evolution from chronic to one-time reimbursement structures.
Practitioners should monitor plasmid supplier qualification delays, neonatal screening pilot outcomes, and gene therapy CMC regulatory guidance revisions for early signals requiring forecast adjustment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Adipose Derived Stem Cell Therapy Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market