
 Polymerase Chain Reaction Reagent Market | 2026-2036
Polymerase Chain Reaction Reagent Market Size, Share, and Industry Trends Forecast 2026-2036
Polymerase Chain Reaction Reagent Market Insights
Direct distribution to large reference laboratories is fragmenting as regional distributors and group purchasing organizations gain leverage over procurement decisions. Thermo Fisher Scientific dominates bulk reagent supply contracts through backward integration into enzyme manufacturing. QIAGEN differentiates with end-to-end workflow solutions spanning sample prep through detection. Bio-Rad Laboratories competes on thermal cycler-reagent bundling in academic channels.
Polymerase chain reaction reagents are biochemical formulations containing thermostable DNA polymerases, deoxynucleotide triphosphates, sequence-specific oligonucleotide primers, and optimized buffer systems that enable exponential amplification of target nucleic acid sequences through thermal cycling, primarily serving molecular diagnostics and life science research applications. DNA polymerase formulations command premium positioning due to enzyme fidelity and hot-start patent estates. Primers represent the fastest-expanding product category as custom synthesis scales and synthetic biology applications multiply. Kit packaging captures the dominant share of end-user value through workflow integration and regulatory documentation bundled with reagents.
The FDA oversees in vitro diagnostic reagent classifications and quality system requirements under 21 CFR Part 820, while the EMA's In Vitro Diagnostic Regulation imposes new conformity assessment burdens on reagent manufacturers seeking European market access. China's NMPA accelerates review pathways for domestic innovative diagnostic reagents through priority审评 procedures. Stakeholders must monitor evolving premarket submission requirements across major jurisdictions as regulatory divergence creates compliance complexity for multinational reagent portfolios.
Market Dynamics
Thermal cycler miniaturization and point-of-care nucleic acid testing are compressing batch-size requirements and fragmenting reagent purchasing authority away from centralized procurement offices.
Growth Catalysts
- IVDR Implementation:Europe's In Vitro Diagnostic Regulation mandates higher analytical performance documentation, driving laboratories toward validated, pre-bundled reagent kits with embedded quality controls.
- CRISPR-Diagnostics Convergence:Gene-editing workflows are expanding demand for high-fidelity polymerases capable of amplifying low-abundance targets prior to guide-RNA mediated detection.
- China's NMPA Priority Review:Accelerated domestic approval pathways for innovative molecular diagnostics are stimulating local reagent manufacturing scale-up in Suzhou and Hangzhou biotech zones.
Market Restraints
- Enzyme Feedstock Concentration:Recombinant DNA polymerase production depends on microbial fermentation capacity concentrated among three contract manufacturers in Germany and Switzerland.
- Primer Synthesis Bottlenecks:Phosphoramidite monomer supply disruptions constrain oligonucleotide output, with single-source dependencies for certain modified base chemistries.
- Reimbursement Compression:US Medicare's MolDX program tightening coverage criteria for molecular diagnostic tests directly constrains reagent volume commitments from hospital laboratories.
Strategic Opportunities
- India's CDSCO Streamlining:New molecular IVD registration guidelines reduce technical documentation burdens for Class C reagents, opening access to diagnostic chains in Mumbai and Bengaluru.
- Digital PCR Migration:Partitioning-based absolute quantification is creating demand for specialized supermix formulations with enhanced inhibitor tolerance for direct blood and tissue lysates.
- Direct-to-Laboratory E-Commerce:Specialized reagent distributors are building digital procurement platforms that bypass traditional medical-device distribution tiers, capturing margin and transaction data.
Industry Challenges
- Assay Transfer Validation:Clinical laboratories face 12-18 month timelines to revalidate molecular diagnostic workflows when switching reagent suppliers, creating switching costs that entrench incumbent relationships.
- ISO 13485 Audit Density:Reagent manufacturers serving multiple jurisdictions must maintain parallel quality management system certifications, with notified body backlogs extending surveillance audit intervals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polymerase Chain Reaction Reagent Market |
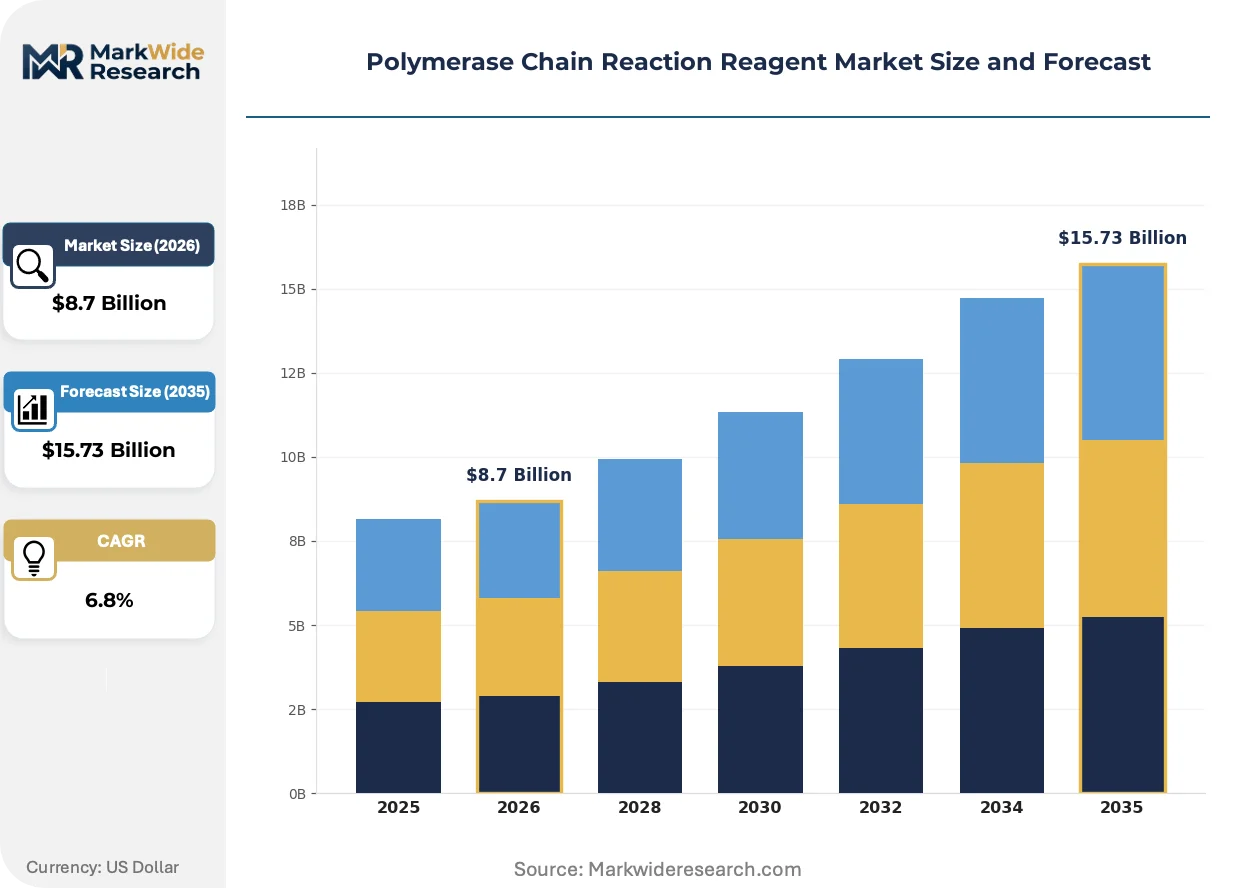
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Polymerase, dNTPs, Primers, Buffers Application: Genetic Testing, Disease Diagnosis, Research, Forensic Analysis End User: Clinical Laboratories, Research Institutions, Pharmaceutical Companies, Diagnostics Centers Packaging Type: Kit, Bulk, Ampoule, Vial |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories Inc., QIAGEN, F. Hoffmann-La Roche Ltd., Agilent Technologies Inc., Abbott, Danaher, Standard BioTools, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polymerase Chain Reaction Reagent Market Trends and Innovations
Multiplexing capabilities and single-cell resolution requirements are forcing reformulation of traditional master mixes, while regulatory documentation burdens are reshaping how reagents are packaged, validated, and sold.
Digital PCR chemistry is hybridizing with real-time quantitative PCR workflows as vendors develop universal supermixes compatible with both partitioning and thermal cycling architectures. Academic core facilities and pharmaceutical target-validation groups are piloting these dual-purpose formulations to reduce inventory complexity. The convergence is compressing the addressable market for application-specific reagent lines while expanding the premium tier for flexible, instrument-agnostic chemistries.
China's NMPA revised its innovative diagnostic reagent approval pathway in 2023, requiring local clinical trials for imported Class III products while offering expedited review for domestically manufactured equivalents. This regulatory asymmetry is accelerating technology transfer agreements between multinational reagent suppliers and Chinese CDMO partners. European and US manufacturers are responding by establishing captive enzyme production within Shanghai and Beijing free-trade zones to qualify for domestic preferential review status.
Hospital laboratory networks are consolidating purchasing decisions through multi-year sole-source agreements that bundle reagent supply with instrument service contracts and assay validation support. This behavioral shift is displacing the traditional spot-buying model where individual principal investigators or department heads selected reagents based on publication precedent or price. The concentration is most visible in the United States, where the ten largest health systems now control molecular diagnostic procurement for over forty percent of hospital-based PCR testing volume.
Polymerase Chain Reaction Reagent Market Segmentation
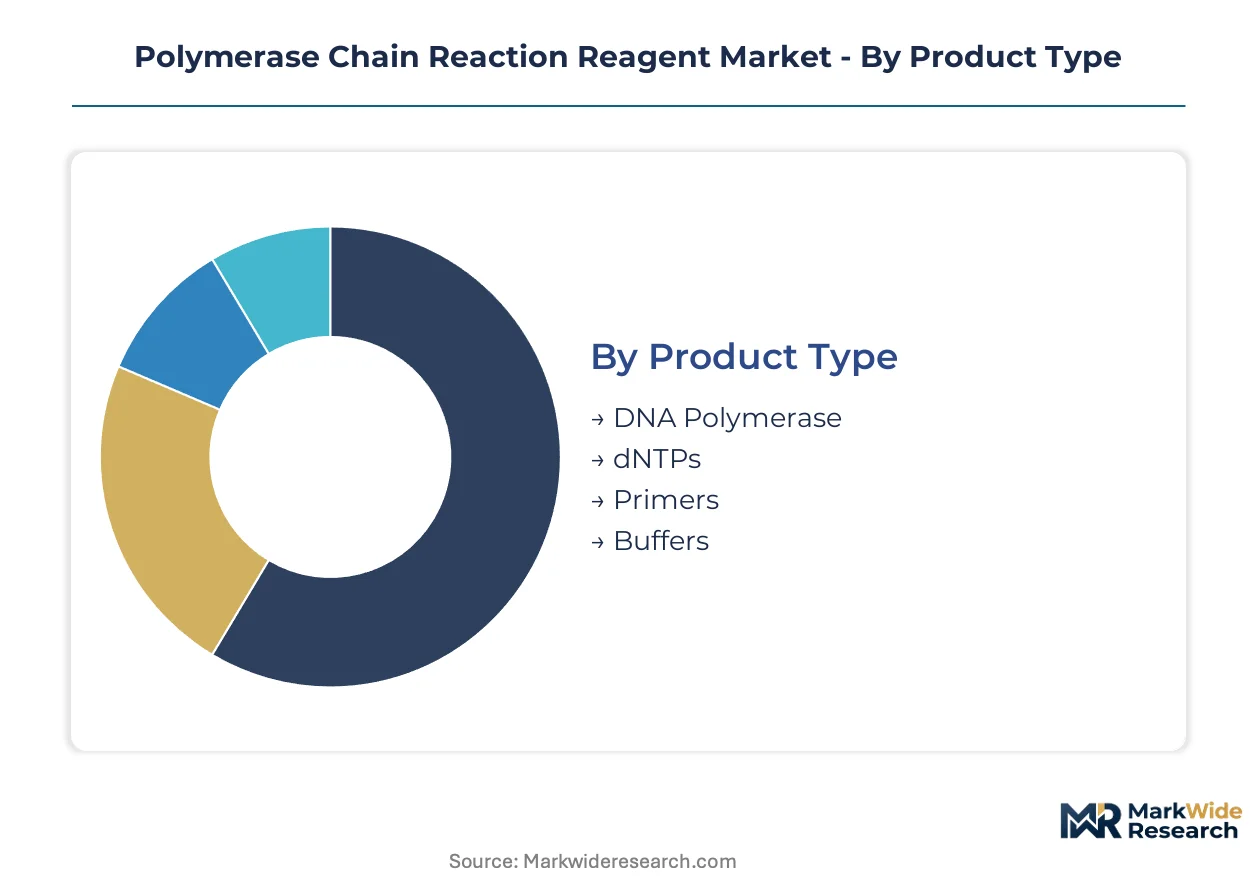
PCR reagent purchasing patterns diverge sharply across segment boundaries. Product formulations, application requirements, and packaging preferences each create distinct procurement workflows with different vendor relationship intensities.
Product Type:
After-sales service intensity peaks with DNA polymerase formulations due to lot-to-lot consistency requirements and enzyme stability troubleshooting.
- DNA Polymerase:Thermostable enzyme formulations with fidelity and hot-start activation specifications determine amplification accuracy. Hospital laboratories in the United States prioritize validated master mixes with embedded quality controls to satisfy FDA oversight requirements. By volume, DNA polymerase leads. By growth pace, primers are ahead.
- dNTPs:Purified deoxynucleotide triphosphate sets with defined concentration ratios and contamination thresholds. Academic core facilities in Germany and Switzerland source through centralized procurement offices to secure fermentation-derived supply from contract manufacturers.
- Primers:Sequence-specific oligonucleotides driving custom synthesis demand. Synthetic biology applications in China's Suzhou and Hangzhou biotech zones multiply order volumes.
- Buffers:Optimized pH and ionic strength solutions enabling thermal cycling performance. Regional distributors bundle buffer formulations with polymerase purchases to simplify inventory management.
Enzyme formulations capture premium positioning through patent-protected hot-start chemistries while primer synthesis scales through automated production platforms.
Application:
Cost tier stratification separates regulated diagnostic applications from research-grade workflows with divergent documentation burdens.
- Genetic Testing:Carrier screening and pharmacogenomic assays requiring validated reagent kits with regulatory documentation. Clinical laboratories expanding molecular diagnostic testing volumes in the United States concentrate procurement through multi-year sole-source agreements.
- Disease Diagnosis:Infectious disease and oncology panel applications with embedded controls and traceability requirements. China's NMPA priority review pathways accelerate domestic reagent manufacturing scale-up for infectious disease panels.
- Research:Exploratory amplification workflows with flexible formulation specifications. Academic channels favor thermal cycler-reagent bundling to reduce per-reaction costs.
- Forensic Analysis:Chain-of-custody protocols with certified reagent lots and contamination prevention. Specialized distributors serve crime laboratories through direct technical support relationships.
Diagnostic applications command price premiums through bundled regulatory documentation while research volumes dominate unit shipments.
End User:
Customer type determines procurement authority concentration versus fragmentation across institutional purchasing structures.
- Clinical Laboratories:Hospital-based and reference laboratories with centralized procurement offices and assay validation requirements. The ten largest US health systems now control molecular diagnostic procurement for over forty percent of hospital-based PCR testing volume.
- Research Institutions:University core facilities and principal investigator laboratories with publication-driven reagent selection. Spot-buying behavior persists where individual researchers select formulations based on methodological precedent.
- Pharmaceutical Companies:Drug development and clinical trial support with GMP-aligned documentation needs. Quality management system certifications from ISO 13485-notified bodies extend surveillance audit intervals for multinational portfolios.
- Diagnostics Centers:Independent testing facilities with high-throughput batch processing and cost-sensitive procurement. Group purchasing organizations gain leverage over procurement decisions in this channel.
Consolidated purchasing among health systems compresses vendor counts while research fragmentation sustains broader supplier bases.
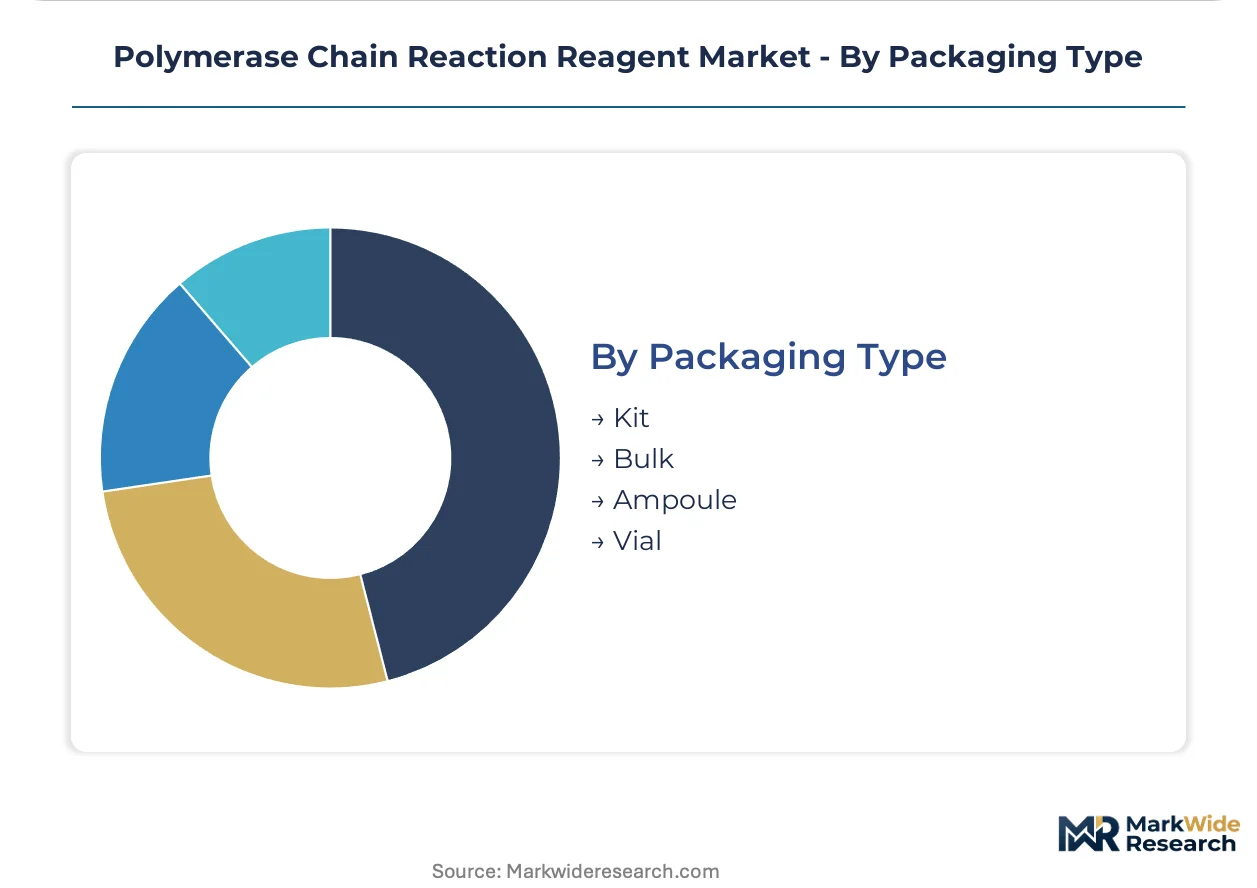
Packaging Type:
Volume requirements scale inversely with point-of-care miniaturization trends reshaping batch-size economics.
- Kit:Pre-formulated master mixes with validated protocols and regulatory documentation. Kit packaging captures the dominant share of end-user value through workflow integration.
- Bulk:Component-level supply for high-throughput facilities with in-house formulation capabilities. Large reference laboratories source bulk enzymes through backward integration into manufacturing.
- Ampoule:Single-use sealed containers for contamination-sensitive forensic and clinical applications. Crime laboratories prioritize ampoule packaging for chain-of-custody integrity.
- Vial:Standard screw-cap containers for research and development flexibility. Academic core facilities favor vial formats for protocol customization.
Kit formats dominate value capture through bundled services while bulk supply serves volume-intensive centralized facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites Europe's enzyme import capacity, while Shanghai Pudong International Airport's pharma-handling terminals anchor Asia-Pacific reagent distribution networks.
United States
Hospital laboratory networks consolidate procurement through multi-year sole-source agreements covering over forty percent of hospital-based PCR testing volume. The FDA's 21 CFR Part 820 quality system requirements shape reagent validation pathways for domestic manufacturers. Boston's biotech corridor and the Research Triangle Park in North Carolina concentrate contract research organizations driving master mix demand.
China
Domestic biotech clusters in Shanghai and Beijing multiply synthetic biology applications and custom primer synthesis orders. The NMPA's 2023 revised innovative diagnostic reagent approval pathway offers expedited review for domestically manufactured equivalents. Suzhou and Hangzhou biotech zones accelerate technology transfer agreements between multinational suppliers and Chinese CDMO partners.
Germany
Academic core facilities in Heidelberg and Munich source fermentation-derived dNTP supply through centralized procurement offices. The EMA's In Vitro Diagnostic Regulation imposes new conformity assessment burdens on reagent manufacturers seeking European market access. Bavaria's enzyme production infrastructure concentrates recombinant DNA polymerase manufacturing capacity.
India
Diagnostic chains in Mumbai and Bengaluru expand molecular testing volumes as CDSCO streamlines Class C reagent registration guidelines. The country's national pharmaceutical regulator reduces technical documentation burdens for molecular IVD products. Hyderabad's genome valley anchors contract research demand for research-grade reagent formulations.
Switzerland
Specialized distributors serve European forensic laboratories through direct technical support relationships and certified reagent lots. Swissmedic maintains stringent quality management system certification requirements for IVD reagent imports. Basel's pharmaceutical corridor concentrates quality control documentation expertise for regulated diagnostic applications.
Polymerase Chain Reaction Reagent Market Competitive Landscape
On the supply side, the industry is consolidating around three contract manufacturers controlling microbial fermentation capacity for recombinant DNA polymerase production. Bulk enzyme supply contracts fragment as regional distributors and group purchasing organizations gain leverage over procurement decisions. Two strategic archetypes dominate: backward-integrated enzyme manufacturers and end-to-end workflow solution providers. Competitive moves concentrate on thermal cycler-reagent bundling and captive production establishment in Chinese free-trade zones.
Among US-based life science conglomerates, Thermo Fisher Scientific Inc. exemplifies the backward-integrated archetype through enzyme manufacturing control, while Bio-Rad Laboratories Inc. occupies a position emphasizing thermal cycler-reagent bundling in academic channels. QIAGEN represents the end-to-end workflow solution provider, anchoring the premium tier through sample prep-to-detection integration. These three structures illustrate how supply-side configuration determines competitive positioning without requiring identical strategic moves.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories Inc. |
| QIAGEN |
| F. Hoffmann-La Roche Ltd. |
| Agilent Technologies Inc. |
| Abbott |
| Danaher |
| Standard BioTools |
| Promega Corporation |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in China's fermentation-derived enzyme production is compressing bulk polymerase pricing while simultaneously incentivizing European contract manufacturers to pivot toward higher-margin custom synthesis services. This utilization asymmetry between Asian and European production bases is reshaping how multinational reagent suppliers configure their regional sourcing portfolios and tier their customer-facing price lists.
Pricing Analysis
Volume-discount tiering separates hospital laboratory networks capturing 40-plus percent of US hospital-based PCR testing volume from spot-buying academic researchers. Three-tier pricing structure across premium, standard, and economy levels aligns with FDA validation documentation, ISO 13485 certification depth, and after-sales technical support intensity. Pricing pressure stems from Medicare's MolDX program tightening coverage criteria, which constrains reagent volume commitments and squeezes mid-tier margins. Diagnostics centers and independent testing facilities exhibit highest price sensitivity, while pharmaceutical companies prioritizing GMP-aligned documentation show lowest sensitivity.
Supply Chain Analysis
Upstream phosphoramidite monomer production draws from Germany, Switzerland, and China, with recombinant DNA polymerase fermentation capacity concentrated in Bavaria and the Rhine corridor. Critical inputs span microbial fermentation feedstocks, synthetic oligonucleotide chemistries, and cold-chain logistics infrastructure. Single-source dependencies for certain modified base chemistries create vulnerability to phosphoramidite supply disruptions. Distribution runs through specialized reagent distributors building digital procurement platforms that bypass traditional medical-device distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as hospital laboratory networks consolidate procurement through multi-year sole-source agreements, fragmenting reagent purchasing authority away from individual principal investigators and compressing vendor counts across the market.
For Market Incumbents: Insulate master mix formulations through captive enzyme production in Shanghai and Beijing free-trade zones to qualify for NMPA domestic preferential review status. Deepen backward integration into primer synthesis automation to offset phosphoramidite monomer supply vulnerabilities. Defend against digital PCR migration threats by developing universal supermix formulations compatible with both partitioning and thermal cycling architectures. For New Entrants and Emerging Players: India's CDSCO-streamlined Class C reagent registration pathway represents the most penetrable entry point for molecular diagnostic chains in Mumbai and Bengaluru. Direct-to-laboratory e-commerce platforms bypassing traditional distribution tiers offer a go-to-market angle with margin capture and transaction data ownership. Research-grade reagent spot-buying channels sustain broader supplier bases against consolidated health system procurement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across automated primer synthesis platforms as synthetic biology applications multiply order volumes. Long-term viability over the analysis window favors acquisition targets with ISO 13485-notified body relationships and multi-jurisdiction quality management system certifications. Watch NMPA technology transfer agreement velocity as an inflection indicator for domestic manufacturing scale-up momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Enzyme Production | Establishing fermentation capacity in Chinese free-trade zones secures NMPA domestic preferential review status for multinational portfolios. |
| Digital PCR Supermix Development | Universal formulations compatible with partitioning and thermal cycling architectures reduce inventory complexity for academic core facilities. |
| Direct-to-Laboratory E-Commerce | Specialized digital procurement platforms bypass traditional medical-device distribution tiers, capturing margin and transaction data ownership. |
| Technology Transfer Agreements | CDMO partnerships in Suzhou and Hangzhou biotech zones accelerate domestic manufacturing scale-up under NMPA priority review pathways. |
| Multi-Jurisdiction QMS Certification | Parallel ISO 13485-notified body relationships extend surveillance audit intervals for reagent manufacturers serving regulated diagnostic applications. |
Research Methodology
Initial hypotheses were tested against primary input from molecular diagnostic laboratory directors, reagent procurement managers at hospital networks, regulatory affairs specialists, and CDMO partnership leads, and refined through secondary validation against FDA 21 CFR Part 820 filings, NMPA priority review pathway documentation, EMA IVDR conformity assessment records, and GPO contract databases. Bottom-up reagent volume modeling triangulated against top-down market sizing from fermentation capacity and phosphoramidite monomer trade flows.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application, end user, and packaging format. CAGRs derived from enzyme formulation volume trajectories, primer synthesis order growth, and kit packaging value capture rates. Industry-specific forecast inputs incorporated thermal cycler miniaturization trends and point-of-care nucleic acid testing diffusion patterns.
Macroeconomic conditions sit as an overlay; deviation in biotech venture funding cycles, healthcare reimbursement policy, and cross-border technology transfer regulations would shift the trajectory. Cross-checking against hospital laboratory capital expenditure surveys and academic core facility budget allocations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Cell Lysis and Dissociation Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Custom Peptide Synthesis Services Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Cell Lysis and Disruption Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Isothermal Nucleic Acid Amplification Technology (INAAT) Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Global High Throughput Screening Market
Biotechnology Services
Antibody Contract Development & Manufacturing Organization Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
Drug Discovery Services Market