
 Peptide and Oligonucleotide CDMO Market | 2026-2036
Peptide and Oligonucleotide CDMO Market Size, Share, and Industry Trends Forecast 2026-2036
Peptide and Oligonucleotide CDMO Market Analytics
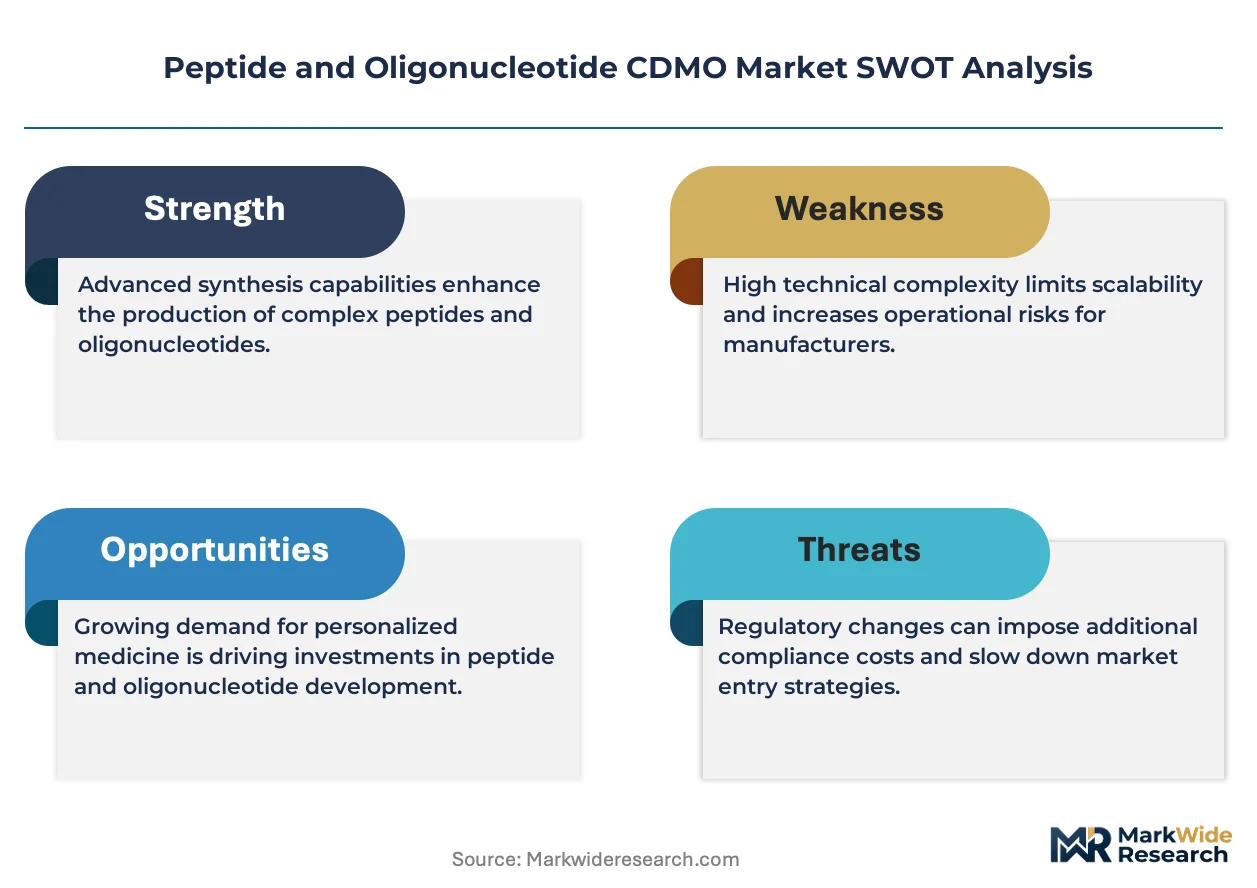
Capital-intensity divergence between integrated multiproduct platforms and single-modality specialists is bifurcating the competitive landscape. Lonza Group Ltd. leverages its Swiss manufacturing base and bioconjugation expertise to anchor high-value peptide programs for global pharma clients. Bachem Holding AG specializes in solid-phase peptide synthesis at scale, dominating long-acting injectable APIs for metabolic and oncology indications. Wuxi Apptec Co., Ltd. competes through integrated discovery-to-commercialization services, extending its reach across oligonucleotide chemistry and analytical development.
Peptide and oligonucleotide CDMOs synthesize complex biomolecules through stepwise chemical assembly, with solid-phase peptide synthesis achieving chain lengths exceeding fifty amino acids and oligonucleotide production requiring phosphoramidite chemistry with sub-ppm impurity thresholds. These capabilities serve pharmaceutical and biotechnology firms seeking outsourced manufacture of GLP-1 agonists, antisense therapies, and siRNA drug substances. Peptide therapeutics generate the deepest revenue pools among product types, reflecting manufacturing complexity and patent-protected demand for metabolic disease treatments. Injectable delivery mode commands premium pricing due to sterile fill-finish requirements and stability validation protocols that oral and topical formats avoid. Automated synthesis technology is displacing manual batch approaches in oligonucleotide production, shortening campaign timelines and reducing solvent waste.
FDA enforces current Good Manufacturing Practice standards for peptide APIs through rigorous pre-approval inspections, while EMA's MDR framework imposes traceability and quality-system requirements on European-sourced oligonucleotide starting materials. China's NMPA aligns with ICH Q7 guidelines for API manufacture, creating harmonized compliance burdens for CDMOs serving multinational sponsors. Switzerland's Swissmedic maintains bilateral recognition agreements with both FDA and EMA, positioning Swiss-based manufacturers such as Bachem and Lonza as regulatory bridgeheads for global programs. Stakeholders must monitor how FDA's evolving guidance on continuous manufacturing and real-time release testing reshapes capital allocation between batch and flow-chemistry platforms.
Market Dynamics
Continuous flow chemistry is compressing batch cycle times for peptide APIs while FDA's real-time release testing guidance forces CDMOs to reconfigure quality infrastructure around in-process analytics rather than end-point testing.
Growth Catalysts
- GLP-1 Agonist Manufacturing Surge:Metabolic disease programs from Novo Nordisk and Eli Lilly are absorbing solid-phase synthesis capacity at specialized CDMOs, with demand for long-acting injectable peptide APIs outstripping qualified manufacturing slots.
- EMA MDR Traceability Mandates:European-sourced oligonucleotide starting materials now require documented supply chain genealogy, driving sponsor companies toward CDMOs with integrated quality management systems rather than fragmented toll manufacturers.
- Phosphoramidite Chemistry Automation:Automated synthesizer platforms are displacing manual oligonucleotide production, shortening campaign timelines from weeks to days and enabling cost-competitive siRNA drug substance supply.
Market Restraints
- Specialized Raw Material Concentration:Fmoc-protected amino acid supply concentrates among three German and Japanese chemical suppliers, exposing peptide CDMOs to input cost volatility and allocation risk during demand spikes.
- Swissmedic Bilateral Dependency:Switzerland's regulatory bridgehead status for FDA-EMA parallel filings creates capacity bottlenecks at Swiss-based manufacturers, limiting sponsor options for globally harmonized programs.
- Biologic Substitution Threat:Recombinant peptide expression in microbial systems offers alternative manufacturing routes for simpler sequences, pressuring chemical synthesis CDMOs on cost for sub-30 amino acid products.
Strategic Opportunities
- India CDMO Capacity Expansion:CDSCO's alignment with ICH Q7 guidelines is enabling Indian manufacturers to qualify for US and European sponsor programs, creating a lower-cost alternative to Swiss and US capacity for non-complex peptides.
- Antisense Therapeutic Pipelines:Neurology and rare disease sponsors are advancing chemically modified oligonucleotide programs that require specialized conjugation and purification capabilities beyond standard phosphoramidite production.
- NMPA Green Channel Acceleration:China's priority review pathways for innovative biologics are compressing regulatory timelines, attracting multinational sponsors to establish captive or partnered manufacturing within NMPA jurisdiction.
Industry Challenges
- Peptide Analytical Scientist Scarcity:Mass spectrometry and HPLC method development for complex peptide impurity profiling requires specialized training that outpaces current academic pipeline output.
- Continuous Manufacturing Validation Burden:FDA's emerging guidance on process analytical technology deployment demands substantial capital for sensor integration and data infrastructure before real-time release becomes operational.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peptide and Oligonucleotide CDMO Market |
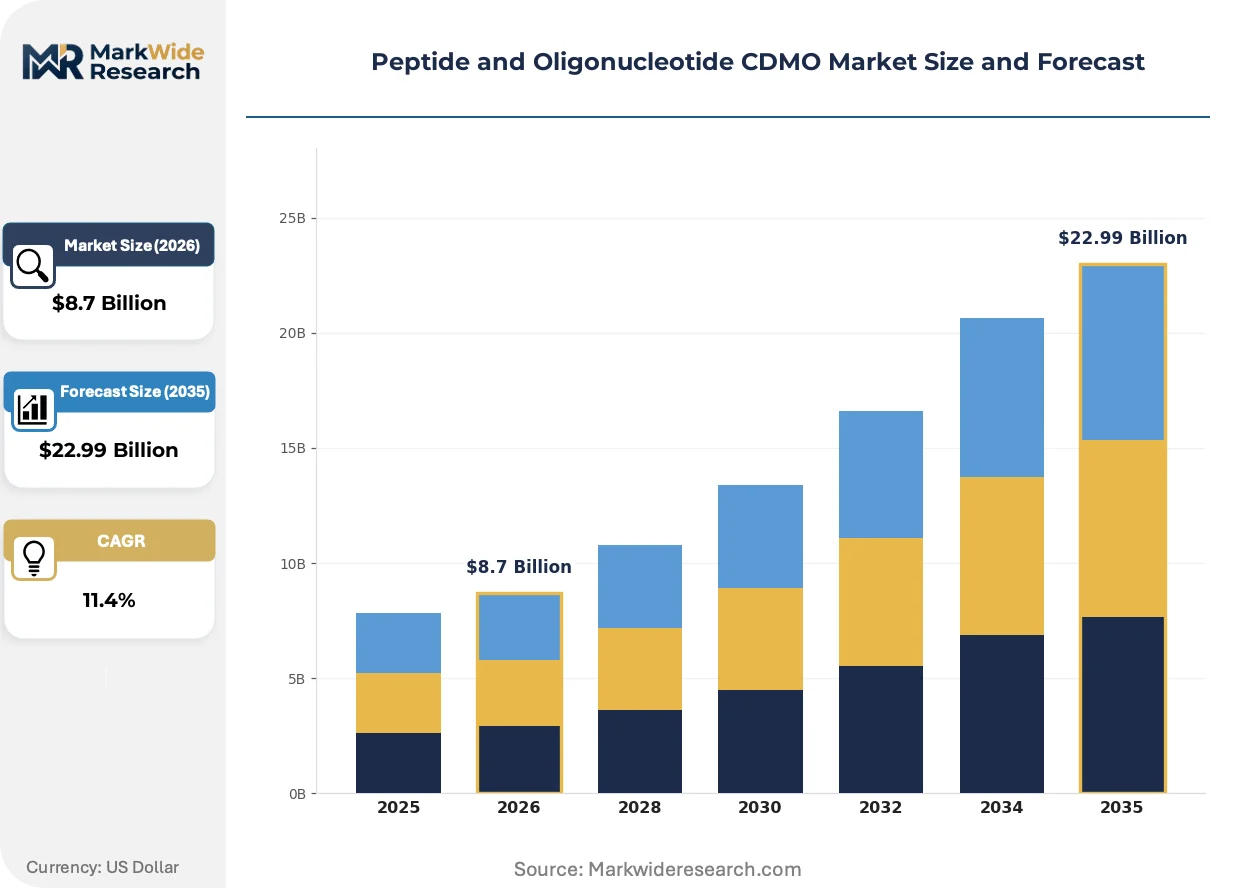
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peptide Therapeutics, Oligonucleotide Therapeutics, APIs, Raw Materials Delivery Mode: Injectable, Oral, Topical, Intranasal End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Research Organizations Technology: Solid-Phase Synthesis, Liquid-Phase Synthesis, Automated Synthesis, Purification Technologies |
| Companies Covered | Catalent, Inc., PolyPeptide Group, Lonza Group Ltd., Corden Pharma GmbH, Wuxi Apptec Co., Ltd., Thermo Fisher Scientific Inc., Bachem Holding AG, Genscript Biotech Corporation, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peptide and Oligonucleotide CDMO Market Evolving Landscape
Digital process control systems and modular manufacturing platforms are converging to enable smaller-batch, higher-flexibility production models that align with personalized medicine pipeline requirements.
Microfluidic reactor technology for solid-phase peptide synthesis is miniaturizing reaction volumes while maintaining yield and purity specifications. Mid-sized biopharma sponsors are piloting these systems for clinical-phase API supply, attracted by reduced solvent waste and faster scale-up. The technology is compressing capital requirements for entry-level peptide manufacturing, enabling specialist CDMOs to compete with integrated multiproduct platforms on niche programs.
EMA's updated MDR framework for in vitro diagnostic companion devices is extending traceability requirements to oligonucleotide components used in PCR-based patient stratification assays. CDMOs serving diagnostic-pharma convergence programs must now maintain dual quality systems for GMP and IVDR compliance. European sponsors are consolidating supplier relationships to reduce audit burden, favoring CDMOs with integrated regulatory affairs capabilities.
Biopharma procurement functions are consolidating peptide and oligonucleotide sourcing under single vendor management frameworks that bundle discovery chemistry, API manufacture, and drug product fill-finish. This organizational change is displacing fragmented toll-manufacturing relationships where sponsors managed multiple handoff points. The shift is most visible among US-based mid-cap biotechnology companies seeking to compress program timelines and reduce quality system redundancy.
Peptide and Oligonucleotide CDMO Market Segmentation
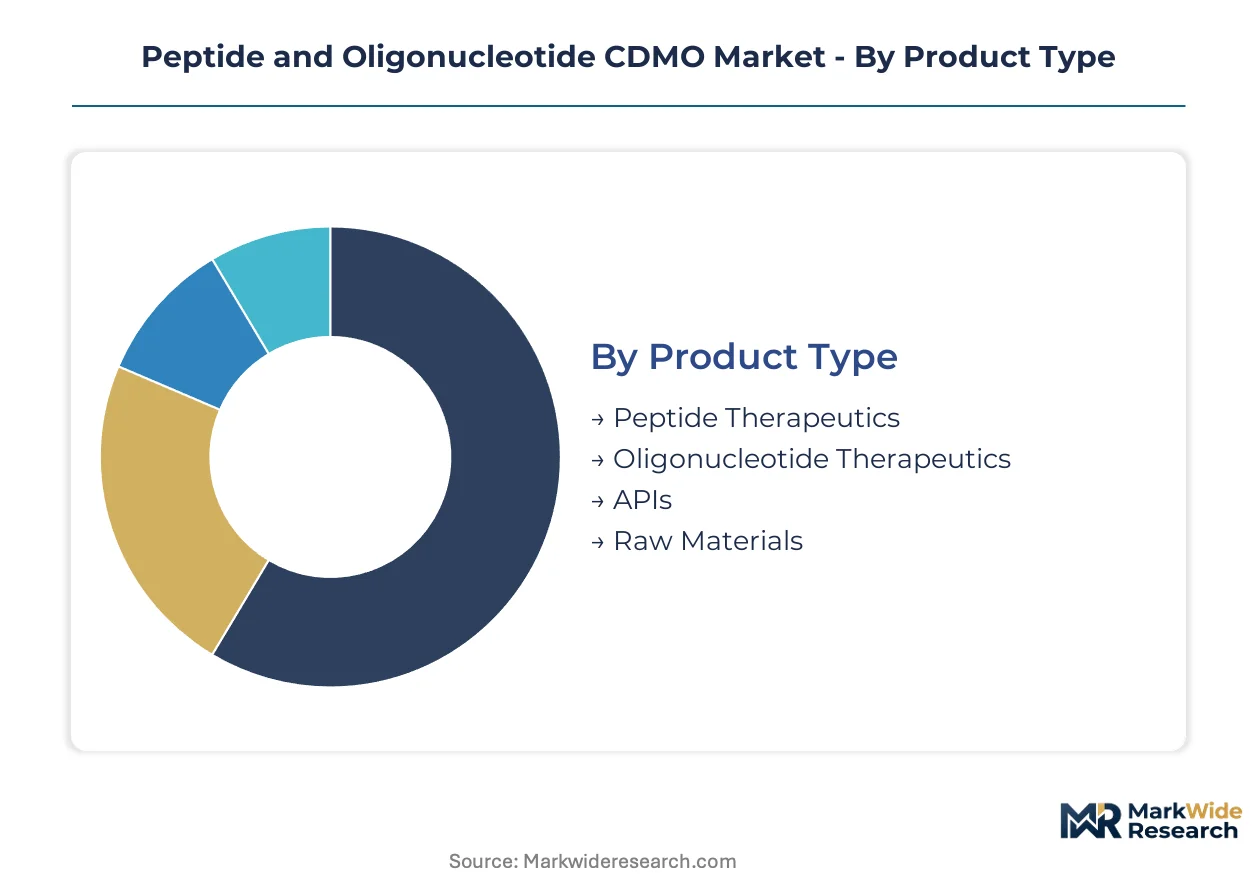
Peptide and oligonucleotide CDMOs serve divergent manufacturing requirements across therapeutic modalities and delivery formats. Segmentation reveals how capital allocation, regulatory burden, and technical specialization concentrate revenue across distinct service categories.
Product Type:
Peptide therapeutics flow through high-value, capacity-constrained channels serving metabolic disease sponsors, while oligonucleotide programs route through automated synthesis platforms with shorter campaign cycles.
- Peptide Therapeutics:Complex biomolecules synthesized through solid-phase or liquid-phase assembly, typically exceeding thirty amino acids with multiple post-translational modifications. Demand concentrates in Switzerland and the United States where FDA and Swissmedic inspections anchor qualified capacity for GLP-1 agonist APIs. Manufacturing complexity sustains premium pricing despite raw material concentration risk from Fmoc-protected amino acid suppliers.
- Oligonucleotide Therapeutics:Chemically modified RNA or DNA sequences requiring phosphoramidite chemistry with sub-ppm impurity thresholds. Antisense and siRNA programs from neurology-focused biotechnology firms are absorbing automated synthesis capacity at specialized CDMOs. EMA MDR traceability mandates favor integrated manufacturers over fragmented toll producers.
- APIs:Isolated drug substances serving both peptide and oligonucleotide final drug products.
- Raw Materials:Protected amino acids, phosphoramidite monomers, and specialty reagents supplying upstream synthesis operations.
By volume, peptide therapeutics leads. By growth pace, oligonucleotide therapeutics is expanding most quickly.
Delivery Mode:
Cost tier stratification separates sterile injectable manufacturing—demanding fill-finish infrastructure and stability validation—from oral and topical formats with lighter capital requirements.
- Injectable:Parenteral delivery systems requiring sterile manufacturing suites, automated filling lines, and cold-chain stability protocols. Novo Nordisk and Eli Lilly metabolic programs are absorbing qualified injectable peptide capacity faster than CDMOs can expand. FDA pre-approval inspections and EMA MDR compliance create qualification bottlenecks that sustain premium pricing tiers.
- Oral:Peptide formulations modified for gastrointestinal absorption through cyclization or permeation enhancers. Biotechnology sponsors in the United States are piloting oral GLP-1 programs that compress development timelines compared to injectable equivalents. Manufacturing avoids sterile infrastructure but requires specialized formulation expertise.
- Topical:Transdermal peptide delivery for dermatology and localized metabolic applications.
- Intranasal:Oligonucleotide and peptide administration through mucosal absorption pathways.
Injectable commands the highest revenue per kilogram. Oral is climbing the fastest as metabolic sponsors pursue patient convenience differentiation.
End User:
Customer type determines contract structure, with pharmaceutical companies demanding integrated discovery-to-commercialization partnerships while research institutions purchase discrete analytical services.
- Pharmaceutical Companies:Multinational sponsors consolidating peptide and oligonucleotide sourcing under single vendor management frameworks. Procurement functions are displacing fragmented toll-manufacturing relationships to compress program timelines. Swiss and US-based CDMOs capture disproportionate share through FDA-EMA parallel filing capabilities.
- Biotechnology Firms:Mid-cap sponsors prioritizing speed-to-IND over manufacturing scale, favoring CDMOs with integrated regulatory affairs and discovery chemistry services. China's NMPA green channel is attracting these firms to establish partnered manufacturing within Asian jurisdiction.
- Research Institutions:Academic and government laboratories purchasing gram-scale peptide synthesis and analytical method development.
- Contract Research Organizations:Service providers subcontracting specialized synthesis or purification capabilities.
Pharmaceutical companies contribute the largest contract values. Biotechnology firms are gaining share fastest as antisense and siRNA pipelines mature.
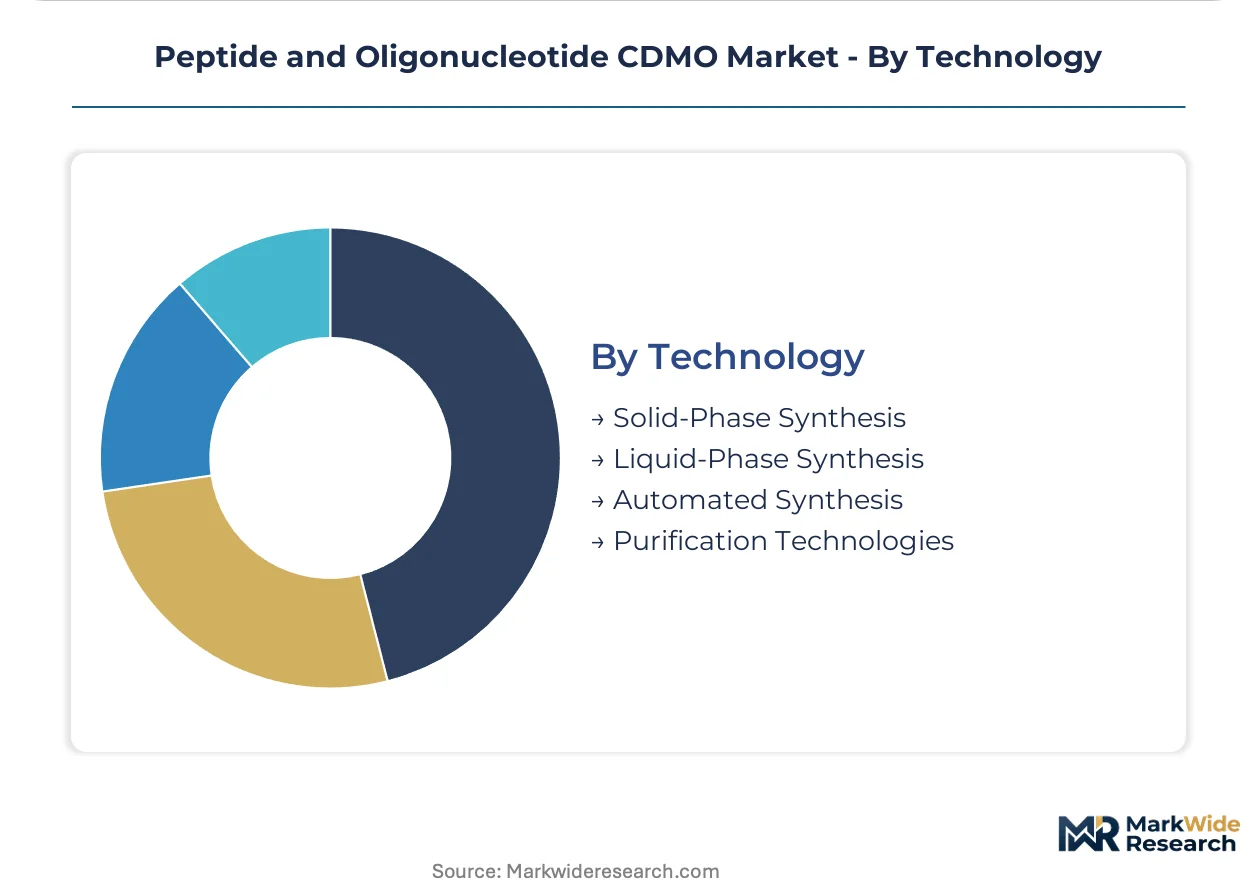
Technology:
Manufacturing maturity separates established solid-phase peptide synthesis from emerging continuous flow platforms that reshape capital efficiency and batch economics.
- Solid-Phase Synthesis:Stepwise amino acid assembly on resin supports, achieving chain lengths exceeding fifty residues for long-acting metabolic peptides. Bachem and Lonza anchor global capacity in Switzerland with validated platforms for FDA-inspected programs. Manual batch approaches face displacement from automated alternatives.
- Automated Synthesis:Robotic phosphoramidite chemistry platforms compressing oligonucleotide campaign timelines from weeks to days. CDMOs serving siRNA drug substance demand are prioritizing capital deployment here over liquid-phase peptide expansion. Reduced solvent waste aligns with sponsor sustainability procurement criteria.
- Liquid-Phase Synthesis:Solution-based peptide assembly for shorter sequences or fragment condensation approaches.
- Purification Technologies:Preparative HPLC and chromatographic systems isolating APIs to specification.
Solid-phase synthesis retains the largest installed base. Automated synthesis is gaining share fastest as oligonucleotide pipelines advance toward commercial scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal specialized manufacturing concentration in jurisdictions with mutual recognition agreements, while emerging production hubs seek qualification parity through regulatory harmonization initiatives.
United States
FDA pre-approval inspections for peptide APIs concentrate sponsor demand around Boston and San Diego biotechnology clusters, with metabolic disease programs from Novo Nordisk and Eli Lilly absorbing qualified capacity. The agency's emerging guidance on continuous manufacturing and real-time release testing is reshaping capital allocation decisions among domestic CDMOs. New Jersey and North Carolina host the densest fill-finish infrastructure for sterile injectable peptides.
Switzerland
Swissmedic maintains bilateral recognition agreements with FDA and EMA, positioning Basel and Visp as regulatory bridgeheads for globally harmonized filing programs. Bachem Holding AG and Lonza Group Ltd. anchor solid-phase peptide synthesis capacity serving long-acting metabolic APIs. The country's specialized workforce scarcity creates bottlenecks that sustain premium pricing tiers for qualified manufacturing slots.
China
NMPA alignment with ICH Q7 guidelines enables domestic CDMOs to qualify for multinational sponsor programs, with Shanghai and Suzhou emerging as oligonucleotide chemistry hubs. The regulator's green channel acceleration for innovative biologics compresses timelines, attracting biotechnology firms to establish partnered manufacturing. Wuxi Apptec Co., Ltd. leverages integrated discovery-to-commercialization services across this jurisdiction.
Germany
Fmoc-protected amino acid supply concentrates among specialized chemical suppliers near Frankfurt and Ludwigshafen, exposing peptide CDMOs to input cost volatility during demand spikes. EMA MDR traceability mandates for European-sourced oligonucleotide starting materials favor CDMOs with integrated quality management systems. Bavaria hosts specialized phosphoramidite monomer production serving automated synthesis platforms.
India
CDSCO alignment with ICH Q7 guidelines is enabling Indian manufacturers to qualify for US and European sponsor programs, creating lower-cost alternatives for non-complex peptides. Hyderabad and Ahmedabad cluster generic peptide API production targeting export markets. The country's analytical scientist pipeline remains thinner than synthesis capacity, constraining method development scale-up.
Peptide and Oligonucleotide CDMO Market Competitive Landscape
Concentration sits with integrated multiproduct platforms and single-modality specialists operating from regulatory bridgehead jurisdictions. Swiss and US-based manufacturers capture disproportionate share through FDA-EMA parallel filing capabilities, while Asian challengers compete on integrated service breadth and cost structure. Two strategic archetypes dominate: capital-intensive integrated platforms offering discovery-to-commercialization bundles, and focused specialists commanding premium pricing through manufacturing complexity. Competitive moves center on automated synthesis technology deployment and quality system integration to meet evolving traceability mandates.
Within the integrated platform tier, Lonza Group Ltd. and Thermo Fisher Scientific Inc. occupy positions spanning multiple therapeutic modalities and geographies. Bachem Holding AG exemplifies the specialized archetype, anchoring solid-phase peptide synthesis capacity from its Swiss base. Wuxi Apptec Co., Ltd. represents the Asian integrated model, extending services across oligonucleotide chemistry and analytical development. Catalent, Inc. and Corden Pharma GmbH sit within the European-American manufacturing network, while Genscript Biotech Corporation and PolyPeptide Group exemplify regional specialists seeking qualification expansion. Merck KGaA occupies a diversified position across life science tools and contract services.
| Leading Market Players |
|---|
| Catalent, Inc. |
| PolyPeptide Group |
| Lonza Group Ltd. |
| Corden Pharma GmbH |
| Wuxi Apptec Co., Ltd. |
| Thermo Fisher Scientific Inc. |
| Bachem Holding AG |
| Genscript Biotech Corporation |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation contracts lock in peptide API supply from Swiss and US manufacturing bases while freezing price visibility against Fmoc-protected amino acid volatility. Pharmaceutical sponsors absorb premium slot pricing at Lonza and Bachem facilities to secure FDA-EMA parallel filing pathways, binding cost predictability to regulatory qualification timelines.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across FDA-inspected premium tiers, volume-scale mid-tiers, and emerging-economy standard tiers. Price differentiation rests on Swissmedic bilateral certification status and sterile fill-finish capability, with Novo Nordisk and Eli Lilly metabolic programs least sensitive due to pipeline priority. Cost compression in standard-tier peptide APIs intensifies as Indian CDSCO-qualified manufacturers expand non-complex synthesis capacity.
Supply Chain Analysis
Strategic stockpiling of Fmoc-protected amino acids and phosphoramidite monomers dominates inventory strategy among peptide CDMOs exposed to German and Japanese chemical supplier concentration. Geographic supply centers on Switzerland, the United States, and China, with raw material dependencies drawing from Frankfurt-area specialty chemical producers and Bavarian phosphoramidite manufacturers. Single-source vulnerability in protected amino acid supply creates structural risk, while distribution runs through sponsor-managed vendor consolidation frameworks that bundle discovery-to-commercialization services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among mid-cap biotechnology firms consolidating peptide and oligonucleotide sourcing under single vendor management frameworks, compressing toll-manufacturer margins and favoring integrated CDMO platforms with regulatory affairs bundling.
For Market Incumbents: Shield qualified manufacturing slots at Swiss and US facilities through accelerated FDA pre-approval inspection readiness and expanded bioconjugation capacity, while deepening backward integration into Fmoc-protected amino acid supply to offset German and Japanese supplier concentration risk. For New Entrants and Emerging Players: Analytical method development scarcity presents service-layer white space where mass spectrometry and HPLC capability gaps constrain incumbent scale-up, with India's CDSCO-aligned manufacturers offering the most penetrable geography for non-complex peptide API qualification and partnered oligonucleotide chemistry scale-up. For Investors and Strategic Acquirers: Capital is best deployed toward automated synthesis technology platforms with phosphoramidite chemistry expertise and integrated quality management systems, with long-term viability hinging on EMA MDR traceability mandate compliance breadth; watch FDA real-time release testing guidance adoption rates as inflection signal for continuous manufacturing platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Synthesis Platform Deployment | Phosphoramidite chemistry automation compresses oligonucleotide campaign timelines from weeks to days at siRNA-focused CDMOs. |
| Regulatory Bridgehead Capacity Expansion | Swissmedic bilateral recognition agreements anchor FDA-EMA parallel filing capabilities for metabolic disease peptide programs. |
| Backward Integration into Raw Materials | In-house Fmoc-protected amino acid production insulates peptide CDMOs from German and Japanese supplier allocation risk. |
| Integrated Quality Management System Investment | EMA MDR traceability mandates favor CDMOs with unified genealogy documentation over fragmented toll manufacturers. |
| Continuous Manufacturing Technology Adoption | FDA process analytical technology guidance drives sensor integration capital deployment for real-time release testing capability. |
Research Methodology
Operator-level perspectives from peptide synthesis chemists, regulatory affairs directors at Swiss and US CDMOs, pharmaceutical procurement executives, and oligonucleotide analytical scientists anchored the qualitative base. Secondary validation drew from FDA pre-approval inspection databases, EMA MDR submission records, Swissmedic bilateral agreement documentation, and NMPA green channel pathway filings. Bottom-up capacity utilization assessments and top-down sponsor pipeline tracking enabled triangulation across the analysis window.
Sensitivity analysis tested forecast outputs against variable assumptions for GLP-1 agonist manufacturing demand absorption, phosphoramidite chemistry automation adoption curves, and CDSCO-qualified Indian manufacturer qualification velocity. Segmentation dimensions spanned product type, delivery mode, end-user archetype, and technology platform across the projection horizon. CAGRs were derived from sponsor pipeline maturity timelines and capacity expansion announcements, with oligonucleotide therapeutic growth rates calibrated to antisense and siRNA clinical advancement velocities.
Underlying assumptions cover sustained FDA-EMA regulatory harmonization, Fmoc-protected amino acid supply continuity, and metabolic disease program sponsor commitment to outsourced peptide manufacturing, with deviation risk concentrated in biologic substitution technology maturation and recombinant peptide expression cost parity. Revision becomes warranted when microbial system peptide yields cross chemical synthesis cost thresholds for sub-thirty amino acid sequences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Asia-Pacific Biotechnology Market
Biotechnology Services
DNA and RNA Sample Preparation Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
Biologics Contract Manufacturing Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Cell Line Development Market
Biotechnology Services
Europe Flow Cytometry Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Biomarker Research Services Market
Biotechnology Services
Research Antibodies Market
Biotechnology Services
GMO Testing Services Market