
 US Digital PCR Market | 2026-2036
US Digital PCR Market Size, Share, and Industry Trends Forecast 2026-2036
US Digital PCR Market Insights
Instrument leasing and reagent rental programs are fragmenting capital barriers for mid-sized clinical laboratories that previously deferred dPCR adoption. Thermo Fisher Scientific Inc. leverages its installed base of qPCR systems to convert existing customers through trade-in pathways toward digital platforms. Bio-Rad Laboratories, Inc. anchors its position through proprietary droplet generation microfluidics that sustain high-margin consumable pull-through. QIAGEN N.V. competes by bundling sample preparation workflows with dPCR readout, reducing hands-on time for hospital pathology departments.
Digital PCR denotes an absolute nucleic acid quantification method that partitions individual target molecules into thousands of discrete micro-reactions, typically achieving single-copy sensitivity without standard curve dependency. The technique eliminates amplification efficiency variation inherent in traditional qPCR, enabling precise rare allele detection for oncology liquid biopsy and transplant rejection monitoring. Consumables dominate revenue contribution as droplet generator cartridges and master mix reagents require repeat purchase per assay run. Instruments command premium positioning but elongate sales cycles given capital equipment procurement protocols at academic institutions. Digital droplet technology leads adoption in clinical settings where partitioning precision directly impacts diagnostic sensitivity for circulating tumor DNA detection.
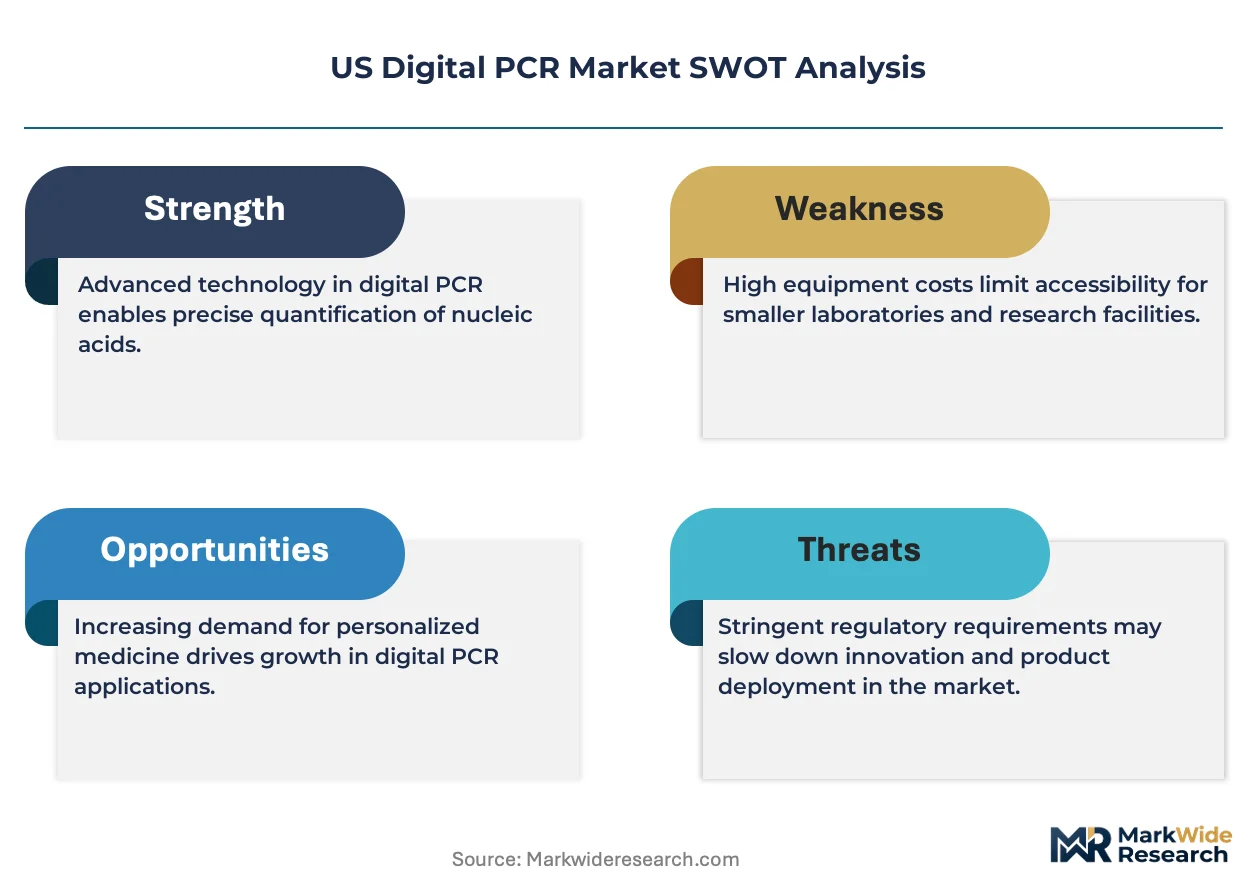
FDA oversight of laboratory-developed tests and companion diagnostic approvals shapes product development roadmaps, while CLIA certification requirements determine serviceable account profiles for vendors. NIH funding allocations and CMS reimbursement decisions for precision oncology tests further condition demand elasticity across hospital and reference laboratory segments. Stakeholders must monitor evolving FDA guidance on dPCR-based liquid biopsy claims as this regulatory clarity will determine which technology platforms secure preferred vendor status at integrated delivery networks.
Market Dynamics
Instrument manufacturers face compressed development timelines as FDA liquid biopsy companion diagnostic pathways accelerate clearance velocity for absolute quantification platforms. The shift from relative qPCR to partition-based enumeration is restructuring procurement patterns across integrated delivery networks.
Growth Catalysts
- NIH precision medicine funding:Research grants to Massachusetts and Maryland institutions create dense early-adopter clusters that validate clinical workflows before commercial scale-out.
- CLIA-certified laboratory expansion:Hospital pathology departments build in-house dPCR capacity to capture margin previously flowing to reference laboratories.
- Circulating tumor DNA detection sensitivity:Single-molecule resolution enables minimal residual disease monitoring that qPCR cannot replicate.
Market Restraints
- Capital equipment procurement cycles:Academic medical centers require 18-24 month budget approval windows that elongate instrument placement timelines.
- Consumable cost structure:Droplet generator cartridges and proprietary master mixes impose per-run economics that challenge high-volume screening applications.
- Technical workflow complexity:Hands-on partitioning steps demand specialized molecular biology training absent in routine clinical chemistry laboratories.
Strategic Opportunities
- Transplant rejection monitoring:Donor-derived cell-free DNA quantification represents an underpenetrated indication beyond oncology liquid biopsy.
- Reagent rental program penetration:Mid-sized community hospitals access dPCR through per-sample pricing that converts capital expenditure to operational budgets.
- CMS precision oncology reimbursement:Coverage decisions for companion diagnostic testing expand addressable patient populations for platform holders.
Industry Challenges
- Bioinformatics interpretation bottleneck:Rare allele calling algorithms require computational biology expertise scarce in community hospital settings.
- Legacy qPCR workflow integration:Pathology information systems lack native dPCR data structures, forcing manual result entry or custom interface development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Digital PCR Market |
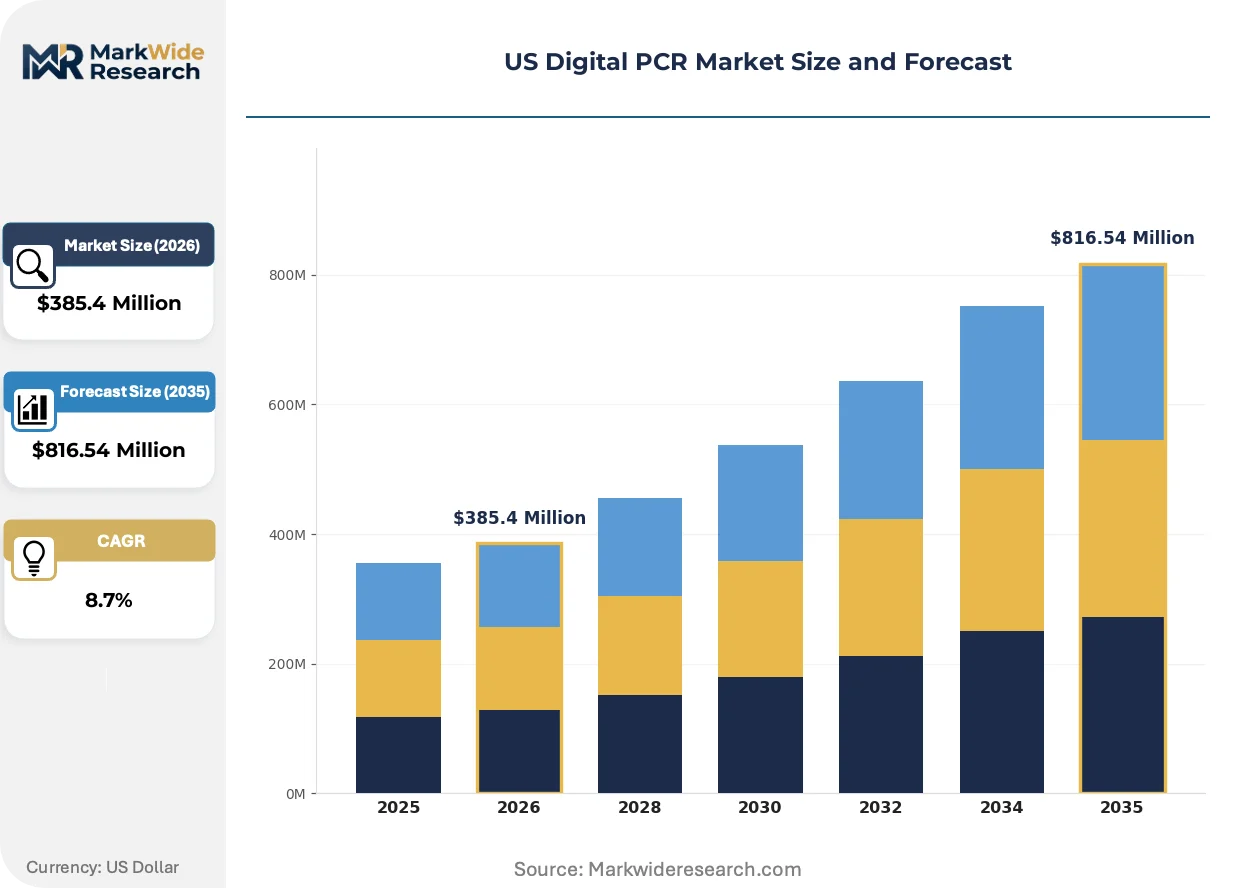
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Consumables, Instruments, Software, Services End User: Research Laboratories, Hospitals, Diagnostic Centers, Academic Institutions Application: Clinical Diagnostics, Research & Development, Environmental Testing, Food Safety Technology: Microfluidics, Nanopore Sequencing, Optical Detection, Digital Droplet Technology |
| Companies Covered | Thermo Fisher Scientific Inc., Bio-Rad Laboratories, Inc., QIAGEN N.V., F. Hoffmann-La Roche Ltd, Danaher Corporation, Merck KGaA, Agilent Technologies, Inc., Sysmex Corporation, Stilla Technologies, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Digital PCR Market Trends and Innovations
Partitioning technology is converging with microfluidic automation to reduce operator-dependent variation in clinical diagnostic settings. These developments are compressing time-to-result and expanding test menu breadth beyond oncology into infectious disease and transplant monitoring.
Chip-based partitioning is hybridizing with integrated fluorescence detection to eliminate manual droplet transfer steps that previously introduced contamination risk. Reference laboratories in the Northeast corridor are adopting these closed-system workflows to meet CLIA complexity requirements for high-complexity testing. The convergence is compressing training timelines for molecular diagnostics technologists while reducing failed run rates.
FDA draft guidance on dPCR-based liquid biopsy companion diagnostics is clarifying analytical validation requirements for circulating tumor DNA claims. This regulatory specificity is enabling manufacturers to design prospective clinical trials that satisfy premarket submission standards. Oncology-focused integrated delivery networks are prioritizing platforms with established FDA clearance pathways over emerging technologies.
Hospital procurement committees are consolidating vendor relationships through multi-year reagent supply agreements that lock in consumable pricing. This purchasing consolidation displaces spot-buying patterns that previously allowed laboratories to trial competing platforms. The shift is most pronounced at academic medical centers with centralized supply chain governance across multiple hospital affiliates.
US Digital PCR Market Segmentation
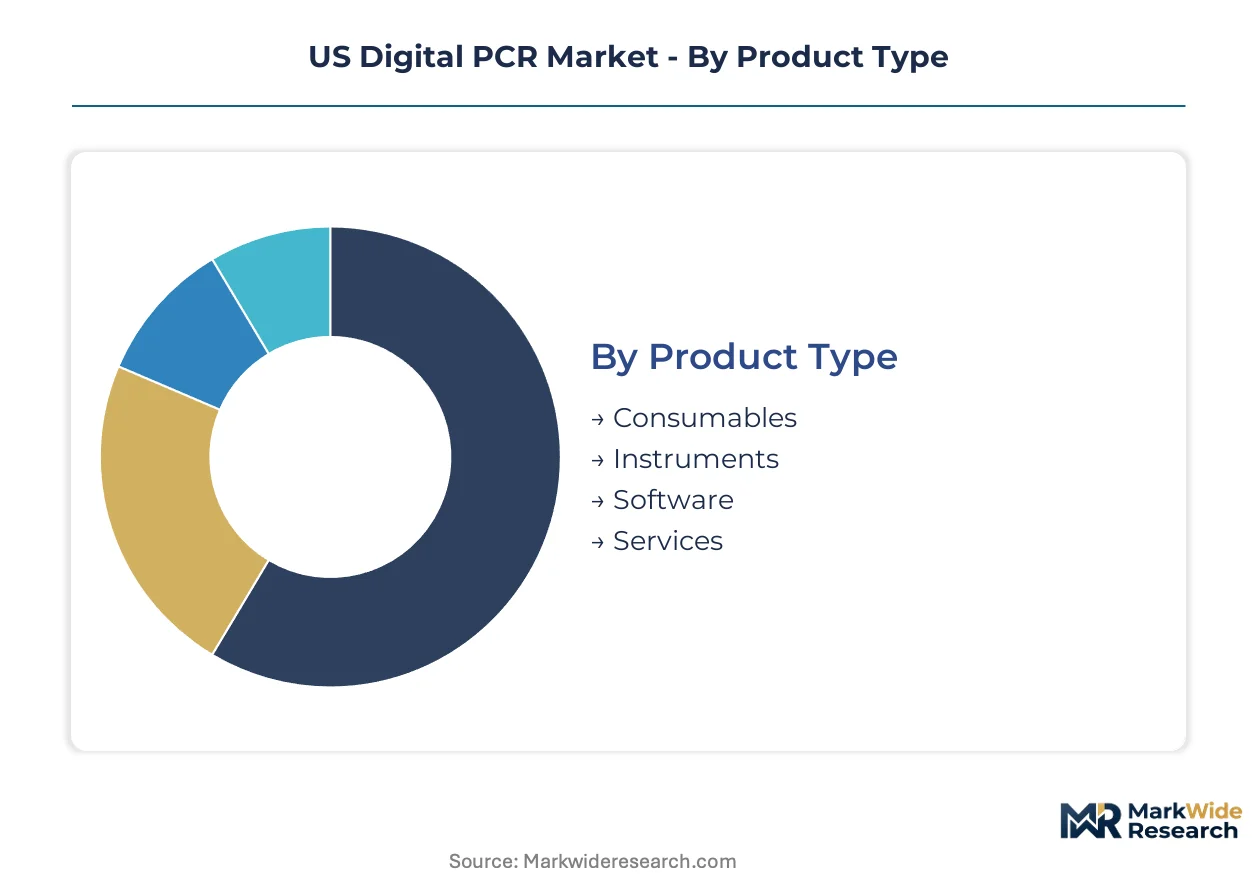
Digital PCR market segmentation reveals how absolute quantification technology penetrates distinct operational environments with divergent procurement priorities. Each dimension—product architecture, customer infrastructure, use case, and underlying physics—carries unique margin profiles and regulatory exposure that determine vendor resource allocation.
Product Type:
Cost tier segmentation distinguishes between recurring revenue streams and one-time capital placements that strain laboratory budget cycles.
- Consumables:Droplet generator cartridges and proprietary master mixes constitute the recurring revenue engine, with per-run economics that lock laboratories into vendor ecosystems. Massachusetts and Maryland research hospitals drive pull-through volume as NIH-funded validation studies expand assay throughput. The consumable cost structure challenges high-volume screening but sustains margins for platform holders.
- Instruments:Capital equipment placements face elongated procurement timelines at academic medical centers, where 18-24 month approval windows delay revenue recognition. Thermo Fisher and Bio-Rad compete through trade-in pathways and leasing programs that convert upfront expenditure to operational budgets. Northeast corridor integrated delivery networks prioritize FDA-cleared platforms with established liquid biopsy workflows.
- Software:Bioinformatics suites for rare allele calling address the interpretation bottleneck that limits community hospital adoption. Cloud-based analysis modules reduce computational infrastructure requirements for mid-sized laboratories.
- Services:Installation validation and CLIA compliance consulting accelerate time-to-first-result for pathology departments building in-house capacity.
Consumables hold installed capacity. Instruments is rotating up the share rankings through reagent rental program penetration.
End User:
Customer type segmentation maps how absolute quantification migrates from research validation into reimbursed clinical workflows.
- Research Laboratories:NIH-funded institutions in the Boston-Cambridge and Bethesda-Rockville corridors validate clinical applications before commercial scale-out, serving as reference sites for platform manufacturers seeking FDA clearance. These early adopters tolerate workflow complexity in exchange for single-molecule sensitivity.
- Hospitals:Pathology departments at academic medical centers build CLIA-certified molecular diagnostics capacity to capture margin previously flowing to reference laboratories, prioritizing closed-system workflows that reduce technologist training timelines. CMS reimbursement decisions for precision oncology tests directly condition capital allocation.
- Diagnostic Centers:Reference laboratories in the Northeast corridor adopt automated microfluidic systems to meet high-complexity testing volume demands from integrated delivery networks.
- Academic Institutions:Core facilities face capital equipment procurement constraints that favor multi-year service agreements over instrument purchases.
Research Laboratories holds installed capacity. Hospitals is rotating up the share rankings as in-house CLIA expansion accelerates.
Application:
Use case segmentation tracks how partition-based enumeration displaces legacy qPCR across diagnostic domains with varying regulatory maturity.
- Clinical Diagnostics:Liquid biopsy companion diagnostics and minimal residual disease monitoring command premium pricing as FDA clearance pathways compress time-to-market for absolute quantification platforms. Circulating tumor DNA detection sensitivity enables applications that relative quantification cannot replicate.
- Research & Development:Biomarker discovery and assay development consume consumables at high throughput but lack reimbursement coverage that would sustain premium pricing.
- Environmental Testing:Pathogen detection in water and soil samples applies dPCR sensitivity to low-abundance target quantification.
- Food Safety:Microbial contamination screening represents a price-sensitive volume opportunity where per-run economics challenge proprietary consumable models.
Clinical Diagnostics holds installed capacity. Research & Development is rotating up the share rankings through NIH precision medicine funding expansion.
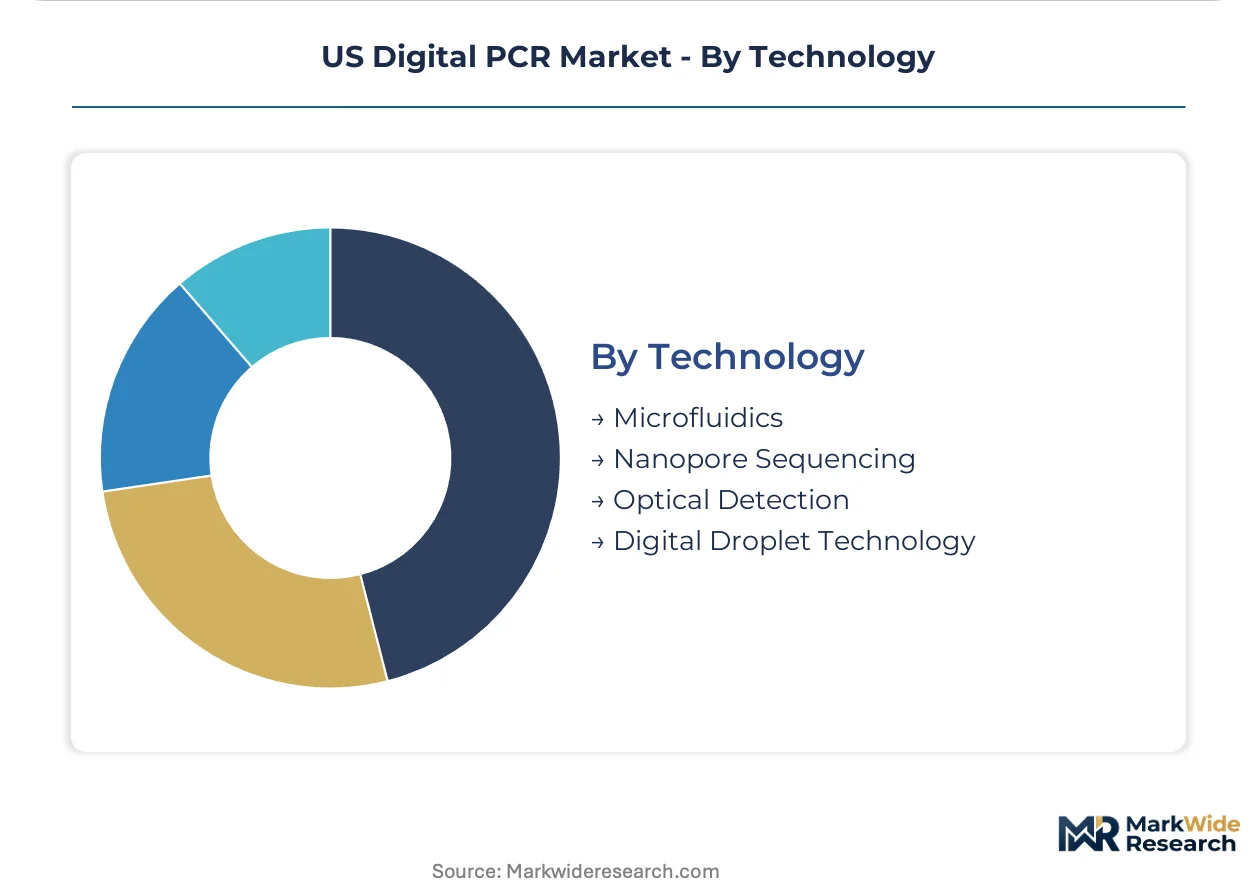
Technology:
Underlying physics segmentation determines partitioning precision, automation integration, and regulatory validation burden.
- Digital Droplet Technology:Proprietary microfluidics from Bio-Rad anchor high-margin consumable pull-through with established FDA clearance precedents for oncology applications. Droplet generation precision directly impacts diagnostic sensitivity for circulating tumor DNA detection in Northeast corridor reference laboratories.
- Microfluidics:Chip-based partitioning with integrated fluorescence detection eliminates manual transfer steps, reducing contamination risk and failed run rates for CLIA-certified hospital laboratories.
- Optical Detection:Endpoint fluorescence readout systems compete on instrument cost but require validated algorithms for rare allele calling.
- Nanopore Sequencing:Hybrid approaches combining partitioning with long-read detection target research applications requiring structural variant resolution.
Digital Droplet Technology holds installed capacity. Microfluidics is rotating up the share rankings through automation convergence trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and NIH-funded research institutions concentrate dPCR procurement decisions in distinct geographic corridors where regulatory proximity shapes technology validation pathways.
Northeast Corridor
Massachusetts and Maryland host the densest clusters of early adopters, with Boston-Cambridge and Bethesda-Rockville institutions validating clinical workflows before commercial scale-out. FDA headquarters proximity accelerates pre-submission consultations for liquid biopsy companion diagnostics. The Massachusetts General Hospital and Dana-Farber Cancer Institute serve as reference sites for platform manufacturers seeking clearance.
Mid-Atlantic
Pennsylvania and New Jersey pathology departments build CLIA-certified molecular diagnostics capacity to capture margin previously flowing to reference laboratories. CMS reimbursement decisions for precision oncology tests directly condition capital allocation at University of Pennsylvania Health System and Jefferson Health. Philadelphia's integrated delivery networks prioritize platforms with established FDA clearance pathways.
West Coast
California's academic medical centers face elongated capital equipment procurement cycles at Stanford Medicine and UCSF Health, where 18-24 month approval windows delay instrument placement. The state's precision medicine initiatives channel research funding toward biomarker discovery applications. San Diego's biotech cluster drives consumable pull-through for assay development workflows.
Southeast
Florida and Georgia hospitals expand in-house dPCR capacity through reagent rental programs that convert capital expenditure to operational budgets. Emory Healthcare and Moffitt Cancer Center adopt automated microfluidic systems to meet high-complexity testing volume demands. The region's community hospital networks trial platforms through per-sample pricing models.
Midwest
Illinois and Ohio reference laboratories consolidate vendor relationships through multi-year reagent supply agreements that lock in consumable pricing. Mayo Clinic and Cleveland Clinic anchor demand for transplant rejection monitoring applications beyond oncology. Chicago's centralized supply chain governance across hospital affiliates accelerates purchasing consolidation trends.
US Digital PCR Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where installed base leverage determines consumable pull-through economics. The market consolidates around three strategic archetypes: diversified life science conglomerates with qPCR conversion pathways, microfluidics specialists with proprietary droplet generation platforms, and sample-to-answer integrators bundling preparation workflows. Dominant competitive moves include trade-in programs targeting legacy instrument replacements and multi-year reagent rental agreements converting capital expenditure to operational budgets.
Among diversified conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions where installed base scale creates conversion pathways from existing qPCR workflows. Bio-Rad Laboratories, Inc. anchors the microfluidics-specialist tier through droplet generation technology that sustains high-margin consumable economics. These three exemplify how platform architecture choices—open versus closed systems, proprietary versus universal consumables—determine competitive positioning across hospital and research segments.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Bio-Rad Laboratories, Inc. |
| QIAGEN N.V. |
| F. Hoffmann-La Roche Ltd |
| Danaher Corporation |
| Merck KGaA |
| Agilent Technologies, Inc. |
| Sysmex Corporation |
| Stilla Technologies |
| Others |
Pricing and Supply Chain Analysis
The I-95 freight corridor linking Massachusetts manufacturing hubs to Maryland distribution centers imposes fuel-indexed surcharges that amplify downstream price differentiation between premium FDA-cleared platforms and economy-tier research instruments. Northeast corridor logistics costs concentrate supply chain leverage among vendors with regional warehousing, compressing margins for distributors serving mid-Atlantic and Southeast accounts without comparable infrastructure density.
Pricing Analysis
Cost-plus contracts with petroleum-indexed freight adjustments dominate consumable supply agreements, particularly for droplet generator cartridges requiring temperature-controlled transport. Price differentiation rests on FDA clearance tier and integrated workflow bundling, with CLIA-certified hospital laboratories showing lowest price sensitivity due to reimbursement coverage, while academic core facilities face capital budget constraints that favor reagent rental conversions. Cost compression in the mid-tier instrument segment is intensifying as leasing programs convert upfront expenditure to operational budgets, eroding traditional hardware margins without consumable lock-in.
Supply Chain Analysis
Upstream feedstock for microfluidic chip fabrication draws from Taiwan semiconductor foundries, German precision molding suppliers, and domestic polymer resin producers in Texas and Louisiana. Critical dependencies include photolithography-grade silicon wafers, medical-grade fluoropolymers, and fluorescence detection optics sourced from Japan and Germany. Single-source vulnerability concentrates in droplet generation microfluidics patents held by limited manufacturers, with distribution running through authorized dealer networks that enforce territorial exclusivity and prevent price arbitrage across integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through multi-year reagent supply agreements at consolidated hospital systems, fragmenting spot-buying leverage that previously allowed laboratories to trial competing platforms. Integrated delivery network procurement centralization across Massachusetts General Brigham and Johns Hopkins Medicine exemplifies this shift toward vendor lock-in over price discovery.
For Market Incumbents: Pre-empt emerging microfluidics automation entrants by accelerating backward integration into droplet generation chip fabrication, securing captive supply of photolithography-grade substrates that constrain competitor scaling. Anchor CLIA-certified service contracts at academic medical centers before reference laboratory outsourcing contracts expire, converting installed instrument bases to multi-year consumable commitments that resist displacement. For New Entrants and Emerging Players: Community hospital pathology departments in Florida and Georgia represent the most penetrable entry point, where reagent rental program gaps and limited bioinformatics infrastructure create workflow friction that simplified closed-system automation can resolve. Transplant rejection monitoring applications beyond oncology liquid biopsy offer indication expansion with lower FDA validation burden and less entrenched incumbent positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates seeking to divest non-core diagnostic platform assets with stranded R&D pipelines. Long-term viability hinges on consumable pull-through economics rather than instrument placement velocity, with FDA clearance pathway momentum serving as the critical inflection signal for platform technology bets.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Liquid Biopsy Clearance Pathway | Accelerates premarket submission timelines for circulating tumor DNA claims at Massachusetts reference sites. |
| Reagent Rental Program Expansion | Converts capital expenditure to operational budgets for mid-sized community hospital laboratories. |
| CLIA-Certified Laboratory Partnership | Captures margin previously flowing to reference laboratories through in-house pathology department capacity. |
| Microfluidic Chip Backward Integration | Secures captive supply of photolithography-grade substrates from Taiwan foundry partners. |
| Transplant Rejection Monitoring Assay Development | Opens underpenetrated indication beyond oncology with lower regulatory validation burden. |
Research Methodology
A standing panel of molecular diagnostics laboratory directors, hospital pathology department heads, FDA regulatory affairs consultants, and GPO contracts managers provided ongoing calibration against primary field interviews with instrument manufacturers and consumable suppliers. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and NIH grant award disclosures. Bottom-up instrument placement and consumable throughput estimates triangulated against top-down market sizing derived from vendor revenue segment disclosures.
Scenario-bracketing framed analytical projections across the modeling period, with base, optimistic, and conservative cases reflecting differential assumptions about FDA liquid biopsy guidance timing and CMS precision oncology coverage expansion. Segmentation dimensions modeled included product architecture tier, end-user facility type, clinical versus research application, and underlying partitioning physics. CAGRs derived from logistic diffusion curves fitted to historical adoption patterns in comparable nucleic acid quantification platforms, with NIH funding allocation trajectories and CLIA laboratory expansion rates serving as key demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in biomedical research funding appropriations or precision oncology reimbursement rates would shift the trajectory materially. Cross-checking against CMS National Coverage Determination timelines and FDA pre-submission meeting outcomes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Europe Downstream Processing Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Molecular Methods Market
Biotechnology Services
Insect Cell Lines Market
Biotechnology Services
In Vivo CRO Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Antibodies Contract Manufacturing Market
Biotechnology Services
Drug Discovery and Development Laboratory Services Market
Biotechnology Services
Drug Discovery Services Market
Biotechnology Services
Global Protein Labeling Market
Biotechnology Services
Prokaryotic Expression Systems Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Global Vector Control Market
Biotechnology Services
Global Eukaryotic Expression Systems Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Serine Protease Market