
 Drug Discovery and Development Laboratory Services Market | 2026-2036
Drug Discovery and Development Laboratory Services Market Size, Share, and Industry Trends Forecast 2026-2036
Drug Discovery and Development Laboratory Services Market Intelligence
Asset-light outsourcing and milestone-based project financing is narrowing the capital barrier for mid-tier biotech firms to access GLP-compliant laboratory capacity. Laboratory Corporation of America Holdings anchors North American toxicology infrastructure through its integrated central lab network. WuXi AppTec Co., Ltd. extends chemistry manufacturing and control services across multiple continents. Eurofins Scientific SE competes through decentralized laboratory footprints that reduce sample logistics burdens for European clients.
Drug discovery and development laboratory services encompass GLP-certified analytical testing, in vitro pharmacology, biomarker quantification, and regulatory dossier preparation conducted under temperature-controlled chain-of-custody protocols to advance therapeutic candidates from target validation through IND submission. Hit identification and lead optimization services command premium pricing due to specialized medicinal chemistry expertise and compressed timelines for patent-sensitive programs. Bioinformatics and CRISPR technology segments attract disproportionate R&D investment as sponsors prioritize genomically targeted therapeutic modalities over traditional small-molecule approaches.
FDA GLP inspections, EMA REACH chemical safety standards, and China's NMPA biologic licensing requirements collectively dictate laboratory accreditation scope, analytical method validation depth, and cross-border data acceptability for multinational submissions. Sponsors selecting laboratory partners now weigh regulatory inspection history alongside technical capability matrices. Stakeholders must monitor evolving OECD mutual recognition agreement coverage as jurisdictions expand localized data residency mandates for clinical trial enabling studies.
Market Dynamics
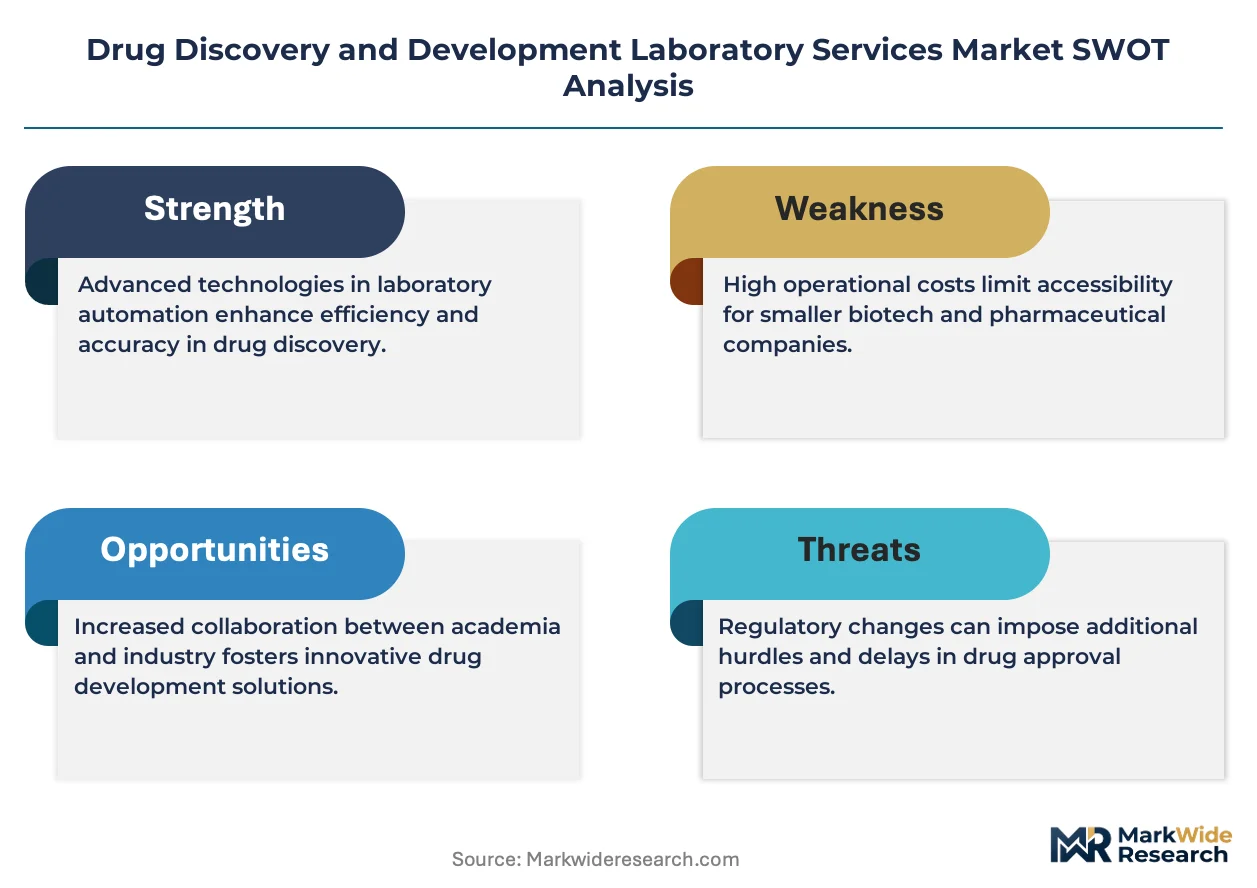
GLP certification requirements from FDA and EMA are compressing vendor selection cycles, forcing sponsors to consolidate testing contracts with laboratories holding multi-jurisdiction inspection histories rather than distributing work across specialized niche providers.
Growth Catalysts
- Biologics pipeline expansion:China's NMPA biologic licensing requirements are accelerating demand for cell-line characterization and viral clearance validation services as domestic developers advance monoclonal antibody programs.
- REACH chemical safety standards:ECHA's expanded substance registration obligations are compelling European sponsors to outsource analytical method development for impurity profiling and genotoxicity assessment.
- CRISPR screening platforms:Functional genomics workflows are displacing traditional high-throughput screening, creating demand for specialized laboratory infrastructure supporting guide-RNA library construction and phenotypic validation.
Market Restraints
- Specialized talent scarcity:Qualified study directors with cross-jurisdiction GLP inspection experience command compensation premiums that inflate fixed cost structures for mid-tier laboratories.
- Reagent supply concentration:Cell culture media and certified reference materials depend on concentrated manufacturing in Germany and the United States, exposing service providers to input cost volatility and customs processing delays.
- Data residency mandates:China's cybersecurity regulations and the European Union's GDPR clinical data provisions are fragmenting cross-border study management, requiring redundant laboratory infrastructure that dilutes capacity utilization rates.
Strategic Opportunities
- India CDMO integration:The country's PLI scheme for pharmaceuticals is attracting sponsor investment in domestic manufacturing, creating parallel demand for adjacent analytical and stability testing services.
- AI-driven molecule design:Convergence of generative chemistry models with automated synthesis platforms is compressing hit-to-lead timelines, rewarding laboratories that integrate computational and wet-lab capabilities under unified project management.
- Cell and gene therapy:Viral vector potency assays and CAR-T cell characterization represent underdeveloped service categories where first-mover laboratories can establish proprietary platform technologies before standardization matures.
Industry Challenges
- Multi-site study coordination:FDA's increasing scrutiny of cross-facility data integrity during pre-approval inspections demands harmonized electronic data capture systems that many legacy laboratories lack capital to deploy.
- Biomarker assay transfer:Sponsor-proprietary immunoassays require extensive bridging studies when moved between laboratories, creating timeline friction that jeopardizes IND submission deadlines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drug Discovery and Development Laboratory Services Market |
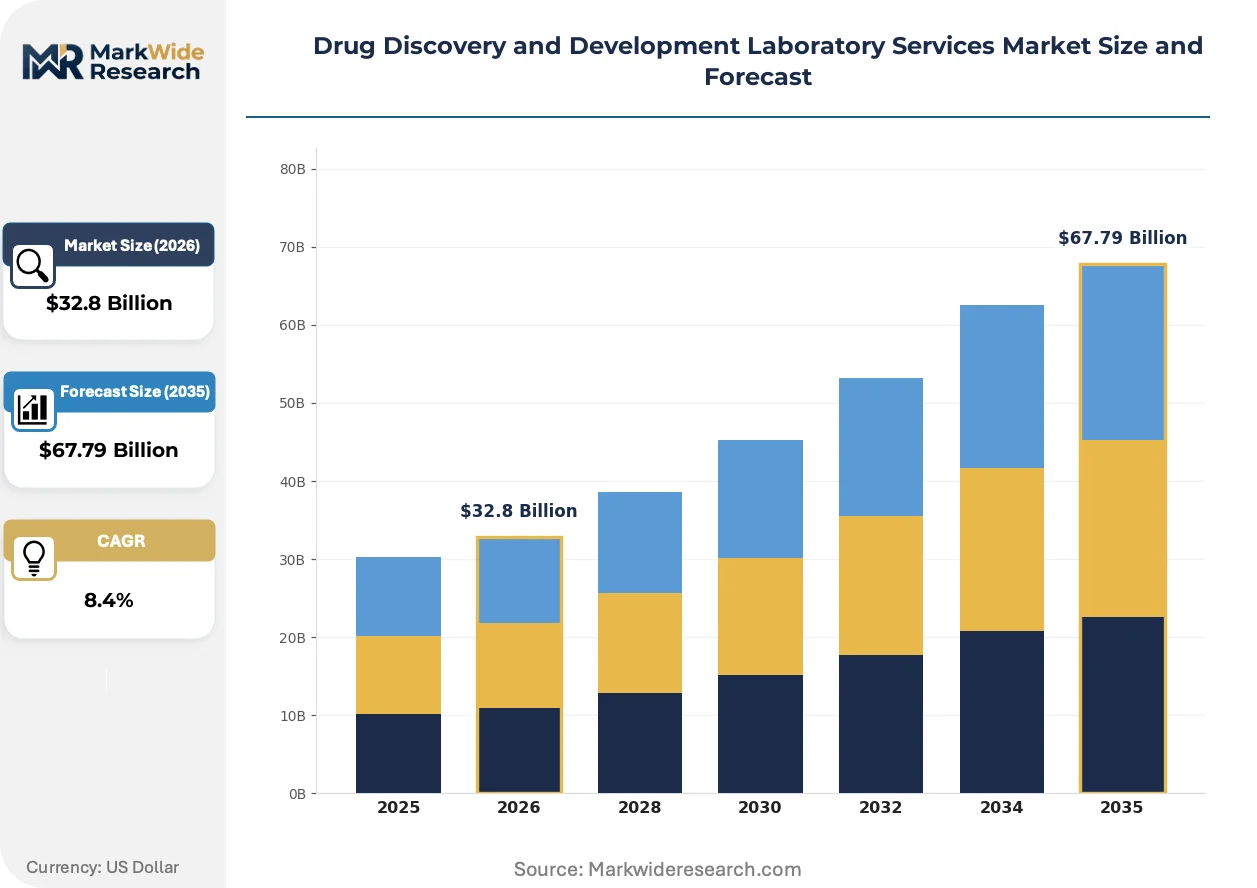
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $67.79 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hit Identification, Lead Optimization, Preclinical Development, Toxicology Technology: High-Throughput Screening, Bioinformatics, CRISPR, Mass Spectrometry End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Research Organizations Application: Oncology, Neurology, Cardiovascular, Infectious Diseases |
| Companies Covered | Laboratory Corporation of America Holdings, Thermo Fisher Scientific Inc., Charles River Laboratories, WuXi AppTec Co., Ltd., EVOTEC SE, F Hoffmann-La Roche AG, Agilent Technologies Inc., Eurofins Scientific SE, Syngene International Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drug Discovery and Development Laboratory Services Market Strategic Shifts & Innovations
Automated laboratory execution systems and distributed manufacturing networks are compressing the traditional separation between discovery chemistry and clinical-scale production, erasing historical handoff friction points.
Organ-on-chip technology is migrating from academic proof-of-concept to regulatory submission packages. Large pharmaceutical sponsors are adopting microphysiological systems for mechanistic toxicology studies ahead of formal FDA qualification. This technology is migrating from exploratory research into IND-enabling safety pharmacology, displacing certain animal model requirements and compressing preclinical development timelines.
EMA's revised guideline on first-in-human clinical trials is mandating enhanced preclinical safety margin justification for high-risk modalities. Sponsors must now submit integrated nonclinical summaries that bridge pharmacokinetic and toxicokinetic data across species. European biotechnology firms are responding by front-loading bioanalytical method validation, extending contractual relationships with GLP laboratories earlier in candidate selection.
Biotech sponsors are unbundling integrated discovery contracts into discrete work packages awarded through competitive bidding platforms. Virtual pharmaceutical companies without captive laboratory infrastructure are sourcing medicinal chemistry, DMPK, and safety assessment through specialized procurement networks. This pattern concentrates contract volume with laboratories offering transparent milestone pricing and real-time data portal access, particularly visible among Boston and San Francisco venture-funded startups.
Drug Discovery and Development Laboratory Services Market Segmentation
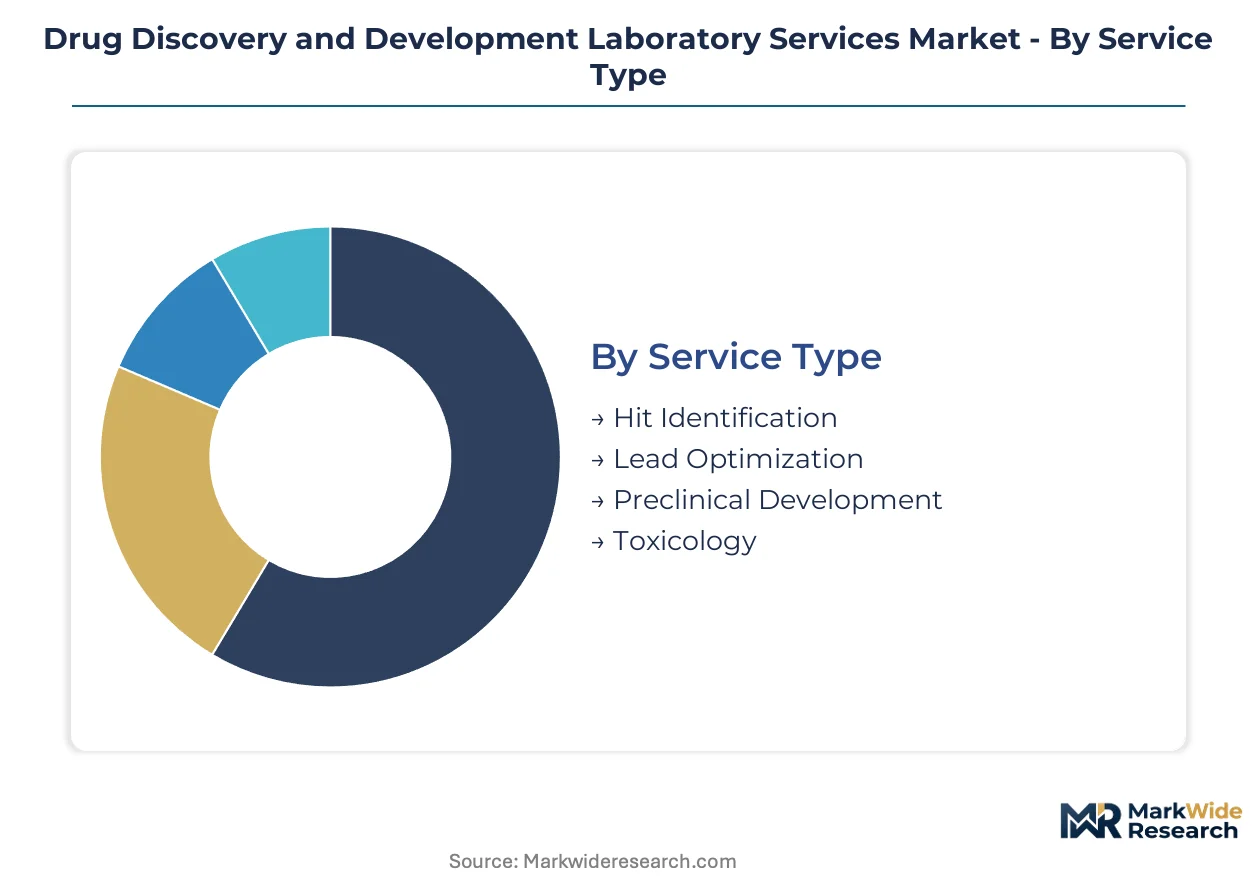
Service differentiation in drug discovery laboratories reflects the staged capital intensity of therapeutic advancement, with early-phase chemistry commanding different capability stacks than GLP-toxicology. Procurement patterns increasingly favor bundled service architectures that compress handoff delays between discovery and IND-enabling phases.
Service Type:
Cost tier differentiation separates exploratory chemistry from regulated safety assessment, with pricing scaling sharply once GLP certification becomes mandatory.
- Hit Identification:Fragment-based and structure-guided screening platforms require specialized protein crystallography and NMR infrastructure. Demand concentrates among Boston and San Francisco venture-funded startups seeking rapid target validation for platform financing milestones. Compressed timelines for patent-sensitive programs sustain premium pricing.
- Lead Optimization:Medicinal chemistry services integrate DMPK prediction with iterative synthesis cycles. China's domestic biotech firms are expanding contractual relationships here as NMPA biologic licensing requirements extend preclinical data packages.
- Preclinical Development:Pharmacokinetic and pharmacodynamic studies bridge candidate selection to regulatory submission.
- Toxicology:GLP-compliant safety assessment represents the highest fixed-cost tier with multi-jurisdiction inspection history as the primary vendor selector.
Hit Identification holds installed capacity. Toxicology is rotating up the share rankings.
Technology:
Application maturity varies sharply across these platforms, with legacy screening infrastructure competing against genomics-native workflows for sponsor R&D allocation.
- High-Throughput Screening:Automated liquid handling and multimodal detection systems process compound libraries against biochemical targets. European sponsors under EMA's revised first-in-human guidelines are reducing reliance here in favor of mechanistic toxicology approaches.
- Bioinformatics:Computational target identification and polypharmacology prediction require specialized data science talent. United States-based laboratories command pricing premiums for integrated cheminformatics pipelines that compress target-to-lead timelines.
- CRISPR:Functional genomics workflows displace traditional screening through guide-RNA library construction.
- Mass Spectrometry:Bioanalytical method development for biomarker quantification and impurity profiling.
High-Throughput Screening holds installed capacity. CRISPR is climbing the fastest.
End User:
Customer type determines contract structure, with virtual biotechs demanding milestone-based pricing and real-time data portals against traditional pharmaceutical annual framework agreements.
- Pharmaceutical Companies:Large sponsors unbundle integrated discovery contracts into discrete work packages awarded through competitive bidding platforms. Multi-site study coordination requirements favor laboratories with harmonized electronic data capture systems.
- Biotechnology Firms:Mid-tier developers without captive infrastructure source medicinal chemistry, DMPK, and safety assessment through specialized procurement networks. Asset-light outsourcing narrows capital barriers to GLP-compliant capacity.
- Academic Institutions:Exploratory research programs generate demand for fee-for-service access to specialized instrumentation.
- Research Organizations:Non-profit and government laboratories contribute to target validation and mechanism-of-action studies.
Pharmaceutical Companies hold installed capacity. Biotechnology Firms are gaining share fastest.
Application:
Therapeutic area concentration reflects pipeline risk-adjusted returns, with oncology dominating sponsor investment despite higher clinical failure rates.
- Oncology:Immuno-oncology and targeted therapy programs drive demand for cell-line characterization and viral vector potency assays. Cell and gene therapy modalities represent underdeveloped service categories where first-mover laboratories can establish proprietary platforms.
- Neurology:Blood-brain barrier penetration studies and CNS safety pharmacology require specialized in vitro and in vivo models. Biomarker assay transfer friction creates timeline pressure that concentrates contracts with laboratories holding established immunoassay bridging capabilities.
- Cardiovascular:Safety pharmacology hERG assays and chronic toxicity studies sustain steady contract flow.
- Infectious Diseases:Antiviral and antibacterial programs generate demand for resistance profiling and PK/PD modeling.
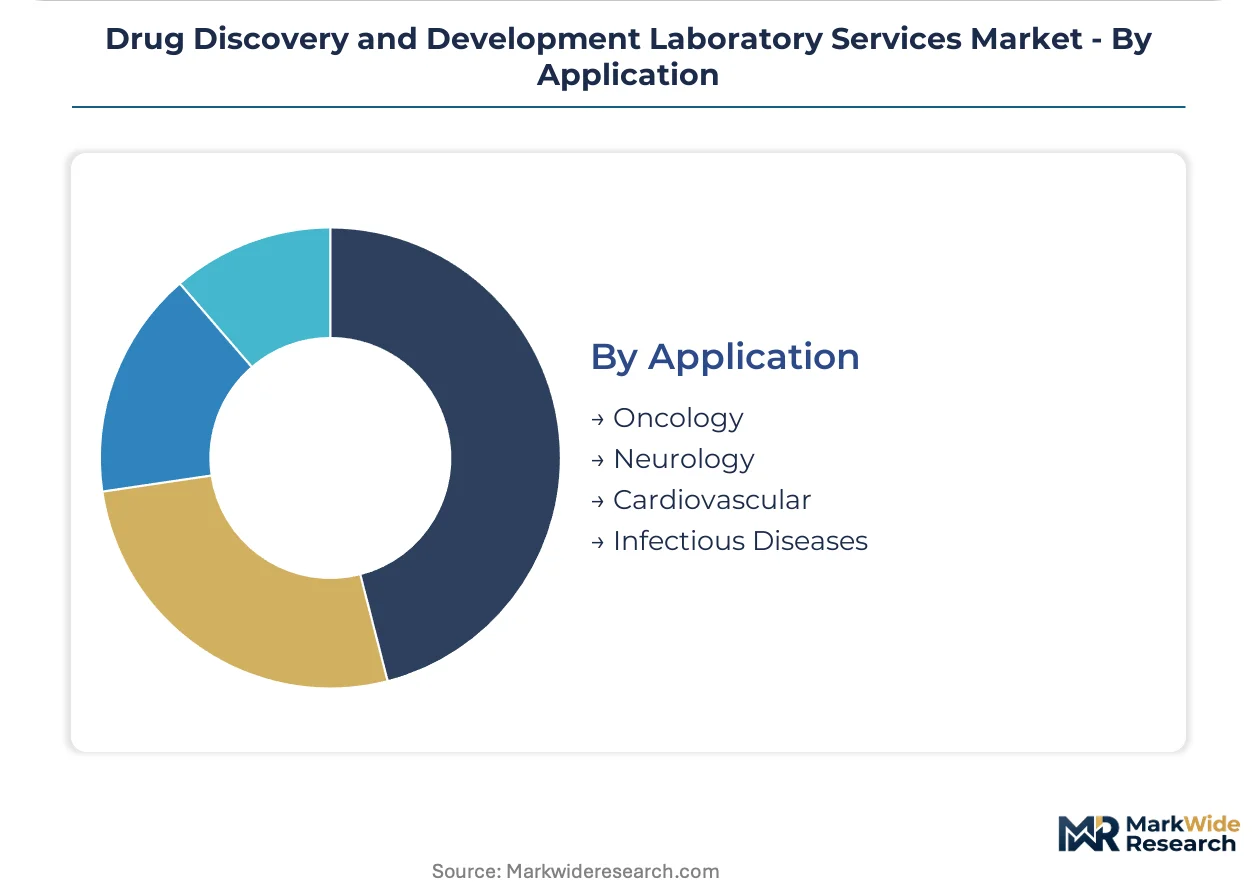
Oncology holds installed capacity. Neurology is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for domestic biotech manufacturing are reshaping laboratory service procurement patterns across major pharmaceutical markets. Regulatory data residency mandates and GLP certification requirements are compelling sponsors to establish localized testing capacity rather than relying on centralized global hubs.
United States
FDA's intensified GLP inspection protocols and IND-enabling study requirements are driving demand for multi-site toxicology infrastructure. The agency's pre-approval inspection scrutiny of cross-facility data integrity favors laboratories with harmonized electronic data capture systems. Greater Boston and San Francisco Bay Area clusters concentrate venture-funded biotech outsourcing contracts for hit identification and lead optimization services.
China
NMPA biologic licensing requirements and domestic monoclonal antibody pipeline expansion are accelerating cell-line characterization and viral clearance validation demand. The country's cybersecurity regulations mandate localized data residency for clinical trial enabling studies. Shanghai and Suzhou industrial parks host expanding GLP-compliant capacity serving both domestic developers and multinational sponsors seeking China-inclusive regulatory submissions.
Germany
ECHA's expanded REACH substance registration obligations are compelling analytical method development outsourcing for impurity profiling and genotoxicity assessment. EMA's revised first-in-human guidelines mandate enhanced preclinical safety margin justification. Munich and Heidelberg clusters concentrate specialized bioanalytical laboratories supporting European biotechnology firms.
India
The PLI scheme for pharmaceuticals is attracting sponsor investment in domestic manufacturing, creating parallel demand for adjacent analytical and stability testing services. CDSCO's evolving biologic licensing framework is driving method validation requirements. Hyderabad and Bangalore industrial corridors are expanding GLP-certified capacity to serve both export-oriented and domestic clinical trial programs.
Switzerland
Swissmedic's alignment with EMA standards and the country's concentration of large pharmaceutical headquarters sustain premium laboratory service demand. Basel's industrial cluster anchors integrated discovery-to-IND service relationships with major sponsors. Geneva and Zurich regions host specialized bioanalytical facilities supporting mechanistic toxicology and biomarker quantification programs.
Drug Discovery and Development Laboratory Services Market Key Industry Players
Channel-controlling players compete with product-specialist players across a market structure consolidating around multi-jurisdiction GLP inspection histories. Tier-one laboratories with integrated central lab networks command framework agreements from large pharmaceutical sponsors. Three archetypes dominate: full-service discovery-to-IND integrators, specialized toxicology and safety assessment providers, and regional analytical testing specialists. Competitive dynamics center on M&A activity absorbing niche capabilities and capacity expansion into data-residency-constrained jurisdictions.
Among North American full-service providers, Laboratory Corporation of America Holdings exemplifies the integrated central lab archetype with extensive toxicology infrastructure. Thermo Fisher Scientific Inc. represents the diversified life sciences conglomerate model spanning instrumentation through contract services. WuXi AppTec Co., Ltd. anchors the Asia-Pacific expansion vector with chemistry manufacturing and control services across multiple continents. These three occupy positions reflecting distinct strategic bets on geographic coverage, service integration depth, and regulatory jurisdiction specialization.
| Leading Market Players |
|---|
| Laboratory Corporation of America Holdings |
| Thermo Fisher Scientific Inc. |
| Charles River Laboratories |
| WuXi AppTec Co., Ltd. |
| EVOTEC SE |
| F Hoffmann-La Roche AG |
| Agilent Technologies Inc. |
| Eurofins Scientific SE |
| Syngene International Limited |
| Others |
Cost & Logistics Intelligence
Cell culture media manufacturing concentrates in Germany and the United States, anchoring input cost volatility that compresses margins for mid-tier laboratories while GLP-certified providers capture pricing premiums through multi-jurisdiction inspection histories.
Pricing Analysis
Certification level creates the primary spread across laboratory service tiers, with FDA and EMA GLP-grade toxicology studies commanding substantial premiums over exploratory chemistry. Three-tier pricing structure across premium, standard, and economy levels reflects vendor inspection history, with multi-site study coordination capabilities justifying top-tier rates. Pricing pressure stems from sponsor consolidation of testing contracts with fewer vendors holding comprehensive accreditation. Virtual biotech firms exhibit highest price sensitivity due to milestone-dependent financing constraints, while large pharmaceutical sponsors prioritize capability matrices over unit cost.
Supply Chain Analysis
Extended payment terms from sponsor-procurement networks strain working capital for specialized reagent suppliers serving this sector. Certified reference materials and cell culture media draw from concentrated manufacturing in Germany, the United States, and select Swiss chemical producers. Single-source vulnerability pervades guide-RNA library construction kits and viral vector raw materials. Distribution runs through temperature-controlled logistics networks with chain-of-custody protocols mandatory for GLP-compliant sample handling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Drug discovery laboratory services represent a compelling service-attach opportunity as regulatory dossier preparation and real-time data portal access expand faster than standalone analytical testing revenue.
For Market Incumbents: Pre-empt sponsor consolidation by acquiring specialized CRISPR screening platforms and organ-on-chip capabilities before standardization matures. Laboratory Corporation of America Holdings and WuXi AppTec demonstrate how integrated central lab networks defend against niche provider displacement. EMA's revised first-in-human guidelines create urgency for front-loaded bioanalytical method validation capacity. For New Entrants and Emerging Players: India's CDMO-adjacent analytical testing corridor offers underpenetrated white-space as PLI scheme manufacturing investment creates parallel stability study demand. Cell and gene therapy viral vector potency assays represent the most penetrable category, lacking established platform technologies. A fee-for-service model with transparent milestone pricing and dedicated project management portals addresses virtual biotech procurement preferences. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional analytical specialists holding single-jurisdiction GLP certification. Long-term viability hinges on multi-continent data residency infrastructure as China's cybersecurity regulations and EU GDPR fragment cross-border study management. Watch for sponsor unbundling of integrated discovery contracts into discrete procurement packages as an inflection signal for specialized provider rollup opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| GLP Certification Expansion | FDA and EMA inspection histories determine vendor selection for IND-enabling toxicology studies. |
| AI-Driven Platform Integration | Generative chemistry models with automated synthesis compress hit-to-lead timelines for patent-sensitive programs. |
| Cell and Gene Therapy Capability Buildout | Viral vector potency assays and CAR-T characterization lack standardized platforms, rewarding first-movers. |
| Data Residency Infrastructure Investment | China's NMPA cybersecurity mandates and EU GDPR require localized laboratory capacity for clinical trial enabling studies. |
| Organ-on-Chip Technology Adoption | Microphysiological systems for mechanistic toxicology displace animal models ahead of formal FDA qualification. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA GLP inspection databases, EMA submission dossiers, and NMPA biologic licensing records. Drug development executives, regulatory affairs leads, and GLP study directors provided qualitative input on vendor selection criteria and inspection preparation protocols. SEC 10-K filings from Laboratory Corporation of America Holdings, Thermo Fisher Scientific, and Eurofins Scientific supplemented capacity and revenue segmentation. Bottom-up service-type demand modeling triangulated against top-down pharmaceutical R&D expenditure allocation.
Forecast inputs include biologics pipeline expansion rates across the United States and China, CRISPR technology adoption curves in functional genomics workflows, and sponsor unbundling patterns for discovery contracts. Segmentation dimensions span service type, technology platform, end-user archetype, and therapeutic application with regional regulatory cluster overlays. CAGRs derive from fitted growth curves calibrated to historical laboratory outsourcing penetration and emerging modality capital intensity.
The forecast holds incumbent behavior within observed patterns; aggressive moves by venture-funded AI-native discovery platforms or state-backed Chinese CDMOs would shift outcomes. Macroeconomic tightening in biotech financing, regulatory harmonization failures between FDA and NMPA, or breakthroughs in fully automated synthesis would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Bio-Services Market
Biotechnology Services
Asia-Pacific Mirna Tools and Services Market
Biotechnology Services
Industrial Microbiology Testing Services Market
Biotechnology Services
Luciferase Assay Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Europe Recombinant Protein Manufacturing Services Market
Biotechnology Services
Global Reporter Gene Assay Market
Biotechnology Services
Cell Line Development Services Market
Biotechnology Services
Dnases, Ligases, and RNA Polymerases Market
Biotechnology Services
Global Vero Cell Media Market
Biotechnology Services
Cell Characterization Assays Kits Market
Biotechnology Services
Global Qpcr Reagents Market
Biotechnology Services
Membrane Protein Characterization Service Market
Biotechnology Services
Aptamers Market
Biotechnology Services
Spain Specialty Enzymes Market
Biotechnology Services
Cdna Synthesis Market