
 Global High Throughput Screening Market | 2026-2036
Global High Throughput Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Throughput Screening Market Foresight
Switzerland is rewriting capacity benchmarks for precision liquid-handling instrumentation. Tecan Trading AG anchors its position through captive supply of robotic workstations. Thermo Fisher Scientific Inc. extends its reach across reagent-to-software integration. Danaher Corporation dominates life-science filtration and consumables adjacent to screening workflows.
High throughput screening encompasses automated platforms that process thousands to millions of biochemical or cellular assays daily, typically operating in 96-, 384-, or 1536-well microplate formats with sub-microliter precision. These systems accelerate candidate identification in drug discovery pipelines by enabling parallel compound evaluation against biological targets. Automated HTS systems command the largest installed base, though microfluidics and label-free detection represent the fastest-expanding technology categories as researchers seek reduced reagent consumption and physiologically relevant readouts. Reagents and labware generate recurring revenue streams that often exceed initial instrument sales over a platform's lifecycle.
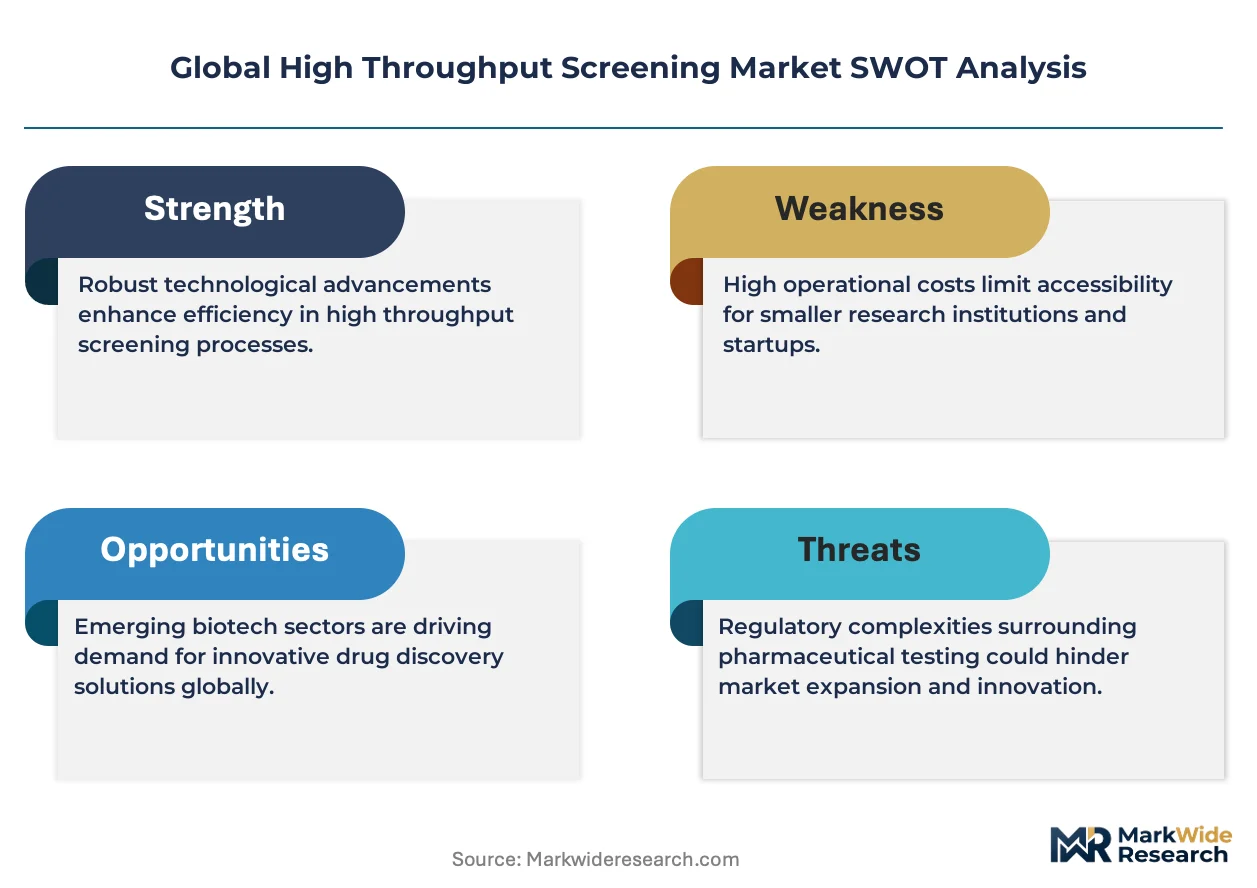
FDA 21 CFR Part 11 compliance requirements shape electronic record-keeping and data integrity standards for screening laboratories serving regulated drug development. EMA's ICH Q14 guidelines on analytical procedure development influence assay validation protocols adopted across European contract research organizations. ISO 13485 quality management standards govern diagnostic applications of HTS platforms, creating certification barriers for new entrants. Stakeholders must weigh instrument interoperability against vendor lock-in as multi-site collaboration becomes standard practice.
Market Dynamics
Compound library automation is compressing assay cycle times while tightening FDA 21 CFR Part 11 compliance requirements reshape laboratory data architecture. These dual pressures force equipment vendors to integrate traceability layers directly into liquid-handling firmware.
Growth Catalysts
- EMA ICH Q14 Guidelines:European contract research organizations are upgrading assay validation protocols to meet harmonized analytical procedure standards, driving replacement demand for legacy plate readers.
- Cellular Assay Expansion:Biopharmaceutical pipelines are pivoting from biochemical to physiologically relevant cellular models, requiring higher-density microplate formats and specialized detection optics.
- China Biotech Clusters:Shenzhen and Suzhou industrial parks are deepening screening infrastructure through government-funded shared instrumentation facilities that lower capital barriers for domestic startups.
Market Restraints
- Optics Supply Concentration:High-precision photomultiplier tubes and sCMOS sensors concentrate among Japanese and German component suppliers, creating vulnerability to export control disruptions.
- Reagent Cost Volatility:Fluorescent probe chemistries depend on rare-earth lanthanide supply chains concentrated in Chinese refining operations.
- Interoperability Friction:Vendor-specific data formats impede multi-site collaboration despite ISO 13485 quality management requirements for diagnostic applications.
Strategic Opportunities
- India CDMO Expansion:Contract development and manufacturing organizations in Hyderabad and Bengaluru are building dedicated HTS capacity to serve Western pharmaceutical outsourcing demand.
- Label-Free Convergence:Surface plasmon resonance and bio-layer interferometry are hybridizing with traditional fluorescence detection to enable real-time binding kinetics without reporter tags.
- US IRA Manufacturing Credits:Domestic production incentives for active pharmaceutical ingredients are prompting reshoring of screening operations to Massachusetts and North Carolina research corridors.
Industry Challenges
- Mechatronics Talent Scarcity:Precision robotics programming for sub-microliter dispensing requires specialized skill sets that outpace university training pipelines in Switzerland and Germany.
- Legacy LIMS Integration:Enterprise laboratory information management systems from the 2010s lack API architectures compatible with modern cloud-native screening platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Throughput Screening Market |
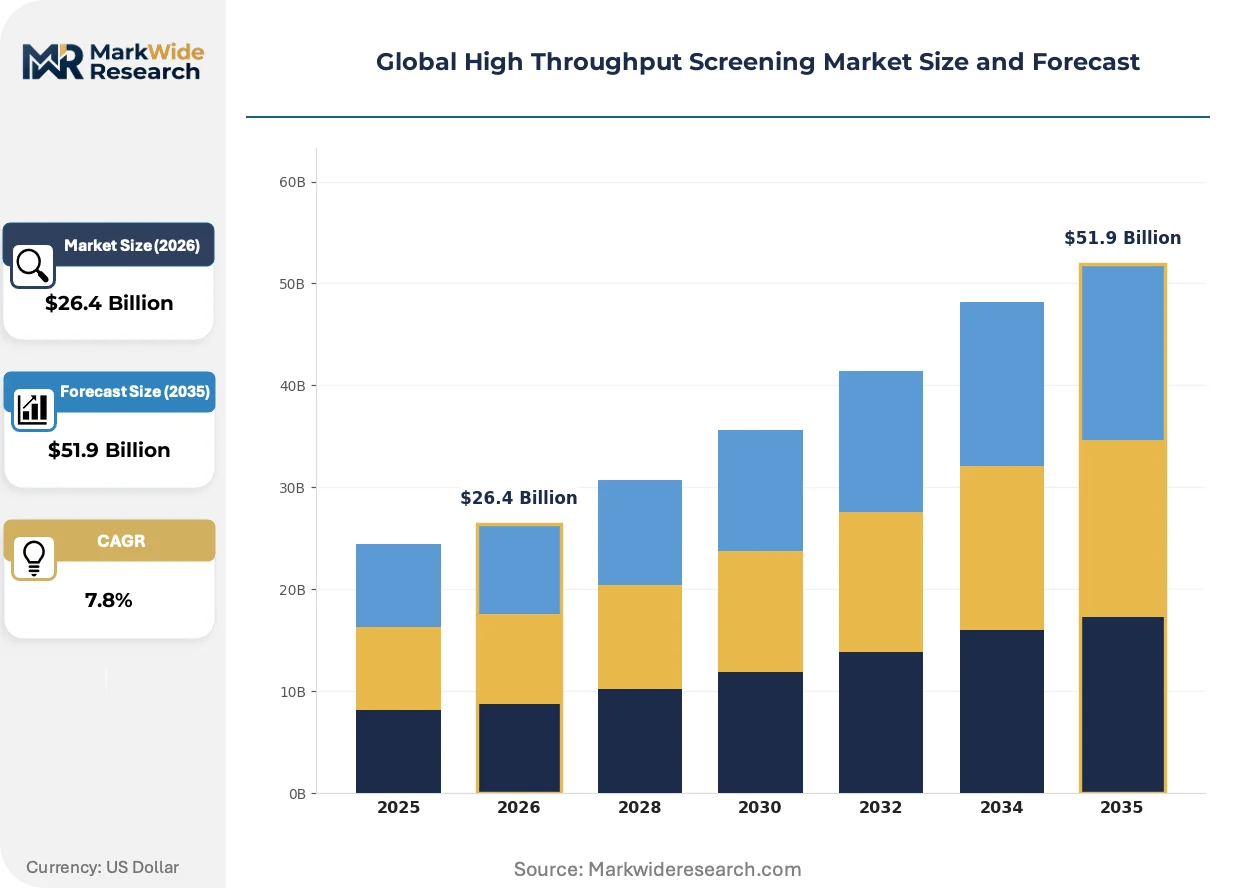
| Market Size in 2026 | $26.4 Billion |
| Market Size in 2035 | $51.9 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated HTS Systems, Detection Instruments, Reagents, Labware, Software Solutions Technology: Fluorescence-Activated Cell Sorting, Mass Spectrometry, Microfluidics, Label-Free Detection, Luminescence Assays Application: Drug Discovery, Agrochemical Screening, Environmental Testing, Material Science, Chemical Analysis End User: Pharmaceutical Companies, Biotechnology Firms, Academic Institutions, Contract Research Organizations, Diagnostic Labs |
| Companies Covered | Thermo Fisher Scientific Inc., Agilent Technologies Inc., Danaher Corporation, Revvity Inc., Merck KGaA, Tecan Trading AG, Bio-Rad Laboratories Inc., Corning Incorporated, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Throughput Screening Market Shifts & Advancements
Microfluidic sample processing is compressing reagent volumes while artificial intelligence is embedding into real-time hit classification algorithms. These developments are forcing vendors to reconsider hardware-software bundling strategies.
Organ-on-chip platforms are hybridizing microfluidic cell culture with integrated biosensors to replicate tissue-level drug responses. Large pharmaceutical toxicology departments are adopting these systems for secondary screening cascades. This convergence is displacing traditional 2D cell-based assays in safety pharmacology workflows by enabling mechanistic toxicity prediction earlier in discovery pipelines.
FDA 21 CFR Part 11 enforcement is tightening electronic signature requirements for screening data packages submitted in IND applications. Biopharmaceutical quality assurance departments are mandating audit trail capabilities that legacy instruments lack. United States-based contract research organizations are responding by consolidating vendor relationships to simplify validation documentation.
Service unbundling is fragmenting traditional instrument-reagent-software bundles. Academic core facilities and mid-sized biotechnology companies are purchasing refurbished platforms while sourcing consumables through third-party distributors. This pattern is most pronounced in German and Dutch research institutes where budget pressures favor operational flexibility over capital-intensive integrated procurements.
Global High Throughput Screening Market Segmentation
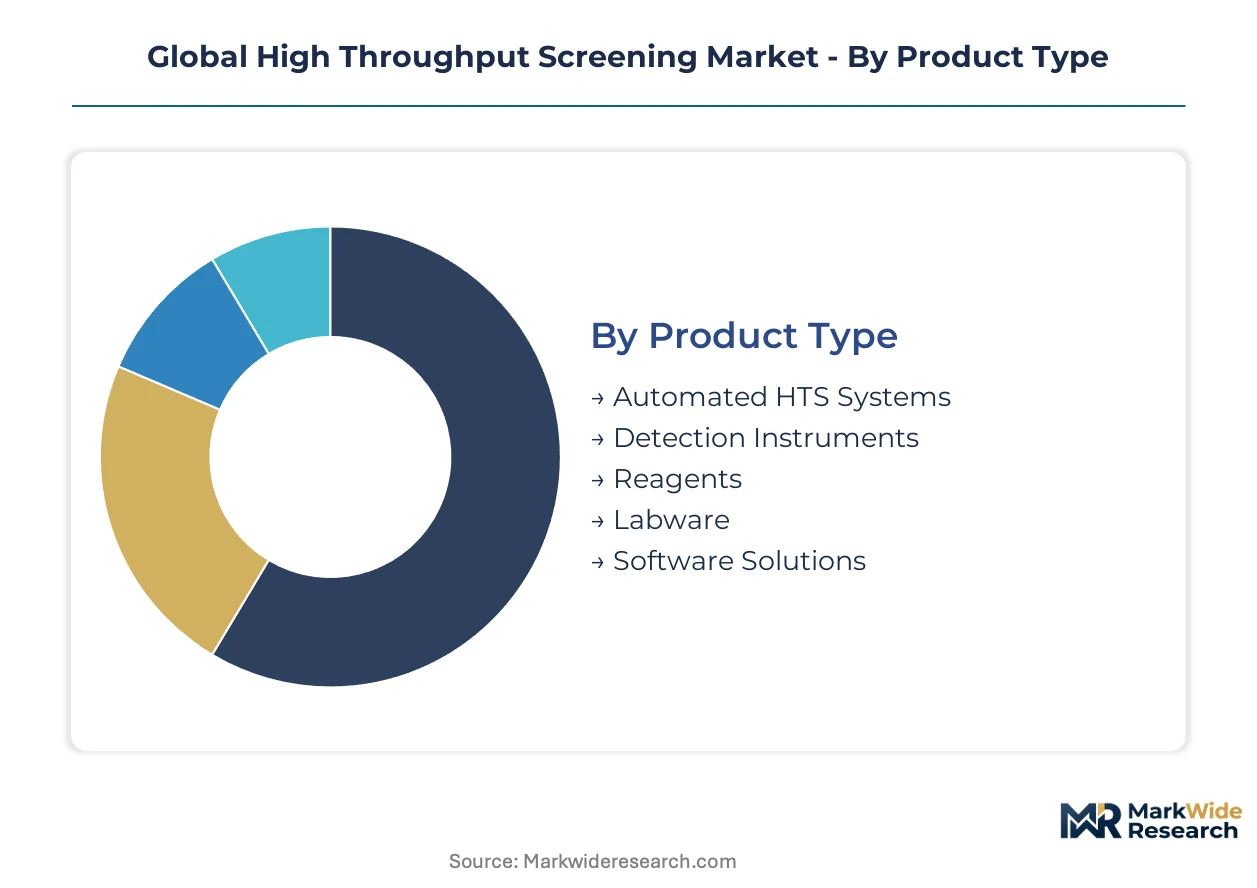
HTS market segmentation reflects divergent procurement logics across capital equipment, consumables, and enabling technologies. Pharmaceutical buyers prioritize instrument reliability and regulatory compliance, while academic facilities optimize for reagent flexibility and open software architectures.
Product Type:
Mature capital equipment segments coexist with rapidly scaling consumables categories as recurring revenue models reshape vendor economics.
- Automated HTS Systems:Robotic liquid-handling workstations integrate precision dispensers, plate handlers, and environmental controls for 24-hour unattended operation. Pharmaceutical companies in Massachusetts and North Carolina research corridors drive replacement cycles as FDA 21 CFR Part 11 compliance requirements tighten audit trail specifications.
- Reagents:Fluorescent probes, reporter enzymes, and cell viability dyes constitute the highest-margin recurring revenue stream. Demand concentrates in German contract research organizations upgrading assay portfolios to meet EMA ICH Q14 validation standards.
- Detection Instruments:Plate readers and imagers with multi-mode optics support absorbance, fluorescence, and luminescence readouts.
- Labware:Microplates in 96-, 384-, and 1536-well formats plus specialized reservoirs and sealing films.
- Software Solutions:Laboratory information management systems and data analysis platforms for hit identification and assay optimization.
Automated HTS Systems handle the majority of throughput; Reagents is the fastest mover on share.
Technology:
Cost tier stratification separates capital-intensive analytical platforms from accessible biochemical methods.
- Microfluidics:Chip-based sample processing reduces reagent consumption to nanoliter volumes while enabling complex gradient generation. Academic core facilities in Swiss and Dutch institutes adopt these systems where budget constraints favor operational flexibility over legacy plate-based workflows.
- Label-Free Detection:Surface plasmon resonance and bio-layer interferometry enable real-time binding kinetics without fluorescent reporters. Biotechnology firms in Shenzhen industrial parks deploy these for mechanistic characterization of antibody candidates.
- Fluorescence-Activated Cell Sorting:Flow cytometry platforms isolate target cell populations based on multiparametric fluorescence signatures.
- Mass Spectrometry:High-resolution detection for compound identification and metabolite profiling in secondary screening.
- Luminescence Assays:ATP-based and reporter gene formats for sensitive detection of cellular responses.
Fluorescence-Activated Cell Sorting commands the largest installed base; Label-Free Detection is climbing the fastest on adoption curves.
Application:
Customer type differentiation separates regulated pharmaceutical workflows from exploratory research environments.
- Drug Discovery:Primary and secondary screening cascades for small-molecule and biologic candidate identification. Large pharmaceutical toxicology departments in the United States pivot toward organ-on-chip platforms for mechanistic safety prediction earlier in development pipelines.
- Agrochemical Screening:Herbicide, fungicide, and insecticide efficacy testing against target organisms and beneficial species. Chinese government-funded shared instrumentation facilities in Suzhou lower capital barriers for domestic ag-biotech startups.
- Environmental Testing:Contaminant detection and ecotoxicity assessment for regulatory compliance monitoring.
- Material Science:High-throughput characterization of polymer and nanomaterial properties.
- Chemical Analysis:Purity verification and impurity profiling for industrial chemical production.
Drug Discovery absorbs the greatest screening capacity; Agrochemical Screening is expanding most quickly as food security priorities intensify.
End User:
Volume concentration varies dramatically between high-throughput industrial operations and fragmented academic installations.
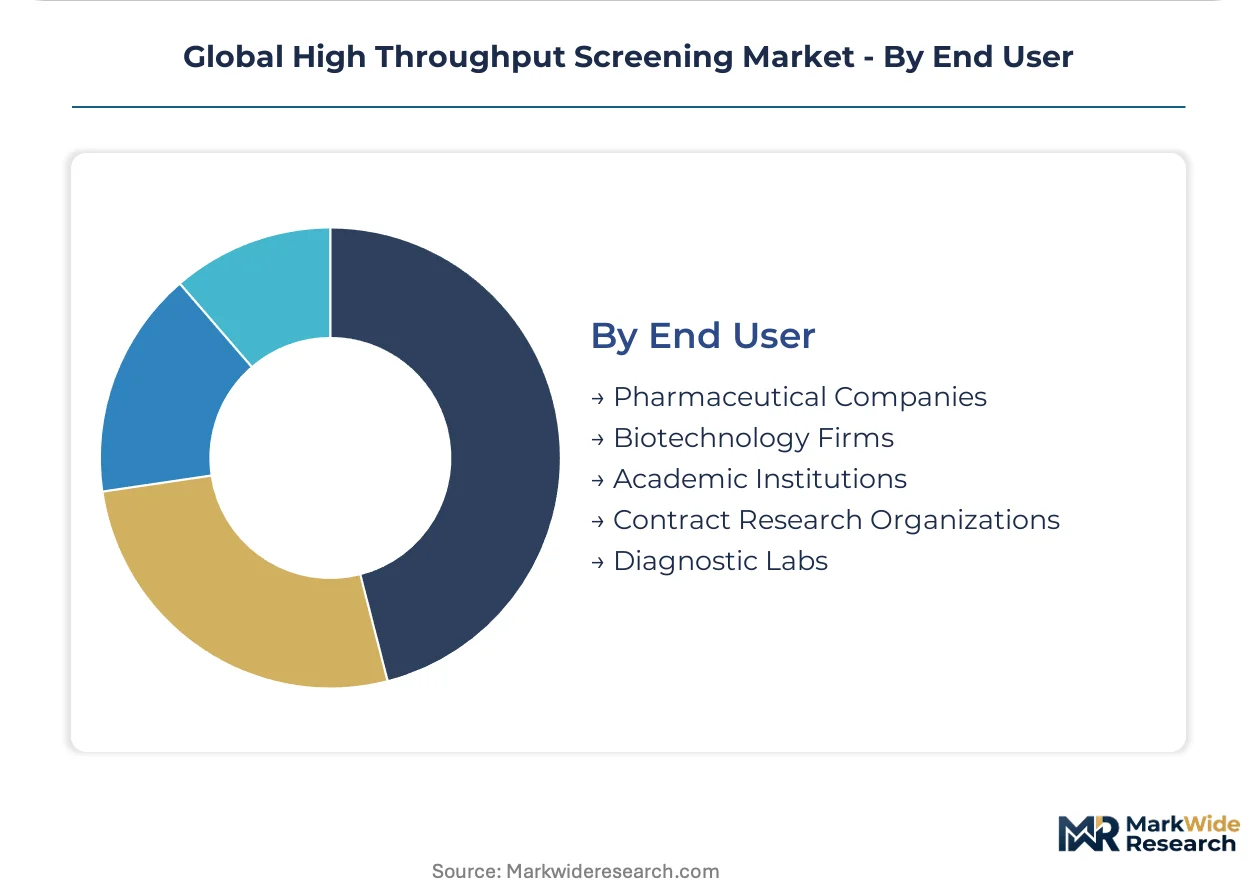
- Pharmaceutical Companies:Integrated discovery organizations operating dedicated screening centers with full-time automation engineers. These facilities in Germany and Switzerland drive demand for 1536-well formats and sub-microliter precision as compound library automation compresses cycle times.
- Contract Research Organizations:Externalized screening services for biotech clients lacking internal infrastructure. CDMOs in Hyderabad and Bengaluru build dedicated HTS capacity to capture Western pharmaceutical outsourcing demand.
- Biotechnology Firms:Venture-funded companies prioritizing speed-to-clinic over internal platform investment.
- Academic Institutions:Core facilities serving multiple principal investigators with shared instrumentation.
- Diagnostic Labs:Clinical applications governed by ISO 13485 quality management and national diagnostic regulations.
Pharmaceutical Companies process the highest absolute throughput; Contract Research Organizations are gaining share fastest as outsourcing deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Pharmaceutical companies in the United States and Germany drive demand for 1536-well formats and sub-microliter precision, while Chinese facilities prioritize cost-efficient 384-well automation in government-funded shared instrumentation centers.
United States
FDA 21 CFR Part 11 compliance requirements are tightening audit trail specifications for screening data packages submitted in IND applications. Massachusetts and North Carolina research corridors are consolidating vendor relationships to simplify validation documentation. Contract research organizations in these states are replacing legacy plate readers with integrated robotic workstations.
Germany
EMA ICH Q14 guidelines on analytical procedure development are driving replacement demand for legacy detection instruments across contract research organizations. Bavarian and North Rhine-Westphalian biotech clusters are deepening screening infrastructure through private-public instrumentation partnerships. German pharmaceutical buyers prioritize instrument reliability and regulatory compliance over operational flexibility.
China
Shenzhen and Suzhou industrial parks are expanding shared instrumentation facilities that lower capital barriers for domestic biotech startups. NMPA validation standards for assay reproducibility are tightening equipment specifications for diagnostic applications. Chinese government funding is concentrating screening capacity in coastal manufacturing zones.
Switzerland
Swissmedic quality requirements are rewriting capacity benchmarks for precision liquid-handling instrumentation. Basel and Zurich biotech corridors demand sub-microliter dispensing accuracy for compound library automation. Swiss precision robotics programming expertise is creating talent scarcity as university training pipelines lag industry expansion.
India
Contract development and manufacturing organizations in Hyderabad and Bengaluru are building dedicated HTS capacity to capture Western pharmaceutical outsourcing demand. CDSCO diagnostic regulations are prompting ISO 13485 certification investments among domestic equipment distributors. Indian CDMOs are prioritizing operational flexibility over capital-intensive integrated procurements.
Global High Throughput Screening Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The market structures around three player categories: diversified life-science conglomerates with captive reagent-to-software integration, precision instrumentation specialists with robotic workstation expertise, and consumables-focused suppliers generating recurring revenue streams. Strategic moves center on M&A for technology portfolio expansion and strategic partnerships for multi-site interoperability.
Within the diversified conglomerate tier, Thermo Fisher Scientific Inc., Danaher Corporation, and Agilent Technologies Inc. exemplify the integrated platform model. Tecan Trading AG represents the precision instrumentation specialist archetype. These anchors occupy positions across the value chain from liquid-handling robotics to detection optics and laboratory information management systems.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Agilent Technologies Inc. |
| Danaher Corporation |
| Revvity Inc. |
| Merck KGaA |
| Tecan Trading AG |
| Bio-Rad Laboratories Inc. |
| Corning Incorporated |
| Promega Corporation |
| Others |
Supply & Pricing Matrix
Shenzhen and Suzhou industrial parks anchor HTS equipment manufacturing capacity, with government-funded shared instrumentation facilities compressing capital recovery timelines and amplifying pricing power for domestic vendors serving cost-sensitive biotech startups.
Pricing Analysis
Geographic price spreads separate Swiss precision robotics from Chinese government-subsidized platforms by factors exceeding two-to-one. Three-tier pricing structure across premium, standard, and economy levels differentiates by FDA 21 CFR Part 11 compliance tier and sub-microliter dispensing precision. Cost compression in economy tiers is intensifying because refurbished platform availability fragments vendor lock-in. Academic core facilities exhibit highest price sensitivity; pharmaceutical quality assurance departments show lowest sensitivity due to validation documentation requirements.
Supply Chain Analysis
Contract manufacturing for precision liquid-handling robotics concentrates in Switzerland, Germany, and China, with Tecan Trading AG and domestic Chinese vendors holding captive production capacity. Photomultiplier tubes and sCMOS sensors draw from Japanese and German component suppliers; rare-earth lanthanide refining for fluorescent probes rests on Chinese operations. Single-source vulnerability in high-precision optics creates tariff exposure risk. Distribution runs through direct vendor relationships with large pharmaceutical companies and third-party distributors serving academic core facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision robotics programming expertise for sub-microliter dispensing has become the binding constraint, with university training pipelines in Switzerland and Germany lagging industry expansion by multiple years.
For Market Incumbents: Build captive talent development moats through apprenticeship partnerships with Swiss Federal Institutes and German technical universities. Deepen backward integration into photomultiplier tube sourcing through strategic partnerships with Hamamatsu Photonics and German sensor specialists. Consolidate vendor relationships among US contract research organizations to simplify FDA 21 CFR Part 11 validation documentation and defend against refurbished platform fragmentation. For New Entrants and Emerging Players: Mid-market cellular assay services in Indian CDMOs represent the most penetrable entry point, with Hyderabad and Bengaluru facilities prioritizing operational flexibility over capital-intensive integrated procurements. Label-free detection hybridization with traditional fluorescence platforms offers technical differentiation without competing head-to-head against entrenched robotic workstation vendors. Pursue white-label service partnerships with Western pharmaceutical companies seeking outsourced secondary screening capacity. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue compounder play because reagent and labware consumables generate margins exceeding instrument sales over platform lifecycles. Target precision liquid-handling specialists with captive robotic programming expertise and established FDA validation documentation. Monitor NMPA diagnostic regulation tightening in China as inflection indicator for domestic equipment vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Certification | FDA 21 CFR Part 11 audit trail capabilities differentiate premium platforms from refurbished alternatives in IND submissions. |
| Consumables Portfolio Expansion | Fluorescent probe chemistries anchored in rare-earth supply chains generate recurring revenue exceeding instrument depreciation cycles. |
| Precision Robotics Talent Development | Swiss apprenticeship partnerships address mechatronics scarcity constraining sub-microliter dispensing capacity expansion. |
| Multi-Site Interoperability Partnership | Cloud-native LIMS integration resolves vendor-specific data format friction impeding CRO collaboration across Massachusetts and North Carolina corridors. |
| Label-Free Detection Hybridization | Surface plasmon resonance convergence with fluorescence optics enables real-time binding kinetics for antibody mechanistic characterization. |
Research Methodology
Initial hypotheses were tested against primary input from pharmaceutical automation engineers, contract research organization procurement directors, academic core facility managers, and regulatory affairs specialists, and refined through secondary validation against FDA 21 CFR Part 11 guidance documents, EMA ICH Q14 technical specifications, ISO 13485 certification databases, and SEC filings from diversified life-science conglomerates. Bottom-up instrument installation counts and top-down pharmaceutical R&D expenditure flows were triangulated to establish market sizing boundaries.
Demand-supply balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, technology modality, application area, and end-user archetype. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of regulatory-driven upgrade mandates. Forecast inputs incorporated EMA ICH Q14 assay validation protocol adoption curves and NMPA diagnostic equipment specification tightening timelines.
Practitioners should monitor export control disruptions affecting Japanese photomultiplier tube supply and Chinese rare-earth refining operations for early signals of cost volatility transmission. Quarterly review of FDA 21 CFR Part 11 enforcement patterns and CDSCO ISO 13485 certification investments is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Services
Bioanalytical Testing Services Market
Biotechnology Services
Phycobiliproteins Market
Biotechnology Services
In-Vitro Fertilization Services Market
Biotechnology Services
Proteinase K Market
Biotechnology Services
Monoclonal Antibody Custom Service Market
Biotechnology Services
Plasmid DNA Contract Manufacturing Market
Biotechnology Services
Electrophoresis Market
Biotechnology Services
Plant Tissue Culture Products Market
Biotechnology Services
Marine Polysaccharides Fucoidan Alginate Market
Biotechnology Services
UK Biotechnology and Pharmaceutical Services Outsourcing Market
Biotechnology Services
Recombinant Factor C Assay Market
Biotechnology Services
Bio-Pharma Logistics Market
Biotechnology Services
Global Alpha Galactosidase Market
Biotechnology Services
Bio-Services Market
Biotechnology Services
Loop-Mediated Isothermal Amplification (LAMP) Market
Biotechnology Services
Stable Cell Line Development Market