
 Cell and Tissue Preservation Market | 2026-2036
Cell and Tissue Preservation Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Tissue Preservation Market Intelligence
North American biobank infrastructure is pivoting toward automated liquid nitrogen systems to handle rising cell therapy volumes. Thermo Fisher Scientific leverages its end-to-end cold-chain portfolio to anchor clinical and commercial preservation workflows. Lonza sustains leadership through specialized cryopreservation media formulations for CAR-T manufacturing. BioLife Solutions differentiates with its proprietary hypothermic and cryogenic storage solutions targeting regenerative medicine bioprocessing.
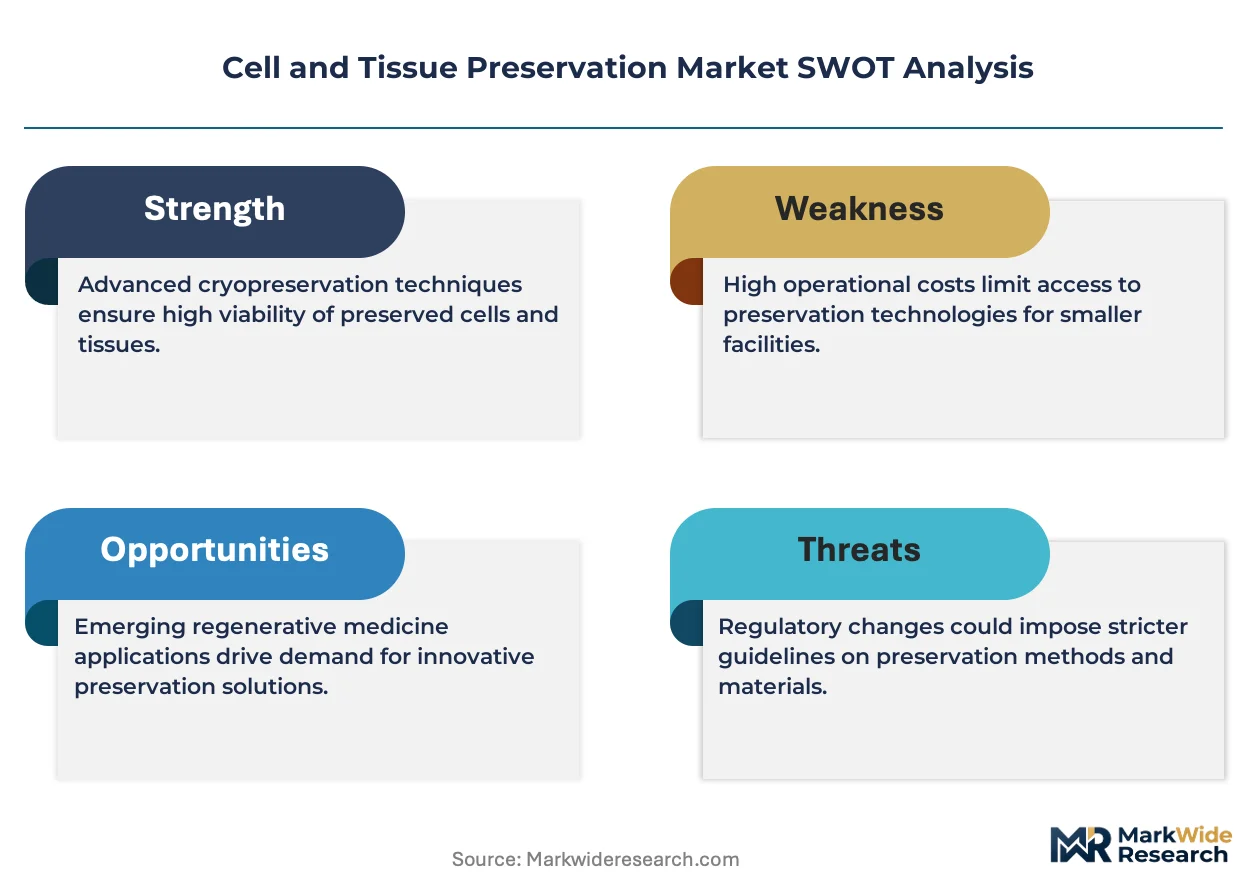
Cell and tissue preservation encompasses the stabilization of viable biological specimens through temperature-controlled environments, typically employing cryoprotective agents such as dimethyl sulfoxide or trehalose to prevent ice crystal formation and maintain membrane integrity for subsequent therapeutic or research applications. The field serves critical functions in regenerative medicine, transplantation logistics, and biopharmaceutical manufacturing where cellular potency must be retained across extended storage intervals. Cryopreservation systems command the largest product share given capital intensity and regulatory qualification requirements, while preservation media generates recurring revenue streams tied to expanding cell therapy pipelines. Vitrification technology is displacing conventional controlled-rate freezing in premium stem cell applications due to superior post-thaw viability metrics.
FDA 21 CFR Part 1271, EU Tissue and Cell Directives, and AABB standards collectively govern preservation protocol validation, traceability, and distribution integrity across the value chain. These frameworks mandate documented temperature excursion management and equipment qualification, elevating compliance costs while favoring vendors with established quality management systems. Stakeholders must monitor evolving cell therapy commercialization scale and corresponding biobank capacity constraints to align preservation infrastructure investments with therapy approval trajectories.
Market Dynamics
Vitrification technology is compressing conventional freezing timelines as stem cell banks and CAR-T manufacturers prioritize post-thaw viability metrics over legacy infrastructure amortization. This shift concentrates procurement authority among facilities capable of validating novel cryoprotectant cocktails.
Growth Catalysts
- FDA 21 CFR Part 1271:Tightened donor eligibility and traceability mandates compel biobanks to upgrade preservation documentation systems, expanding demand for qualified cold-chain equipment.
- Dimethyl sulfoxide alternatives:Trehalose and ethylene glycol formulations reduce cytotoxicity in clinical-grade cell therapies, opening preservation protocols to sensitive induced pluripotent stem cell applications.
- Germany's ATMP manufacturing clusters:Concentrated cell therapy production in Cologne and Heidelberg drives localized demand for high-throughput cryogenic storage infrastructure.
Market Restraints
- Liquid nitrogen supply volatility:Regional production bottlenecks in industrial gas manufacturing expose biobanks to price spikes and allocation rationing during peak demand periods.
- EMA tissue directive compliance costs:Extended qualification timelines for multi-site preservation networks delay facility commissioning by 18-24 months.
- Controlled-rate freezer obsolescence:Capital-intensive equipment stranded by vitrification adoption creates stranded asset risk for mid-scale biorepositories.
Strategic Opportunities
- Japan's regenerative medicine commercialization:PMDA's accelerated approval pathways for iPSC-derived therapies create demand for specialized hypothermic transport containers.
- AI-enabled cryoprotectant screening:Machine learning convergence with high-throughput cell viability assays compresses formulation optimization from months to weeks.
- Point-of-care thawing devices:Decentralized cell therapy administration shifts preservation value capture toward bedside warming technologies.
Industry Challenges
- Cryobiology specialist scarcity:Limited academic programs in low-temperature cell biology constrain hiring for process development roles at expanding manufacturing sites.
- Multi-modal cold-chain integration:Reconciling vapor-phase nitrogen, mechanical freezers, and hypothermic perfusion systems within single facilities complicates validation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Tissue Preservation Market |
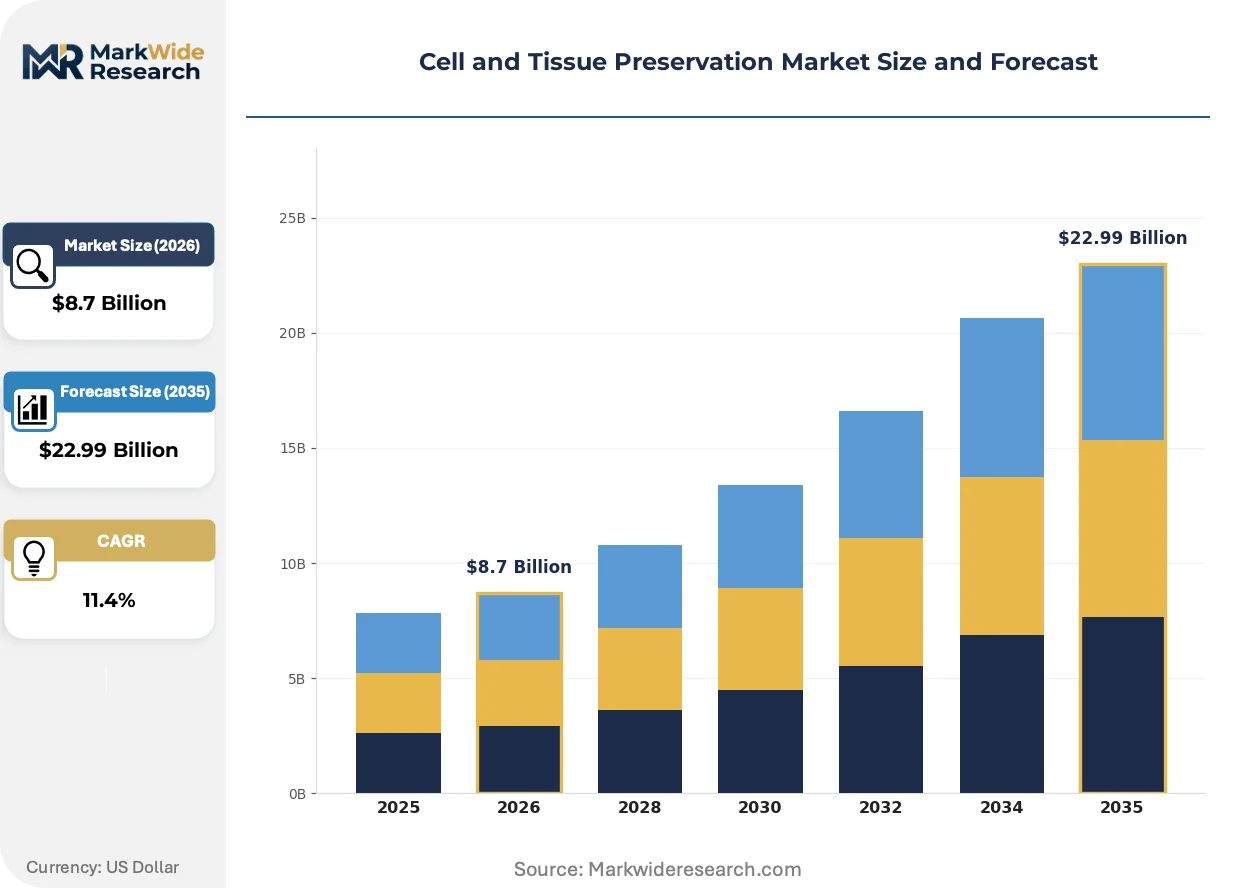
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cryopreservation Systems, Preservation Media, Storage Containers, Thawing Kits Application: Stem Cell Therapy, Organ Transplantation, Tissue Engineering, Vaccine Production Technology: Vitrification, Controlled Rate Freezing, Liquid Nitrogen Storage, Passive Cooling End User: Biobanks, Research Institutions, Hospitals, Pharmaceutical Companies |
| Companies Covered | Thermo Fisher Scientific, Inc., Lonza, BD, Merck KGaA, Cytiva, Agilent Technologies, Inc., Avantor, Inc., FUJIFILM Irvine Scientific, BioLife Solutions Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Tissue Preservation Market Strategic Shifts & Innovations
Preservation workflows are fragmenting into modular, application-specific configurations rather than universal platform approaches. This decomposition enables faster protocol adaptation but fragments vendor relationships.
Closed-system vitrification devices are unifying cryoprotectant loading, ultra-rapid cooling, and sealed storage within single-use cartridges. Academic medical centers in Boston and Stanford have adopted these systems for clinical-grade induced pluripotent stem cell banking. The technology is unifying previously separate equipment categories, compressing capital expenditure timelines for new facility buildouts.
EMA's 2024 revision to the Tissues and Cells Directive introduces mandatory electronic temperature logging with blockchain-anchored audit trails. Biobanks serving multinational pharmaceutical sponsors must retrofit legacy monitoring infrastructure. European contract manufacturing organizations face the steepest compliance burden given cross-border sample movement volumes.
Cell therapy sponsors are unbundling preservation services from manufacturing contracts, establishing direct relationships with specialized logistics providers. This disintermediation fragments incumbent CDMO revenue streams while elevating cold-chain specialists to strategic partner status. The pattern is most pronounced in California's Bay Area biocluster where sponsor concentration enables vendor diversification.
Cell and Tissue Preservation Market Segmentation
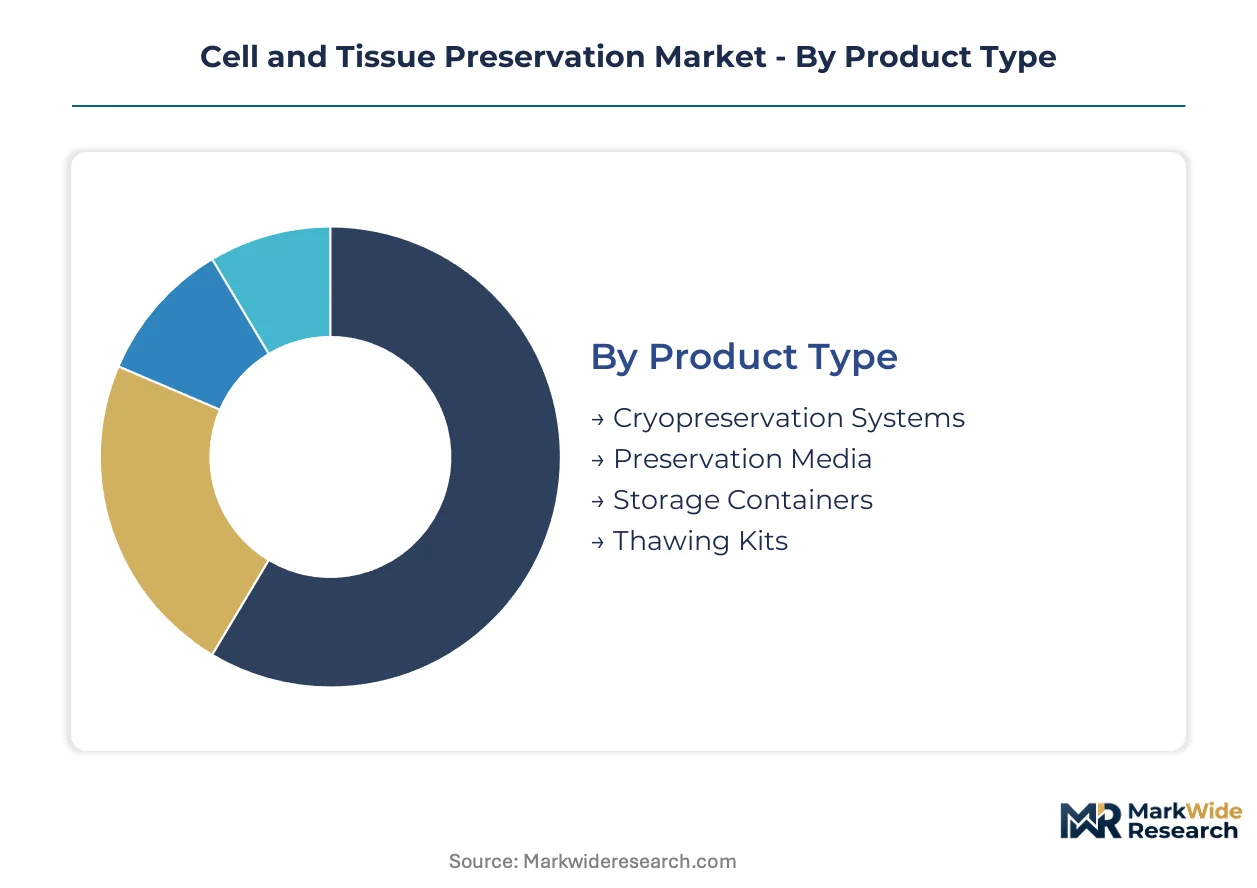
Preservation technology selection hinges on cell-type sensitivity, regulatory qualification burdens, and throughput economics. Each segment category reflects distinct procurement hierarchies where capital equipment, consumables, and services command separate budget cycles and vendor relationships.
Product Type:
Capital intensity and recurring revenue potential drive buyer prioritization across hardware and consumable portfolios.
- Cryopreservation Systems:Automated controlled-rate freezers and liquid nitrogen dewars dominate facility CapEx allocations. CAR-T manufacturing sites in Germany and Japan prioritize equipment with integrated 21 CFR Part 11 compliance documentation to accelerate FDA and PMDA inspections.
- Preservation Media:Serum-free and chemically defined formulations command premium pricing in clinical-grade applications. Trehalose-based alternatives to dimethyl sulfoxide are capturing share in iPSC banking protocols where post-thaw viability directly impacts therapeutic potency.
- Storage Containers:Vapor-phase nitrogen canisters and mechanical freezer racks standardize inventory management across multi-site biobank networks.
- Thawing Kits:Single-use warming devices reduce contamination risk in point-of-care cell therapy administration.
Cryopreservation Systems leads on scale; Preservation Media leads on momentum.
Application:
Clinical commercialization timelines determine validation rigor and price tolerance across therapeutic categories.
- Stem Cell Therapy:Induced pluripotent and mesenchymal stem cell applications demand the highest preservation fidelity. Japan's accelerated PMDA approval pathways for iPSC-derived products are compressing protocol development cycles for hypothermic transport containers.
- Organ Transplantation:Hypothermic machine perfusion systems extend viable preservation windows for hearts and lungs. US transplant centers face CMS reimbursement pressure to reduce discard rates of marginal donor organs.
- Tissue Engineering:Scaffold-seeded constructs require staged cooling profiles to maintain three-dimensional architecture during bioreactor-to-surgery logistics.
- Vaccine Production:Viral vector stability during master cell bank storage underpins pandemic preparedness stockpiling strategies.
Stem Cell Therapy commands premium pricing; Organ Transplantation faces the steepest regulatory qualification barriers.
Technology:
Post-thaw viability benchmarks are displacing legacy infrastructure amortization schedules in procurement decisions.
- Vitrification:Ultra-rapid cooling eliminates ice crystal formation through glass transition. Academic medical centers in Boston and Stanford have adopted closed-system vitrification cartridges for clinical-grade iPSC banking, unifying cryoprotectant loading and sealed storage.
- Controlled Rate Freezing:Programmable temperature descent remains standard for bulk cell banking where throughput outweighs marginal viability gains. Mid-scale biorepositories face stranded asset risk as vitrification adoption accelerates.
- Liquid Nitrogen Storage:Vapor-phase and liquid-phase systems anchor long-term biobank capacity planning.
- Passive Cooling:Insulated shippers with phase-change materials address last-mile distribution gaps in decentralized therapy administration.
Controlled Rate Freezing retains installed base dominance; Vitrification climbs the fastest among emerging modalities.
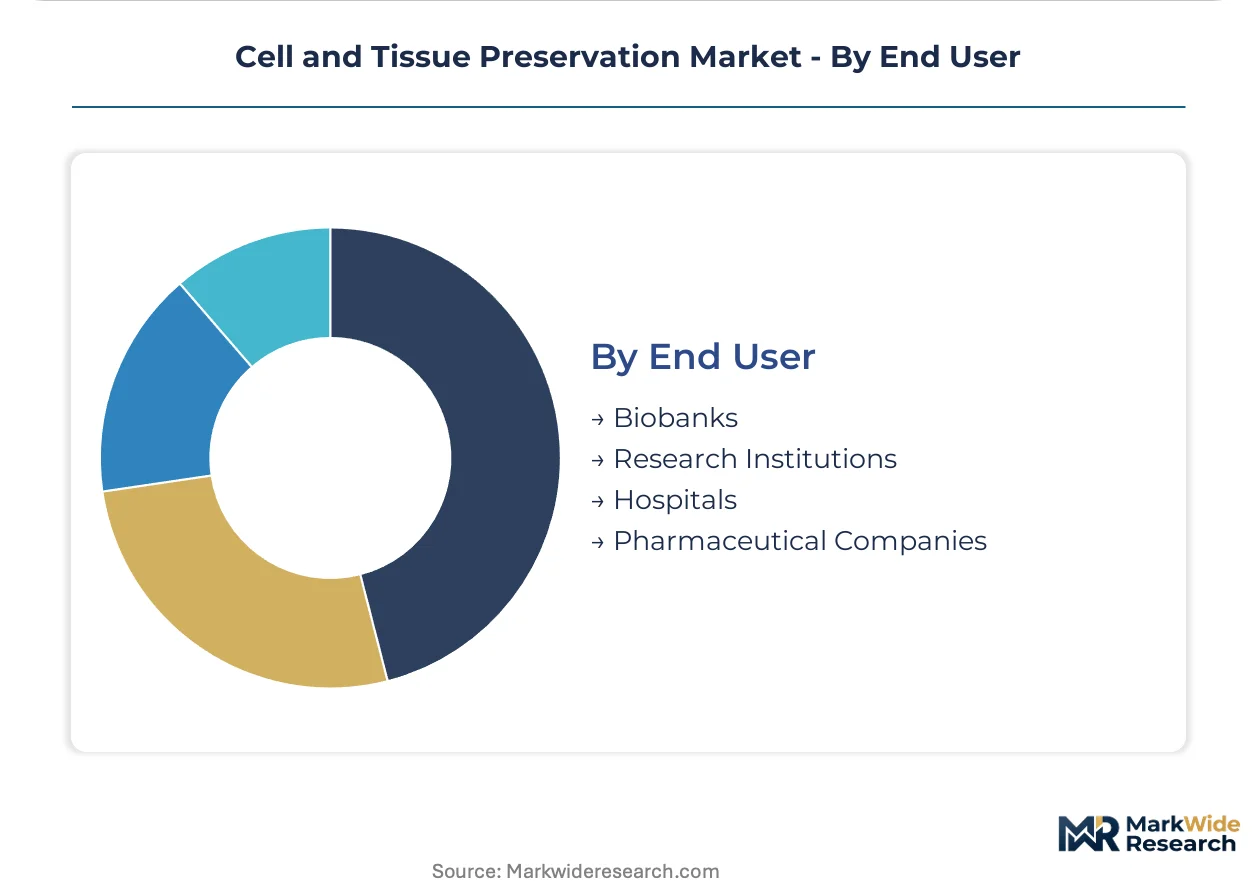
End User:
Facility scale and regulatory exposure shape vendor relationship structures and service bundling preferences.
- Biobanks:Population-scale repositories and disease-specific collections drive demand for automated inventory management and blockchain-anchored chain-of-custody systems. EMA's 2024 Tissues and Cells Directive revision mandates electronic temperature logging that European biobanks must retrofit into legacy infrastructure.
- Pharmaceutical Companies:Cell therapy sponsors are unbundling preservation from manufacturing contracts to establish direct logistics provider relationships, elevating cold-chain specialists to strategic partner status in California's Bay Area cluster.
- Research Institutions:Academic labs prioritize cost-efficient vapor-phase nitrogen dewars for preclinical specimen archiving.
- Hospitals:Transplant centers and stem cell transplant units require bedside thawing capabilities for patient-specific therapies.
Biobanks anchor volume procurement; Pharmaceutical Companies drive technology substitution fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cell therapy preservation infrastructure as manufacturers migrate toward jurisdictions with streamlined advanced therapy frameworks and lower qualification burdens. Production gravity is shifting toward countries with established ATMP manufacturing clusters and harmonized cold-chain standards.
United States
FDA's 21 CFR Part 1271 mandates drive biobank infrastructure upgrades across commercial and academic facilities. The agency's tightened donor eligibility and traceability requirements compel facilities to adopt qualified cold-chain equipment with integrated compliance documentation. Boston and Stanford academic medical centers anchor clinical-grade iPSC banking adoption of closed-system vitrification cartridges.
Germany
EMA tissue directive compliance costs delay multi-site preservation network commissioning by 18-24 months, concentrating investment in established manufacturing hubs. Cologne and Heidelberg ATMP clusters generate localized demand for high-throughput cryogenic storage infrastructure. German biobanks face retrofit pressure from the 2024 Tissues and Cells Directive revision mandating blockchain-anchored temperature logging.
Japan
PMDA's accelerated approval pathways for iPSC-derived therapies compress protocol development cycles for specialized hypothermic transport containers. The regulator's regenerative medicine commercialization framework creates demand for point-of-care thawing capabilities. Tokyo and Osaka metropolitan areas concentrate cell therapy sponsor activity and corresponding preservation service unbundling from manufacturing contracts.
United Kingdom
Medicines and Healthcare products Regulatory Agency alignment with EU ATMP standards preserves cross-border sample movement viability post-Brexit. London's contract manufacturing organizations face steep compliance burdens for multinational pharmaceutical sponsor relationships. The Cambridge biocluster drives adoption of automated liquid nitrogen systems for rising cell therapy volumes.
Switzerland
Swissmedic's pragmatic qualification timelines attract preservation service providers seeking European market access without EMA's extended validation requirements. Basel's pharmaceutical concentration supports specialized cryopreservation media demand for CAR-T manufacturing workflows. Swiss biobanks leverage blockchain-anchored audit trail infrastructure to serve multinational sponsor temperature logging mandates.
Cell and Tissue Preservation Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue vitrification technology and AI-enabled cryoprotectant screening as differentiation vectors. The market exhibits tiered concentration with diversified life sciences conglomerates anchoring capital equipment supply and specialized media formulators capturing recurring revenue streams. Three archetypes dominate: end-to-end cold-chain portfolio holders, cryopreservation media specialists, and point-of-care logistics innovators. Competitive dynamics center on strategic partnerships between therapy sponsors and preservation service providers, plus technology licensing for closed-system vitrification devices.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA occupy positions spanning equipment, media, and analytical instrumentation. Lonza represents the specialized manufacturing services archetype with integrated cryopreservation capabilities. BioLife Solutions exemplifies the focused preservation technology vector with proprietary hypothermic and cryogenic storage solutions targeting regenerative medicine bioprocessing.
| Leading Market Players |
|---|
| Thermo Fisher Scientific, Inc. |
| Lonza |
| BD |
| Merck KGaA |
| Cytiva |
| Agilent Technologies, Inc. |
| Avantor, Inc. |
| FUJIFILM Irvine Scientific |
| BioLife Solutions Inc. |
| Others |
Cost & Logistics Intelligence
Cryobiology specialist scarcity in the United States and Germany creates labor-cost differentials that widen pricing-tier spreads between premium vitrification systems and standard controlled-rate freezers. FDA 21 CFR Part 1271 compliance documentation requirements add qualification premiums to equipment serving pharmaceutical sponsors, while research institutions face softer price ceilings.
Pricing Analysis
Direct-to-OEM discounts compress distributor margins for cryopreservation media volumes above contractual thresholds. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade formulations with full regulatory documentation from research-use products. Pricing pressure stems from vitrification technology adoption stranding legacy controlled-rate freezer inventories. Academic biobanks exhibit highest price sensitivity; CAR-T manufacturers accept premium positioning for validated cold-chain integrity.
Supply Chain Analysis
Regional distribution centers in the United States, Germany, and Japan anchor hub-and-spoke patterns for liquid nitrogen dewar replenishment and cryoprotectant media fulfillment. Manufacturing draws from industrial gas production in the Gulf Coast, specialty chemical synthesis in Basel, and precision machining in Japan. Single-source vulnerability concentrates in dimethyl sulfoxide precursor supply from Chinese petrochemical complexes. Distribution runs through pharmaceutical logistics specialists with temperature-validated fleets rather than general freight networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell and tissue preservation market functions as a stable compounder anchored by irreversible biobank infrastructure buildout for commercial cell therapy manufacturing.
For Market Incumbents: Extend cryopreservation media formulation portfolios into trehalose-based alternatives before DMSO displacement accelerates. Anchor automated liquid nitrogen system deployments in Germany's ATMP clusters to preempt emerging entrant equipment plays. Deepen backward integration into cryoprotectant raw material supply to defend margin position against industrial gas volatility. For New Entrants and Emerging Players: Capture point-of-care thawing device white space as cell therapy administration decentralizes toward hospital-based administration. Japan's PMDA-accelerated iPSC pathway offers the most penetrable geography for specialized hypothermic transport container introduction. Lead with AI-enabled cryoprotectant screening services to bypass capital-intensive equipment manufacturing barriers. For Investors and Strategic Acquirers: Valuations sit cheapest among cryopreservation media specialists with recurring revenue streams and regulatory qualification moats. Five-to-ten-year viability hinges on unbundling trends elevating cold-chain logistics providers to strategic partner status. Watch for FDA 21 CFR Part 1271 documentation automation inflection as signal for scalable platform acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Vitrification Cartridge Launch | Stanford and Boston academic centers validate clinical-grade iPSC banking protocols. |
| Blockchain-Anchored Temperature Logging Retrofit | EMA's 2024 Tissues and Cells Directive mandates electronic audit trail infrastructure. |
| AI-Enabled Cryoprotectant Screening Service | Machine learning convergence compresses formulation optimization timelines for sponsors. |
| Trehalose-Based Media Formulation Expansion | Reduced cytotoxicity opens iPSC applications beyond DMSO-limited protocols. |
| Point-of-Care Thawing Device Development | Bedside warming capabilities capture value as administration decentralizes from central facilities. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with cryopreservation process development leads, biobank operations directors, regulatory affairs specialists at cell therapy sponsors, and cold-chain logistics procurement managers inform demand-side dynamics. Secondary sources include FDA 21 CFR Part 1271 guidance documents, EMA tissue directive revisions, PMDA regenerative medicine approval databases, and AABB accreditation standards. Bottom-up equipment installation counts and top-down therapy pipeline scaling triangulate market sizing.
Rate-of-change decomposition separates installed base replacement cycles from net new capacity additions across the analysis window. Segmentation dimensions encompass product type, application, technology modality, and end-user facility scale. CAGRs derive from therapy approval trajectory alignment with biobank capacity planning timelines. Cryoprotectant media consumption per manufacturing batch and vapor-phase nitrogen storage capacity utilization serve as industry-specific forecast anchors.
Liquid nitrogen supply volatility, EMA qualification timeline extensions, and vitrification technology substitution velocity are the dominant revision risks to modeled outputs. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Biotechnology
Myeloproliferative Disorders Drugs Market
Medical Biotechnology
Mitochondrial Myopathies Market
Medical Biotechnology
Waldenstrom Macroglobulinemia Market
Medical Biotechnology
Alpha Mannosidosis Market
Medical Biotechnology
Global Metformin-Pioglitazone Market
Medical Biotechnology
Cancer Monoclonal Antibodies Market
Medical Biotechnology
Alport Syndrome Market
Medical Biotechnology
Serum Lactate Testing Market
Medical Biotechnology
Global Ornithine-Transcarbamylase Deficiency Market
Medical Biotechnology
Global DNA Vaccines Market
Medical Biotechnology
Fetal Macrosomia Market
Medical Biotechnology
CMO and CDMO Biotechnology Market
Medical Biotechnology
Anti-Cathepsin B Market
Medical Biotechnology
Beta Thalassemia Testing Market
Medical Biotechnology
Muscular Dystrophy Drugs Market
Medical Biotechnology
Testicular Cancer Drugs Market